
 Global Digital Market | 2026-2036
Global Digital Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Market Analysis
Premium-tier cloud infrastructure is rotating toward sovereign and edge deployments as enterprises prioritize data residency. Amazon anchors North American hyperscale capacity through backward integration into custom silicon and fiber networks. Alibaba Group dominates Asia-Pacific commerce-to-cloud linkages by leveraging its domestic logistics-data flywheel. Shopify competes in the mid-market by specializing in merchant-centric API extensibility rather than infrastructure ownership.
The Global Digital encompasses software applications, distributed computing platforms, and associated professional services delivered over internet protocol networks, typically requiring sub-100 millisecond latency for real-time transaction processing and API interoperability. Its primary commercial purpose is to automate business workflows, monetize data assets, and enable scalable customer engagement without proportional capital expenditure. Platforms and services together capture the dominant margin pools as recurring revenue models displace perpetual licensing, while cloud computing infrastructure leads technology investment as enterprises migrate workload orchestration from on-premises data centers to distributed edge nodes. AI represents the fastest-growing technology segment as inference workloads multiply across customer touchpoints, though Blockchain remains concentrated in cross-border settlement and supply chain provenance applications with narrower commercial traction.
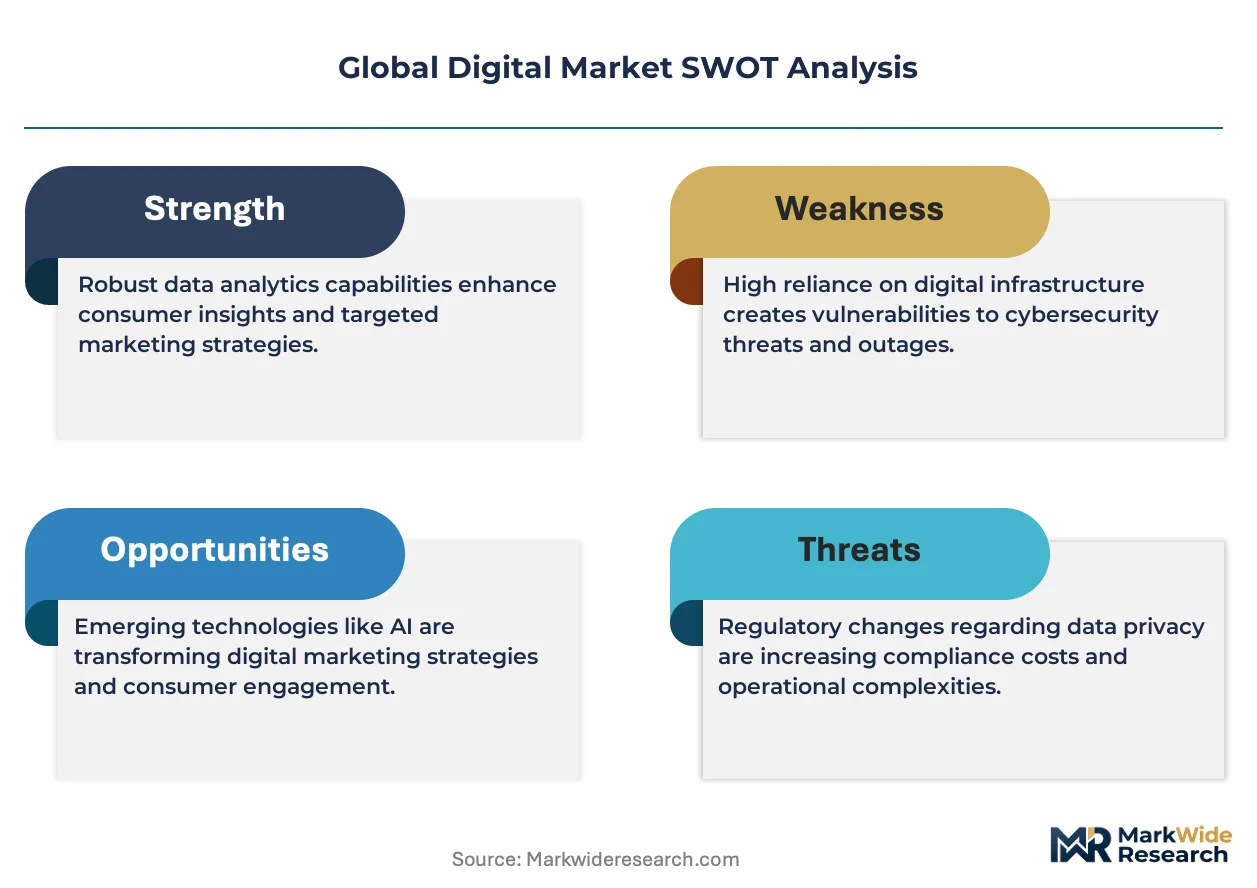
FDA digital health guidance, EU AI Act risk classifications, and China's NMPA algorithmic medical device rules collectively reshape product development roadmaps and market access requirements for health-adjacent digital offerings. GDPR and CSRD disclosure mandates in Europe force data governance architecture redesigns that cascade into global product standards. Stakeholders must monitor divergent regulatory timelines across Washington, Brussels, and Beijing to avoid compliance fragmentation that inflates engineering overhead.
Market Dynamics
Enterprise workload migration toward sovereign cloud infrastructure is compressing vendor margins while fragmenting procurement across national data residency requirements. The EU AI Act's risk-classification system and China's NMPA algorithmic medical device rules are forcing parallel product development tracks that inflate engineering overhead.
Growth Catalysts
- FDA Digital Health Guidance:The agency's pre-certification pathway for software-as-medical-device accelerates time-to-market for AI-enabled diagnostics in the United States.
- Healthcare Cloud Migration:Hospital systems in Germany and France are consolidating electronic health records onto GDPR-compliant sovereign infrastructure, creating sustained demand for localized compute capacity.
- Edge Inference Deployment:Retail supply chains in China are distributing AI workloads to store-level edge nodes to achieve sub-50 millisecond transaction latency for real-time inventory optimization.
Market Restraints
- Custom Silicon Cost Concentration:Hyperscale providers' backward integration into ARM-based server processors is raising barriers for second-tier cloud vendors dependent on merchant silicon.
- Cross-Border Data Friction:China's Cybersecurity Law and data localization requirements fragment global SaaS architectures, forcing redundant infrastructure deployment.
- Quantum-Safe Migration Uncertainty:NIST's post-quantum cryptography standards timeline remains unresolved, freezing long-term security architecture decisions for financial services infrastructure.
Strategic Opportunities
- India's Data Center Expansion:The country's Digital Personal Data Protection Act and PLI scheme for IT hardware are attracting sovereign cloud investments from European and Asian operators.
- AI-Blockchain Convergence:Supply chain provenance applications are integrating machine learning inference with immutable ledger verification for pharmaceutical cold-chain monitoring.
- Embedded Finance APIs:Non-financial platforms in Brazil and Mexico are embedding regulated payment services through open-banking frameworks, creating new distribution channels for cloud-native fintech infrastructure.
Industry Challenges
- Multicloud Orchestration Talent Scarcity:Platform engineering skills for Kubernetes-native workload portability command premium compensation, constraining mid-market enterprise adoption.
- EU AI Act Compliance Timelines:High-risk system providers face 24-month implementation windows for conformity assessment procedures that lack accredited third-party bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Market |
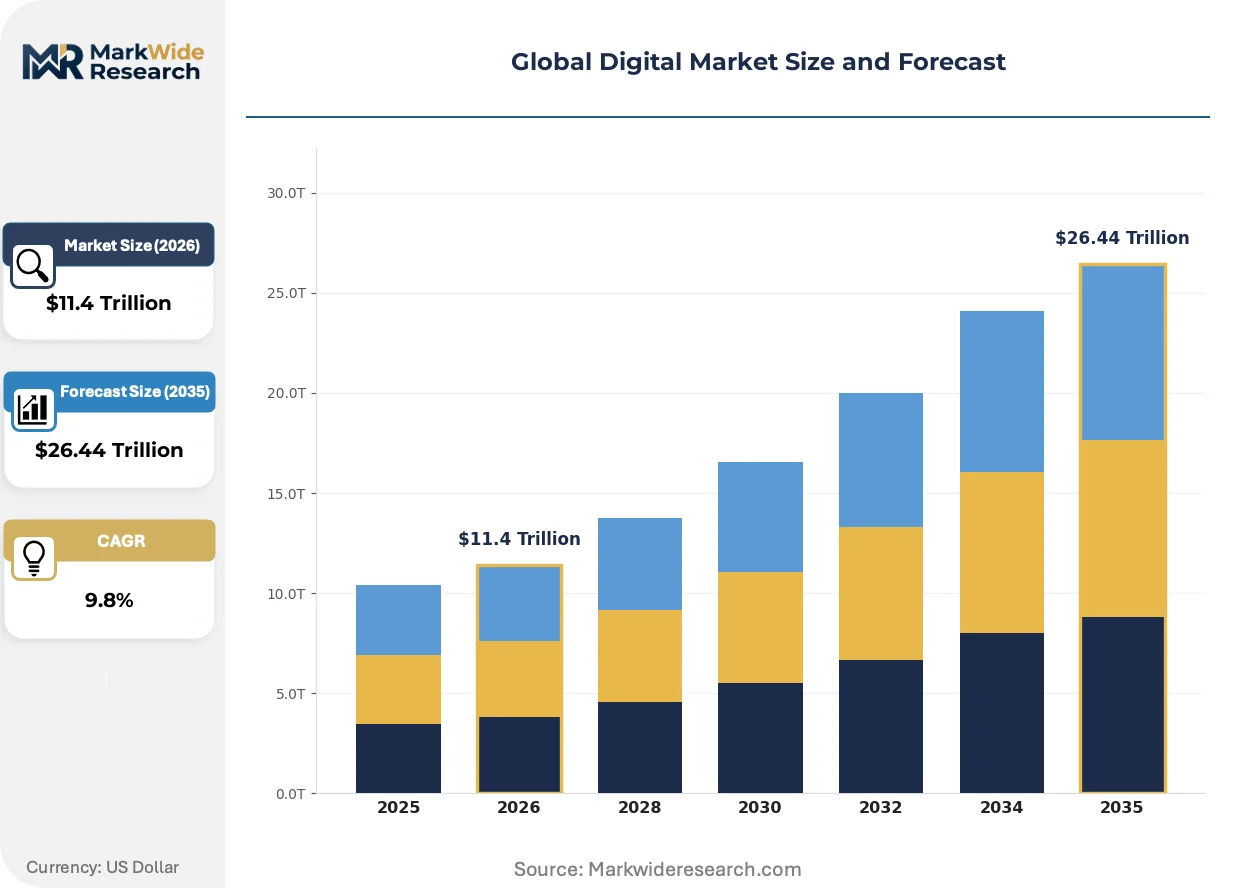
| Market Size in 2026 | $11.4 Trillion |
| Market Size in 2035 | $26.44 Trillion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Applications, Platforms, Services Customer Type: Enterprises, SMEs, Individual Users, Freelancers Service Type: Consulting, Support, Development, Implementation Technology: Cloud Computing, AI, Blockchain, IoT |
| Companies Covered | Amazon, Alibaba Group, Pinduoduo, JD.com, Taobao, Tmall, Shopify, Shopee, Sea Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Market Emerging Trajectories
Generative AI inference workloads are redistributing compute demand from centralized training clusters toward distributed edge deployment. This architectural shift is compressing hardware refresh cycles and fragmenting vendor relationships across the stack.
Foundation model deployment is bifurcating between hyperscale API access and on-premises fine-tuning for regulated industries. Healthcare systems in Germany and financial institutions in Switzerland are prioritizing in-house model adaptation to satisfy GDPR and FINMA data governance requirements. This split is forcing infrastructure vendors to maintain dual product lines with diverging margin structures.
The EU AI Act's risk-tier classification system is mandating conformity assessments for high-risk applications including biometric identification and credit scoring. Medical device manufacturers are restructuring quality management systems to accommodate both MDR and AI Act compliance simultaneously. This regulatory layering is most acute in France and the Netherlands where notified bodies face capacity constraints.
Enterprise software procurement is consolidating around outcome-based consumption metrics rather than per-seat licensing. Industrial manufacturers in Japan and automotive suppliers in South Korea are negotiating contracts tied to production throughput or supply chain visibility outcomes. This shift is most visible in Germany's Mittelstand sector where CFOs demand clearer ROI linkages for SaaS expenditure.
Global Digital Market Segmentation
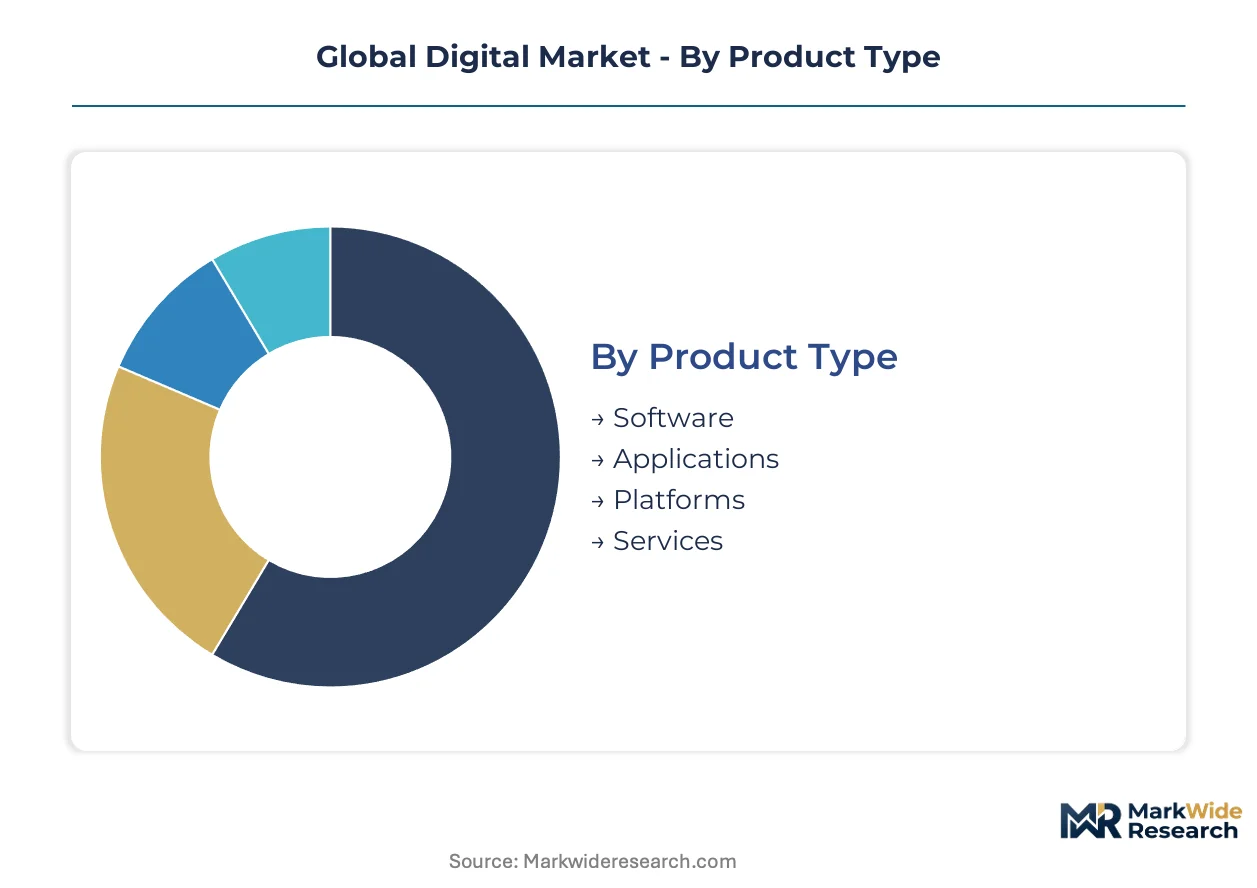
Segmentation in the Global Digital Market reveals how procurement priorities diverge across buyer sophistication, regulatory exposure, and workload criticality. Understanding these fault lines helps vendors calibrate pricing architecture and compliance investment.
Product Type:
Platform and services segments face acute substitution pressure from vertically integrated hyperscale providers bundling infrastructure with software.
- Platforms:Cloud-native orchestration layers enabling workload portability across sovereign and edge nodes. Hospital systems in Germany and France are consolidating procurement here to satisfy GDPR data residency mandates while containing vendor fragmentation.
- Services:Professional and managed services supporting migration, integration, and ongoing optimization. Financial institutions in Switzerland prioritize these offerings to bridge internal talent gaps for FINMA-compliant AI deployment.
- Software:Standalone applications delivered via SaaS or perpetual licensing models.
- Applications:Purpose-built solutions for specific business functions or vertical workflows.
Platforms retain volume leadership; Services holds the steepest expansion curve as enterprises outsource complexity.
Customer Type:
Cost tier stratification separates buyers by procurement sophistication and compliance burden rather than absolute spend scale.
- Enterprises:Large organizations with dedicated procurement functions negotiating outcome-based contracts tied to production throughput or supply chain visibility. Germany's Mittelstand sector increasingly mimics this behavior despite mid-market scale.
- SMEs:Small and medium enterprises seeking standardized solutions with minimal customization requirements. These buyers in India and Brazil are accelerating cloud adoption through sovereign data center expansions and open-banking API integration.
- Individual Users:Solo practitioners and consumers purchasing productivity or creative tools directly.
- Freelancers:Independent contractors assembling multi-tool stacks for project-based work.
Enterprises dominate current revenue; SMEs are climbing the fastest as digitization penetrates mid-market supply chains.
Service Type:
Application context determines which service lines capture margin—implementation for greenfield deployments versus support for regulated operational continuity.
- Consulting:Strategic advisory for cloud architecture, data governance, and regulatory compliance. Demand concentrates where EU AI Act and China's NMPA rules force parallel product development tracks.
- Development:Custom engineering for API extensibility and workflow automation. Retail supply chains in China leverage these services to deploy store-level edge inference for inventory optimization.
- Support:Ongoing technical assistance and maintenance for deployed solutions.
- Implementation:Deployment and integration services for new technology rollouts.
Consulting captures premium pricing; Development shows the sharpest demand acceleration as AI inference workloads multiply.
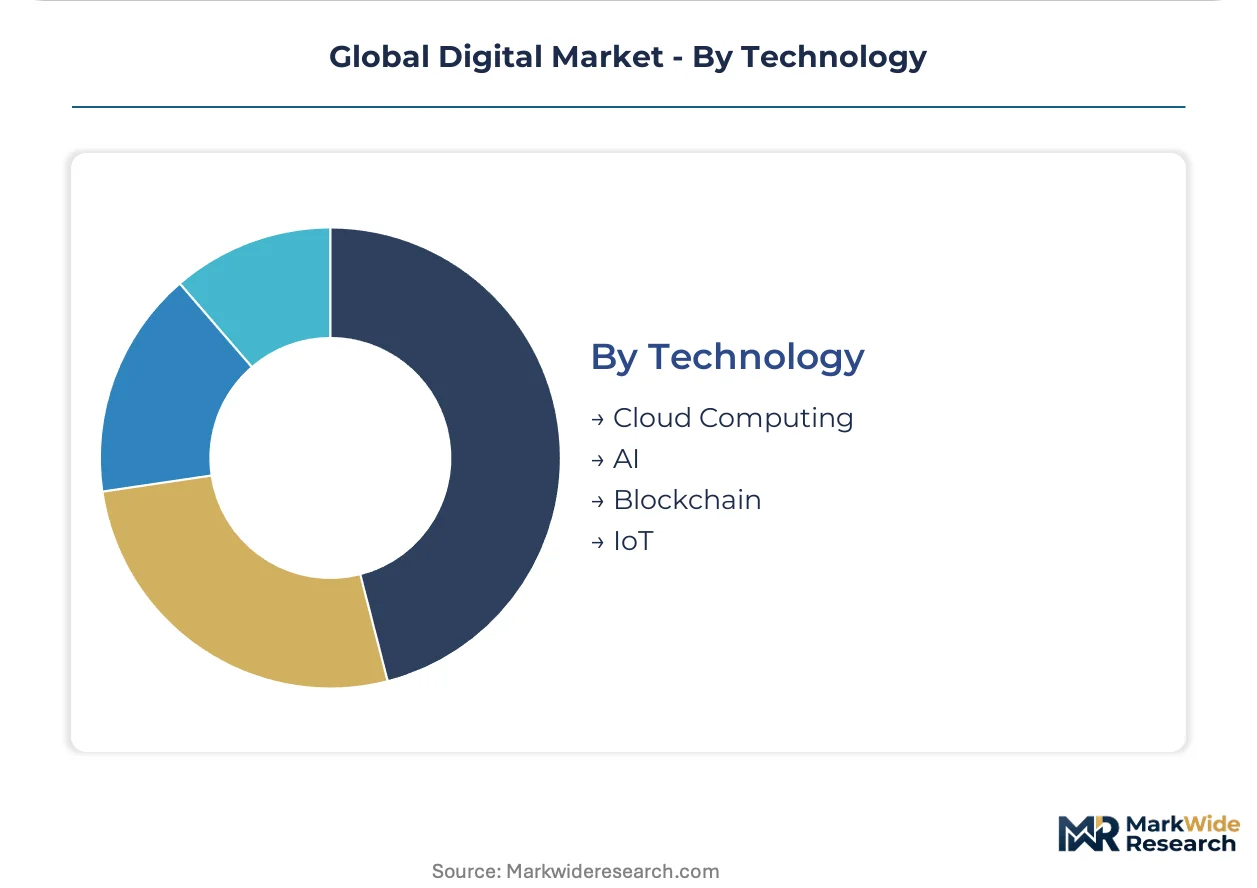
Technology:
Supply concentration in custom silicon and foundation model training infrastructure is reshaping competitive access across technology lanes.
- Cloud Computing:Distributed infrastructure for workload orchestration from centralized data centers to edge nodes. Sovereign deployments in Germany, France, and India are fragmenting procurement across national residency requirements.
- AI:Machine learning inference and training systems redistributing compute demand toward distributed edge deployment. Healthcare systems prioritize in-house fine-tuning to satisfy GDPR and FINMA data governance requirements.
- IoT:Connected device networks enabling real-time data collection and automated response.
- Blockchain:Distributed ledger technology concentrated in cross-border settlement and pharmaceutical cold-chain provenance applications.
Cloud Computing maintains installed base dominance; AI exhibits the most rapid share gain as generative workloads commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center capacity clusters in the United States, Germany, and China as sovereign cloud requirements fragment procurement across national boundaries. Enterprise workload migration concentrates in jurisdictions with clear data residency frameworks. Regulatory divergence between Washington, Brussels, and Beijing forces parallel infrastructure deployment strategies.
United States
FDA digital health pre-certification pathways accelerate AI-enabled diagnostic deployment across hospital systems. The SEC's climate disclosure rules and state-level privacy laws in California and New York reshape data governance architectures for financial services. Northern Virginia's data center corridor anchors hyperscale expansion as cloud providers backward integrate into custom silicon and fiber networks.
Germany
Hospital systems consolidate electronic health records onto GDPR-compliant sovereign infrastructure, creating sustained demand for localized compute. The EU AI Act's risk-classification system mandates conformity assessments for high-risk biometric and credit-scoring applications. Frankfurt's financial data hub and Munich's industrial cloud clusters drive edge deployment for automotive and machinery supply chains.
China
Retail supply chains distribute AI inference workloads to store-level edge nodes for sub-50 millisecond inventory optimization. The NMPA's algorithmic medical device rules and Cybersecurity Law data localization requirements fragment global SaaS architectures. Shenzhen's hardware ecosystem and Hangzhou's commerce-to-cloud linkages anchor domestic platform concentration.
India
The Digital Personal Data Protection Act and PLI scheme for IT hardware attract sovereign cloud investments from European and Asian operators. RBI's data localization mandates for payment systems force redundant infrastructure deployment. Mumbai's financial services corridor and Bangalore's SaaS startup cluster drive mid-market enterprise adoption.
Switzerland
Financial institutions prioritize in-house foundation model fine-tuning to satisfy FINMA data governance requirements. FINMA's outsourcing guidelines and the country's non-EU GDPR alignment create premium pricing for compliant infrastructure. Zurich's private banking technology centers and Geneva's commodity trading platforms anchor specialized cloud demand.
Global Digital Market Vendor Landscape
Concentration sits with vertically integrated hyperscale providers bundling infrastructure with software layers. The vendor base separates into three distinct tiers: custom silicon-owning hyperscalers, commerce-platform-linked cloud operators, and API-specialist merchant enablers. M&A activity targets edge computing assets and sovereign data center footprints. Strategic partnerships between hardware fabricators and software platforms accelerate workload portability solutions.
Within the hyperscale tier, Amazon anchors North American capacity through captive silicon and fiber investments. Alibaba Group occupies a parallel position in Asia-Pacific commerce-to-cloud linkages. Shopify exemplifies the API-specialist archetype by concentrating on merchant extensibility rather than infrastructure ownership. These three represent divergent strategic bets on where value capture concentrates in distributed digital infrastructure.
| Leading Market Players |
|---|
| Amazon |
| Alibaba Group |
| Pinduoduo |
| JD.com |
| Taobao |
| Tmall |
| Shopify |
| Shopee |
| Sea Limited |
| Others |
Supply Flow & Price Mechanics
Hyperscale capacity utilization in Northern Virginia, Frankfurt, and Shenzhen creates asymmetric scale economies that compress unit economics for second-tier cloud vendors while elevating price floors for sovereign-compliant deployments. This concentration dynamic simultaneously fragments procurement across national data residency mandates and inflates engineering overhead for parallel compliance tracks.
Pricing Analysis
The EU AI Act's risk-classification system dictates the pricing tier structure across high-risk biometric systems, limited-risk chatbots, and minimal-risk productivity tools. Three-tier pricing structure across premium sovereign-compliant, standard commercial, and economy merchant-silicon levels separates buyers by data governance burden and latency requirements. Cost compression in the standard tier is intensifying because hyperscalers' backward integration into ARM-based processors raises barriers for merchant-silicon-dependent vendors. SMEs in India and Brazil exhibit the sharpest price sensitivity, while financial institutions in Switzerland and hospital systems in Germany absorb premium pricing for FINMA and GDPR-aligned infrastructure.
Supply Chain Analysis
Container availability constraints across the Shanghai-Rotterdam and Shenzhen-Long Beach trade lanes expose hyperscale hardware procurement to logistics chokepoint risks. Custom silicon fabrication concentrates in Taiwan, South Korea, and the United States, while fiber optic cable and server chassis manufacturing anchors in China and Mexico. Supply chains draw from advanced-node semiconductors, rare earth elements for magnetics, and specialized cooling fluids. Single-source vulnerability in EUV lithography equipment creates systemic concentration risk. Distribution runs through direct hyperscale procurement channels and tier-one systems integrators serving regulated enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Market rewards defensive moats built on regulatory entrenchment and customer switching costs. Network effects from commerce-to-cloud data flywheels and API ecosystem lock-in create durable competitive positioning for established platforms.
For Market Incumbents: Shield installed base relationships by accelerating sovereign cloud certification investments in Germany, France, and India before EU AI Act conformity assessment deadlines tighten. Prioritize backward integration into custom silicon and captive fiber networks to defend margin position against merchant-silicon-dependent challengers. Lock in hospital systems and financial institutions through outcome-based contracts tied to production throughput or compliance automation metrics.
For New Entrants and Emerging Players: Anchor in edge inference deployment for retail supply chains in China and embedded finance API integration in Brazil and Mexico where open-banking frameworks reduce regulatory friction. Target mid-market manufacturers in Germany's Mittelstand sector seeking clearer ROI linkages for SaaS expenditure. Pursue Kubernetes-native workload portability solutions that command premium compensation and address multicloud orchestration talent scarcity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors with healthcare and financial services vertical specialization where GDPR, FINMA, and FDA compliance requirements create switching-cost moats. Long-term viability favors acquisition targets with sovereign data center footprints in India and Switzerland plus demonstrated conformity assessment capabilities for EU AI Act high-risk systems. Monitor NIST post-quantum cryptography standardization timelines as an inflection signal for financial services infrastructure refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem lock-in captures merchant extensibility revenue pools from mid-market retailers. |
| Sovereign Cloud Certification | GDPR and EU AI Act alignment opens procurement channels with German hospital systems. |
| Backward Integration into Silicon | Captive ARM processor supply reduces dependency on merchant semiconductor vendors. |
| Edge Node Deployment | Sub-50 millisecond latency positions inventory optimization for Chinese retail supply chains. |
| Strategic Partnership | Healthcare system alliances accelerate FDA pre-certification for AI-enabled diagnostics. |
Methodological Framework
Initial hypotheses were tested against primary input from CTOs, platform engineers, IT procurement officers, and integration specialists and refined through secondary validation. Hyperscaler capex disclosures, SEC filings, EU regulatory submissions, and hospital procurement databases anchored quantitative sizing. Bottom-up build-ups from workload migration patterns and top-down cross-checks against national data center capacity announcements ensured triangulation integrity.
Variance decomposition across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Foundation model inference demand curves, sovereign infrastructure investment pipelines, and regulatory implementation timelines fed industry-specific forecast inputs throughout the projection horizon.
Material uncertainties — NIST post-quantum cryptography standardization delays, EU AI Act notified body capacity constraints, and China's Cybersecurity Law enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions about enterprise workload migration velocity and hyperscale capacity expansion cadence. Practitioners should keep alternative scenarios live as regulatory divergence across Washington, Brussels, and Beijing evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Micro Market
Others
Wearable AI Market
Others
Global Transparent Plastics Market
Others
Global Telemetry Market
Others
Industrial Gauges Market
Others
Linseed Oil Market
Others
Lined Tank Market
Others
Global Duty-Free Retailing Market
Others
Ammeters Market
Others
Convertible Shipper Display Market
Others
Security Envelopes Market
Others
Metal Air Battery Market
Others
Ceramic Machinery Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Mini Pcs Market
Others
Buchner Funnels Market