
 Global Augmented Reality in Retail Market | 2026-2036
Global Augmented Reality in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Reality in Retail Market Analysis
The in-store digital experience layer is reconfiguring how retailers convert foot traffic into transactions. Google leverages its ARCore platform to anchor cloud-based spatial computing across thousands of partner stores. Microsoft sustains enterprise-grade mixed reality infrastructure that competes with consumer-facing deployments. Apple controls the premium device pipeline through tight hardware-software integration in its retail ecosystem.
Augmented Reality in Retail overlays computer-generated imagery onto physical store environments through camera-equipped smartphones, headsets, or projection systems, typically operating at 60 frames per second with sub-10 millisecond motion-to-photon latency to prevent user disorientation. The technology serves commercial purposes by collapsing the gap between digital browsing and physical inspection, letting shoppers manipulate three-dimensional product models at true scale before purchase. Markerless tracking leads the technology dimension because it eliminates dependency on printed visual codes, while virtual fitting commands the highest margins within the application segment by reducing return rates for fashion retailers. Product visualization is maturing fastest in furniture outlets where room-scale spatial mapping has become technically reliable.
The EU AI Act imposes risk-classification obligations on AR systems that process biometric data in European retail environments, forcing vendors to document algorithmic decision pathways. The FDA has begun scrutinizing optical display systems for ocular safety thresholds, while China's SAMR enforces GB standards on electromagnetic emissions from head-mounted retail devices. Stakeholders must monitor which regulator moves first on immersive commerce liability frameworks.
Market Dynamics
The retail AR sector pivots on algorithmic transparency mandates cascading from Brussels to national capitals, forcing vendors to reengineer biometric processing pipelines while hardware makers race to certify optical systems under divergent safety regimes.
Growth Catalysts
- EU AI Act compliance services:Risk-classification documentation for biometric AR systems creates a captive consulting revenue stream for European system integrators.
- Markerless SLAM advancement:Simultaneous localization and mapping without printed markers collapses deployment friction in flagship store rollouts.
- China's SAMR electromagnetic standards:Head-mounted device certification requirements accelerate domestic supply chain maturation for export-ready manufacturers.
Market Restraints
- Optical component concentration:Waveguide manufacturing clusters in Taiwan and South Korea create single-source vulnerability for Western headset vendors.
- FDA ocular safety thresholds:Extended exposure limits for near-eye displays delay product launches by 8-14 months for US-bound hardware.
- Smartphone AR substitution:Camera-based spatial computing on existing devices caps enterprise willingness to fund dedicated headset procurement.
Strategic Opportunities
- India's PLI scheme extension:Electronics manufacturing incentives now cover AR hardware assembly, attracting contract manufacturers to Gujarat and Tamil Nadu clusters.
- Pharmacy retail visualization:Over-the-counter medication packaging AR overlays remain undeployed across European and North American drugstore chains.
- LiDAR-to-photogrammetry convergence:Apple's sensor arrays and NeRF rendering pipelines enable room-scale furniture placement without dedicated scanning hardware.
Industry Challenges
- Spatial computing talent scarcity:Computer vision engineers with retail UX specialization command premium compensation in San Francisco, London, and Shenzhen labor markets.
- Legacy POS integration complexity:ERP systems from the 2010s lack API architectures for real-time inventory synchronization with AR visualization layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Reality in Retail Market |
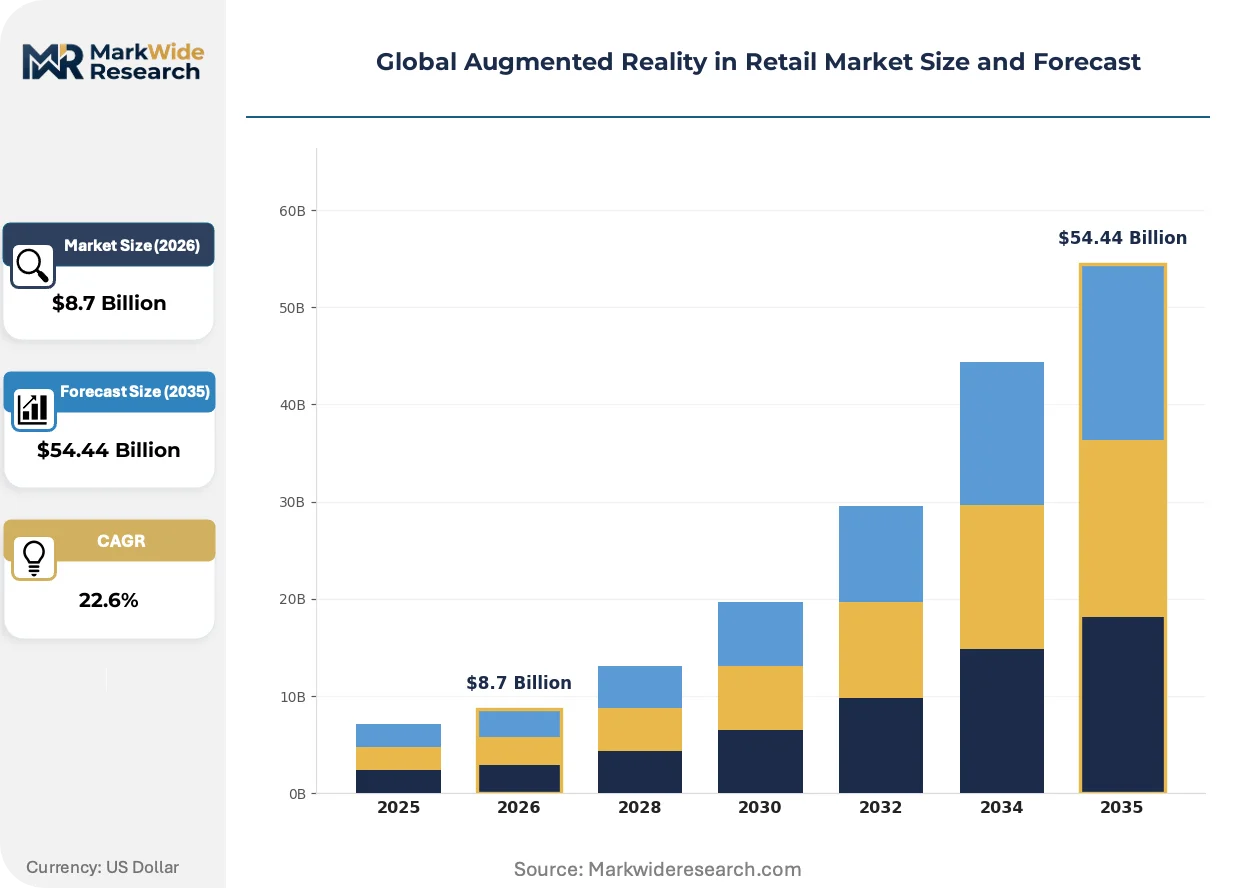
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $54.44 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Marker-based, Markerless, Projection-based, Superimposition End User: Fashion Retailers, Electronics Stores, Furniture Outlets, Grocery Chains Application: Virtual Fitting, Product Visualization, In-Store Navigation, Interactive Displays Solution: Software Development, Hardware Integration, Custom Solutions, Content Creation |
| Companies Covered | PTC, Google, Microsoft, Apple, Snap Inc., Magic Leap, Niantic, Vuforia, Blippar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Reality in Retail Market Emerging Trajectories
Spatial computing is migrating from novelty deployment to infrastructure layer, with cloud-rendering pipelines and edge-compute nodes now treated as critical retail technology investments rather than experimental budgets.
Cloud-native AR rendering is virtualizing the computational burden of photorealistic product visualization. Department store chains in Germany and Japan now stream high-polygon furniture models from AWS and Azure edge locations rather than processing locally. This architecture is virtualizing the hardware requirements for immersive commerce, enabling smartphone-grade devices to deliver headset-quality spatial experiences.
The EU AI Act's risk-tier framework is forcing biometric data processors to publish algorithmic decision trees for European deployments. AR vendors serving fashion retail must now document how body-scanning measurements translate to size recommendations. French and Italian luxury houses face the steepest compliance burdens given their reliance on personalized fit algorithms in flagship boutiques.
Buyers now expect seamless handoff between digital browsing and physical inspection without redundant data entry. German automotive retailers report that customers initiating AR vehicle configuration on mobile devices abandon purchases when showroom staff cannot access their saved preferences. This friction is compressing vendor selection criteria toward platforms with unified identity layers spanning web, app, and in-store touchpoints.
Global Augmented Reality in Retail Market Segmentation
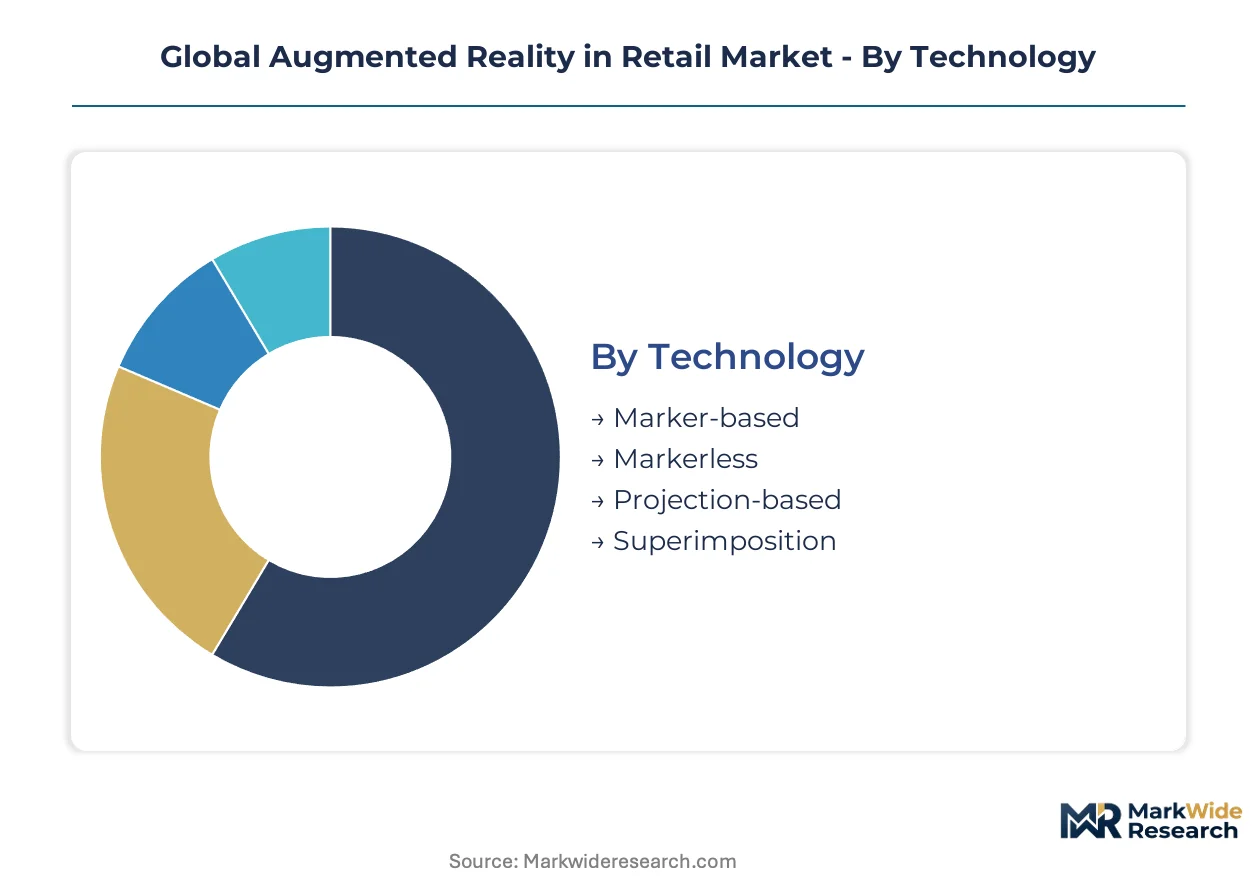
Retail AR deployments fragment across distinct technical architectures and commercial use cases, each carrying different capital intensity profiles and payback horizons. Understanding segment velocity helps vendors allocate R&D resources between proven revenue streams and emerging application areas.
Technology:
Cycle times vary dramatically across tracking methodologies, with camera-based approaches refreshing every 12-18 months while optical waveguide hardware extends to 36-month development horizons.
- Markerless:Simultaneous localization and mapping algorithms eliminate printed visual codes, enabling spontaneous deployment in flagship stores. Demand concentrates among German automotive retailers and Japanese department stores seeking frictionless customer onboarding without physical infrastructure investment.
- Marker-based:Printed fiducial markers anchor spatial registration through computer vision pattern recognition. Electronics stores in Shenzhen and Seoul leverage this mature stack for high-reliability product demonstrations where environmental control is guaranteed.
- Projection-based:Spatial light modulation projects synthetic imagery directly onto physical surfaces without wearable hardware. Grocery chains in France experiment with shelf-edge overlay systems for dynamic pricing displays.
- Superimposition:Real-time object replacement renders digital alternatives over physical product placements. Furniture outlets in the United States deploy this for finish and fabric visualization on existing showroom samples.
Markerless tracking anchors the volume base while projection-based systems gain share at the steepest rate.
End User:
Margin structures diverge sharply across retail verticals, with fashion commanding premium implementation fees while grocery operates on thin per-location economics.
- Fashion Retailers:Body-scanning algorithms and size recommendation engines drive the highest per-deployment value. Italian and French luxury houses invest heavily in flagship boutique installations to reduce return rates on high-margin garments.
- Furniture Outlets:Room-scale spatial mapping enables true-scale product placement visualization. IKEA and West Elm deployments across Germany and the United States demonstrate proven ROI through reduced delivery returns.
- Electronics Stores:Specification overlay and feature comparison tools dominate this segment. Chinese consumer electronics chains use AR to communicate technical differentiation in crowded smartphone and appliance showrooms.
- Grocery Chains:Nutritional information and origin storytelling overlays remain nascent. European supermarket pilots focus on fresh produce provenance visualization to justify premium pricing tiers.
Furniture outlets anchor the volume base while fashion retailers gain share at the steepest rate.
Application:
Customer-facing utility determines deployment priority, with transaction-adjacent applications receiving capital allocation ahead of experiential enhancements.
- Virtual Fitting:Biometric measurement pipelines translate body scans into size recommendations with sub-centimeter accuracy. Apparel chains in the United States and China report measurable return rate reductions driving platform investment.
- Product Visualization:Photorealistic 3D rendering enables manipulation of digital twins at true scale. German furniture retailers stream high-polygon models from edge compute nodes to customer smartphones.
- In-Store Navigation:Spatial wayfinding guides shoppers to shelf locations through camera-overlay directional cues. Large-format grocery and electronics stores in Japan deploy this to reduce staff assistance requests.
- Interactive Displays:Gesture-controlled product exploration creates engagement metrics without direct transaction linkage. Department stores use these for brand storytelling in cosmetic and fragrance departments.
Product visualization anchors the volume base while virtual fitting gains share at the steepest rate.
Solution:
Revenue recognition patterns separate recurring software subscriptions from one-time hardware and content deliverables.
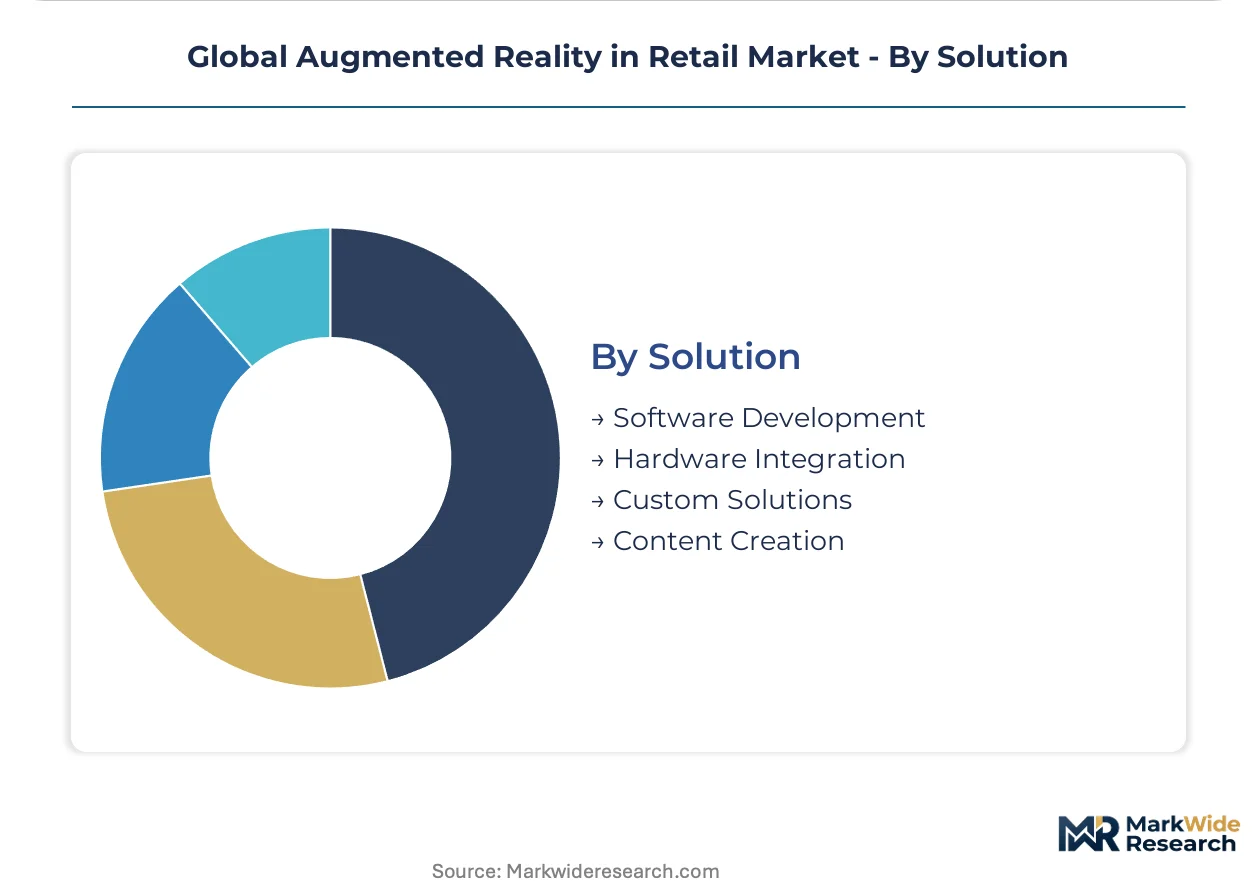
- Software Development:SDK licensing and platform-as-a-service models generate predictable annual recurring revenue. ARCore and proprietary engine deployments span thousands of retail locations across the United States and India.
- Content Creation:3D asset pipelines and photogrammetry services command project-based fees. Fashion retailers commission seasonal collection digitization on 6-8 week production cycles.
- Hardware Integration:Headset procurement, sensor installation, and network configuration deliver one-time implementation revenue. Chinese manufacturing clusters supply waveguide components to Western system integrators.
- Custom Solutions:Bespoke application development addresses unique retail workflows and legacy system constraints. European luxury houses commission tailored fit algorithms protected as trade secrets.
Software development anchors the volume base while content creation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border fiber optic corridors and submarine cable landings in Portugal, Spain, and France underpin Europe's data throughput capacity for cloud-rendered AR experiences. Dense 5G base station grids in Seoul-Tokyo-Shenzhen triangle cities enable sub-20 millisecond latency for real-time spatial computing.
United States
Fashion retailers in Los Angeles and New York deploy body-scanning algorithms to reduce return rates on high-margin garments. FDA ocular safety thresholds for near-eye displays extend hardware certification timelines by 8-14 months. Seattle and San Francisco Bay Area clusters concentrate platform engineering talent for ARCore and proprietary spatial computing stacks.
Germany
Automotive retailers in Munich and Stuttgart use AR vehicle configurators to compress sales cycles for premium electric models. EU AI Act risk-classification mandates force biometric data processors to document algorithmic decision pathways. Berlin hosts system integrators specializing in compliance documentation for European luxury house deployments.
China
Electronics chains in Shenzhen and Shanghai leverage marker-based tracking for high-reliability smartphone demonstrations in controlled showroom environments. SAMR electromagnetic standards for head-mounted devices accelerate domestic supply chain maturation. Guangdong manufacturing clusters produce waveguide components for export-ready headset vendors.
Japan
Department stores in Tokyo and Osaka stream high-polygon furniture models from AWS and Azure edge nodes to customer smartphones. METI industrial policy supports spatial computing R&D consortia for retail applications. Nagoya engineering centers develop simultaneous localization and mapping algorithms for frictionless flagship store onboarding.
India
Contract manufacturers establish AR hardware assembly operations in Gujarat and Tamil Nadu under PLI scheme incentives. Electronics manufacturing incentives now cover component sourcing for headset vendors targeting export markets. Bangalore software development centers produce SDK licensing and platform-as-a-service models for recurring revenue streams.
Global Augmented Reality in Retail Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in optical waveguide and sensor manufacturing. The vendor base separates into consolidated platform operators with cloud infrastructure leverage and fragmented hardware fabricators competing on assembly cost. Three archetypes dominate: cloud-rendering platform owners, optical component suppliers, and vertical retail solution developers. Competitive moves concentrate on strategic partnerships between platform licensors and luxury retail houses, plus capacity expansion in Indian and Vietnamese contract manufacturing.
Within the platform integrator tier, Google and Microsoft exemplify cloud-native spatial computing architectures that virtualize hardware requirements for immersive commerce. Magic Leap occupies a position in the premium headset segment where optical waveguide manufacturing complexity creates defensive moats. These three anchors illustrate how software platform control, enterprise infrastructure depth, and specialized hardware design each generate distinct competitive positioning in retail AR deployment.
| Leading Market Players |
|---|
| PTC |
| Microsoft |
| Apple |
| Snap Inc. |
| Magic Leap |
| Niantic |
| Vuforia |
| Blippar |
| Others |
Supply Flow & Price Mechanics
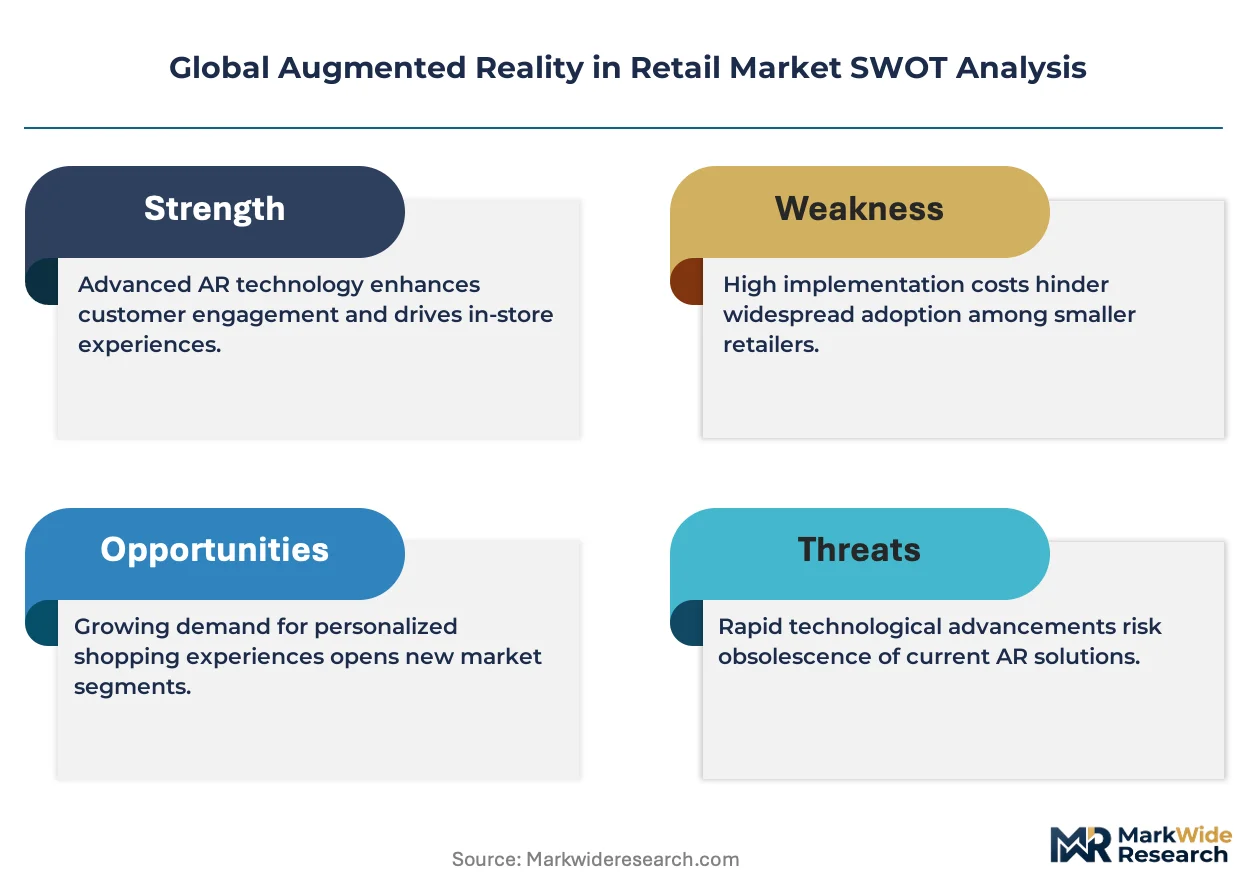
Optical waveguide manufacturing concentration in Taiwan and South Korea creates single-source vulnerability that compresses margin tiers for Western headset vendors while simultaneously forcing tiered pricing spreads based on component certification grade and volume commitments.
Pricing Analysis
Volume-discount tiering structures separate enterprise flagship deployments from mid-market retail chains and pilot-scale implementations. Pricing stratifies across premium, standard, and economy tiers based on SDK licensing depth and edge-compute provisioning. Cost compression in the standard tier is intensifying because Chinese contract manufacturers are scaling AR hardware assembly under India's PLI scheme incentives. Grocery chains exhibit highest price sensitivity due to thin per-location economics, while French and Italian luxury houses accept premium positioning for bespoke biometric fit algorithms.
Supply Chain Analysis
Upstream feedstock for optical waveguides draws from rare-earth processing facilities in China and specialized glass-melting operations in Japan and Germany. Waveguide substrates, MEMS scanning mirrors, and LiDAR sensor arrays constitute critical component dependencies. Single-source vulnerability concentrates in Taiwanese semiconductor packaging for spatial computing chipsets. Distribution runs through system integrators in Berlin and San Francisco Bay Area clusters before reaching retail deployment sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across compliance documentation services, pharmacy retail visualization, and LiDAR-to-photogrammetry convergence creates niche entry points as EU AI Act mandates splinter vendor requirements by risk classification tier.
For Market Incumbents: Entrench cloud-rendering platform control by certifying optical systems under FDA ocular safety thresholds ahead of competitors, while backward integration into waveguide component sourcing mitigates Taiwanese supply concentration risk. Capacity addition in Indian Gujarat and Tamil Nadu clusters secures cost-advantaged hardware assembly for export markets. For New Entrants and Emerging Players: Establish a beachhead in pharmacy retail visualization across European and North American drugstore chains, where over-the-counter medication packaging AR overlays remain undeployed. India's PLI scheme extension for electronics manufacturing offers the most penetrable geography for contract manufacturing entry. Go-to-market positioning should emphasize SAMR pre-certified hardware for re-export to Western markets. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertical retail solution developers with documented EU AI Act risk-classification pipelines. Long-term viability hinges on platform owners capturing recurring SDK licensing revenue rather than one-time hardware margins. Watch for FDA optical safety clearance timelines as inflection indicator for US market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Rendering Platform Integration | AWS and Azure edge nodes enable smartphone-grade devices to deliver headset-quality spatial experiences for German furniture retailers. |
| EU AI Act Compliance Documentation | System integrators in Berlin capture captive consulting revenue from French and Italian luxury houses requiring algorithmic transparency. |
| LiDAR-to-Photogrammetry Convergence | Apple's sensor arrays and NeRF rendering pipelines eliminate dedicated scanning hardware for room-scale furniture placement. |
| India PLI Scheme Manufacturing Expansion | Gujarat and Tamil Nadu clusters attract contract manufacturers targeting export-ready headset assembly for Western vendors. |
| Pharmacy Retail Visualization Deployment | European and North American drugstore chains represent undeployed white-space for over-the-counter medication packaging AR overlays. |
Methodological Framework
A spread of perspectives from platform engineering directors at cloud hyperscalers, procurement leads at German automotive retailers, regulatory affairs specialists navigating EU AI Act implementation, and optical component sourcing managers at Taiwanese waveguide manufacturers converged on the working assumptions. Primary interview insights were cross-validated against secondary sources including FDA 510(k) optical device filings, SAMR electromagnetic certification databases, EU AI Act delegated act drafts, and hyperscaler capex disclosures for edge-compute infrastructure. Bottom-up deployment counts by retail vertical were triangulated against top-down platform revenue estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning tracking methodology, retail vertical, customer-facing application, and solution revenue model. CAGRs were derived from installed base expansion rates and per-deployment value trajectories. Industry-specific forecast inputs included EU AI Act compliance cost pass-through assumptions and FDA optical safety certification timeline distributions for near-eye display hardware.
Stress conditions across waveguide supply disruption scenarios, EU AI Act enforcement intensity gradients, and smartphone AR substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about markerless SLAM algorithm maturation and cloud-rendering latency thresholds. Cross-checking against hyperscaler edge-compute deployment announcements and retail chain flagship rollout timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
IoT Testing Market
Others
Bird Food Market
Others
North America Machine Vision Systems Market
Others
North America Smart Homes Market
Others
Small Office Home Office (SOHO) Servers Market
Others
High Frequency Vibrator Market
Others
Latin America Travel Retail Market
Others
Banknote Printing Machine Market
Others
United States Indoor LBS Market
Others
Cat Food Market
Others
Global Maritime Freight Transport Market
Others
Global Supply Chain Risk Management Software Market
Others
Solar Animal Repellent Market
Others
Process Instrumentation Equipment Market
Others
Middle East and Africa Surface Analysis Market
Others
Video Encoder Market