
 Photo Booth/Kiosk Market | 2026-2036
Photo Booth/Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Booth/Kiosk Market Analytics
Software-defined photo delivery and cloud-based gallery subscriptions is repositioning vendor economics from one-time hardware sales toward recurring revenue streams. Foto Master leverages proprietary animation software to command premium placement in high-traffic entertainment venues. Photo-Me International anchors its competitive stance through extensive self-service kiosk networks across European retail locations. Apple Industries differentiates with durable steel-frame construction and modular component architecture suited for high-frequency commercial deployment.
A photo booth or kiosk constitutes an automated imaging terminal integrating digital camera sensors, touchscreen interfaces, instant dye-sublimation printers, and optional augmented reality overlays into a self-contained enclosure or open-air rig. These systems serve commercial and social purposes by capturing, processing, and distributing photographic content without dedicated operator attendance. Open-air kiosk configurations now capture the dominant share of new installations, as venues prioritize spatial flexibility and group accommodation over enclosed booth footprints. Augmented reality technology represents the fastest-expanding capability segment, though instant printing retains the deepest margin pool through proprietary media and consumable lock-in. Temporary setup installations lead volume in the event-driven segment, while permanent fixture deployments generate superior lifetime value in retail and hospitality footprints.
FCC certification governs wireless transmission modules in US-deployed units, while CE marking and GDPR compliance shape product design for European market access. Japan's METI energy-efficiency guidelines additionally influence power-supply specifications for kiosk systems sold into that market. Stakeholders must weigh biometric privacy legislation momentum against hardware refresh investments, as regulatory fragmentation threatens to complicate cross-border product standardization and deployment scalability.
Market Dynamics
Software-defined photo delivery is decentralizing hardware value toward recurring cloud subscriptions, forcing manufacturers to rebuild revenue models around data services rather than unit sales.
Growth Catalysts
- GDPR-compliant data workflows:European privacy mandates compel vendors to engineer consent-first capture systems, creating competitive differentiation for compliant hardware.
- Dye-sublimation instant printing:Proprietary media lock-in generates consumable revenue streams that subsidize hardware deployment costs across wedding and corporate verticals.
- Experiential retail clusters:United Kingdom and Japan destination-event spending sustains refresh demand for open-air kiosk configurations in high-traffic venues.
Market Restraints
- Biometric privacy fragmentation:Emerging state-level legislation in multiple US jurisdictions forces redundant engineering cycles that complicate cross-border product standardization.
- Camera sensor supply concentration:Dependence on concentrated semiconductor fabrication creates input cost volatility and extended lead times for kiosk manufacturers.
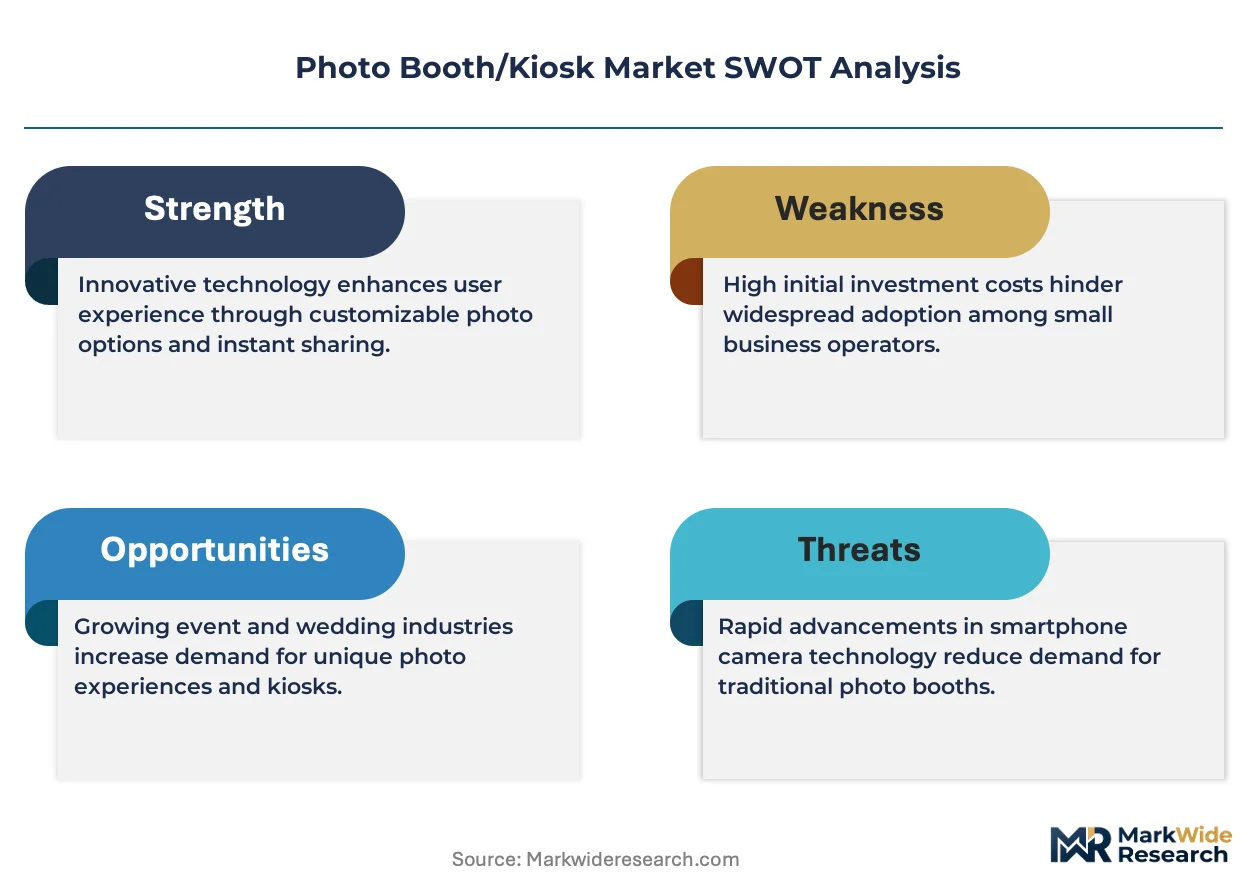
- Smartphone substitution threat:Native AR filters and instant sharing capabilities on personal devices erode the unique value proposition of dedicated capture terminals.
Strategic Opportunities
- Underpenetrated German hospitality:Boutique hotel and restaurant segments show latent demand for permanent fixture deployments with lifetime value superior to temporary event setups.
- CE marking as market access tool:Harmonized European compliance standards enable scaled distribution across member states without country-by-country certification duplication.
- AR-printing convergence:Integration of augmented reality overlays with physical output creates hybrid experiences that smartphones cannot replicate natively.
Industry Challenges
- FCC certification timelines:Wireless transmission module approval for US-deployed units extends product launch windows and strains working capital.
- Legacy venue integration:Retrofitting open-air configurations into established enclosed booth footprints demands custom mechanical engineering and site-specific installation protocols.
- Cloud architecture talent scarcity:Shortage of engineers with parallel expertise in embedded imaging systems and subscription platform development constrains vendor pivot speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Booth/Kiosk Market |
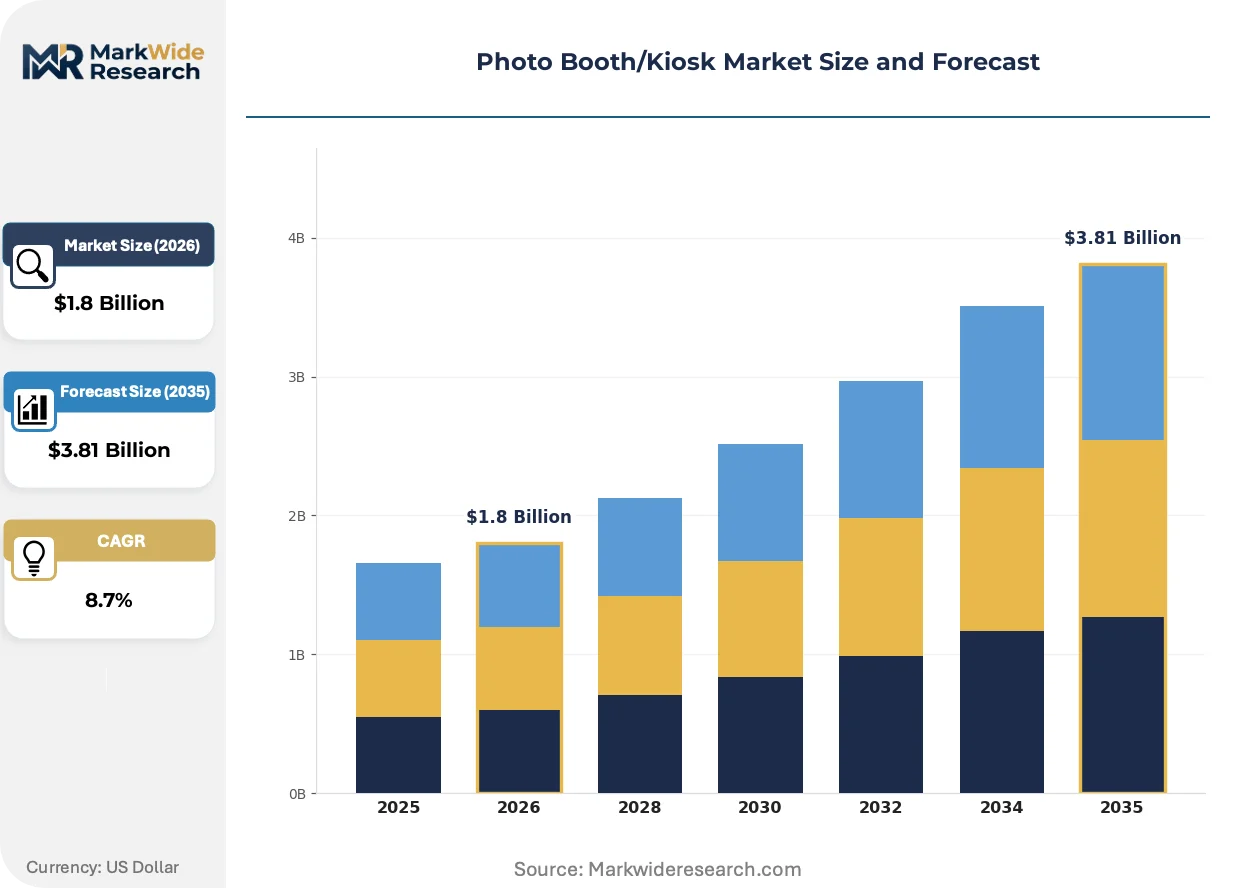
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Booth, Open-Air Kiosk, Selfie Station, Virtual Booth Technology: Digital Cameras, Touchscreen, Instant Printing, Augmented Reality End User: Event Planners, Retailers, Hospitality, Corporate Clients Installation: Temporary Setup, Permanent Fixture, Mobile Unit, DIY Configurations |
| Companies Covered | Foto Master, Faceplace, Photobooth Supply Co., Apple Industries, Innovative Foto, Photo-Me International, ATA Photo Booths, Olea Kiosks Inc, DC PhotoBooths, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Booth/Kiosk Market Evolving Landscape
Three forces are compressing the traditional hardware-centric model: cloud-native delivery architectures, biometric privacy engineering, and procurement preference for flexible deployment formats.
Edge-compute image processing is decentralizing post-capture workflows from centralized servers to kiosk-embedded GPUs. Wedding planners and corporate event coordinators now demand real-time filter rendering without latency-dependent internet connectivity. This shift is compressing vendor margins on cloud storage upsells while elevating importance of on-device silicon specifications.
GDPR and emerging US state biometric statutes are mandating consent-first capture protocols with automated deletion triggers. Manufacturers must engineer dual-stack firmware supporting both European data-localization requirements and American state-by-state privacy variations. Kiosk operators in Germany and France face the steepest compliance engineering burden due to CNIL enforcement precedents and cross-border data transfer restrictions.
Event-driven buyers now prioritize temporary setup flexibility over permanent fixture investments, compressing hardware depreciation cycles. Rental channel intermediaries capture growing share of venue procurement, displacing direct manufacturer relationships. United Kingdom experiential retail clusters show the most pronounced shift toward short-term deployment contracts with bundled operator service packages.
Photo Booth/Kiosk Market Segmentation
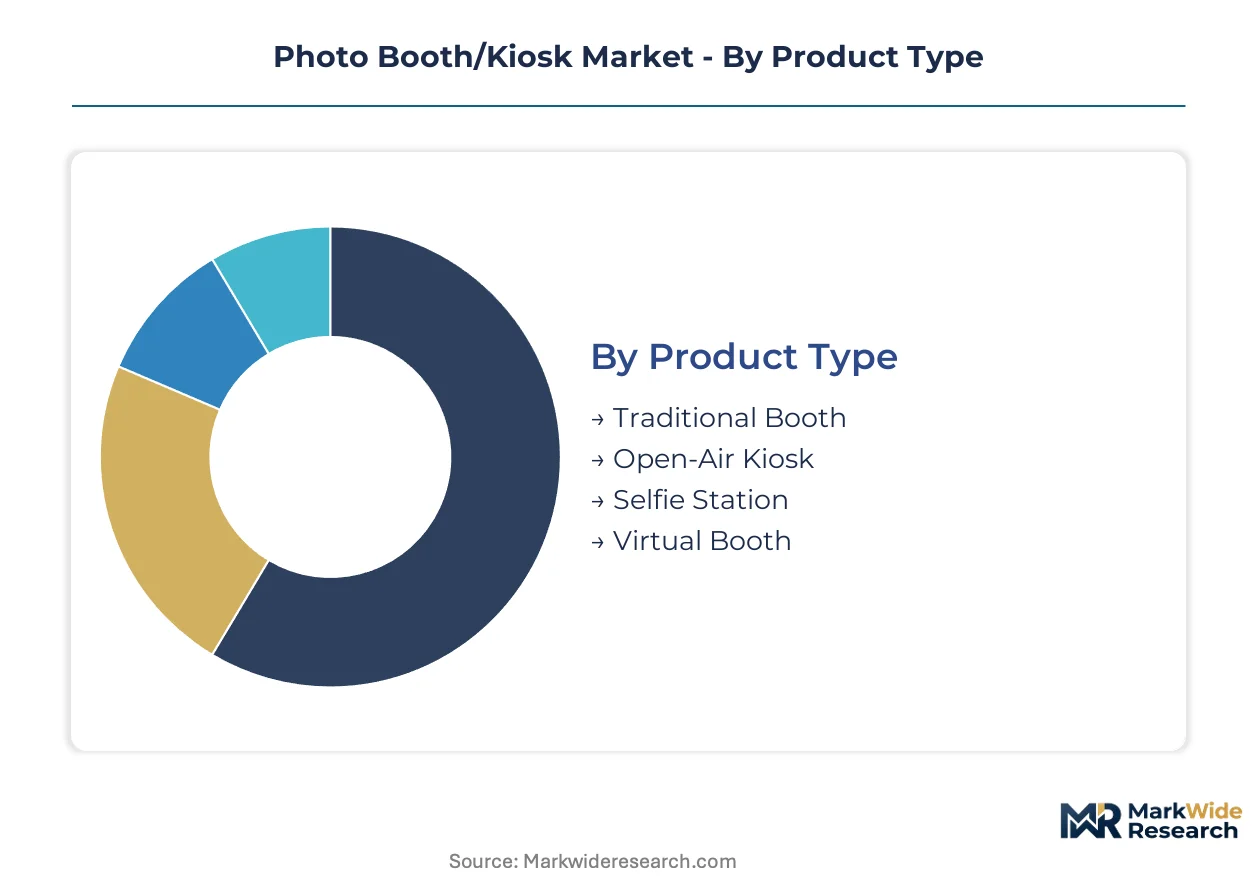
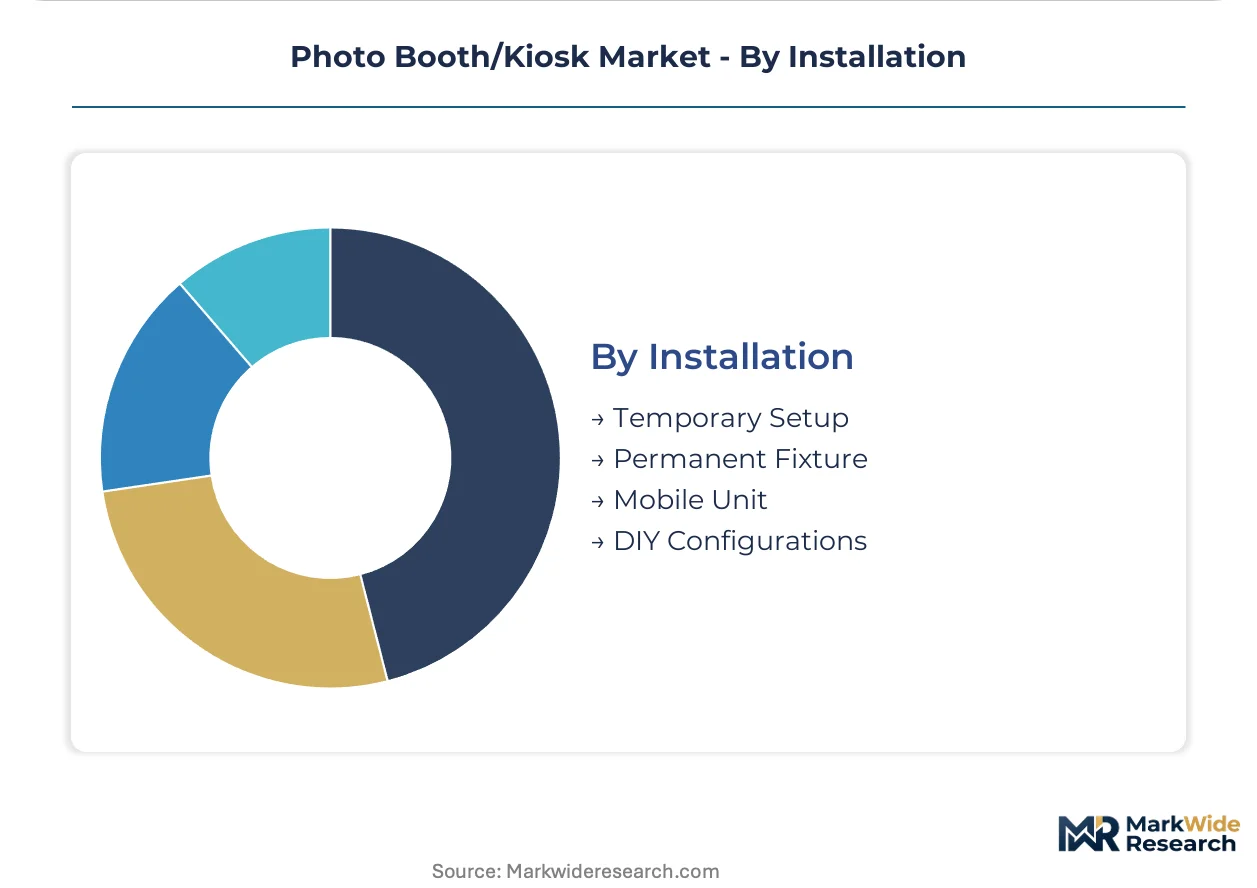
Segmentation in the photo booth and kiosk market reveals how hardware configurations, software capabilities, and deployment models align with distinct buyer economics. Vendors must balance standardized platform architectures against venue-specific customization demands across four intersecting dimensions.
Product Type:
Customization intensity varies sharply across this category, from fully enclosed proprietary designs to modular open-air systems that venues reconfigure per event.
- Open-Air Kiosk:These systems deploy camera arrays on adjustable stands with backdrop flexibility rather than fixed enclosures. Wedding planners in the United Kingdom and corporate event coordinators in Germany now specify these configurations for group photography and spatial adaptability in historic venues with footprint constraints.
- Traditional Booth:Enclosed cabin designs with integrated seating and controlled lighting deliver consistent output quality regardless of ambient conditions. Boutique hotels in Japan maintain preference for these fixtures in permanent lobby installations where guest privacy and climate control matter.
- Selfie Station:Compact tablet-based terminals with front-facing cameras and ring-light arrays occupy minimal floor space. These units target high-traffic retail environments where rapid throughput outweighs production value.
- Virtual Booth:Software-only solutions leveraging user smartphones for capture with cloud-based processing and AR overlay delivery. This format eliminates hardware logistics entirely for distributed corporate events and remote participation scenarios.
Leading the category by volume: Open-Air Kiosk. Expanding most quickly: Virtual Booth.
Technology:
Margin profiles diverge across this category between capital-intensive hardware components and recurring software licensing streams.
- Augmented Reality:Real-time filter rendering, background replacement, and 3D overlay insertion demand GPU acceleration at the edge. Event planners in experiential retail clusters now require these capabilities as table stakes, compressing vendor differentiation timelines.
- Instant Printing:Dye-sublimation engines with proprietary media cartridges generate consumable revenue that subsidizes hardware placement costs. The lock-in economics here sustain profitability across wedding and corporate verticals despite upfront equipment depreciation.
- Digital Cameras:CMOS sensor modules with fixed or interchangeable lens options determine baseline image quality specifications. Supply concentration in semiconductor fabrication creates input cost volatility for manufacturers sourcing these components.
- Touchscreen:Capacitive interface panels ranging from 10-inch portrait orientations to 32-inch landscape formats govern user interaction flow. These components face commodity pricing pressure from tablet market scale.
Deepest margin pool: Instant Printing. Steepest capability expansion: Augmented Reality.
End User:
Procurement authority and decision speed vary dramatically across this category, from centralized corporate purchasing to fragmented individual event contracts.
- Event Planners:These buyers prioritize temporary deployment flexibility and bundled operator services over equipment ownership. United Kingdom destination-event spending sustains refresh demand through rental channel intermediaries that displace direct manufacturer relationships.
- Corporate Clients:Brand activation teams and human resources departments seek measurable engagement metrics and lead capture integration. GDPR-compliant data workflows have become mandatory evaluation criteria for European deployment decisions.
- Hospitality:Hotels, restaurants, and entertainment venues evaluate lifetime value against upfront capital commitment for permanent fixture installations. The German boutique hotel segment shows latent demand with superior returns compared to temporary event setups.
- Retailers:Experiential marketing teams in high-traffic locations deploy kiosks for dwell-time extension and social media amplification. Japan's METI energy-efficiency guidelines influence power-supply specifications for these continuously operating units.
Highest contract frequency: Event Planners. Longest sales cycles: Corporate Clients.
Installation:
Depreciation treatment and working capital requirements separate this category into asset-light service models and capital-intensive infrastructure commitments.
- Temporary Setup:Rental-based deployment with delivery, installation, operation, and removal bundled into single-event pricing. This model dominates volume in the event-driven segment while compressing hardware refresh cycles.
- Permanent Fixture:Hardwired installations with electrical, data, and physical security integration into venue infrastructure. These deployments generate superior lifetime value in retail and hospitality footprints despite extended payback periods.
- Mobile Unit:Trailer-mounted or vehicle-integrated systems with self-contained power and climate control for outdoor deployment. Festival circuits and seasonal attractions in France drive demand for these configurations.
- DIY Configurations:Unassembled kit formats with customer-managed installation and operator training. Price-sensitive buyers in secondary markets accept quality trade-offs for acquisition cost reduction.
Widest margin compression: Temporary Setup. Steepest lifetime value: Permanent Fixture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication clusters concentrate in East Asia, while experiential retail deployment and privacy-driven software customization dominate demand in Western Europe and Japan. This production-consumption divide shapes vendor supply chain configurations and compliance engineering priorities.
United States
Wedding planners and corporate event coordinators in California and New York Metro drive hardware refresh cycles for open-air kiosk configurations. FCC certification timelines for wireless transmission modules extend product launch windows and strain manufacturer working capital. Austin and Nashville hospitality clusters show rising permanent fixture demand despite biometric privacy fragmentation across state jurisdictions.
United Kingdom
Experiential retail spending in London and Manchester sustains rental channel growth for temporary event deployments. GDPR-compliant data workflows with CNIL-aligned consent-first capture protocols have become mandatory for venue procurement decisions. Edinburgh and Birmingham destination-event clusters increasingly specify bundled operator service packages over direct equipment purchases.
Germany
Boutique hotel segments in Bavaria and North Rhine-Westphalia exhibit latent demand for permanent fixture installations with superior lifetime value. CE marking enables scaled distribution across member states without country-by-country certification duplication. Berlin and Hamburg corporate event coordinators prioritize GDPR-engineered hardware with automated deletion triggers for brand activation deployments.
Japan
METI energy-efficiency guidelines influence power-supply specifications for continuously operating retail kiosks in Tokyo and Osaka. Destination-event spending in Kyoto and Fukuoka sustains refresh demand for traditional enclosed booth configurations in permanent hospitality installations. Chubu region manufacturing clusters supply precision touchscreen components for domestic and export markets.
France
Festival circuits in Provence-Alpes-Côte d'Azur and Occitanie drive mobile unit demand for trailer-mounted outdoor deployments. ANSM and CNIL enforcement precedents impose the steepest compliance engineering burden for biometric data handling among European markets. Paris experiential retail clusters lead adoption of augmented reality overlay capabilities in high-traffic venue installations.
Photo Booth/Kiosk Market Competitive Landscape
Top-tier vendors anchor premium positioning through proprietary software and extensive kiosk networks, while mid-tier fabricators compete on modular hardware flexibility and regional service density. The vendor base organizes around three strategic archetypes: animation-software specialists commanding entertainment venue placement, steel-frame construction experts targeting high-frequency commercial deployment, and self-service network operators leveraging retail footprint scale. Dominant competitive moves include strategic partnerships with rental channel intermediaries and portfolio diversification into cloud-based gallery subscriptions.
Among the named players, Foto Master and Photo-Me International occupy positions at opposite ends of the value chain spectrum. Foto Master exemplifies the software-differentiated archetype through its proprietary animation platform, while Photo-Me International represents the network-scale model with extensive European retail presence. Apple Industries sits within the durability-focused tier, with steel-frame construction credentials suited for permanent commercial installations. These three anchors illustrate how vendor economics are pivoting from one-time hardware sales toward recurring revenue architectures.
| Leading Market Players |
|---|
| Foto Master |
| Faceplace |
| Photobooth Supply Co. |
| Apple Industries |
| Innovative Foto |
| Photo-Me International |
| ATA Photo Booths |
| Olea Kiosks Inc |
| DC PhotoBooths |
| Others |
Value Network & Pricing Analysis
Dye-sublimation thermal print heads and proprietary media cartridges cascade through three pricing tiers as they move from East Asian fabrication plants to wedding rental channels and permanent hospitality installations across Germany and Japan. CMOS sensor modules and capacitive touchscreen panels concentrate upstream with semiconductor foundries, compressing margins for kiosk assemblers while consumable lock-in economics downstream subsidize hardware placement costs.
Pricing Analysis
Margin tightening in mid-tier hardware reflects camera sensor supply concentration and extended lead times from concentrated semiconductor fabrication. Three-tier pricing structure across premium animation-software bundles, standard open-air configurations, and economy selfie stations separates vendors by GPU acceleration capabilities and GDPR-engineered firmware. Pricing pressure stems from smartphone substitution threat eroding unique value proposition of dedicated capture terminals. Event planners exhibit highest price sensitivity through rental channel intermediaries, while corporate clients prioritize compliance certification over unit cost.
Supply Chain Analysis
CE marking and FCC certification gate market access before components reach assembly lines, forcing redundant engineering cycles for cross-border deployment. Hardware fabrication clusters concentrate in China, Japan, and South Korea, with Chubu region supplying precision touchscreen components and domestic sensor modules feeding regional kiosk manufacturers. Supply chains draw from concentrated CMOS sensor sources, proprietary dye-sublimation media, and GPU acceleration silicon, creating single-source vulnerability in semiconductor inputs. Distribution runs through rental channel intermediaries capturing growing venue procurement share, displacing direct manufacturer relationships in United Kingdom experiential retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR data-handling obligations and emerging US state biometric privacy rules construct a cost-of-compliance barrier that favors incumbents with engineering resources to navigate regulatory fragmentation, punishing undercapitalized entrants unable to fund dual-stack firmware development.
For Market Incumbents: Lock in consumable revenue streams through proprietary dye-sublimation media lock-in that subsidizes hardware deployment costs against smartphone substitution threat. Deepen backward integration into GPU acceleration silicon and edge-compute modules to compress cloud dependency and defend margin position from software-defined delivery disruption. Prioritize certification investment for CE marking and emerging state-level biometric compliance to create regulatory moats.
For New Entrants and Emerging Players: AR-printing convergence technology offers entry wedge into experiential retail clusters where hybrid physical-digital experiences resist smartphone replication. Target underpenetrated German boutique hospitality segment with permanent fixture deployments generating superior lifetime value against temporary event setup competition. Pursue white-label operator service bundling as go-to-market angle, displacing direct equipment purchases through rental channel partnerships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-differentiated specialists with proprietary animation platforms in United Kingdom and Japanese destination-event clusters where experiential spending remains resilient. Long-term viability hinges on recurring revenue architecture transition completion within the analysis window. Watch cloud-native delivery adoption rates as inflection indicator separating hardware-locked vendors from platform-scale winners.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Firmware Development | CNIL enforcement precedents in France and cross-border data restrictions mandate consent-first capture systems with automated deletion triggers. |
| Cloud-Native Gallery Platform Launch | Recurring subscription revenue repositioning counters one-time hardware sales erosion from smartphone substitution pressure. |
| Proprietary Animation Software Acquisition | Foto Master's GPU-accelerated filter rendering commands premium placement in high-traffic entertainment venues. |
| Rental Channel Partnership Expansion | United Kingdom event planners increasingly specify bundled operator service packages over direct equipment procurement. |
| Edge-Compute Silicon Integration | On-device GPU processing compresses latency for real-time AR rendering without internet dependency at wedding and corporate deployments. |
Research Methodology
SEC filings from kiosk manufacturers and component suppliers, trade customs data for CMOS sensor and dye-sublimation media flows, and METI energy-efficiency guideline documentation formed the secondary backbone. Primary interviews with wedding planning directors, corporate event coordinators, hotel procurement managers, and photo booth rental operators combined with secondary validation through FCC certification databases and GDPR enforcement precedent analysis. Bottom-up unit shipment estimates and top-down experiential retail spending triangulation anchored market sizing across the projection horizon.
Bottom-up modeling deployed product type, technology capability, end user vertical, and installation format segmentation dimensions throughout the forecast period. CAGRs derived from hardware refresh cycle analysis, cloud subscription adoption curves, and regulatory compliance investment trajectories. Forecast inputs incorporated biometric privacy legislation momentum and camera sensor supply lead time volatility specific to kiosk manufacturing.
Several conditions sit outside the modeled scope, including sudden smartphone AR capability breakthroughs eliminating dedicated hardware value proposition and catastrophic semiconductor supply disruption extending beyond current lead time assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and venue experiential spending resilience. A model refresh is warranted upon material change in US state biometric privacy legislation adoption velocity or GDPR cross-border data transfer restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sports Events Market
Others
Global Digital Market
Others
GCC Health and Wellness Market
Others
Global Military Wearable Sensors Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Military Wearable Market
Others
High-Performance Films Market
Others
Global Hardware Acceleration Market
Others
Automatic Barriers and Bollards Market
Others
Durian Market
Others
Canada Laser Hair Removal Market
Others
Software Synthesizers Market
Others
Europe Indoor Air Purification Market
Others
Aerospace Tester Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Global Smart Kitchen Market