
 Aerospace Software Testing Market | 2026-2036
Aerospace Software Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Software Testing Market Insights
Buyer concentration among defense contractors and space technology firms is rebalancing as commercial airframe manufacturers fragment demand across specialized avionics suppliers. Parasoft leverages deep static analysis capabilities to anchor North American market presence. Vector Informatik dominates European model-based testing workflows through embedded systems specialization. Rapita Systems differentiates via DO-178C certification tooling for safety-critical aerospace codebases.
Aerospace software testing encompasses verification and validation protocols for flight-critical code, avionics firmware, and embedded control systems operating under DO-178C, DO-330, and ARP4754A guidelines; engineers execute static analysis, dynamic profiling, and hardware-in-the-loop simulation to detect runtime anomalies before deployment in autonomous flight control and satellite navigation architectures. Automated testing approaches absorb the fastest investment growth as manufacturers replace manual regression cycles with continuous integration pipelines. Avionics testing software captures concentrated margin pools where certification-grade toolchains command premium positioning against commoditized performance monitoring segments.
FAA mandates through DO-178C and EASA's adoption of ED-12C shape tool selection criteria across OEM supply chains, while EU AI Act emerging provisions force algorithmic transparency audits into next-generation autonomous flight systems. China's MIIT and NMPA are developing parallel certification frameworks for commercial drone and urban air mobility software stacks. Stakeholders must monitor divergence between Western safety-critical standards and Chinese domestic GB compliance pathways as export controls reshape cross-border testing tool licensing.
Market Dynamics
DO-178C certification requirements are compressing validation timelines while forcing defense contractors and commercial OEMs to rebuild testing infrastructure around automated continuous integration pipelines rather than manual verification cycles.
Growth Catalysts
- DO-178C Mandate Intensification:FAA and EASA enforcement of ED-12C guidelines compels flight control system vendors to expand verification budgets. Certification-grade toolchains capture premium positioning against legacy manual testing approaches.
- Urban Air Mobility Proliferation:Autonomous eVTOL developers in Germany and the United States require dedicated avionics testing protocols for beyond-visual-line-of-sight operations. Hardware-in-the-loop simulation demand concentrates around Munich and Stuttgart engineering clusters.
- Model-Based Design Adoption:Embedded systems engineers are replacing handwritten code with auto-generated C from MATLAB/Simulink workflows. This shift multiplies validation complexity and drives specialized tooling procurement.
Market Restraints
- Specialized Engineering Talent Scarcity:DO-178C-qualified verification engineers command compensation premiums that inflate project costs. Training pipelines at German technical universities and US aerospace institutes cannot match contractor demand velocity.
- Hardware-in-the-Loop Capital Intensity:Full flight simulator rigs and FPGA-based emulation platforms require seven-figure capital commitments. Mid-tier avionics suppliers face exclusion from certification-grade testing capabilities.
- Export Control Licensing Friction:US ITAR and EU dual-use regulations restrict testing toolchain transfer to Chinese aerospace programs. Western vendors forfeit revenue from COMAC and eVTOL developers building to GB standards.
Strategic Opportunities
- AI-Assisted Test Generation:Large language models trained on aerospace codebases are automating test case derivation from requirements specifications. Vector Informatik and specialized startups are integrating these capabilities into embedded workflows.
- Satellite Constellation Scale:Starlink competitors and national programs require standardized software validation across distributed spacecraft architectures. Batch testing protocols for firmware updates present white-space tooling demand.
- EU AI Act Algorithmic Auditing:Emerging transparency mandates for autonomous decision systems create verification service opportunities. Flight control AI modules now require explainability documentation alongside traditional safety cases.
Industry Challenges
- Multi-Core Processor Certification Complexity:DO-178C was architected for single-core deterministic execution. Avionics engineers struggle to demonstrate temporal isolation on modern many-core chips from NXP and Infineon.
- Legacy System Integration Friction:Thirty-year-old avionics buses like ARINC 429 must interface with Ethernet-based modern architectures. Testing protocols must span heterogeneous technology generations without compromising safety integrity levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Software Testing Market |
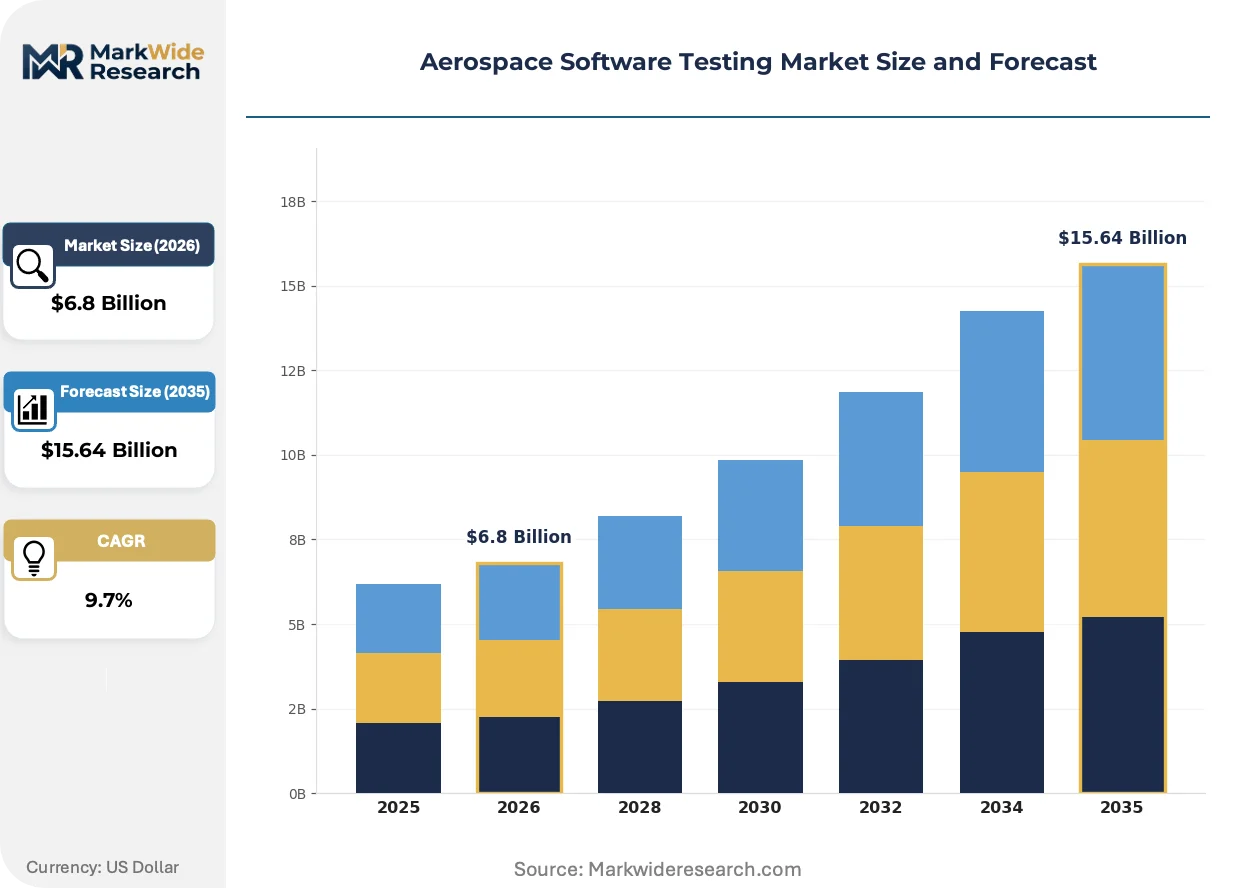
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Flight Simulation Software, Avionics Testing Software, Navigation System Validation, Safety Compliance Tools, Performance Monitoring Software Testing Approach: Manual Testing, Automated Testing, Model-Based Testing, Static Analysis, Dynamic Analysis, Regression Testing Application Area: Control Systems, Communication Interfaces, Embedded Systems, Data Processing Units, Software Integration, Fault Tolerance Evaluation End User Type: Airframe Manufacturers, Avionics Suppliers, Defense Contractors, Space Technology Firms, Flight Operation Centers |
| Companies Covered | Parasoft, Rapita Systems, QualiTest, Vector Informatik, National Instruments, General Digital, Intertek Group plc, Element Materials Technology, MISTRAS Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Software Testing Market Trends and Innovations
Digital twin architectures are displacing physical prototype dependency across flight software validation, compressing development cycles while expanding simulation fidelity requirements for aerodynamic and electromagnetic interaction modeling.
Hardware-in-the-loop platforms are integrating FPGA-based processor emulation to execute actual flight software binaries against simulated sensor inputs. Major defense contractors in the United States and Germany are adopting these systems for regression testing of autonomous flight control modules. This integration is compressing the validation timeline from months to weeks for software updates.
The EU AI Act's algorithmic transparency provisions are forcing aerospace OEMs to document decision pathways within neural network-based flight systems. EASA is developing guidance for machine learning component certification that parallels traditional DO-178C assurance levels. European urban air mobility developers face the steepest compliance curve as they integrate computer vision into navigation stacks.
Continuous integration pipelines are displacing staged waterfall validation for avionics software releases. Tier-one suppliers now demand automated regression suites that execute thousands of test vectors overnight. This behavioral shift is most visible in Germany's automotive-aerospace convergence corridor, where Vector Informatik's embedded tooling expertise transfers directly to flight system workflows.
Aerospace Software Testing Market Segmentation
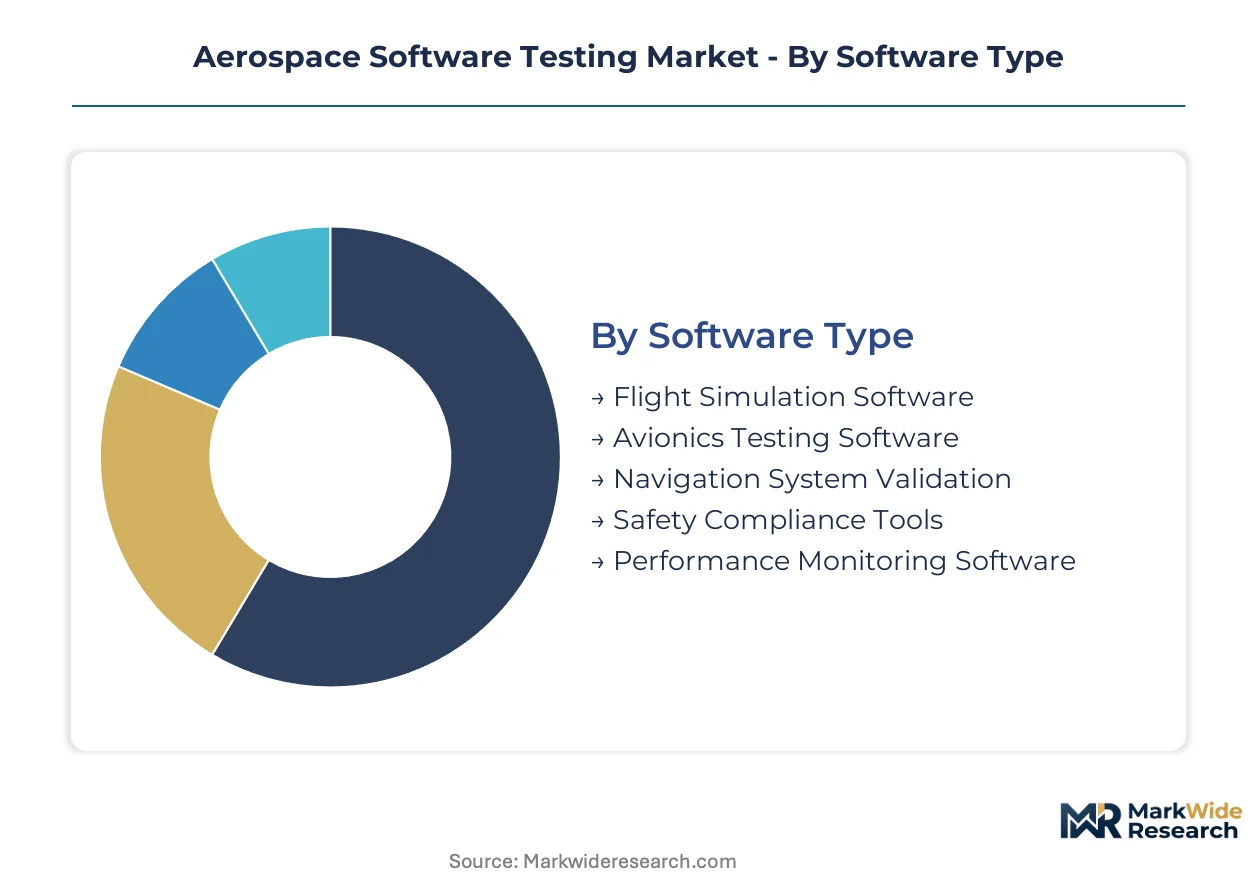
Aerospace software testing segments diverge sharply by capital requirements and certification complexity. Flight control systems demand seven-figure hardware-in-the-loop investments, while performance monitoring tools operate on subscription SaaS models with minimal infrastructure.
Software Type:
Capital intensity peaks where certification-grade toolchains require dedicated engineering teams and regulatory pre-approval from FAA or EASA.
- Flight Simulation Software:High-fidelity aerodynamic modeling environments replicate atmospheric conditions, sensor failures, and emergency scenarios. Demand concentrates at Boeing and Airbus engineering centers in Seattle and Toulouse, driven by new aircraft program validation requirements.
- Avionics Testing Software:DO-178C certification toolchains execute static analysis, code coverage measurement, and requirements traceability. German defense contractors in Bavaria and Baden-Württemberg anchor European procurement, compelled by ED-12C enforcement timelines.
- Navigation System Validation:GPS/GNSS signal simulation for satellite-based augmentation systems.
- Safety Compliance Tools:Automated documentation generators for certification artifacts.
- Performance Monitoring Software:Runtime telemetry analysis for fleet-wide anomaly detection.
Avionics Testing Software absorbs the bulk of installed capacity; Flight Simulation Software is expanding most quickly.
Testing Approach:
Automation penetration varies inversely with legacy system dependency, as handwritten ARINC 429 interfaces resist continuous integration migration.
- Automated Testing:Continuous integration pipelines execute regression suites overnight, replacing manual verification cycles. SpaceX and Blue Origin facilities in Texas and Florida drive adoption, compelled by rapid iteration schedules for reusable launch systems.
- Model-Based Testing:Auto-generated test vectors from MATLAB/Simulink state machines validate embedded control logic. Stuttgart automotive-aerospace engineering clusters anchor German demand, transferring automotive validation expertise to urban air mobility developers.
- Manual Testing:Engineer-led inspection of certification artifacts and edge-case exploration.
- Static Analysis:Automated source code scanning for runtime error detection without execution.
- Dynamic Analysis:Runtime profiling of memory usage and execution paths in simulated environments.
- Regression Testing:Systematic re-validation of unchanged code against modified dependencies.
Automated Testing commands the largest share of new investment; Model-Based Testing climbs the fastest as auto-generated code proliferates.
Application Area:
Margin concentration tracks safety integrity level, with DO-178C Level A systems commanding premium pricing against Level C diagnostic tools.
- Control Systems:Flight-critical autopilot and fly-by-wire software requiring deterministic real-time response. Airbus A350 and Boeing 787 development programs in Toulouse and Charleston concentrate demand, mandated by FAA airworthiness directives.
- Embedded Systems:Microcontroller firmware for sensor acquisition and actuator command. Munich engineering clusters serve German eVTOL developers, driven by beyond-visual-line-of-sight certification requirements.
- Communication Interfaces:ARINC 429, AFDX, and Ethernet avionics bus protocol validation.
- Data Processing Units:Flight management computer algorithm verification.
- Software Integration:Multi-vendor subsystem interoperability testing.
- Fault Tolerance Evaluation:Failure mode propagation analysis in redundant architectures.
Control Systems dominate certification expenditure; Embedded Systems gain share fastest as distributed avionics architectures proliferate.
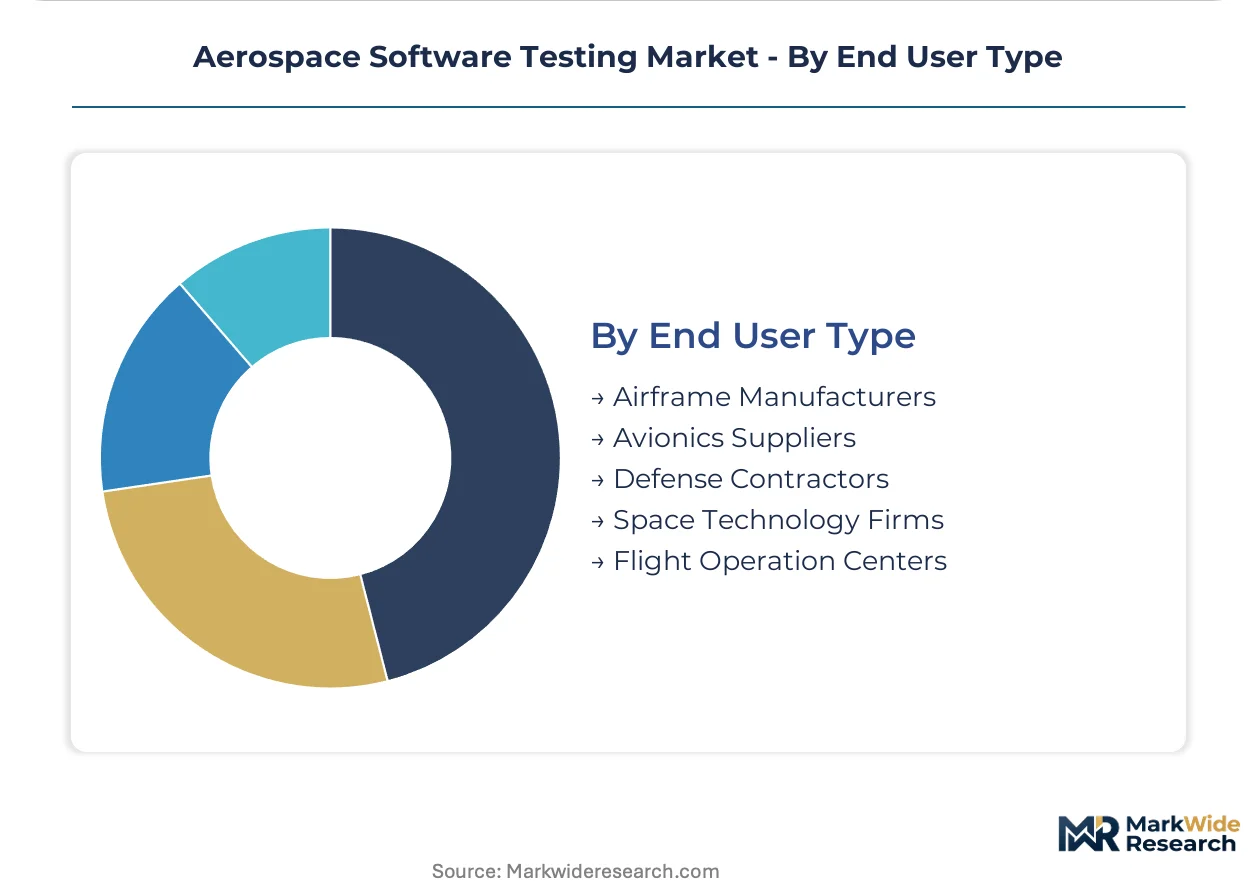
End User Type:
Procurement scale correlates with vertical integration depth, as airframe manufacturers internalize testing capabilities that tier-two suppliers once provided.
- Defense Contractors:Mission-critical flight system validation for fighter and unmanned platforms. Lockheed Martin and Northrop Grumman operations in California and Texas anchor North American demand, compelled by ITAR-controlled export restrictions and classified program requirements.
- Airframe Manufacturers:Integrated system validation across supplier-delivered subsystems. Boeing Commercial Airplanes in Washington and South Carolina drives integrated testing platform procurement, consolidating previously fragmented supplier validation.
- Avionics Suppliers:Component-level certification for tier-two and tier-three vendors.
- Space Technology Firms:Satellite constellation firmware validation and ground station software.
- Flight Operation Centers:Fleet monitoring and operational software maintenance testing.
Defense Contractors deploy the deepest testing infrastructure; Airframe Manufacturers are expanding capabilities most aggressively through vertical consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors in the United States and Germany command the deepest testing infrastructure investments, while commercial airframe manufacturers in France and the United Kingdom fragment procurement across specialized avionics suppliers.
United States
Lockheed Martin and Northrop Grumman operations in California and Texas anchor mission-critical flight system validation, compelled by ITAR-controlled export restrictions and classified program requirements. FAA enforcement of DO-178C guidelines shapes tool selection criteria across OEM supply chains. Seattle engineering clusters concentrate Boeing Commercial Airplanes' integrated testing platform procurement, consolidating previously fragmented supplier validation.
Germany
Vector Informatik and Rapita Systems anchor Europe's avionics testing ecosystem through embedded systems specialization and DO-178C certification tooling. EASA adoption of ED-12C intensifies verification protocols across NATO-aligned supply chains. Munich and Stuttgart engineering clusters serve German eVTOL developers, driven by beyond-visual-line-of-sight certification requirements and hardware-in-the-loop simulation demand.
France
Airbus engineering centers in Toulouse concentrate high-fidelity flight simulation software demand for new aircraft program validation. EASA guidance for machine learning component certification parallels traditional DO-178C assurance levels. French urban air mobility developers face steep compliance curves as they integrate computer vision into navigation stacks under emerging EU AI Act provisions.
United Kingdom
Rapita Systems maintains specialized positioning for safety-critical aerospace codebases through certification-grade tooling. UK defense procurement frameworks align with NATO ED-12C enforcement timelines for flight control system vendors. Cambridge and Bristol engineering corridors host autonomous systems testing facilities for satellite constellation firmware validation.
China
MIIT and NMPA are developing parallel certification frameworks for commercial drone and urban air mobility software stacks. Export control licensing friction from US ITAR and EU dual-use regulations restricts testing toolchain transfer to Chinese aerospace programs. COMAC and domestic eVTOL developers building to GB standards operate outside Western vendor licensing networks.
Aerospace Software Testing Market Competitive Landscape
North American producers anchor one tier through static analysis and hardware-in-the-loop capabilities; European specialists hold differentiated positioning in model-based testing workflows and certification-grade toolchains. The vendor base distributes across consolidated defense contractor procurement channels and fragmented commercial aviation supply chains. Three archetypes dominate: embedded systems specialists, safety-critical certification vendors, and broad-based testing platform providers. Competitive moves concentrate on strategic partnerships for FPGA-based emulation integration and geographic expansion into urban air mobility engineering clusters.
Within the certification-tooling tier, Parasoft and Rapita Systems exemplify divergent geographic specializations—Parasoft occupies a position in North American static analysis markets, while Rapita Systems anchors UK-based safety-critical code validation. Vector Informatik represents the embedded systems archetype through German model-based testing workflows. National Instruments sits within the instrumentation-heavy segment, bridging aerospace applications with broader industrial testing markets. These three named entities collectively illustrate how regulatory alignment with FAA, EASA, and emerging EU AI Act mandates shapes competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Parasoft |
| Rapita Systems |
| QualiTest |
| Vector Informatik |
| National Instruments |
| General Digital |
| Intertek Group plc |
| Element Materials Technology |
| MISTRAS Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
FPGA board price indices cascade through aerospace software testing supply chains, compressing margins for hardware-in-the-loop platforms while subscription-based static analysis tools capture pricing power through certification-grade differentiation.
Pricing Analysis
Volume concentrates in commoditized performance monitoring SaaS tiers while margin pools accrue to DO-178C certification toolchains commanding six-figure licensing commitments. Price differentiation hinges on FAA/EASA pre-approval status and embedded systems integration depth. Pricing pressure stems from mid-tier avionics suppliers seeking automated alternatives to manual verification cycles. Defense contractors exhibit lowest price sensitivity; commercial eVTOL startups face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with German FPGA emulation hardware and US-origin static analysis compilers. Component sourcing draws from Taiwan for semiconductor substrates, Germany for automotive-grade embedded controllers, and the United States for aerospace-specific certification IP. Tariff exposure runs through ITAR-controlled toolchain licensing restricting cross-border transfer. Distribution runs through defense contractor procurement frameworks and fragmented commercial aviation supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace software testing has become a vertical-integration race as airframe manufacturers internalize validation capabilities previously outsourced to tier-two suppliers, with FPGA-based emulation emerging as the critical upstream control point.
For Market Incumbents: Deepen embedded systems integration capabilities to counter automotive-aerospace convergence threats from Stuttgart engineering clusters. Prioritize in-house production of hardware-in-the-loop platforms to defend margin pools against commoditized SaaS entrants. Lock in certification pre-approval status with EASA's evolving machine learning guidance before compliance timelines compress. For New Entrants and Emerging Players: AI-assisted test generation from requirements specifications offers the most penetrable wedge for specialized entrants. Target satellite constellation firmware validation as white-space demand outpacing incumbent tooling roadmaps. Pursue partnership-based go-to-market models with Munich urban air mobility developers seeking beyond-visual-line-of-sight certification support. For Investors and Strategic Acquirers: Distressed-cycle entries favor embedded systems specialists with DO-178C tooling portfolios in German engineering corridors. Long-term viability centers on regulatory alignment density rather than feature breadth. Watch EASA algorithmic transparency enforcement timelines as inflection indicator for AI-validation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Emulation Integration | Compresses flight software validation timelines from months to weeks for Boeing and Airbus programs. |
| Certification Pre-Approval Investment | Locks in premium positioning against EASA's ED-12C enforcement timelines across NATO supply chains. |
| AI-Assisted Test Generation | Automates requirements-to-test-case derivation for Vector Informatik's model-based workflows. |
| Urban Air Mobility Partnership | Captures Munich and Stuttgart eVTOL demand driven by beyond-visual-line-of-sight mandates. |
| Satellite Constellation Platform | Addresses Starlink competitor batch-testing needs for distributed spacecraft firmware updates. |
Research Methodology
Document review covered FAA certification guidance documents, EASA ED-12C implementation notices, and EU AI Act algorithmic transparency drafts, complemented by interviews with avionics testing directors at German defense contractors, software verification leads at US airframe manufacturers, and procurement officers at satellite constellation operators. Secondary validation drew from ITAR licensing records, customs data on FPGA hardware imports, and hyperscaler capex disclosures for ground station infrastructure. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Historical spending patterns cross-referenced against expert panel input on DO-178C compliance cost inflation and automated testing adoption curves. Segmentation modeling spanned software type, testing approach, application area, and end-user vertical across the projection horizon. CAGRs derived from regression analysis of certification timeline compression and hardware-in-the-loop capital deployment rates. Industry-specific inputs included EASA machine learning guidance development status and MIIT parallel framework progress for Chinese GB standards.
Several conditions sit outside the modeled scope, including potential ITAR regulation expansion, unforeseen EU AI Act enforcement delays, and Chinese domestic certification framework divergence. Forecasts reflect documented assumptions on regulatory alignment timelines and technology substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cloud Gaming Baas Market
Others
Stand-Up Pouch Valves Market
Others
Industrial Computers Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Tobacco Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Binoculars Market
Others
UK Automotive LED Lighting Market
Others
Wingboards Market
Others
Automotive Smart Lighting Market
Others
Smart Doorbell Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Automatic Barriers and Bollards Market
Others
Cloud Advertising Market
Others
Solar Panel Testers Market
Others
Fenoxanil Market