
 Construction Fabrics Market | 2026-2036
Construction Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Fabrics Market Intelligence
Specialized installation expertise for tensile architecture and advanced geotextile systems is bifurcating the competitive landscape. Sioen Industries NV leverages its manufacturing scale to supply a broad range of coated fabrics for various construction needs. Saint-Gobain differentiates through its portfolio of high-performance fiberglass materials for reinforcement applications. Serge Ferrari specializes in composite membranes developed for lightweight architectural structures and facades.
Construction fabrics are engineered textiles designed for building and civil engineering projects. Composed of materials like polypropylene or polyester, they provide functions such as separation, filtration, and reinforcement. Their primary purpose is to improve the performance and lifespan of structures like roads and landfills. Geotextiles represent the largest product type, driven by extensive use in soil stabilization applications.
ISO specifications govern global product standards, defining testing methods for tensile strength and durability. In the United States, EPA guidelines influence the selection of erosion control fabrics. Europe’s CE marking ensures materials meet harmonized safety criteria for market access. Suppliers must navigate the trade-off between developing higher-performance materials and meeting the cost pressures of civil engineering procurement.
Market Dynamics
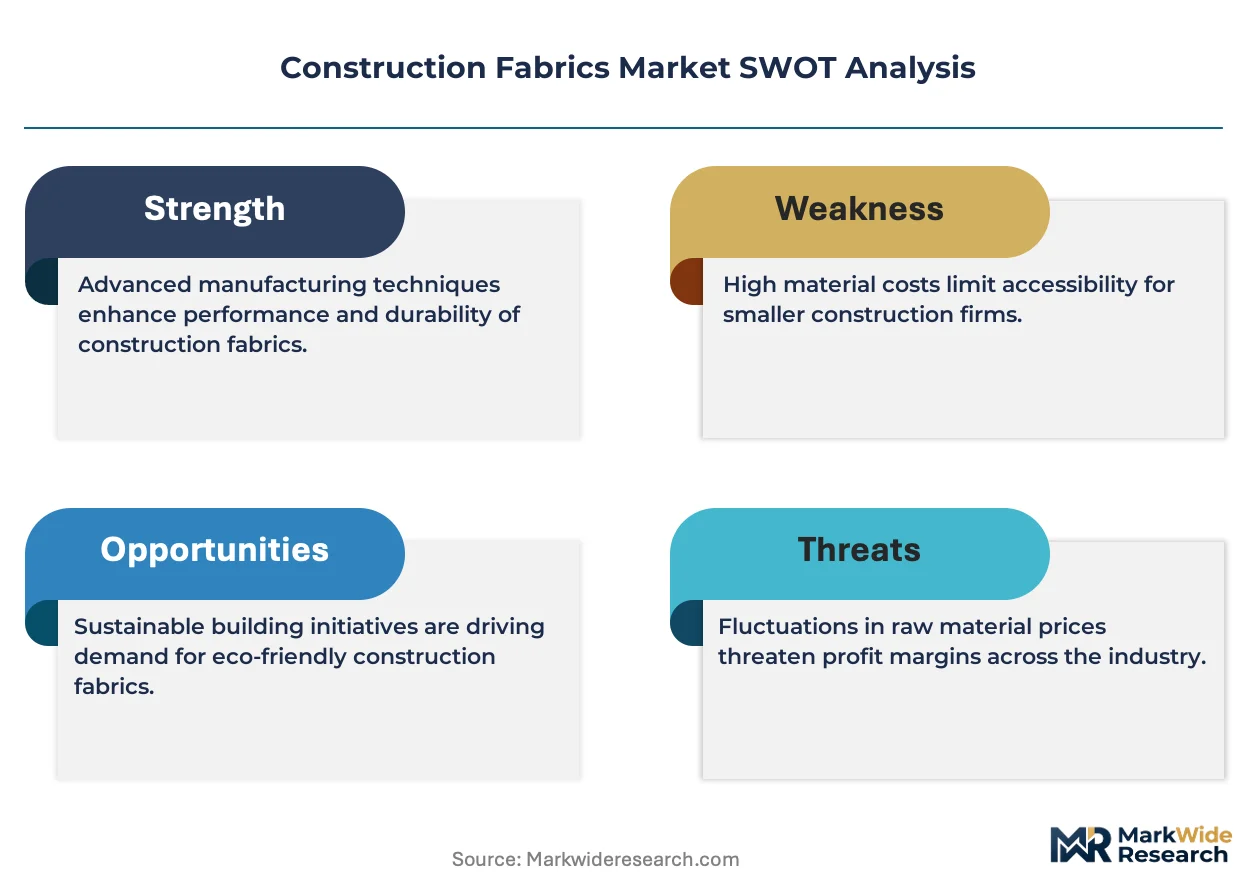
A structural tension between government-led sustainability mandates and the cost-sensitive nature of civil engineering procurement is defining the market. This dynamic forces innovation in resource-efficient geotextiles while navigating strict budget criteria for large-scale infrastructure projects, creating a clear divide between performance-driven and cost-driven segments.
Growth Catalysts
- Infrastructure Modernization:Government spending on upgrading aging water management systems and transportation networks, particularly in North America and Europe, directly increases consumption of geotextiles for reinforcement and drainage.
- EU Green Deal:European Union policies are accelerating the specification of durable, recycled-content geotextiles in public infrastructure projects to meet circular economy and resource efficiency targets.
- Urban Coastal Resilience:Investment in coastal protection and erosion control systems in response to climate change is creating new demand for high-strength woven fabrics and geocomposites in shoreline stabilization.
Market Restraints
- Raw Material Volatility:Fluctuations in the price of petroleum-derived polymers like polypropylene and polyester directly impact manufacturing costs and create pricing instability for end-users in large civil projects.
- Substitution from Aggregates:In cost-sensitive projects, traditional materials like sand and gravel for drainage and separation layers present a low-tech, but viable, alternative to specified geotextiles.
- Fragmented Specifications:The absence of globally harmonized design codes for advanced geotextile systems complicates engineering specifications and can favor conventional, better-understood construction techniques.
Strategic Opportunities
- Smart Geotextiles:Integrating fiber-optic sensors into geotextile grids offers a new service model for real-time structural health monitoring of critical infrastructure like dams, railways, and levees.
- Agricultural Applications:Untapped demand exists for specialized fabrics in precision agriculture for functions like weed control, soil moisture management, and greenhouse thermal screens.
- Biodegradable Materials:Developing fabrics from polylactic acid (PLA) or other biopolymers for temporary erosion control creates a sustainable product line for environmentally sensitive projects.
Industry Challenges
- Installation Skill Gap:The availability of certified installation crews for complex tensile membrane structures and advanced geotextile systems lags behind material innovation, creating project execution bottlenecks.
- Certification Timelines:The lengthy process of obtaining project-specific or regional approvals, such as from individual US state Departments of Transportation, delays market entry for new, higher-performance products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Fabrics Market |
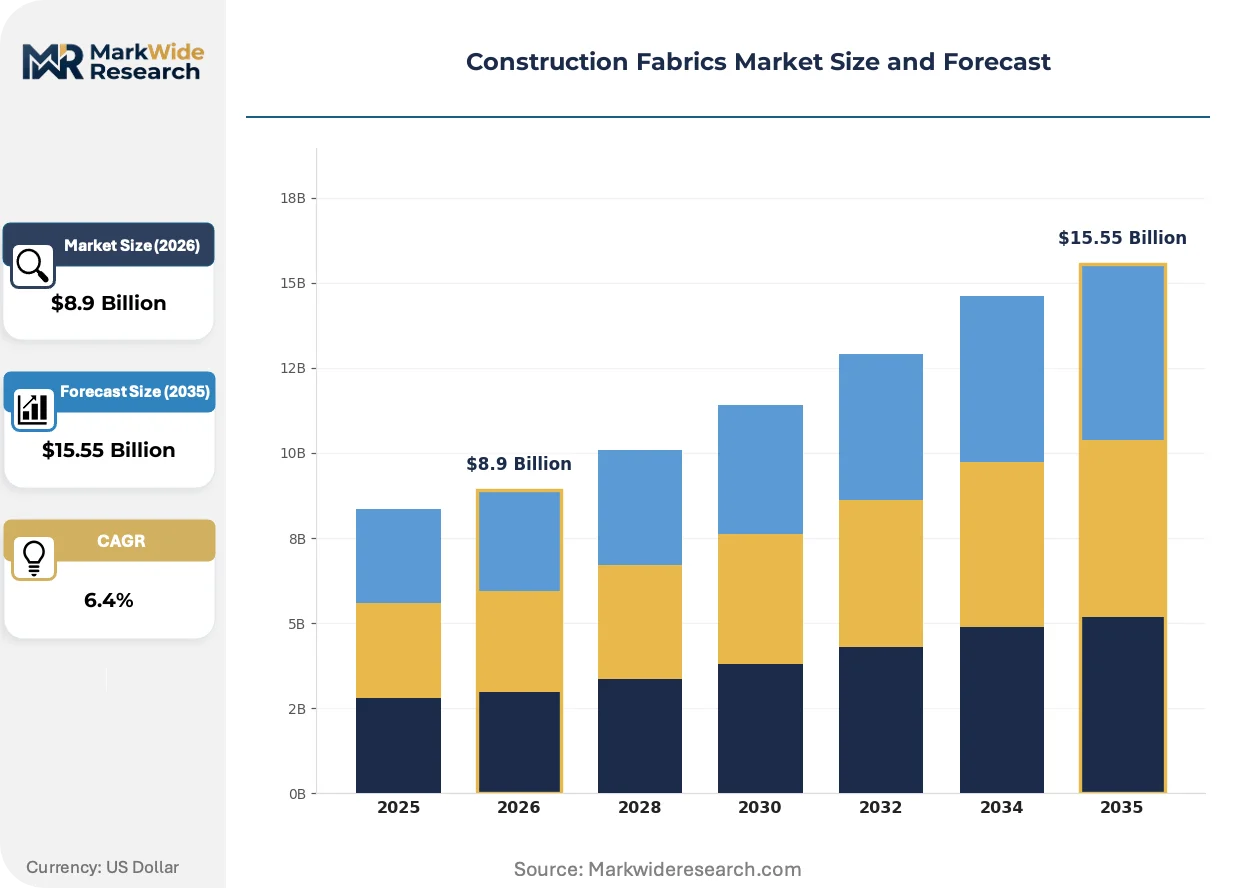
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Mesh Fabrics, Coated Fabrics, Erosion Control Fabrics, Concrete Reinforcement Fabrics Material: Polypropylene, Polyester, Nylon, Polyethylene, Fiberglass Application: Soil Stabilization, Drainage Systems, Waterproofing, Noise Barriers, Road Construction End User: General Contractors, Civil Engineers, Infrastructure Developers, Building Renovators, Bridge Builders |
| Companies Covered | Sioen Industries NV, Sattler AG, Seaman Corporation, TAIYO KOGYO CORPORATION, Serge Ferrari, Saint-Gobain, HIRAOKA & Co., Ltd., ENDUTEX COATED TECHNICAL TEXTILES, Freudenberg SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Fabrics Market Strategic Shifts & Innovations
Material science advancements are enabling a shift from commodity textiles to engineered systems with verifiable performance characteristics. This evolution is driven by demands for longer asset lifespans, improved resource efficiency, and greater resilience in civil infrastructure.
Geotextiles integrated with fiber-optic sensors provide real-time data on strain, temperature, and moisture. Asset managers for critical infrastructure like bridges and pipelines are adopting these smart textiles for predictive maintenance. This technology is miniaturizing geotechnical monitoring, embedding diagnostic capability directly into the reinforcement fabric rather than relying on external, post-installation sensors.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates extensive disclosure on environmental impacts throughout the value chain. This regulation compels large construction firms to quantify and report the lifecycle footprint of materials, including geotextiles. Consequently, fabric manufacturers supplying the European market must now provide verifiable data on recycled content and production emissions to remain competitive.
Project owners are shifting from transactional, price-per-unit purchasing to specifying integrated systems with long-term performance warranties. This model challenges traditional distributors selling commodity rolls, favoring manufacturers that provide engineering design and installation support as a bundled solution. The shift is most pronounced in large-scale transportation and water management infrastructure projects across North America.
Construction Fabrics Market Segmentation
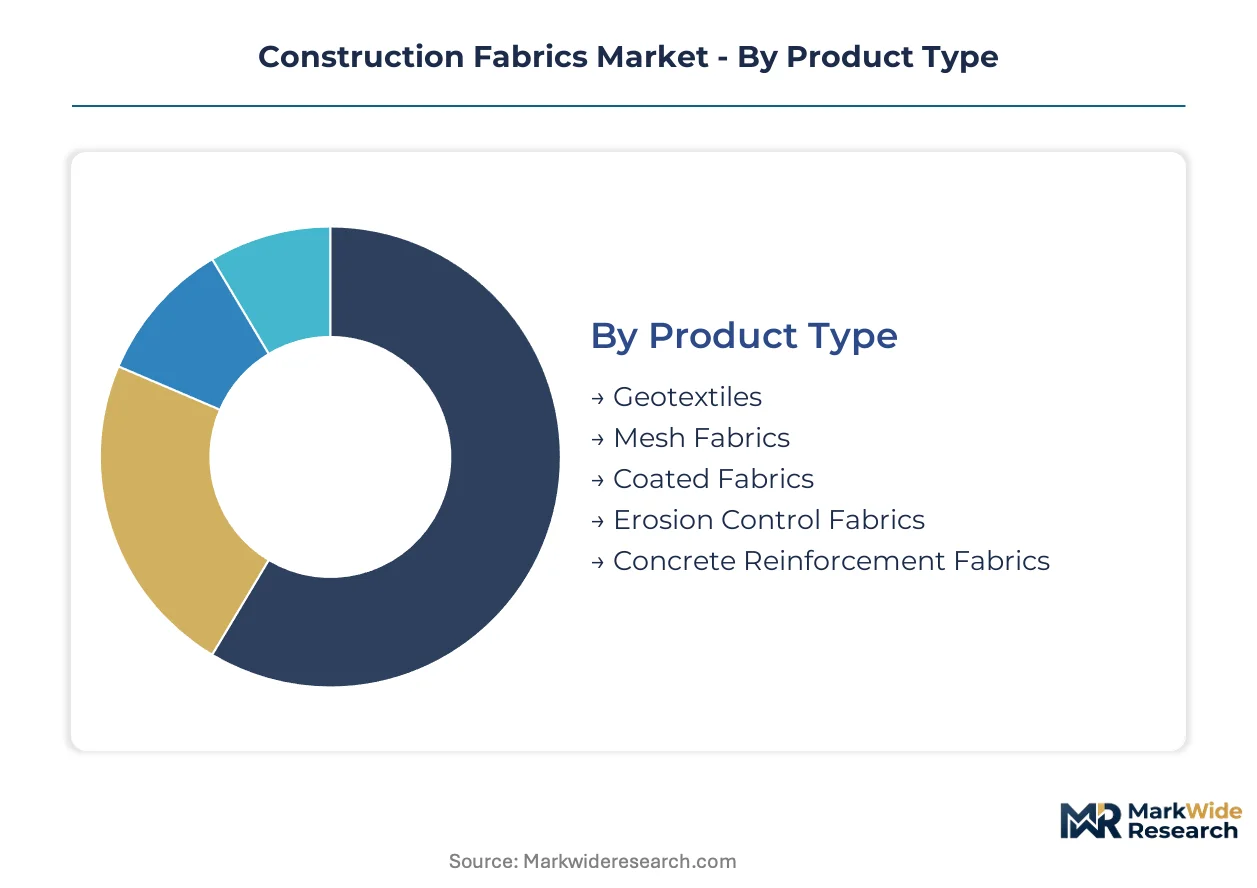
Market segmentation provides a granular view of the diverse product offerings and end-use applications within the construction fabrics industry. Understanding these distinctions helps manufacturers align product development with specific project requirements and procurement patterns. This analysis highlights the varying performance demands and material preferences across different construction disciplines.
Product Type:
The distribution of construction fabric product types reflects established procurement channels, with commodity items often sourced through broad distributors and specialized materials requiring direct manufacturer engagement.
- Geotextiles:These permeable synthetic fabrics, typically made from polypropylene or polyester, separate, filter, reinforce, protect, or drain soil. Their extensive use in soil stabilization and erosion control applications drives demand from large-scale infrastructure projects across China and North America.
- Coated Fabrics:These textiles feature a polymer coating, such as PVC or silicone, enhancing durability, waterproofing, and UV resistance for architectural membranes and industrial shelters. Sioen Industries NV leverages its manufacturing scale to supply these fabrics for diverse construction needs, particularly in Europe.
- Mesh Fabrics:Open-weave materials primarily used for reinforcement in plaster, stucco, and facade systems.
- Erosion Control Fabrics:Biodegradable or synthetic mats designed to prevent soil loss on slopes and shorelines.
- Concrete Reinforcement Fabrics:High-strength woven or non-woven materials integrated into concrete to improve tensile strength and crack resistance.
Geotextiles dominate the installed base. Coated fabrics are where innovation and expansion concentrate.
Material:
The material segment reflects the cost structures inherent in polymer-based manufacturing, influencing both product performance and market pricing.
- Polypropylene:A thermoplastic polymer widely used for its high strength-to-weight ratio and chemical resistance in non-woven geotextiles and separation layers. Fluctuations in petroleum prices directly impact the manufacturing costs of these widely adopted materials.
- Polyester:A synthetic polymer known for its high tensile strength, creep resistance, and durability, making it suitable for reinforcement applications in roads and embankments. Demand for polyester-based fabrics is strong in regions with extensive new infrastructure development, such as China.
- Nylon:Valued for its abrasion resistance and elasticity, often used in specialized applications requiring high impact strength.
- Polyethylene:A versatile polymer utilized in geomembranes and drainage composites for its impermeability and chemical inertness.
- Fiberglass:High-performance material providing excellent dimensional stability and reinforcement in concrete and asphalt overlays.
Petroleum-derived polymers form the bedrock of current production. Bio-based alternatives represent the next generation of sustainable materials.
Application:
Applications for construction fabrics span critical civil engineering functions, each addressing specific project requirements.
- Soil Stabilization:The use of geotextiles and geogrids to improve the bearing capacity of weak soils and prevent differential settlement in foundations and roadbeds. This application is central to infrastructure modernization efforts in North America and Europe.
- Road Construction:Integration of fabrics to reinforce subgrades, prevent reflective cracking in asphalt, and extend pavement lifespan, driven by extensive road and rail network construction in China.
- Drainage Systems:Fabrics that filter soil while allowing water to pass, preventing clogging of subsurface drains and French drains.
- Waterproofing:Impermeable membranes and liners used in tunnels, basements, and landfill caps to prevent water ingress.
- Noise Barriers:Specialized fabrics integrated into structures to attenuate sound, particularly along highways and railways.
Infrastructure development drives the largest volumes. Specialized applications ensure structural integrity in diverse environments.
End User:
End-user segments dictate procurement channels and the demand for integrated solutions, from material supply to installation support.
- Infrastructure Developers:Large organizations responsible for planning, funding, and executing major public works projects like highways, railways, and ports. Their uptake of construction fabrics is strong due to the need for long-term performance and durability in large-scale civil engineering.
- Civil Engineers:Professionals involved in the design and oversight of infrastructure projects, specifying fabric types based on technical requirements and regulatory compliance. Their demand often includes engineering design and installation support as part of a bundled solution.
- General Contractors:Companies managing the day-to-day operations of construction projects, procuring materials based on project specifications and cost efficiency.
- Building Renovators:Firms specializing in the repair and upgrade of existing structures, utilizing fabrics for insulation, waterproofing, and facade improvements.
- Bridge Builders:Specialized contractors focusing on the construction and maintenance of bridges, where high-strength reinforcement and erosion control fabrics are critical.
Large-scale infrastructure projects command significant purchasing power. Specialized contractors require tailored product and service bundles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for construction fabrics vary significantly by region, reflecting diverse infrastructure priorities and regulatory frameworks. China's demand concentrates on large-scale new builds, while European markets prioritize resource-efficient geotextiles for circular economy initiatives. North America focuses on modernization and resilience projects.
China
China's extensive new road and rail network construction drives significant demand for geotextiles and polyester-based fabrics. The nation's dual carbon goals promote material efficiency and sustainable construction practices in major projects. The Yangtze River Delta region sees continuous investment in transportation infrastructure, requiring vast quantities of reinforcement materials.
United States
The United States prioritizes infrastructure modernization, particularly for aging water management systems and transportation networks. EPA guidelines influence erosion control fabric selection, while individual state Departments of Transportation set project-specific material standards. The Northeast Corridor continues to invest in critical infrastructure upgrades, demanding high-performance fabrics for long-term durability.
Germany
Germany's public infrastructure projects increasingly specify durable, recycled-content geotextiles, aligned with EU Green Deal initiatives. CE marking ensures materials meet harmonized safety criteria for market access, while the CSRD mandates lifecycle footprint reporting. North Rhine-Westphalia, a major industrial region, implements sustainable building practices, driving demand for resource-efficient construction fabrics.
India
India's rapid urbanization and ambitious infrastructure development programs fuel substantial demand for construction fabrics in roads and railways. BIS standards govern product quality for geotextiles and other construction materials in public works projects. Maharashtra, a leading economic state, is a hub for infrastructure investment, requiring significant volumes of soil stabilization and reinforcement fabrics.
Construction Fabrics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for construction fabrics. This tiered structure sees large manufacturers offering a broad product range, while niche players focus on high-performance materials or specific applications. Strategic archetypes include diversified material producers and specialized architectural fabricators. Companies are pursuing both portfolio diversification into advanced materials and geographic expansion to capture emerging market demand.
On the scale-driven end, Belgium-based Sioen Industries NV exemplifies a broad-range manufacturer leveraging its production capabilities across various coated fabrics. France-based Saint-Gobain, a diversified materials company, represents a leader in high-performance fiberglass for reinforcement applications. Switzerland-based Serge Ferrari, known for its composite membranes, occupies a position as a specialist in lightweight architectural structures and facades, differentiating through material innovation.
| Leading Market Players |
|---|
| Sioen Industries NV |
| Sattler AG |
| Seaman Corporation |
| TAIYO KOGYO CORPORATION |
| Serge Ferrari |
| Saint-Gobain |
| HIRAOKA & Co., Ltd. |
| ENDUTEX COATED TECHNICAL TEXTILES |
| Freudenberg SE |
| Others |
Cost & Logistics Intelligence
Large-scale polymer manufacturing capacity underpins the construction fabrics market, driving cost efficiencies that reinforce supply concentration among major producers. This scale also establishes competitive price floors, influencing procurement strategies for bulk materials.
Pricing Analysis
Project-based procurement defines pricing in the construction fabrics market, with large infrastructure developers often negotiating long-term contracts for significant volumes. Price differentiation stems from material performance specifications, such as tensile strength or UV resistance, and certification levels like CE marking. Pricing softness reflects the cost-sensitive nature of civil engineering projects, particularly for commodity geotextiles. Infrastructure developers, focused on long-term performance, are less price-sensitive than general contractors procuring standard materials.
Supply Chain Analysis
Volatility in petroleum-derived polymer prices creates a significant chokepoint for the construction fabrics supply chain, directly impacting polypropylene and polyester manufacturing costs. Geographic supply concentrates in China and Europe, where major producers like Sioen Industries NV and Saint-Gobain operate large-scale facilities. The supply chain relies heavily on upstream petrochemicals, making it vulnerable to energy market fluctuations. Downstream distribution runs through a mix of specialized distributors for advanced systems and commodity material suppliers for standard products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction fabrics market represents a defensive moat story, primarily due to regulatory entrenchment through ISO specifications and CE marking. This creates significant barriers to entry for new materials and uncertified suppliers.
For Market Incumbents:Secure long-term supply contracts for critical polymer inputs to mitigate raw material volatility impacting manufacturing costs. Invest in certification processes for advanced geotextiles to reinforce market position against emerging, unproven materials. Expand engineering design services to offer bundled solutions, addressing the installation skill gap. This approach defends against margin pressure from commodity product substitution.
For New Entrants and Emerging Players:Anchor in niche applications such as smart geotextiles for real-time infrastructure monitoring, where specialized expertise differentiates offerings. Target biodegradable materials for temporary erosion control in environmentally sensitive projects, leveraging sustainability mandates. Focus on developing verifiable data for lifecycle footprint reporting to meet EU CSRD requirements. Direct sales to civil engineers specifying advanced systems offers a viable go-to-market angle.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized manufacturers offering integrated solutions with long-term performance warranties. Over the next decade, the market offers stable, infrastructure-driven growth with increasing demand for high-performance materials. Acquisition targets should include firms with strong R&D in biopolymers or sensor integration for smart fabrics. A key signal to watch is the adoption rate of mandatory lifecycle footprint reporting in new regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Biopolymer R&D | Developing fabrics from polylactic acid creates sustainable product lines for environmentally sensitive projects. |
| Expand Geotextile Sensor Integration | Integrating fiber-optic sensors into geotextile grids offers real-time structural health monitoring for critical infrastructure. |
| Certify for EU CSRD Compliance | Verifiable data on recycled content and production emissions ensures market access for European construction firms. |
| Acquire Installation Expertise | Addressing the installation skill gap for advanced geotextile systems reduces project execution bottlenecks. |
| Develop Integrated System Warranties | Shifting to long-term performance warranties attracts infrastructure developers seeking bundled solutions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry reports, government publications, and company financial disclosures. Interviews with civil engineers, infrastructure developers, general contractors, and material science experts provided qualitative insights. This analysis incorporated both bottom-up market sizing from product sales data and top-down validation against macroeconomic indicators. Data triangulation ensured comprehensive market understanding.
Market segmentation dimensions modeled include product type, material, application, and end-user, alongside regional adoption patterns. The analytical framework projects compound annual growth rates by assessing historical trends and future demand drivers across the analysis window. Demand for geotextiles in road construction, influenced by government infrastructure spending, served as a key forecast input. Material price volatility also shaped volume and value projections.
Decision-makers should treat outputs as directional under current infrastructure spending and regulatory stability assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, but raw material price shocks or shifts in environmental mandates present significant risks. Practitioners should keep alternative scenarios live as global economic conditions and climate resilience investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Document Camera Market
Others
Dry-Cleaning and Laundry Services Market
Others
Middle East Location-Based Services Market
Others
Latin America Fire Sprinklers Market
Others
Global Snow Sports Apparel Market
Others
Mini Pcs Market
Others
Gem Faceting Machine Market
Others
Flexible PVC Films and Sheets Market
Others
Global OTA Testing Market
Others
North America Automotive LED Lighting Market
Others
Mobile MRI Services Market
Others
Aboveground Storage Tanks Market
Others
Global Duty-Free Retailing Market
Others
Smart Home Gateways Market
Others
Global Radar Systems Market
Others
AI in Home Automation Market