
 Industrial Wearable Devices Market | 2026-2036
Industrial Wearable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wearable Devices Market Intelligence
China's Shenzhen electronics manufacturing cluster is reshaping component sourcing for industrial wearable assembly. Honeywell International Inc. leverages its safety equipment heritage to anchor enterprise smart helmet deployments across North American heavy industry. Zebra Technologies competes through ruggedized wearable computers purpose-built for warehouse logistics environments. Vuzix specializes in waveguide optics that differentiate its smart glasses from consumer-grade alternatives.
Industrial wearable devices integrate sensors, wireless connectivity, and heads-up displays into form factors rated for hazardous environments, typically meeting IP67 dust ingress and drop-test specifications for temperatures spanning minus twenty to plus fifty degrees Celsius. These systems execute remote expert guidance, biometric safety alerts, and hands-free data capture to reduce downtime and injury rates. Smart glasses lead product type revenue due to established enterprise software ecosystems, while wearable cameras capture the fastest growth trajectory as body-worn evidence collection spreads beyond law enforcement into industrial incident documentation. Augmented reality technology commands premium pricing in training and remote assistance applications where overlay precision directly correlates with operational error reduction.
FDA oversight of biometric monitoring accuracy intersects with OSHA personal protective equipment certification to create dual compliance thresholds for health-tracking wearables in industrial settings. The EU AI Act's risk classification framework for automated decision-making systems will reshape firmware development roadmaps for European deployments. Stakeholders must monitor evolving electromagnetic compatibility standards from IEC as device density increases on factory floors with interconnected sensor networks.
Market Dynamics
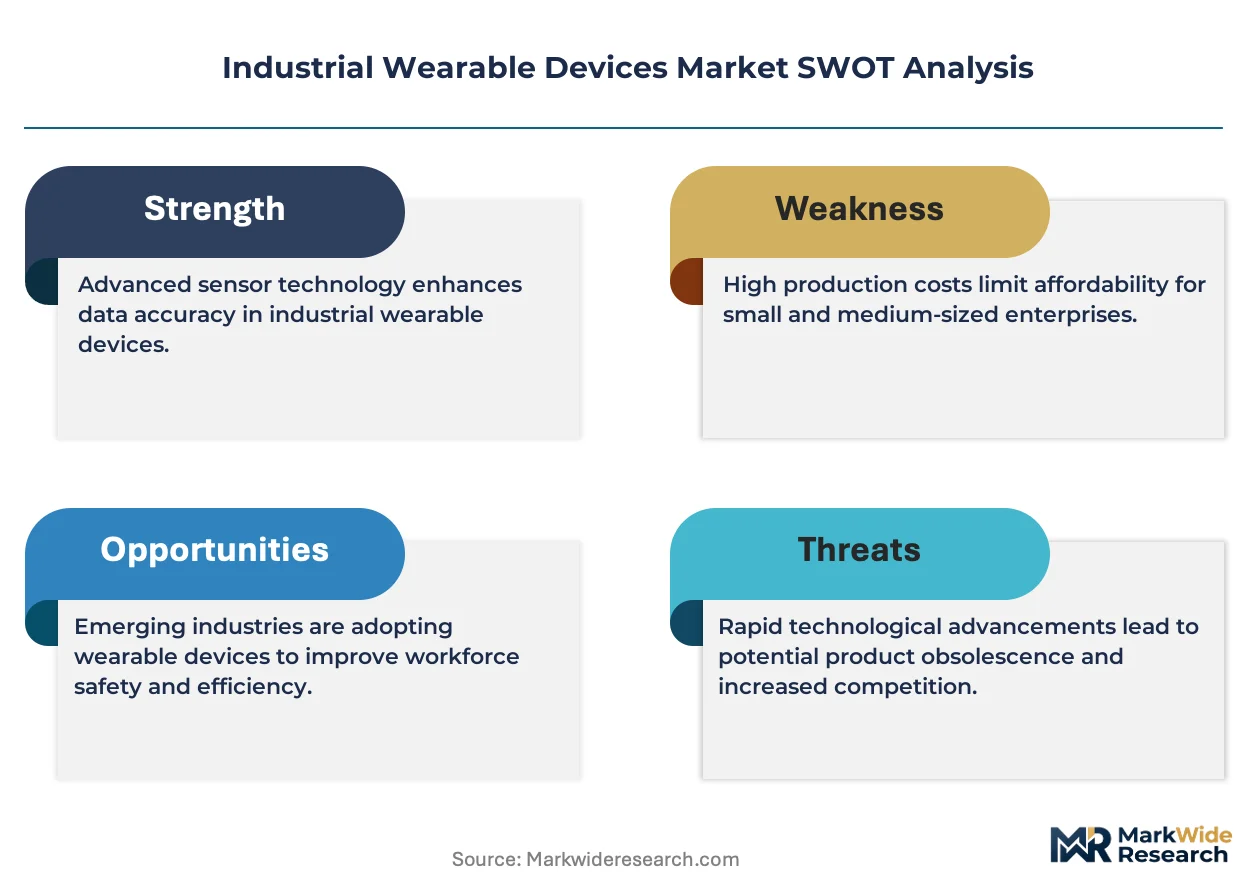
OSHA workplace safety mandates are compressing certification timelines for industrial wearables, forcing manufacturers to front-load compliance investment before hardware differentiation. This regulatory acceleration is concentrating procurement authority among buyers with dedicated safety engineering functions.
Growth Catalysts
- EU AI Act risk classification:The European Union's automated decision-making framework is mandating firmware transparency for European deployments, creating pull for compliant edge-computing architectures in German industrial corridors.
- Oil and gas field technician remote assistance:Head-mounted display deployments are expanding across upstream operations as operators prioritize downtime reduction in hazardous extraction environments.
- Biometric safety monitoring:FDA oversight intersecting with OSHA personal protective equipment certification is creating dual compliance thresholds that health-tracking wearables must satisfy for industrial deployment.
Market Restraints
- Waveguide optics supply concentration:Precision optical component manufacturing clusters in Shenzhen create single-source vulnerability for smart glasses assembly.
- IEC electromagnetic compatibility evolution:Interconnected sensor density on factory floors is forcing continuous firmware recertification as interference standards tighten.
- IP67 enclosure cost structure:Dust ingress and drop-test specifications spanning minus twenty to plus fifty degrees Celsius require specialized sealing materials that inflate bill-of-materials.
Strategic Opportunities
- Wearable cameras in incident documentation:Body-worn evidence collection is spreading beyond law enforcement into industrial safety investigation, opening white space in manufacturing verticals.
- India PLI scheme localization:Production-linked incentives for electronics manufacturing are attracting assembly capacity for ruggedized wearable computers targeting domestic logistics operators.
- Augmented reality training convergence:Overlay precision technology is hybridizing with enterprise software ecosystems to reduce operational error rates in heavy industry skill transfer.
Industry Challenges
- Dual certification timeline compression:FDA biometric accuracy validation running parallel to OSHA PPE approval is extending product launch cycles for health-monitoring industrial wearables.
- Legacy system integration friction:Hands-free data capture devices must interface with decades-old manufacturing execution systems lacking standardized APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wearable Devices Market |
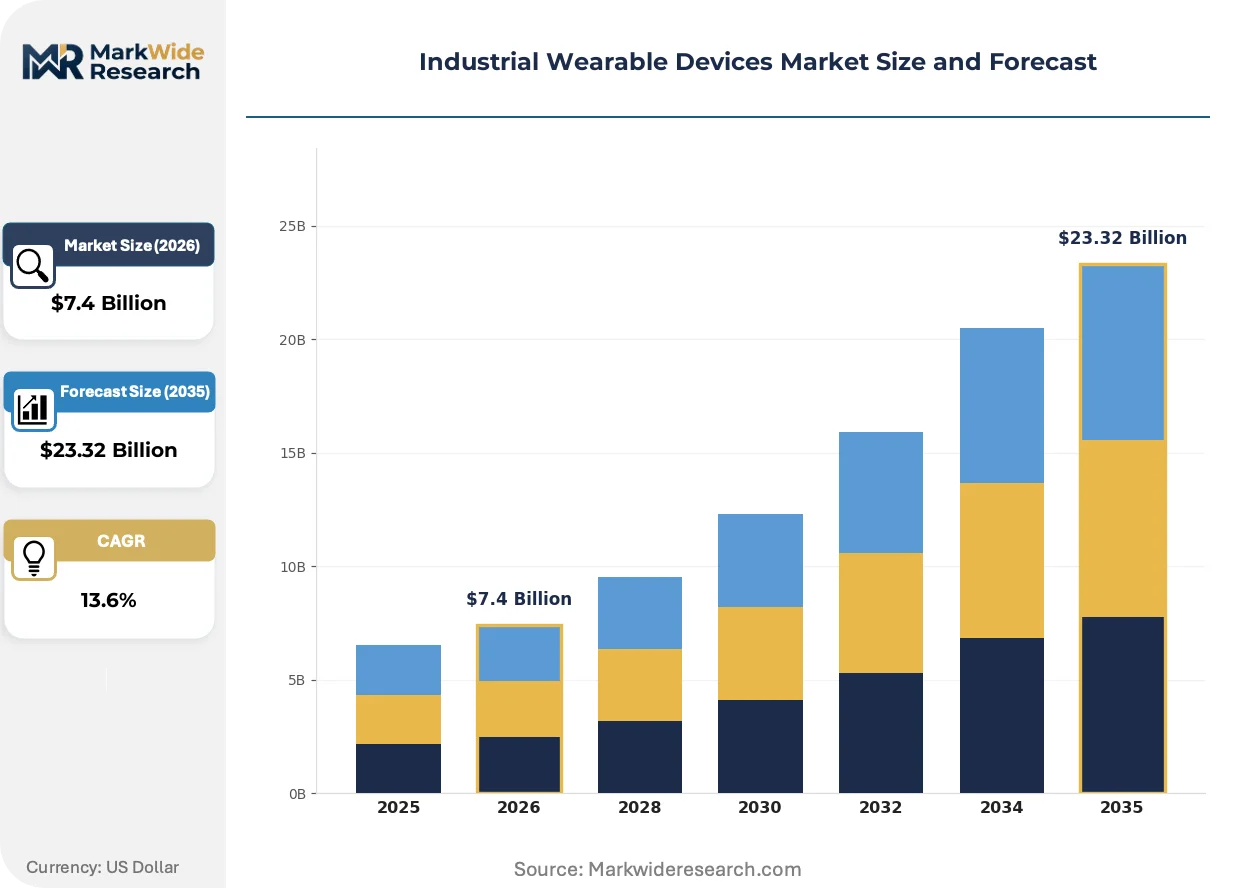
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $23.32 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Smart Helmets, Wearable Cameras, Fitness Trackers Technology: Bluetooth, RFID, IoT, Augmented Reality End User: Manufacturing, Construction, Logistics, Healthcare Application: Remote Assistance, Safety Monitoring, Training, Data Collection |
| Companies Covered | Apple Inc., Microsoft, Epson, Fujitsu, Google, Zebra Technologies, Honeywell International Inc., Samsung Electronics, Vuzix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wearable Devices Market Strategic Shifts & Innovations
Industrial wearable architecture is pivoting from standalone hardware to sensor-network nodes, with firmware development now preceding industrial design in vendor roadmaps. This inversion is compressing the traditional product cycle.
Waveguide optics technology is hybridizing display systems for smart glasses, merging see-through optical paths with micro-LED illumination engines. Oil and gas operators are adopting these systems for field technician remote assistance at accelerated procurement cycles. The structural consequence is collapsing the price premium between consumer-grade and industrial-grade head-mounted displays.
EU AI Act risk classification frameworks are reshaping firmware development roadmaps for European deployments, mandating algorithmic transparency for automated safety alerts. Industrial wearable vendors are rearchitecting edge-computing stacks to satisfy explainability requirements. Smart glasses with biometric monitoring functions face the steepest compliance burden under this regime.
Buyer procurement authority is consolidating among enterprises with dedicated safety engineering functions capable of navigating dual FDA-OSHA certification requirements. Distributors serving mid-market manufacturers without internal compliance expertise are losing share to direct vendor relationships. This concentration is most visible in Germany's industrial corridor, where automotive and chemical conglomerates dominate wearable device procurement.
Industrial Wearable Devices Market Segmentation
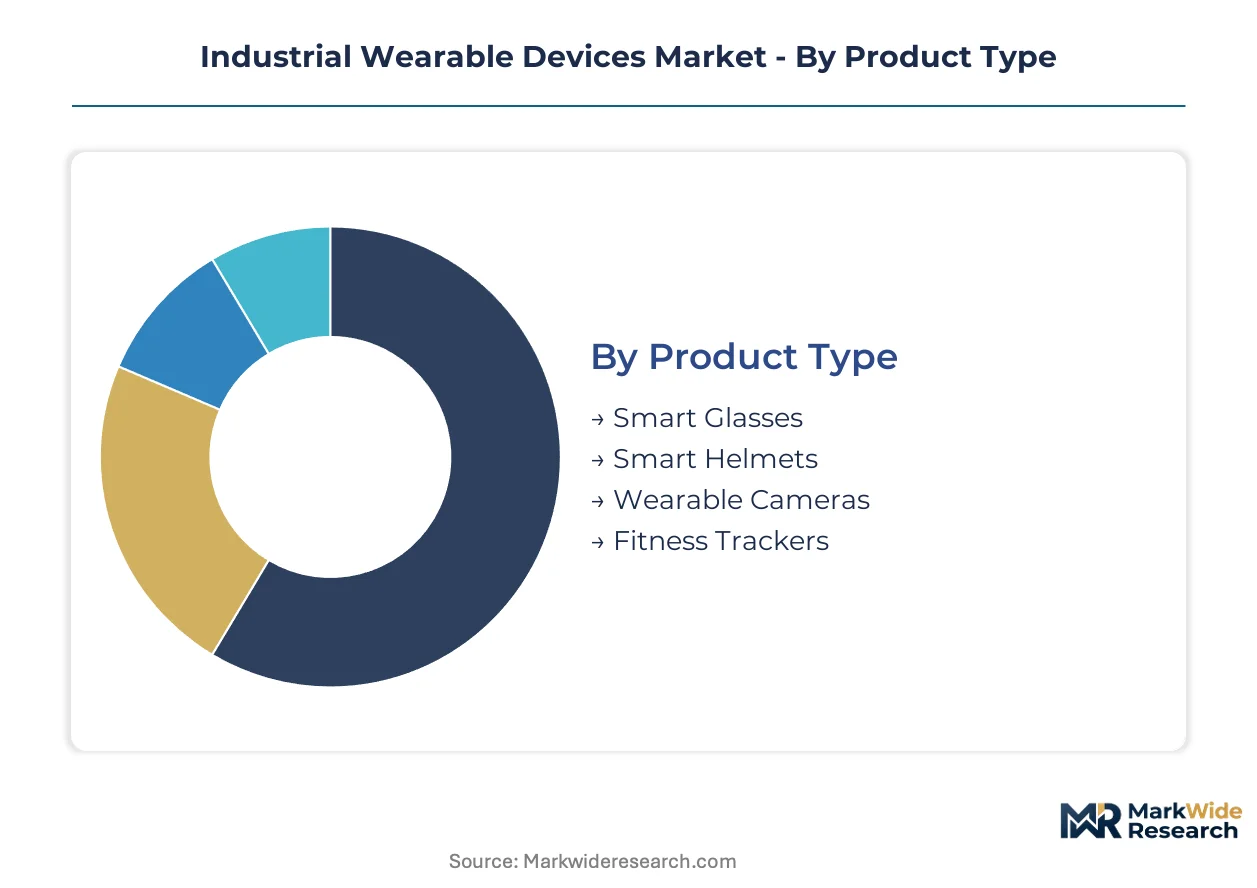
Industrial wearable procurement cycles vary dramatically across product categories, with some segments refreshing every eighteen months while others operate on seven-year replacement timelines. Understanding these velocity differentials shapes inventory planning and vendor relationship strategies for enterprise buyers.
Product Type:
Smart glasses turn over fastest as display technology advances, while fitness trackers linger longest in deployment cycles due to simpler sensor architectures.
- Smart Glasses:Waveguide optics and micro-LED illumination engines deliver see-through overlay precision for hands-free data visualization. Oil and gas operators in Texas and Alberta prioritize these for field technician remote assistance where downtime reduction justifies accelerated refresh schedules.
- Wearable Cameras:Body-worn recording systems with IP67-rated enclosures capture industrial incident documentation beyond traditional law enforcement applications. Manufacturing safety investigators in Germany's industrial corridor drive fastest adoption as evidence collection protocols formalize.
- Smart Helmets:Integrated heads-up displays with biometric monitoring meet dual OSHA-FDA certification thresholds for hazardous environment deployment.
- Fitness Trackers:Simplified wrist-worn form factors monitor worker vitals without augmented reality complexity, serving baseline safety compliance needs.
Smart glasses dominate installed base. Wearable cameras are where expansion concentrates.
Technology:
Connectivity protocols stratify by data throughput requirements, with high-bandwidth applications commanding premium component costs.
- Augmented Reality:Spatial computing engines overlay digital information onto physical environments with millimeter-level registration accuracy. Heavy industry training programs in Japan and South Korea leverage this precision to reduce operational error rates during skill transfer.
- IoT:Mesh network architectures enable factory-floor sensor density with edge-computing nodes processing safety alerts locally. EU AI Act compliance mandates are reshaping firmware development roadmaps for European deployments.
- Bluetooth:Low-energy protocols support wearable-to-gateway communication for biometric data streaming in controlled indoor environments.
- RFID:Passive and active tagging systems integrate with wearable readers for inventory tracking and access control in warehouse logistics.
Augmented Reality commands premium pricing tiers. IoT connectivity is gaining share fastest in new deployments.
End User:
Sector-specific hazard profiles dictate ruggedization requirements and certification complexity across buyer verticals.
- Manufacturing:Automotive and chemical conglomerates in Germany's industrial corridor consolidate procurement authority through dedicated safety engineering functions capable of navigating dual FDA-OSHA certification requirements.
- Logistics:Warehouse operators deploy ruggedized wearable computers for hands-free data capture integrated with legacy manufacturing execution systems. India's PLI scheme for electronics manufacturing is attracting assembly capacity targeting domestic logistics operators.
- Construction:Drop-test specifications and dust ingress protection dominate specification sheets for outdoor deployment environments.
- Healthcare:FDA biometric accuracy validation intersects with infection control protocols for clinical setting deployments.
Manufacturing holds the deepest installed base. Logistics is climbing the fastest as e-commerce fulfillment networks expand.
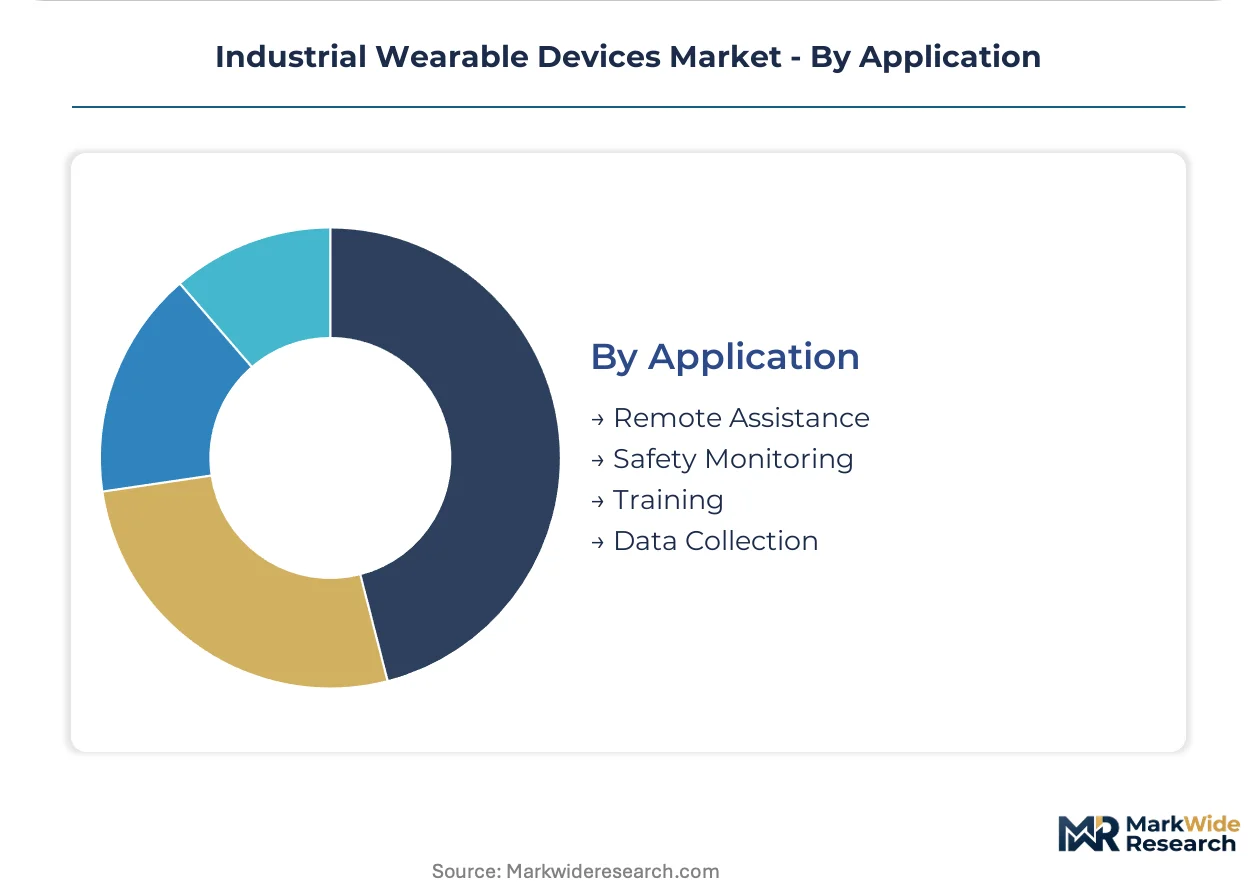
Application:
Use case maturity determines software ecosystem development and integration complexity for enterprise deployments.
- Remote Assistance:Real-time video streaming connects field technicians with centralized experts through head-mounted displays. Oil and gas upstream operations prioritize this application for hazardous extraction environment troubleshooting.
- Safety Monitoring:Biometric alerts for heat stress, fatigue, and fall detection require FDA oversight of measurement accuracy alongside OSHA personal protective equipment certification.
- Training:Augmented reality overlay precision directly correlates with operational error reduction in heavy industry skill transfer scenarios.
- Data Collection:Hands-free barcode scanning and voice-input logging streamline inventory and quality assurance workflows.
Remote Assistance anchors current revenue. Safety Monitoring is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates in the United States are compressing certification timelines for industrial wearables, forcing manufacturers to front-load compliance investment before hardware differentiation. This regulatory acceleration is concentrating procurement authority among buyers with dedicated safety engineering functions.
United States
Oil and gas operators in Texas and Alberta are expanding head-mounted display deployments for field technician remote assistance. OSHA mandates accelerate device certification requirements for hazardous environment deployment. Houston's energy corridor anchors upstream procurement concentration for downtime reduction investments.
Germany
Automotive and chemical conglomerates consolidate procurement authority through dedicated safety engineering functions. EU AI Act risk classification frameworks mandate firmware transparency for automated decision-making systems. Stuttgart and Ludwigshafen industrial clusters drive smart glasses adoption for augmented reality training convergence.
China
Shenzhen's electronics manufacturing cluster reshapes component sourcing for industrial wearable assembly. GB standards and MIIT regulations govern electromagnetic compatibility for factory-floor sensor networks. Pearl River Delta assembly capacity targets domestic logistics operators under dual carbon goals compliance.
Japan
Heavy industry training programs leverage augmented reality overlay precision to reduce operational error rates. METI industrial policy supports edge-computing architectures for explainable safety alerts. Nagoya and Osaka manufacturing belts concentrate wearable computer deployments for skill transfer applications.
India
Production-linked incentives for electronics manufacturing attract assembly capacity for ruggedized wearable computers. BIS certification requirements intersect with PLI scheme localization mandates. Maharashtra and Gujarat industrial corridors target domestic logistics operators with warehouse automation procurement.
Industrial Wearable Devices Market Key Industry Players
Industrial safety heritage specialists and consumer technology crossovers split the market along certification depth versus scale economics. The vendor base organizes into three strategic archetypes: legacy safety equipment manufacturers with OSHA relationships, ruggedized computing specialists with logistics vertical focus, and optical technology purists with waveguide differentiation. Dominant competitive moves include backward integration into precision component supply and firmware rearchitecting for EU AI Act compliance.
Among North American safety heritage players, Honeywell International Inc. exemplifies the industrial certification archetype, while Zebra Technologies occupies the ruggedized logistics computing position. Vuzix represents the waveguide optics specialization tier. These three anchors illustrate how vendor positioning stratifies across compliance depth, environmental ruggedization, and display technology precision.
| Leading Market Players |
|---|
| Apple Inc. |
| Microsoft |
| Epson |
| Fujitsu |
| Zebra Technologies |
| Honeywell International Inc. |
| Samsung Electronics |
| Vuzix |
| Others |
Cost & Logistics Intelligence
The Shenzhen-Hong Kong logistics corridor's freight cost volatility ripples through industrial wearable assembly economics, amplifying price spreads between waveguide optics-intensive smart glasses and simpler fitness tracker form factors while compressing margins for mid-tier ruggedized computers.
Pricing Analysis
Geographic price spreads between German automotive procurement clusters and Indian logistics operator deployments exceed forty percent for equivalent smart helmet specifications. Three-tier pricing structure across premium AR-enabled, standard connected, and economy sensor-only levels reflects dual FDA-OSHA certification depth. Pricing pressure stems from Shenzhen component cost compression bleeding into finished device markets. Mid-market manufacturers without dedicated safety engineering functions exhibit highest price sensitivity, while oil and gas operators prioritize downtime reduction over unit economics.
Supply Chain Analysis
Extended payment terms from Shenzhen optical component suppliers now stretch ninety to one hundred twenty days, straining working capital for waveguide-dependent smart glasses assemblers. Manufacturing concentrates in China, South Korea, and Vietnam for display modules, sensor arrays, and final assembly respectively. Precision waveguide substrates, micro-LED dies, and IP67-rated sealing compounds constitute critical input dependencies. Single-source vulnerability for waveguide optics creates structural risk. Distribution runs through direct vendor relationships with safety-engineering-capable enterprises, bypassing traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial wearable market fragmentation creates niche opportunities as EU AI Act compliance requirements splinter procurement authority away from generalist IT channels toward specialized safety engineering functions.
For Market Incumbents: Insulate certification moats by accelerating dual FDA-OSHA validation pipelines before emerging Asian electronics assemblers achieve compliance scale. Backward integration into waveguide optics supply reduces Shenzhen single-source exposure. Channel control through direct safety engineering relationships defends against distributor disintermediation. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer underpenetrated white space for ruggedized wearable computers targeting domestic logistics operators under PLI scheme localization. Wearable cameras for manufacturing incident documentation represent the most penetrable application segment. Go-to-market through BIS certification partnerships accelerates market access. For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape toward edge-computing firmware specialists with explainable algorithm architectures. Long-term viability centers on vendors capable of navigating dual biometric accuracy and PPE certification thresholds. Watch FDA-OSHA timeline convergence as inflection indicator for health-monitoring wearable valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waveguide Optics | Shenzhen supply concentration creates captive manufacturing priority for smart glasses vendors. |
| EU AI Act Firmware Re-architecture | Algorithmic transparency mandates reshape edge-computing development roadmaps for European deployments. |
| Direct Safety Engineering Channel Buildout | Procurement authority concentration favors bypassing distributors to reach German automotive conglomerates. |
| India PLI Scheme Assembly Localization | Production-linked incentives attract ruggedized wearable capacity for domestic logistics operators. |
| Dual Certification Pipeline Acceleration | FDA biometric validation parallel to OSHA PPE approval extends launch cycles for health-tracking devices. |
Research Approach
A spread of perspectives from plant safety directors, OEM procurement managers, waveguide optics engineers, and industrial software integration specialists converged on the working assumptions driving this analysis. Primary fieldwork with enterprise wearable deployers in German automotive clusters and Texas oil and gas operations combined with secondary validation through OSHA certification databases, IEC electromagnetic compatibility standards filings, FDA 510(k) submissions, and EU AI Act implementation guidance. Bottom-up unit economics triangulated against top-down sectoral spending patterns.
Demand-supply balance framing anchored the forecast architecture across the analysis window. Segmentation dimensions modeled include product type, connectivity protocol, end-use vertical hazard profile, and application maturity tier. CAGRs derived from replacement cycle velocity differentials and certification timeline compression effects. Industry-specific inputs incorporated IP67 enclosure cost structures and waveguide optics yield rates.
Practitioners should monitor IEC electromagnetic compatibility standard evolution and EU AI Act enforcement calibration for early signals of firmware recertification burden. Forecasts reflect assumptions about regulatory timeline stability and Shenzhen supply chain continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Supply Chain Risk Management Software Market
Others
United States Bean Bags Market
Others
Global Alpha Cypermethrin Market
Others
Europe Aircraft Lighting Systems Market
Others
Hypersensitivity Market
Others
Italy 3D Printing Construction Market
Others
Textile Composites Market
Others
Heavy Duty Vacuum Bottle Market
Others
Drum Motor Market
Others
Diamond Mining Market
Others
Mobile Edge Computing Market
Others
Europe Medical Simulation Market
Others
Wingboards Market
Others
Cremation Furnace Market
Others
Radar Speed Signs Market
Others
Mexico Retail Market