
 Gyroscope Market | 2026-2036
Gyroscope Market Size, Share, and Industry Trends Forecast 2026-2036
Gyroscope Market Intelligence
MEMS-to-optical technology migration is fragmenting the established supplier hierarchy as defense and aerospace buyers hedge between mature ring laser systems and emerging chip-scale alternatives. Honeywell International Inc. anchors the high-end inertial navigation segment with deep proprietary expertise in ring laser fabrication. Robert Bosch GmbH leverages its automotive MEMS scale to cross-sell industrial gyroscope variants through shared wafer-level packaging infrastructure. STMicroelectronics competes aggressively on unit cost by dominating consumer-grade MEMS shipments to mobile device manufacturers.
A gyroscope is a rotating or vibrating device that measures angular velocity or orientation relative to an inertial frame, with MEMS variants fabricated from polysilicon structures on silicon wafers achieving drift rates below one degree per hour in tactical-grade configurations. Its primary commercial purpose is stabilizing platforms, guiding vehicles, and enabling spatial awareness in systems where GPS signals are unavailable or insufficient. MEMS gyroscopes command the highest shipment volumes due to smartphone and wearable integration, though fiber optic gyroscopes capture disproportionate margin pools in marine guidance and autonomous underwater vehicle applications where bias stability requirements exceed mechanical alternatives. Ring laser gyroscopes retain structural importance in aviation firm procurement for long-haul aircraft inertial reference units despite weight and power penalties.
FAA airworthiness standards and EU MDR certification requirements for surgical navigation systems both impose stringent drift and calibration protocols that filter out uncertified suppliers. China's SAMR enforces GB standards on industrial automation gyroscopes that mandate shock resistance testing above commercial consumer specifications. South Korea's MFDS regulates medical device inertial sensors with traceability requirements that favor established vendors over new entrants. Stakeholders must monitor how quantum sensing prototypes displace classical optical gyroscopes in defense research laboratory procurement before committing to capacity expansion in fiber optic coil winding equipment.
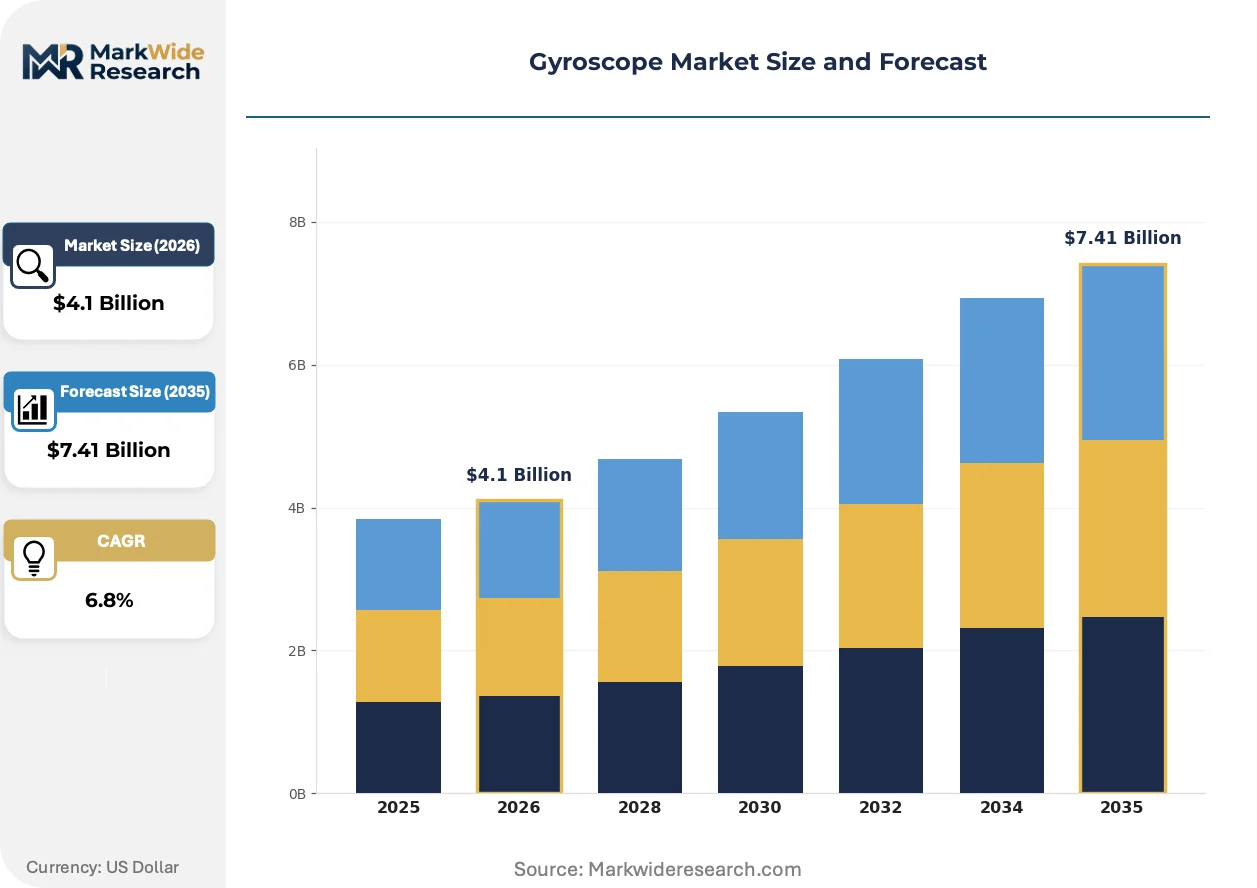
Market Dynamics
MEMS-to-optical technology migration is fragmenting supplier hierarchies as defense and aerospace buyers hedge between mature ring laser systems and emerging chip-scale alternatives, forcing incumbents to defend fabrication expertise while new entrants exploit wafer-level packaging scale.
Growth Catalysts
- FAA airworthiness mandates:Aviation firms must upgrade inertial reference units on long-haul fleets, sustaining procurement of high-drift-stability ring laser gyroscopes despite weight penalties.
- Augmented reality integration:Smartphone manufacturers are embedding sophisticated motion sensing arrays, pulling MEMS gyroscope volumes through shared wafer-level packaging infrastructure.
- China's GB standards tightening:SAMR enforcement of industrial automation sensor specifications above consumer-grade shock resistance is filtering uncertified suppliers from precision instrument manufacturing.
Market Restraints
- Fiber optic coil winding equipment concentration:Defense research laboratory procurement of quantum sensing prototypes threatens stranded capital in classical optical gyroscope production lines.
- Polysilicon input volatility:MEMS fabrication depends on semiconductor-grade silicon wafer supply chains vulnerable to energy cost fluctuations and foundry capacity allocation.
- EU MDR certification friction:Surgical navigation system drift and calibration protocols impose multi-year validation timelines that exclude emerging MEMS vendors from medical device markets.
Strategic Opportunities
- Autonomous underwater vehicle expansion:Marine guidance applications with bias stability requirements exceeding mechanical alternatives offer disproportionate margin pools for fiber optic gyroscope specialists.
- South Korea wearable procurement:Samsung Electronics and domestic robotics firms are concentrating demand for compact, high-drift-stability units in drone and wearable platforms.
- Quantum-classical convergence:Chip-scale atomic interferometry integration with existing MEMS packaging flows could open navigation-grade performance at consumer-electronics cost structures.
Industry Challenges
- Inertial navigation systems integration:Legacy aviation firm procurement cycles require backward compatibility with decades-old ring laser architectures, complicating MEMS substitution roadmaps.
- Multi-jurisdiction certification timelines:Simultaneous FAA, EASA, and CAAC airworthiness validation for tactical-grade gyroscopes stretches engineering resources across incompatible test protocols.
- Specialized coil winding talent scarcity:Fiber optic gyroscope manufacturing depends on craft-level expertise in polarization-maintaining fiber handling that lacks formal training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gyroscope Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS Gyroscopes, Fiber Optic Gyroscopes, Ring Laser Gyroscopes, Vibrating Structure Gyroscopes, Hemispherical Resonator Gyroscopes Technology: Analog, Digital, Optical, Mechanical, Quartz Application: Aerospace Navigation, Consumer Electronics, Robotics Control, Marine Guidance, Virtual Reality Systems End User: Defense Systems, Mobile Device Manufacturers, Industrial Automation, Aviation Firms, Research Laboratories |
| Companies Covered | TDK Corporation, Analog Devices Inc., Honeywell International Inc., Safran S.A., Northrop Grumman Corporation, Robert Bosch GmbH, Murata Manufacturing Co. Ltd., Silicon Sensing Systems Limited, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gyroscope Market Strategic Shifts & Innovations
Wafer-level packaging advances and quantum sensing maturation are compressing the performance-cost frontier across all gyroscope categories, while regulatory fragmentation between aviation, medical, and defense certification regimes is forcing modular product architectures.
Chip-scale atomic gyroscopes exploiting nuclear magnetic resonance in alkali vapor cells are rendering obsolete the thermal stabilization hardware required by tactical-grade MEMS units. Defense research laboratories in the US and China are prototyping these devices for GPS-denied navigation. The structural consequence is a compression of the performance tiering that previously separated consumer, industrial, and navigation-grade categories.
EU MDR certification requirements for surgical navigation systems now mandate traceable calibration drift documentation across the device lifecycle. This policy shift is elevating quality system investments above pure unit cost competition. European surgical robot manufacturers are responding by consolidating supplier bases around vendors with established notified body relationships, excluding Asian MEMS specialists from premium medical segments.
Aviation procurement departments are unbundling inertial reference unit after-sales service from hardware purchase, contracting directly with specialized calibration laboratories rather than original equipment manufacturers. This channel disintermediation is visible most acutely in South Korea and Japan, where MRO providers are capturing recurring revenue streams that previously anchored supplier profitability. The shift forces gyroscope vendors to defend position through firmware update subscriptions rather than captive service networks.
Gyroscope Market Segmentation
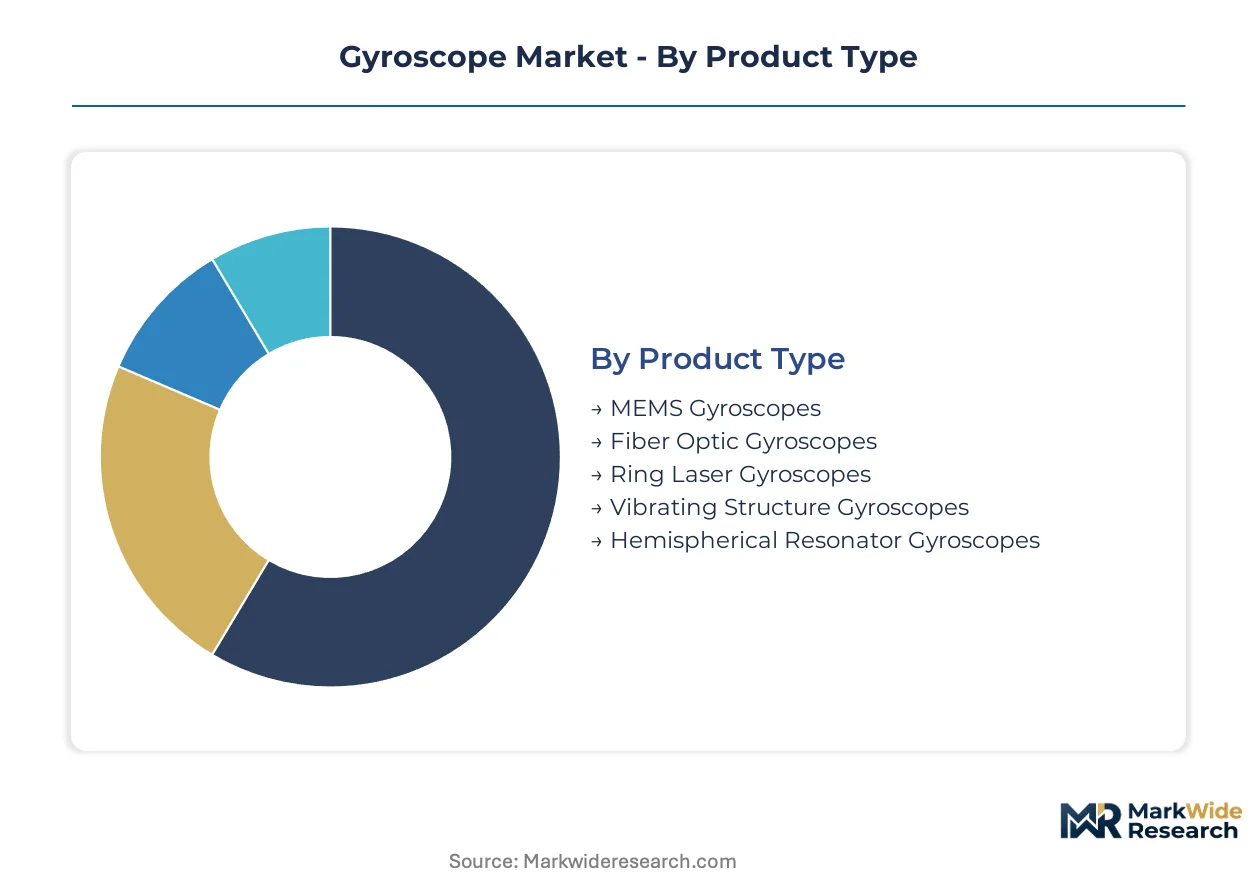
Gyroscope market segmentation reveals divergent procurement rhythms across product architectures. MEMS variants turn over in smartphone production cycles measured in months, while ring laser systems persist across aircraft service lives spanning decades.
Product Type:
MEMS gyroscopes refresh fastest through consumer electronics channels, whereas hemispherical resonator units exhibit the longest replacement intervals in satellite platforms.
- MEMS Gyroscopes:Fabricated from polysilicon structures on silicon wafers using semiconductor batch processing. Samsung Electronics and Apple procurement for smartphone motion sensing drives volumes through shared wafer-level packaging infrastructure with automotive sensor lines.
- Fiber Optic Gyroscopes:Exploit Sagnac interference in polarization-maintaining fiber coils to achieve bias stability below 0.01 degrees per hour. Marine guidance applications for autonomous underwater vehicles in South Korea and Japan concentrate demand where mechanical alternatives fail depth tolerance specifications.
- Ring Laser Gyroscopes:HeNe gas discharge cavities in monolithic glass-ceramic blocks dominate aviation firm procurement for long-haul inertial reference units despite weight and power penalties.
- Vibrating Structure Gyroscopes:Piezoelectrically driven tuning fork architectures serve cost-sensitive industrial automation where SAMR GB standards mandate shock resistance above consumer specifications.
- Hemispherical Resonator Gyroscopes:Fused quartz shell structures with electrostatic drive electrodes anchor strategic satellite navigation programs requiring zero maintenance across fifteen-year orbital lifespans.
MEMS gyroscopes anchor the volume base while fiber optic variants gain share at the steepest rate.
Technology:
Analog interfaces dominate legacy defense integration, but digital outputs are displacing voltage-encoded signals in new robotics platforms.
- Analog:Continuous voltage proportional to angular rate simplifies integration with legacy avionics architectures. Defense systems procurement for existing fighter aircraft fleets sustains demand despite calibration drift vulnerabilities.
- Digital:SPI and I2C protocol outputs enable direct microcontroller interfacing in consumer electronics. STMicroelectronics and Bosch MEMS shipments to mobile device manufacturers standardize on digital formats for firmware update compatibility.
- Optical:Interferometric detection schemes in fiber optic and ring laser configurations achieve navigation-grade performance without moving parts.
- Mechanchanical:Rotor-based angular momentum conservation principles persist in specialized test equipment where absolute accuracy validation requires traceable physical rotation.
- Quartz:Piezoelectric crystalline resonators offer intermediate performance between MEMS and optical grades for industrial vibration monitoring.
Analog technology retains the installed base while digital formats expand most quickly in new design wins.
Application:
Aerospace navigation commands extended validation timelines, whereas consumer electronics compress development-to-production intervals below eighteen months.
- Aerospace Navigation:Strapdown inertial measurement units for commercial and military aircraft require FAA, EASA, and CAAC airworthiness certification. Boeing and Airbus procurement cycles for long-haul fleet upgrades sustain ring laser gyroscope demand despite MEMS substitution pressure.
- Consumer Electronics:Smartphone and wearable motion sensing arrays integrate multiple MEMS axes for image stabilization and augmented reality. Samsung Electronics and Apple volume procurement concentrates in South Korea and China foundry ecosystems.
- Robotics Control:Industrial automation and service robot balance systems demand tactical-grade drift specifications. Local robotics firms in South Korea drive compact, high-stability unit procurement for drone platforms.
- Marine Guidance:Submersible and surface vessel navigation in GPS-denied environments favors fiber optic gyroscope immunity to magnetic interference.
- Virtual Reality Systems:Head-mounted display orientation tracking pulls consumer-grade MEMS volumes through shared supply chains with smartphone motion sensors.
Consumer electronics anchors the volume base while robotics control climbs the fastest in procurement growth.
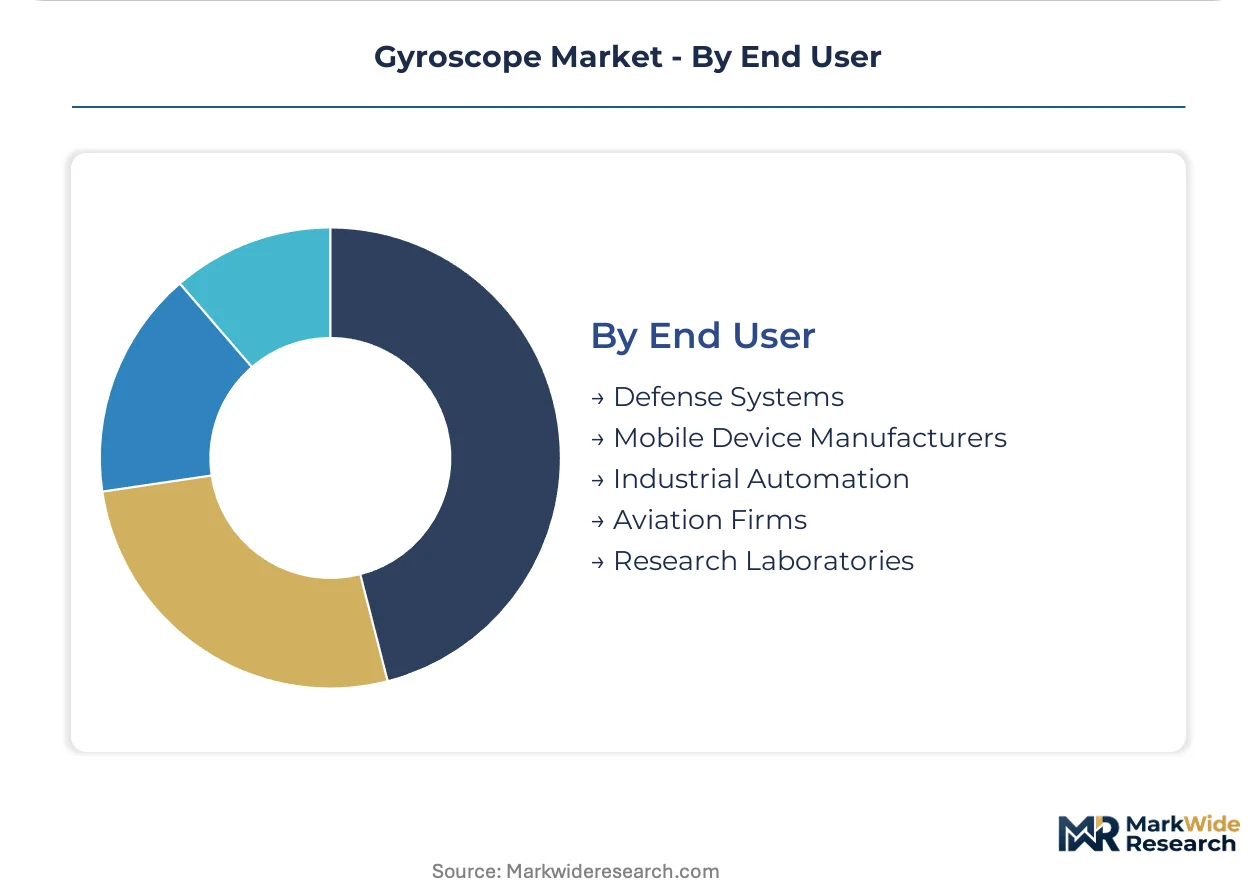
End User:
Defense systems procurement stretches across multi-year appropriation cycles, but mobile device manufacturers compress supplier qualification to quarterly evaluations.
- Defense Systems:Classified inertial navigation programs for missile guidance and submarine navigation mandate ITAR compliance and domestic sourcing. US and Chinese defense research laboratories prototype quantum sensing alternatives that threaten classical optical gyroscope production line viability.
- Mobile Device Manufacturers:Smartphone OEMs in China and South Korea dominate MEMS gyroscope consumption through wafer-level packaging scale economies. Apple and Samsung Electronics procurement specifications drive drift performance improvements in consumer-grade silicon.
- Industrial Automation:Factory robot positioning and automated guided vehicle navigation require SAMR GB standard compliance for shock resistance. China's tightening energy efficiency regulations filter uncertified suppliers from precision instrument manufacturing.
- Aviation Firms:Commercial airline procurement departments unbundle inertial reference unit hardware from after-sales service, contracting MRO providers in South Korea and Japan directly for calibration.
- Research Laboratories:Defense and academic institutions prototype chip-scale atomic gyroscopes using nuclear magnetic resonance in alkali vapor cells.
Mobile device manufacturers anchor the volume base while research laboratories gain share fastest in emerging technology procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and consumer electronics OEMs concentrate demand in distinct geographic clusters, with regulatory certification requirements fragmenting supplier access across national boundaries.
United States
FAA airworthiness mandates drive aviation firm upgrades of inertial reference units on long-haul fleets. The Department of Defense funds quantum sensing prototypes at research laboratories that threaten classical optical gyroscope production viability. California and Arizona host concentrated defense contractor ecosystems where ITAR compliance filters foreign suppliers from classified navigation programs.
China
SAMR enforcement of GB standards for industrial automation sensors tightens shock resistance specifications above consumer-grade requirements. The dual carbon goals pressure precision instrument manufacturers toward energy-efficient fabrication. Yangtze River Delta foundry clusters in Shanghai and Suzhou concentrate MEMS wafer-level packaging capacity serving domestic smartphone OEMs.
Germany
Automotive Tier 1 suppliers cross-sell industrial gyroscope variants through shared semiconductor packaging infrastructure. REACH and RoHS compliance requirements elevate quality system investments above pure unit cost competition. Bavaria's Munich-Stuttgart corridor anchors industrial automation sensor development with embedded robotics integration.
South Korea
Samsung Electronics and domestic robotics firms concentrate procurement of compact, high-drift-stability units for drone and wearable platforms. MFDS traceability requirements for medical device inertial sensors favor established vendors over new entrants. Seoul Capital Area and Busan-Ulsan clusters dominate MEMS foundry capacity allocation for motion sensing arrays.
Japan
METI industrial policy supports fiber optic gyroscope manufacturing for autonomous underwater vehicle marine guidance applications. JIS standards mandate calibration documentation that extends supplier qualification timelines. Nagoya-Tokyo industrial corridors concentrate precision instrument manufacturing with captive coil winding expertise for polarization-maintaining fiber handling.
Gyroscope Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The supplier base separates into volume-driven MEMS fabricators, navigation-grade optical specialists, and dual-use defense contractors with captive calibration networks. Three archetypes dominate: wafer-scale semiconductor integrators, craft-level fiber optic coil winders, and systems houses bundling hardware with firmware subscriptions. Competitive moves concentrate on strategic partnerships for quantum sensing R&D and geographic expansion through MRO service unbundling.
Among diversified technology conglomerates, TDK Corporation and Analog Devices Inc. exemplify the scale-driven archetype with semiconductor heritage. Honeywell International Inc. occupies a distinctive position as a systems house with deep inertial navigation integration expertise. These three anchors represent contrasting strategic postures: component supply at volume, precision sensing at premium tiers, and bundled platform solutions with recurring service revenue.
| Leading Market Players |
|---|
| TDK Corporation |
| Analog Devices Inc. |
| Honeywell International Inc. |
| Safran S.A. |
| Northrop Grumman Corporation |
| Robert Bosch GmbH |
| Murata Manufacturing Co. Ltd. |
| Silicon Sensing Systems Limited |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Wafer-level packaging capacity concentration in Yangtze River Delta foundries anchors margin capture for MEMS gyroscope vendors, while polysilicon input costs transmit directly to consumer-grade unit economics downstream.
Pricing Analysis
Cost-plus contracts with semiconductor-grade silicon wafer indexation dominate MEMS procurement between foundries and fabless design houses. Three-tier pricing structure across navigation-grade, tactical-grade, and consumer-grade levels separates ring laser systems from fiber optic marine units from smartphone MEMS chips. Cost compression in consumer-grade tiers is intensifying because Samsung Electronics and Apple procurement teams consolidate supplier bases around wafer-scale partners. Mobile device manufacturers exhibit highest price sensitivity, while aviation firms accepting FAA-mandated ring laser upgrades show lowest sensitivity due to airworthiness certification lock-in.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for MEMS gyroscope vendors serving dual geography OEMs. Manufacturing concentrates in China, South Korea, and Japan, with Yangtze River Delta and Seoul Capital Area foundries feeding consumer electronics demand. Polysilicon wafers, polarization-maintaining fiber, and HeNe gas discharge cavities constitute critical input dependencies. Single-source vulnerability in semiconductor-grade silicon supply threatens MEMS fabrication continuity. Distribution runs through direct OEM contracts for aviation and defense, while consumer electronics channels leverage electronics manufacturing service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mobile device manufacturers as Samsung Electronics and Apple procurement teams consolidate MEMS supplier qualifications to quarterly evaluation cycles.
For Market Incumbents: Pre-empt MEMS-to-optical substitution by accelerating chip-scale atomic gyroscope R&D partnerships with defense research laboratories. Lock in wafer-level packaging capacity through multi-year foundry commitments in Yangtze River Delta clusters. Quantum sensing prototypes threaten classical optical gyroscope production line viability; vertical integration into alkali vapor cell fabrication secures navigation-grade positioning. For New Entrants and Emerging Players: Build out calibration laboratory networks in South Korea and Japan where aviation procurement departments unbundle after-sales service from hardware purchase. Marine guidance applications for autonomous underwater vehicles offer the most penetrable segment given bias stability requirements exceeding mechanical alternatives. Target fiber optic coil winding expertise acquisition as the critical go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chip-scale atomic interferometry development programs as defense research laboratory funding accelerates. Long-term viability favors vendors with navigation-grade certification portfolios spanning FAA, EASA, and CAAC jurisdictions. Acquisition targets should exhibit captive polarization-maintaining fiber handling expertise and established notified body relationships. The signal to watch is quantum sensing prototype procurement velocity at US and Chinese defense laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum Sensing R&D Partnership | Chip-scale atomic gyroscope development with DARPA and Chinese defense laboratories displaces classical optical systems. |
| Wafer-Level Packaging Scale-Up | Yangtze River Delta foundry commitments secure MEMS cost structures for Samsung Electronics and Apple procurement. |
| Calibration Laboratory Network Expansion | South Korea and Japan MRO providers capture recurring revenue streams from aviation procurement disintermediation. |
| Polarization-Maintaining Fiber Integration | Backward integration into coil winding expertise defends fiber optic gyroscope margin pools in marine guidance. |
| Multi-Jurisdiction Certification Investment | Simultaneous FAA, EASA, and CAAC airworthiness validation filters emerging MEMS vendors from aviation tier. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with MEMS design engineers, aviation procurement officers, fiber optic coil winding specialists, and defense research laboratory program managers; and secondary validation through FAA airworthiness directives, SAMR GB standard filings, SEC 10-K disclosures from listed sensor vendors, and customs trade data on semiconductor-grade silicon wafer flows. Bottom-up unit shipment estimates across smartphone OEM procurement channels triangulated against top-down market value reconstruction from ring laser aviation contract announcements.
Forecast inputs span product architecture, drift stability grade, application sector, and end-user procurement archetype across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include quantum sensing prototype funding trajectories at defense research laboratories and GB standards enforcement timelines for industrial automation sensors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by chip-scale atomic gyroscope entrants or accelerated quantum sensing procurement by defense laboratories would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Smart Hydrophone Market