
 IoT Sensor Market | 2026-2036
IoT Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Sensor Market Intelligence
The transition to silicon-based MEMS technology from older, discrete sensor components is consolidating the physical footprint and power consumption of sensor packages. Bosch Sensortec specializes in motion and environmental sensors for consumer electronics. Texas Instruments leverages its broad analog and embedded processing portfolio to serve diverse industrial applications. STMicroelectronics competes on the strength of its extensive microcontroller and sensor fusion expertise.
An IoT sensor is a device that converts physical parameters like temperature or pressure into electrical signals for an IoT network. These devices often integrate a transducer with micro-processing capabilities to handle initial signal conditioning. Temperature and pressure sensors represent foundational, high-volume categories. The industrial and automotive end-user segments drive demand for high-reliability and application-specific sensor designs.
Wireless communication modules within IoT sensors must comply with regulations like the FCC in the United States. In Europe, the RoHS directive restricts hazardous substances in sensor manufacturing, while China's GB standards mandate specific product conformity tests. Stakeholders must navigate the diverging data privacy frameworks and cybersecurity requirements to ensure market access and user trust.
Market Dynamics
The central force shaping the IoT sensor market is the integration of micro-processing and edge computing capabilities directly into sensor modules. This shift transforms sensors from simple data transducers into nodes of distributed intelligence, altering value chains and competitive dynamics.
Growth Catalysts
- MEMS Technology Advancement:The transition to silicon-based micro-electromechanical systems (MEMS) reduces the size, cost, and power consumption of sensors, accelerating their integration into mass-market consumer electronics and wearable devices.
- Industry 4.0 Initiatives:Government-backed programs, such as Germany's Industry 4.0 strategy, create significant pull for high-reliability sensors in automated manufacturing, predictive maintenance, and smart logistics applications.
- Connected Vehicle Systems:The automotive sector's development of advanced driver-assistance systems (ADAS) and autonomous driving functions requires a growing density of sophisticated sensors for environment perception and vehicle control.
Market Restraints
- Diverging Privacy Regulations:Navigating disparate data privacy laws, such as Europe's GDPR and various state-level rules in the United States, creates significant compliance overhead and legal risk for global sensor deployments.
- Power Management Limitations:The energy budget for battery-powered wireless sensors remains a critical technical constraint, limiting operational lifespan and data transmission frequency in remote or large-scale deployments.
- Hazardous Substance Compliance:European Union directives like RoHS restrict the use of certain materials in electronics manufacturing, compelling sensor makers to invest in alternative materials and redesign production processes.
Strategic Opportunities
- Edge AI Integration:Embedding artificial intelligence and machine learning algorithms directly onto sensor hardware opens new applications in real-time anomaly detection and predictive analytics without cloud latency.
- Smart Agriculture Deployments:Underpenetrated sectors like precision agriculture offer significant growth potential for environmental sensors that monitor soil moisture, nutrient levels, and micro-climates to optimize crop yields.
- Cybersecurity-as-a-Service:The increasing risk of attacks on IoT networks creates an opportunity for vendors to offer bundled security services, including device authentication and encrypted data transmission, as a value-added feature.
Industry Challenges
- Legacy System Integration:Connecting modern IoT sensors with older industrial control systems and operational technology (OT) infrastructure often requires complex and costly custom engineering to ensure compatibility and data integrity.
- Interoperability and Standards:A fragmented landscape of wireless communication protocols and data formats hinders seamless interoperability between different vendors' platforms, creating lock-in and complicating system expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Sensor Market |
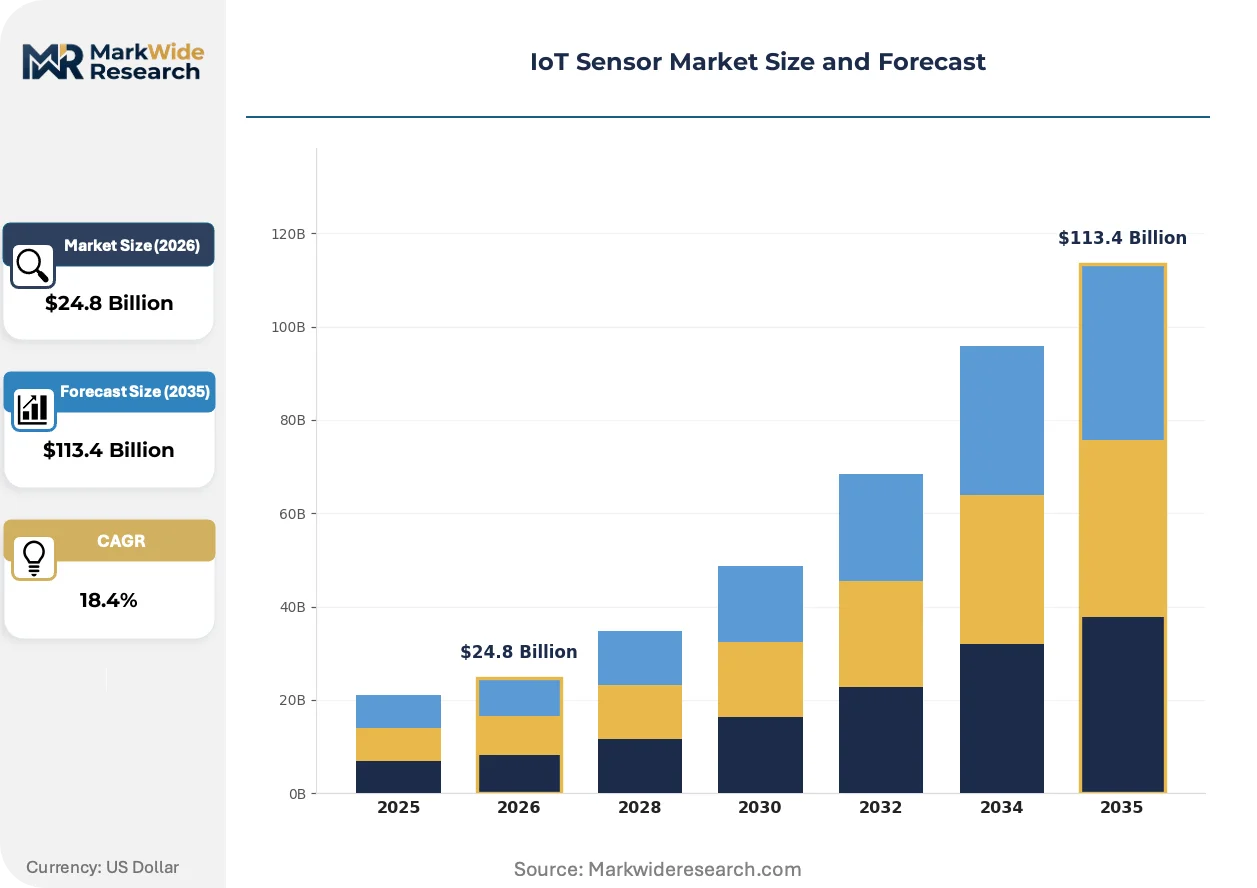
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $113.4 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Humidity Sensors, Motion Sensors Deployment: Cloud-Based, Edge Computing, On-Premises, Hybrid End User: Healthcare, Automotive, Agriculture, Industrial Connectivity: Wi-Fi, Bluetooth, Zigbee, LoRaWAN |
| Companies Covered | Texas Instruments, Infineon Technologies, Honeywell International, TE Connectivity, Analog Devices, Bosch Sensortec, NXP Semiconductors, Sensirion, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Sensor Market Strategic Shifts & Innovations
A fundamental re-architecture is underway, moving intelligence from centralized cloud platforms to the network edge. This decentralization enables sensors to perform initial data processing and analysis, reducing latency and bandwidth requirements for large-scale IoT deployments.
Sensor fusion combines inputs from multiple sensor types, such as accelerometers and gyroscopes, to produce more accurate and reliable data than any single sensor could alone. The automotive and consumer electronics sectors are rapidly adopting this technology for navigation and user interface applications. This technique is converging with on-device AI processors to enable complex, real-time environmental perception and decision-making without cloud dependency.
China's mandatory GB standards dictate specific product conformity tests for electronic devices sold within its market. This regulatory framework forces non-Chinese manufacturers to engage in separate, often lengthy, design and validation cycles specifically for China. The industrial and automotive sensor segments are particularly affected, requiring specialized compliance resources to secure market access.
Enterprise customers are increasingly moving away from purchasing discrete sensor components toward procuring pre-integrated, full-stack monitoring solutions. This shift challenges the business model of traditional component distributors while benefiting system integrators and platform-as-a-service (PaaS) providers. This pattern is most pronounced in the smart building and industrial automation sectors, where buyers demand turnkey operational insights.
IoT Sensor Market Segmentation
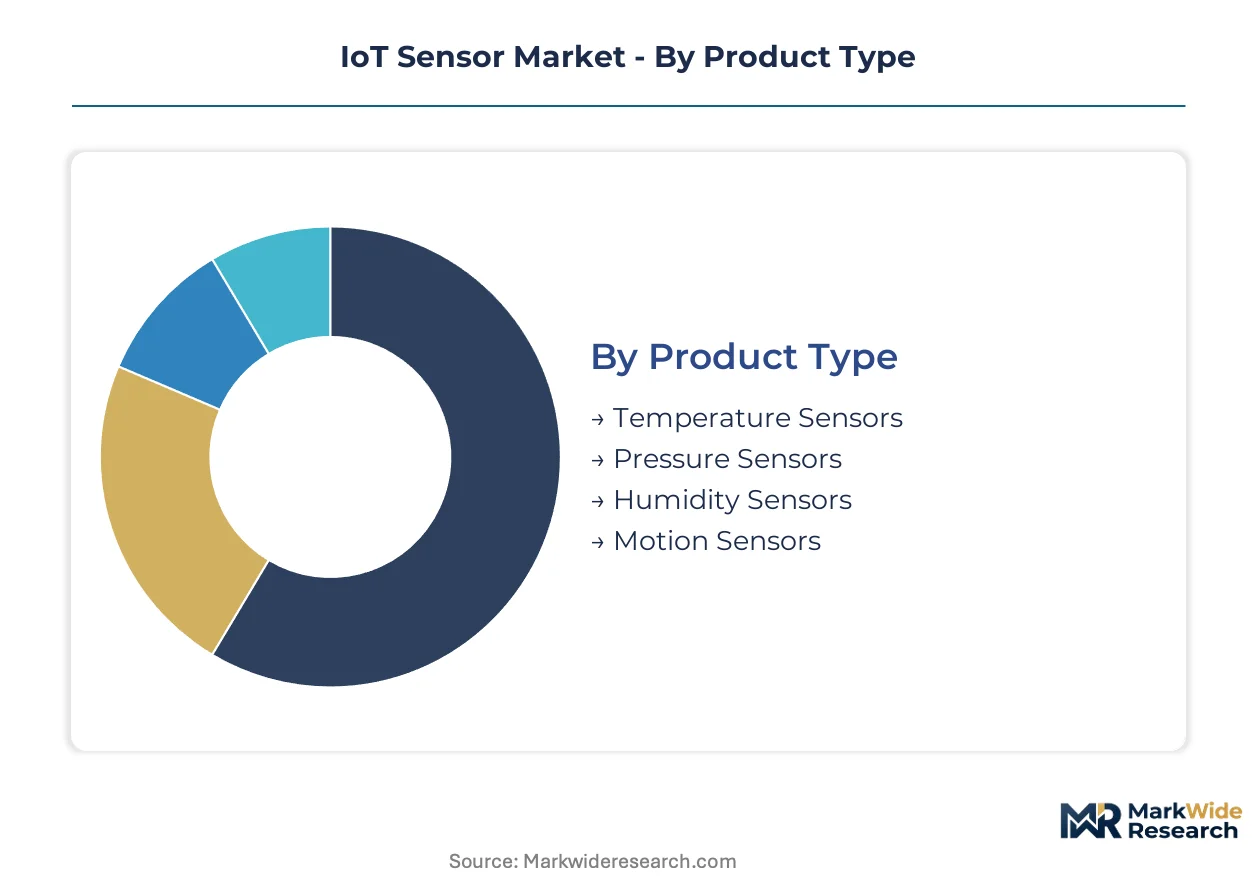
Segmenting the IoT sensor market reveals critical dynamics shaping product development and deployment strategies. Understanding these distinct categories allows stakeholders to align technological investments with specific end-user requirements and regulatory frameworks. This granular view highlights areas of concentrated demand and emerging opportunities across various industry verticals.
Product Type:
The product type spectrum ranges from highly standardized, foundational sensors to specialized, application-specific designs.
- Temperature Sensors:These devices measure heat energy, converting thermal changes into electrical signals for monitoring environments or processes. Demand concentrates in industrial automation and smart building applications, driven by energy efficiency mandates and predictive maintenance needs.
- Pressure Sensors:These components detect force applied over an area, translating physical pressure into an electrical output. The automotive sector and medical device manufacturing exhibit strong demand for high-accuracy pressure sensors, essential for safety systems and critical patient monitoring.
- Humidity Sensors:These devices quantify moisture content in the air or gases, crucial for environmental control and agricultural applications.
- Motion Sensors:Detecting physical movement or displacement, these sensors are integral to security systems and consumer electronics for user interaction.
Most installed capacity flows through Temperature Sensors. Expansion is steepest in Pressure Sensors.
Deployment:
Deployment models differentiate based on where data processing and intelligence reside, influencing latency and bandwidth requirements.
- Edge Computing:This model processes data directly at or near the sensor, reducing latency and bandwidth usage for real-time decision-making. Automotive ADAS systems and industrial robotics heavily leverage edge computing for immediate environmental perception and control.
- Cloud-Based:Data is transmitted to remote servers for processing, storage, and analysis, enabling large-scale data aggregation and complex analytics. Smart city initiatives and large-scale environmental monitoring projects frequently adopt cloud-based deployments for centralized control.
- On-Premises:All data processing and storage occur within the user's local infrastructure, offering enhanced security and direct control over sensitive information. Manufacturing facilities with stringent data sovereignty requirements prefer on-premises IoT sensor deployments.
- Hybrid:This approach combines elements of both cloud and on-premises or edge computing, optimizing for flexibility and specific workload requirements.
Edge Computing deployments are gaining share fastest. Cloud-Based deployments command the largest installed base.
End User:
End-user segments exhibit distinct requirements for sensor reliability, accuracy, and environmental robustness.
- Automotive:This sector demands high-reliability sensors for advanced driver-assistance systems (ADAS) and autonomous vehicle functions, critical for safety and performance. Vehicle control systems and in-cabin monitoring generate substantial sensor demand.
- Industrial:Industrial applications require ruggedized sensors capable of operating in harsh environments for process control, asset tracking, and predictive maintenance. Industry 4.0 initiatives in Germany drive significant sensor adoption for factory automation.
- Healthcare:Medical applications utilize IoT sensors for patient monitoring, remote diagnostics, and smart hospital management, requiring clinical-grade accuracy and data privacy compliance.
- Agriculture:Precision agriculture uses environmental sensors to monitor soil conditions, crop health, and livestock, optimizing resource use and yield.
The Industrial segment represents the largest volume consumption. The Automotive segment shows the most rapid expansion.
Connectivity:
Connectivity options vary by range, power consumption, and data throughput, dictating suitability for different IoT applications.
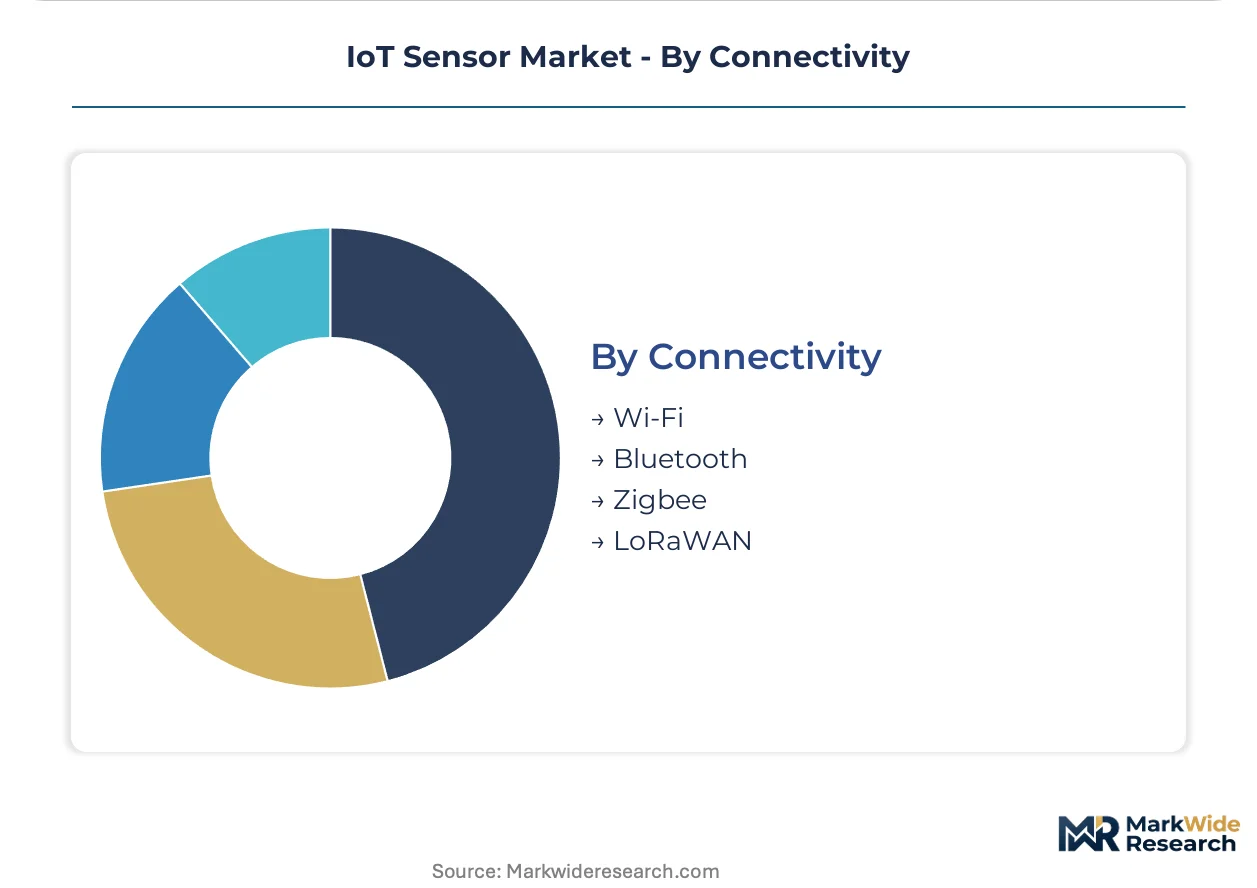
- Wi-Fi:This protocol offers high bandwidth for short-range communication, suitable for data-intensive applications within local area networks. Smart home devices and enterprise IoT deployments frequently rely on Wi-Fi for connectivity.
- LoRaWAN:A low-power, wide-area network (LPWAN) protocol, LoRaWAN enables long-range communication with minimal power consumption, ideal for remote monitoring. Smart agriculture and utility metering applications benefit from LoRaWAN's extended reach and battery life.
- Bluetooth:Known for short-range, low-power personal area networking, Bluetooth connects wearables and local device clusters.
- Zigbee:This low-power, low-data-rate wireless technology forms mesh networks, commonly found in smart lighting and home automation systems.
Wi-Fi modules account for the highest unit shipments. LoRaWAN connectivity is experiencing the most significant uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing infrastructure drives significant IoT sensor demand for Industry 4.0 applications. This strategic focus positions the country as a pivotal hub for sensor innovation and deployment. Other global regions also exhibit distinct demand patterns and regulatory landscapes.
Germany
Industry 4.0 initiatives in Germany create substantial demand for high-reliability sensors in automated manufacturing and predictive maintenance. The KBA, Germany's federal motor transport authority, mandates rigorous testing for automotive sensor components. Bavaria's automotive cluster, including cities like Stuttgart and Munich, spearheads sensor integration into advanced driver-assistance systems.
United States
The United States market sees strong demand for IoT sensors driven by smart city initiatives and industrial automation projects. Wireless communication modules within IoT sensors must comply with FCC regulations for market access. Silicon Valley continues as a key innovation hub, fostering sensor development for diverse applications, including edge computing.
China
China's rapid expansion in smart manufacturing and consumer electronics fuels significant IoT sensor adoption. GB standards mandate specific product conformity tests for electronic devices sold within the market. The Yangtze River Delta region, encompassing cities like Shanghai and Shenzhen, concentrates electronics production and sensor integration.
Japan
Advanced robotics and automotive sectors in Japan generate consistent demand for sophisticated IoT sensors. METI, the Ministry of Economy, Trade and Industry, supports research into next-generation sensor technologies. Tokyo's extensive tech ecosystem and large manufacturing base drive sensor development for industrial and consumer applications.
South Korea
South Korea's focus on smart homes and consumer electronics propels demand for compact, efficient IoT sensors. Devices require KC certification for compliance with national safety and electromagnetic compatibility standards. Gyeonggi Province, surrounding Seoul, is a major center for semiconductor manufacturing and sensor R&D.
IoT Sensor Market Key Industry Players
Global majors compete with regional champions across technology specialization and geographic reach. The IoT sensor market exhibits a tiered structure, with large diversified players alongside niche specialists. Strategic archetypes include integrated component providers and platform-focused solution developers. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Leading integrated component providers, such as Texas Instruments, leverage extensive analog and embedded processing portfolios to serve diverse industrial applications. Similarly, Bosch Sensortec, a German-based entity, exemplifies specialization in motion and environmental sensors, particularly for consumer electronics. STMicroelectronics, with its European roots, occupies a strong position through extensive microcontroller and sensor fusion expertise.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies |
| Honeywell International |
| TE Connectivity |
| Analog Devices |
| Bosch Sensortec |
| NXP Semiconductors |
| Sensirion |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Automotive OEMs, driven by ADAS requirements, heavily influence pricing structures for high-reliability sensors through long-term contracts. This demand for performance and consistent supply shapes a predominantly contract-based pricing model.
Pricing Analysis
Rising silicon wafer costs and specialized packaging materials are increasingly passed through to IoT sensor buyers, impacting overall unit economics. The market primarily operates on contract-based long-term agreements, especially for high-volume industrial and automotive applications. Price differentiation stems from automotive-grade certification levels and the degree of application-specific customization. Pricing softness in consumer electronics sensors reflects high volume competition, while industrial integrators are less price-sensitive for mission-critical deployments.
Supply Chain Analysis
Dual-sourcing requirements from major automotive and industrial clients mitigate single-point-of-failure risks within the IoT sensor supply chain. Supply concentrates heavily in East Asia, drawing from semiconductor fabrication in Taiwan, packaging in China, and specialized components from South Korea. Geopolitical tensions represent a significant structural risk, potentially disrupting the flow of critical microcontrollers and silicon. Distribution predominantly runs through direct sales channels to large OEMs and through specialized system integrators for complex industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT sensor market functions as a stable compounder, driven by the continuous integration of edge computing capabilities into sensor modules. This fundamental re-architecture ensures sustained demand across diverse end-user segments.
For Market Incumbents: Extend existing product portfolios with embedded AI capabilities to counter the threat of specialized edge AI startups. Deepen vertical integration into microcontroller design, leveraging R&D investments to enhance sensor fusion accuracy and reduce latency. Focus on securing long-term supply contracts with automotive and industrial clients to defend market share. Invest in advanced materials research to comply with evolving regulations like RoHS, reducing compliance overhead.
For New Entrants and Emerging Players: Launch via platform-as-a-service models targeting underserved precision agriculture and smart building sectors. Focus on developing full-stack monitoring solutions that simplify deployment for enterprise customers, reducing integration complexity. The smart agriculture segment offers the most penetrable entry point due to its underpenetration. Offer bundled cybersecurity-as-a-service to differentiate from traditional component suppliers.
For Investors and Strategic Acquirers: Industrial automation giants are the most active acquirers in this space, seeking to enhance their Industry 4.0 solution offerings. The long-term viability of the IoT sensor market spans a 5-10 year window, driven by digital transformation. Target acquisition archetypes include niche specialists in edge AI processing and sensor fusion, offering proprietary algorithms. A key signal to watch is the increasing standardization of communication protocols, which will unlock broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Edge AI-enabled Sensor Modules | This initiative reduces data latency and bandwidth requirements for real-time decision-making in autonomous systems. |
| Form Strategic Partnerships with System Integrators | These partnerships expand market reach for pre-integrated, full-stack monitoring solutions in industrial automation. |
| Acquire Sensor Fusion Expertise | Acquisition of specialized firms enhances accuracy and reliability for complex environmental perception applications. |
| Expand Manufacturing Footprint in Germany | Localizing production supports Industry 4.0 initiatives and complies with stringent regional quality standards. |
| Invest in RoHS-Compliant Materials | Adopting new materials ensures market access in Europe and mitigates hazardous substance regulatory risks. |
Research Approach
Multiple input streams — primary interviews, industry reports, and regulatory filings — were reconciled to construct a robust dataset. Interviews engaged R&D directors, procurement managers, and system architects across automotive and industrial sectors. Secondary validation drew from SEC 10-K filings, trade association publications, and national regulatory body documents like FCC and KBA. This approach employed both bottom-up market sizing and top-down validation to ensure data integrity.
Data stream reconciliation informed the analytical framework across the analysis window, integrating historical trends with future projections. Segmentation dimensions modeled included product type, deployment model, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from a weighted average of market drivers, restraints, and strategic opportunities. Key forecast inputs included projected connected vehicle production volumes and Industry 4.0 investment trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological disruption or unforeseen geopolitical shifts. Forecasts reflect assumptions regarding regulatory stability and sustained industrial investment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Body Worn Temperature Sensors Market