
 Smart Hydrophone Market | 2026-2036
Smart Hydrophone Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Hydrophone Market Insights
China's coastal manufacturing zone for underwater acoustic instruments is fragmenting as domestic MEMS foundries and piezoelectric ceramic suppliers multiply. Teledyne Reson leverages its Danish heritage and North Sea service infrastructure to sustain premium positioning in multibeam calibration. Ocean Sonics anchors its footprint through Nova Scotia-based production tailored to environmental compliance monitoring. Brüel & Kjær competes on transducer precision for defense-grade vector hydrophone arrays.
A smart hydrophone is an instrumented underwater acoustic sensor that converts pressure fluctuations into electrical or optical signals, typically operating across bandwidths from infrasonic frequencies below 1 Hz to ultrasonic ranges exceeding 100 kHz, with integrated digital signal processing for real-time beamforming and noise suppression. Its primary commercial purpose is to enable persistent, networked observation of submarine environments for security, resource extraction, and climate science. Passive hydrophone configurations retain dominant volume share in defense and seismic monitoring, while fiber optic interferometric designs are displacing legacy piezoelectric systems in deep-ocean deployments where electromagnetic immunity matters. The aquaculture application segment shows the steepest trajectory as Norway and Scotland mandate real-time cetacean and predator detection at salmon farm perimeters.
ISO 17208-1 underwater acoustic measurement standards and the EU Marine Strategy Framework Directive shape product certification requirements for European suppliers, while China's MEE enforces noise thresholds at offshore wind construction sites. The US Navy's testing ranges operate under NOAA marine mammal protection oversight, creating dual compliance burdens for defense contractors. Stakeholders must weigh captive versus outsourced MEMS fabrication as supply chain geography becomes a procurement criterion rather than a cost variable.
Market Dynamics
Defense procurement programs across NATO member states are accelerating adoption of passive and multibeam arrays, while China's dual carbon goals and marine spatial planning directives are reshaping environmental monitoring requirements. This dual-track demand structure is concentrating supply chain investment in specialized subsea technology clusters.
Growth Catalysts
- Norway's salmon farm mandates:Real-time cetacean and predator detection requirements at aquaculture perimeters are pulling fiber optic interferometric systems into volume deployment.
- ISO 17208-1 certification pull:European suppliers face structured demand for calibrated underwater acoustic measurement standards across offshore wind construction monitoring.
- MEE noise thresholds:China's offshore wind construction site regulations are forcing real-time acoustic monitoring integration into project execution timelines.
Market Restraints
- Piezoelectric ceramic supply concentration:Domestic MEMS foundry fragmentation in China's coastal manufacturing zone is creating quality inconsistency for precision transducer sourcing.
- Deep-ocean electromagnetic immunity requirements:Fiber optic interferometric designs face technical limitation in shallow-water cost-sensitive deployments where legacy piezoelectric systems retain economic advantage.
- Dual compliance burdens:US Navy testing ranges operating under NOAA marine mammal protection oversight create regulatory friction for defense contractors balancing security and environmental protocols.
Strategic Opportunities
- Scotland's expanding aquaculture perimeter:Underpenetrated deployment of networked predator detection systems at salmon farms outside Norway's technology cluster offers first-mover positioning.
- EU Marine Strategy Framework Directive:Regulatory tailwind for persistent acoustic monitoring is creating certified product demand that favors established European calibration infrastructure.
- MEMS-piezoelectric convergence:Technology convergence between microelectromechanical fabrication and precision ceramic transduction is enabling miniaturized vector hydrophone arrays for unmanned underwater vehicles.
Industry Challenges
- Multibeam calibration expertise scarcity:Specialized acoustic metrology skill gaps are extending deployment timelines for defense-grade vector hydrophone arrays requiring precision beamforming validation.
- Captive versus outsourced MEMS fabrication decisions:Supply chain reconfiguration friction is forcing stakeholders to weigh fabrication geography as procurement criterion rather than cost variable.
- Legacy system integration complexity:Real-time beamforming and noise suppression capabilities require substantial capex for retrofitting existing passive monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Hydrophone Market |
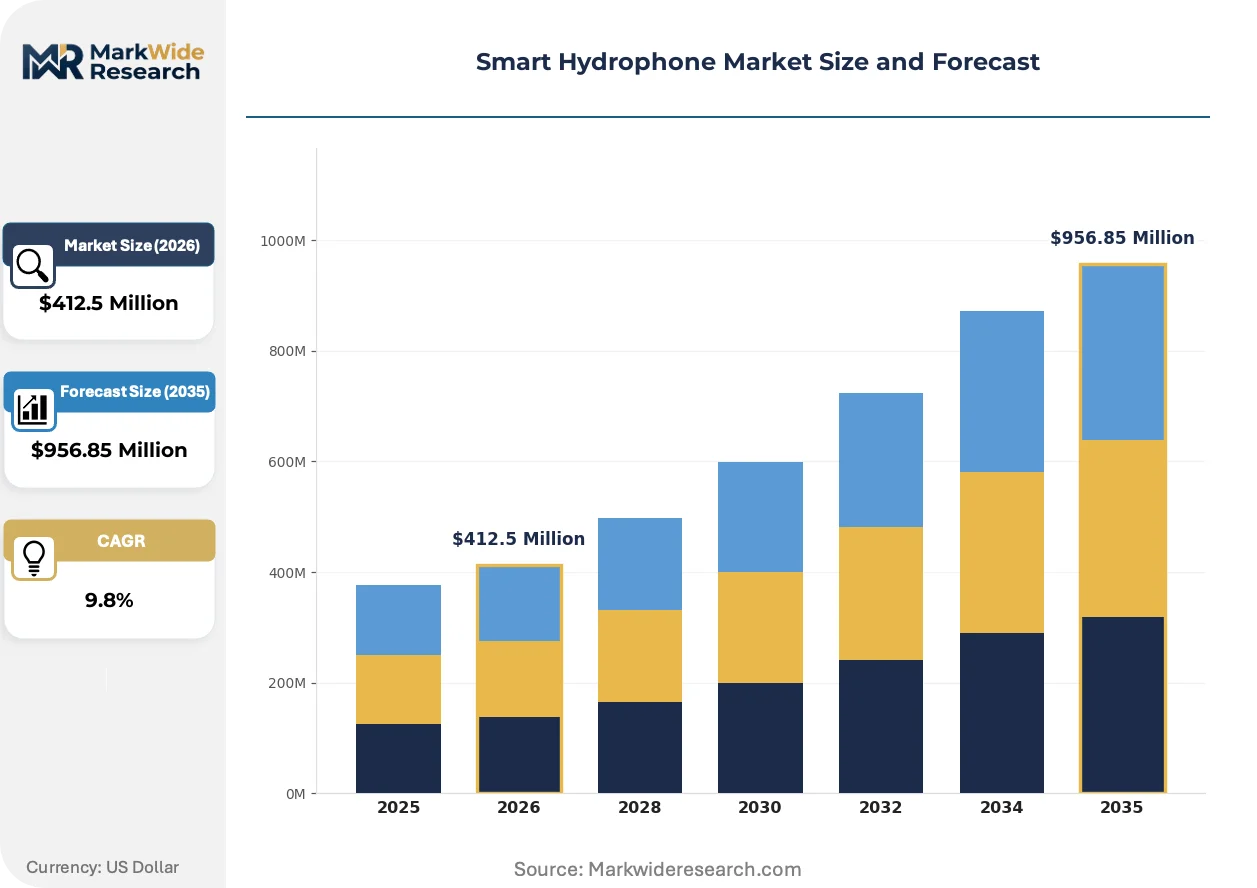
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Hydrophone, Passive Hydrophone, Multibeam Hydrophone, Vector Hydrophone Technology: Fiber Optic, MEMS, Piezoelectric, Electromechanical End User: Marine Research, Defense, Energy & Utilities, Environmental Monitoring Application: Underwater Communication, Seismic Monitoring, Oceanographic Research, Aquaculture |
| Companies Covered | Teledyne Reson, Ocean Sonics, Brüel & Kjær, Sa Electronica Submarina, Seabed BV, Metas AS, Sea and Land Technologies, Aquarian Audio, GeoSpectrum Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Hydrophone Market Trends and Innovations
Fiber optic sensing architectures are actively reshaping competitive positioning in deep-ocean deployments, while regulatory certification requirements are hardening product development timelines. These forces are compressing the window for technology differentiation.
Photonic interferometric hydrophones are hybridizing pressure fluctuation detection with intrinsic immunity to electromagnetic interference. Offshore wind developers in the North Sea are adopting these systems at accelerated pace for construction-phase marine mammal monitoring. This architecture is hybridizing the traditional trade-off between deep-ocean performance and shallow-water cost economics, enabling unified procurement specifications across water depth categories.
China's MEE noise threshold enforcement at offshore wind construction sites is mandating real-time acoustic monitoring integration into environmental impact assessments. Industrial consequence includes mandatory sensor deployment timelines that precede foundation installation. Offshore wind construction segments in China's coastal provinces are responding by pre-qualifying suppliers with established MEE certification pathways.
Buyers are consolidating vendor relationships around calibration service capability rather than hardware transaction economics. Defense contractors and energy majors are disintermediating traditional distribution channels in favor of direct technical partnerships with manufacturers maintaining North Sea service infrastructure. This pattern is most visible in Norway's Bergen and Trondheim subsea technology cluster, where co-location of research institutions and energy headquarters enables integrated procurement of measurement systems with ongoing metrology support.
Smart Hydrophone Market Segmentation
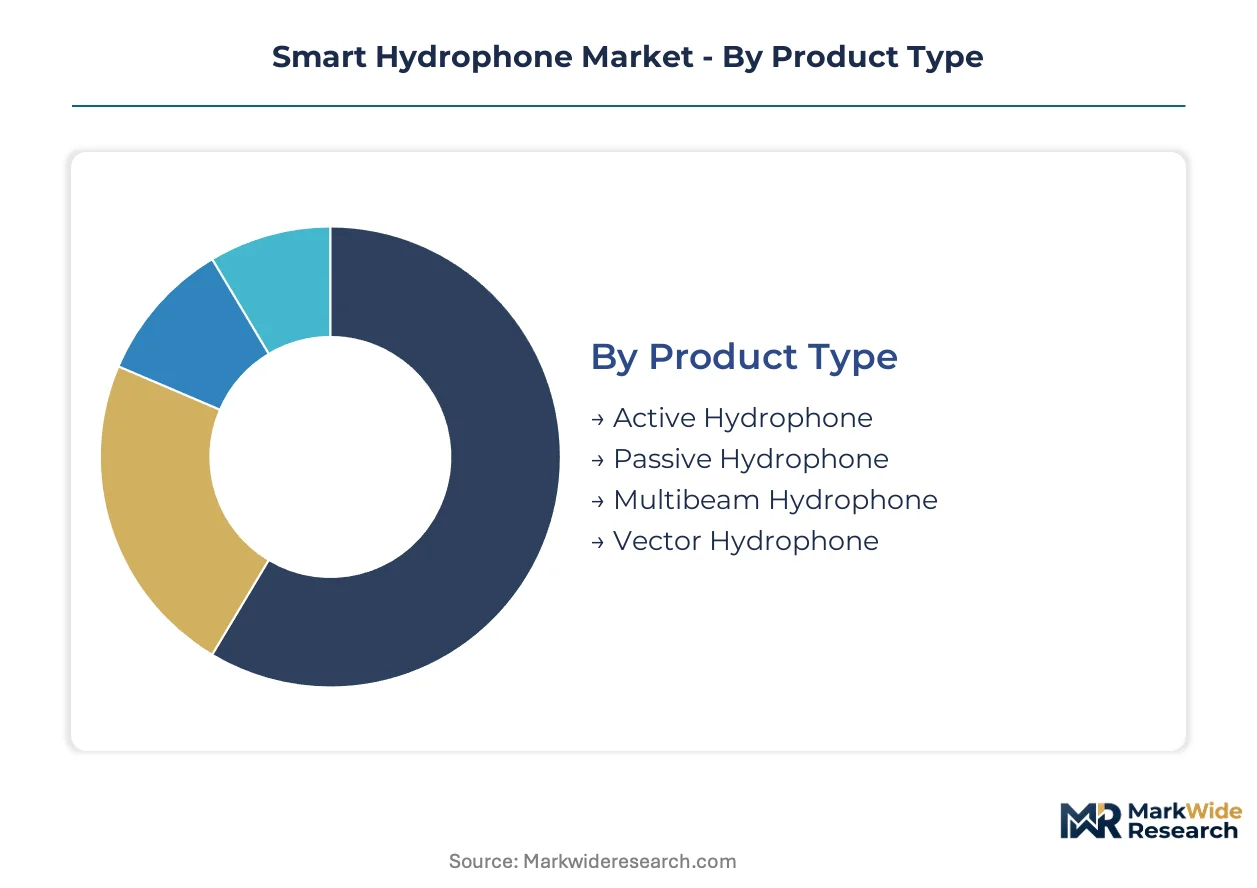
Smart hydrophone procurement patterns diverge sharply by deployment environment and compliance burden. Defense-grade vector arrays command extended validation cycles, while aquaculture perimeter systems turn over on annual replacement schedules tied to regulatory re-certification.
Product Type:
Passive hydrophone configurations retain the longest field service life, often exceeding fifteen years in deep-ocean observatories. Multibeam and vector arrays face compressed replacement cycles driven by beamforming algorithm obsolescence and calibration drift.
- Passive Hydrophone:Single-element or sparse array designs convert acoustic pressure fluctuations without active signal emission, minimizing power consumption and detection vulnerability. NATO member states concentrate procurement for seabed surveillance networks, where electromagnetic silence and mechanical reliability outweigh upgrade frequency. Long procurement cycles and defense budget predictability sustain incumbent supplier relationships.
- Multibeam Hydrophone:Arrayed transducer configurations enable simultaneous multiple-angle acoustic sampling through integrated beamforming electronics. Offshore wind developers in the North Sea deploy these for construction-phase marine mammal monitoring, pulled by ISO 17208-1 certification requirements and real-time noise threshold compliance. Replacement demand concentrates where calibration infrastructure is co-located.
- Active Hydrophone:Self-emitting sonar systems with integrated source and receiver elements for target interrogation.
- Vector Hydrophone:Tri-axial particle velocity sensors combined with pressure transducers for directional acoustic characterization.
Passive hydrophone dominates installed base. Multibeam hydrophone is where expansion concentrates.
Technology:
Piezoelectric ceramic systems occupy the lowest cost tier but face supply fragmentation. Fiber optic architectures command premium positioning where electromagnetic immunity justifies capex intensity.
- Fiber Optic:Interferometric sensing architectures modulate laser phase through pressure-induced optical path length variation, eliminating conductive elements and enabling kilometer-scale cable deployments. China's offshore wind construction sites under MEE noise threshold enforcement are pulling volume adoption for foundation-phase environmental monitoring. Deep-ocean immunity requirements sustain pricing power despite shallow-water cost disadvantages.
- Piezoelectric:Ceramic transducer elements generate electrical charge through mechanical strain under acoustic pressure, leveraging mature manufacturing processes and established calibration protocols. Norway's salmon farm perimeter mandates drive replacement volume for cetacean detection systems, though domestic MEMS foundry fragmentation in China's coastal zones creates sourcing inconsistency for precision ceramic suppliers.
- MEMS:Microelectromechanical fabrication enables miniaturized pressure sensing structures with batch-processed consistency.
- Electromechanical:Traditional moving-coil or variable-capacitance transduction for specialized low-frequency applications.
Piezoelectric dominates installed base. Fiber optic is where expansion concentrates.
End User:
Defense procurement operates on multi-year program cycles with embedded service contracts. Environmental monitoring segments exhibit volatile spike demand tied to construction permitting timelines.
- Defense:Passive and multibeam arrays for submarine detection, seabed surveillance, and underwater navigation supporting NATO member state procurement programs. US Navy testing ranges operate under NOAA marine mammal protection oversight, creating dual compliance burdens that extend vendor qualification timelines and favor established calibration service providers.
- Environmental Monitoring:Persistent acoustic observation for regulatory compliance, species distribution mapping, and noise impact assessment. China's MEE enforces real-time monitoring integration at offshore wind construction sites, mandating sensor deployment before foundation installation and creating pre-qualified supplier concentration.
- Marine Research:Academic and institutional deployments for oceanographic process studies and long-term observatory networks.
- Energy & Utilities:Subsea infrastructure monitoring, pipeline leak detection, and offshore platform integrity assessment.
Defense dominates installed base. Environmental monitoring is where expansion concentrates.
Application:
Aquaculture perimeter systems turn over fastest due to biofouling and mechanical damage. Seismic monitoring arrays persist for decades with incremental sensor refresh.
- Aquaculture:Real-time cetacean and predator detection at salmon farm perimeters, now mandated in Norway and expanding to Scotland. Fiber optic interferometric systems are climbing fastest as networked perimeter coverage replaces single-point deterrents.
- Seismic Monitoring:Ocean-bottom cable arrays for earthquake detection, tsunami warning, and hydrocarbon exploration.
- Underwater Communication:Acoustic modem networks for subsea data transmission and autonomous vehicle coordination.
- Oceanographic Research:Long-term acoustic observation for climate process studies and ecosystem monitoring.
Seismic monitoring dominates installed base. Aquaculture is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea subsea cable infrastructure underwrites Norway's central role in smart hydrophone deployment, with Bergen and Trondheim hosting co-located energy headquarters and research institutions that drive integrated procurement.
United States
US Navy testing ranges and NOAA marine mammal protection oversight create dual compliance demand for defense-grade vector arrays. The EPA and NOAA jointly administer environmental protocols that extend vendor qualification timelines. The Pacific Northwest hosts concentrated calibration service providers supporting both military and research deployments.
Norway
Salmon farm perimeter mandates for real-time cetacean detection pull fiber optic interferometric systems into volume deployment. National aquaculture regulations require networked predator detection at licensed farm boundaries. The Bergen-Trondheim corridor concentrates subsea technology clusters where energy majors co-locate with measurement system suppliers.
China
Offshore wind construction sites under MEE noise threshold enforcement mandate real-time acoustic monitoring integration before foundation installation. The dual carbon goals and marine spatial planning directives reshape environmental monitoring procurement timelines. Coastal manufacturing zones around Shanghai and Guangdong fragment as domestic MEMS foundries multiply.
United Kingdom
Scotland's expanding aquaculture perimeter offers underpenetrated deployment opportunities for networked predator detection systems. The EU Marine Strategy Framework Directive shapes certification requirements for persistent acoustic monitoring products. Aberdeen's subsea engineering cluster supports North Sea offshore wind construction monitoring demand.
Germany
North Sea offshore wind developers adopt multibeam arrays for construction-phase marine mammal monitoring under ISO 17208-1 certification requirements. The EU Green Deal accelerates renewable energy infrastructure deployment with embedded acoustic compliance. Hamburg and Bremerhaven harbor subsea service infrastructure serving Baltic and North Sea projects.
Smart Hydrophone Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in transducer and signal processing supply. The vendor base separates into three strata: defense contractors with embedded service contracts, environmental monitoring specialists with calibration infrastructure, and emerging MEMS fabricators chasing cost-sensitive volume. Strategic moves concentrate on geographic co-location with energy majors and backward integration into ceramic transducer supply.
Within the calibration-anchored tier, Teledyne Reson and Ocean Sonics occupy positions shaped by proximity to North Sea demand. Brüel & Kjær represents the precision transducer archetype for defense-grade applications. These three exemplify how service infrastructure co-location with research institutions and energy headquarters determines competitive positioning more than hardware transaction economics.
| Leading Market Players |
|---|
| Teledyne Reson |
| Ocean Sonics |
| Brüel & Kjær |
| Sa Electronica Submarina |
| Seabed BV |
| Metas AS |
| Sea and Land Technologies |
| Aquarian Audio |
| GeoSpectrum Technologies |
| Others |
Pricing and Supply Chain Analysis
Norway's Bergen-Trondheim subsea technology cluster concentrates calibration service capacity, giving co-located suppliers pricing power over defense contractors and energy majors who bundle hardware procurement with ongoing metrology support. China's coastal MEMS foundry fragmentation erodes ceramic transducer pricing discipline, forcing buyers to treat fabrication geography as a procurement criterion rather than cost variable.
Pricing Analysis
Volume-discount tiering structures separate defense-grade vector hydrophone arrays from aquaculture perimeter systems and environmental monitoring deployments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 17208-1 calibrated multibeam systems commanding sustained premiums. Cost compression in piezoelectric ceramic sourcing is intensifying because domestic foundry multiplication in China's coastal zones creates quality inconsistency. Aquaculture operators in Norway and Scotland exhibit highest price sensitivity due to annual re-certification cycles, while NATO defense programs show lowest sensitivity given embedded long-term service contracts.
Supply Chain Analysis
Contract-manufacturing concentration rests on Danish heritage facilities serving Teledyne Reson's North Sea infrastructure, Nova Scotia-based production anchoring Ocean Sonics' environmental compliance focus, and Brüel & Kjær's precision transducer operations. Geographic supply concentration draws from Denmark, Norway, and China's coastal provinces. Raw material dependencies center on piezoelectric ceramics, optical fiber cable assemblies, and MEMS fabrication substrates. Single-source vulnerability pervades specialized acoustic metrology skill gaps extending beamforming validation timelines. Distribution runs through direct technical partnerships disintermediating traditional channels, with energy majors and defense contractors favoring manufacturers maintaining regional service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision acoustic metrology expertise functions as the binding constraint across deployment timelines, with multibeam calibration capability scarcity determining vendor selection more than hardware specifications. This capability gap separates incumbent service-anchored suppliers from component-focused challengers.
For Market Incumbents: Build calibration service moats through co-location with North Sea energy headquarters and research institutions in Bergen and Trondheim. Add captive MEMS fabrication capacity in Denmark or Norway to offset China's ceramic transducer quality fragmentation. ISO 17208-1 certification investment functions as the defensive lever against emerging fiber optic specialists lacking established metrology infrastructure. For New Entrants and Emerging Players: Scotland's expanding salmon farm perimeter outside Norway's technology cluster represents the most penetrable entry point for networked predator detection systems. China's offshore wind construction sites under MEE noise threshold enforcement offer second-mover positioning for fiber optic interferometric suppliers with pre-qualified certification pathways. Direct technical partnership with Scottish aquaculture operators bypasses established Norwegian vendor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors calibration-anchored environmental monitoring specialists over defense hardware pure-plays. Long-term viability across the analysis window rests on service infrastructure co-location with energy majors rather than transactional component sales. Acquisition target archetype combines fiber optic sensing IP with established MEE or ISO 17208-1 certification pathways. Watch for inflection in Norway's aquaculture mandate expansion rate and China's offshore wind construction permitting velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Co-location | Proximity to Bergen-Trondheim energy headquarters locks in defense and offshore wind procurement relationships. |
| MEMS-Piezoelectric Convergence R&D | Miniaturized vector hydrophone arrays for unmanned underwater vehicles open unmanned platform integration revenue. |
| MEE Certification Pre-qualification | Early pathway establishment captures China's offshore wind construction monitoring mandate before competitor saturation. |
| Scotland Aquaculture Direct Partnership | First-mover positioning in underpenetrated salmon farm perimeter networks outside Norwegian vendor strongholds. |
| Fiber Optic Interferometric Scale-up | Deep-ocean electromagnetic immunity advantages extend into shallow-water cost economics through manufacturing learning. |
Research Methodology
A spread of perspectives from defense procurement officers at NATO member states, offshore wind project developers in the North Sea, aquaculture operations managers in Norway and Scotland, acoustic metrology specialists, and MEMS fabrication engineers converged on the working assumptions. Primary interview insights combined with secondary validation from ISO 17208-1 certification records, MEE noise threshold enforcement documentation, EU Marine Strategy Framework Directive implementation reports, and customs trade data for underwater acoustic instrument categories. Bottom-up unit deployment estimates across passive, multibeam, and vector hydrophone configurations triangulated against top-down market sizing from defense budget allocations and renewable energy infrastructure investment flows.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, technology architecture, end-user procurement cycle, and application replacement frequency. CAGRs derived from deployment timeline elasticity to regulatory mandate implementation rates and construction permitting velocity. Industry-specific forecast inputs incorporated salmon farm licensing expansion trajectories and offshore wind foundation installation schedules.
Macroeconomic conditions sit as an overlay; deviation in defense budget predictability, renewable energy infrastructure investment flows, or ceramic transducer input costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory mandate enforcement consistency and technology substitution rates. Quarterly review of NATO procurement program announcements, MEE certification pathway updates, and MEMS foundry capacity additions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Meteorological Devices Market