
 Factory Automation Sensor Market | 2026-2036
Factory Automation Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Factory Automation Sensor Market Analysis
Aftermarket service revenue is reshaping margin capture across the factory automation sensor landscape. Siemens leverages its digital service platforms to extend lifecycle value beyond hardware shipments. Rockwell Automation anchors North American channel control through integrated motion and sensing portfolios. Honeywell International competes on hazardous-environment certification depth in oil and gas deployments.
Factory automation sensors are electromechanical or solid-state devices that detect physical properties—displacement, temperature, pressure, or optical reflectance—and convert them into processable electrical signals, typically operating at voltage ranges from five to twenty-four volts DC with response times under one millisecond for high-speed assembly applications. Their primary industrial purpose is to enable closed-loop control, predictive maintenance triggers, and zero-defect quality gates in continuous-flow manufacturing environments. Proximity sensors dominate unit volume across assembly line applications where ferrous and non-ferrous object detection must survive coolant immersion and vibration cycles. Optical technology segments command premium positioning in cleanroom semiconductor and pharmaceutical packaging lines where sub-millimeter resolution is mandatory. Pressure sensors sustain replacement-cycle profitability in energy and oil and gas process control, where calibration drift mandates scheduled sensor swaps.
The EU AI Act, CE marking under the Machinery Directive, and FCC Part 15 emissions standards collectively dictate electromagnetic compatibility thresholds, functional safety integrity levels, and algorithmic transparency for AI-enabled sensing systems. OSHA lockout/tagout regulations in the United States further shape demand for redundant safety-rated proximity switches in heavy manufacturing cells. Stakeholders must monitor how converging cybersecurity mandates for operational technology networks alter sensor firmware architecture and supplier qualification timelines.
Market Dynamics
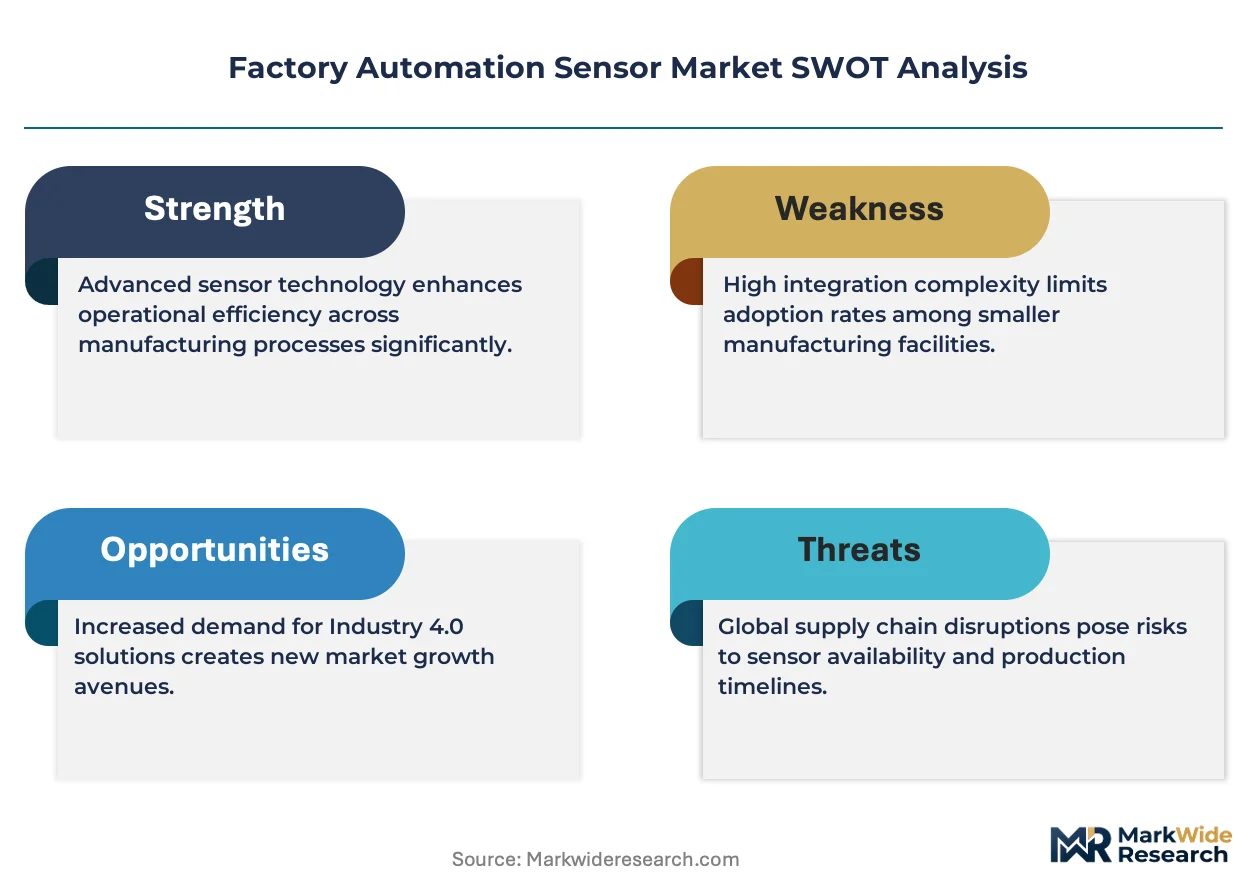
EU AI Act compliance deadlines and CE marking under the Machinery Directive are compressing supplier qualification timelines while forcing firmware architecture redesigns across proximity, optical, and pressure sensor portfolios.
Growth Catalysts
- Automotive assembly expansion:OEMs in Germany, Japan, and the United States are embedding multi-sensor arrays for real-time quality gates and predictive maintenance triggers on high-speed production lines.
- EU AI Act mandates:Algorithmic transparency requirements for AI-enabled sensing systems are accelerating replacement cycles of legacy electromechanical devices with firmware-upgradeable solid-state alternatives.
- OSHA lockout/tagout enforcement:Heavy manufacturing cells across the United States must install redundant safety-rated proximity switches, creating baseline demand for certified industrial sensors.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing facilities exposes proximity sensor manufacturers to input cost volatility and export restriction risk.
- Semiconductor fabrication bottlenecks:Photodiode and CMOS image sensor foundry capacity constraints in Taiwan and South Korea extend lead times for optical sensor modules beyond 26 weeks.
- Functional safety certification friction:IEC 61508 SIL 3 validation for safety-rated sensors requires 18-24 month third-party assessment cycles that delay product commercialization.
Strategic Opportunities
- India smart manufacturing corridors:PLI scheme incentives for electronics manufacturing and industrial automation are attracting sensor suppliers to Gujarat and Tamil Nadu industrial clusters.
- Hydrogen economy sensor demand:Pressure and gas detection sensors for electrolyzer and fuel cell manufacturing represent an emerging application vertical with limited incumbent specialization.
- Edge AI convergence:On-device inference capability is hybridizing with traditional sensing hardware, enabling millisecond-latency defect detection without cloud dependency.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers proficient in real-time operating systems and IEC 62304 medical device software standards constrains product development velocity.
- Legacy PLC integration complexity:Brownfield manufacturing environments running Rockwell or Siemens legacy control architectures require costly gateway hardware to interface with modern IO-Link sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factory Automation Sensor Market |
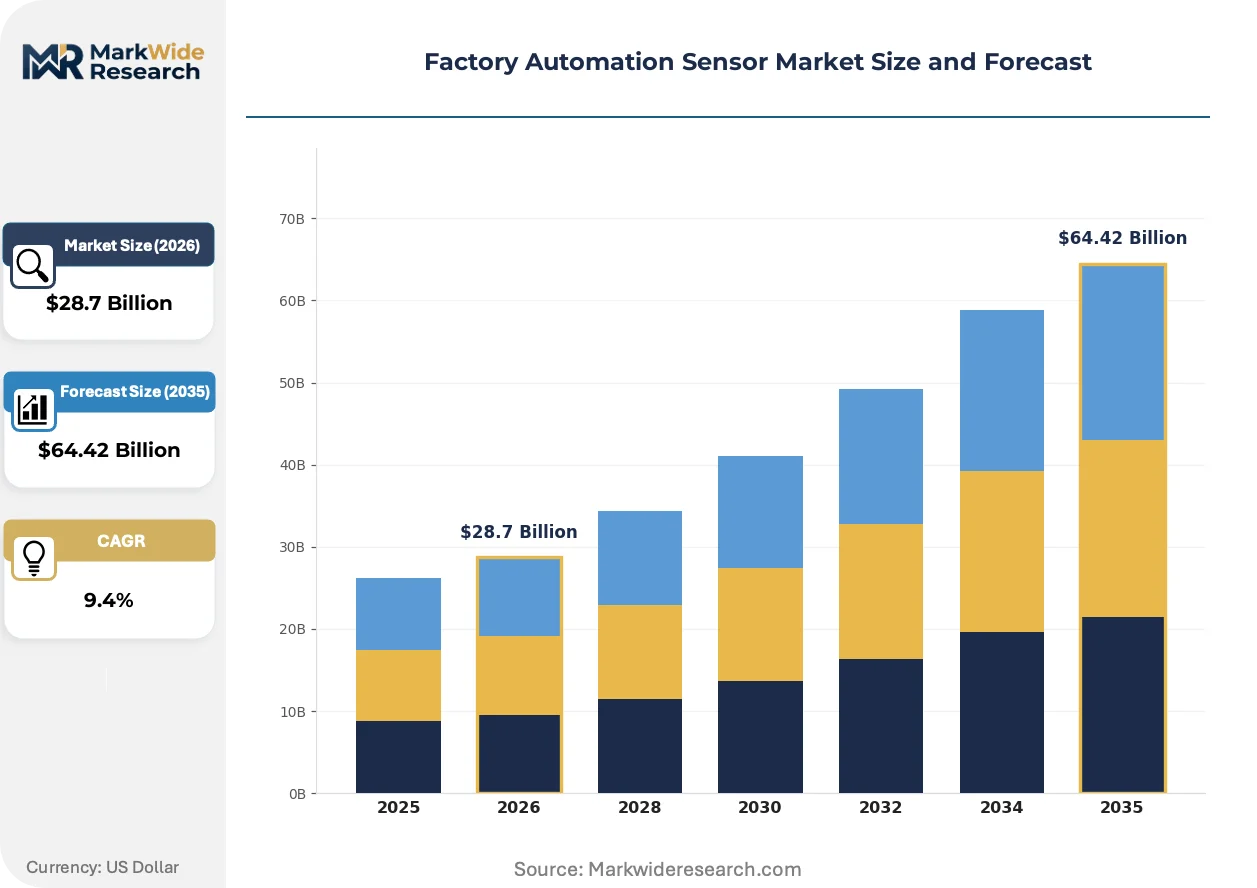
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proximity Sensors, Temperature Sensors, Pressure Sensors, Light Sensors Technology: Inductive, Capacitive, Optical, Ultrasonic End User: Manufacturing, Energy, Oil & Gas, Automotive Application: Assembly Lines, Process Control, Quality Assurance, Safety Monitoring |
| Companies Covered | Rockwell Automation, Honeywell International, Texas Instruments, Panasonic Corporation, STMicroelectronics, Siemens, ABB, Analog Devices, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factory Automation Sensor Market Emerging Trajectories
Sensor architectures are fragmenting between edge-intelligent devices and cloud-dependent systems, with regulatory pressure and cybersecurity mandates determining which pathway dominates specific end-use verticals.
Time-of-flight optical sensing is hybridizing with structured light projection to deliver sub-millimeter depth mapping for robotic bin-picking and semiconductor wafer handling. Automotive tier-one suppliers in Germany and Japan are adopting these hybrid modules at pilot scale, with production ramp expected across EV battery assembly lines. The technology is compressing the addressable market for standalone laser displacement sensors by consolidating multiple measurement functions into single-device footprints.
EU AI Act algorithmic transparency requirements are forcing sensor suppliers to document training data provenance and decision-boundary logic for AI-enabled defect detection systems. Industrial OEMs in pharmaceutical packaging and medical device manufacturing face the steepest compliance burdens, with CE marking audits now incorporating software bill-of-materials reviews. German sensor specialists are responding by partitioning firmware into certified deterministic cores and sandboxed machine learning inference engines.
Aftermarket service unbundling is disrupting traditional hardware-plus-maintenance contract structures in North American automotive and oil and gas verticals. End-users are purchasing sensors through distributor channels while sourcing calibration and firmware update services directly from manufacturer digital platforms, compressing distributor margin capture. This pattern is most visible in Texas and Louisiana process control installations, where Honeywell and Emerson field service organizations are building direct customer relationships independent of original equipment procurement channels.
Factory Automation Sensor Market Segmentation
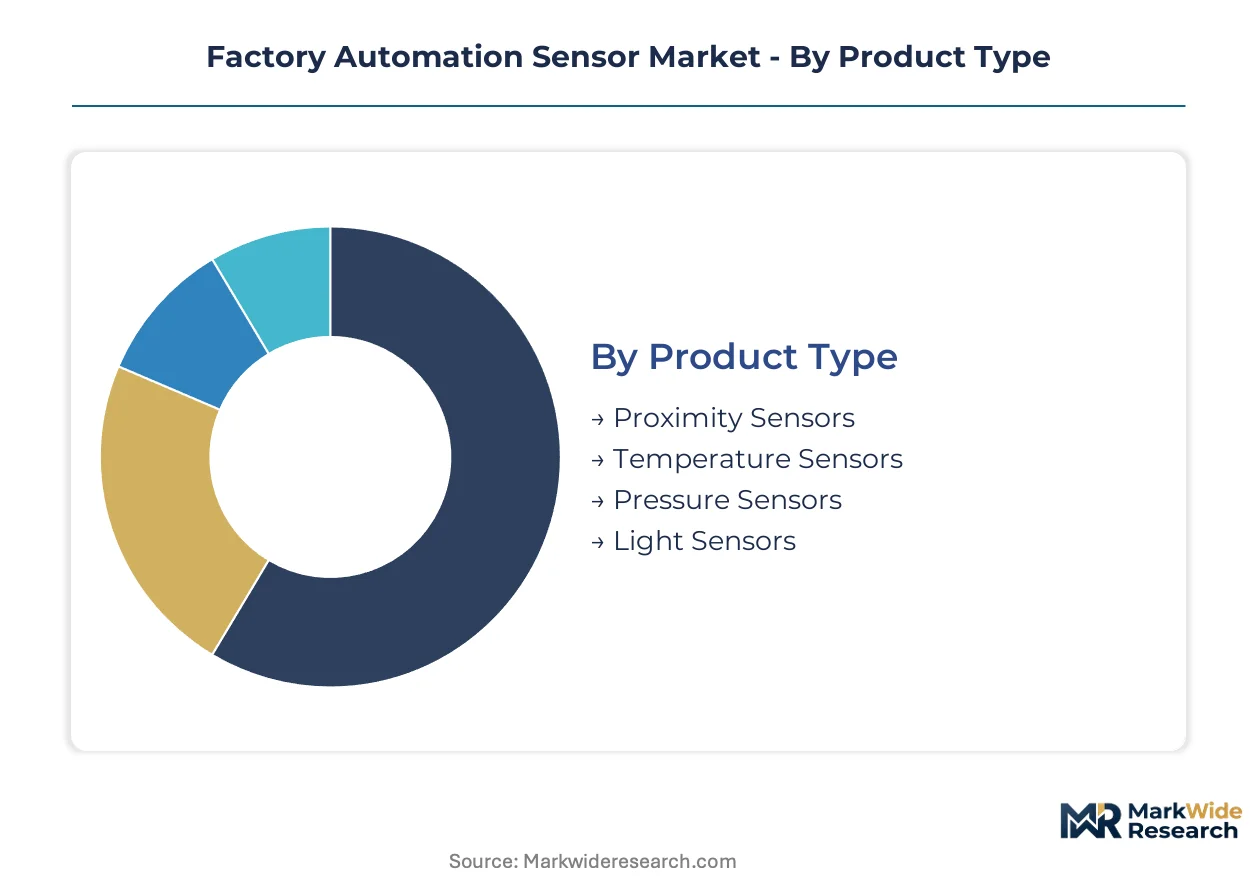
Segmentation in factory automation sensors determines where aftermarket service revenue concentrates and which technical specifications command calibration-dependent recurring income. Product architecture, sensing modality, and end-use severity collectively shape replacement-cycle predictability and margin durability across supplier portfolios.
Product Type:
Aftermarket service intensity varies sharply by product type, with calibration drift sensitivity and environmental exposure determining lifecycle value capture for sensor manufacturers.
- Proximity Sensors:These solid-state devices detect ferrous and non-ferrous metallic objects through electromagnetic field disruption, typically operating at sensing distances from two to forty millimeters. Automotive assembly lines in Germany and Japan embed these in coolant-immersed machining stations where vibration cycles accelerate wear, driving scheduled replacement programs and firmware update revenue streams.
- Pressure Sensors:Piezoelectric or strain-gauge transducers measure fluid and gas pressure across ranges from vacuum to thousands of PSI, requiring periodic calibration to counter drift in process control environments. Oil and gas deployments in Texas and Louisiana generate sustained aftermarket demand through hazardous-area certification maintenance and sensor swap protocols mandated by safety audits.
- Temperature Sensors:Thermocouple and RTD-based devices track thermal profiles in heat-treatment and extrusion processes.
- Light Sensors:Photodiode and phototransistor assemblies detect ambient or reflected light intensity for presence and position verification.
By volume, Proximity Sensors leads. By growth pace, Pressure Sensors is ahead.
Technology:
Technology selection correlates directly with foundry capacity constraints and semiconductor content, creating divergent supply risk profiles across sensor architectures.
- Optical:CMOS image sensors and photodiode arrays deliver sub-millimeter resolution for cleanroom semiconductor and pharmaceutical packaging applications. Taiwan and South Korea foundry bottlenecks extend lead times beyond twenty-six weeks, compressing availability for high-precision modules while sustaining premium pricing.
- Inductive:Coil-based electromagnetic sensing dominates ferrous metal detection in heavy manufacturing cells where coolant immersion and metallic debris are constant. OSHA lockout/tagout enforcement across United States automotive plants creates baseline demand for redundant safety-rated inductive switches with SIL 3 certification.
- Capacitive:Electric field variation detection enables non-metallic object sensing and liquid level monitoring.
- Ultrasonic:Time-of-flight acoustic ranging supports distance measurement in dusty or transparent-object environments.
Optical commands the highest unit margins. Inductive ships the greatest aggregate volume.
End User:
End-user verticals segment by process severity and regulatory exposure, with hazardous-environment certifications creating supplier stickiness in energy-intensive applications.
- Automotive:EV battery assembly and powertrain manufacturing deploy multi-sensor arrays for real-time quality gates. Germany and Japan OEMs are expanding sensor density on high-speed lines to enable predictive maintenance triggers and zero-defect protocols.
- Oil & Gas:Offshore platforms and downstream refineries demand explosion-proof housings and SIL-rated redundancy. Honeywell and Emerson field service organizations in Texas and Louisiana are building direct customer relationships through calibration and firmware services independent of original procurement channels.
- Manufacturing:General industrial automation spans packaging, material handling, and machine tool applications.
- Energy:Power generation and grid infrastructure utilize sensors for turbine monitoring and transformer thermal management.
Automotive generates the densest sensor counts per facility. Oil and Gas produces the highest service attach rates.
Application:
Application context determines response-time requirements and integration complexity, with safety-critical functions commanding stricter certification burdens than process optimization roles.
- Safety Monitoring:Redundant proximity and pressure switches enforce machine guarding and emergency shutdown protocols. EU Machinery Directive CE marking and OSHA regulations in the United States mandate functional safety integrity levels that extend supplier qualification timelines.
- Quality Assurance:Optical and ultrasonic sensors perform dimensional verification and defect detection at production speeds. EU AI Act algorithmic transparency requirements are forcing documentation of training data provenance for AI-enabled inspection systems in pharmaceutical packaging.
- Assembly Lines:High-speed part presence and position verification for discrete manufacturing.
- Process Control:Continuous feedback loops for temperature, pressure, and flow regulation.
Safety Monitoring carries the steepest compliance burden. Quality Assurance is climbing the fastest on AI-enabled upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor deployment patterns diverge sharply by geography. Germany prioritizes precision metrology for automotive quality gates. The United States emphasizes safety-rated redundancy for heavy manufacturing. Japan concentrates on miniaturization for electronics assembly.
United States
Automotive OEMs in Michigan and Tennessee are embedding multi-sensor arrays for EV battery assembly quality control. OSHA lockout/tagout enforcement mandates redundant safety-rated proximity switches in heavy manufacturing cells. Houston process control installations drive aftermarket service demand through hazardous-area certification maintenance.
Germany
Automotive tier-one suppliers in Stuttgart and Munich adopt hybrid time-of-flight optical modules for robotic bin-picking applications. EU AI Act algorithmic transparency requirements accelerate replacement of legacy electromechanical sensors with firmware-upgradeable alternatives. Bavarian industrial clusters anchor precision sensor R&D for semiconductor wafer handling.
Japan
Electronics manufacturers in Kansai and Nagoya deploy sub-millimeter resolution sensors for cleanroom semiconductor packaging. METI industrial automation incentives support smart manufacturing corridor investments in Aichi Prefecture. Toyota City production lines exemplify dense sensor integration for predictive maintenance triggers.
China
MIIT smart manufacturing directives accelerate sensor deployment across Yangtze River Delta electronics assembly hubs. Domestic automotive OEMs in Shanghai and Shenzhen expand quality gate sensor density for EV powertrain manufacturing. GB standards alignment pressures foreign suppliers to localize firmware architecture.
India
PLI scheme incentives for electronics manufacturing attract sensor suppliers to Gujarat and Tamil Nadu industrial corridors. Automotive OEMs in Pune and Chennai pilot multi-sensor arrays for assembly line quality verification. BIS certification requirements extend supplier qualification timelines for safety-rated devices.
Factory Automation Sensor Market Vendor Landscape
Capability concentration sits with precision specialists; scale advantage sits with diversified automation conglomerates. The market structures around three tiers: integrated motion-control platforms, hazardous-environment certification specialists, and semiconductor component suppliers. Dominant competitive moves include aftermarket service platform unbundling and edge AI firmware architecture partnerships.
Among diversified automation conglomerates, Rockwell Automation and Siemens occupy positions anchoring North American and European channel control respectively. Honeywell International exemplifies the hazardous-environment certification archetype through oil and gas field service depth. STMicroelectronics and Infineon Technologies represent the semiconductor component tier supplying photodiode and CMOS cores to downstream module integrators.
| Leading Market Players |
|---|
| Rockwell Automation |
| Honeywell International |
| Texas Instruments |
| Panasonic Corporation |
| STMicroelectronics |
| Siemens |
| ABB |
| Analog Devices |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet processing concentration in Chinese facilities anchors input cost volatility for proximity sensor manufacturers, pushing margin pools toward firmware-upgradeable solid-state architectures that command calibration-dependent recurring revenue streams.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs in Germany and Japan and tier-one sensor suppliers, though spot-market purchasing persists for replacement-cycle volume in North American oil and gas installations. Three-tier pricing structure across SIL-certified premium, standard industrial-grade, and economy non-safety-rated levels separates buyers by functional safety requirements. Pricing pressure stems from semiconductor foundry bottlenecks in Taiwan and South Korea extending optical module lead times. Automotive assembly lines exhibit lowest price sensitivity due to zero-defect quality gate mandates, while general manufacturing packaging applications face acute cost compression.
Supply Chain Analysis
Export-control regimes restricting photodiode and CMOS image sensor technology flows from Taiwan and South Korea constrain optical sensor module availability for precision applications. Manufacturing concentration centers on China for rare earth magnet processing, Germany for precision inductive coil winding, and Japan for sub-millimeter resolution cleanroom assemblies. Raw material dependencies include neodymium and dysprosium for proximity sensing, silicon wafers for photodiode fabrication, and specialty ceramics for pressure transducer membranes. Single-source vulnerability in Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through authorized distributor networks with direct manufacturer platform access for aftermarket firmware and calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs consolidating multi-sensor array procurement across Germany, Japan, and the United States, fragmenting supplier margin capture and forcing unbundled service architectures.
For Market Incumbents: Harden firmware architecture against EU AI Act algorithmic transparency mandates by partitioning deterministic safety cores from sandboxed machine learning inference engines. Deepen SIL 3 certification depth to defend against emerging semiconductor component suppliers encroaching from photodiode and CMOS tiers. Anchor channel control through integrated motion platforms that lock in replacement-cycle predictability. For New Entrants and Emerging Players: Hydrogen economy pressure and gas detection applications for electrolyzer manufacturing represent the most penetrable white-space entry point, with limited incumbent specialization and accelerating capital deployment. India PLI scheme corridors in Gujarat and Tamil Nadu offer second-mover positioning for electronics manufacturing cluster proximity. Pursue direct digital platform relationships with process control operators to bypass established distributor margin capture. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge AI-enabled sensor architectures requiring real-time operating systems firmware talent and IEC 62304 medical device software compliance capabilities. Acquisition targets should prioritize semiconductor component suppliers with captive photodiode or CMOS foundry relationships. Watch for MIIT smart manufacturing directive acceleration in Yangtze River Delta clusters as inflection signal for Chinese domestic demand substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Architecture Partnership | Enables millisecond-latency defect detection for EU AI Act compliance in pharmaceutical packaging. |
| Backward Integration into Photodiode Foundry | Reduces Taiwan and South Korea capacity constraint exposure for optical sensor module production. |
| Direct Digital Service Platform Launch | Bypasses distributor margin capture through manufacturer-hosted calibration and firmware update revenue. |
| SIL 3 Certification Investment | Meets OSHA lockout/tagout enforcement requirements in United States heavy manufacturing cells. |
| India Manufacturing Corridor Establishment | Captures PLI scheme incentives for electronics manufacturing in Gujarat and Tamil Nadu clusters. |
Methodological Framework
Desk research of SEC 10-K filings, EU Machinery Directive regulatory databases, and semiconductor foundry capacity disclosures preceded structured interviews with automotive OEM procurement directors, industrial automation plant engineers, aftermarket service heads, and sensor firmware development leads. Primary fieldwork combined with secondary validation across customs trade data, IHS Markit vehicle production databases, and IEC certification registries. Bottom-up unit demand modeling triangulated against top-down industrial automation capex forecasts.
Assumptions held fixed include current EU AI Act compliance deadlines, OSHA enforcement patterns, and rare earth magnet export regime stability, while semiconductor foundry capacity expansion timelines and India PLI scheme incentive trajectories were stress-tested across scenarios. Segmentation dimensions spanned product type, sensing technology, end-user vertical, application severity, and regional regulatory cluster. CAGRs derived from regression against historical industrial automation sensor deployment intensity and forward OEM quality gate expansion plans.
Practitioners should monitor MIIT smart manufacturing directive acceleration, Taiwan foundry capacity allocation shifts, and EU AI Act audit precedent formation for early signals of forecast revision. Material shifts in rare earth magnet export restrictions, functional safety certification harmonization, or edge AI inference standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market