
 Global Acceleration and Yaw Rate Sensors Market | 2026-2036
Global Acceleration and Yaw Rate Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acceleration and Yaw Rate Sensors Market Foresight
Multi-source procurement for high-precision inertial components is realigning supply relationships across the tiered sensor ecosystem. Bosch Sensortec leverages captive MEMS foundry capacity to control cost positions in automotive gyroscopes. NXP Semiconductors anchors its portfolio through ASIL-certified accelerometer lines for vehicle stability control. STMicroelectronics dominates consumer-grade IMU shipments while extending process expertise into industrial-grade yaw rate modules.
Acceleration and yaw rate sensors measure linear and rotational motion through MEMS, capacitive, piezoelectric, optical, or magnetoresistive transduction principles, typically resolving angular rates below 0.1 degrees per second and accelerations to micro-g precision for closed-loop control systems. MEMS sensors occupy the highest volume tier due to silicon batch-fabrication economics, while fiber optic gyroscopes command premium positioning in aviation systems where bias stability requirements exceed tactical-grade thresholds. Vehicle stability control applications consume the largest value share among end-use segments, whereas robotics navigation represents the fastest-expanding demand pool as warehouse automation and autonomous mobile robot deployments multiply.
FDA device-classification frameworks for surgical navigation systems, ECE R79 steering-type approval requirements in Europe, and China's GB/T standards for autonomous vehicle sensor suites collectively tighten performance validation protocols. These regulations force suppliers to maintain dual certification tracks and traceable calibration chains. Stakeholders must monitor evolving functional-safety thresholds as OEMs push sensor fusion architectures toward higher automation levels.
Market Dynamics
Automotive OEMs are consolidating sensor procurement around ASIL-D certified inertial measurement units as Level 3 autonomy programs advance, compressing supplier qualification timelines and favoring vertically integrated MEMS fabricators with captive calibration facilities.
Growth Catalysts
- Vehicle Stability Mandates:ECE R79 steering-type approval requirements in Europe now mandate redundant yaw rate sensing for heavy commercial vehicles, expanding addressable unit volumes across German and Swedish truck manufacturers.
- Robotics Navigation:Warehouse automation deployments in Shenzhen and Nagoya are consuming tactical-grade IMUs for autonomous mobile robot localization, creating parallel demand streams outside traditional automotive channels.
- GB Standard Tightening:China's MIIT is accelerating GB/T autonomous vehicle sensor reliability protocols, forcing domestic EV manufacturers to upgrade from consumer-grade to automotive-qualified inertial components.
Market Restraints
- Silicon Wafer Cost Volatility:MEMS foundry input costs fluctuate with 300mm silicon wafer spot pricing, squeezing gross margins for fabless sensor designers without long-term supply agreements.
- Aviation-Grade Concentration:Fiber optic gyroscope production concentrates among a handful of defense-aerospace suppliers with ITAR-controlled manufacturing, limiting price competition and procurement flexibility.
- Optical Interferometry Substitution:Chip-scale atomic clocks paired with optical gyroscopes threaten tactical-grade MEMS yaw rate sensors in long-duration navigation applications where bias drift accumulation is critical.
Strategic Opportunities
- Indian Industrial Automation:India's PLI scheme for manufacturing automation is creating first-time demand for industrial-grade accelerometers in Pune and Chennai automotive component plants.
- Surgical Navigation:FDA device-classification frameworks for robotic surgery systems are opening certified-channel revenue for sub-micro-g accelerometers in instrument tracking applications.
- Sensor Fusion Convergence:LiDAR-IMU tight coupling in autonomous perception stacks is automating calibration workflows and creating bundled procurement opportunities for multi-modal sensor suppliers.
Industry Challenges
- Functional Safety Talent Scarcity:ISO 26262 certified systems engineers command premium compensation, constraining supplier capacity to parallel-process multiple OEM qualification programs.
- Dual Certification Timelines:Simultaneous AEC-Q100 automotive and DO-160G aviation qualification cycles extend product development by 18-24 months, delaying revenue recognition for multi-market sensor platforms.
- Legacy Fleet Integration:Retrofitting CAN-FD compatible IMUs into existing vehicle stability control architectures requires gateway hardware redesigns that fragment aftermarket upgrade paths.
Report Scope
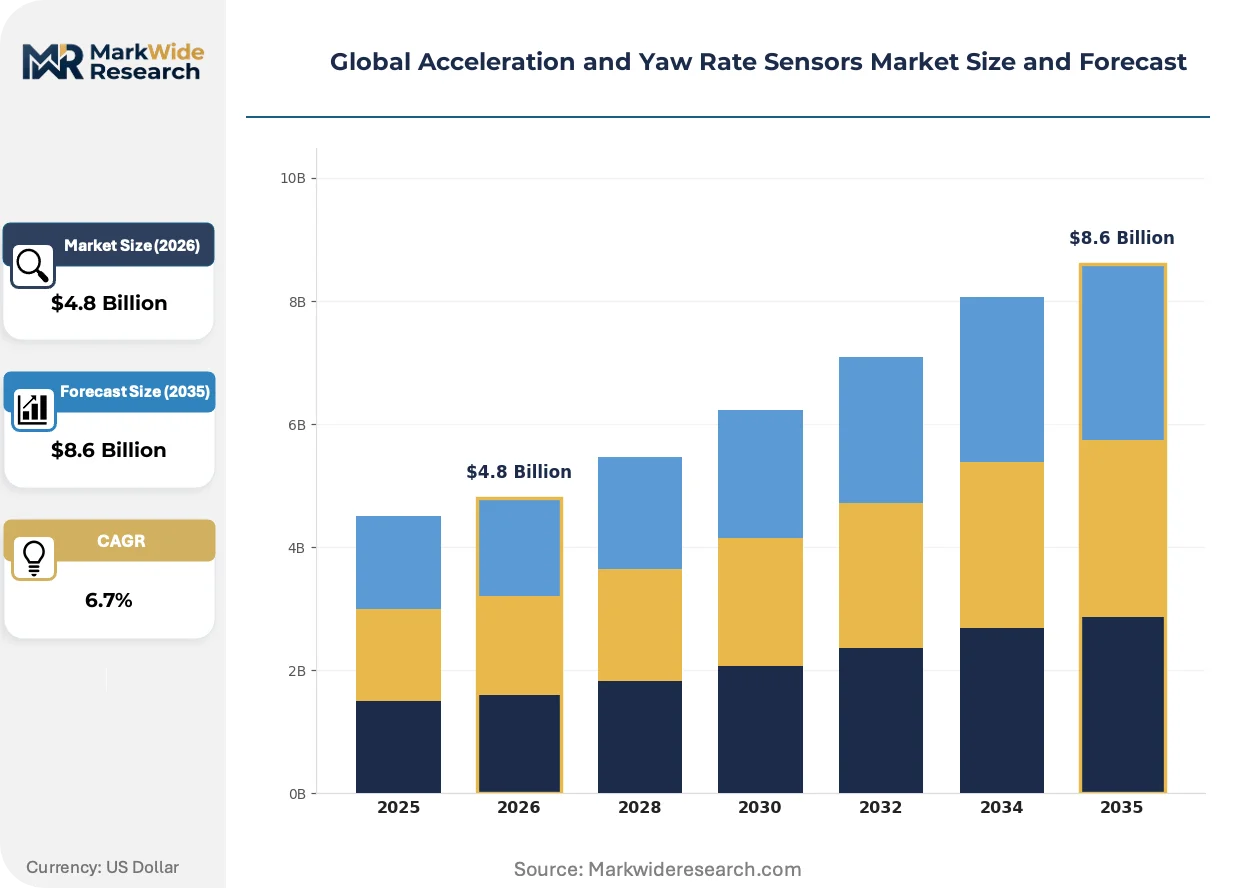
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acceleration and Yaw Rate Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS Sensors, Capacitive Sensors, Piezoelectric Sensors, Optical Sensors, Magnetoresistive Sensors Technology: Gyroscope, Accelerometer, Hall Effect, Fiber Optic, Radar Application: Vehicle Stability Control, Robotics Navigation, Industrial Automation, Aviation Systems, Sports Analytics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Aerospace Manufacturers, Robotics Engineers |
| Companies Covered | Epson Europe Electronics, ZF, Bosch Sensortec, NXP Semiconductors, Honeywell, Continental AG, Baumer Group, Analog Devices, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acceleration and Yaw Rate Sensors Market Shifts & Advancements
Silicon photonics and advanced MEMS process nodes are converging to redefine performance-cost tradeoffs across inertial sensing tiers, while regulatory fragmentation between aviation, automotive, and medical safety standards is forcing modular certification architectures.
Deep-reactive-ion-etched MEMS gyroscopes with sub-degree-per-hour bias stability are automating the displacement of bulky mechanical rate sensors in industrial stabilization platforms. Agricultural equipment manufacturers in the US Midwest are adopting these chip-scale units for implement guidance. The technology is automating cost reduction in precision farming navigation stacks previously dominated by fiber optic alternatives.
Europe's CSRD sustainability disclosure requirements are mandating lifecycle carbon accounting for electronic components sold into automotive supply chains. Sensor suppliers must now document embodied energy from wafer fabrication through end-of-life recycling. German Tier-1 integrators are responding by prioritizing European-sourced MEMS wafers over Asian alternatives to compress Scope 3 emissions reporting complexity.
Aftermarket distributors are unbundling calibration services from hardware sales as OEMs demand traceable metrology chains for warranty compliance. Independent service providers in Seoul and Detroit are capturing recurring revenue streams previously retained by original sensor manufacturers. This pattern is most visible in commercial vehicle fleet retrofits where NHTSA defect investigation exposure drives documented maintenance protocols.
Global Acceleration and Yaw Rate Sensors Market Segmentation
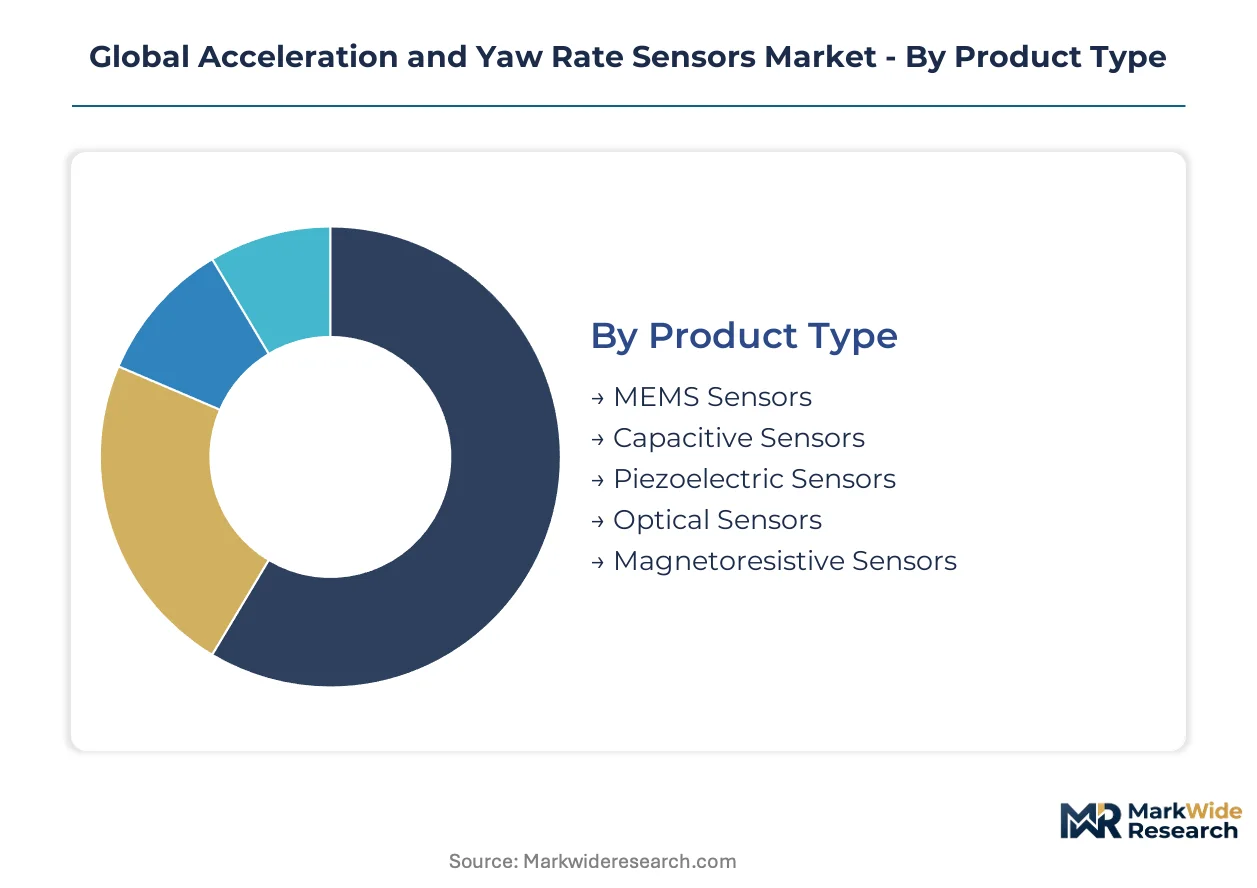
Acceleration and yaw rate sensors fragment across multiple technical and commercial dimensions that determine qualification requirements, pricing power, and supplier selection criteria. Understanding these segment boundaries reveals where MEMS batch economics dominate versus where optical precision commands premium positioning.
Product Type:
Standardization through silicon batch fabrication sits at one extreme; custom transduction physics requiring dedicated tooling occupies the other.
- MEMS Sensors:Silicon micromachined structures fabricated on 200mm and 300mm wafers deliver angular rate resolution below 0.1 degrees per second at automotive price points. German and Japanese OEMs source these in volume for vehicle stability control systems where ASIL-D certification is mandatory.
- Capacitive Sensors:Electrostatic transduction between interdigitated comb structures provides linear acceleration measurement with micro-g precision for closed-loop suspension systems. Shenzhen-based EV manufacturers are expanding procurement of these components as China's MIIT tightens GB standards for autonomous vehicle sensor reliability.
- Piezoelectric Sensors:Quartz or ceramic crystal elements generate charge proportional to mechanical stress for high-shock industrial environments.
- Optical Sensors:Interferometric and ring laser configurations serve aviation applications where bias stability requirements exceed tactical-grade thresholds.
- Magnetoresistive Sensors:Anisotropic magnetoresistance or tunneling junction structures detect magnetic field variations for complementary heading reference in sensor fusion architectures.
Leading the category by volume: MEMS Sensors. Expanding most quickly: Optical Sensors in long-duration navigation where bias drift accumulation is critical.
Technology:
Volume concentration clusters around mature electromechanical platforms while emerging photonic methods capture specialized positioning.
- Gyroscope:Rotational rate measurement through Coriolis force detection in vibrating MEMS structures or Sagnac effect in fiber optic rings. Warehouse automation deployments in Nagoya consume tactical-grade units for autonomous mobile robot localization.
- Accelerometer:Proof-mass displacement sensing for linear acceleration spans consumer-grade IMUs to sub-micro-g surgical navigation instruments. FDA device-classification frameworks for robotic surgery systems are opening certified-channel revenue for precision-grade variants.
- Hall Effect:Magnetic field-based angular position sensing complements inertial measurements in steering-angle detection.
- Fiber Optic:Coil-based Sagnac interferometers serve defense-aerospace applications with ITAR-controlled manufacturing constraints.
- Radar:Doppler and FMCW methods provide velocity measurement redundancy in automotive sensor fusion stacks.
Dominant by shipment volume: Accelerometer. Steepest expansion trajectory: Fiber Optic in aviation systems requiring bias stability beyond MEMS capabilities.
Application:
End-use maturity spans decades-old automotive safety mandates to emerging robotics navigation protocols still stabilizing.
- Vehicle Stability Control:Yaw rate and lateral acceleration sensing for electronic stability programs represents the largest value share among end-use segments. ECE R79 steering-type approval requirements in Europe now mandate redundant yaw rate sensing for heavy commercial vehicles.
- Robotics Navigation:Tactical-grade IMUs for simultaneous localization and mapping in warehouse automation. Deployments in Shenzhen and Seoul are multiplying as autonomous mobile robot fleets scale.
- Industrial Automation:Machine tool stabilization and precision positioning in automotive component plants.
- Aviation Systems:Attitude heading reference systems and inertial reference units for commercial and military aircraft.
- Sports Analytics:Wearable biomechanical measurement for athlete performance optimization.
Highest revenue concentration: Vehicle Stability Control. Gaining share fastest: Robotics Navigation as warehouse automation multiplies.
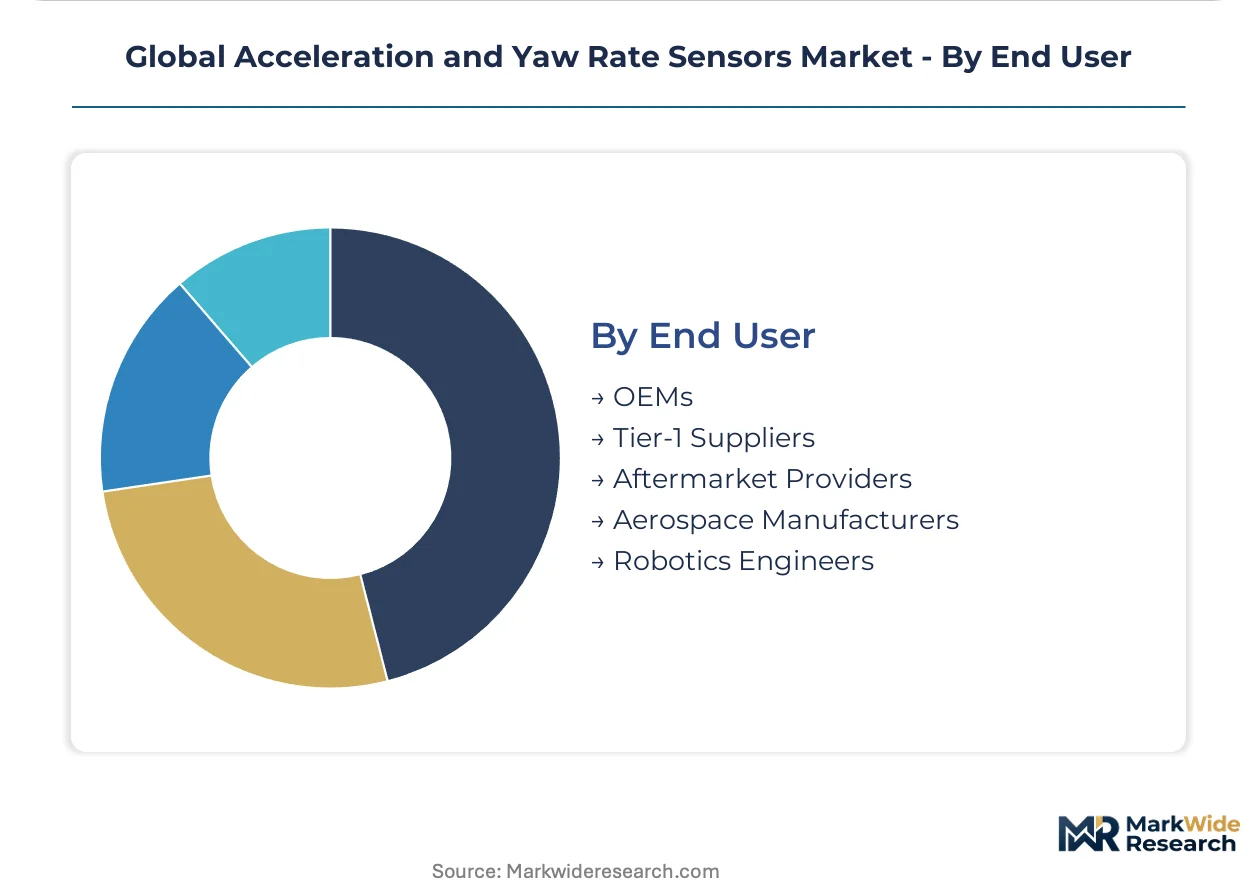
End User:
Procurement sophistication varies from integrated captive design teams to fragmented aftermarket service providers.
- OEMs:Automotive manufacturers with internal sensor fusion engineering capabilities and direct MEMS foundry relationships. German OEMs are consolidating procurement around ASIL-D certified inertial measurement units as Level 3 autonomy programs advance.
- Tier-1 Suppliers:Bosch and Continental-class integrators combining sensor modules with control electronics for vehicle stability systems. These suppliers maintain captive calibration facilities to compress qualification timelines.
- Aftermarket Providers:Independent distributors and service networks for fleet retrofits and replacement components.
- Aerospace Manufacturers:Boeing and Airbus-tier airframers with DO-160G qualification requirements extending development cycles.
- Robotics Engineers:Warehouse automation OEMs and autonomous system developers sourcing tactical-grade IMUs for localization stacks.
Controlling largest procurement volume: OEMs. Expanding most rapidly: Robotics Engineers as warehouse automation deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-machining clusters anchor European sensor fabrication, while East Asian silicon foundries concentrate MEMS wafer supply for automotive and robotics applications.
Germany
ECE R79 steering-type approval requirements mandate redundant yaw rate sensing for heavy commercial vehicles, expanding procurement from domestic truck manufacturers. The country's KBA enforces type-approval protocols that compress supplier qualification timelines. Stuttgart and Munich host Tier-1 integrators consolidating around ASIL-D certified inertial measurement units.
China
Domestic EV manufacturers upgrade from consumer-grade to automotive-qualified inertial components as MIIT tightens GB/T autonomous vehicle sensor reliability protocols. Shenzhen manufacturing clusters consume tactical-grade IMUs for warehouse automation deployments. The Pearl River Delta concentrates capacitive sensor fabrication for closed-loop suspension systems.
Japan
METI industrial automation programs drive demand for sub-degree-per-hour MEMS gyroscopes in precision farming navigation stacks. Nagoya automotive suppliers expand orders for vehicle stability control systems with captive calibration facilities. The Chubu region anchors robotics navigation IMU consumption for autonomous mobile robot localization.
United States
FDA device-classification frameworks for robotic surgery systems open certified-channel revenue for sub-micro-g accelerometers in instrument tracking applications. NHTSA defect investigation exposure drives documented maintenance protocols in commercial vehicle fleet retrofits. Detroit aftermarket distributors unbundle calibration services from hardware sales.
South Korea
Seoul-based robotics engineers source tactical-grade IMUs for simultaneous localization and mapping in warehouse automation. The country's MFDS maintains medical device standards that parallel FDA frameworks for surgical navigation systems. Busan-Ulsan manufacturing corridors concentrate sensor fusion module assembly for export markets.
Global Acceleration and Yaw Rate Sensors Market Competitive Landscape
Capacity expansion dominates the current landscape as automotive OEMs compress supplier qualification timelines around ASIL-certified components. The vendor base organizes into three tiers: vertically integrated MEMS fabricators with captive foundry capacity, fabless designers reliant on contract manufacturing, and specialized optical sensor houses serving defense-aerospace applications. Strategic archetypes include silicon-batch-scale producers, precision-grade specialists, and multi-modal sensor fusion integrators. M&A activity and strategic partnerships concentrate among Tier-1 automotive suppliers seeking backward integration into inertial component supply.
Among European-based electronics manufacturers, Epson Europe Electronics and Continental AG exemplify integrated-systems archetypes with automotive channel access. Bosch Sensortec anchors the captive-foundry tier, representing vertical control over MEMS wafer fabrication and calibration workflows. These three entities occupy positions spanning component supply through module integration, reflecting the market's stratification between silicon-scale producers and precision-grade specialists.
| Leading Market Players |
|---|
| Epson Europe Electronics |
| ZF |
| Bosch Sensortec |
| NXP Semiconductors |
| Honeywell |
| Continental AG |
| Baumer Group |
| Analog Devices |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
300mm silicon wafer spot pricing cascades through MEMS foundry economics into three distinct pricing tiers for automotive inertial components, with German OEMs absorbing premium ASIL-D certification costs while Chinese EV manufacturers negotiate volume-driven standard-grade supply agreements.
Pricing Analysis
Warranty-bundled calibration services are unbundling from hardware transactions as NHTSA defect investigation exposure forces commercial fleet operators toward documented maintenance protocols. Pricing stratifies across automotive-qualified, industrial-grade, and consumer-tier certification levels, with ISO 26262 functional safety tiers commanding substantial premiums over unqualified alternatives. Cost compression in consumer-grade MEMS accelerometers is intensifying because Shenzhen-based EV manufacturers are upgrading to automotive-qualified components under tightening MIIT protocols. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to captive calibration requirements, whereas aftermarket distributors face margin pressure from independent service providers in Seoul and Detroit.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs are fragmenting wafer procurement across Taiwan, South Korea, and domestic European MEMS foundries to mitigate ITAR-controlled fiber optic gyroscope concentration risks. The supply chain draws from 300mm silicon wafers, deep-reactive-ion-etching equipment, and ASIC companion chips for signal conditioning. Single-source vulnerability in ITAR-controlled fiber optic gyroscope manufacturing limits procurement flexibility for defense-aerospace applications. Distribution runs through Tier-1 integrators with captive calibration facilities, direct OEM procurement programs, and independent aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as automotive OEMs compress supplier qualification timelines, with backward integration into MEMS foundry capacity representing the decisive upstream lever for securing ASIL-D certification pipelines.
For Market Incumbents: Lock in captive wafer supply through long-term foundry agreements or in-house 200mm/300mm MEMS fabrication investments to defend against fabless competitors exposed to silicon cost volatility. Prioritize parallel-track certification workflows that compress AEC-Q100 and DO-160G timelines simultaneously, as dual qualification delays threaten revenue recognition for multi-market sensor platforms. Expand calibration facility footprints in Nagoya and Stuttgart to capture unbundled service revenue from fleet retrofit mandates.
For New Entrants and Emerging Players: Surgical navigation engineers represent an underserved buyer archetype seeking sub-micro-g accelerometers outside established automotive supply relationships. Target FDA-certified channel development for robotic surgery instrument tracking applications, where incumbent automotive suppliers lack dedicated medical device sales infrastructure. Pursue direct procurement relationships with warehouse automation OEMs in Shenzhen bypassing traditional Tier-1 integrators.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless sensor designers with established AEC-Q100 qualification in Germany facing silicon wafer cost volatility pressure. Long-term viability hinges on acquisition targets possessing automotive certification pipelines rather than consumer-grade volume positions. Watch for MIIT GB/T protocol acceleration as the inflection signal triggering domestic Chinese EV manufacturer procurement upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Investment | Bosch Sensortec's vertical wafer control secures cost positions against fabless competitors exposed to spot pricing. |
| Dual Certification Parallel Processing | Simultaneous AEC-Q100 and DO-160G workflows compress 18-24 month development cycles for multi-market platforms. |
| Calibration Service Unbundling | Independent Seoul and Detroit providers capture recurring revenue from NHTSA-driven fleet maintenance protocols. |
| Medical Device Channel Development | FDA surgical navigation certification opens premium pricing for sub-micro-g accelerometer variants outside automotive tiers. |
| Silicon Photonics R&D Partnership | Chip-scale atomic clock integration threatens tactical-grade MEMS displacement in long-duration navigation applications. |
Research Methodology
Multi-period observation of MEMS foundry utilization rates, ASIL certification pipeline backlogs, and GB/T protocol implementation timelines anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, MEMS foundry operations managers, and aftermarket service network heads. Secondary validation incorporated SEC filings from sensor manufacturers, MIIT regulatory bulletins, FDA device-classification databases, and vehicle production data from IHS Markit. Bottom-up shipment modeling triangulated against top-down OEM procurement budget analysis.
Segment-weighting across product type, technology, application, and end-user dimensions structured the analytical framework throughout the projection horizon. Modeled dimensions included MEMS versus optical transduction physics, gyroscope versus accelerometer versus multi-axis IMU configurations, vehicle stability control versus robotics navigation versus aviation systems end-uses, and OEM versus Tier-1 versus aftermarket procurement channels. CAGRs derived from shipment-volume trajectories calibrated against semiconductor capital expenditure cycles and automotive platform launch schedules.
Revisions become necessary when MIIT accelerates GB/T autonomous vehicle sensor reliability mandates, ECE R79 expands redundant yaw rate requirements beyond heavy commercial vehicles, or fiber optic gyroscope ITAR restrictions loosen to permit new manufacturing entrants. Deviation in silicon wafer spot pricing volatility or ASIL-D certified systems engineer availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Window Sensors Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Nano Radiation Sensors Market