
 Europe Digital Thermometer Market | 2026-2036
Europe Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Thermometer Market Analytics
Multi-source component procurement is repositioning how European digital thermometer manufacturers manage sensor supply chains. Beurer GmbH leverages its German manufacturing footprint to sustain domestic production of infrared sensor modules. Omron Corporation anchors its competitive stance through extensive pharmacy distribution networks across France and Italy. Microlife Corporation specializes in Bluetooth-enabled temperature logging systems that differentiate its portfolio in the connected health segment.
A digital thermometer measures body temperature through electronic thermistor or infrared sensor technology, typically achieving accuracy within ±0.1°C and displaying readings on LCD or LED interfaces for clinical and home diagnostic purposes. Forehead infrared models lead volume sales through pharmacy and supermarket channels, while Bluetooth-enabled devices represent the fastest-growing technology segment as remote patient monitoring expands. Oral thermometers remain a mature, price-competitive category with concentrated margin pools in private-label supermarket contracts.
The EU Medical Device Regulation (MDR) and CE marking framework enforce clinical accuracy standards and post-market surveillance obligations that shape product development timelines and market access costs for manufacturers. Germany's BfArM and France's ANSM coordinate national vigilance reporting that influences recall protocols and design modification requirements across member states. Stakeholders must monitor evolving MDR guidance documents on software-as-a-medical-device classifications that could reclassify connected thermometer applications.
Market Dynamics
EU Medical Device Regulation (MDR) compliance timelines are compressing product development cycles while infrared sensor supply constraints force manufacturers toward multi-source procurement strategies across European production networks.
Growth Catalysts
- Home healthcare expansion:Aging demographics in Germany, France, and the United Kingdom sustain replacement demand through pharmacy and supermarket channels.
- EU MDR accuracy mandates:Clinical-grade device requirements tighten quality thresholds, favoring manufacturers with established post-market surveillance systems.
- Bluetooth-enabled temperature logging:Remote patient monitoring adoption accelerates demand for connected health integration in chronic disease management protocols.
Market Restraints
- Infrared sensor supply concentration:Dependence on Asian semiconductor foundries creates input volatility for European thermometer assembly operations.
- CE marking cost escalation:Notified body capacity constraints extend certification timelines and raise market access expenses for new entrants.
- Oral thermometer price commoditization:Private-label supermarket contracts compress margin pools in mature product categories.
Strategic Opportunities
- Eastern European pharmacy channel penetration:Underdeveloped distribution density in Poland and Romania offers first-mover positioning for branded device portfolios.
- Software-as-a-medical-device reclassification:Evolving MDR guidance documents may create regulatory clarity for connected thermometer applications.
- Telehealth platform integration:Temperature data interoperability with remote consultation systems opens new reimbursement pathways.
Industry Challenges
- Post-market surveillance staffing:Vigilance reporting requirements under Germany's BfArM and France's ANSM strain regulatory affairs capacity.
- Legacy system integration:Bluetooth-enabled devices face interoperability friction with hospital electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Thermometer Market |
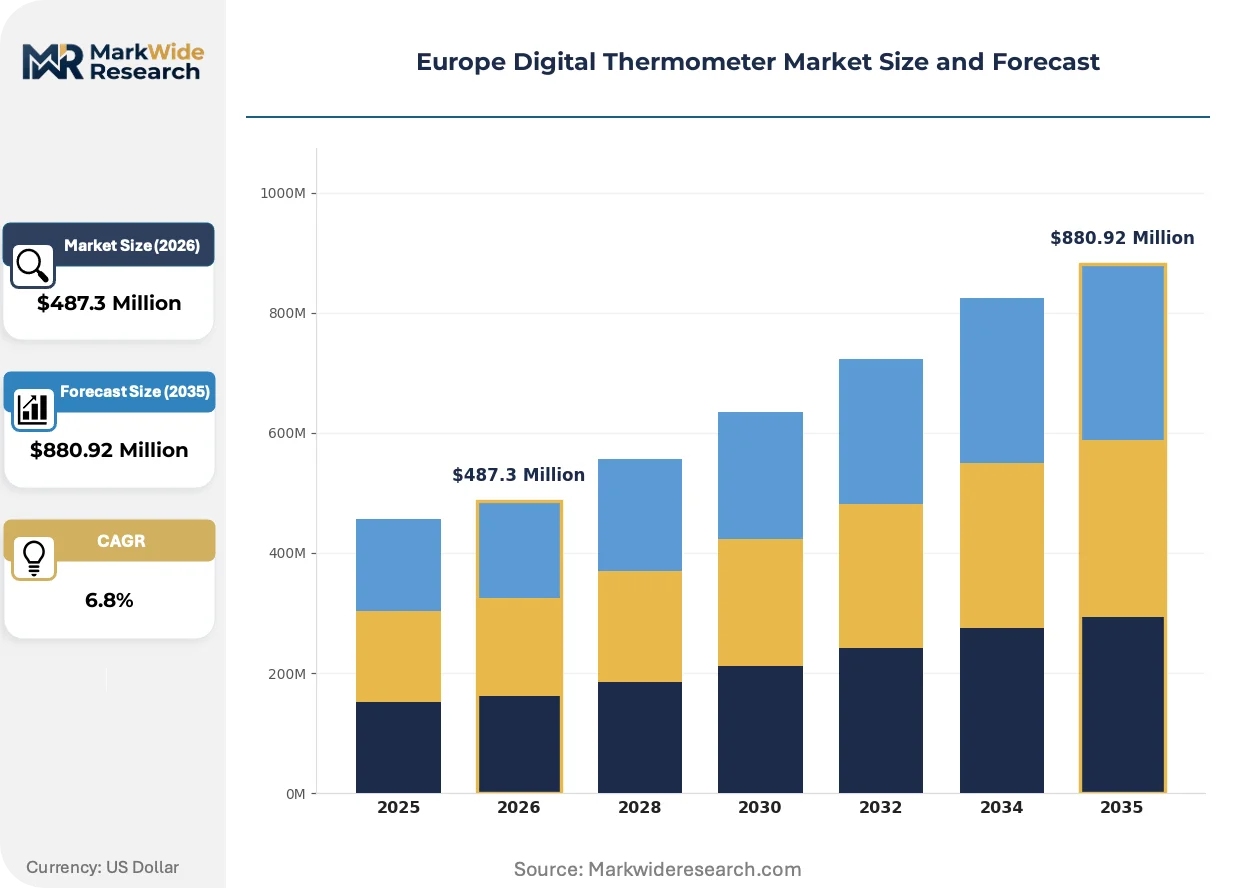
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forehead, In-ear, Oral, Underarm End User: Households, Hospitals, Clinics, Laboratories Technology: Infrared, Digital Display, Bluetooth Enabled, Traditional Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Omega Engineering, Terumo Corporation, Beurer GmbH, Welch Allyn, Fluke Corporation, Omron Corporation, Optris GmbH, EASYWELL BIOMEDICALS, Microlife Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Thermometer Market Evolving Landscape
Sensor fusion architectures and regulatory software classifications are restructuring how European manufacturers design clinical-grade temperature measurement systems for connected health environments.
Thermopile array sensors paired with ambient temperature compensation algorithms are unifying forehead infrared accuracy across variable room conditions. Home healthcare providers in the Netherlands and Belgium are adopting these modules for pediatric monitoring applications. The technology is unifying previously separate calibration workflows into single-chip solutions that reduce manufacturing complexity.
EU MDR guidance on software-as-a-medical-device is reclassifying connected thermometer data transmission as a regulated clinical function. Manufacturers must now submit algorithm validation documentation alongside hardware certifications. French and Italian notified bodies are processing these combined submissions under extended review timelines that favor established quality management systems.
Pharmacy chains are consolidating procurement decisions at central buying offices rather than regional distribution levels. Independent retailers in Spain and Portugal face margin compression as volume discounts concentrate with multinational pharmacy groups. Germany's pharmacy cooperative structures resist this concentration through collective bargaining arrangements that preserve local formulary autonomy.
Europe Digital Thermometer Market Segmentation
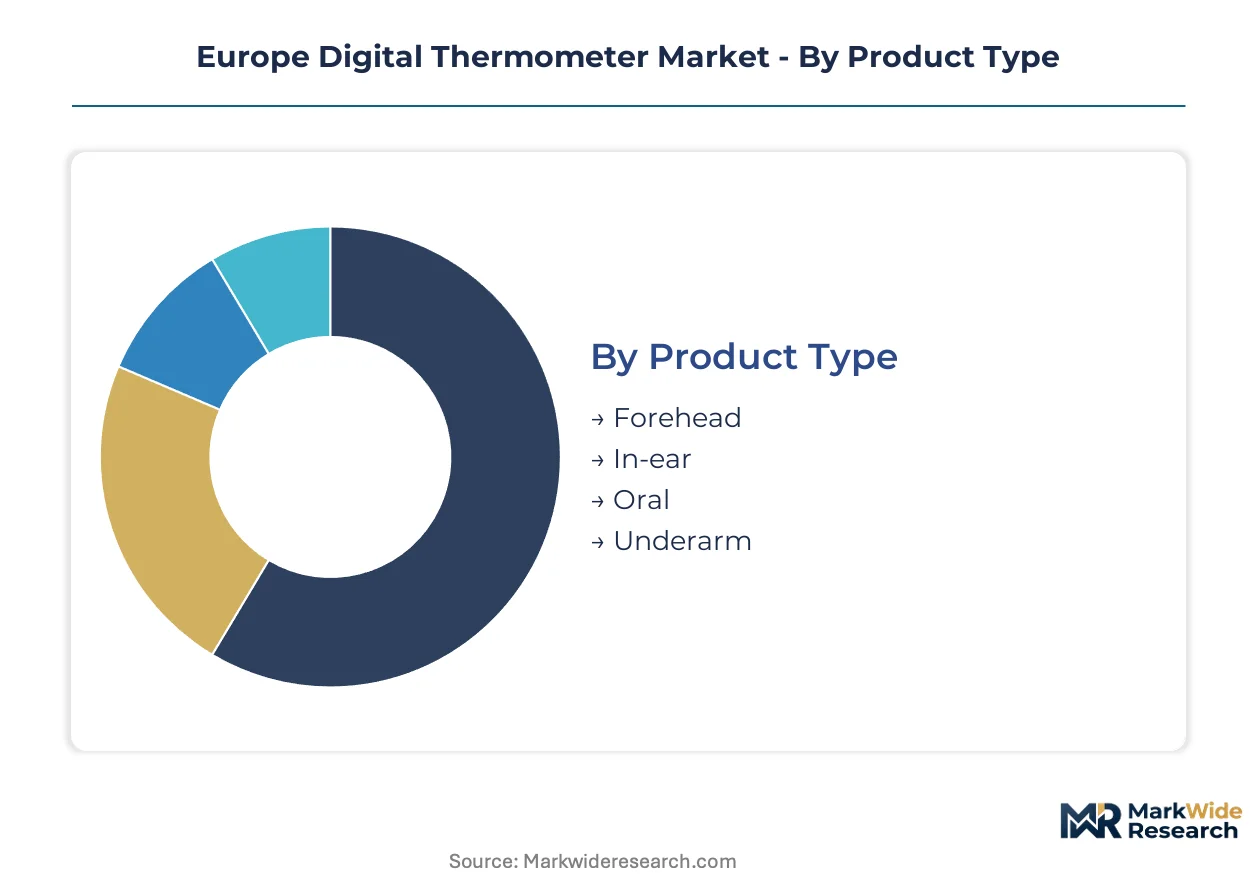
Segmentation in the Europe Digital Thermometer Market reveals how product specifications, channel strategies, and connectivity features align with distinct purchasing behaviors across German pharmacy networks, French hospital procurement, and British supermarket retail. Manufacturers calibrate sensor accuracy, wireless protocols, and packaging formats to match the compliance thresholds and price elasticity of each vertical.
Product Type:
Standardization dominates forehead and oral formats, while in-ear and underarm models retain customization for pediatric and clinical applications respectively.
- Forehead:Non-contact infrared thermopile sensors measure temporal artery temperature without skin contact. Demand concentrates in French and Italian pharmacy chains where parents prioritize speed for fever screening in children. CE marking under EU MDR requires clinical validation studies for infrared accuracy claims.
- In-ear:Tympanic membrane measurement via sealed probe tips achieves core temperature correlation. German hospital procurement offices specify disposable probe covers and calibration certificates for infection control compliance. The segment commands premium pricing through clinical-grade certification.
- Oral:Thermistor-based sublingual measurement remains the price-competitive baseline for home diagnostics.
- Underarm:Axillary placement with extended measurement duration serves infant monitoring and sleep-tracking applications.
Most installed capacity flows through Forehead. Expansion is steepest in In-ear.
End User:
Cost tier separation distinguishes volume-driven household purchases from compliance-intensive institutional procurement.
- Households:Bluetooth-enabled devices with smartphone app integration dominate replacement cycles in aging British and Dutch demographics. Remote patient monitoring subscriptions create recurring revenue attachments for chronic disease management.
- Hospitals:Multi-patient tympanic systems with disposable probe covers satisfy ANSM vigilance reporting requirements in France. Procurement specifications mandate ISO 80601-2-56 compliance for clinical accuracy.
- Clinics:Forehead infrared units with rapid screening protocols support high-throughput primary care workflows.
- Laboratories:Calibrated reference thermometers with traceable certificates serve validation and quality control functions.
Households absorb the highest unit volumes. Hospitals drive margin concentration through certification premiums.
Technology:
Maturity gradients separate established digital display architectures from emerging connectivity stacks requiring software validation.
- Infrared:Thermopile arrays with ambient temperature compensation algorithms unify measurement stability across variable European climate conditions. Dutch home healthcare providers adopt these modules for pediatric telemonitoring programs.
- Bluetooth Enabled:Temperature data transmission with encrypted cloud synchronization faces reclassification under evolving EU MDR software-as-a-medical-device guidance. French notified bodies process combined hardware-software submissions under extended review timelines.
- Digital Display:LCD and LED interfaces with memory functions represent the mature baseline for non-connected applications.
- Traditional:Mercury-free glass alternatives persist in regulatory backup and educational contexts.
Digital Display retains the largest installed base. Bluetooth Enabled is climbing the fastest as remote monitoring protocols expand.
Distribution Channel:
Supply concentration in multinational pharmacy groups contrasts with fragmented specialty retail and direct-to-consumer online growth.
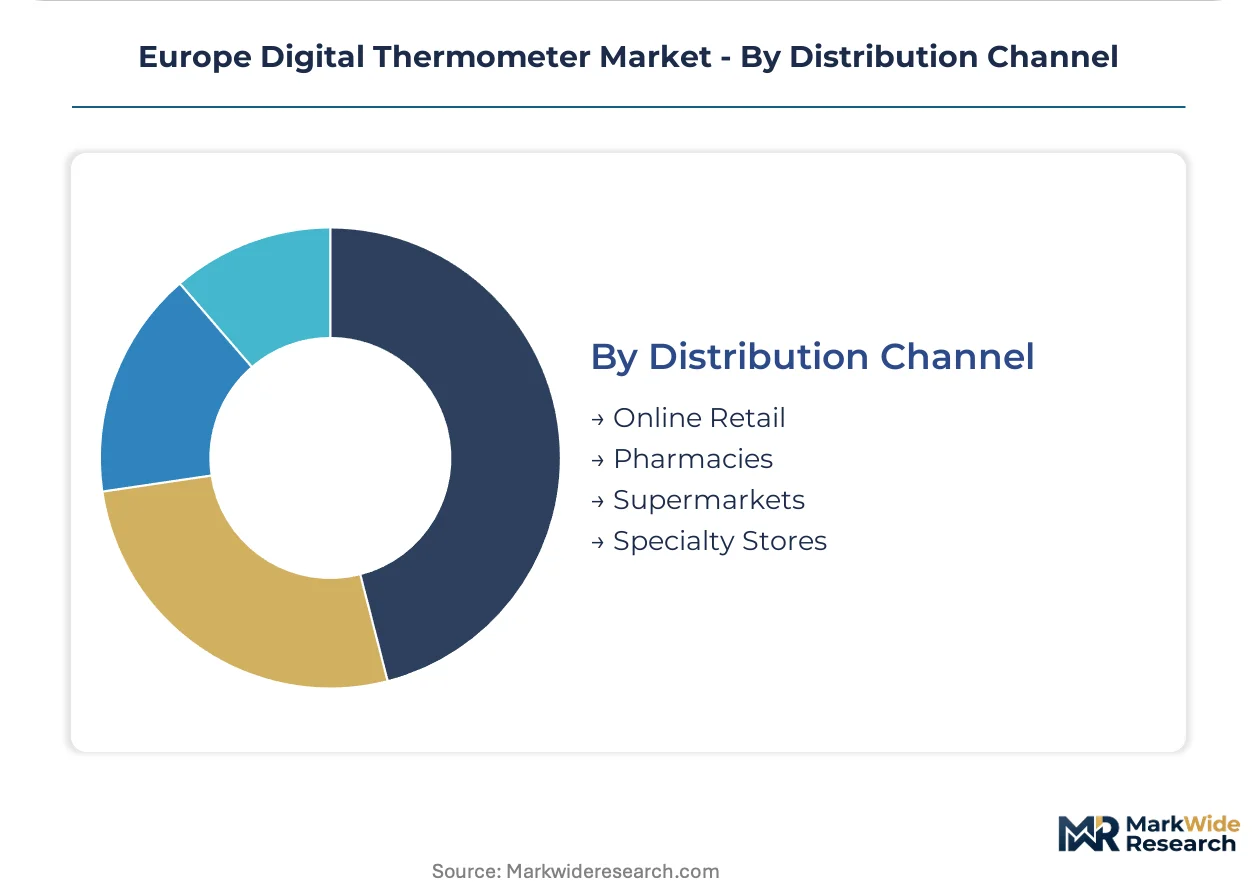
- Pharmacies:Central buying offices at chains like Alliance Healthcare and Phoenix Group consolidate procurement decisions across Germany, France, and Italy. Volume discounts compress margins for independent retailers in Spain and Portugal.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups while enabling subscription models for connected device ecosystems. German consumers demonstrate highest willingness-to-pay for Bluetooth-enabled premium formats through this channel.
- Supermarkets:Private-label oral thermometers with basic specifications dominate price-sensitive mass market positioning.
- Specialty Stores:Medical equipment retailers serve institutional buyers with calibration services and extended warranties.
Pharmacies channel the majority of clinical-grade volume. Online Retail is gaining share fastest among connected health adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European digital thermometer manufacturing through its concentration of precision sensor fabricators and medical device assembly operations serving pharmacy networks across the continent.
Germany
BfArM vigilance reporting requirements drive manufacturers toward integrated post-market surveillance systems. The EU MDR compliance timeline compresses product development cycles for companies headquartered in Bavaria and Baden-Württemberg. Berlin-based pharmacy cooperatives resist procurement centralization through collective bargaining arrangements that preserve local formulary autonomy.
France
ANSM coordinates national vigilance protocols that influence recall procedures across thermometer portfolios distributed through Alliance Healthcare channels. CE marking submissions for connected devices face extended review timelines at French notified bodies processing combined hardware-software certifications. Lyon and Paris host the densest pharmacy network concentration for clinical-grade infrared models.
United Kingdom
Aging demographics in Greater London and the Midlands sustain replacement demand for Bluetooth-enabled home healthcare devices. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit alignment with EU MDR accuracy standards. Manchester-based distribution centers channel supermarket private-label contracts for oral thermometer price-competitive segments.
Netherlands
Pediatric telemonitoring programs in Amsterdam and Rotterdam adopt thermopile array sensors with ambient temperature compensation algorithms. Dutch home healthcare providers integrate connected thermometers into chronic disease management protocols. Eindhoven's semiconductor ecosystem supplies calibration components for clinical-grade device manufacturers.
Italy
Pharmacy chain consolidation concentrates procurement decisions at central buying offices in Milan and Rome. ANSM-aligned vigilance reporting shapes design modification requirements for infrared thermometer portfolios. Northern Italian industrial districts manufacture disposable probe covers for tympanic hospital systems serving multi-patient workflows.
Europe Digital Thermometer Market Competitive Landscape
Global majors compete with regional champions across distribution channel density and regulatory certification speed. The vendor base organizes around three strategic archetypes: diversified health technology conglomerates with pharmacy network scale, specialized sensor manufacturers with German production footprints, and connected health specialists with Bluetooth-enabled portfolio differentiation. Competitive moves concentrate on M&A for distribution access and vertical integration into infrared sensor module production.
Within the diversified health technology tier, Omron Corporation and Terumo Corporation represent scale-driven positions anchored through extensive European pharmacy relationships. Beurer GmbH exemplifies the regional manufacturing archetype with its German production footprint sustaining domestic sensor module assembly. Microlife Corporation occupies the connected health specialization vector through Bluetooth-enabled temperature logging systems targeting remote patient monitoring adoption.
| Leading Market Players |
|---|
| Omega Engineering |
| Terumo Corporation |
| Beurer GmbH |
| Welch Allyn |
| Fluke Corporation |
| Omron Corporation |
| Optris GmbH |
| EASYWELL BIOMEDICALS |
| Microlife Corporation |
| Others |
Value Network & Pricing Analysis
Pharmacy cooperative buying offices in Germany and France command substantial leverage over thermometer manufacturers, compressing margins through volume-based procurement frameworks that reward scale with preferential unit economics. This buyer concentration forces pricing stratification across premium clinical-grade, standard connected-health, and economy private-label tiers.
Pricing Analysis
Infrared sensor module costs from Asian semiconductor foundries pass through directly to European assembly operations, elevating input sensitivity for forehead and in-ear thermometer categories. Pricing stratifies across premium, standard, and economy tiers, with CE marking under EU MDR and Bluetooth software validation serving as primary differentiation drivers. Pricing pressure stems from private-label supermarket contracts in oral thermometer segments where brand premiums collapse. Household consumers demonstrate highest price sensitivity for basic digital displays, while hospital procurement offices absorb certification premiums for ISO 80601-2-56 compliant tympanic systems.
Supply Chain Analysis
Reverse logistics flows for calibration certificate reissuance and warranty returns concentrate through German distribution hubs serving BfArM vigilance reporting requirements. Component sourcing draws from Taiwan and South Korea for thermopile arrays, China for LCD modules, and Germany for precision calibration equipment. Single-source vulnerability in infrared sensor supply creates exposure to Asian foundry capacity constraints. Distribution runs through central pharmacy buying offices at Alliance Healthcare and Phoenix Group, with direct-to-consumer platforms gaining share among connected health adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Digital Thermometer Market functions as a regulatory compounder where EU MDR compliance timelines and software-as-a-medical-device reclassifications continuously elevate barriers, concentrating returns among manufacturers with established notified body relationships and integrated post-market surveillance systems.
For Market Incumbents: Anchor competitive position through backward integration into infrared sensor module production and captive calibration certificate services that reduce dependence on Asian semiconductor foundries. Defend against emerging connected-health specialists by accelerating combined hardware-software submissions at French and Italian notified bodies before guidance documents harden. Prioritize pharmacy cooperative relationships in Germany that resist central buying office consolidation through collective bargaining arrangements preserving local formulary autonomy. For New Entrants and Emerging Players: Direct-to-consumer online platforms offer the most penetrable route for Bluetooth-enabled thermometer portfolios targeting Dutch and British aging demographics with remote patient monitoring subscriptions. White-space exists in Eastern European pharmacy channel penetration across Poland and Romania where distribution density remains underdeveloped relative to German and French networks. Target pediatric telemonitoring program tenders in Netherlands and Belgium where thermopile array sensor adoption creates specification windows for algorithm-validated temperature logging systems. For Investors and Strategic Acquirers: Diversified health technology conglomerates with existing European pharmacy network scale represent the most active acquirer category in this space, seeking connected-health capability bolt-ons to complement legacy device portfolios. Acquisition focus should center on mid-cap specialists with validated EU MDR quality management systems and established ANSM or BfArM vigilance reporting infrastructure. Monitor software-as-a-medical-device guidance document finalization as inflection indicator for reclassification-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Combined Hardware-Software Submission | French notified bodies process these under extended timelines favoring established quality systems. |
| Backward Integration into Infrared Sensor Production | German manufacturing footprints reduce Asian foundry dependency and input cost volatility. |
| Pharmacy Cooperative Collective Bargaining | Berlin-based cooperatives preserve local formulary autonomy against central buying office concentration. |
| Bluetooth Temperature Logging Platform Development | Dutch home healthcare providers integrate these into chronic disease management protocols. |
| Eastern European Distribution Channel Expansion | Poland and Romania offer first-mover positioning where pharmacy network density lags Western Europe. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers at Dutch telemonitoring programs, regulatory affairs leads at notified bodies, and pharmacy cooperative purchasing directors grounded qualitative findings in operational reality. Secondary validation drew from EMA guidance documents, BfArM vigilance reports, ANSM certification databases, and EU MDR implementation tracking. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across product type, technology, and channel segments.
Bottom-up modeling built forecasts from individual country adoption curves for connected health devices, while top-down approaches anchored projections to macro healthcare expenditure trends and aging demographic replacement cycles across the analysis window. Segmentation dimensions included product format, connectivity protocol, end-user institution type, and distribution channel concentration. CAGR derivation incorporated technology substitution rates for Bluetooth-enabled devices displacing basic digital displays, alongside regulatory compliance cost escalations affecting new entrant market access.
The model assumes a particular technology adoption path; alternative pathways for thermopile array sensor integration or software-as-a-medical-device reclassification severity would alter the outlook. Forecasts reflect assumptions regarding notified body capacity expansion and infrared semiconductor supply stabilization. Practitioners should monitor EU MDR guidance document evolution, Asian foundry capacity announcements, and pharmacy chain consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Latin America Lidar Market