
 Vibration Analyzer Market | 2026-2036
Vibration Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Vibration Analyzer Market Analytics
German sensor manufacturers and precision instrumentation specialists is expanding production capacity for piezoelectric accelerometers and FFT-based diagnostic systems. Emerson Electric Co. leverages integrated software-hardware platforms to anchor its position in process industries. SKF sustains competitive differentiation through captive bearing diagnostics expertise that extends into aftermarket services. Siemens AG dominates European rail and power generation accounts with IEC-compliant certification pathways.
A vibration analyzer measures mechanical oscillation amplitude, frequency, and phase using piezoelectric or MEMS accelerometers, typically resolving signals from 0.1 Hz to 20 kHz for rotating machinery fault detection. The instrument converts analog vibration signatures into digital spectra through fast Fourier transform algorithms, enabling technicians to identify imbalance, misalignment, bearing degradation, or structural resonance before catastrophic failure. Portable analyzers still command the largest installed base due to field service flexibility, though wireless analyzers are gaining fastest as IIoT architectures embed continuous monitoring nodes across distributed assets. Machine learning technology segments attract disproportionate R&D investment because algorithmic fault classification reduces reliance on specialized human diagnosticians and compresses response times in critical applications.
OSHA enforces permissible vibration exposure limits that compel employers to deploy certified measurement instruments for workplace safety compliance. The EU Machinery Directive and ISO 10816 together mandate condition monitoring integration for machinery placed on the European market, directly stimulating analyzer procurement. FDA 21 CFR Part 11 requirements in pharmaceutical manufacturing further constrain instrument validation protocols. Stakeholders must weigh capital deployment between retrofitting legacy wired installations and migrating to cloud-connected wireless architectures that promise lower lifecycle service costs but demand cybersecurity infrastructure investment.
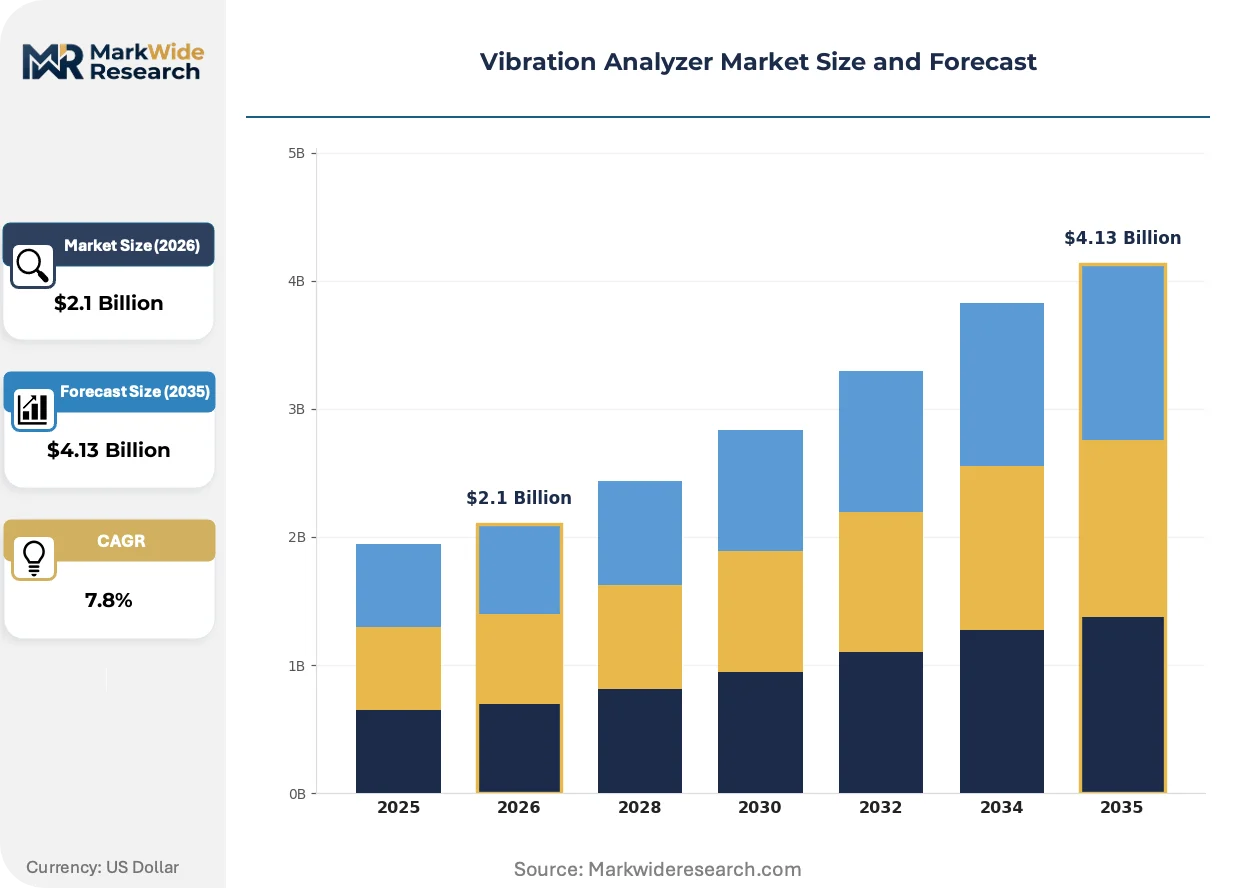
Market Dynamics
Predictive maintenance mandates across energy and manufacturing verticals are compressing replacement cycles for wired diagnostic equipment, while machine-learning classification algorithms reduce technician training burdens and accelerate fault detection workflows in distributed asset environments.
Growth Catalysts
- EU Machinery Directive:Mandatory condition monitoring integration for machinery placed on the European market directly stimulates analyzer procurement from OEMs and retrofit contractors.
- OSHA vibration exposure standards:Permissible exposure limits compel employers in US manufacturing and construction to deploy certified measurement instruments for workplace safety compliance.
- Piezoelectric accelerometer advances:German precision manufacturing clusters demand high-frequency analysis capabilities for quality assurance in automotive powertrain testing.
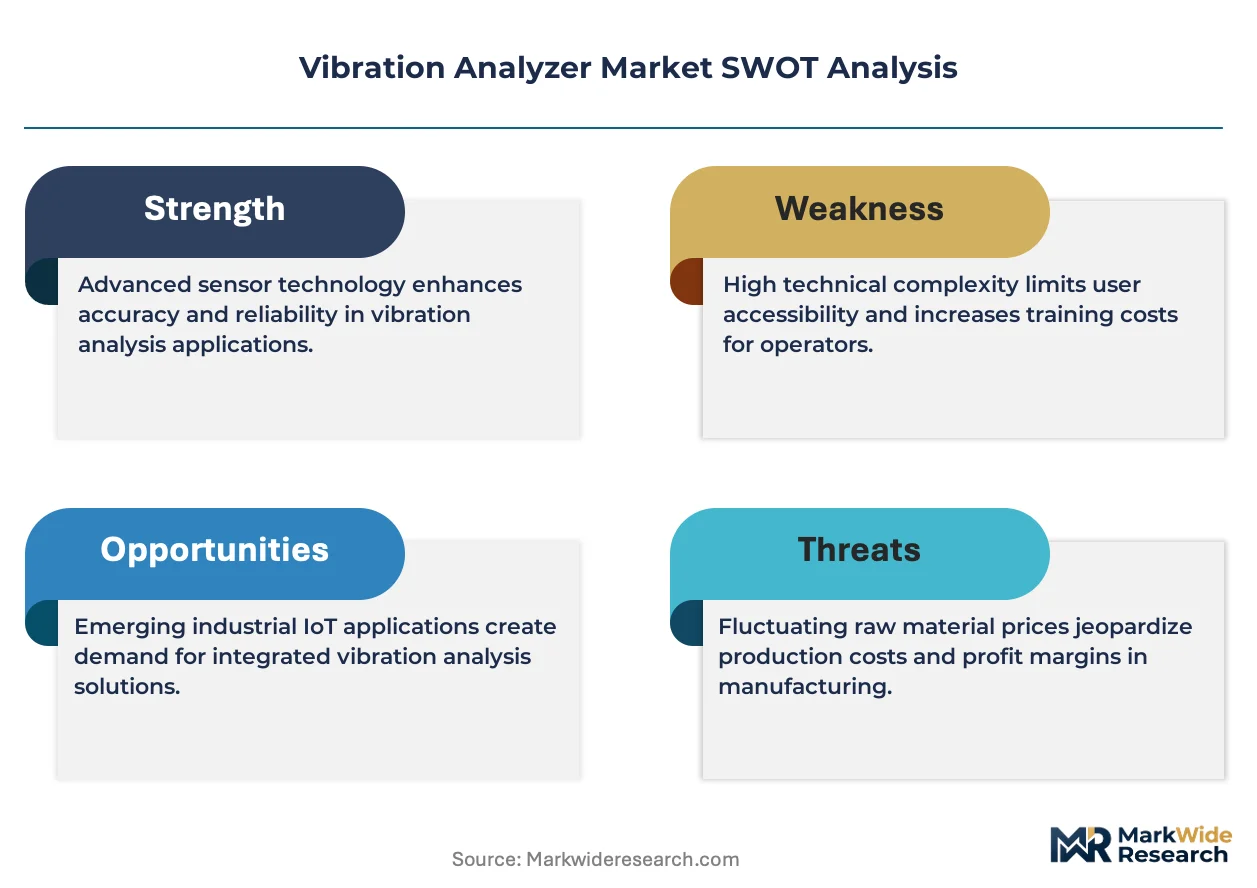
Market Restraints
- MEMS sensor cost volatility:Silicon wafer pricing fluctuations and foundry capacity constraints in East Asian semiconductor manufacturing squeeze margins for mid-tier analyzer producers.
- Calibration certification friction:ISO 10816 compliance timelines and national metrology institute traceability requirements extend sales cycles by 4-8 weeks in regulated industries.
- Wireless infrastructure substitution:Cloud-connected IIoT monitoring nodes displace standalone portable analyzers in greenfield industrial deployments, threatening replacement revenue streams.
Strategic Opportunities
- Pharmaceutical validation protocols:FDA 21 CFR Part 11 requirements create captive demand for instrument qualification documentation and audit-trail software in US drug manufacturing.
- Railway electrification:IEC-compliant certification pathways for high-voltage traction systems open specialized procurement channels in European and Asian rail networks.
- Edge-AI convergence:On-device neural network inference combined with 5G low-latency backhaul enables real-time anomaly detection without cloud dependency in remote oil and gas assets.
Industry Challenges
- Vibration diagnostician scarcity:Specialized expertise in FFT interpretation and bearing fault signature recognition constrains service expansion for aftermarket providers.
- Legacy system integration:Retrofitting cloud-connected wireless architectures into existing SCADA environments demands cybersecurity infrastructure investment and protocol translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibration Analyzer Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Wired Analyzers, Wireless Analyzers, Fixed Analyzers Technology: Time Domain, Frequency Domain, Waveform Analysis, Machine Learning End User: Aerospace, Automotive, Manufacturing, Energy Application: Predictive Maintenance, Structural Health Monitoring, Condition Monitoring, Quality Control |
| Companies Covered | Baker Hughes Company, Emerson Electric Co., SKF, Schaeffler AG, Honeywell International Inc., Rockwell Automation, Siemens AG, Parker Hannifin Corp, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibration Analyzer Market Evolving Landscape
Machine learning algorithms are compressing fault classification timelines while wireless IIoT architectures embed continuous monitoring nodes across geographically dispersed industrial assets, fundamentally altering how maintenance organizations procure and deploy diagnostic instrumentation.
Edge-computing vibration analyzers are integrating on-device neural network inference engines that process accelerometer data locally without cloud dependency. Offshore oil platform operators and remote mining sites are deploying these units fastest where connectivity is intermittent or bandwidth-constrained. This architecture is integrating predictive maintenance workflows into safety-critical environments previously excluded from real-time monitoring due to latency requirements.
OSHA enforcement of permissible vibration exposure limits is tightening calibration traceability requirements for workplace safety measurement tools. Industrial employers must now document instrument certification through accredited national metrology institutes. US manufacturing facilities, particularly in metalworking and foundry operations, are responding by consolidating analyzer fleets under enterprise asset management platforms that automate recertification scheduling.
Service unbundling is fragmenting traditional hardware-software bundles as end-users demand modular procurement. Pharmaceutical and food processing plants are separating instrument validation, cloud analytics subscriptions, and field calibration into distinct purchase decisions. This pattern is most visible in North American and Western European markets where procurement teams possess sufficient technical sophistication to evaluate component vendors independently.
Vibration Analyzer Market Segmentation
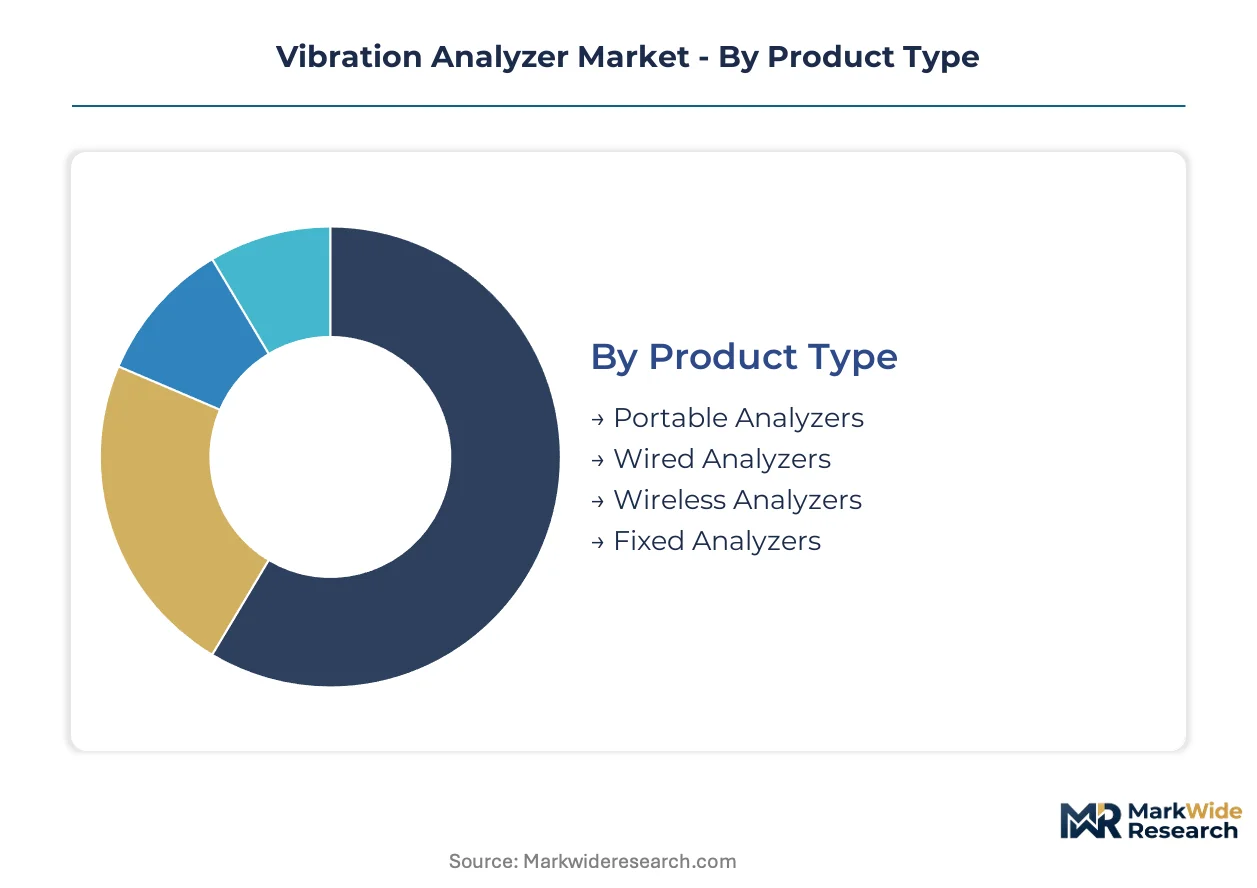
Vibration analyzer procurement patterns diverge sharply across deployment contexts, with wireless architectures displacing portable units in greenfield IIoT installations while wired systems retain dominance in regulated retrofit environments. Understanding these segment boundaries clarifies where R&D investment concentrates and which certification pathways command premium pricing.
Product Type:
Supply concentration tilts toward German and Japanese manufacturers for piezoelectric accelerometer cores, while MEMS-based units flow from Taiwanese foundries with volatile lead times.
- Portable Analyzers:Battery-powered handheld units integrating FFT processing and local display for field technicians. Demand concentrates in US metalworking and construction sectors where OSHA vibration exposure compliance mandates workplace measurements. Calibration certification friction through NIST-traceable laboratories extends replacement cycles.
- Wireless Analyzers:Battery-operated nodes transmitting accelerometer data via LoRaWAN or 5G to cloud analytics platforms. German automotive clusters and Texas oilfield operators deploy these fastest for distributed asset coverage without cabling infrastructure. Machine learning-enabled fault classification reduces technician training burdens.
- Wired Analyzers:Permanently installed units with shielded cable connections to PLC or SCADA systems. Legacy manufacturing facilities in Japan and South Korea favor these for electromagnetic interference immunity in high-voltage environments.
- Fixed Analyzers:Rack-mounted or panel-integrated systems for continuous monitoring stations. European rail electrification projects specify these for IEC-compliant traction system diagnostics.
Today's leader: Portable Analyzers. Tomorrow's challenger: Wireless Analyzers.
Technology:
Cost tier stratification separates premium machine learning platforms from commodity time-domain instruments, with frequency domain systems occupying the mid-market validation niche.
- Machine Learning:Neural network inference engines trained on bearing fault signature databases for automated anomaly classification. Pharmaceutical manufacturers under FDA 21 CFR Part 11 requirements adopt these to compress validation documentation and reduce human diagnostician dependency.
- Frequency Domain:FFT-based spectral analysis resolving vibration signatures into discrete frequency bins for imbalance and misalignment detection. German precision manufacturing clusters demand high-resolution capabilities for automotive powertrain quality assurance.
- Time Domain:Peak-to-peak amplitude and RMS velocity measurements without spectral decomposition. Basic predictive maintenance programs in emerging manufacturing economies favor these for lowest capital deployment.
- Waveform Analysis:Raw time-series capture with post-processing flexibility for transient event investigation. Aerospace MRO facilities in France and California use these for turbine blade resonance studies.
Machine learning platforms are climbing the fastest, though frequency domain systems retain the largest installed revenue base.
End User:
Application intensity varies by sector, with energy verticals deploying continuous monitoring at scale while automotive concentrates investment in precision manufacturing quality gates.
- Energy:Oil and gas upstream operators and wind farm asset managers. Offshore platform operators in the North Sea and Gulf of Mexico deploy edge-AI analyzers where connectivity constraints exclude cloud dependency.
- Automotive:Powertrain testing laboratories and final assembly line quality stations. German OEMs and their tier-one suppliers drive specification requirements for high-frequency analysis capabilities.
- Manufacturing:General industrial rotating equipment including pumps, motors, and compressors. US metalworking facilities respond to OSHA enforcement with certified measurement instrument procurement.
- Aerospace:Engine test cells, airframe structural validation, and MRO operations. FAA certification pathways for engine health monitoring systems constrain supplier qualification.
Energy verticals are gaining share fastest, though automotive retains the highest specification density per unit.
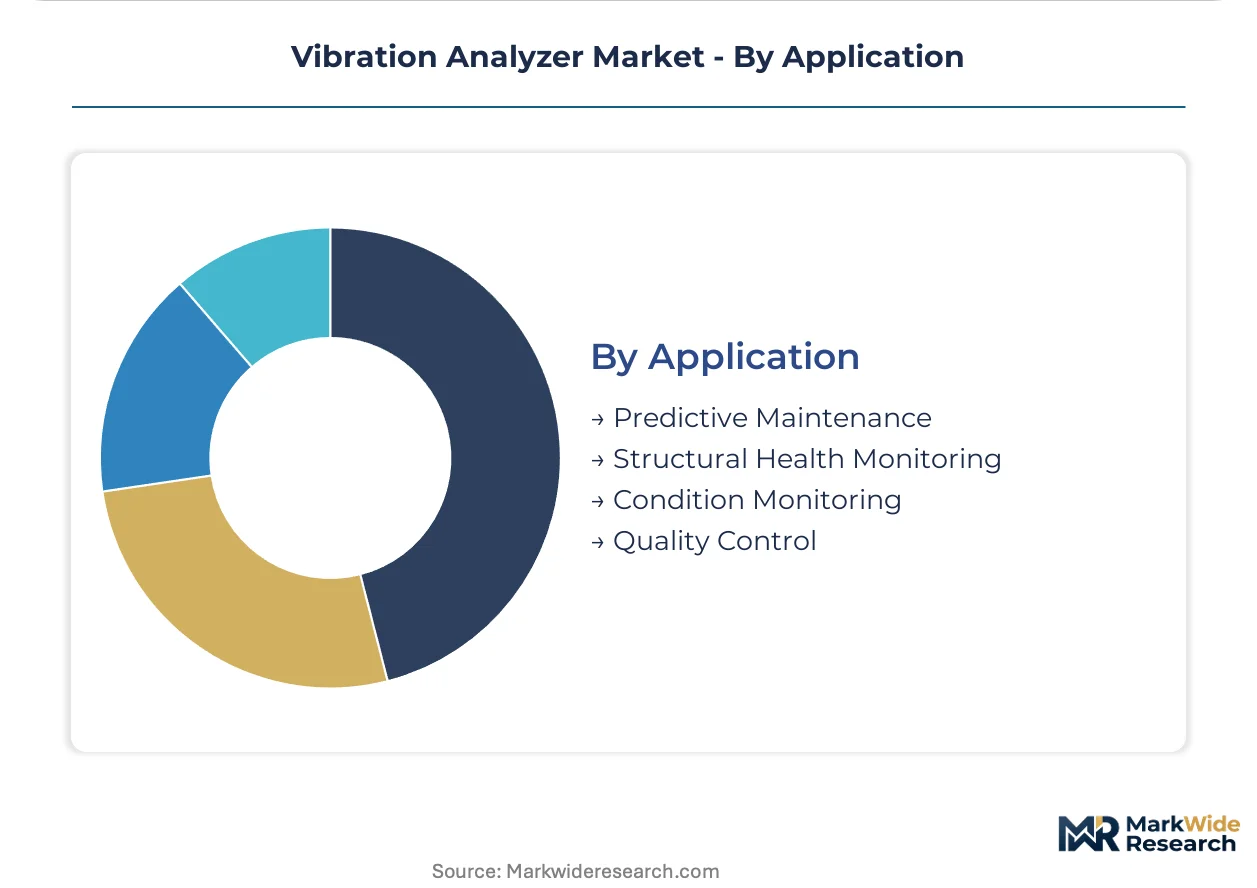
Application:
Customer type bifurcation separates safety-critical infrastructure operators from quality-driven discrete manufacturers, with procurement authority residing in different organizational functions.
- Predictive Maintenance:Scheduled intervention based on degradation trend analysis rather than calendar intervals. Energy sector mandates across US utility and European rail networks accelerate replacement of run-to-failure practices.
- Condition Monitoring:Continuous surveillance of rotating machinery health parameters with alarm thresholds. EU Machinery Directive compliance requirements directly stimulate analyzer procurement for machinery placed on the European market.
- Quality Control:End-of-line vibration testing for assembled products against specification limits. Automotive powertrain and white goods manufacturers in Germany and Japan deploy these for warranty cost reduction.
- Structural Health Monitoring:Civil infrastructure and airframe integrity assessment using accelerometer networks. Bridge operators in California and tunnel systems in Switzerland adopt wireless architectures for long-term degradation tracking.
Condition monitoring commands the largest current deployment base, while structural health monitoring represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier specification density while the United States drives volume through OSHA-mandated workplace compliance programs. Japanese and Chinese manufacturers compete on sensor cost engineering, though calibration certification requirements favor established European suppliers.
United States
OSHA enforcement of permissible vibration exposure limits compels metalworking and construction employers to deploy certified measurement instruments. FDA 21 CFR Part 11 requirements in pharmaceutical manufacturing constrain instrument validation protocols. Texas oilfield operators and California aerospace MRO facilities anchor demand for wireless and waveform analysis systems respectively.
Germany
Automotive powertrain testing laboratories and precision manufacturing clusters demand high-frequency analysis capabilities for quality assurance. The EU Machinery Directive mandates condition monitoring integration for machinery placed on the European market. Bavarian and Baden-Württemberg industrial corridors concentrate bearing diagnostics expertise and piezoelectric accelerometer production capacity.
China
Wind farm asset managers and general manufacturing rotating equipment programs compress replacement cycles for diagnostic hardware. GB standards and MIIT industrial equipment regulations shape certification requirements for domestic procurement. Yangtze River Delta manufacturing hubs absorb MEMS-based units for cost-sensitive predictive maintenance deployment.
Japan
Legacy manufacturing facilities favor wired analyzers for electromagnetic interference immunity in high-voltage environments. METI industrial efficiency programs and JIS standards guide instrumentation procurement in process industries. Nagoya automotive clusters and Osaka precision machinery districts sustain demand for frequency-domain systems with high-resolution capabilities.
United Kingdom
Railway electrification projects specify IEC-compliant fixed analyzers for high-voltage traction system diagnostics. HSE vibration exposure regulations parallel OSHA frameworks in mandating certified workplace measurement tools. Midlands manufacturing corridors and Scottish offshore oil support bases deploy portable and edge-AI units for distributed asset coverage.
Vibration Analyzer Market Competitive Landscape
German producers anchor one tier; US specialists hold process industry integration positions. The vendor base separates into three concentration levels: diversified industrial conglomerates with captive diagnostic divisions, precision sensor manufacturers with accelerometer core competencies, and software-centric platforms unbundling analytics from hardware. Strategic moves concentrate on M&A for bearing diagnostics expertise and capacity expansion for wireless IIoT node production.
Within the diversified industrial tier, Emerson Electric Co. and Siemens AG exemplify integrated software-hardware platform strategies. SKF occupies a position as a bearing-centric specialist extending into aftermarket services. These three represent distinct archetypes: the process automation conglomerate, the European rail and power generation incumbent, and the captive component-to-service vertical.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Emerson Electric Co. |
| SKF |
| Schaeffler AG |
| Honeywell International Inc. |
| Rockwell Automation |
| Siemens AG |
| Parker Hannifin Corp |
| Fluke Corporation |
| Others |
Value Network & Pricing Analysis
Captive production of piezoelectric accelerometer cores by German precision manufacturers anchors both supply security and premium pricing power for high-frequency diagnostic systems. This integration pattern insulates tier-one suppliers from MEMS cost volatility while forcing mid-tier competitors into price-competitive procurement from Taiwanese foundries.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing hubs are reshaping price floors for MEMS-based portable analyzers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10816-certified systems with NIST-traceable calibration from basic time-domain units. Cost compression in the economy tier is intensifying because silicon wafer pricing fluctuations squeeze foundry margins. Automotive powertrain testing laboratories in Germany exhibit the lowest price sensitivity, while general manufacturing rotating equipment programs in emerging economies prioritize capital deployment minimization.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries for MEMS accelerometer wafers. German and Japanese manufacturers anchor piezoelectric sensor production, while Chinese assembly operations handle cost-sensitive portable unit integration. Raw material dependencies span lithium niobate crystals, precision-machined aluminum housings, and shielded cable assemblies. Tariff exposure on semiconductor components from East Asian suppliers threatens margin stability for mid-tier producers. Distribution runs through direct OEM relationships for fixed analyzers and industrial distributors for portable field-service units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA enforcement timelines in the United States run ahead of EU Machinery Directive implementation schedules, creating a twelve-to-eighteen-month arbitrage window for certification-capable suppliers to capture US workplace compliance demand before European mandates fully activate.
For Market Incumbents: Deploy machine learning algorithm libraries as defensive moats against software-centric entrants unbundling analytics from hardware. SKF's captive bearing diagnostics expertise and Emerson's integrated platform architectures demonstrate how proprietary fault signature databases constrain competitor access to automotive and process industry accounts. Capacity expansion in edge-AI inference chips insulates against semiconductor supply constraints threatening wireless analyzer production. For New Entrants and Emerging Players: Enter via pharmaceutical validation protocol services as an unbundled software layer, bypassing capital-intensive hardware manufacturing. FDA 21 CFR Part 11 documentation and audit-trail software represent the most penetrable segment, with incumbent hardware vendors lacking specialized compliance engineering depth. A SaaS-based instrument qualification platform targeting North American drug manufacturing procurement teams offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service providers because ISO 10816 compliance timelines extend sales cycles and fragment aftermarket service markets. Long-term viability hinges on wireless IIoT architecture migration rates; the signal to watch is 5G private network deployment velocity in oil and gas upstream operations, which determines whether edge-AI analyzers displace cloud-dependent alternatives in bandwidth-constrained environments.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Platform Integration | Neural network fault classification reduces technician training burdens for distributed asset operators. |
| Wireless IIoT Node Production Scale-Up | LoRaWAN and 5G-enabled units capture greenfield industrial deployment demand from Texas oilfield operators. |
| Certification Investment in IEC Pathways | European rail electrification projects specify compliant fixed analyzers for high-voltage traction diagnostics. |
| Backward Integration into Accelerometer Cores | In-house piezoelectric sensor production insulates German manufacturers from foundry capacity constraints. |
| Pharmaceutical Validation Service Expansion | FDA 21 CFR Part 11 documentation capabilities create captive demand in US drug manufacturing procurement. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors and plant engineers, secondary validation through SEC filings and customs data, and technical specification review — were reconciled to construct segment-level demand estimates. Conversations with aftermarket service heads at bearing manufacturers, OEM procurement teams in automotive powertrain testing, and biomedical engineers in pharmaceutical manufacturing informed deployment pattern assumptions. Trade data from German precision instrumentation exports, Japanese wired analyzer shipments, and Chinese MEMS component flows anchored supply-side calibration. Bottom-up unit economics and top-down industrial equipment spend ratios were cross-checked for consistency.
Data-stream reconciliation across product type, technology tier, end-use vertical, and application intensity dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from replacement cycle compression rates in energy sector predictive maintenance programs and wireless architecture penetration curves in greenfield industrial deployments. Modeled inputs included OSHA enforcement trajectory assumptions for workplace compliance instrumentation and EU Machinery Directive implementation timelines for condition monitoring mandates.
Inputs from FDA warning letter databases and EMA machinery safety guidance were available through the study window; gaps in real-time wireless IIoT deployment metrics at remote oil and gas assets introduce uncertainty bands around edge-AI adoption velocity. Forecasts reflect documented assumptions regarding semiconductor foundry capacity expansion and 5G private network rollout schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ohm Meter Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Destructive Testing Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
DSL Tester Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
Compression Testers Market