
 Global Printed Sensor Market | 2026-2036
Global Printed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printed Sensor Market Outlook
Automotive OEMs is unwinding legacy reliance on conventional silicon sensors in favor of printed alternatives for cabin pressure and seat occupancy detection. Interlink Electronics specializes in force-sensing resistor architectures for human-machine interface applications. Thin Film Electronics ASA leverages its printed memory and sensor integration platform to anchor Nordic supply relationships. Tekscan dominates pressure mapping niches in medical and industrial end uses with calibrated matrix arrays.
Printed sensors are thin-film transducers fabricated through additive processes such as screen printing or inkjet deposition of conductive, semiconducting, and dielectric inks onto flexible polymer substrates, typically achieving thicknesses below 500 micrometers to enable conformal integration with curved surfaces. Their primary purpose is to convert mechanical, thermal, or chemical stimuli into electrical signals for real-time monitoring in weight-critical or geometry-constrained systems. Pressure sensors occupy the largest product category due to penetration across automotive seating and wearable fitness bands, while gas sensors represent the fastest-expanding segment driven by indoor air quality mandates and industrial leak detection requirements. Inkjet printing technology leads in R&D intensity for multilayer precision, though screen printing sustains cost advantages at production scale for single-layer conductive traces.
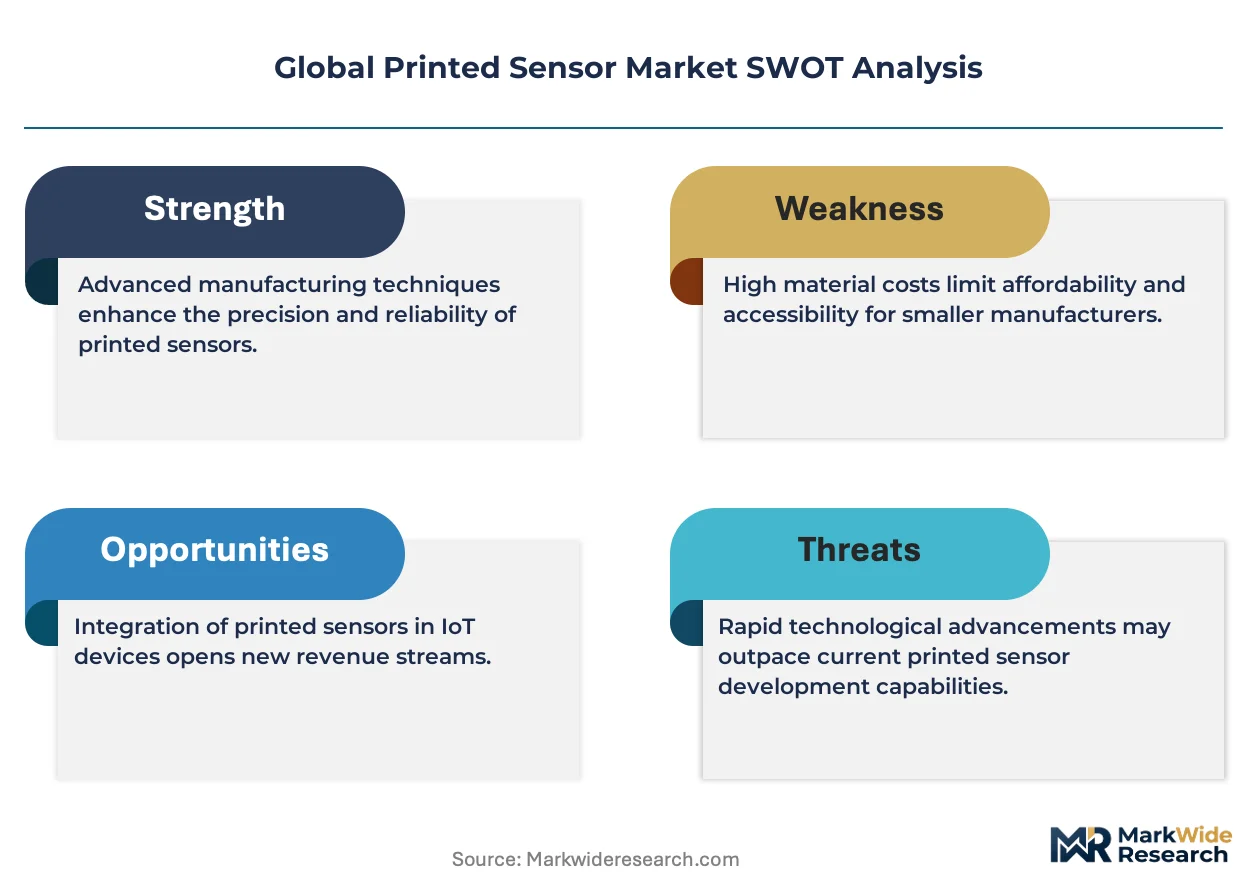
FDA biocompatibility standards for patient-contact devices and EPA restrictions on volatile organic compounds in solvent-based inks constrain formulation choices and manufacturing site qualifications. REACH substance authorization in Europe limits certain nanoparticle additives, pushing suppliers toward silver flake and carbon-based conductive alternatives. Stakeholders must monitor evolving IEC performance standards for flexible electronics and decide between regional compliance investments or platform unification strategies.
Market Dynamics
Automotive manufacturers are systematically replacing silicon-based pressure sensors with printed alternatives to reduce wiring harness weight and enable conformal integration across curved interior surfaces. This substrate-level technology transition is compressing qualification timelines and forcing ink formulators to harmonize thermal stability with biocompatibility requirements.
Growth Catalysts
- REACH Substance Authorization:European restrictions on nanoparticle additives are accelerating supplier migration toward silver flake and carbon-based conductive alternatives, opening formulation partnerships between chemical distributors and printed electronics foundries.
- Remote Patient Monitoring:Healthcare systems in Germany and the United States are deploying flexible biosensors for continuous glucose and cardiac monitoring, creating pull-through demand for roll-to-roll manufacturing capacity.
- Fraunhofer Institute Clusters:Applied research consortia in Bavaria and Saxony are de-risking scale-up of hybrid printed-inorganic sensor architectures through shared pilot lines and open-access characterization facilities.
Market Restraints
- Silver Price Volatility:Conductive ink formulations remain exposed to London Metal Exchange silver price swings, compressing gross margins for screen printing operations serving automotive tier-one suppliers.
- Solvent-Based Ink Restrictions:EPA volatile organic compound limits and equivalent state-level air quality regulations in California and Texas are forcing capital expenditure toward water-based or UV-curable deposition systems.
- Substrate Supply Concentration:Polyethylene naphthalate film production concentrates among Japanese and Korean chemical conglomerates, creating single-source vulnerability for temperature-stable flexible sensor substrates.
Strategic Opportunities
- Indoor Air Quality Mandates:French and Dutch building codes are mandating continuous VOC and CO2 monitoring in commercial structures, opening printed gas sensor deployment in HVAC retrofit channels.
- Printed Memory Integration:Convergence of sensor arrays with non-volatile memory layers enables localized data logging for cold-chain pharmaceutical tracking without external power.
- Brazilian Industrial Leak Detection:ANVISA process safety requirements for chemical manufacturing facilities are creating first-mover advantage for calibrated printed hydrogen sulfide sensor networks.
Industry Challenges
- Multiphysics Simulation Talent:Design of electromechanical sensor response requires scarce expertise coupling fluid dynamics with conductive percolation modeling, lengthening product development cycles.
- FDA 510(k) Pathway Complexity:Patient-contact printed biosensors face extended biocompatibility testing timelines for ISO 10993 cytotoxicity and sensitization endpoints, delaying revenue recognition.
- Legacy System Integration:Automotive OEM electrical architectures built around silicon sensor voltage output standards require signal conditioning layer redesign to accommodate printed sensor resistance-mode interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printed Sensor Market |
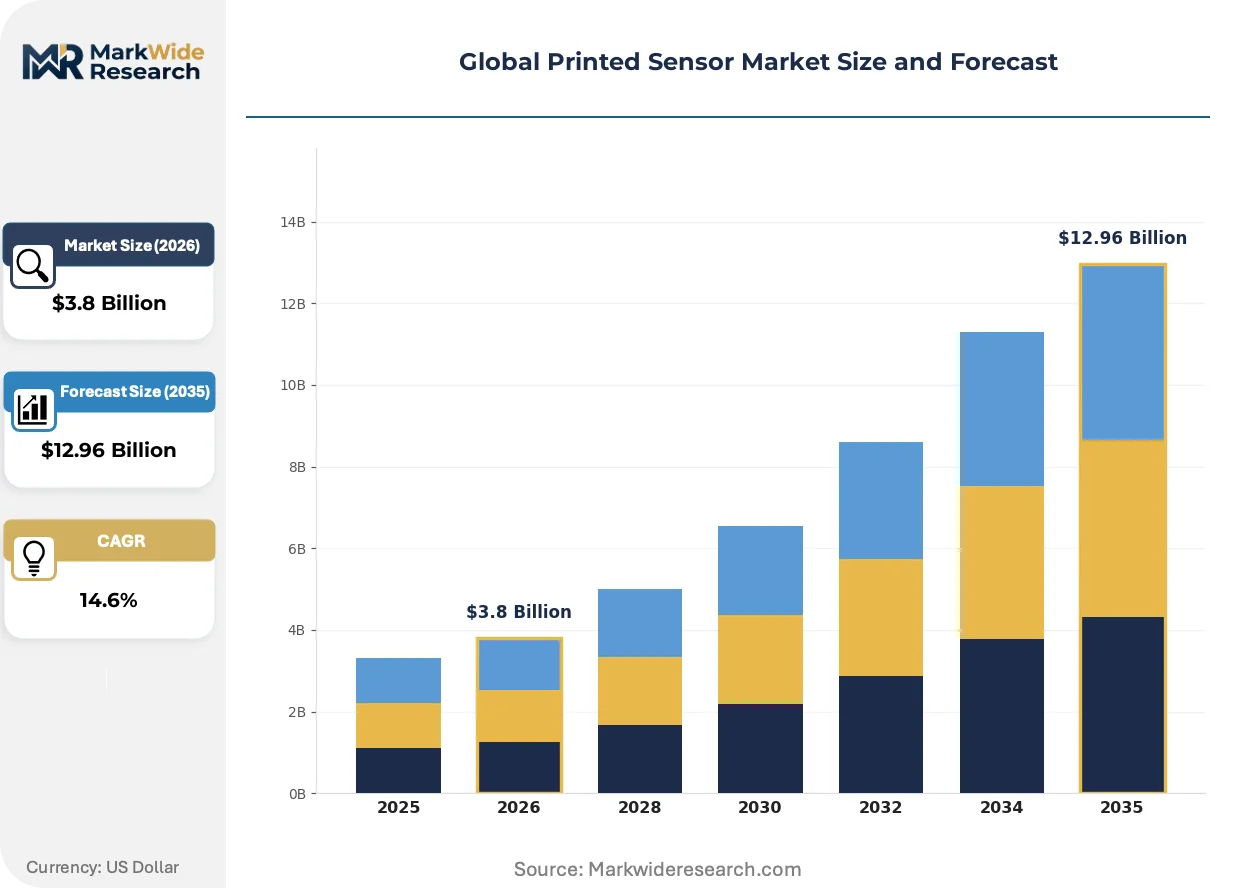
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Gas Sensors, Humidity Sensors Application: Wearable Devices, Smart Packaging, Environmental Monitoring, Automotive End User: Healthcare, Consumer Electronics, Industrial Automation, Agriculture Technology: Inkjet Printing, Screen Printing, Gravure Printing, Flexography |
| Companies Covered | Interlink Electronics Inc., Thin Film Electronics ASA, GSI Technologies LLC, ISORG SA, Peratech Holdco Limited, Canatu Oy, PolyIC GmbH. & Co. Kg, Tekscan Inc., Nissha Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printed Sensor Market Strategic Shifts
Deposition technology selection is fragmenting across end-use requirements, with precision demands and cost thresholds diverging sharply between medical diagnostic and automotive interior applications. This divergence is forcing equipment suppliers to modularize print head architectures rather than pursue universal platforms.
Silver nanowire conductive inks are supplanting traditional silver flake formulations in high-resolution biosensor electrodes. Medical device contract manufacturers in Massachusetts and Minnesota are adopting these materials to achieve sub-50-micrometer trace widths for glucose monitoring strips. The transition is compressing incumbent inkjet nozzle maintenance intervals while enabling conformal coverage over skin-textured surfaces previously inaccessible to rigid electrodes.
EU Medical Device Regulation (MDR) Class IIa reclassification of wearable diagnostic sensors is tightening clinical evidence requirements for printed biosensor platforms. Manufacturers must now submit post-market surveillance data demonstrating electrical stability across flex cycling. German notified bodies are interpreting this most stringently for continuous monitoring applications, driving consolidation of quality management systems among mid-tier sensor assemblers.
Automotive procurement organizations are unbundling sensor module sourcing from tier-one seating suppliers, establishing direct relationships with printed electronics foundries. This disintermediation is visible most acutely in Stuttgart and Wolfsburg supply corridors, where OEM technical teams now specify ink-substrate combinations rather than accepting black-box module specifications. The shift compresses tier-one margin pools while rewarding formulators with validated automotive production part approval process track records.
Global Printed Sensor Market Segmentation
Printed sensor architectures diverge sharply across deposition methods and substrate requirements, fragmenting procurement strategies by end-use tolerance for precision versus unit cost. Understanding these segment boundaries clarifies where formulation partnerships yield sustainable margin capture versus commodity exposure.
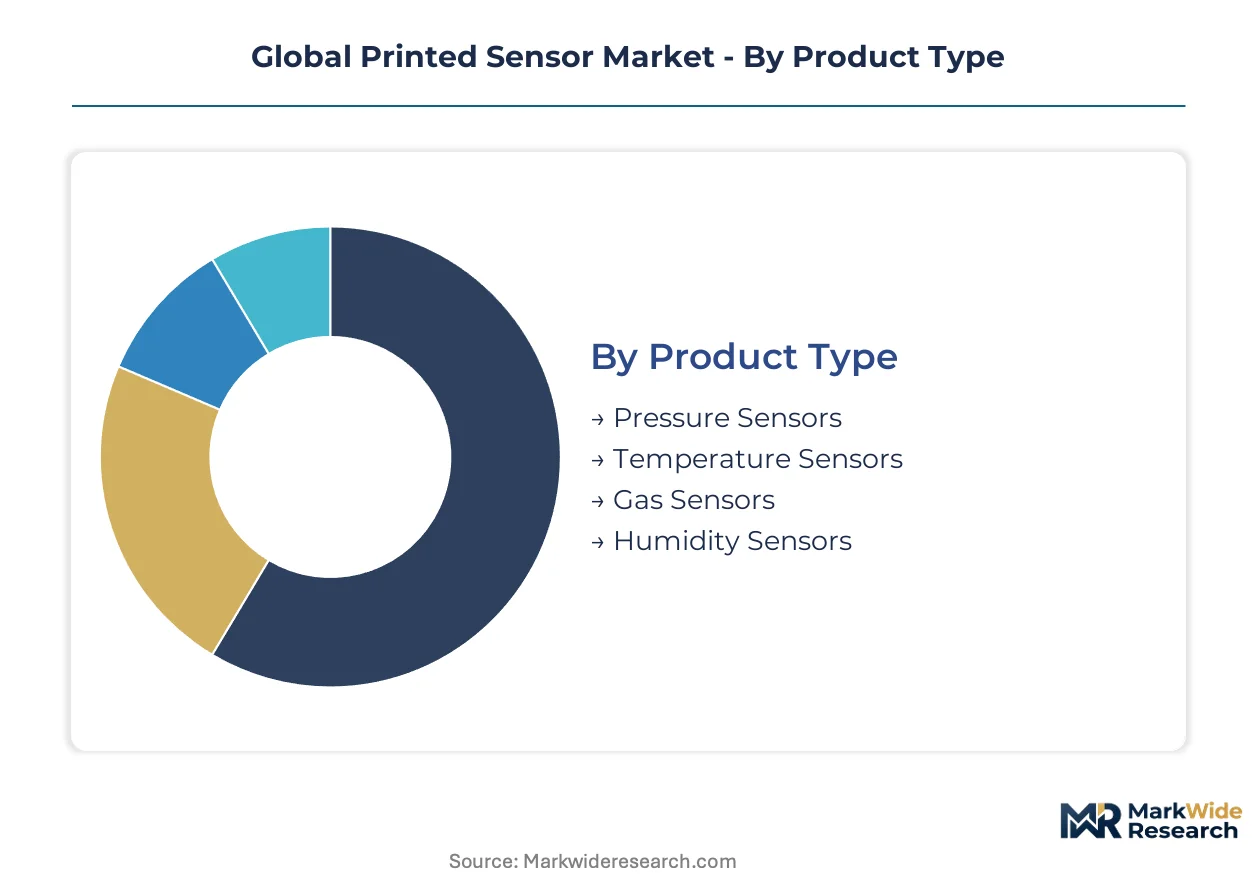
Product Type:
Margin pools concentrate in pressure sensing architectures where automotive seating specifications and wearable form factors command premium ink qualification investments.
- Pressure Sensors:These transducers translate mechanical deformation into resistance changes through piezoresistive or capacitive mechanisms printed onto polyester or polyimide substrates. Automotive OEMs in Germany and the United States specify these for seat occupancy detection and cabin pressure management, driving demand for thermal cycling validation beyond 10,000 flex repetitions.
- Gas Sensors:Chemiresistive layers detect volatile organic compounds and carbon dioxide through functionalized carbon nanotube or metal oxide formulations. French and Dutch building codes mandating continuous indoor air quality monitoring are accelerating deployment in HVAC retrofit channels across commercial real estate.
- Temperature Sensors:Printed thermistors and thermocouples leverage silver or carbon conductive traces with negative temperature coefficient inks for cold-chain pharmaceutical tracking.
- Humidity Sensors:Capacitive architectures using dielectric polymers absorb moisture to shift electrical properties, finding niche adoption in agricultural greenhouse automation.
The dominant share belongs to pressure sensors, while gas sensors are closing the gap fastest.
Application:
Application selection determines whether volume economics or precision premiums govern supplier relationships, with automotive and medical channels diverging on qualification timelines.
- Automotive:Conformal sensor integration across curved interior surfaces reduces wiring harness weight while enabling seat occupancy, cabin pressure, and human-machine interface detection. Stuttgart and Wolfsburg procurement teams now specify ink-substrate combinations directly rather than accepting tier-one module specifications.
- Wearable Devices:Continuous glucose and cardiac monitoring patches require sub-50-micrometer trace widths and ISO 10993 biocompatibility certification. Massachusetts and Minnesota contract manufacturers are migrating to silver nanowire formulations for skin-conformal coverage.
- Smart Packaging:Printed indicators track temperature excursions and tamper evidence for pharmaceutical and perishable logistics.
- Environmental Monitoring:Distributed sensor networks detect industrial leaks and ambient air quality in chemical manufacturing facilities.
Automotive commands the largest revenue pool, though wearable devices are expanding most quickly as FDA 510(k) pathways mature for continuous monitoring indications.
End User:
End-user concentration shapes whether roll-to-roll manufacturing investments target high-mix-low-volume medical batches or automotive scale economies.
- Healthcare:Remote patient monitoring systems in German hospitals and United States health systems deploy flexible biosensors for glucose, cardiac, and respiratory tracking. EU MDR Class IIa reclassification is tightening post-market surveillance requirements for electrical stability across flex cycling.
- Consumer Electronics:Fitness bands and smartwatches integrate force-sensing resistors for touch interface and activity recognition, prioritizing cost compression over clinical-grade precision.
- Industrial Automation:Pressure and position sensing in robotic systems and process control equipment.
- Agriculture:Soil moisture and greenhouse climate monitoring in precision farming operations.
Healthcare generates the highest unit margins, while consumer electronics is gaining share fastest through fitness wearable proliferation.
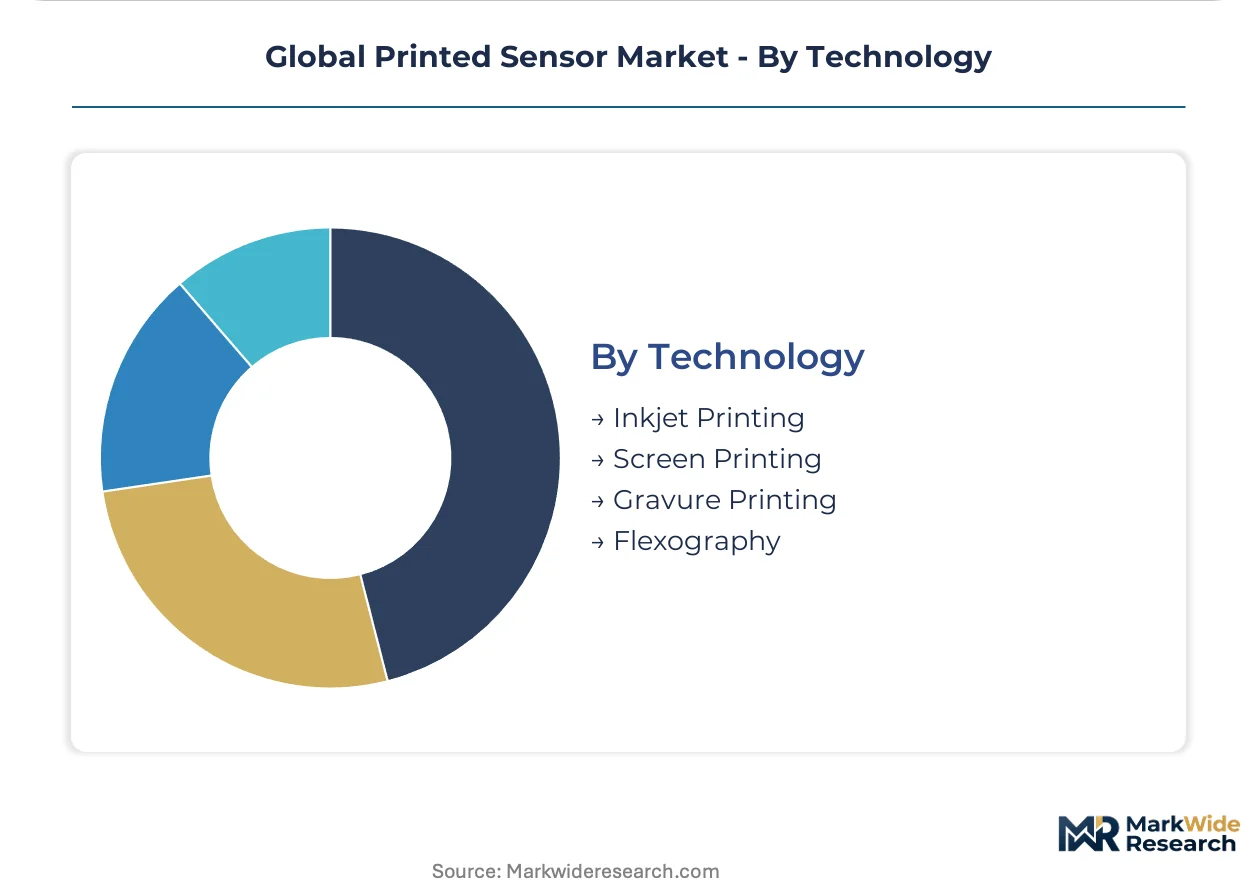
Technology:
Deposition technology selection fragments equipment supplier strategies between precision-module architectures and high-throughput production platforms.
- Screen Printing:Mesh-based stencil deposition achieves 20-100 micrometer line widths with silver flake or carbon conductive inks at production scale. This method sustains cost advantages for single-layer automotive traces despite higher material consumption than alternative methods.
- Inkjet Printing:Piezoelectric drop-on-demand systems enable multilayer precision below 50 micrometers for biosensor electrodes and diagnostic strip architectures. The technology leads R&D intensity but compresses nozzle maintenance intervals with nanowire ink formulations.
- Gravure Printing:Engraved cylinder transfer suits high-volume replication of uniform patterns for packaging and decorative applications.
- Flexography:Raised relief plate printing serves lower-resolution requirements in label and flexible packaging integration.
Screen printing holds the dominant installed base, while inkjet printing is climbing the fastest as medical diagnostic specifications tighten trace geometry tolerances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's dominance in conductive ink imports, while the Trans-Siberian Railway link shapes raw material flows into German manufacturing clusters. These infrastructure assets anchor regional supply security for printed sensor substrates and silver-based formulations.
Germany
Automotive OEM procurement teams in Stuttgart and Wolfsburg specify ink-substrate combinations directly for seat occupancy detection systems. REACH substance authorization limits certain nanoparticle additives, pushing formulators toward silver flake alternatives. Fraunhofer institutes in Bavaria and Saxony operate shared pilot lines de-risking hybrid printed-inorganic sensor scale-up.
United States
FDA 510(k) pathway complexity extends biocompatibility testing timelines for patient-contact biosensors in Massachusetts and Minnesota contract manufacturing. EPA volatile organic compound restrictions force capital expenditure toward water-based deposition systems in California and Texas. Boston and Minneapolis medical device clusters concentrate silver nanowire formulation adoption for glucose monitoring applications.
France
Building codes mandating continuous VOC and CO2 monitoring accelerate printed gas sensor deployment in HVAC retrofit channels across commercial real estate. ANSM interprets EU MDR Class IIa reclassification stringently for wearable diagnostic sensors. Paris and Lyon industrial zones concentrate quality management system consolidation among mid-tier sensor assemblers.
Japan
PMDA biocompatibility standards for patient-contact devices constrain formulation choices for continuous cardiac monitoring patches. METI funding supports roll-to-roll manufacturing capacity expansion for flexible electronics. Tokyo and Osaka chemical conglomerates dominate polyethylene naphthalate film production for temperature-stable flexible substrates.
Brazil
ANVISA process safety requirements for chemical manufacturing facilities create first-mover advantage for calibrated printed hydrogen sulfide sensor networks. The country's national pharmaceutical regulator tightens material traceability for cold-chain pharmaceutical tracking applications. São Paulo industrial corridors anchor deployment of printed temperature indicators for perishable logistics.
Global Printed Sensor Market Competitive Environment
Listed leaders compete with private specialists across qualification-intensive segments, creating a tiered structure where public companies access capital for capacity expansion while private entities retain agility in formulation partnerships. The vendor base separates into three strategic archetypes: diversified electronics conglomerates with printed sensor divisions, pure-play printed electronics foundries, and specialized ink formulators. Dominant competitive moves include direct OEM procurement relationships that disintermediate tier-one module suppliers, and backward integration into captive silver flake production to hedge London Metal Exchange price volatility.
Among Nordic supply relationships, Thin Film Electronics ASA occupies a position exemplifying printed memory and sensor integration platforms. Tekscan Inc. and Interlink Electronics Inc. represent the specialist tier, with the former anchoring pressure mapping niches and the latter exemplifying force-sensing resistor architectures for human-machine interfaces. These three entities illustrate how geographic clustering—Norway for memory-integrated sensors, Massachusetts for calibrated matrix arrays, and California for HMI applications—shapes competitive positioning without requiring universal platform strategies.
| Leading Market Players |
|---|
| Interlink Electronics Inc. |
| Thin Film Electronics ASA |
| GSI Technologies LLC |
| ISORG SA |
| Peratech Holdco Limited |
| Canatu Oy |
| PolyIC GmbH. & Co. Kg |
| Tekscan Inc. |
| Nissha Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silver nanowire ink substitution for traditional flake formulations is redrawing supply geography toward Massachusetts and Minnesota contract manufacturers while compressing nozzle maintenance economics and reformulating cost structures across medical diagnostic tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM direct procurement from tier-one module sourcing and consumer electronics commodity supply. Price differentiation centers on ISO 10993 biocompatibility certification grade and volume scale, with FDA-cleared medical batches commanding substantial premiums over industrial grades. Cost compression in automotive seating specifications is intensifying because Stuttgart and Wolfsburg procurement teams now specify ink-substrate combinations directly. Consumer electronics fitness bands exhibit highest price sensitivity, while healthcare remote monitoring patches show lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Strait of Malacca transit underwrites polyethylene naphthalate film flows from Japanese and Korean chemical conglomerates into German automotive clusters. Raw material sourcing draws from silver flake refineries, carbon nanotube functionalization facilities, and flexible polymer substrate extrusion plants. Single-source vulnerability concentrates in temperature-stable substrate production, with Tokyo and Osaka suppliers anchoring global capacity. Distribution runs through Rotterdam container terminals for European conductive ink imports and Trans-Siberian Railway links for German manufacturing feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) and EU MDR Class IIa certification creates sticky supplier relationships that resist displacement.
For Market Incumbents: Shield formulation partnerships by deepening captive silver flake production to hedge London Metal Exchange volatility. Secure automotive production part approval process track records in Stuttgart and Wolfsburg corridors before tier-one suppliers reassert module bundling. Prioritize post-market surveillance data infrastructure for EU MDR electrical stability across flex cycling requirements.
For New Entrants and Emerging Players: Differentiate on hybrid printed-inorganic sensor architectures through Fraunhofer institute pilot line access in Bavaria and Saxony. Target Brazilian industrial leak detection networks where ANVISA process safety requirements create first-mover calibration advantages. Pursue direct OEM procurement relationships that bypass entrenched tier-one seating suppliers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed printed electronics foundries holding validated automotive track records but lacking medical certification depth. Five-to-ten year viability hinges on convergence of sensor arrays with non-volatile memory layers for cold-chain pharmaceutical tracking. Monitor silver nanowire ink adoption rates in Massachusetts and Minnesota contract manufacturing as inflection signal for medical diagnostic margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Flake Production | Captive supply hedges London Metal Exchange volatility for automotive ink formulators. |
| FDA 510(k) Submission for Continuous Monitoring Patches | Biocompatibility certification unlocks reimbursement pathways in United States health systems. |
| Joint Venture with Fraunhofer Pilot Lines | Shared characterization facilities de-risk scale-up of hybrid printed-inorganic architectures. |
| Long-term Supply Agreement with Japanese Substrate Producers | PEN film security insulates against single-source concentration in temperature-stable flexible bases. |
| Geographic Expansion into Brazilian Industrial Corridors | ANVISA leak detection mandates create calibrated sensor network deployment opportunities. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with printed electronics foundry managers, automotive tier-one procurement directors, medical device contract manufacturers, and conductive ink formulators; and secondary validation through SEC filings, EPA volatile organic compound regulatory dockets, FDA 510(k) clearance databases, and REACH substance authorization records. Bottom-up triangulation across deposition technology adoption rates and top-down reconciliation against automotive seating production volumes anchored segmentation outputs.
Across the analysis window, the forecasting framework modeled product type, application, end user, and technology dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from roll-to-roll manufacturing capacity expansion trajectories and inkjet printing R&D intensity curves. Silver nanowire adoption rates in glucose monitoring strips and Fraunhofer pilot line utilization metrics served as industry-specific calibration inputs.
The analysis sits within stated boundaries; outcomes outside FDA pathway maturation timelines or REACH authorization scope would require recalibration. Forecasts reflect assumptions regarding automotive OEM disintermediation persistence and EU MDR enforcement stringency. Practitioners should keep alternative scenarios live as silver price volatility and substrate supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Global Radar Sensor Market