
 Silicon-Based Fingerprint Sensors Market | 2026-2036
Silicon-Based Fingerprint Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon-Based Fingerprint Sensors Market Intelligence
Subscription-based firmware update services for biometric authentication modules is repositioning how sensor vendors capture lifetime value from OEM customers. Goodix Technology Co., Ltd. leverages its CMOS design heritage to dominate capacitive sensor shipments for mid-tier smartphones. Synaptics Incorporated anchors its position through deep integration with notebook OEMs for Windows Hello-compliant modules. Fingerprint Cards AB differentiates by specializing in ultra-low-power architectures for battery-constrained IoT devices.
Silicon-based fingerprint sensors are semiconductor devices fabricated on silicon wafers using CMOS or MEMS processes, typically achieving resolution of 500-1000 pixels per inch to capture ridge and valley patterns for biometric identification. These sensors convert capacitive, optical, or ultrasonic signals into digital templates for identity verification across consumer, financial, and security applications. Capacitive sensors occupy the largest volume share due to mature foundry economics and proven integration with smartphone button and under-display architectures. Ultrasonic sensors represent the fastest-expanding technology segment as Samsung and Chinese OEMs adopt through-display authentication that penetrates moisture and contaminants. Government ID Programs concentrate the highest margin pools, where FIPS 201 and similar compliance requirements sustain premium pricing for certified modules.
The FBI's Electronic Biometric Transmission Specification shapes product development for vendors serving US federal contracts, while the EU's GDPR and eIDAS framework mandate consent-based biometric processing that elevates on-device template storage architectures. China's GB/T standards for biometric performance testing create a parallel certification pathway that domestic champions like Goodix navigate with regulatory alignment. India's BIS compulsory registration order for electronic components adds a compliance layer for imported silicon modules. Stakeholders must monitor how NIST's ongoing revision of fingerprint minutiae standards reshapes interoperability requirements across banking and border-control procurement cycles.
Market Dynamics
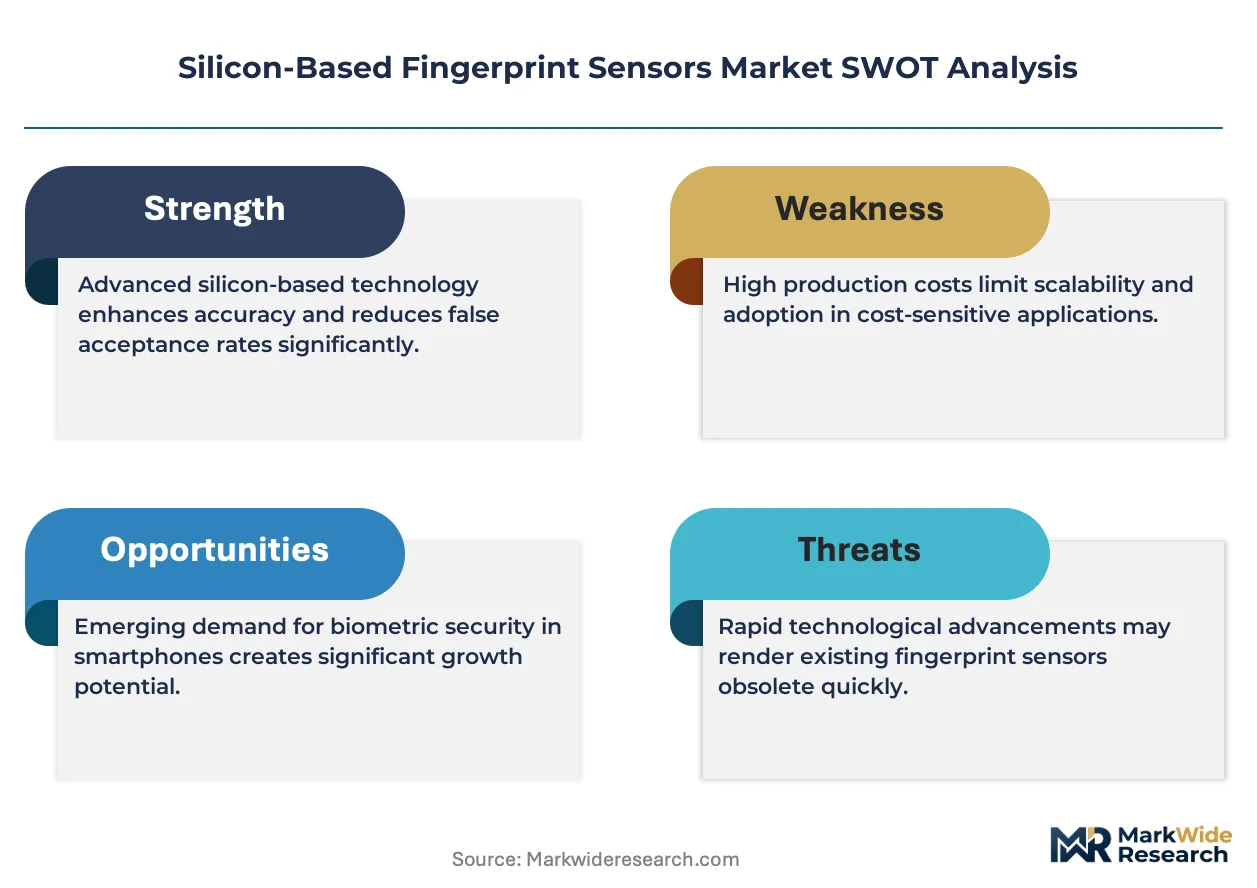
Ultrasonic through-display authentication is compressing capacitive sensor margins while redrawing competitive boundaries between CMOS heritage vendors and MEMS specialists.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Local assembly incentives are accelerating domestic module production capacity and reducing import dependency for smartphone OEMs.
- GDPR and eIDAS framework in Europe:Mandated consent-based biometric processing elevates on-device template storage architectures, favoring certified silicon vendors.
- Shenzhen-Dongguan electronics corridor:Concentrated module integration activity compresses assembly costs fastest, pulling sensor demand into this manufacturing cluster.
Market Restraints
- 300mm silicon wafer supply concentration:Taiwan and South Korea foundries control advanced CMOS fabrication, exposing sensor vendors to geopolitical supply disruption.
- FIPS 201 certification timelines:US federal compliance requirements extend product qualification cycles to 18-24 months, freezing out unqualified competitors.
- Optical fingerprint alternatives:Under-display optical sensors from established display panel vendors threaten ultrasonic premium positioning in mid-tier smartphones.
Strategic Opportunities
- Battery-constrained IoT authentication:Ultra-low-power sensor architectures address untapped demand in smart locks, payment terminals, and wearable devices.
- China's GB/T biometric standards:Domestic certification pathways create protected market access for locally aligned module vendors.
- Subscription firmware services:Recurring revenue models for authentication algorithm updates reposition vendor-OEM relationships beyond hardware shipment economics.
Industry Challenges
- MEMS-CMOS process integration:Ultrasonic sensor production requires rare cross-domain engineering talent spanning acoustic physics and semiconductor fabrication.
- NIST minutiae standard revisions:Ongoing template format updates force continuous R&D investment to maintain banking and border-control procurement eligibility.
Report Scope
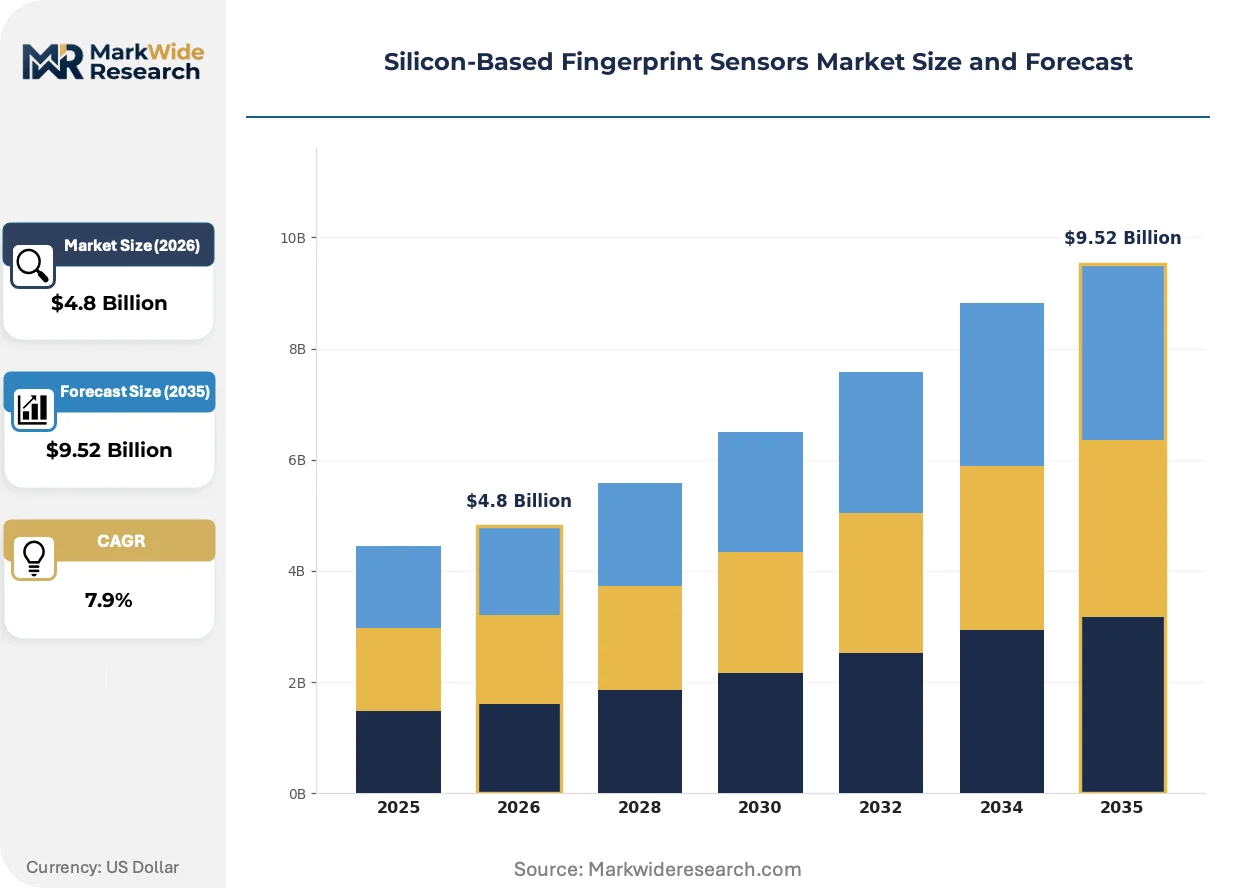
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon-Based Fingerprint Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Optical Sensors, Ultrasonic Sensors, Thermal Sensors, Piezoelectric Sensors Technology: CMOS, MEMS, AFIS, Thin Film Transistor, Nanoimprint, Photolithography Application: Smartphones, Banking Terminals, Access Control Systems, Time & Attendance, Automotive Security, Government ID Programs End User: Consumer Electronics Manufacturers, Financial Institutions, Security Service Providers, Automotive OEMs, Public Sector Agencies |
| Companies Covered | Synaptics Incorporated, Goodix Technology Co., Ltd., Fingerprint Cards AB, Egis Technology Inc., IDEX Biometrics ASA, NEXT Biometrics Group ASA, Qualcomm Incorporated, Sony Corporation, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon-Based Fingerprint Sensors Market Strategic Shifts & Innovations
Authentication architectures are migrating from discrete hardware modules toward system-level biometric platforms that bundle sensing, processing, and template management.
Ultrasonic sensor arrays fabricated with piezoelectric MEMS processes are penetrating moisture-contaminated display surfaces that capacitive technologies cannot read. Samsung and Chinese smartphone OEMs have adopted this architecture for flagship through-display authentication, compressing the addressable market for conventional capacitive button sensors. The technology is converging with flexible OLED panel manufacturing, enabling curved-edge and foldable device form factors previously incompatible with rigid sensor substrates.
China's GB/T standards for biometric performance testing are creating parallel certification requirements that diverge from FBI and NIST frameworks. Domestic vendors aligned with MIIT standardization committees gain accelerated market access, while foreign competitors face extended compliance timelines. Module suppliers serving government ID programs must now maintain dual certification tracks to address procurement pools in both regulatory spheres.
Enterprise notebook buyers are unbundling Windows Hello-compliant module procurement from full system contracts, creating direct vendor relationships previously intermediated by OEMs. Dell, HP, and Lenovo enterprise divisions now source fingerprint sensors through separate component tenders, compressing supplier margins while demanding faster customization cycles. This pattern is most visible in North American and Western European corporate fleet refresh programs where security procurement teams have gained independent purchasing authority.
Silicon-Based Fingerprint Sensors Market Segmentation
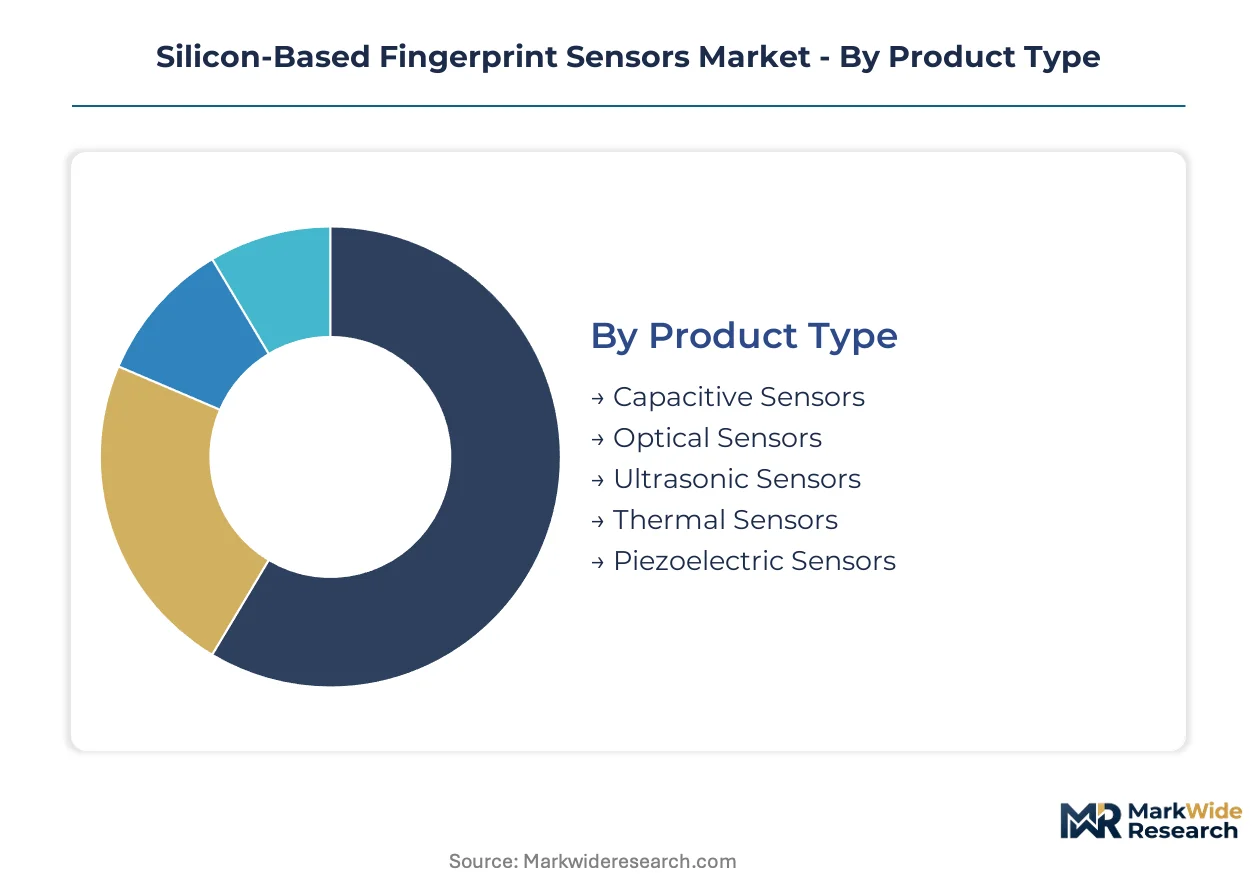
Silicon-based fingerprint sensors fragment across multiple technical and commercial dimensions that shape procurement patterns. Each segmentation axis reveals distinct margin structures, certification requirements, and customer concentration patterns that vendors must navigate.
Product Type:
Capital intensity varies sharply across sensor modalities, with ultrasonic and piezoelectric architectures demanding specialized MEMS foundry partnerships while capacitive designs leverage mature CMOS economics.
- Capacitive Sensors:These devices measure electrical field variations between ridge and valley patterns using CMOS-fabricated electrode arrays. Smartphone OEMs in Shenzhen-Dongguan corridor source capacitive modules in highest volume, though margin compression from optical alternatives is intensifying.
- Ultrasonic Sensors:Piezoelectric MEMS arrays transmit acoustic pulses through display glass to capture 3D fingerprint topology. Samsung and Chinese flagship OEMs are concentrating demand here for through-display authentication that penetrates moisture and contaminants.
- Optical Sensors:CMOS image sensors paired with LED illumination capture visible-light fingerprint patterns. Banking terminal manufacturers favor these for cost-sensitive deployments where display integration is unnecessary.
- Thermal Sensors:Pyroelectric materials detect temperature differential between ridges and valleys. Niche applications in outdoor access control systems drive limited procurement volumes.
- Piezoelectric Sensors:Pressure-sensitive polymers generate electrical signals from mechanical deformation. Wearable device makers are piloting these for flexible form factors.
Capacitive sensors absorb the bulk of installed capacity; ultrasonic sensors are expanding most quickly.
Technology:
Process maturity creates a technology hierarchy where CMOS and MEMS dominate production economics while emerging nanoimprint methods promise cost breakthroughs for large-area sensors.
- CMOS:Standard complementary metal-oxide-semiconductor fabrication enables high-density electrode arrays at foundry scale. Goodix and Synaptics leverage Taiwan and South Korea foundry partnerships to serve smartphone and notebook OEMs respectively.
- MEMS:Microelectromechanical systems processing integrates piezoelectric materials for ultrasonic transduction. Qualcomm and domestic Chinese vendors are concentrating R&D here for through-display authentication modules.
- AFIS:Automated fingerprint identification systems software processes minutiae templates for large-scale biometric databases. Government ID program contractors integrate AFIS-compliant algorithms for FBI and NIST certification.
- Thin Film Transistor:TFT backplanes enable flexible sensor substrates for curved and foldable devices. Panel manufacturers in Korea are piloting these for automotive interior applications.
- Nanoimprint:Mechanical patterning of polymer substrates reduces lithography costs for large-area sensors. Research-stage deployments target cost reduction in access control modules.
- Photolithography:Optical patterning of semiconductor layers defines electrode geometries in high-resolution sensors. Mature equipment ecosystems support this across all major foundry regions.
CMOS and MEMS together command dominant production volume; nanoimprint methods are climbing the fastest as flexible device demand accelerates.
Application:
End-use requirements fragment the market between consumer volume plays and high-margin certified segments with divergent qualification timelines.
- Smartphones:Under-display and button-integrated modules dominate unit shipments. Chinese OEMs are driving specification evolution toward ultrasonic and optical architectures as capacitive button designs phase out.
- Government ID Programs:FIPS 201 and similar compliance mandates sustain premium pricing for certified modules. US federal procurement cycles extend 18-24 months, freezing out unqualified vendors.
- Banking Terminals:PCI PTS compliance requirements shape sensor selection for payment authentication hardware. Indian financial institutions are expanding deployments following digital payment infrastructure buildout.
- Access Control Systems:Enterprise and residential security installations favor ruggedized outdoor-rated modules. European GDPR compliance elevates on-device template storage specifications.
- Time & Attendance:Workforce management systems integrate fingerprint sensors for payroll verification. Cost sensitivity here favors optical and capacitive alternatives over ultrasonic premium positioning.
- Automotive Security:In-vehicle biometric authentication for ignition and personalization is emerging. Tier-1 suppliers are qualifying sensors for AEC-Q100 automotive reliability standards.
Smartphone applications absorb dominant unit volume; Government ID Programs deliver steepest margin expansion.
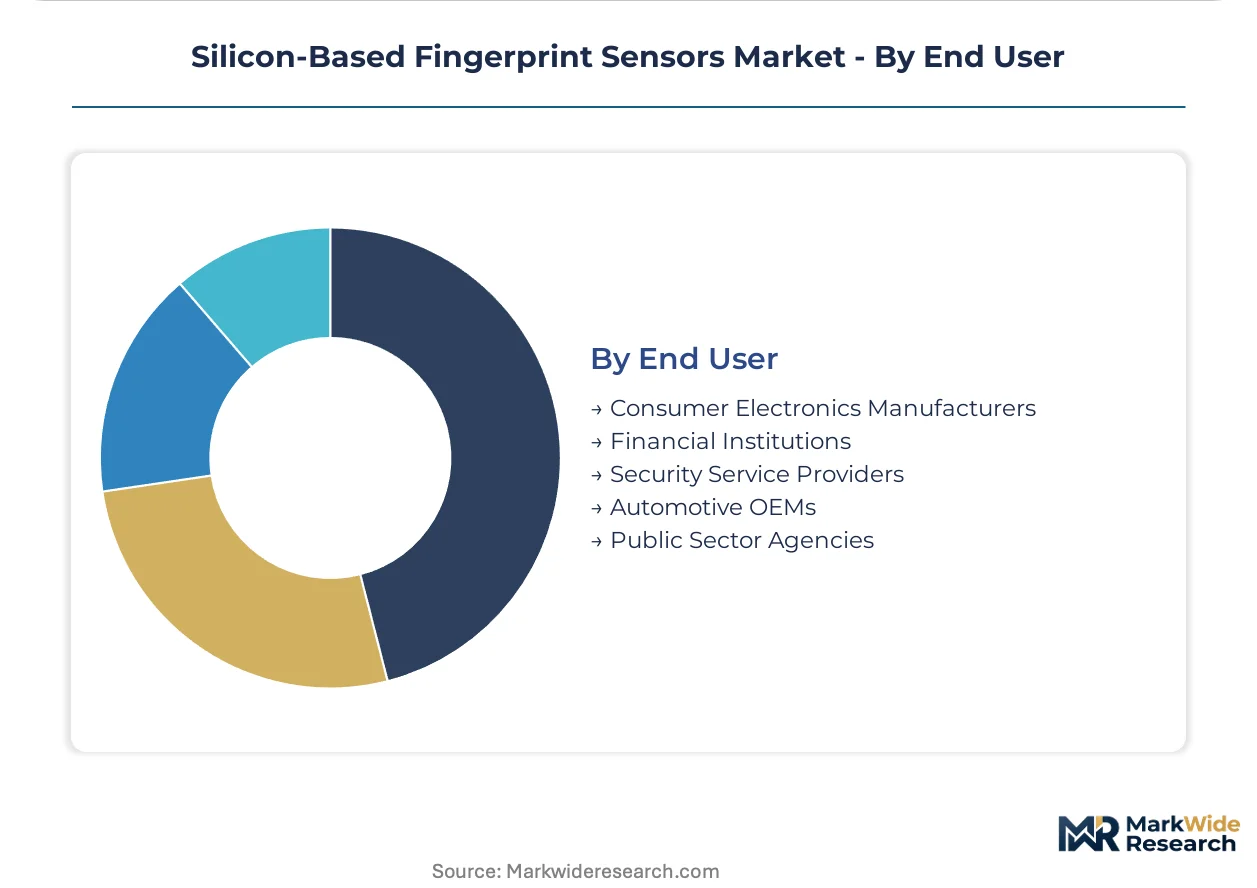
End User:
Customer concentration patterns split between consolidated electronics OEMs with component sourcing power and fragmented security integrators with specialized service requirements.
- Consumer Electronics Manufacturers:Smartphone and notebook OEMs drive 500-million-unit annual procurement scale. Dell, HP, and Lenovo enterprise divisions now unbundle Windows Hello module sourcing from full system contracts.
- Financial Institutions:Banks and payment processors specify biometric hardware for customer-facing terminals. India's RBI guidelines and Europe's PSD2 framework shape authentication architecture requirements.
- Security Service Providers:System integrators deploy access control and time-attendance solutions across commercial buildings. These customers prioritize firmware customization and API flexibility over hardware specifications.
- Automotive OEMs:Vehicle manufacturers are qualifying biometric modules for driver identification and cabin personalization. German and Japanese OEMs lead specification development for production integration.
- Public Sector Agencies:Government procurement offices enforce FIPS 201, FBI EBTS, and parallel national standards. China's MIIT certification pathways create protected access for domestic-aligned vendors.
Consumer electronics manufacturers concentrate highest unit demand; public sector agencies sustain premium pricing through certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the bulk of silicon-based fingerprint sensor module assembly, while the United States and Germany anchor premium-tier demand through federal certification programs. India's electronics manufacturing incentives are accelerating domestic production capacity.
China
Smartphone OEMs in the Shenzhen-Dongguan corridor drive dominant procurement volumes for under-display and ultrasonic sensor modules. MIIT's GB/T biometric standards create parallel certification pathways that domestic-aligned vendors navigate with regulatory preference. The Yangtze River Delta and Pearl River Delta manufacturing clusters compress integration costs fastest through concentrated module assembly activity.
United States
Federal ID program contractors sustain premium demand for FIPS 201-certified modules with extended qualification cycles. The FBI's Electronic Biometric Transmission Specification shapes product development requirements for vendors serving government procurement. Enterprise notebook buyers in North American corporate fleet programs now unbundle Windows Hello-compliant sensor sourcing from full system contracts.
India
PLI scheme incentives for electronics manufacturing are accelerating local sensor assembly capacity and reducing import dependency for smartphone OEMs. BIS compulsory registration orders for electronic components add compliance layers for imported silicon modules. Karnataka and Tamil Nadu electronics manufacturing zones are concentrating new module integration facilities.
Germany
Automotive OEMs are qualifying biometric modules for in-vehicle driver identification and cabin personalization systems. GDPR and eIDAS framework mandates elevate on-device template storage specifications for enterprise and consumer applications. Bavaria-based Tier-1 suppliers lead specification development for AEC-Q100 automotive reliability standards.
South Korea
Advanced CMOS foundries in Taiwan and South Korea control fabrication capacity for high-density sensor electrode arrays. Samsung's adoption of ultrasonic through-display authentication concentrates flagship-tier demand for piezoelectric MEMS modules. Seoul Capital Area semiconductor clusters anchor process development for flexible OLED-convergent sensor architectures.
Silicon-Based Fingerprint Sensors Market Key Industry Players
Top-tier vendors anchor federal certification and flagship smartphone supply, while mid-tier specialists compete on cost and customization velocity. The vendor base stratifies across CMOS heritage fabricators, MEMS acoustic specialists, and algorithm-software integrators. Archetypes include foundry-dependent scale players, ultra-low-power architecture specialists, and government ID program certification holders. Competitive moves center on MEMS-CMOS process integration partnerships and subscription firmware service models that extend customer lifetime value.
Within the CMOS heritage tier, Goodix Technology Co., Ltd. and Synaptics Incorporated exemplify divergent positioning strategies. Goodix occupies a scale-driven position serving mid-tier smartphone OEMs through Taiwan foundry partnerships. Synaptics anchors enterprise notebook procurement channels through Windows Hello compliance integration. Fingerprint Cards AB represents the ultra-low-power specialist archetype addressing battery-constrained IoT authentication demand.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Goodix Technology Co., Ltd. |
| Fingerprint Cards AB |
| Egis Technology Inc. |
| IDEX Biometrics ASA |
| NEXT Biometrics Group ASA |
| Qualcomm Incorporated |
| Sony Corporation |
| Infineon Technologies AG |
| Others |
Cost & Logistics Intelligence
Federal certification tiers bifurcate silicon-based fingerprint sensors into premium FIPS 201-compliant modules and commodity smartphone-grade alternatives, with this divergence manifesting in both pricing power and foundry sourcing strategies. Vendors serving US federal procurement pools command sustained premiums through 18-24 month qualification timelines, while Shenzhen-Dongguan corridor assemblers compress capacitive sensor margins through concentrated module integration activity.
Pricing Analysis
Margin tightening in smartphone-grade capacitive modules reflects optical under-display alternatives displacing button-integrated architectures across Chinese OEM portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 201-certified government ID modules from Windows Hello-compliant notebook components and unbranded access control alternatives. Cost-down pressure on mid-tier ultrasonic sensors accelerates because Samsung and domestic Chinese flagship makers concentrate procurement scale with Qualcomm and Goodix respectively. Banking terminal manufacturers exhibit highest price sensitivity, prioritizing PCI PTS compliance at minimum unit cost, while federal contractors absorb premium positioning for certified template storage architectures.
Supply Chain Analysis
MEMS acoustic engineering talent scarcity in Taiwan, South Korea, and China's Yangtze River Delta constrains ultrasonic sensor foundry expansion despite flagship OEM demand. Silicon wafer supply draws from TSMC and Samsung Foundry CMOS lines for capacitive electrode arrays, while Qualcomm's piezoelectric MEMS partnerships anchor ultrasonic transduction capacity. Single-source vulnerability concentrates in 300mm wafer fabrication, where geopolitical disruption would cascade through smartphone and federal procurement pipelines. Distribution runs through Shenzhen module integrators for consumer electronics, direct component tenders for enterprise notebook OEMs, and specialized security distributors for government ID program contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum in silicon-based fingerprint sensors centers on MEMS-CMOS process convergence, with vendors racing to capture rare cross-domain engineering capabilities that ultrasonic architectures demand.
For Market Incumbents: Deploy subscription firmware services to reposition vendor-OEM relationships beyond hardware shipment economics. Defensive consolidation requires deepening Taiwan and South Korea foundry partnerships against supply disruption, while accelerating dual certification tracks for GB/T and NIST frameworks to protect government ID program access. Optical under-display alternatives from display panel vendors threaten ultrasonic premium positioning in mid-tier smartphones. For New Entrants and Emerging Players: Direct-to-security-integrator channels bypass consolidated electronics OEM procurement power and enable firmware customization revenue. Battery-constrained IoT authentication in smart locks and payment terminals offers most penetrable white-space, with ultra-low-power architecture specialization as the viable go-to-market angle against Goodix and Synaptics scale advantages. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS acoustic specialists given Samsung and Chinese flagship OEM adoption of through-display authentication. Long-term viability over a 5-10 year window favors vendors with captive piezoelectric process development or exclusive foundry partnerships. Watch NIST minutiae standard revision timelines as inflection indicator for banking and border-control procurement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS-CMOS Process Integration Partnership | Qualcomm's piezoelectric foundry alliances enable ultrasonic through-display authentication for Samsung flagships. |
| Dual Certification Track Investment | Parallel GB/T and FIPS 201 compliance protects vendor access to both Chinese government and US federal procurement pools. |
| Subscription Firmware Service Launch | Recurring authentication algorithm updates extend customer lifetime value beyond discrete hardware shipment economics. |
| Ultra-Low-Power Architecture Development | Fingerprint Cards AB's battery-optimized designs address untapped smart lock and wearable device demand. |
| Direct Security Integrator Channel | Unmediated relationships with access control and time-attendance system builders bypass OEM procurement compression. |
Research Approach
Independent corroboration across sensor module procurement managers, biometric algorithm engineers, and federal compliance officers underwrites the qualitative findings in this study. Primary interviews with Taiwan foundry planning executives, Shenzhen-Dongguan integration facility directors, and Windows Hello program managers combined with secondary validation from SEC 10-K filings, MIIT standardization committee disclosures, and NIST biometric testing reports. Bottom-up shipment estimates from module integrators triangulate against top-down OEM bill-of-materials analysis.
Comparable-period anchoring to historical smartphone biometric adoption curves and federal ID program deployment cycles shapes the projection horizon across the analysis window. Segmentation modeling spans sensor modality, fabrication process, application tier, and end-user concentration patterns. CAGRs derive from foundry capacity expansion announcements, OEM product roadmap disclosures, and certification timeline trajectories. Industry-specific forecast inputs include PLI scheme incentive disbursement rates and GB/T standard revision schedules.
The model holds under stable Taiwan-South Korea foundry relations and continued ultrasonic flagship adoption; deviation in geopolitical supply access or optical sensor cost breakthroughs would shift trajectory. Forecasts reflect documented assumptions regarding MEMS process yield maturation and federal procurement cycle continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
US Smart Air Purifier Market