
 Depth Sensing Market | 2026-2036
Depth Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Depth Sensing Market Intelligence
Silicon photonics is consolidating as the dominant substrate for time-of-flight receivers, displacing legacy CMOS-only architectures in high-precision modules. Texas Instruments leverages its analog foundry scale to anchor supply for automotive-grade depth processors. Sony Group Corporation dominates image sensor supply for structured light and stereo vision systems. Qualcomm Incorporated positions its Snapdragon depth perception IP across mobile and extended reality deployment channels.
Depth sensing measures three-dimensional spatial relationships between a sensor and target surfaces using emitted energy patterns and return signal analysis, typically operating at wavelengths from 850 nm to 1550 nm for eye-safe industrial and consumer applications. Time of flight leads volume shipments in mobile device deployment, while LiDAR captures the fastest expansion trajectory driven by automotive Tier-1 supplier qualification programs. Stereo vision remains the most mature architecture with compressed margins, whereas ultrasonic sensing occupies niche wearable device applications where power budgets are severely constrained.
FCC Part 15 laser product regulations govern emitter safety certification for US consumer electronics deployment, while the EU AI Act and GDPR impose strict biometric data governance on gesture recognition and security surveillance applications. China's MIIT enforces GB standards for depth camera modules in smart city infrastructure. Stakeholders must monitor evolving laser exposure thresholds and biometric consent frameworks as these determine market access velocity for next-generation deployment categories.
Market Dynamics
Solid-state LiDAR arrays are consolidating supply relationships around automotive Tier-1 qualification programs, compressing development cycles and displacing mechanical scanning architectures in production vehicle designs. This substrate transition is redrawing competitive boundaries between silicon photonics foundries and legacy CMOS sensor houses.
Growth Catalysts
- EU AI Act biometric governance:Mandatory consent frameworks for depth-based gesture recognition are creating certified-module demand premiums in security and access control installations across Germany, France, and the Netherlands.
- Automotive solid-state LiDAR adoption:Stuttgart and Munich sensor clusters are anchoring qualification programs that lock in multi-year supply commitments for time-of-flight receiver arrays.
- Silicon photonics substrate migration:Eye-safe 1550 nm emitter integration is unifying emitter and receiver fabrication onto single-chip architectures, collapsing module assembly complexity.
Market Restraints
- Indium phosphide supply concentration:III-V compound semiconductor foundry capacity concentrates in East Asian contract manufacturers, exposing automotive qualification timelines to input volatility.
- FCC Part 15 laser safety certification:US consumer electronics deployment faces extended emitter testing protocols that compress margin structures for high-volume mobile device integrations.
- Stereo vision margin compression:Mature dual-camera architectures face displacement pressure from time-of-flight miniaturization, eroding revenue per unit in security surveillance retrofit markets.
Strategic Opportunities
- China smart city infrastructure:MIIT GB standards enforcement is mandating depth camera module deployment in urban traffic management and pedestrian safety systems across tier-one municipalities.
- Extended reality convergence:Hand tracking and spatial mapping applications are unifying structured light and time-of-flight architectures in next-generation headset reference designs.
- Japan METI industrial automation incentives:Subsidized robot vision upgrades are accelerating adoption of high-precision depth sensing in manufacturing quality inspection lines.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FCC, CE marking, and MIIT compliance for laser emitters extends product launch windows by 12-18 months.
- Silicon photonics talent scarcity:Foundry process engineering expertise for integrated photonic-electronic design concentrates in a handful of academic and corporate laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depth Sensing Market |
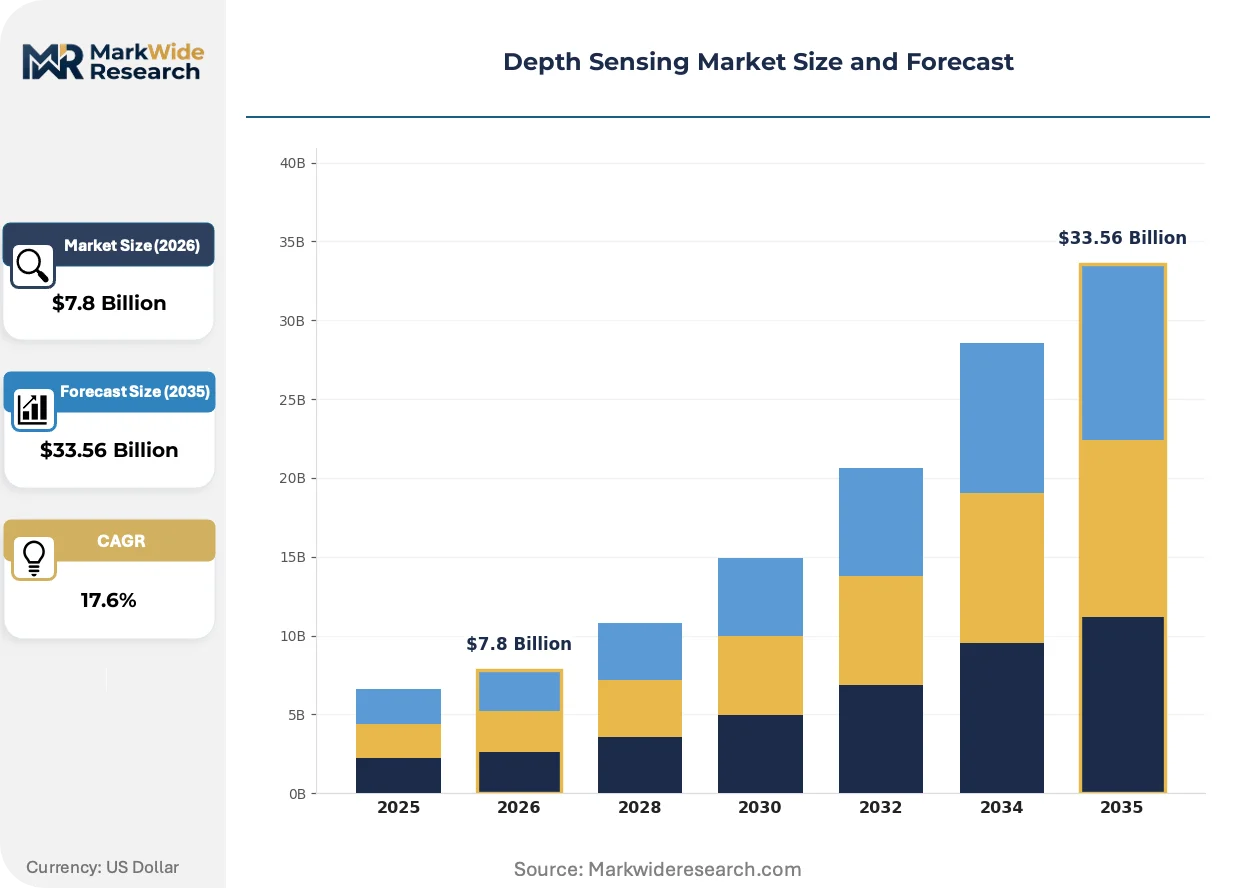
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Time of Flight, Structured Light, Stereo Vision, LiDAR, Ultrasonic, Photometric Stereo Application: Augmented Reality, Robotics, Gesture Recognition, Security Surveillance, Industrial Automation, 3D Mapping End User: Consumer Electronics, Manufacturing Units, Defense Agencies, Research Institutes, Entertainment Studios, Automotive Tier-1 Suppliers Deployment: Mobile Devices, Wearable Devices, Fixed Installations, Drones, Smart Cameras, Automotive Sensors |
| Companies Covered | Texas Instruments Incorporated, Lattice Semiconductor Corporation, Sony Group Corporation, Himax Technologies, Inc., OmniVision Technologies, Inc., STMicroelectronics N.V., ams AG, Qualcomm Incorporated, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depth Sensing Market Strategic Shifts & Innovations
Silicon photonics is collapsing the traditional separation between emitter and receiver supply chains, enabling single-foundry production of complete depth modules. This integration is compressing cost structures while tightening quality control loops for automotive safety applications.
Monolithic integration of vertical-cavity surface-emitting lasers with silicon photonics waveguides is unifying emitter and detection functions onto single substrates. Automotive Tier-1 suppliers in Germany are accelerating adoption for solid-state LiDAR production programs. This unification is eliminating hybrid packaging steps that previously dominated module cost and failure rates.
GDPR Article 9 biometric data restrictions are forcing explicit consent architectures into depth-enabled security and retail analytics deployments. EU member state data protection authorities are enforcing purpose limitation on gesture recognition data streams. Surveillance and access control vendors are responding with edge-processing designs that eliminate cloud transmission of raw depth maps.
Automotive OEMs are consolidating sensor procurement around qualified Tier-1 module suppliers rather than direct component sourcing. This concentration is displacing open-market spot purchasing for time-of-flight receivers and structured light projectors. The shift is most visible in German and South Korean vehicle programs where functional safety certification requirements dominate supplier selection criteria.
Depth Sensing Market Segmentation
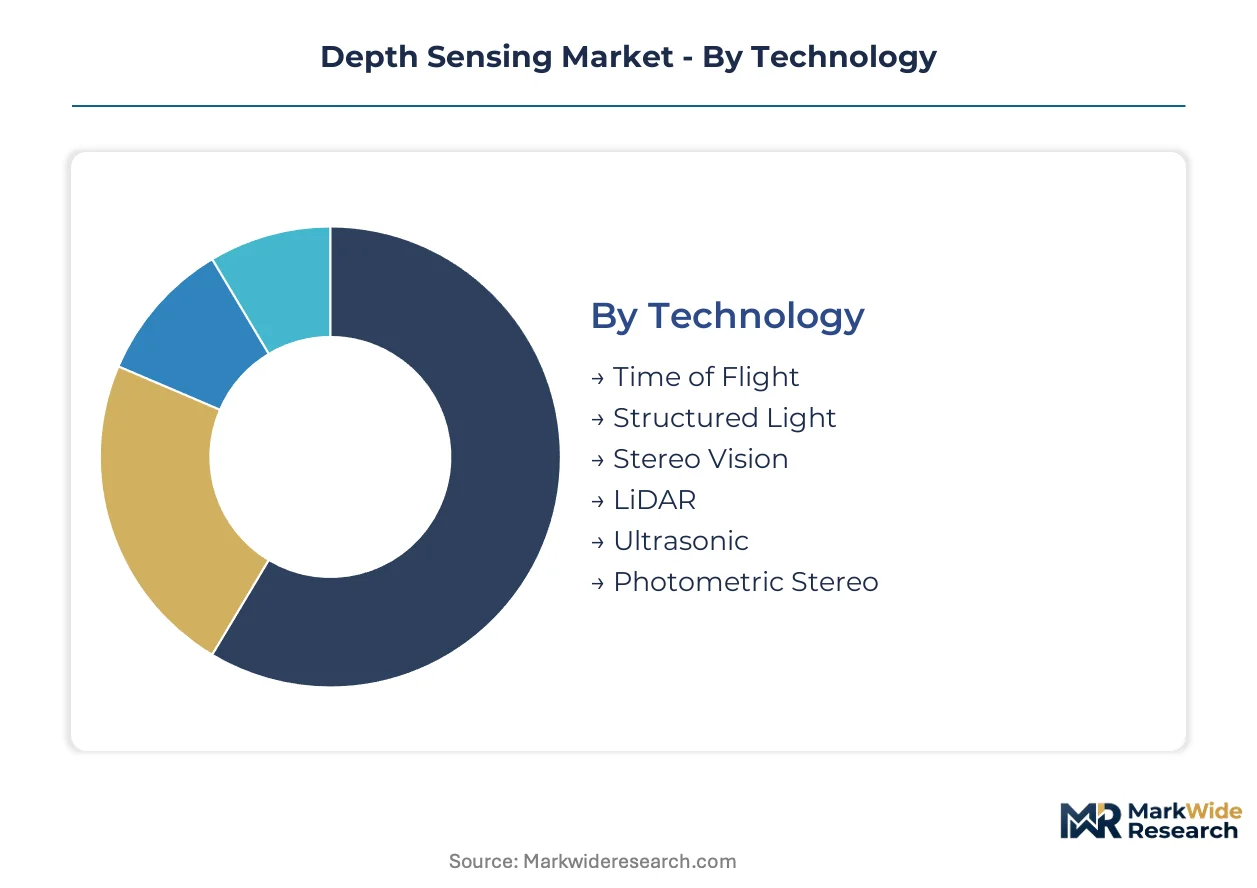
Technology architecture determines module cost, precision range, and certification pathway across depth sensing deployments. Application context shapes wavelength selection and safety classification requirements. End-user procurement patterns concentrate volume in automotive and consumer electronics channels while fragmenting across specialized industrial segments.
Technology:
Standardization dominates emitter-receiver integration, while customization persists in wavelength selection and safety classification tiers.
- Time of Flight:Measures distance via phase-shift or direct pulse timing between emitter and sensor, typically employing 850 nm or 940 nm vertical-cavity surface-emitting lasers. Mobile device manufacturers in Germany and South Korea anchor volume demand as slim module profiles displace structured light in flagship smartphone depth cameras.
- LiDAR:Deploys scanning or solid-state laser arrays for medium-to-long-range spatial mapping, with 1550 nm emitters gaining automotive traction for eye-safe operation at extended distances. Stuttgart and Munich automotive sensor clusters are locking in multi-year supply commitments for solid-state arrays as Tier-1 qualification programs accelerate.
- Stereo Vision:Dual-camera triangulation architecture with mature algorithm stacks and compressed hardware margins.
- Structured Light:Pattern projection systems dominant in facial authentication and industrial metrology applications.
- Ultrasonic:Low-power proximity detection for severely constrained wearable power budgets.
- Photometric Stereo:Surface normal reconstruction from multi-angle illumination for precision manufacturing inspection.
Leading the category by volume: Time of Flight. Expanding most quickly: LiDAR.
Application:
Volume concentrates in consumer-facing interfaces, while margin pools in safety-critical and industrial precision workflows.
- Augmented Reality:Hand tracking and spatial mapping unify structured light and time-of-flight architectures in next-generation headset reference designs. Extended reality OEMs in California and Taiwan are consolidating sensor procurement around qualified module suppliers.
- Industrial Automation:Robot vision and quality inspection lines deploy high-precision depth sensing under Japan METI subsidy programs. Manufacturing quality inspection in Osaka and Nagoya automotive supplier parks is driving adoption of photometric stereo and time-of-flight hybrid systems.
- Gesture Recognition:EU AI Act biometric consent frameworks are creating certified-module demand premiums in security and access control.
- Security Surveillance:GDPR Article 9 restrictions are forcing edge-processing designs that eliminate cloud transmission of raw depth maps.
- Robotics:Navigation and manipulation systems require real-time point cloud generation at varying ranges.
- 3D Mapping:Urban infrastructure and construction survey applications drive demand for long-range LiDAR modules.
Highest volume application: Gesture Recognition in consumer devices. Steepest expansion trajectory: Industrial Automation.
End User:
Procurement scale separates commodity volume buyers from specialized qualification-driven customers.
- Consumer Electronics:Smartphone, tablet, and peripheral OEMs drive annual volume in the hundreds of millions of units. South Korean and Chinese mobile device manufacturers are consolidating sensor procurement around qualified module suppliers for flagship depth camera integration.
- Automotive Tier-1 Suppliers:Functional safety certification requirements dominate supplier selection criteria in German and South Korean vehicle programs. Stuttgart-based sensor clusters are anchoring qualification programs that lock in multi-year supply commitments for time-of-flight receiver arrays.
- Manufacturing Units:Quality inspection and robot vision upgrades under subsidy programs in Japan and Germany.
- Defense Agencies:Classified requirements for long-range sensing and counter-UAS applications.
- Research Institutes:Custom specifications for experimental robotics and spatial computing platforms.
- Entertainment Studios:Volumetric capture and virtual production stage deployments.
Dominant procurement volume: Consumer Electronics. Fastest-growing customer segment: Automotive Tier-1 Suppliers.
Deployment:
Form factor constraints separate mobile integration challenges from fixed installation flexibility.
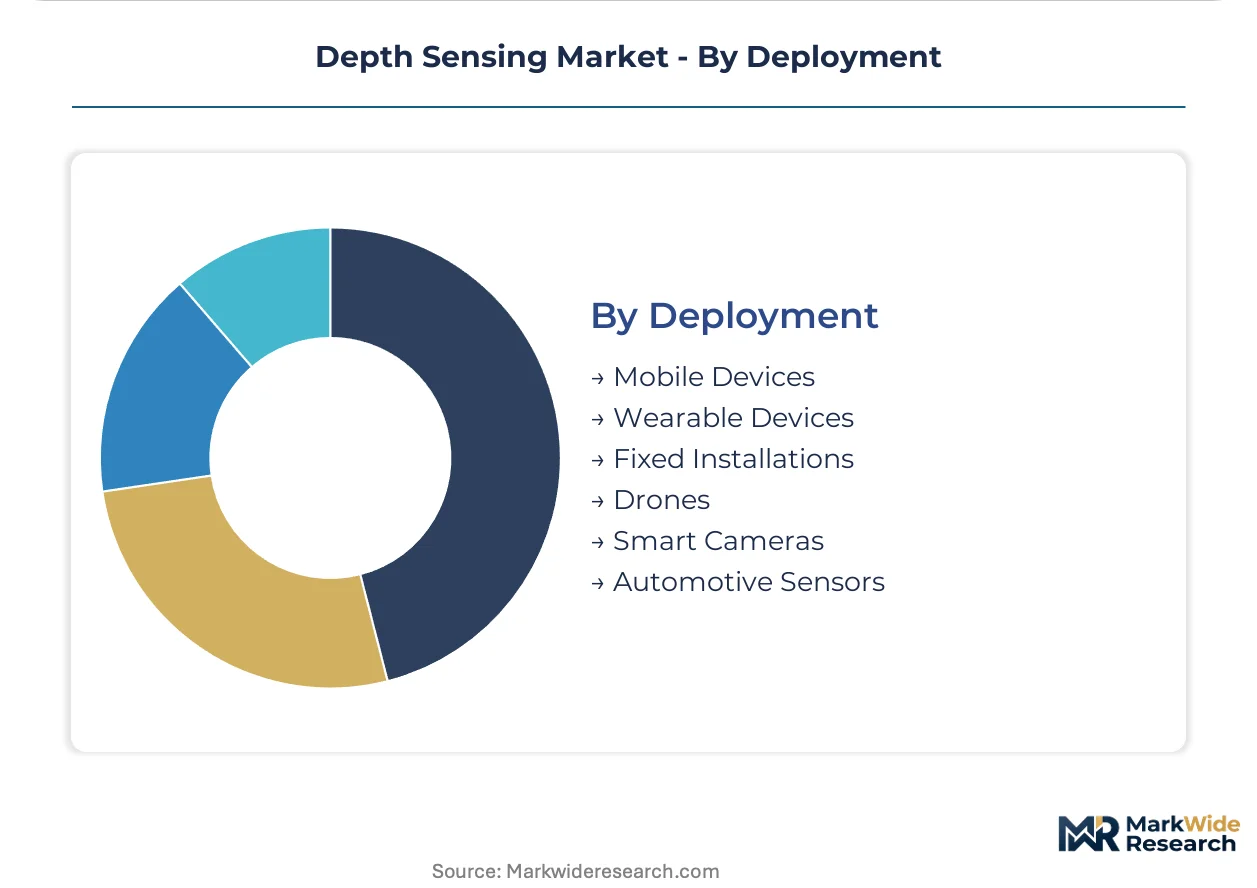
- Mobile Devices:Slim module profiles and FCC Part 15 laser safety certification compress margin structures for high-volume integrations. Extended emitter testing protocols in US consumer electronics deployment extend product launch windows.
- Automotive Sensors:Solid-state LiDAR arrays are displacing mechanical scanning architectures in production vehicle designs. German automotive OEMs are consolidating sensor procurement around qualified Tier-1 module suppliers rather than direct component sourcing.
- Wearable Devices:Severe power budgets favor ultrasonic and low-power time-of-flight miniaturization.
- Fixed Installations:Security and access control systems face EU AI Act biometric governance requirements.
- Drones:Obstacle avoidance and precision landing systems require lightweight, shock-resistant modules.
- Smart Cameras:Edge-processing depth analytics for retail and urban traffic management under China MIIT GB standards.
Highest shipment volume: Mobile Devices. Fastest expansion: Automotive Sensors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and Singapore are concentrating photonics foundry investment. Stuttgart's automotive sensor cluster anchors European qualification programs. Government subsidies in Japan and Germany are accelerating industrial automation deployment.
United States
FCC Part 15 laser safety certification governs consumer electronics deployment, extending emitter testing protocols for mobile device integrations. Silicon Valley and Austin semiconductor design houses are consolidating around automotive LiDAR reference architectures. California-based extended reality OEMs are locking in multi-year supply commitments for time-of-flight receiver arrays.
Germany
EU AI Act biometric consent frameworks are creating certified-module demand premiums in security installations. KBA functional safety requirements dominate automotive Tier-1 supplier selection criteria. Stuttgart and Munich sensor clusters are anchoring solid-state LiDAR qualification programs with multi-year supply commitments for production vehicle designs.
China
MIIT GB standards enforcement mandates depth camera module deployment in smart city infrastructure across tier-one municipalities. Yangtze River Delta free-trade zones are concentrating silicon photonics foundry capacity. Shenzhen-based mobile device manufacturers are consolidating sensor procurement around qualified module suppliers for flagship depth camera integration.
Japan
METI industrial automation subsidies are accelerating robot vision upgrades in manufacturing quality inspection lines. JIS standards govern precision measurement equipment certification. Osaka and Nagoya automotive supplier parks are driving adoption of photometric stereo and time-of-flight hybrid systems under subsidized upgrade programs.
South Korea
MFDS medical device regulations intersect with depth-enabled surgical navigation systems in Seoul hospital networks. Seoul Capital Area electronics conglomerates are consolidating sensor procurement for flagship smartphone depth camera integration. Busan-Ulsan shipbuilding clusters are exploring LiDAR-based precision welding guidance systems.
Depth Sensing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The supplier base concentrates around analog foundry scale and image sensor fabrication expertise. Three archetypes dominate: silicon photonics foundries with integrated emitter-receiver capability, analog semiconductor houses with automotive-grade certification depth, and image sensor specialists with structured light and stereo vision portfolios. Competitive moves center on Tier-1 automotive qualification lock-ins and silicon photonics talent acquisition from academic laboratories.
Within the analog foundry tier, Texas Instruments Incorporated and Infineon Technologies AG exemplify scale-driven supply anchoring for automotive-grade depth processors. Sony Group Corporation occupies a position representing image sensor dominance across structured light and stereo vision architectures. Qualcomm Incorporated sits within the mobile-extended reality convergence vector, positioning depth perception IP across Snapdragon deployment channels.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Lattice Semiconductor Corporation |
| Sony Group Corporation |
| Himax Technologies, Inc. |
| OmniVision Technologies, Inc. |
| STMicroelectronics N.V. |
| ams AG |
| Qualcomm Incorporated |
| Infineon Technologies AG |
| Others |
Cost & Logistics Intelligence
Automotive Tier-1 qualification programs in Germany and South Korea are compressing supplier selection timelines and forcing foundries to prioritize certified capacity over spot-market flexibility, which props pricing premiums for qualified silicon photonics modules while eroding margins on uncertified legacy architectures.
Pricing Analysis
Short-lead-time premiums dominate contract negotiations as automotive OEMs lock in multi-year supply commitments ahead of production ramp schedules. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates qualified Tier-1 supply from spot-market components. Pricing pressure stems from FCC Part 15 laser safety certification extending testing protocols for US consumer electronics deployment. Consumer electronics OEMs exhibit highest price sensitivity due to compressed margin structures in high-volume mobile device integrations, while automotive Tier-1 suppliers accept premium pricing for functional safety certification depth.
Supply Chain Analysis
ISO 26262 functional safety certification and KBA automotive approval requirements gate supply relationships, concentrating qualified foundry capacity among analog semiconductor houses with automotive-grade process expertise. Manufacturing concentrates in Taiwan, South Korea, and Germany, with III-V compound semiconductor foundry capacity tethered to East Asian contract manufacturers for indium phosphide emitter fabrication. Raw material dependencies span silicon-on-insulator wafers, vertical-cavity surface-emitting laser epitaxy, and precision optical packaging substrates. Single-source vulnerability in III-V compound foundry capacity exposes automotive qualification timelines to input volatility. Distribution runs through qualified Tier-1 module suppliers rather than open-market component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics foundry capacity scarcity props pricing power for qualified suppliers, with automotive Tier-1 qualification timelines extending 18-24 months and locking out unqualified competitors from premium contract pools.
For Market Incumbents: Lock in multi-year supply commitments with Stuttgart and Munich automotive sensor clusters before competitor qualification programs mature. Deepen captive supply of vertical-cavity surface-emitting laser epitaxy capacity to offset III-V foundry concentration risk. Accelerate monolithic integration roadmaps to collapse hybrid packaging costs and defend margin position against emerging silicon photonics specialists. For New Entrants and Emerging Players: Begin with China smart city infrastructure deployments under MIIT GB standards enforcement, where certification requirements remain less stringent than automotive Tier-1 programs. Target tier-one municipal traffic management systems in the Yangtze River Delta for initial volume traction. Pursue partnership-based go-to-market models with Shenzhen-based module integrators to bypass direct automotive qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with silicon photonics foundries possessing integrated emitter-receiver capability given automotive solid-state LiDAR adoption acceleration. Long-term viability hinges on qualification depth rather than scale alone across the projection horizon. Target acquisition archetypes combine academic laboratory talent pipelines with existing Tier-1 automotive relationships. Watch for inflection in German KBA approval velocity as signal for competitive position shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Tier-1 Qualification Lock-in | Secures multi-year supply commitments from Stuttgart OEMs ahead of competitor certification cycles. |
| Silicon Photonics Talent Acquisition | Captures scarce foundry process engineering expertise from academic laboratories in Taiwan and Germany. |
| Monolithic Integration Roadmap Acceleration | Collapses hybrid packaging costs for VCSEL-silicon photonics unification in solid-state LiDAR modules. |
| China Smart City Partnership Formation | Establishes volume foothold in MIIT-mandated depth camera deployments across tier-one municipalities. |
| Edge-Processing Architecture Development | Addresses GDPR Article 9 biometric data restrictions in EU security surveillance installations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with automotive Tier-1 procurement directors, silicon photonics foundry process engineers, depth camera module integrators, and EU data protection compliance officers. SEC 10-K disclosures, MIIT GB standard certification databases, KBA functional safety approval registers, and EU AI Act implementation guidance documents provided validation layers. Bottom-up module shipment estimates triangulated against top-down automotive production and consumer electronics device forecasts.
Data-stream reconciliation across technology architecture, application vertical, end-user procurement scale, and deployment form factor dimensions shaped the analytical framework over the projection horizon. CAGRs derived from weighted average of historical qualification cycle durations, substrate transition adoption curves, and regulatory enforcement timelines. Forecast inputs incorporated automotive Tier-1 supplier consolidation patterns and silicon photonics foundry capacity expansion announcements.
Underlying measurement precision varies by segment; automotive solid-state LiDAR and mobile time-of-flight carry tighter precision than emerging photometric stereo industrial applications. Forecasts reflect assumptions regarding certification timeline stability and substrate migration velocity. A model refresh is warranted upon material change in EU AI Act biometric consent enforcement intensity or III-V compound semiconductor foundry capacity allocation policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Global RFID Sensor Market