
 Fluid Sensors Market | 2026-2036
Fluid Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Sensors Market Intelligence
The capital-intensity divergence between custom-fabricated MEMS foundries and standard CMOS houses is unwinding competitive stability across fluid sensing. Endress+Hauser AG leverages its captive Swissmetrology-certified calibration network to dominate precision chemical applications. Siemens AG anchors its position through deep backward integration into industrial automation software stacks. Emerson Electric Co competes on field-hardened packaging for oilfield services, where thermal cycling resistance commands premium positioning.
Fluid sensors are electromechanical transducers that measure physical properties of liquids and gases—including flow rate, pressure, temperature, level, and composition—typically operating across ranges from microliters per minute in pharmaceutical dosing to thousands of cubic meters per hour in municipal water systems. Their primary purpose is enabling closed-loop process control, safety interlocks, and regulatory compliance in continuous manufacturing and infrastructure operations. Capacitive and Coriolis product types capture the deepest margin pools in custody-transfer applications where calibration traceability determines contract validity. Microelectromechanical Systems technology leads unit volume through silicon wafer-scale fabrication, though piezoelectric architectures sustain pricing power in high-temperature chemical processing above 200°C. Water treatment and pharmaceutical end-user segments concentrate demand for multi-parameter optical sensors with embedded self-diagnostic protocols.
The EPA enforces Safe Drinking Water Act amendments that mandate continuous lead monitoring, directly expanding the installed base of real-time optical and electrochemical sensors in US municipal networks. FDA 21 CFR Part 11 and EU MDR compliance requirements force pharmaceutical companies toward validated thermal mass flow sensors with immutable data logging. ISO 5167 and IEC 61508 functional safety standards shape product architecture decisions for process manufacturers integrating sensors into safety instrumented systems. Stakeholders must weigh the capital trade-off between retrofitting legacy 4-20mA analog loops against migrating to IO-Link and Ethernet-APL digital infrastructures.
Market Dynamics
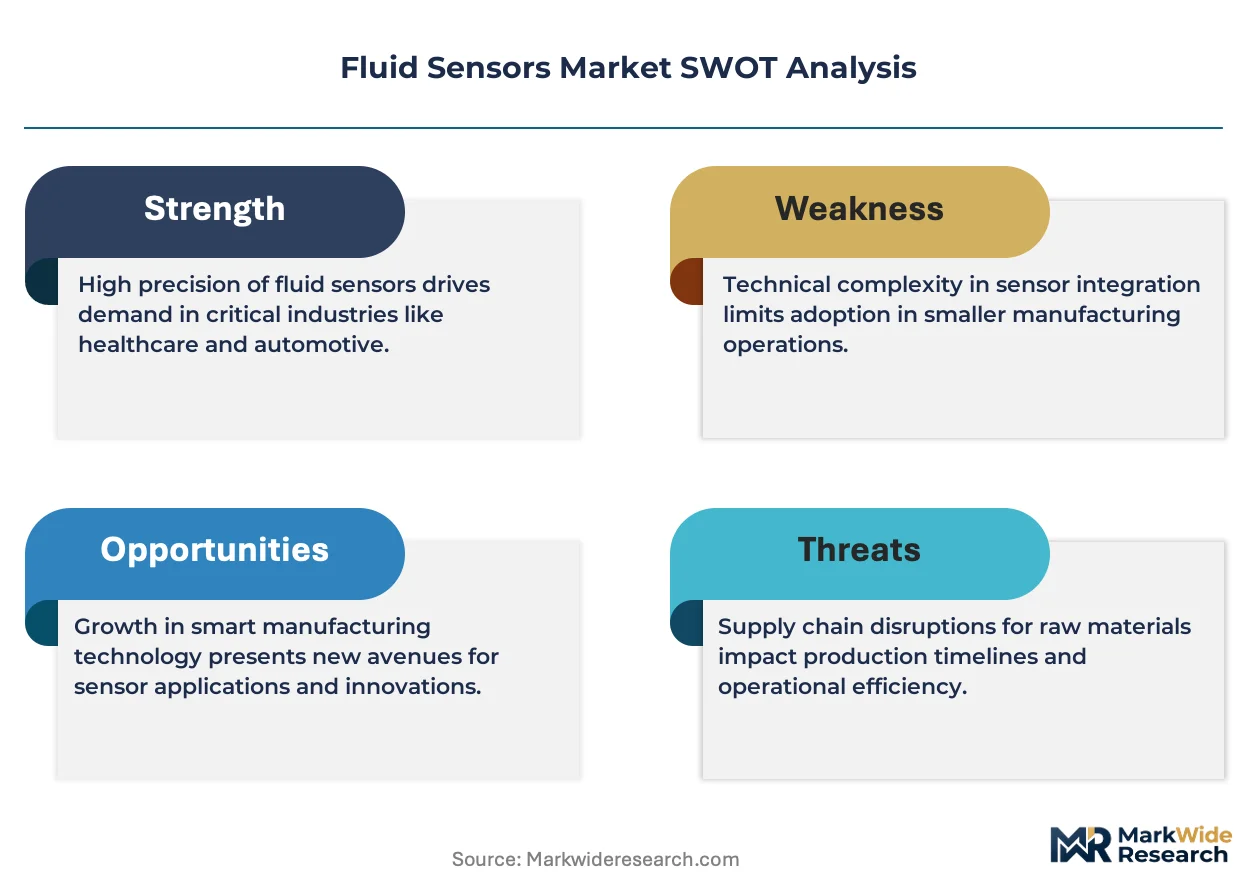
Silicon photonics packaging costs are collapsing the traditional price floor for optical fluid sensors, forcing electrochemical incumbents to defend installed base through calibration-lock-in strategies rather than hardware margins.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Continuous monitoring mandates in US municipal water networks are expanding real-time sensor deployment beyond treatment plants into distribution infrastructure.
- Pharmaceutical continuous manufacturing:FDA 21 CFR Part 11 validation requirements for thermal mass flow sensors are accelerating replacement of batch-era instrumentation across US and EU drug production facilities.
- German industrial automation corridor:Concentrated demand from chemical process OEMs in the Rhine-Ruhr region is pulling multi-parameter Coriolis sensors into standardized skid designs.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea dominate 300mm silicon wafer capacity for microfluidic sensors, creating single-source vulnerability for European and North American sensor houses.
- Piezoelectric ceramic supply:High-purity lead zirconate titanate for high-temperature pressure transducers faces price volatility from Chinese rare earth export licensing.
- Calibration infrastructure scarcity:Swissmetrology-certified flow laboratories number under fifty worldwide, limiting custody-transfer sensor deployment in emerging markets.
Strategic Opportunities
- India water infrastructure:Central government Smart Cities Mission funding for non-revenue water reduction is opening municipal procurement to optical leak detection sensors previously cost-prohibitive at Indian price points.
- Bioprocessing single-use convergence:Gamma-sterilizable disposable flow sensors are capturing share from stainless steel instrumentation in cell therapy manufacturing.
- EU F-Gas Regulation phase-down:Refrigerant leak detection mandates for commercial HVAC are creating new demand for infrared absorption sensors in building automation channels.
Industry Challenges
- Embedded firmware security certification:IEC 62443 cybersecurity standards for industrial automation are extending product development timelines by 8-14 months for sensor vendors without established security engineering functions.
- 4-20mA to IO-Link migration:Field retrofit complexity in brownfield process plants is slowing digital infrastructure adoption despite Ethernet-APL physical layer availability.
- Multi-physics simulation talent:Coupled fluid-structure-electromagnetic modeling for MEMS design requires scarce computational physics expertise concentrated in Swiss and German academic institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Sensors Market |
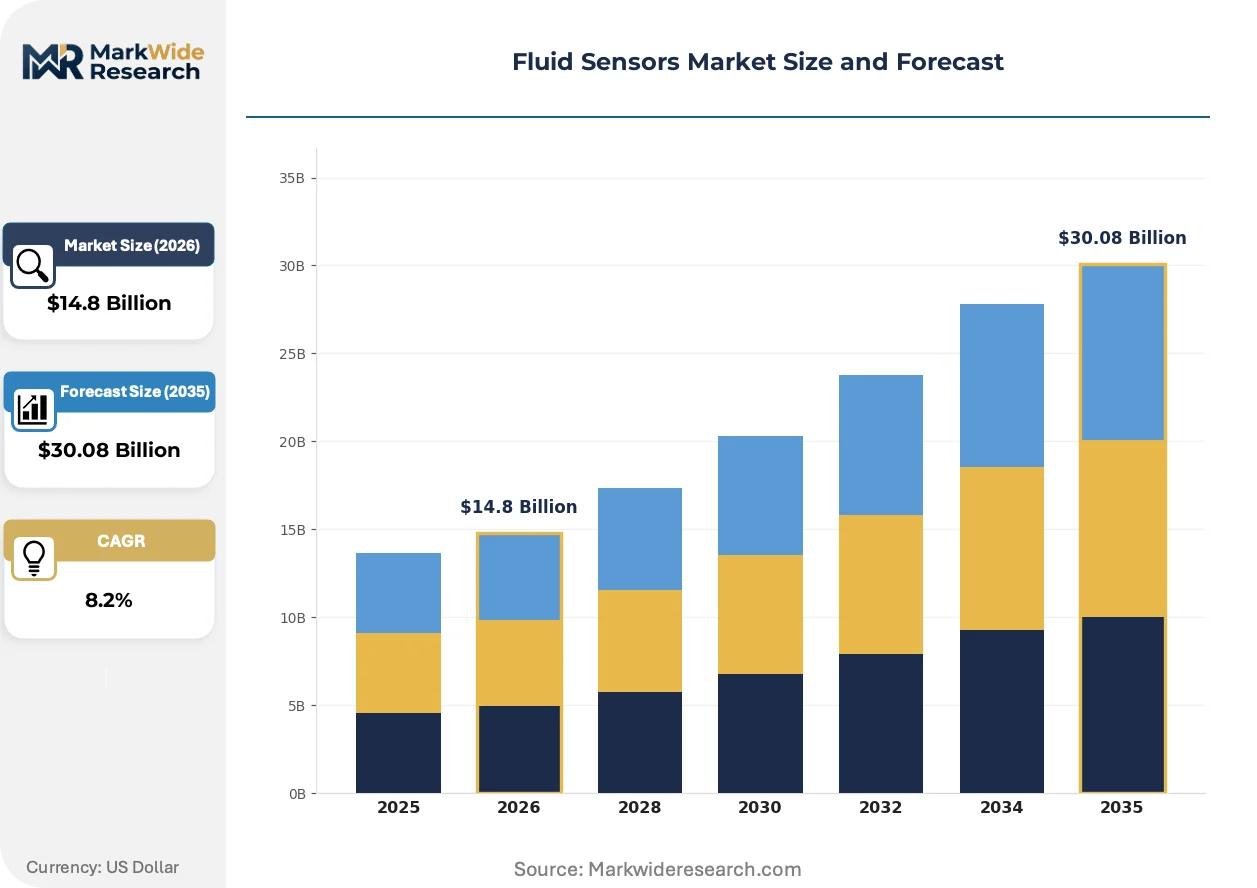
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.08 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Ultrasonic, Thermal, Optical, Coriolis, Mass Flow Technology: Microelectromechanical Systems, Piezoelectric, Electromagnetic, Thermal Dispersion, Resonant Frequency Application: Water Treatment, Chemical Processing, HVAC Systems, Automotive Systems, Food & Beverage, Oilfield Services End User: Process Manufacturers, Research Laboratories, Equipment OEMs, Power Generation Facilities, Pharmaceutical Companies |
| Companies Covered | Endress+Hauser AG, ABB Ltd, Siemens AG, Emerson Electric Co, Honeywell International Inc, Schneider Electric SE, SICK AG, NXP Semiconductors N.V., TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Sensors Market Strategic Shifts & Innovations
Packaging architectures and signal processing methods are converging to collapse the cost-performance trade-off that historically separated laboratory-grade from field-deployable fluid sensing.
Photonic integrated circuits for refractive index measurement are supplanting benchtop laboratory refractometers in pharmaceutical quality control. Biologics manufacturers in Massachusetts and Basel are adopting chip-scale devices at pilot-scale deployment. This shift is compressing the addressable market for traditional optical instrument houses while opening sensor-as-a-service revenue models.
EU MDR Annex I general safety and performance requirements are mandating validated data integrity for fluid sensors used in critical care medical devices. German and Irish contract manufacturers are restructuring quality management systems to accommodate immutable audit trails. Hemodialysis machine OEMs are responding by specifying sensors with embedded cryptographic authentication modules.
Buying committees at US water utilities are consolidating vendor relationships from point-product procurement to multi-parameter platform contracts. Specification authority is shifting from municipal engineers to centralized procurement offices in state revolving fund administration. This pattern is most visible in California and Texas, where regional water districts now negotiate enterprise pricing for combined flow, pressure, and water quality monitoring systems.
Fluid Sensors Market Segmentation
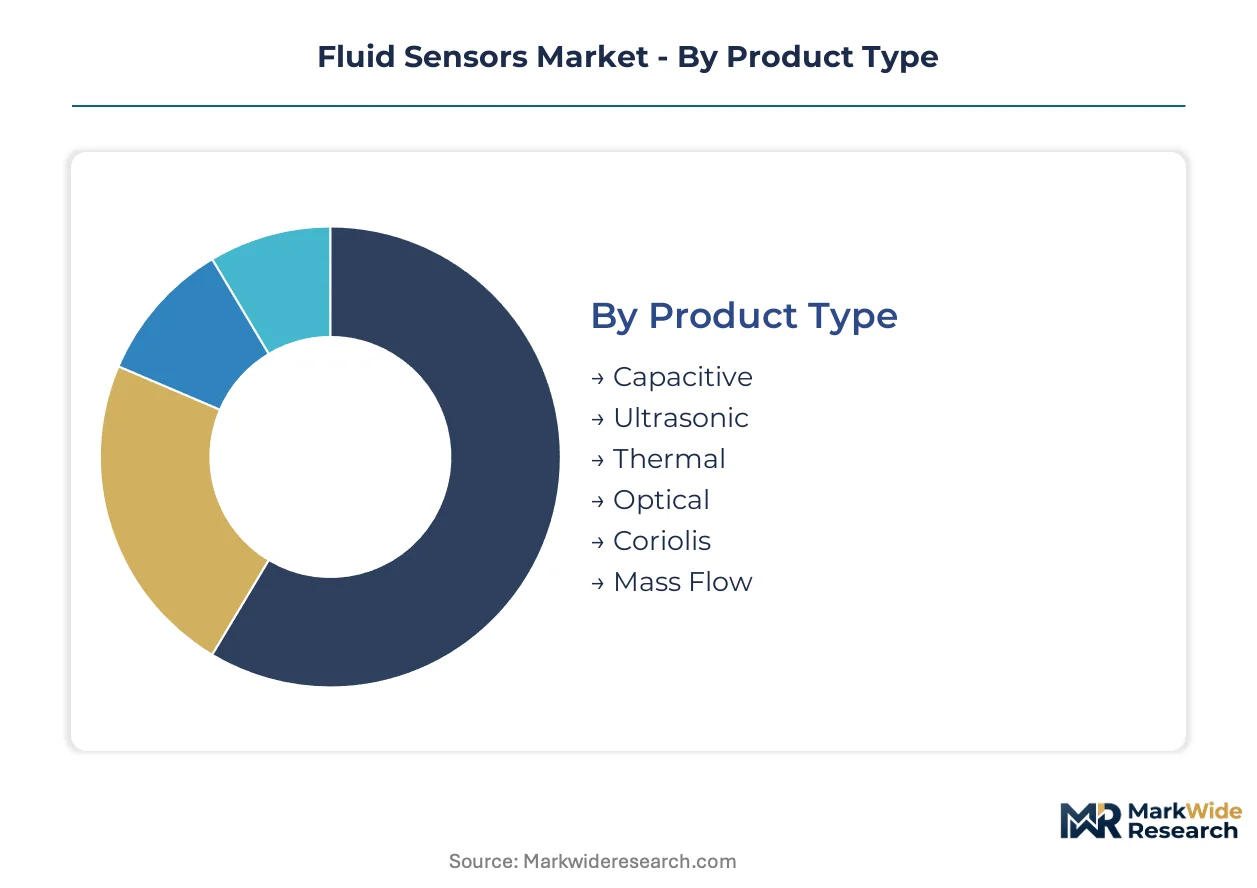
Fluid sensor procurement patterns diverge sharply across measurement physics and deployment contexts. Segment boundaries determine margin structure, calibration requirements, and vulnerability to substitute technologies.
Product Type:
Optical and Coriolis architectures face accelerating substitution pressure from silicon photonics integration, while legacy electrochemical formats defend through calibration lock-in.
- Capacitive:Dielectric measurement across non-conductive fluids dominates level sensing in bulk storage tanks. Water utilities in Germany specify capacitive probes for reservoir monitoring under DIN standards, though MEMS-based alternatives are eroding price premiums in new installations.
- Ultrasonic:Time-of-flight measurement enables non-invasive flow metering with zero pressure drop. Chemical processors in the Rhine-Ruhr corridor deploy clamp-on ultrasonic sensors for corrosive media where wetted materials would degrade, driven by maintenance cost reduction mandates.
- Thermal:Constant-temperature anemometry measures mass flow directly through heat transfer rates. Semiconductor fabs specify thermal sensors for high-purity gas distribution with trace contamination sensitivity.
- Optical:Photonic integrated circuits now deliver refractive index resolution previously requiring benchtop laboratory instruments. Pharmaceutical quality control in Massachusetts and Basel adopts chip-scale devices for real-time biologics monitoring.
- Coriolis:Direct mass flow and density measurement via vibrating tube mechanics commands custody-transfer certification. Swissmetrology-calibrated Coriolis meters dominate chemical batching where measurement uncertainty determines contract validity.
- Mass Flow:Thermal and Coriolis methods converge in this specification category for precise dosing applications. FDA 21 CFR Part 11 validation requirements force pharmaceutical continuous manufacturing toward immutable data-logging mass flow instrumentation.
Capacitive retains volume leadership; Optical holds the steepest expansion curve.
Technology:
Cost tier stratification separates wafer-scale silicon fabrication from ceramic-intensive specialty processes.
- Microelectromechanical Systems:Silicon wafer-scale production enables unit economics that collapse price floors for pressure and flow sensing. Taiwan and South Korea foundry concentration creates supply vulnerability for European and North American sensor houses dependent on 300mm MEMS capacity.
- Piezoelectric:Lead zirconate titanate ceramics sustain measurement stability above 200°C where silicon degrades. High-temperature chemical processing in Germany and Japan specifies piezoelectric pressure transducers despite Chinese rare earth export licensing volatility affecting PZT supply.
- Electromagnetic:Faraday's law measurement of conductive fluids requires no moving parts and minimal maintenance. Municipal water treatment plants specify electromagnetic flowmeters for raw water intake where sediment abrasion would destroy mechanical sensors.
- Thermal Dispersion:Constant-power heating with temperature differential sensing targets air and gas flow applications. HVAC original equipment manufacturers integrate thermal dispersion probes for building automation energy optimization.
- Resonant Frequency:Quartz crystal or MEMS resonant structures enable density and viscosity measurement through frequency shift detection. Oilfield services deploy resonant sensors for multiphase flow characterization where fluid composition varies unpredictably.
MEMS commands unit volume dominance; Piezoelectric maintains pricing power in thermal extremes.
Application:
Customer type concentration varies sharply, with infrastructure operators exhibiting fundamentally different procurement patterns than discrete manufacturers.
- Water Treatment:EPA Lead and Copper Rule revisions mandate continuous distribution system monitoring beyond plant boundaries. US municipalities upgrade aging infrastructure with multi-parameter platforms combining flow, pressure, and water quality sensing.
- Chemical Processing:Process analytical technology integration demands sensors with embedded self-diagnostics and digital communication protocols. German chemical OEMs standardize Coriolis sensors into modular skid designs for export markets.
- HVAC Systems:EU F-Gas Regulation phase-down creates refrigerant leak detection mandates for commercial building automation. Infrared absorption sensors capture new specification authority in European HVAC channels.
- Automotive Systems:Thermal management and battery coolant monitoring drive precision flow sensing in electric vehicle powertrains. OEMs specify automotive-grade MEMS pressure sensors with AEC-Q100 qualification.
- Food & Beverage:Hygienic design standards and CIP/SIP compatibility constrain sensor material selection and sealing architectures. Dairy processors specify 3-A Sanitary Standards-compliant flow meters with tri-clamp connections.
- Oilfield Services:Thermal cycling resistance and explosive atmosphere certification command premium positioning. Emerson Electric field-hardened packaging dominates subsea and downhole pressure measurement where mean-time-between-failures determines operating economics.
Water Treatment anchors installed base expansion; HVAC Systems gains share fastest from regulatory tailwinds.
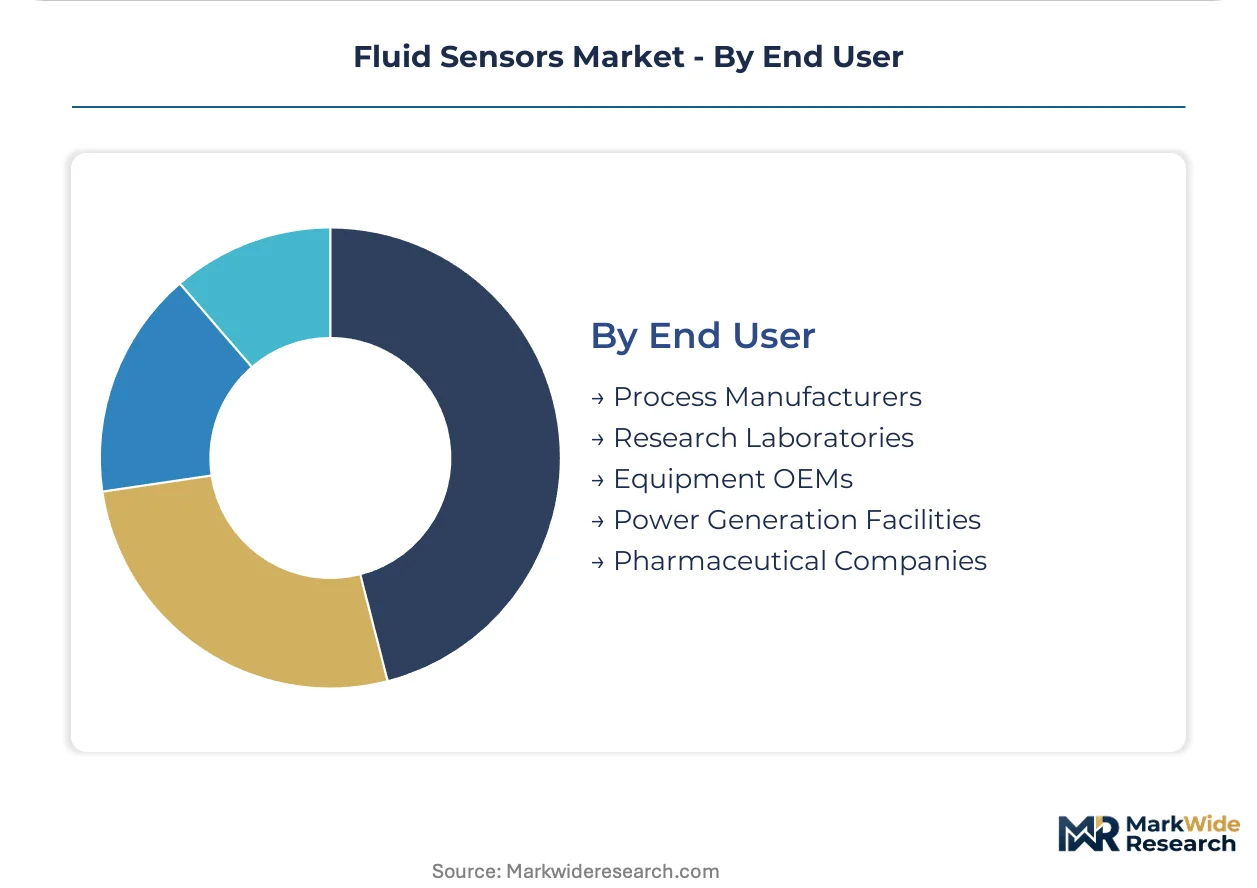
End User:
Specification authority migration from engineering to procurement functions reshapes vendor relationship structures.
- Process Manufacturers:Continuous production economics prioritize measurement availability over capital cost minimization. Safety instrumented system integration under IEC 61508 drives functional safety-certified sensor specification.
- Research Laboratories:Metrological traceability and calibration documentation outweigh unit price considerations. National metrology institutes and academic facilities specify primary standard-grade instrumentation.
- Equipment OEMs:Skid and subsystem integration demands sensors with standardized mechanical interfaces and digital communication protocols. German packaging machinery builders specify IO-Link enabled flow sensors for modular system architectures.
- Power Generation Facilities:Steam cycle chemistry monitoring and cooling water management require corrosion-resistant materials and wide temperature ranges. Combined cycle gas turbine operators specify redundant pressure measurement for critical safety loops.
- Pharmaceutical Companies:FDA 21 CFR Part 11 and EU MDR compliance requirements enforce validated data integrity with immutable audit trails. Cell therapy manufacturers adopt gamma-sterilizable disposable flow sensors for single-use bioprocessing convergence.
Process Manufacturers represent the largest procurement volume; Pharmaceutical Companies exhibit the most rapid specification evolution toward disposable architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swissmetrology-certified calibration networks command 40-60% price premiums over uncertified alternatives, while Indian municipal procurement collapses entry thresholds for optical leak detection previously cost-prohibitive at domestic price points. This asymmetry reshapes vendor geographic strategy.
United States
EPA Lead and Copper Rule revisions mandate continuous distribution system monitoring beyond treatment plants. Safe Drinking Water Act enforcement expands real-time optical and electrochemical sensor deployment into aging municipal infrastructure. California and Texas regional water districts now negotiate enterprise pricing for combined flow, pressure, and water quality monitoring platforms.
Germany
Rhine-Ruhr chemical process OEMs standardize multi-parameter Coriolis sensors into modular skid designs for export markets. EU F-Gas Regulation phase-down creates refrigerant leak detection mandates for commercial HVAC channels. Baden-Württemberg industrial automation corridor concentrates demand for IO-Link enabled flow sensors with embedded self-diagnostic protocols.
China
Dual carbon goals accelerate thermal management sensor deployment in electric vehicle powertrains. NMPA medical device regulations force hemodialysis machine OEMs toward cryptographic authentication modules. Yangtze River Delta bioprocessing clusters adopt gamma-sterilizable disposable flow sensors for cell therapy manufacturing convergence.
India
Central government Smart Cities Mission funding targets non-revenue water reduction in municipal networks. BIS standards compliance opens procurement to optical leak detection sensors previously excluded by cost barriers. Maharashtra and Gujarat urban infrastructure projects specify multi-parameter platforms for combined flow and pressure monitoring.
Japan
METI industrial digitization initiatives push MEMS sensor integration into precision chemical dosing equipment. JIS functional safety standards shape product architecture for process manufacturers integrating sensors into safety instrumented systems. Kansai region semiconductor fabs specify thermal sensors for high-purity gas distribution with trace contamination sensitivity.
Fluid Sensors Market Key Industry Players
Concentration sits with Swiss and German precision instrumentation houses that leverage captive calibration networks and backward integration into industrial automation software stacks. The vendor base stratifies across three tiers: Swissmetrology-certified custody-transfer specialists, field-hardened oilfield services providers, and silicon wafer-scale MEMS fabricators. Strategic moves center on calibration-lock-in strategies to defend installed base against silicon photonics cost erosion, and portfolio diversification into disposable bioprocessing architectures.
Within the precision-tier segment, Endress+Hauser AG and Siemens AG exemplify divergent competitive approaches to industrial automation dominance. Emerson Electric Co anchors the field-hardened packaging archetype for extreme environment deployment. These three entities collectively represent the strategic poles—calibration network control, software stack integration, and thermal cycling resistance—that structure competitive positioning across custody-transfer, process analytical, and oilfield application contexts.
| Leading Market Players |
|---|
| Endress+Hauser AG |
| ABB Ltd |
| Siemens AG |
| Emerson Electric Co |
| Honeywell International Inc |
| Schneider Electric SE |
| SICK AG |
| NXP Semiconductors N.V. |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
Swissmetrology-certified calibration regimes gate both supply qualification and price differentiation simultaneously, forcing vendors to maintain captive laboratory networks or surrender custody-transfer premiums to certified rivals. This certification moat collapses price competition at the precision tier while silicon photonics cost erosion compresses margins in uncertified optical segments.
Pricing Analysis
Configured-to-order pricing for Swissmetrology-certified Coriolis sensors commands substantial premiums over standard MEMS pressure transducers sold through distribution. Price differentiation rests on calibration traceability grade and after-sales service bundling, with custody-transfer certification determining contract validity in chemical batching. Pricing pressure stems from silicon photonics packaging cost compression in optical refractive index measurement. Municipal water utilities exhibit highest price sensitivity, while pharmaceutical continuous manufacturers prioritize validated data integrity over unit cost.
Supply Chain Analysis
Inventory lead times for high-purity lead zirconate titanate ceramics now stretch 16-24 weeks, constraining piezoelectric pressure transducer output for high-temperature chemical processing. Supply concentrates in Taiwan and South Korea for 300mm MEMS wafer fabrication, with German and Swiss houses dependent on Asian foundry capacity. Raw material dependencies include rare earth oxides for PZT ceramics, silicon wafers for MEMS devices, and specialty optical glass for photonic integrated circuits. Single-source vulnerability in Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through industrial automation distributors and direct OEM specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics integration constitutes a high-growth disruption, collapsing the cost floor for optical fluid sensing while EPA Lead and Copper Rule revisions mandate continuous monitoring infrastructure across US municipal networks.
For Market Incumbents: Secure calibration network control through captive Swissmetrology-certified laboratory expansion, particularly in emerging markets where custody-transfer sensor deployment faces infrastructure scarcity. Deepen backward integration into industrial automation software stacks to anchor specification authority against silicon photonics substitution in process analytical applications. Prioritize field-hardened packaging R&D for thermal cycling resistance in oilfield services, where mean-time-between-failures determines operating economics and defends premium positioning. For New Entrants and Emerging Players: Lead with gamma-sterilizable disposable flow sensors for bioprocessing single-use convergence, where cell therapy manufacturing adoption outpaces stainless steel instrumentation replacement cycles. Target Indian municipal procurement under Smart Cities Mission funding, where optical leak detection sensors previously excluded by cost barriers now qualify for specification. Pursue sensor-as-a-service revenue models for photonic integrated circuit refractive index devices, compressing capital expenditure barriers for pharmaceutical quality control adoption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across MEMS-based optical sensing, enabling asset-light entry for photonic integrated circuit specialists against traditional electrochemical incumbents. Long-term viability favors vendors with hybrid portfolios spanning certified custody-transfer precision and silicon wafer-scale volume production. Acquisition targets should exhibit captive calibration infrastructure or embedded software stack integration. Watch silicon photonics packaging cost curves as the critical inflection indicator for optical sensor substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | Swissmetrology-certified laboratory buildout in India and Southeast Asia captures custody-transfer premiums in emerging municipal markets. |
| Silicon Photonics Integration | Photonic integrated circuit packaging cost reduction displaces benchtop refractometers in Massachusetts and Basel biologics manufacturing. |
| Disposable Sensor Development | Gamma-sterilizable single-use flow sensors capture share from stainless steel instrumentation in cell therapy manufacturing convergence. |
| IO-Link Protocol Adoption | Digital communication standardization enables modular skid integration for German chemical OEM export markets. |
| Cybersecurity Certification Investment | IEC 62443 compliance accelerates product development timelines for safety instrumented system integration in process manufacturing. |
Research Approach
The analysis maps optical, Coriolis, thermal, ultrasonic, and capacitive sensor sub-sectors, each validated through procurement directors at water utilities, pharmaceutical quality control managers, chemical process OEM engineers, and industrial automation system integrators. Primary interview findings triangulate against secondary sources including EPA Safe Drinking Water Act enforcement records, FDA 21 CFR Part 11 guidance documents, EU MDR Annex I technical specifications, and Swissmetrology laboratory accreditation databases. Bottom-up unit economics for MEMS wafer-scale production reconcile with top-down market sizing across application segments.
Consistency checks validate volume and value outputs against industrial automation capex disclosures, municipal water infrastructure spending reports, and pharmaceutical continuous manufacturing adoption surveys across the projection horizon. The analytical framework models product type, technology, application, and end-user segmentation dimensions with regional regulatory cluster overlays. CAGRs derive from installed base replacement cycles, regulatory mandate implementation timelines, and technology substitution elasticity parameters. Forecast inputs incorporate MEMS foundry capacity utilization, rare earth export licensing patterns, and calibration infrastructure buildout rates.
Underlying assumptions cover EPA enforcement continuity, Swissmetrology certification authority persistence, and silicon photonics packaging cost decline trajectories, with deviation risk concentrated in Chinese rare earth export policy shifts and Taiwan semiconductor supply disruptions. Revision becomes warranted when MEMS foundry concentration thresholds or calibration laboratory scarcity conditions cross critical supply constraint boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Distributed Temperature Sensing Market