
 Quantum Sensors Market | 2026-2036
Quantum Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Sensors Market Intelligence
Software-defined quantum sensor calibration is consolidating value around recurring service contracts rather than hardware-only transactions. ID Quantique SA leverages its Geneva-based quantum cryptography heritage to anchor European government demand for secure timing distribution. M Squared Lasers Limited sustains its position through proprietary soliton laser architectures that reduce atomic interferometer noise floors. Robert Bosch GmbH competes by integrating NV-center diamond magnetometers into automotive-grade inertial navigation modules for autonomous vehicle platforms.
Quantum sensors exploit superposition and entanglement to measure physical quantities with precision exceeding classical limits, typically operating at cryogenic temperatures below 4 Kelvin or leveraging laser-cooled atomic ensembles to achieve part-per-billion sensitivity for gravitational or magnetic field detection. These instruments serve critical functions in geophysical resource mapping, defense navigation, and medical imaging where conventional sensors fail. Magnetometers dominate current revenue contribution due to mature superconducting quantum interference device fabrication pipelines and established installation bases in oil exploration surveys. Atomic clock segments capture premium pricing from defense and telecommunications buyers requiring sub-nanosecond synchronization across distributed networks. NV-center platforms represent the fastest-expanding technology category as room-temperature diamond quantum sensors displace cryogenic alternatives in biomedical and automotive applications.
The US NIST maintains primary standards for atomic timekeeping that shape procurement specifications across federal agencies and allied defense programs, while the EU Quantum Flagship initiative channels public R&D funding toward sovereign manufacturing capacity for superconducting and photonic quantum sensors. Japan's METI coordinates industry consortia to secure domestic supply chains for rare-earth elements used in atomic vapor cell construction. Stakeholders must monitor how export control expansions affecting cryogenic electronics and laser systems redirect component sourcing strategies across national boundaries.
Market Dynamics
Defense procurement programs across NATO member states are expanding budgets for quantum-enhanced navigation systems that operate without GPS dependency, creating a structural pull that reshapes manufacturing priorities and R&D allocation across the supply base.
Growth Catalysts
- EU Quantum Flagship initiative:Public R&D funding channels toward sovereign manufacturing capacity for superconducting and photonic quantum sensors, accelerating domestic foundry buildouts.
- Atomic clock segments:Defense and telecommunications buyers requiring sub-nanosecond synchronization across distributed networks capture premium pricing and sustain order backlogs.
- Superconducting quantum interference device foundries:Cryogenic manufacturing capacity in Germany and Japan scales to meet geophysics contractor demand for oil exploration surveys.
Market Restraints
- Helium-3 and rare-earth supply concentration:Japan's METI coordinates industry consortia to secure domestic supply chains, yet global atomic vapor cell construction remains vulnerable to export bottlenecks.
- Cryogenic infrastructure capex:Operating temperatures below 4 Kelvin require specialized dilution refrigerators with limited qualified vendors.
- Laser system export controls:National security classifications on frequency-stabilized sources redirect component sourcing strategies and extend lead times.
Strategic Opportunities
- NV-center diamond platforms:Room-temperature quantum sensors displace cryogenic alternatives in biomedical imaging and automotive inertial navigation modules.
- Software-defined calibration services:Recurring service contracts consolidate value around predictive maintenance and remote parameter optimization.
- US NIST atomic timekeeping standards:Federal procurement specifications shape allied defense program requirements, creating standardization tailwinds for compliant vendors.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified personnel for dilution refrigerator operation and superconducting circuit fabrication command premium compensation and extend hiring timelines.
- Integration complexity with legacy navigation systems:Atomic interferometer outputs require signal conditioning layers that interface with existing inertial measurement unit architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Sensors Market |
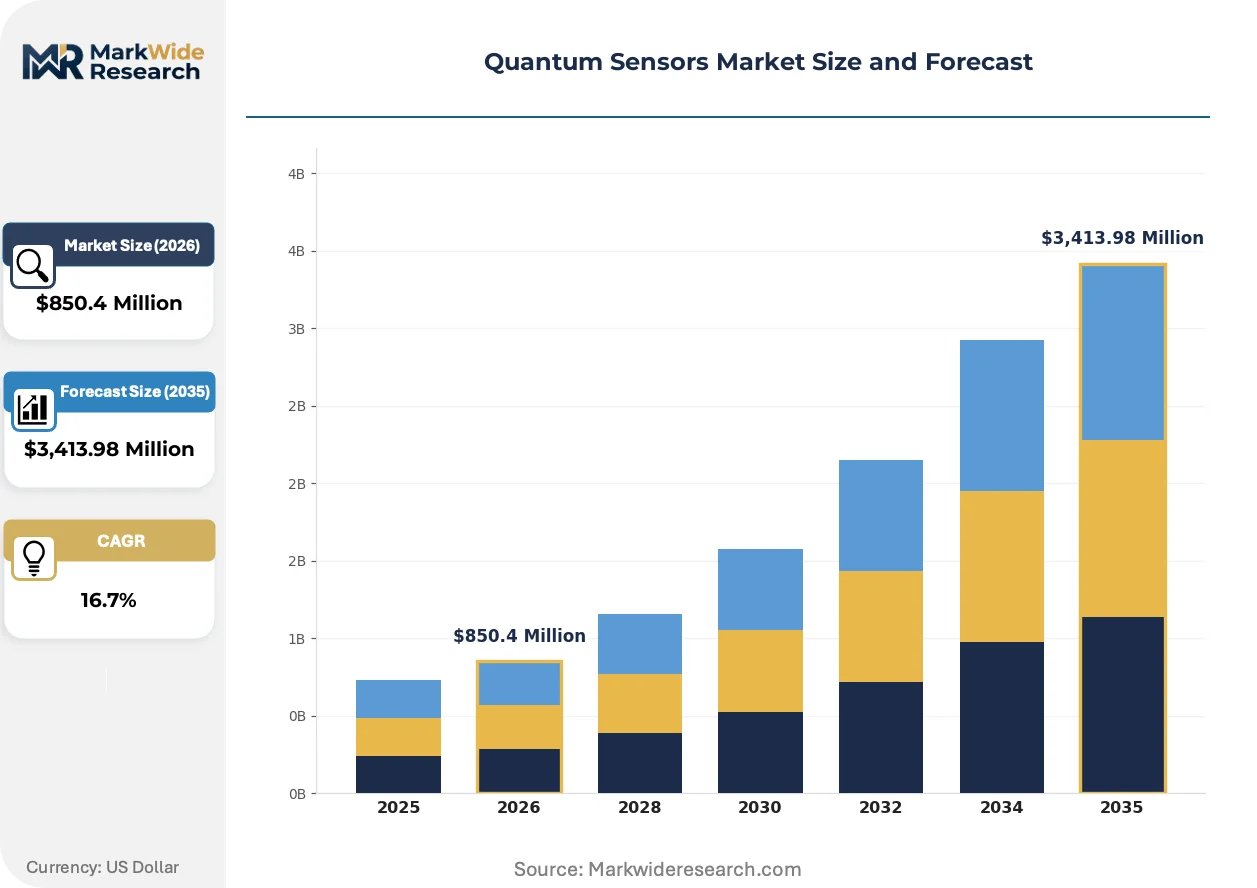
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $3,413.98 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photo-detectors, Magnetometers, Gravity Sensors, Temperature Sensors Technology: Superconducting Quantum Interference Devices, Quantum Dot Sensors, Atomic Clocks, NV Centers End User: Healthcare Institutions, Aerospace, Defense, Environmental Monitoring Application: Navigation, Geophysics, Oil Exploration, Biometric Systems |
| Companies Covered | Campbell Scientific, Inc., ID Quantique SA, Muquans SAS, LI-COR, Inc., M Squared Lasers Limited, AOSense, Inc., Robert Bosch GmbH, GWR Instruments, Inc., Microsemi Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Sensors Market Strategic Shifts & Innovations
Superconducting quantum interference device foundries in Germany and Japan are scaling cryogenic manufacturing capacity to meet order backlogs from geophysics contractors, while NV-center diamond platforms gain traction in room-temperature applications that bypass helium infrastructure entirely.
Photonic integrated circuits for atomic interferometry are decentralizing sensor architectures by replacing free-space optical benches with chip-scale waveguide networks. Automotive Tier-1 suppliers are adopting these platforms for autonomous vehicle navigation modules at accelerated qualification cycles. The shift compresses form factors and enables distributed sensor arrays that operate without centralized cryogenic support.
REACH and RoHS compliance frameworks in Europe are tightening material restrictions on mercury-based atomic vapor cells and certain rare-earth processing chemicals. Manufacturers are reformulating cell chemistry and redesigning supply chains to maintain CE marking eligibility. Atomic clock segments face the steepest reformulation costs due to legacy reliance on restricted isotopes.
Defense procurement officers are consolidating vendor relationships through multi-year performance-based contracts that bundle hardware, calibration, and field service. Traditional equipment-only transactions are losing share to integrated service agreements in NATO member states. The UK Ministry of Defence and US Army Research Laboratory have pioneered this structure for quantum-enhanced navigation programs.
Quantum Sensors Market Segmentation
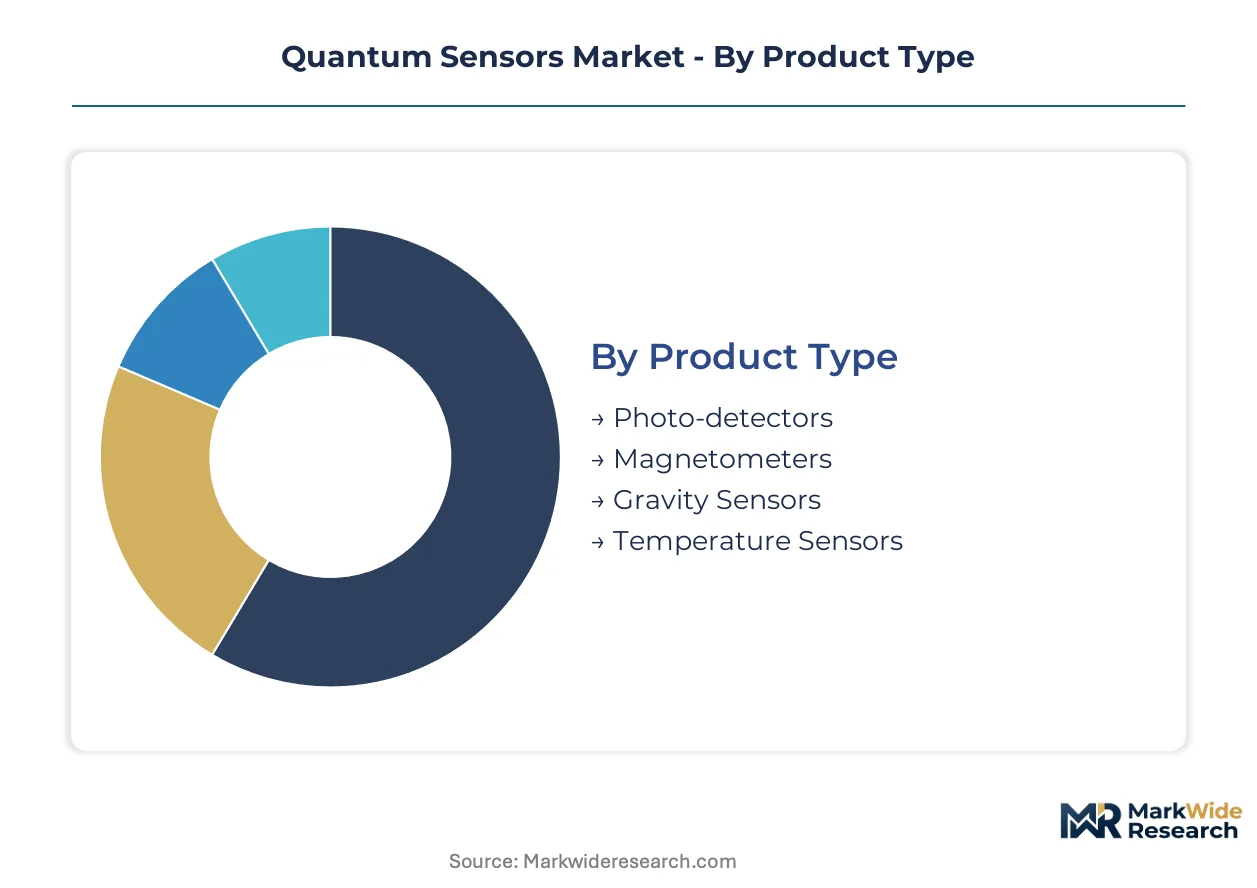
Segmentation in quantum sensors reveals how buyers prioritize sensitivity specifications against operational temperature constraints. Procurement officers weigh cryogenic infrastructure requirements against room-temperature deployment flexibility when allocating capital across product categories.
Product Type:
Buyers select product types based on field sensitivity requirements and total cost of ownership across cooling infrastructure.
- Magnetometers:Superconducting quantum interference devices achieve femtotesla resolution for subsurface mineral detection. Oil exploration contractors in Norway and Saudi Arabia drive order backlogs as seismic survey programs expand offshore licensing blocks.
- Gravity Sensors:Cold atom interferometers measure gravitational gradients with microgal precision for underground void detection. Defense navigation programs across NATO member states fund development of GPS-denied positioning systems using atom interferometry baselines.
- Photo-detectors:Single-photon avalanche diodes serve quantum key distribution networks requiring timing jitter below 100 picoseconds.
- Temperature Sensors:Johnson noise thermometers provide primary standards calibration for national metrology institutes without cryogenic reference points.
Magnetometers lead on scale; gravity sensors lead on momentum.
Technology:
Technology selection hinges on manufacturing maturity and supply chain access to specialized components like helium-3 and isotopically pure diamond.
- Superconducting Quantum Interference Devices:Niobium-aluminum oxide junctions fabricated at 4 Kelvin deliver unmatched magnetic flux resolution. German foundries scale cryogenic cleanroom capacity to meet geophysics contractor demand for borehole logging tools.
- NV Centers:Nitrogen-vacancy defects in synthetic diamond enable vector magnetometry at room temperature. Automotive Tier-1 suppliers in Stuttgart and Detroit integrate NV-center chips into autonomous vehicle navigation modules bypassing helium infrastructure entirely.
- Atomic Clocks:Cesium fountain standards anchor telecommunications synchronization networks with instability below 10^-15.
- Quantum Dot Sensors:Colloidal semiconductor nanocrystals provide tunable optical detection for biomedical imaging applications.
Superconducting devices dominate current procurement volumes; NV centers are climbing the fastest.
End User:
End-user budgets reflect mission-criticality of precision timing and navigation in contested operational environments.
- Defense:Military procurement officers specify quantum-enhanced inertial navigation for submarine and aircraft platforms operating under GPS jamming scenarios. The US Army Research Laboratory and UK Ministry of Defence structure multi-year performance contracts bundling hardware with calibration services.
- Aerospace:Satellite operators require atomic frequency standards for onboard timekeeping with drift below one nanosecond per day. European Space Agency programs and commercial constellation builders in the US drive qualification cycles for space-hardened quantum sensors.
- Healthcare Institutions:Magnetoencephalography suites deploy superconducting arrays for neural activity mapping in pre-surgical planning.
- Environmental Monitoring:Volcanic surveillance networks use portable atomic gravimeters to detect magma chamber inflation with centimeter-level precision.
Defense leads on scale; aerospace leads on momentum.
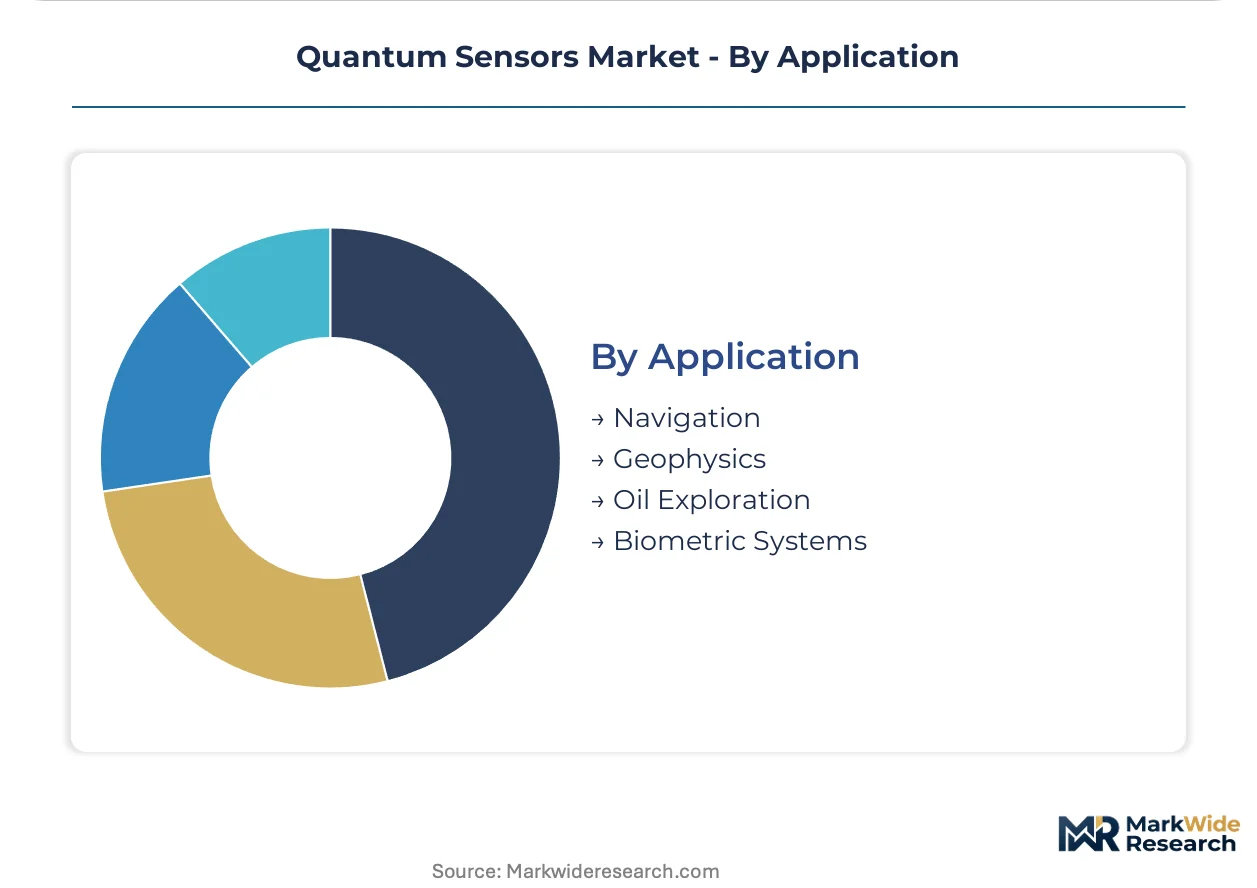
Application:
Application demand correlates with regulatory pressure on exploration accuracy and biometric authentication reliability.
- Navigation:Quantum inertial measurement units provide drift-free positioning for autonomous systems in denied environments. NATO member states expand budgets for quantum-enhanced navigation systems operating independently of satellite constellations.
- Geophysics:Airborne gravity gradiometry surveys map subsurface density variations for mineral exploration. Contractors in Australia and Canada deploy superconducting gravity sensors across frontier basins with limited seismic coverage.
- Oil Exploration:Borehole magnetometers detect resistivity contrasts in unconventional reservoir characterization.
- Biometric Systems:Quantum-enhanced optical coherence tomography improves iris recognition false-accept rates.
Navigation leads on scale; geophysics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting quantum sensor manufacturing toward jurisdictions with subsidized cryogenic infrastructure and permissive dual-use export classifications. Germany and Japan attract foundry investments through METI and EU Quantum Flagship funding streams that offset dilution refrigerator capital costs. The United States maintains demand primacy through NIST procurement standards that cascade into allied defense programs.
United States
Defense procurement from the Army Research Laboratory and DARPA sustains order backlogs for atomic interferometer platforms. The NIST atomic timekeeping standards shape federal specifications that allied NATO programs adopt. Boston and Boulder clusters host superconducting circuit fabrication facilities serving geophysics contractors.
Germany
EU Quantum Flagship channels public R&D funding toward sovereign superconducting and photonic sensor manufacturing. REACH compliance frameworks tighten material restrictions on mercury-based atomic vapor cells, forcing reformulation investments. Stuttgart anchors automotive Tier-1 integration of NV-center diamond magnetometers for autonomous navigation modules.
Japan
METI coordinates industry consortia to secure domestic supply chains for rare-earth elements in atomic vapor cell construction. Cryogenic manufacturing capacity scales in Osaka and Tokyo to meet geophysics contractor demand for borehole logging tools. Export controls on frequency-stabilized laser systems redirect component sourcing toward domestic vendors.
United Kingdom
The Ministry of Defence structures multi-year performance contracts bundling quantum-enhanced navigation hardware with calibration services. CE marking requirements under EU-UK trade protocols maintain alignment with REACH material restrictions. Oxford and Cambridge clusters concentrate cold atom interferometry research for GPS-denied positioning systems.
Switzerland
Geneva-based quantum cryptography heritage anchors European government demand for secure timing distribution networks. Swissmedic-equivalent frameworks for precision instrument calibration create service revenue stickiness. Zurich ETH spinouts commercialize photonic integrated circuits that displace free-space optical benches in atomic interferometry.
Quantum Sensors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated service agreements while geophysics contractors prioritize equipment-only transactions. The vendor base concentrates around cryogenic foundry operators and laser system architects, creating tiered access based on helium-3 supply relationships and frequency-stabilized source qualifications. Three archetypes dominate: superconducting device foundries with dilution refrigerator captive capacity, atomic clock specialists leveraging NIST traceability, and NV-center diamond platform integrators bypassing cryogenic infrastructure entirely. Competitive moves center on multi-year performance contracting and photonic integrated circuit licensing to compress form factors.
Among European quantum technology specialists, ID Quantique SA and Muquans SAS exemplify the secure timing and atomic interferometry archetypes respectively. M Squared Lasers Limited represents UK-based laser architecture specialists that reduce noise floors in atomic ensemble systems. Robert Bosch GmbH anchors the automotive integration tier, translating diamond quantum sensors into vehicle-grade navigation modules. These three occupy positions across the premium equipment and integrated service vectors.
| Leading Market Players |
|---|
| Campbell Scientific, Inc. |
| ID Quantique SA |
| Muquans SAS |
| LI-COR, Inc. |
| M Squared Lasers Limited |
| AOSense, Inc. |
| Robert Bosch GmbH |
| GWR Instruments, Inc. |
| Microsemi Corp. |
| Others |
Cost & Logistics Intelligence
Photonic integrated circuit adoption is compressing sensor form factors while simultaneously shifting cost economics from cryogenic infrastructure toward semiconductor foundry economics. This transition concentrates manufacturing leverage among photonics specialists in Germany and Japan while eroding pricing power for legacy superconducting device vendors dependent on dilution refrigerator capacity.
Pricing Analysis
Distributor margins for quantum sensor hardware typically range from 15-25% for standard magnetometer configurations, while direct-to-OEM contracts for defense navigation systems command steeper discounts tied to multi-year calibration service bundles. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable atomic clocks from commercial-grade timing modules and uncalibrated research prototypes. Cost compression in cryogenic SQUID systems is intensifying because foundry capacity expansion in Osaka and Berlin is shortening order backlogs. Academic research labs exhibit the highest price sensitivity due to grant-funded procurement cycles, whereas defense procurement officers prioritize performance specifications over unit economics.
Supply Chain Analysis
Specialized freight for dilution refrigerators and helium-3 isotopes adds 8-12% to landed costs for geophysics contractors operating in frontier basins. Component sourcing concentrates in Germany, Japan, and the United States for superconducting junction fabrication, frequency-stabilized laser systems, and atomic vapor cell assembly. Rare-earth element supply for cesium and rubidium cells rests on METI-coordinated Japanese consortia and limited European processing capacity. Single-source vulnerability around helium-3 stockpiles from nuclear weapons program decommissioning creates procurement risk for cryogenic sensor manufacturers. Distribution runs through defense prime contractors for NATO navigation programs and through specialized scientific distributors for academic and oil exploration buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The quantum sensors market functions as a regulatory compounder where EU Quantum Flagship funding and NIST procurement standards create structural demand floors that insulate vendors from cyclical technology spending cuts.
For Market Incumbents: Cement long-term positioning through captive dilution refrigerator capacity in Germany or Japan and exclusive helium-3 supply relationships with national stockpile administrators. NV-center diamond platforms threaten to displace cryogenic magnetometers in automotive navigation modules, making backward integration into synthetic diamond growth or photonic foundry partnerships essential defensive moves. Multi-year performance contracting with NATO defense ministries locks out competitors through integrated calibration service bundles. For New Entrants and Emerging Players: Capture white-space in room-temperature biomedical imaging applications where NV-center sensors bypass helium infrastructure entirely. Automotive Tier-1 supplier qualification cycles in Stuttgart and Detroit offer the most penetrable entry path, with software-defined calibration services as the preferred go-to-market angle against incumbent hardware-only vendors. Environmental monitoring networks for volcanic surveillance present underserved demand for portable atomic gravimeters. For Investors and Strategic Acquirers: Valuations sit cheapest among cryogenic foundry operators with idle capacity and established government contracting relationships. Long-term viability over the coming decade hinges on successful transition from superconducting devices toward photonic integrated circuit architectures. Watch for inflection in automotive OEM design-win announcements for quantum-enhanced inertial navigation modules as the signal that NV-center platforms have crossed from research to production scale.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Foundry Partnership | ETH Zurich spinouts commercialize chip-scale atomic interferometers that displace free-space optical benches. |
| Helium-3 Supply Agreement | Japanese METI-coordinated consortia secure domestic rare-earth chains for atomic vapor cell construction. |
| Multi-Year Performance Contract | UK Ministry of Defence bundles hardware with calibration services, locking out equipment-only competitors. |
| NV-Center Platform Qualification | Robert Bosch GmbH integrates diamond magnetometers into automotive-grade navigation for autonomous vehicles. |
| REACH Compliance Reformulation | Mercury-free atomic vapor cell chemistry maintains CE marking eligibility under tightening European material restrictions. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with defense procurement officers, cryogenic engineering directors at foundry operators, geophysics contractor technical leads, and automotive Tier-1 supplier platform engineers. Secondary validation drew from EU Quantum Flagship progress reports, NIST technical specifications for atomic timekeeping, METI industry consortium disclosures, and SEC filings from listed quantum technology specialists. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Rate-of-change decomposition across the analysis window separated volume growth from price evolution and mix shift effects. Segmentation dimensions modeled include product type, technology platform, end-user vertical, and application area, with additional granularity on cooling infrastructure requirement and NIST traceability certification level. CAGRs were derived from installed base growth rates and replacement cycle analysis for superconducting devices, supplemented by order backlog data from German and Japanese foundries.
Underlying measurement precision varies by segment; atomic clock and defense navigation categories carry tighter precision than emerging NV-center biomedical applications due to established procurement reporting requirements. Forecasts reflect assumptions about continued EU and US public R&D funding, helium-3 supply continuity, and automotive qualification cycle timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Rangefinder Market