
 Magnetoresistive Sensors Market | 2026-2036
Magnetoresistive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetoresistive Sensors Market Foresight
Automotive electrification is repositioning demand away from traditional internal-combustion applications toward battery management and motor commutation systems. Infineon Technologies AG leverages its power semiconductor footprint to bundle magnetoresistive sensing with IGBT and silicon carbide platforms. Allegro MicroSystems, Inc. anchors its competitive stance through proprietary packaging that withstands harsh underhood temperatures. TDK Corporation sustains R&D intensity across thin-film magnetic materials, extending its sensor portfolio into high-resolution position detection for robotics.
Magnetoresistive sensors detect magnetic field variations through resistance changes in ferromagnetic thin films, typically operating at supply voltages below five volts with sensitivities reaching millivolts per gauss for precision motion tracking. Giant magnetoresistive elements dominate automotive wheel-speed and crankshaft applications where moderate cost and proven reliability matter most. Tunnel magnetoresistive architectures capture the fastest expansion in industrial automation encoders and medical imaging equipment, where picotesla resolution justifies premium pricing. Analog output configurations retain volume leadership, though digital interfaces are gaining ground in consumer electronics where microcontroller integration simplifies design cycles.
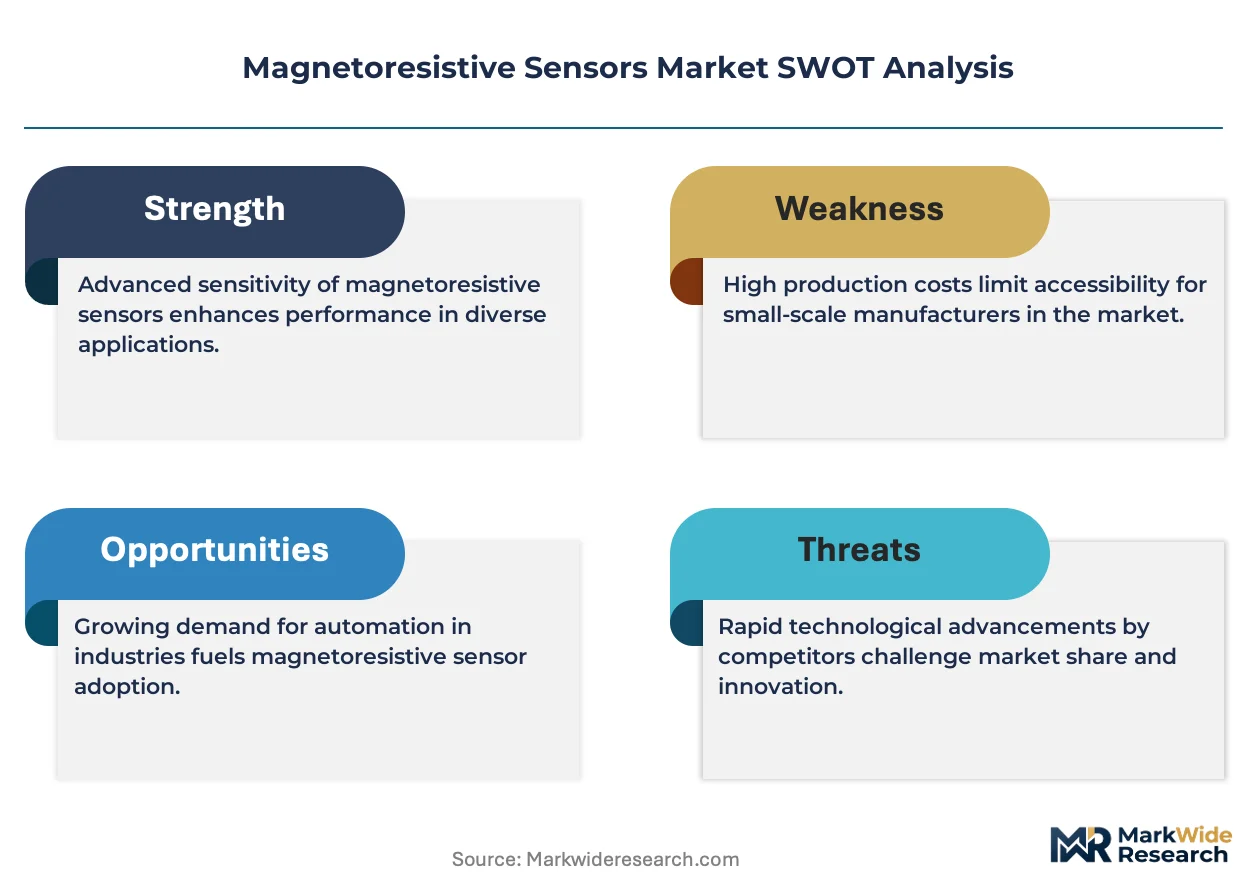
FDA device classification rules in the United States and EU MDR conformity requirements in Europe shape biocompatibility and electromagnetic compatibility testing burdens for healthcare-grade sensors. NHTSA functional safety expectations and ISO 26262 automotive risk standards compel suppliers to document failure modes across magnetoresistive arrays used in steering-angle and pedal-position modules. Stakeholders must weigh the capital requirements of tunnel magnetoresistive fabrication against the margin compression threatening commodity anisotropic product lines as foundry capacity tightens for specialized magnetic thin-film deposition.
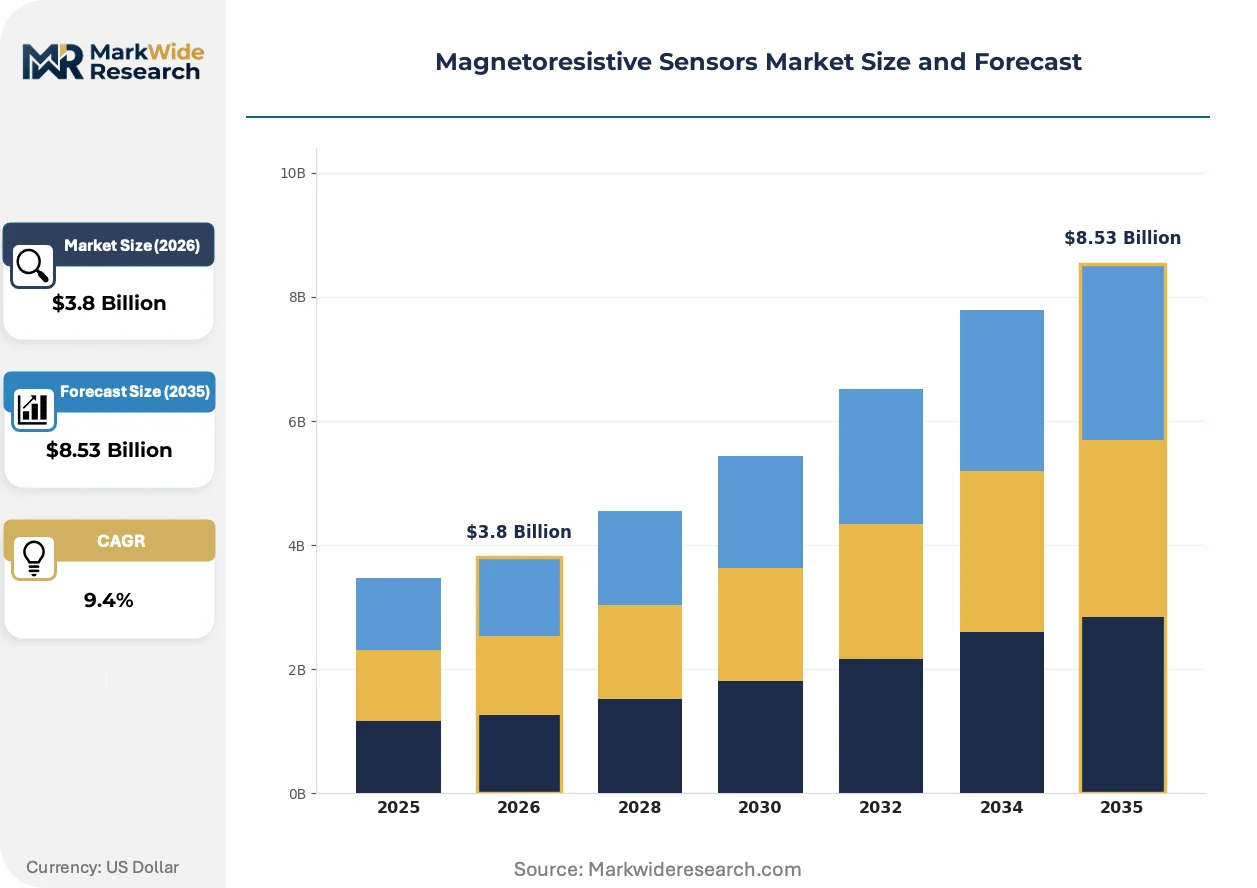
Market Dynamics
Automotive electrification is compressing design cycles for magnetic sensing architectures as OEMs consolidate sensor fusion platforms across battery management and motor commutation systems.
Growth Catalysts
- NHTSA functional safety mandates:Steering-angle and pedal-position modules now require documented failure-mode analysis under ISO 26262, forcing tier-one suppliers to upgrade magnetoresistive array specifications.
- Thin-film deposition advances:Tunnel magnetoresistive architectures achieve picotesla resolution for industrial automation encoders and medical imaging equipment, opening premium pricing tiers.
- Germany's automotive electronics corridor:Munich and Stuttgart clusters concentrate demand for electric powertrain integration, pulling sensor procurement toward high-temperature packaging specifications.
Market Restraints
- Foundry capacity constraints:Specialized magnetic thin-film deposition equipment faces 18-24 month lead times, throttling tunnel magnetoresistive output expansion.
- Commodity anisotropic magnetoresistive margin compression:Standard wheel-speed sensor prices erode as Chinese packaging houses scale output for legacy internal-combustion applications.
- Raw material volatility:Cobalt and nickel prices for ferromagnetic thin films fluctuate with battery chemistry demand, squeezing input cost predictability.
Strategic Opportunities
- EU Green Deal industrial benchmarks:Carbon-accounting requirements for automotive supply chains favor magnetoresistive sensors over Hall-effect alternatives with lower embodied energy.
- Robotics position detection:Collaborative robot manufacturers in Japan and South Korea source high-resolution encoders for force-feedback joints.
- Digital interface migration:SPI and I2C outputs displace analog configurations in consumer electronics, simplifying microcontroller integration and shortening design cycles.
Industry Challenges
- ISO 26262 documentation burden:Functional safety certification for automotive-grade arrays demands 12-18 month validation timelines, delaying revenue recognition.
- Magnetic thin-film process engineering scarcity:Foundry technicians with sputtering and lithography expertise command premium compensation, constraining expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetoresistive Sensors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anisotropic Magnetoresistive, Giant Magnetoresistive, Tunnel Magnetoresistive, Others Application: Automotive, Consumer Electronics, Industrial Automation, Medical Devices End User: Aerospace, Defense, Healthcare, Telecommunications Technology: Analog, Digital, Mixed Signal, High Speed |
| Companies Covered | Infineon Technologies AG, Allegro MicroSystems, Inc., TDK Corporation, NVE Corporation, Honeywell International Inc., Asahi Kasei Microdevices Corporation, STMicroelectronics N.V., TE Connectivity Ltd., Melexis NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetoresistive Sensors Market Shifts & Advancements
Magnetoresistive sensing architectures are fragmenting into application-optimized variants as end-users reject one-size-fits-all specifications.
Sensor fusion integration is converging with power semiconductor platforms. Automotive module suppliers bundle magnetoresistive position detection with silicon carbide gate drivers and IGBT protection circuits. This convergence collapses board space requirements and reduces electromagnetic interference susceptibility. Tier-one electrification programs in Germany and Japan now specify fused sensing-power architectures as baseline requirements.
EU MDR conformity requirements tighten electromagnetic compatibility testing for healthcare-grade sensors. Medical device manufacturers must document biocompatibility and interference resilience across implantable and diagnostic equipment categories. Tunnel magnetoresistive suppliers serving imaging modalities face expanded notified body audit scopes, compressing certification timelines and raising compliance staffing levels.
Specification consolidation among battery-electric vehicle platforms concentrates procurement authority at OEM headquarters. Tier-two sensor vendors lose direct customer relationships as Volkswagen, BMW, and Hyundai centralize magnetoresistive sourcing decisions. This concentration forces component suppliers to qualify through platform-level contracts rather than individual module design wins, privileging scale and balance sheet strength over technical differentiation.
Magnetoresistive Sensors Market Segmentation
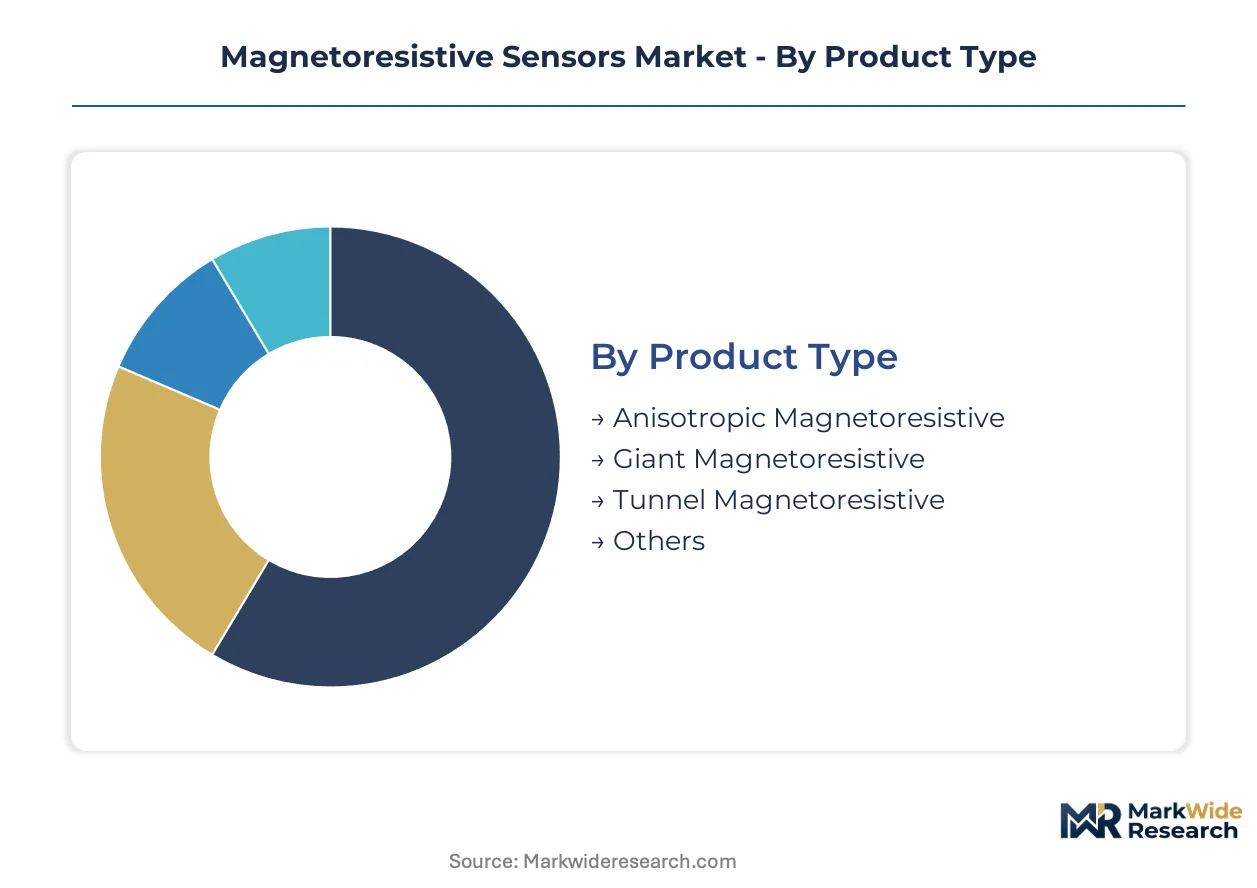
Magnetoresistive sensor procurement splits across incompatible performance requirements, with automotive electrification and industrial automation pulling specifications in divergent directions. Buyers prioritize either cost-scalable architectures for high-volume wheel-speed detection or picotesla-resolution platforms for precision robotics and medical imaging.
Product Type:
Cost-performance tradeoffs dominate technology selection, with foundry capacity constraints and thin-film deposition complexity widening the gap between commodity and premium tiers.
- Giant Magnetoresistive:Ferromagnetic multilayer structures achieve moderate sensitivity at supply voltages below five volts, suiting harsh underhood environments. Procurement concentrates among Germany's tier-one suppliers for electric powertrain position feedback, though margin compression accelerates as Chinese packaging houses scale output.
- Tunnel Magnetoresistive:MgO barrier architectures deliver picotesla resolution through spin-dependent tunneling, commanding premium pricing in industrial encoders and MRI equipment. Munich and Stuttgart automotive clusters now specify TMR for steering-angle modules under NHTSA functional safety mandates, stretching foundry lead times to 18-24 months.
- Anisotropic Magnetoresistive:Single-domain thin-film elements serve legacy internal-combustion crankshaft applications where proven reliability outweighs sensitivity requirements.
- Others:Colossal and extraordinary magnetoresistive variants occupy niche research instrumentation with limited commercial traction.
Volume sits with Giant Magnetoresistive; growth tilts toward Tunnel Magnetoresistive.
Application:
End-use specifications fragment across incompatible certification regimes, with automotive ISO 26262 documentation burdens diverging sharply from FDA device classification timelines.
- Automotive:Battery management and motor commutation systems now specify fused sensing-power architectures with silicon carbide gate drivers. Volkswagen, BMW, and Hyundai centralize procurement authority at headquarters, forcing tier-two vendors to qualify through platform-level contracts rather than individual module design wins.
- Industrial Automation:Collaborative robot manufacturers in Japan and South Korea source high-resolution encoders for force-feedback joints, with EU Green Deal carbon-accounting requirements favoring magnetoresistive alternatives over Hall-effect sensors.
- Consumer Electronics:SPI and I2C digital outputs displace analog configurations, simplifying microcontroller integration for smartphone and wearable manufacturers.
- Medical Devices:EU MDR conformity requirements tighten electromagnetic compatibility testing burdens, compressing certification timelines for implantable and diagnostic equipment categories.
Revenue concentrates in Automotive; steepest expansion trajectory emerges in Industrial Automation.
End User:
Defense and aerospace procurement operates on qualification-heavy timelines distinct from commercial healthcare and telecommunications cycles.
- Defense:Harsh-environment packaging specifications for armored vehicle navigation systems prioritize reliability over cost, with proprietary ceramic housings dominating.
- Healthcare:FDA device classification rules and EU MDR requirements impose parallel biocompatibility and electromagnetic compatibility testing burdens on diagnostic and therapeutic equipment.
- Aerospace:FAA certification timelines for flight control position sensing extend 24-36 months, privileging established suppliers with documented failure-mode libraries.
- Telecommunications:Base station antenna positioning modules demand moderate precision at aggressive cost points, with Chinese OEMs driving specification consolidation.
Contract value peaks in Defense; volume scales fastest in Healthcare.
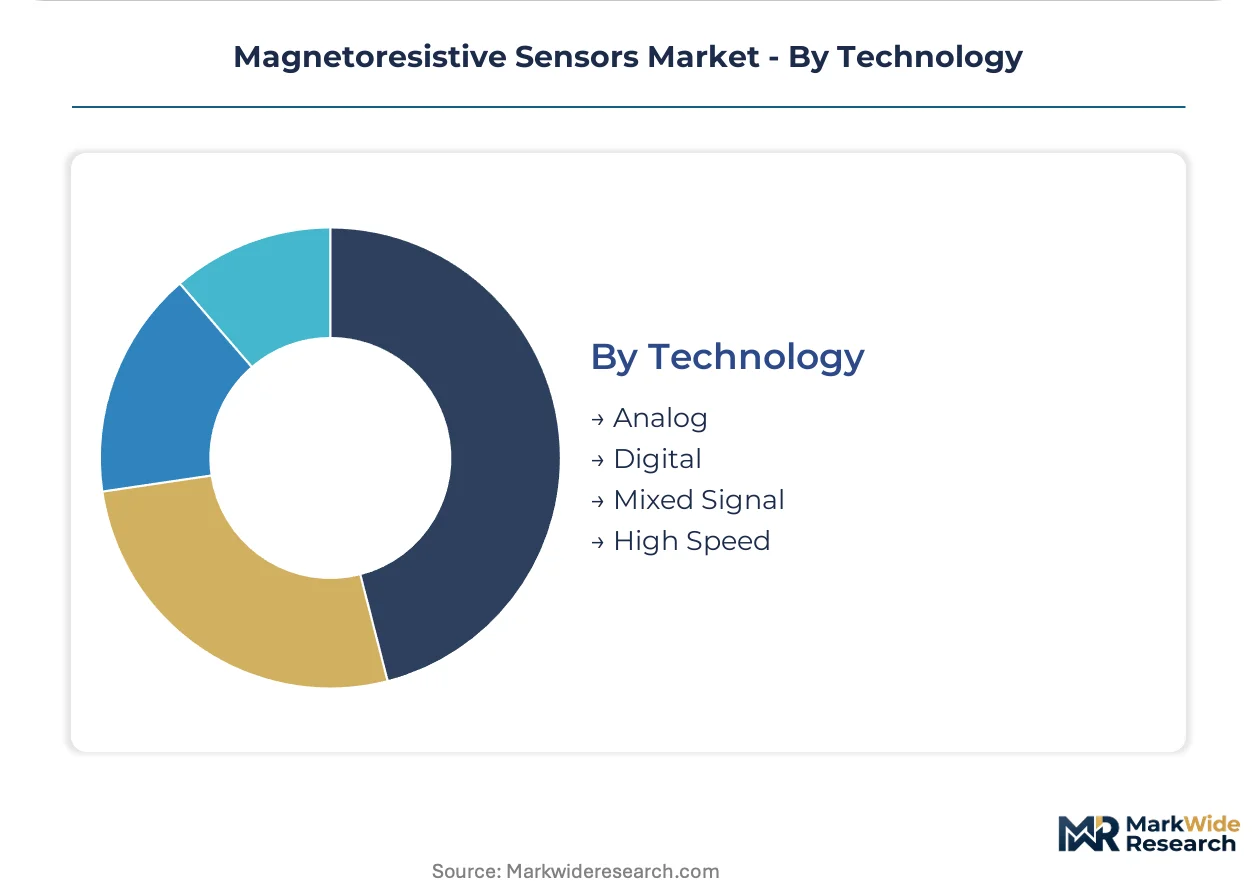
Technology:
Interface selection determines design cycle length and microcontroller compatibility, with digital migration accelerating in cost-sensitive consumer segments.
- Analog:Continuous voltage output retains volume leadership in automotive wheel-speed detection where legacy module architectures resist redesign.
- Digital:SPI and I2C protocols gain ground in consumer electronics and industrial IoT deployments, collapsing board space requirements and reducing electromagnetic interference susceptibility.
- Mixed Signal:On-chip ADC integration serves medical imaging equipment requiring simultaneous high resolution and noise immunity.
- High Speed:Sub-microsecond response specifications address rare event detection in particle physics instrumentation and specialized defense applications.
Shipment volume favors Analog; design win momentum shifts toward Digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Special Economic Zone drives magnetoresistive sensor concentration through semiconductor packaging tax holidays and bonded logistics facilities. German automotive electronics clusters around Munich and Stuttgart anchor European demand for high-temperature sensor modules. Japanese precision equipment manufacturers in Nagoya and Osaka sustain premium encoder production for robotics applications.
United States
NHTSA functional safety mandates for steering-angle and pedal-position modules compel tier-one suppliers to upgrade magnetoresistive array specifications under ISO 26262 documentation requirements. FDA device classification rules and FCC electromagnetic compatibility standards impose parallel testing burdens on diagnostic equipment manufacturers. Detroit's automotive supplier corridor concentrates procurement authority for battery-electric vehicle platforms.
Germany
EU Green Deal industrial benchmarks favor magnetoresistive sensors over Hall-effect alternatives with lower embodied energy across automotive supply chains. KBA type-approval requirements for electric powertrain components tighten performance validation timelines. Stuttgart's tier-one electrification programs specify fused sensing-power architectures with silicon carbide gate drivers as baseline requirements.
China
MIIT automotive semiconductor localization targets accelerate domestic magnetoresistive sensor foundry investments for electric vehicle motor commutation systems. Dual carbon goals under MEE supervision reshape procurement toward low-carbon magnetic thin-film deposition processes. Yangtze River Delta packaging houses scale commodity anisotropic sensor output for legacy internal-combustion applications.
Japan
METI's robotics and factory automation initiatives channel R&D subsidies toward high-resolution encoder development for collaborative robot force-feedback joints. PMDA medical device quality management standards extend certification timelines for implantable sensor applications. Osaka-based precision equipment manufacturers anchor tunnel magnetoresistive production for industrial automation.
South Korea
MFDS medical device registration requirements and KSA industrial standards shape electromagnetic compatibility testing for healthcare-grade sensors. Government-backed semiconductor clusters in Yongin and Pyeongtaek concentrate thin-film magnetic materials R&D for automotive and consumer electronics integration. Hyundai Motor Group's platform-level procurement centralization forces component suppliers to qualify through headquarters contracts.
Magnetoresistive Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive electrification consolidating procurement authority at OEM headquarters. The vendor base organizes into three tiers: diversified semiconductor conglomerates bundling sensing with power platforms, pure-play magnetic sensor specialists defending niche resolution specifications, and Asian packaging houses competing on cost-scalable wheel-speed modules. Competitive moves concentrate on sensor-power fusion architectures and foundry capacity reservations for specialized thin-film deposition.
Among diversified semiconductor conglomerates, Infineon Technologies AG and STMicroelectronics N.V. occupy positions exemplifying the bundled sensing-power platform archetype. Allegro MicroSystems, Inc. represents the pure-play specialist tier with proprietary packaging expertise. TDK Corporation anchors the magnetic materials vertical, extending sensor portfolios through thin-film R&D intensity.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Allegro MicroSystems, Inc. |
| TDK Corporation |
| NVE Corporation |
| Honeywell International Inc. |
| Asahi Kasei Microdevices Corporation |
| STMicroelectronics N.V. |
| TE Connectivity Ltd. |
| Melexis NV |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Germany's automotive electronics corridor maintain pricing discipline through captive thin-film deposition capacity, insulating premium tunnel magnetoresistive tiers from commodity anisotropic erosion while Chinese packaging houses absorb margin compression in legacy wheel-speed modules.
Pricing Analysis
Short lead-time premiums for tunnel magnetoresistive arrays now command substantial markups over standard 18-24 month delivery schedules. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified automotive-grade modules from industrial encoder specifications and consumer electronics spot volumes. Pricing pressure stems from Yangtze River Delta packaging houses scaling commodity anisotropic output for legacy internal-combustion applications. Tier-one automotive procurement teams exhibit lowest price sensitivity due to platform-level contract consolidation, while consumer electronics buyers drive aggressive cost negotiation.
Supply Chain Analysis
Reverse-logistics flows for failed automotive-grade sensors remain underdeveloped, with most tier-one suppliers treating warranty returns as write-offs rather than refurbishment feedstock. Geographic concentration centers on Germany, Japan, and China for specialized magnetic thin-film deposition, with Munich-Stuttgart clusters anchoring premium automotive qualification. Raw material dependencies draw from cobalt and nickel ferromagnetic thin films, MgO barrier substrates, and proprietary ceramic packaging compounds. Single-source vulnerability pervades sputtering equipment with 18-24 month lead times. Distribution runs through direct OEM platform contracts and tier-one module supplier integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints and ISO 26262 documentation burdens are forcing tier-two sensor vendors into distressed exits, creating acquisition opportunities for balance-sheet-strong conglomerates capable of platform-level contract qualification.
For Market Incumbents: Deepen backward integration into specialized magnetic thin-film deposition to secure captive supply against 18-24 month equipment lead times. Accelerate sensor-power fusion architecture development with silicon carbide gate driver bundling to defend against Hall-effect substitution in battery management systems. Concentrate R&D spending on picotesla-resolution tunnel magnetoresistive platforms where premium pricing persists. For New Entrants and Emerging Players: EU Green Deal industrial benchmarks in Europe open a window for low-carbon magnetic thin-film deposition specialists to displace incumbent Hall-effect suppliers in carbon-accounting-sensitive automotive supply chains. Target industrial automation encoder segments in Japan and South Korea where collaborative robot force-feedback joint specifications favor high-resolution alternatives. Pursue digital interface migration as primary go-to-market angle, offering SPI and I2C outputs that collapse customer design cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play magnetic sensor specialists with proprietary packaging expertise and existing automotive qualification libraries in Germany and Japan. Long-term viability hinges on tunnel magnetoresistive technology migration and sensor-power fusion platform consolidation. Monitor foundry equipment order backlogs and tier-one OEM platform contract award announcements as inflection indicators for capacity-constrained supply dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thin-Film Deposition | Captive sputtering capacity insulates margin from 18-24 month equipment lead times at specialized foundries. |
| Sensor-Power Fusion Platform Development | Bundling magnetoresistive sensing with silicon carbide gate drivers collapses board space for Volkswagen-BMW electrification programs. |
| EU MDR Conformity Pathway Investment | Expanded notified body audit scope preparation compresses certification timelines for implantable medical device categories. |
| Digital Interface Migration | SPI and I2C output adoption accelerates design wins in consumer electronics microcontroller integration. |
| Platform-Level Contract Qualification | Direct OEM headquarters relationships bypass tier-two module supplier disintermediation in Hyundai-BMW procurement centralization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tier-one automotive procurement directors, thin-film deposition process engineers, magnetic sensor R&D leads, and medical device quality managers combined with NHTSA safety mandate documentation, EU MDR conformity databases, and semiconductor equipment order backlogs. Bottom-up segment sizing triangulated against top-down automotive production and industrial automation capital expenditure aggregates.
Granularity-level modeling addressed product type splits across giant, tunnel, and anisotropic magnetoresistive architectures; application segmentation spanning automotive electrification, industrial automation, consumer electronics, and medical devices; technology differentiation between analog, digital, and mixed-signal interfaces; and geographic production cluster concentration. CAGRs derived from segment-level volume and value build-ups across the analysis window, with automotive battery-electric vehicle platform penetration and collaborative robot encoder adoption serving as primary demand elasticity inputs.
The model assumes a particular technology adoption path; alternative pathways for tunnel magnetoresistive displacement of Hall-effect sensors in cost-sensitive automotive applications would alter the outlook. Forecasts reflect assumptions regarding foundry capacity expansion timelines, ISO 26262 documentation burden evolution, and raw material price stabilization. Practitioners should monitor NHTSA rulemaking announcements, EU Green Deal carbon-accounting implementation schedules, and Chinese MIIT semiconductor localization subsidy disbursements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Smart Glove Market