
 Ring Laser Gyroscope Market | 2026-2036
Ring Laser Gyroscope Market Size, Share, and Industry Trends Forecast 2026-2036
Ring Laser Gyroscope Market Intelligence
Software-defined inertial compensation is repositioning how ring laser gyroscope vendors package value, shifting revenue from hardware-only sales to subscription-based calibration and firmware-update models. Honeywell International Inc. leverages its captive aerospace channel to bundle gyroscope maintenance with avionics overhaul cycles. Thales Group anchors European defense demand through sovereign navigation programs in France and neighboring NATO markets. Safran Electronics & Defense differentiates via dual-use product lines that serve both military guidance and commercial space launchers.
A ring laser gyroscope measures angular rotation by detecting phase shifts between counter-propagating laser beams within a closed optical cavity, achieving bias stability below 0.001 degrees per hour in strategic-grade configurations. The device serves as the inertial reference for platforms where GPS denial or jamming renders satellite navigation unreliable. Closed-loop product architectures command the deepest margin pools due to thermal compensation complexity and hermetic sealing requirements. Solid-state technology leads unit shipments, though optical interferometry variants are gaining traction in satellite attitude control where radiation tolerance matters. Aerospace systems applications absorb the largest revenue share, driven by fighter jet modernization and hypersonic vehicle programs.
ITAR and EAR frameworks in the United States restrict ring laser gyroscope exports based on bias performance thresholds, fragmenting supplier access to allied defense markets. The EU Green Deal and associated CSRD reporting obligations are pressing commercial aviation integrators to document supply chain emissions from precision optical manufacturing. Japan's METI coordinates domestic gyroscope development through JIS standards that align with U.S. military qualification protocols. Stakeholders must monitor how emerging quantum inertial sensors alter procurement specifications before committing to multi-year ring laser gyroscope production investments.
Market Dynamics
Defense procurement programs across NATO member states are expanding ring laser gyroscope integration into next-generation missile guidance platforms, while software-defined inertial compensation is repositioning how vendors package value through subscription-based calibration models.
Growth Catalysts
- ITAR-funded modernization:The Department of Defense sustains multi-year contracts for strategic-grade inertial measurement units, creating stable demand visibility for precision optical manufacturers.
- Hypersonic vehicle development:Fighter jet modernization and hypersonic programs require closed-loop architectures with thermal compensation complexity that commands premium positioning.
- Commercial space expansion:Satellite attitude control applications are gaining traction for optical interferometry variants where radiation tolerance matters.
Market Restraints
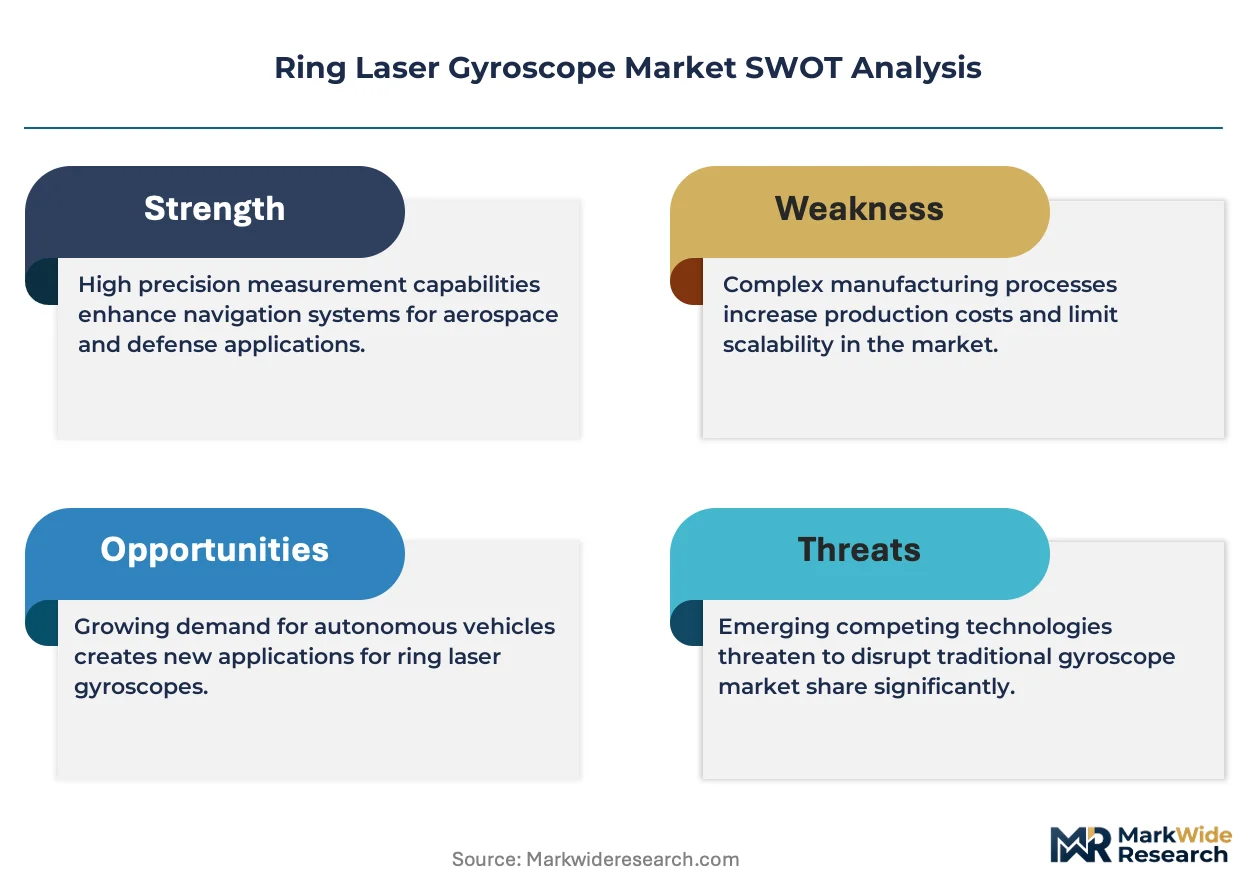
- Export control fragmentation:ITAR and EAR frameworks restrict exports based on bias performance thresholds, limiting supplier access to allied defense markets.
- Hermetic sealing cost concentration:Closed-loop product architectures require specialized thermal compensation and hermetic sealing that concentrates production among qualified vendors.
- Quantum sensor substitution threat:Emerging quantum inertial sensors are altering procurement specifications before multi-year production investments conclude.
Strategic Opportunities
- CSRD compliance services:The EU Green Deal and associated CSRD reporting obligations press commercial aviation integrators to document supply chain emissions from precision optical manufacturing.
- JIS-aligned Japanese demand:Japan's METI coordinates domestic development through standards that align with U.S. military qualification protocols, creating dual-qualification pathways.
- Firmware-update revenue streams:Subscription-based calibration models are displacing hardware-only sales, enabling recurring revenue from installed strategic-grade units.
Industry Challenges
- Skill concentration in optical cavity fabrication:Bias stability below 0.001 degrees per hour requires specialized expertise in closed optical cavity production that remains scarce.
- Dual-use certification complexity:Vendors must navigate divergent military and commercial space qualification timelines simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ring Laser Gyroscope Market |
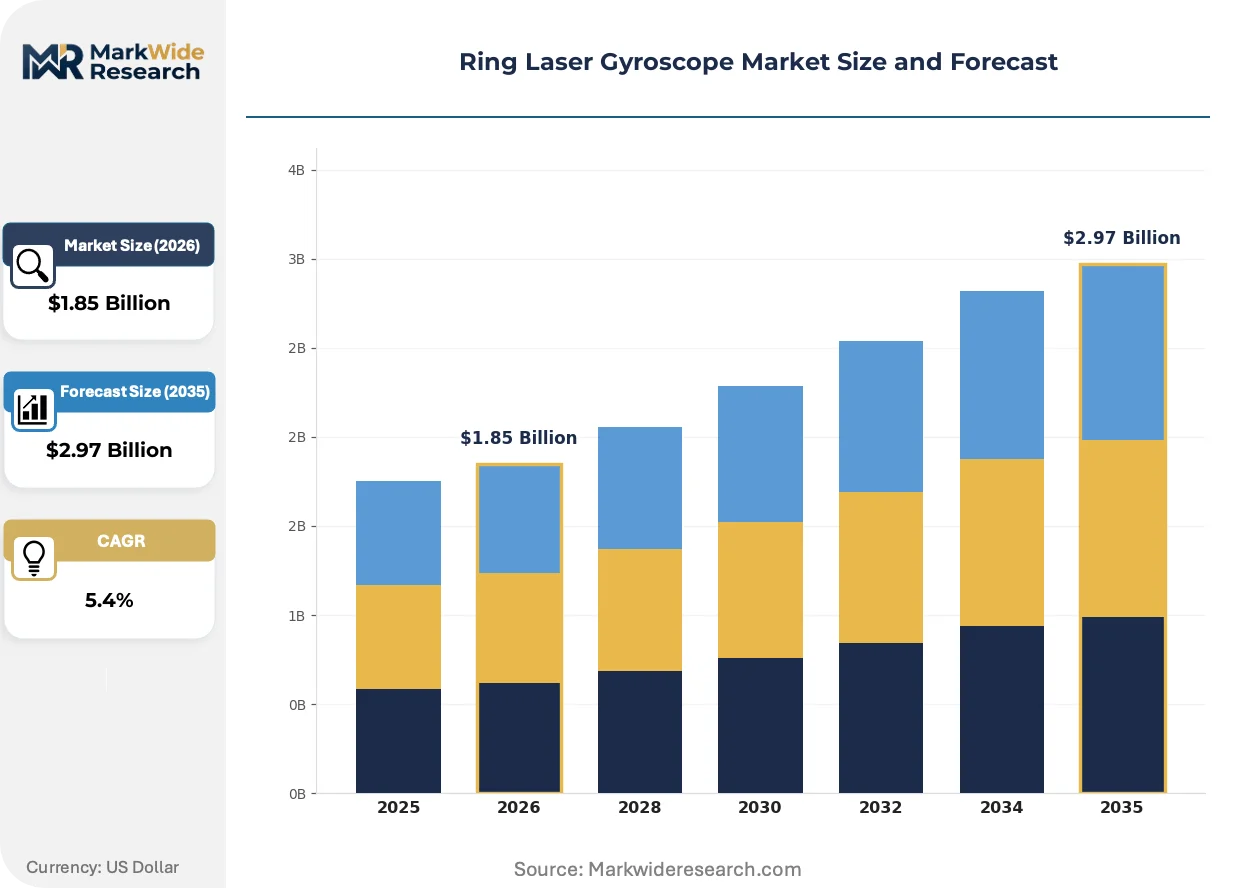
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-Loop, Open-Loop, Fiber Optic, Miniature, Modular Technology: Solid-State, Semiconductor, MEMS, Optical Interferometry, Glass Laser Application: Navigation Systems, Guidance Control, Inertial Measurement, Autonomous Vehicles, Aerospace Systems End User: Military Defense, Commercial Aviation, Marine Navigation, Space Exploration |
| Companies Covered | Teledyne CDL, Inc., Thales Group, Honeywell International Inc., Lockheed Martin Corporation, Mitsubishi Precision Co., Ltd, Northrop Grumman Corporation, Kearfott Corporation, Raytheon Technologies Corporation, Safran Electronics & Defense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ring Laser Gyroscope Market Strategic Shifts & Innovations
Software-defined architectures are compressing traditional hardware value chains while regulatory frameworks fragment supplier access across defense-aligned markets.
Integrated photonics is automating phase-shift detection through silicon-based optical circuits that reduce thermal drift compensation overhead. Missile guidance platform integrators are adopting these solid-state configurations for production-scale deployment. The technology is automating calibration workflows that previously required manual intervention between overhaul cycles.
CSRD disclosure mandates now require commercial aviation suppliers to document embodied emissions from precision optical manufacturing processes. Integrators must trace carbon intensity through hermetic sealing and specialty gas supply chains. European aerospace clusters are responding by consolidating supplier qualification around ISO 14001-aligned environmental management systems.
Defense buyers are compressing switching cycles for inertial navigation units as GPS denial scenarios proliferate in contested electromagnetic environments. Platform integrators now unbundle gyroscope maintenance from airframe overhaul schedules to sustain mission readiness. This pattern concentrates most visibly in U.S. Department of Defense multi-year contracting structures.
Ring Laser Gyroscope Market Segmentation
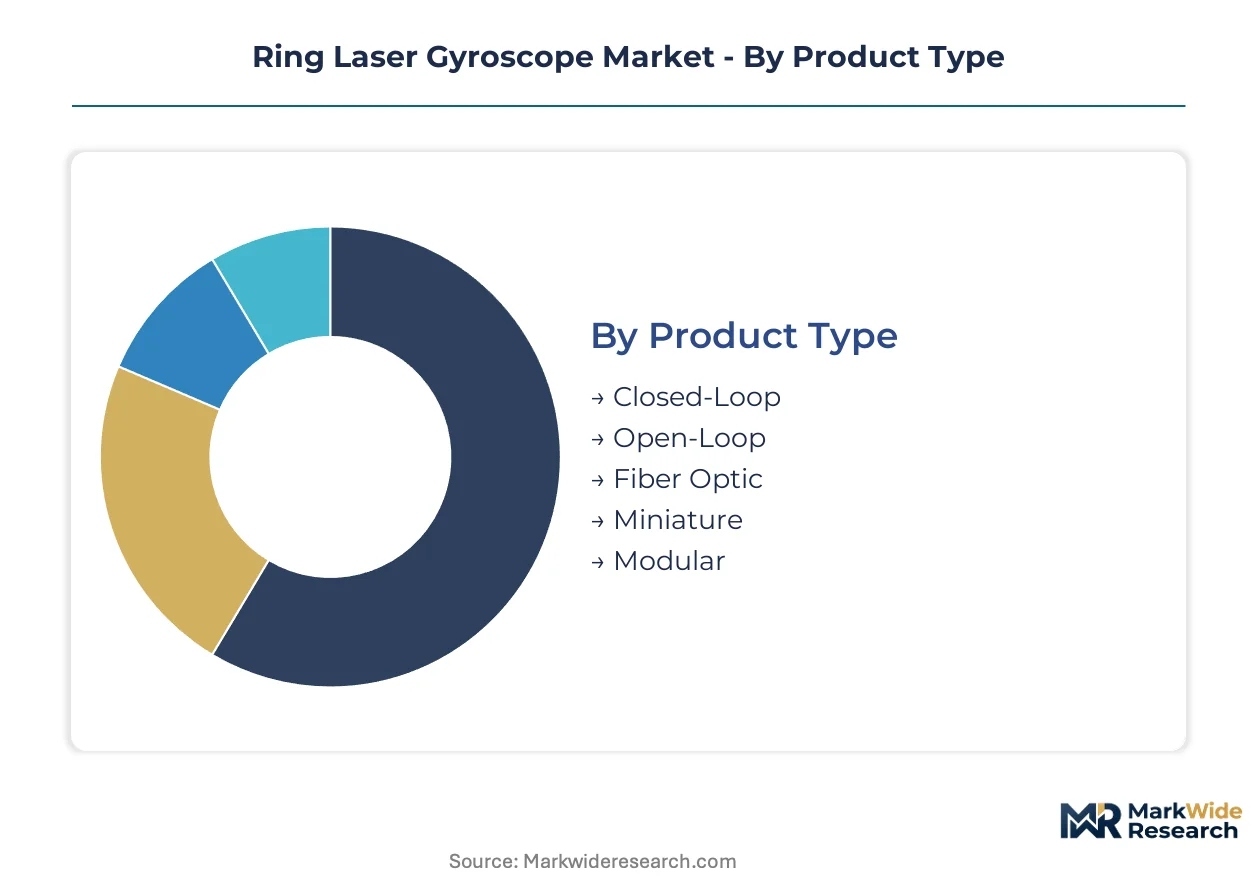
Ring laser gyroscope procurement patterns diverge sharply across product architectures and end-use qualifications. Defense buyers prioritize bias stability thresholds that civilian integrators rarely require, creating parallel demand tracks with distinct certification timelines.
Product Type:
Capital intensity concentrates in closed-loop architectures requiring hermetic sealing and thermal compensation infrastructure that open-loop alternatives bypass entirely.
- Closed-Loop:Hermetically sealed cavities with active thermal stabilization achieve bias stability below 0.001 degrees per hour for strategic-grade navigation. The U.S. Department of Defense sustains multi-year contracting for these configurations in missile guidance platforms.
- Open-Loop:Simplified optical paths without active feedback loops trade precision for cost reduction in commercial aviation attitude reference systems. Commercial aviation integrators in Europe favor these units for CSRD-aligned fleet modernization where extreme precision is secondary.
- Fiber Optic:Coil-based sensing elements reduce optical cavity fabrication complexity.
- Miniature:Compact form factors targeting UAV and small satellite constraints.
- Modular:Swappable subassemblies for field-level maintenance in distributed platforms.
Most installed capacity flows through Closed-Loop. Expansion is steepest in Miniature.
Technology:
Manufacturing yield curves favor solid-state processes over glass laser alternatives requiring manual optical polishing expertise.
- Solid-State:Integrated photonics automates phase-shift detection through silicon-based circuits, compressing calibration overhead and enabling production-scale deployment for missile guidance integrators.
- Optical Interferometry:Radiation-hardened variants serve satellite attitude control where cosmic ray tolerance outweighs atmospheric systems requirements. Japanese METI-coordinated programs align JIS qualification protocols with these specifications for dual-use commercial space launchers.
- Semiconductor:Foundry-compatible fabrication paths for high-volume consumer inertial sensing.
- MEMS:Microelectromechanical alternatives displacing optical methods in cost-constrained navigation.
- Glass Laser:Traditional helium-neon cavities requiring specialized optical craft labor.
Production volume concentrates in Solid-State. Technology transition is accelerating fastest in Optical Interferometry.
Application:
Platform integration complexity varies from discrete component sales to embedded subsystem contracts with multi-decade support obligations.
- Aerospace Systems:Fighter jet modernization and hypersonic vehicle programs demand closed-loop thermal compensation that commands premium positioning and multi-year qualification cycles.
- Navigation Systems:GPS-denied contingency planning across NATO member states is expanding ring laser gyroscope integration into next-generation platforms requiring sovereign inertial reference.
- Guidance Control:Terminal-phase precision for ballistic and cruise missile architectures.
- Inertial Measurement:Six-degree-of-freedom motion tracking for platform stabilization.
- Autonomous Vehicles:Dead-reckoning backup for terrestrial navigation in signal-degraded environments.
Revenue concentration sits with Aerospace Systems. Procurement momentum is building fastest in Navigation Systems.
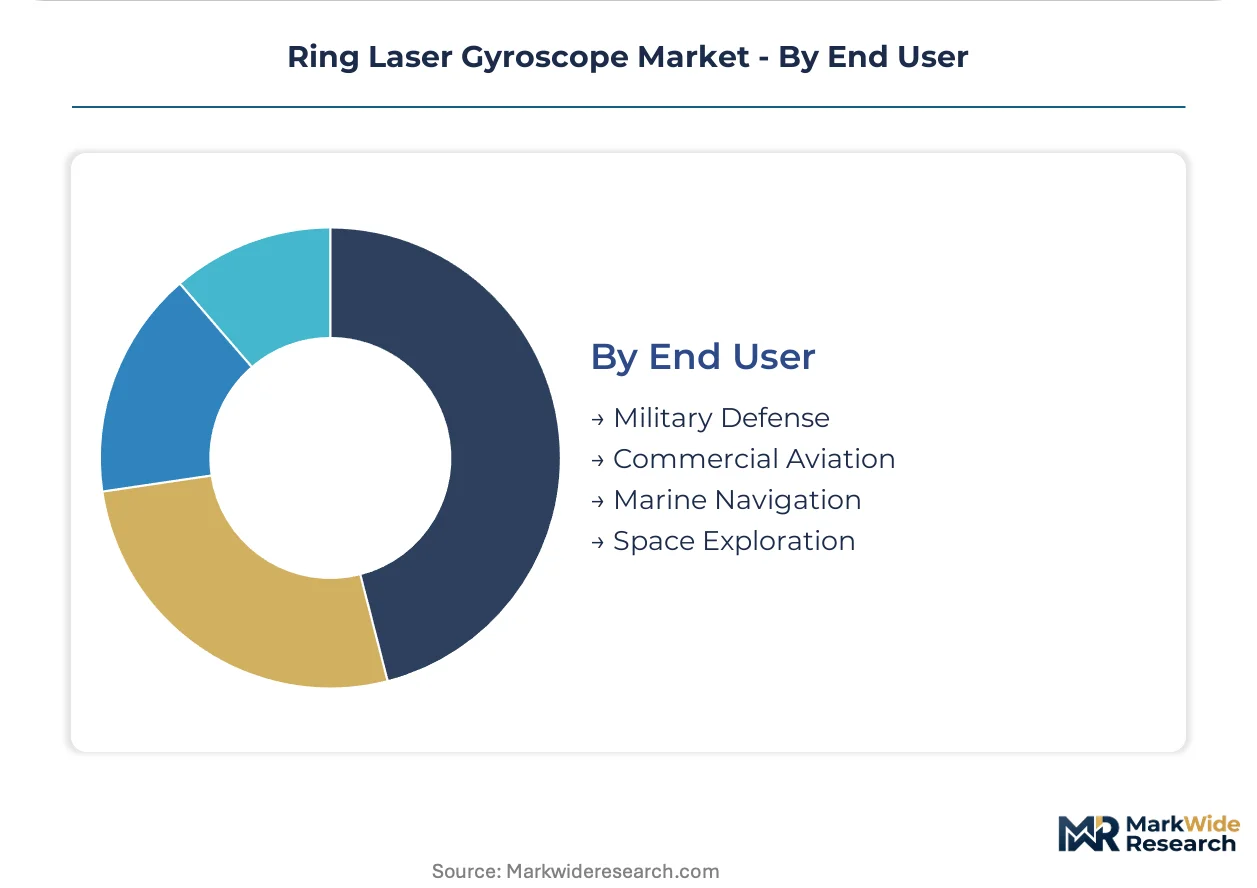
End User:
Qualification protocols diverge between ITAR-governed defense channels and commercial aviation certification timelines.
- Military Defense:ITAR and EAR frameworks restrict exports based on bias performance thresholds, fragmenting supplier access and concentrating production among qualified vendors with security clearance infrastructure.
- Commercial Aviation:EU Green Deal CSRD obligations now require documented supply chain emissions from precision optical manufacturing, consolidating supplier qualification around ISO 14001-aligned environmental management systems.
- Marine Navigation:Submarine inertial navigation requiring extended submerged operation without external reference.
- Space Exploration:Launch vehicle guidance and satellite attitude determination with radiation tolerance specifications.
Contract value concentrates in Military Defense. Sustainability-driven procurement is expanding most quickly in Commercial Aviation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where ITAR compliance costs diverge from European dual-use certification burdens, creating arbitrage opportunities for qualified vendors. The United States retains sovereign manufacturing for strategic-grade units while allied nations develop parallel supply chains under NATO standardization protocols.
United States
The Department of Defense sustains multi-year contracts for closed-loop inertial measurement units with bias stability below 0.001 degrees per hour. ITAR and EAR frameworks restrict exports based on performance thresholds, fragmenting supplier access to foreign defense markets. Arizona and Florida host concentrated aerospace clusters where Honeywell and Northrop Grumman maintain captive production for missile guidance platforms.
France
Safran Electronics & Defense anchors European sovereign navigation programs through dual-use product lines serving military guidance and commercial space launchers. The EU Green Deal and CSRD reporting obligations press integrators to document supply chain emissions from precision optical manufacturing. The Paris-Saclay aerospace cluster consolidates supplier qualification around ISO 14001-aligned environmental management systems for next-generation fighter integration.
Japan
METI coordinates domestic gyroscope development through JIS standards that align with U.S. military qualification protocols, creating dual-certification pathways for export. Commercial space expansion drives demand for radiation-hardened optical interferometry variants in satellite attitude control. The Nagoya-Tokyo industrial corridor concentrates optical cavity fabrication expertise for strategic-grade navigation systems.
Germany
Bundeswehr modernization programs integrate ring laser gyroscopes into precision strike systems under NATO interoperability mandates. REACH and RoHS regulations impose material disclosure requirements on hermetic sealing and specialty gas supply chains. The Munich-Stuttgart aerospace axis hosts subsystem integrators serving both domestic defense procurement and EU collaborative armament programs.
United Kingdom
Strategic Defence Review commitments prioritize sovereign inertial navigation for GPS-denied operational scenarios across Royal Navy and Royal Air Force platforms. UK export control regulations mirror ITAR thresholds while allowing streamlined intra-NATO technology transfer. The Bristol-Cambridge precision engineering corridor supports Thales Group navigation system integration for European missile architectures.
Ring Laser Gyroscope Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with defense-qualified vendors commanding premium positioning in strategic-grade procurement while commercial aviation integrators source through consolidated subsystem tiers. The vendor base concentrates among ITAR-cleared entities with security clearance infrastructure, creating high barriers for new qualification. Three archetypes dominate: captive aerospace divisions, sovereign defense electronics specialists, and dual-use navigation component suppliers. Competitive dynamics center on multi-year contracting capture and firmware-update subscription models that displace hardware-only revenue.
Among U.S.-based defense conglomerates, Honeywell International Inc., Lockheed Martin Corporation, and Northrop Grumman Corporation occupy positions within the captive aerospace tier, leveraging established Department of Defense relationships. European representation concentrates through Thales Group and Safran Electronics & Defense, exemplifying sovereign navigation specialists with dual-use commercial space exposure. Japanese precision manufacturers including Mitsubishi Precision Co., Ltd. represent METI-coordinated development aligned with NATO qualification protocols.
| Leading Market Players |
|---|
| Teledyne CDL, Inc. |
| Thales Group |
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| Mitsubishi Precision Co., Ltd |
| Northrop Grumman Corporation |
| Kearfott Corporation |
| Raytheon Technologies Corporation |
| Safran Electronics & Defense |
| Others |
Cost & Logistics Intelligence
Captive aerospace channel integration by Honeywell and Northrop Grumman anchors both supply security and pricing power through multi-year Department of Defense contracting structures that bypass spot-market volatility. This vertical control over hermetic sealing and thermal compensation infrastructure locks in premium positioning for strategic-grade units while fragmenting access for non-cleared competitors.
Pricing Analysis
Direct-to-OEM discounts dominate procurement for closed-loop strategic-grade units, with the Department of Defense sustaining multi-year contracts that compress distributor margins entirely. Three-tier pricing structure across ITAR-restricted strategic, dual-use commercial, and open-loop aviation grades reflects certification burden and bias stability thresholds. Cost compression in open-loop commercial aviation tiers is intensifying because CSRD disclosure mandates add compliance overhead without commensurate performance premiums. Commercial aviation integrators exhibit highest price sensitivity, while defense procurement officers prioritize mission assurance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense demand through Arizona and Florida aerospace clusters where Honeywell and Northrop Grumman maintain captive production. Hermetic sealing draws from specialized glass-to-metal feedthrough suppliers concentrated in the United States, Japan, and Germany. High-purity helium-neon gas mixtures and precision optical polishing equipment rest on limited qualified vendor pools. Single-source vulnerability in ITAR-cleared optical cavity fabrication creates chokepoint exposure. Distribution runs through security-cleared subsystem integrators serving missile guidance platform contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITAR modernization funding operates as a regulatory compounder, with multi-year Department of Defense contracts creating demand visibility that outlasts typical procurement cycles.
For Market Incumbents: Cement ITAR compliance infrastructure as a moat against quantum sensor substitution threats by accelerating firmware-update subscription capture. Deepen backward integration into hermetic sealing supply chains to defend margin position against REACH and RoHS material disclosure cost inflation. Prioritize JIS-aligned dual-qualification pathways for Japanese METI-coordinated programs. For New Entrants and Emerging Players: Digital-channel calibration-as-a-service platforms offer the lowest friction entry vector for commercial aviation open-loop segments where CSRD compliance services command premium positioning. Target European commercial aviation integrators consolidating supplier qualification around ISO 14001-aligned environmental management systems. Pursue modular subassembly architectures for UAV and small satellite miniature form factors as the most penetrable white space. For Investors and Strategic Acquirers: Roll-up economics work for ITAR-cleared precision optical manufacturers because security clearance infrastructure creates artificial scarcity that defends pricing power. Five-to-ten-year viability hinges on quantum sensor displacement timelines rather than cyclical defense spending. Watch procurement specification shifts in NATO hypersonic vehicle programs as the critical inflection signal for strategic-grade demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Update Subscription Capture | Recurring revenue from installed strategic-grade units displaces transactional hardware sales for Honeywell and Safran. |
| ITAR Clearance Infrastructure Investment | Security-cleared production capacity fragments supplier access and concentrates contract awards among qualified vendors. |
| JIS-NATO Dual-Qualification Pathway | Japanese METI-coordinated development aligns with U.S. military protocols for commercial space launcher access. |
| CSRD Compliance Service Layer | European aerospace clusters consolidate supplier qualification around ISO 14001-aligned environmental management systems. |
| Hermetic Sealing Backward Integration | Captive supply of glass-to-metal feedthroughs defends margin position against REACH material disclosure requirements. |
Research Approach
Bottom-up aerospace systems and navigation platform modeling reconciled against top-down precision optical manufacturer capacity tracking forms the analytical core. Primary interviews with missile guidance platform engineers, defense procurement officers, commercial aviation subsystem integrators, and hermetic sealing specialists combined with secondary validation from Department of Defense contract announcements, FAA certification databases, EU CSRD disclosure filings, and JIS standard documentation. Top-down customs data and trade flow analysis triangulated against bottom-up production capacity surveys.
Input-output matrices map closed-loop versus open-loop unit economics across ITAR-restricted, dual-use, and commercial certification tiers. Segmentation dimensions include product architecture, technology type, application platform, and end-user qualification protocol across the analysis window. CAGRs derive from production capacity expansion schedules, defense procurement pipeline visibility, and commercial space launch cadence projections. Hypersonic vehicle program timelines and quantum sensor development milestones inform scenario-weighted outputs.
ITAR regulatory reinterpretation, quantum inertial sensor technical maturation, and NATO defense spending allocation shifts are the dominant revision risks. Forecasts reflect base-case assumptions regarding sovereign navigation program continuity and GPS-denied contingency planning persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Silicon Photonics Wafer Market
Optical Components
Optical Film Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Global Optical Measurement Market
Optical Components
Photosensitive Glass Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Europe Tunable Laser Market
Optical Components
North America Optical Film Market
Optical Components
Global Adaptive Optics Market
Optical Components
Optical Cross Connect Market
Optical Components
North America Tunable Laser Market
Optical Components
Diode Laser Module Market