
 Accelerometer and Gyroscope Market | 2026-2036
Accelerometer and Gyroscope Market Size, Share, and Industry Trends Forecast 2026-2036
Accelerometer and Gyroscope Market Intelligence
Automotive Electronics Council's AEC-Q100 stress test qualification is redrawing the supplier landscape for the automotive sector. This standard mandates rigorous reliability testing, creating barriers for non-compliant component manufacturers. Robert Bosch GmbH dominates the automotive sensor segment through its deep integration with vehicle systems. STMicroelectronics N.V. specializes in MEMS sensors for consumer and automotive markets, while Analog Devices, Inc. leverages its precision technology for industrial and aerospace systems.
Accelerometers and gyroscopes are inertial sensors that measure linear acceleration and angular velocity, respectively. Many modern devices utilize MEMS technology, where microscopic moving structures on a silicon chip detect motion changes. These components are essential for orientation, navigation, and stabilization in various systems. The consumer electronics application segment, driven by smartphone manufacturers, represents the largest volume, while industrial automation offers higher margins for specialized, durable sensors.
Regulatory frameworks create distinct performance and reliability requirements across end-markets. For instance, FAA regulations govern sensor use in aerospace navigation systems in the United States, while CE marking is mandatory for consumer devices in Europe and GB standards apply to automotive components in China. Component selection will increasingly hinge on balancing performance specifications against the power consumption demands of battery-operated devices.
Market Dynamics
The market is defined by a divergence between high-volume consumer electronics and high-reliability sectors like automotive. This tension between cost-driven miniaturization and certified performance creates a bifurcated development and supply path.
Growth Catalysts
- Sensor Fusion Algorithms:Advanced software combining sensor data improves navigation accuracy, driving adoption in robotics and UAVs where precise orientation is critical.
- Industrial IoT Expansion:The growth of smart factories for predictive maintenance creates demand for durable sensors to monitor machinery health and vibration.
- Automotive Safety Mandates:Regulations requiring Electronic Stability Control (ESC) directly mandate gyroscopes, ensuring baseline demand from the automotive sector.
Market Restraints
- MEMS Fabrication Costs:The high capital investment for cleanroom facilities and specialized lithography equipment creates a significant barrier to entry for new manufacturers.
- Inherent Sensor Drift:All inertial sensors suffer from accumulated error over time, requiring complex software compensation or frequent recalibration in precision applications.
- Supply Chain Concentration:Heavy concentration of assembly and testing facilities in China exposes the market to geopolitical tensions and potential logistical disruptions.
Strategic Opportunities
- Wearable Medical Devices:Integrating medical-grade sensors into wearables for remote patient monitoring and fall detection represents a high-value growth avenue.
- Edge AI Integration:Combining low-power sensors with on-device machine learning enables real-time analysis for gesture recognition and predictive equipment failure alerts.
- Precision Agriculture:Underpenetrated applications in agriculture, especially in markets like Brazil, offer opportunities for sensors on drones and autonomous tractors.
Industry Challenges
- Power Consumption Optimization:A primary engineering challenge is reducing sensor power draw for battery-operated devices like smartphones without compromising sensitivity.
- Complex Qualification Cycles:Achieving certifications like automotive AEC-Q100 or aerospace standards involves extensive, multi-year testing, delaying revenue and adding significant cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accelerometer and Gyroscope Market |
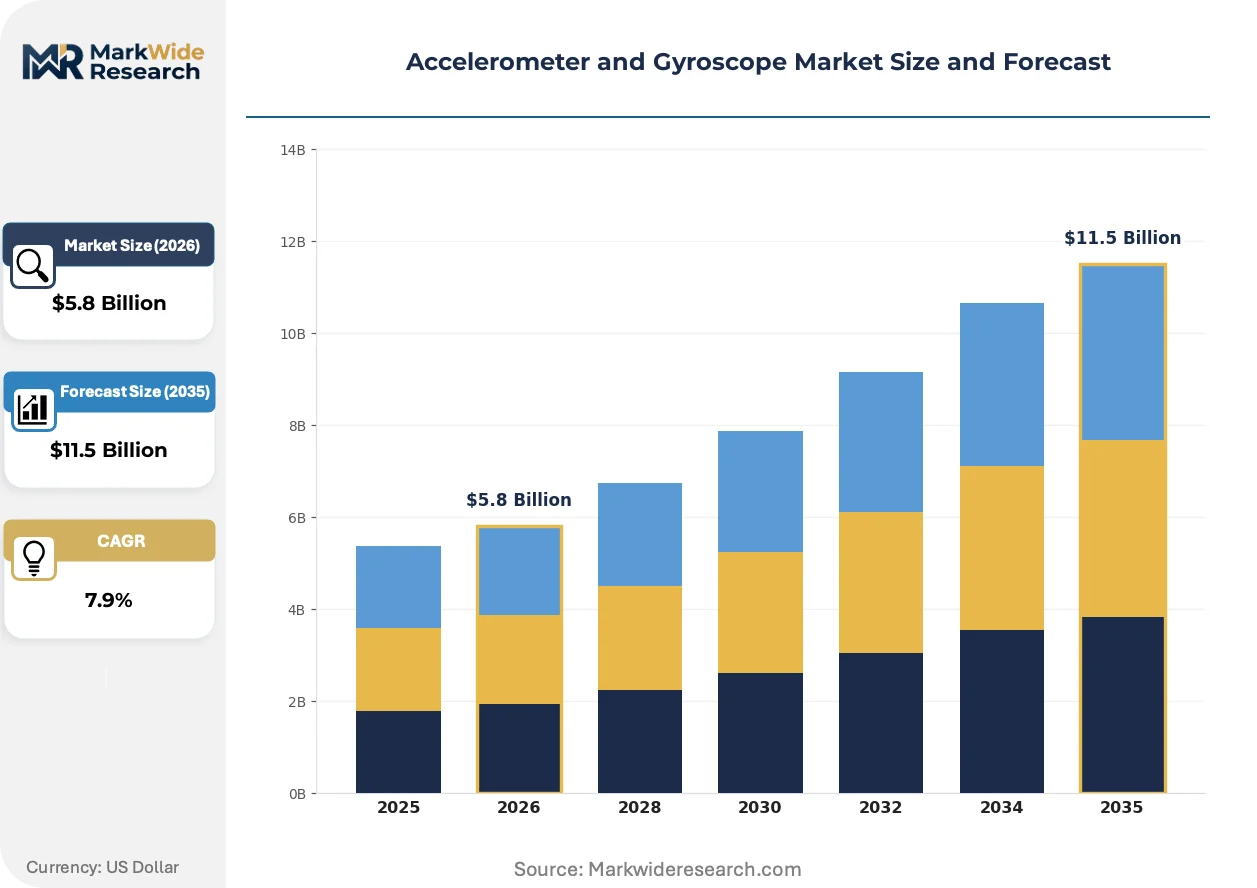
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Capacitive, Piezoelectric, MEMS, Fiber Optic, Resonant, Hall Effect Technology: Analog, Digital, Wireless, Optical, Microelectromechanical, Quantum Application: Consumer Electronics, Aerospace & Defense, Industrial Automation, Sports Instruments, Navigation Systems, Robotics End User: Smartphone Manufacturers, Drone OEMs, Manufacturing Plants, Sports Equipment Companies, Automotive Suppliers, Robotics Firms |
| Companies Covered | Analog Devices, Inc., Honeywell International Inc., STMicroelectronics N.V., Infineon Technologies AG, NXP Semiconductors N.V., Robert Bosch GmbH, Murata Manufacturing Co., Ltd., Texas Instruments Incorporated, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accelerometer and Gyroscope Market Strategic Shifts & Innovations
A shift towards integrated sensor systems and the increasing value of software are redefining product capabilities. The market is moving beyond discrete components to focus on complete, context-aware motion tracking solutions.
Integrated Inertial Measurement Units (IMUs) combine accelerometers and gyroscopes on a single silicon die. Consumer electronics and drone manufacturers are adopting these combo sensors rapidly due to their small footprint. This integration is supplanting the use of separate, single-function components, reducing board space, assembly complexity, and system cost for OEMs.
The European Union's updated General Safety Regulation (GSR) mandates new advanced driver-assistance systems (ADAS). This directly increases the need for high-fidelity inertial sensors for features like intelligent speed assistance. Automotive suppliers must now develop sensors that meet demanding Automotive Safety Integrity Level (ASIL) requirements tied to these safety-critical functions.
A notable change in buying behavior is occurring in industrial and medical equipment design. OEMs are sourcing pre-certified, software-integrated inertial modules instead of raw sensor components. This approach offloads complex calibration and algorithm development, shortening the customer's design cycle. The pattern is most pronounced in Germany's industrial automation sector.
Accelerometer and Gyroscope Market Segmentation
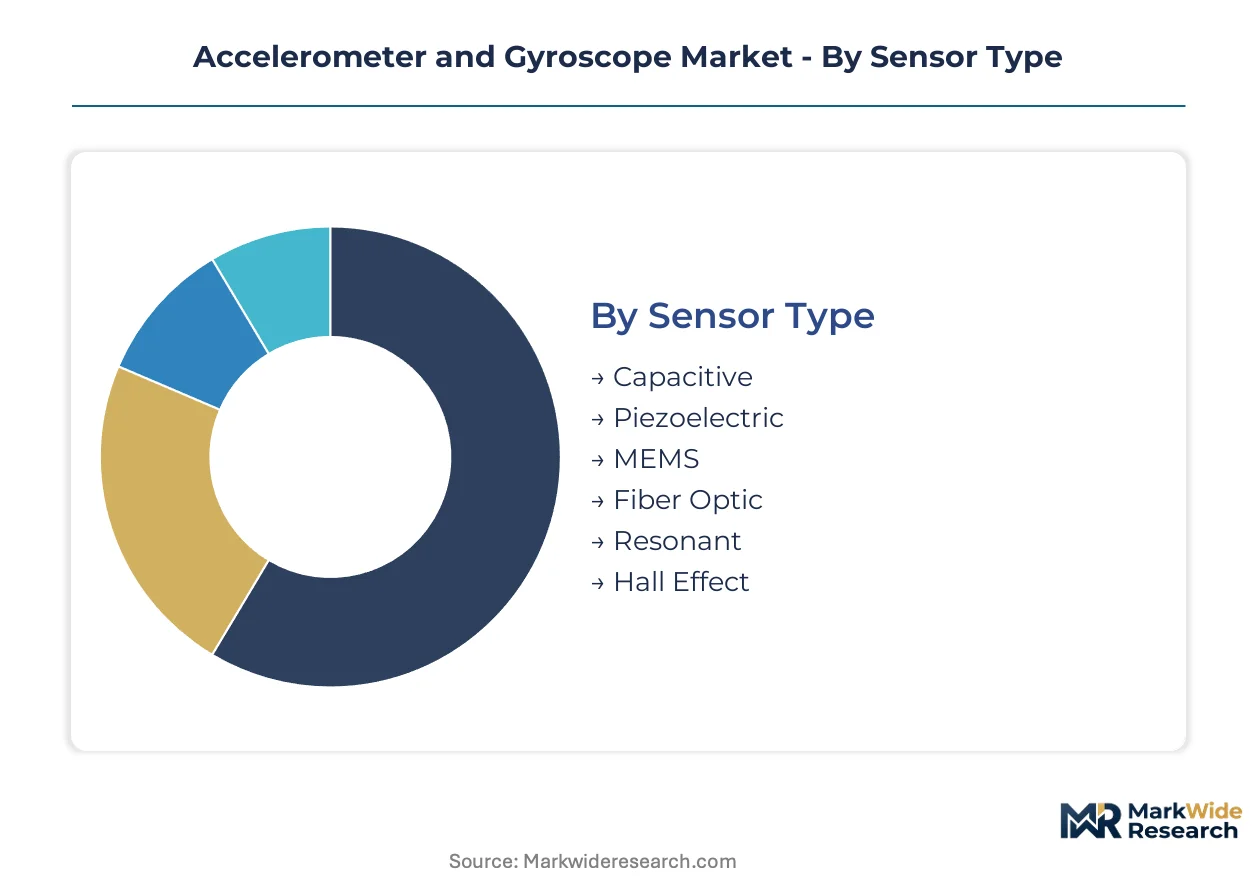
The Accelerometer and Gyroscope Market is intricately segmented, reflecting the diverse technical requirements and end-user demands across various industries. Understanding these segments reveals distinct value propositions and competitive dynamics for component manufacturers and system integrators.
Sensor Type:
The market for accelerometers and gyroscopes exhibits varying degrees of geographic concentration, with certain sensor types seeing localized production hubs while others are globally distributed.
- MEMS:Micro-Electro-Mechanical Systems sensors integrate mechanical and electrical components on a silicon chip, enabling miniature and cost-effective motion detection. Demand concentrates heavily in East Asian consumer electronics manufacturing clusters, driven by smartphone and wearable device integration.
- Capacitive:These sensors detect changes in capacitance caused by seismic mass movement, offering high sensitivity and low power consumption. Adoption is significant in European automotive safety systems, where precision and long-term stability are critical for advanced driver-assistance features.
- Piezoelectric:These sensors generate an electrical charge proportional to applied force, commonly used for vibration monitoring in industrial machinery.
- Fiber Optic:Utilizing light interference for motion sensing, these high-precision sensors serve specialized navigation in aerospace and defense applications.
- Resonant:Resonant sensors measure frequency shifts in a vibrating structure due to inertial forces, finding use in high-stability industrial controls.
- Hall Effect:These magnetic field sensors detect motion indirectly and are employed in simple position sensing for consumer devices.
MEMS commands the established base. The steepest expansion runs through Capacitive sensors.
Technology:
Technology maturity levels dictate adoption cycles, with established methods providing reliability and newer innovations promising enhanced capabilities.
- Microelectromechanical:This technology underpins MEMS sensors, enabling compact, high-performance inertial measurement units on a single silicon die. Demand is driven by the miniaturization trend in consumer electronics and the need for integrated solutions in robotics.
- Digital:Digital output sensors integrate analog-to-digital converters, simplifying system design and reducing noise for OEMs. These are widely adopted in automotive systems globally, where direct digital interfacing improves data integrity and processing efficiency.
- Analog:These sensors provide continuous voltage outputs, requiring external analog-to-digital conversion, still prevalent in cost-sensitive industrial applications.
- Wireless:Wireless sensor technologies facilitate flexible deployment and data transmission, gaining traction in industrial IoT for remote monitoring.
- Optical:Optical sensors use light principles for highly accurate motion detection, primarily deployed in high-precision navigation and scientific instrumentation.
- Quantum:Emerging quantum technologies promise ultra-high precision inertial sensing, currently under research for next-generation defense and navigation systems.
The segment for Analog technology maintains foundational importance, while Microelectromechanical is rapidly gaining market share.
Application:
Market volume distribution across applications reflects varying scale requirements, from mass-produced consumer goods to highly specialized industrial uses.
- Consumer Electronics:This application segment includes smartphones, wearables, and gaming devices, leveraging accelerometers and gyroscopes for user interface, gesture recognition, and activity tracking. High-volume production in China drives cost-effective sensor integration for global brands.
- Industrial Automation:Sensors in this segment monitor machinery health, enable robotics, and guide automated vehicles in factories, demanding durability and precision. Germany's advanced manufacturing sector shows significant demand for robust, specialized inertial sensors.
- Aerospace & Defense:High-reliability sensors are critical for aircraft navigation, missile guidance, and satellite stabilization, adhering to stringent FAA regulations.
- Sports Instruments:Accelerometers track performance metrics in fitness trackers and smart sports equipment, enhancing user data collection.
- Navigation Systems:These applications rely on inertial sensors for dead reckoning and GPS augmentation, ensuring accurate positioning in various environments.
- Robotics:Inertial sensors provide orientation and motion feedback for robotic arms and autonomous mobile robots, crucial for precise control.
High-volume applications are led by Consumer Electronics, with specialized growth emerging in Industrial Automation.
End User:
Customer types range from high-volume manufacturers requiring integrated solutions to specialized firms demanding certified, robust components.
- Smartphone Manufacturers:These OEMs integrate accelerometers and gyroscopes for screen orientation, gaming, and health tracking, driving massive unit volumes. Samsung and Apple, among others, require high-volume, low-cost, and power-efficient MEMS solutions.
- Automotive Suppliers:Companies like Robert Bosch GmbH source sensors for Electronic Stability Control, airbags, and ADAS, demanding AEC-Q100 qualification and ASIL compliance. These suppliers focus on long-term reliability and safety-critical performance for global vehicle production.
- Drone OEMs:Manufacturers of unmanned aerial vehicles utilize inertial sensors for flight stabilization, navigation, and payload control.
- Manufacturing Plants:These end users deploy sensors for condition monitoring, predictive maintenance, and process automation in smart factories.
- Sports Equipment Companies:Firms developing smart sports gear and fitness wearables integrate sensors for activity tracking and performance analysis.
- Robotics Firms:Companies specializing in industrial and service robots use inertial sensors for precise motion control and environmental interaction.
Key strategic customers include Smartphone Manufacturers, with Robotics Firms representing a targeted growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smartphone manufacturers and industrial automation firms drive significant demand for accelerometers and gyroscopes across key global regions. High-volume consumer electronics production centers and advanced manufacturing hubs dictate regional market dynamics. These sectors require both cost-effective and high-precision sensor solutions.
China
Consumer electronics manufacturing and electric vehicle production drive substantial demand for MEMS sensors in China. GB standards regulate automotive components, ensuring quality and safety for local and export vehicle models. Shenzhen's electronics manufacturing cluster integrates these sensors into a vast array of devices, from smartphones to drones.
Germany
Advanced industrial automation and premium automotive manufacturing create strong demand for durable and precise sensors in Germany. The KBA oversees automotive component approvals, emphasizing reliability and safety for vehicle systems. Bavaria's industrial clusters specialize in high-precision sensor development for machinery health monitoring and ADAS applications.
United States
Aerospace and defense applications, alongside industrial IoT, fuel requirements for high-reliability inertial sensors. FAA regulations govern sensor use in aerospace navigation systems, mandating rigorous performance standards. Silicon Valley's technology ecosystem fosters innovation in sensor fusion and edge AI integration.
Japan
Automotive safety systems and robotics applications consistently require high-fidelity accelerometers and gyroscopes. JIS standards guide component manufacturing, promoting quality and interoperability across industrial sectors. The Tokyo-Nagoya corridor hosts significant automotive and robotics R&D, integrating advanced sensor technologies.
South Korea
Smartphone manufacturing and emerging autonomous vehicle development propel demand for compact and efficient MEMS sensors. The Ministry of Food and Drug Safety (MFDS) regulates medical devices, impacting sensor integration in wearables. Seoul's vibrant tech industry focuses on miniaturization and power optimization for consumer electronics.
Accelerometer and Gyroscope Market Key Industry Players
Player mix skews toward established semiconductor manufacturers and specialized sensor technology firms. The market structure exhibits a tiered consolidation, with a few dominant players controlling significant shares in high-volume segments like consumer electronics. Key strategic archetypes include integrated device manufacturers offering broad portfolios and niche specialists focusing on high-precision applications for industrial and aerospace sectors. Dominant competitive moves involve strategic partnerships for system integration and continuous investment in advanced MEMS fabrication capabilities to secure supply.
Companies like Robert Bosch GmbH exemplify the integrated device manufacturer archetype, leveraging deep automotive sector ties and extensive system integration capabilities for advanced vehicle systems. STMicroelectronics N.V. represents a major player in MEMS sensor fabrication, serving both consumer and automotive markets with high-volume production capabilities and diverse product lines. Analog Devices, Inc. occupies a strong position among precision technology specialists, providing robust solutions for industrial and aerospace systems demanding high accuracy and long-term reliability. These firms continually refine their offerings to meet evolving application requirements and stringent qualification cycles.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Honeywell International Inc. |
| STMicroelectronics N.V. |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Robert Bosch GmbH |
| Murata Manufacturing Co., Ltd. |
| Texas Instruments Incorporated |
| TDK Corporation |
| Others |
Cost & Logistics Intelligence
AEC-Q100 qualification gates both supply qualification and price differentiation simultaneously within the automotive sensor market. This rigorous standard creates distinct pricing tiers for compliant components, influencing manufacturing investment decisions and supply chain configurations.
Pricing Analysis
Cost-plus contracts, often indexed to silicon wafer prices, define many long-term agreements for specialized sensors. Price differentiation stems from certification levels, such as automotive ASIL compliance, and the volume scale of production. Pricing pressure stems from cost-driven miniaturization in consumer electronics, where high unit volumes demand aggressive pricing. Aerospace and defense applications exhibit the least price sensitivity due to stringent reliability requirements, while smartphone manufacturers remain highly price-sensitive.
Supply Chain Analysis
Geopolitical tensions in East Asia expose the market to potential logistical disruptions, given the heavy concentration of assembly and testing facilities in China. Raw material dependencies include specialized silicon wafers and rare earth elements for advanced MEMS fabrication. Single-source vulnerability for specific components represents a structural risk for many OEMs. Distribution runs through a bifurcated model, with direct sales to large automotive and consumer electronics OEMs and specialized distributors serving industrial and niche markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rise of advanced MEMS technology positions this market for high-growth disruption. Integration of inertial sensors into new applications like edge AI and precision agriculture creates significant value opportunities.
For Market Incumbents: Shield core automotive and industrial segments by deepening vertical integration into advanced MEMS fabrication capabilities. Invest in ASIL-compliant sensor development to counter threats from emerging ADAS requirements. Prioritize R&D in sensor fusion algorithms to maintain a competitive edge against new software-centric entrants. Control of key certification processes acts as a strong lever against commoditization.
For New Entrants and Emerging Players: Fast-track regulatory approval pathways in medical devices enable new entrants to target high-value wearable medical devices. Focus on underpenetrated applications like precision agriculture in Brazil or industrial IoT in Germany with software-integrated modules. A go-to-market angle emphasizing low-power consumption and simplified integration can attract smartphone manufacturers seeking efficiency gains.
For Investors and Strategic Acquirers: The European Union's updated General Safety Regulation reshapes the acquisition landscape for companies with ASIL-compliant sensor solutions. Long-term viability rests on firms demonstrating robust IP portfolios in sensor fusion and edge AI integration. Acquisition targets should include niche specialists with strong certifications in aerospace or medical devices. A key signal to watch is the adoption rate of pre-certified, software-integrated inertial modules across industrial automation sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced MEMS Fabrication | Secures supply chain control and cost advantages for high-volume consumer electronics. |
| Develop ASIL-Compliant Sensor Solutions | Meets stringent automotive safety mandates, crucial for ADAS adoption in Germany. |
| Target Wearable Medical Device Integration | Unlocks high-value growth in remote patient monitoring, regulated by the MFDS in South Korea. |
| Form Strategic Partnerships for Edge AI | Accelerates real-time data processing at the sensor level, enhancing predictive maintenance. |
| Expand into Precision Agriculture Markets | Captures new demand for autonomous vehicles and drones in underpenetrated regions like Brazil. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted for primary insights into market dynamics. Interviews included automotive engineers, consumer electronics product managers, aerospace system integrators, and industrial automation specialists. Secondary validation drew from SEC filings, government regulatory documents like FAA and KBA guidelines, industry consortium reports, and academic journals, triangulating data through bottom-up and top-down approaches.
The analysis window for this market extends over the projection horizon, capturing shifts in technology and application. Segmentation dimensions modeled include sensor type, technology, application, end user, and regional manufacturing clusters. Compound annual growth rates were derived from historical data analysis and projected market expansion, incorporating industry-specific forecast inputs such as MEMS fabrication capacity and automotive production forecasts.
Underlying assumptions cover manufacturing capacity and regulatory stability, with deviation risk concentrated in geopolitical shifts. Forecasts reflect these assumptions, but practitioners should keep alternative scenarios live as technological breakthroughs and regulatory changes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Hall-Effect Sensors Market