
 Gum Arabic Market | 2026-2036
Gum Arabic Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Arabic Market Intelligence
Margin capture from crude gum arabic sales is narrowing as value shifts towards specialized, processed grades. Specialists like Nexira SAS leverage deep R&D capabilities to develop proprietary hydrocolloid blends for food and beverage clients. Meanwhile, global ingredient giants such as Cargill, Incorporated and Ingredion Incorporated control significant portions of the supply chain through extensive sourcing networks in Africa and large-scale processing facilities.
Gum arabic is a natural hydrocolloid harvested from the sap of the Acacia senegal and Acacia seyal trees. This complex polysaccharide functions as a superior emulsifier and stabilizer in aqueous systems, primarily used in the food, beverage, and pharmaceutical industries. The Acacia senegal variety commands a premium as it offers superior emulsification properties required in applications like beverage flavor emulsions. Consequently, the Food & Beverages application segment, driven by confectionery and soft drink production, constitutes the largest end-use market.
Market access hinges on compliance with food additive regulations established by bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). EFSA's designation E414 and the FDA's GRAS (Generally Recognized as Safe) status provide the legal foundation for its widespread use in consumer products. Stakeholders must therefore focus on securing supply chain resilience and diversifying sourcing origins to mitigate geopolitical and climate-related risks.
Market Dynamics
The market's central dynamic is the value shift from raw, unprocessed gum to specialized, high-purity grades. This transition is driven by food and beverage industry demands for functional ingredients with verifiable quality and consistent performance characteristics.
Growth Catalysts
- Clean-Label Ingredient Demand:The consumer-led push for natural ingredients in the food and beverage sector, particularly in confectionery and soft drinks, elevates gum arabic over synthetic emulsifiers and stabilizers.
- Supportive Regulatory Status:Favorable classifications, including the EFSA's E414 designation in Europe and GRAS status from the U.S. FDA, provide a solid legal basis for its use in a wide array of consumer goods.
- Pharmaceutical Sector Use:The pharmaceutical industry utilizes gum arabic as an excipient for its binding, emulsifying, and stabilizing properties in tablets and liquid suspensions, creating a stable, high-value demand stream.
Market Restraints
- Geopolitical & Climate Instability:Supply is heavily concentrated in the African Sahel region, making the market vulnerable to disruptions from political instability, conflict, and climate change-induced droughts or inconsistent rainfall.
- Threat from Synthetic Alternatives:In price-sensitive applications, gum arabic faces competition from other hydrocolloids like modified starches or xanthan gum, which can offer lower cost and more stable pricing.
- Inconsistent Raw Material Quality:Natural variations in gum exudates between harvests and tree species (*Acacia senegal* vs. *Acacia seyal*) create processing challenges and require sophisticated blending to achieve standardized commercial grades.
Strategic Opportunities
- Nutraceutical & Functional Foods:There is a significant opportunity to incorporate gum arabic into nutraceuticals and functional foods, capitalizing on its scientifically recognized prebiotic and dietary fiber properties.
- Expansion of Cultivation:Developing organized cultivation and harvesting in new, climatically suitable regions beyond the traditional African belt can mitigate supply concentration risks and improve supply chain resilience.
- High-Value Application Development:Formulating proprietary hydrocolloid blends for emerging sectors like plant-based meat alternatives and microencapsulation for flavor or active pharmaceutical ingredients presents a path to higher margins.
Industry Challenges
- Supply Chain Traceability:Implementing and verifying full traceability from smallholder harvesters in remote regions to processing facilities is complex and costly, yet increasingly demanded by regulators and end-users.
- Advanced Processing Requirements:The capital investment needed for spray drying and purification technologies to produce the high-purity grades required by the pharmaceutical and beverage industries is substantial.
- Sustainable Harvesting Practices:Ensuring sustainable harvesting techniques across a fragmented and vast sourcing network is a persistent operational challenge, crucial for long-term tree health and supply viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Arabic Market |
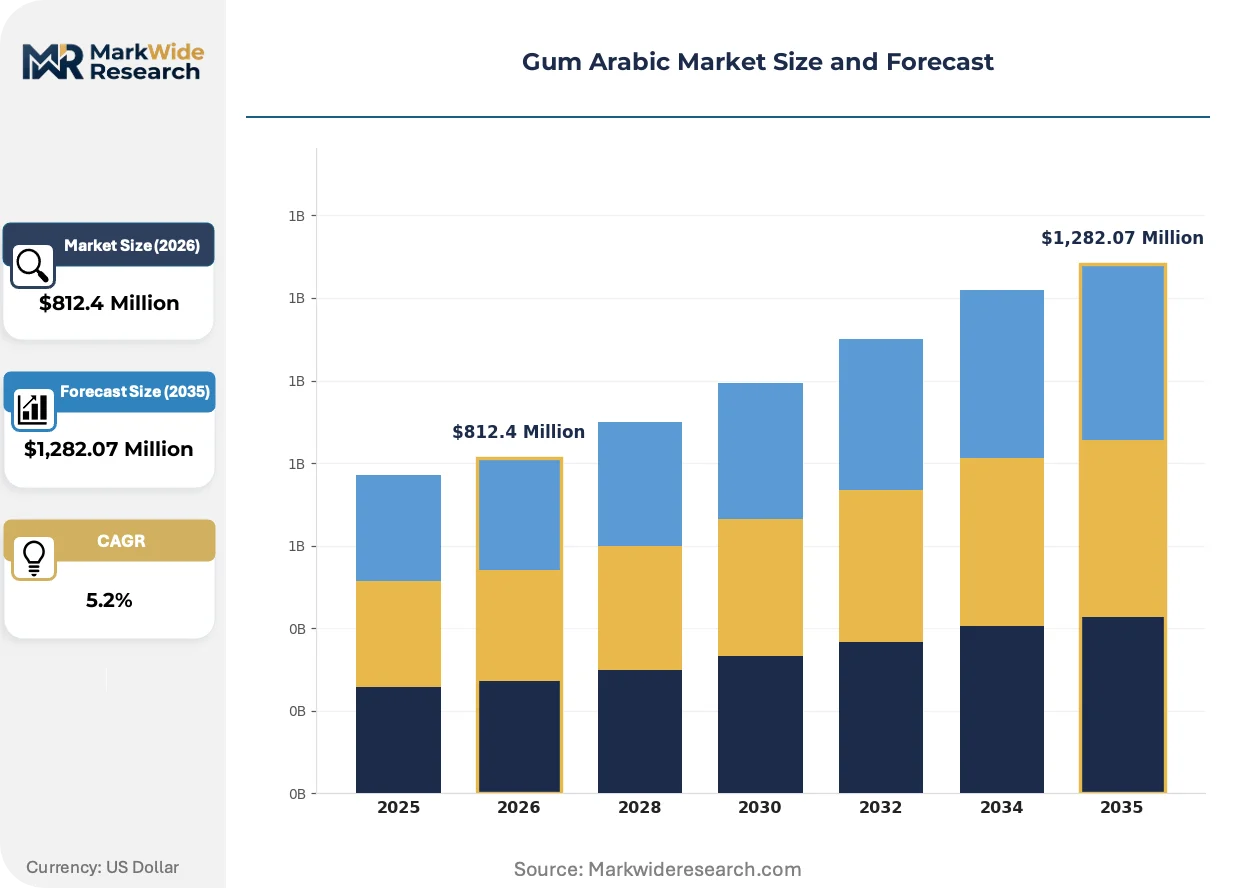
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,282.07 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
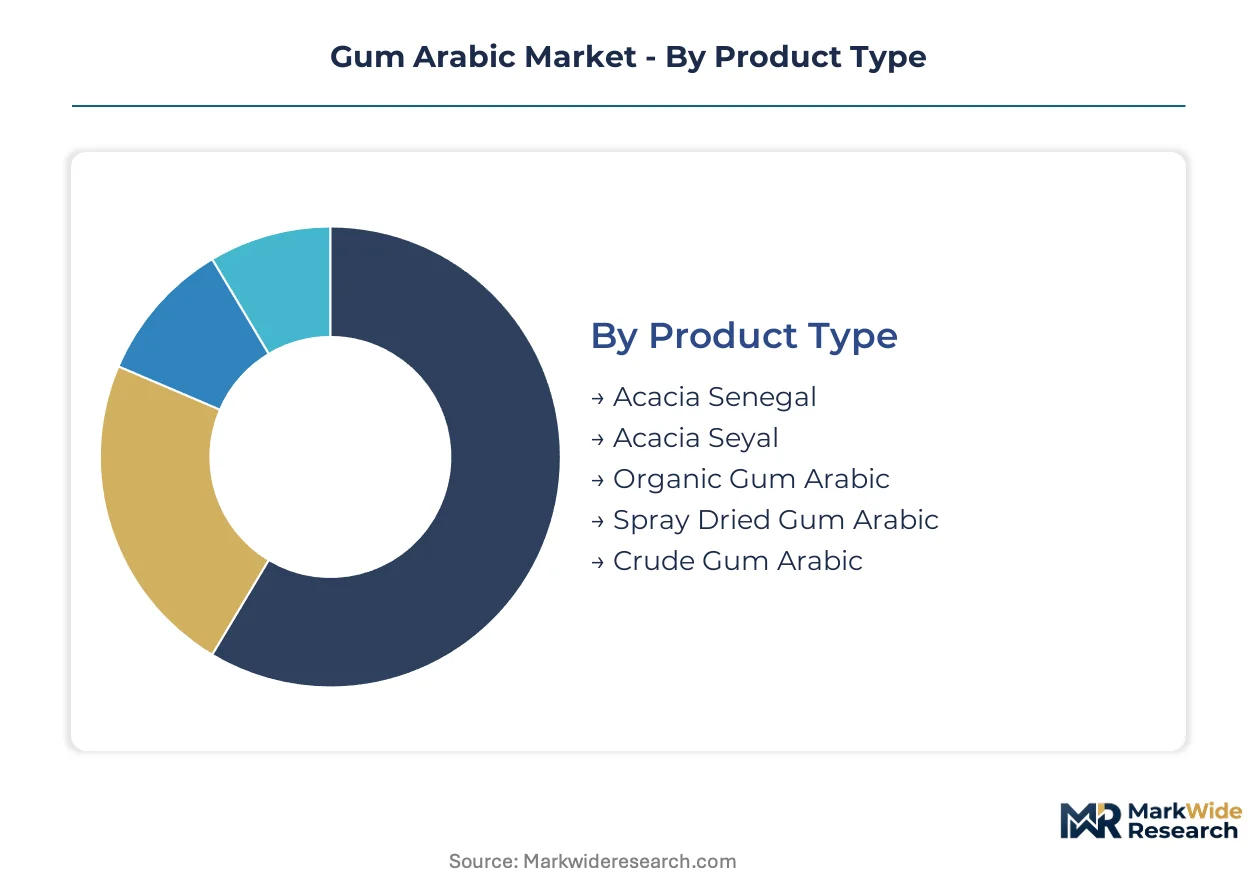
| Segmentation | Product Type: Acacia Senegal, Acacia Seyal, Organic Gum Arabic, Spray Dried Gum Arabic, Crude Gum Arabic Application: Food & Beverages, Cosmetics, Pharmaceuticals, Inks & Paints, Textile Finishing End User: Food Manufacturers, Personal Care Producers, Drug Formulators, Printing Houses, Textile Mills Packaging Type: Bags, Drums, Bulk Containers, Boxes, Tins |
| Companies Covered | Farbest Brands, Alland & Robert SAS, Nexira SAS, Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Kerry Group Plc, Sudanese Gum Arabic Company Limited, Agrigum International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Arabic Market Strategic Shifts & Innovations
The gum arabic market is evolving from a simple commodity trade into a sophisticated ingredient science business. This transformation centers on adding value through processing technology, supply chain verification, and the development of application-specific functional systems for global food and pharmaceutical clients.
Traceability Technology
Blockchain-based traceability platforms are being implemented to provide immutable records of gum arabic's journey from harvest to final product. Food and beverage manufacturers are leading the adoption of these systems to authenticate origin and prove compliance with sustainability mandates. This technology is digitizing the supply chain, compressing audit times and enhancing trust for regulators and consumers.
Sustainability Reporting Mandates
The European Union’s Corporate Sustainability Reporting Directive (CSRD) is compelling ingredient importers to disclose detailed environmental and social data. This forces companies to document the impact of their sourcing activities in African nations, including labor practices and environmental management. The food processing sector, especially in Germany and France, is most affected and is investing heavily in data collection to comply.
Strategic Sourcing Models
Buyers in the beverage and confectionery industries are moving from transactional, spot-market acquisitions toward long-term strategic partnerships. This shift is marginalizing traditional commodity traders who cannot guarantee the consistent quality or specific grades required for advanced formulations. The pattern is most visible in the United States and Europe, where large manufacturers seek to secure stable supplies of premium *Acacia senegal* gum.
Gum Arabic Market Segmentation
The gum arabic market segments reflect diverse functional requirements and supply chain complexities. Understanding these distinctions allows stakeholders to identify specific value pools and tailor product offerings. Segmentation highlights specialized demand across industries.
Product Type:
Product type segmentation illustrates a maturity spectrum, from raw commodity grades to highly refined formulations. This differentiation impacts pricing, processing, and end-use suitability.
- Acacia Senegal:This variety, from Acacia senegal trees, contains more arabinogalactan proteins, providing superior emulsification capabilities. Demand concentrates in high-end beverage flavor emulsions, critical for product integrity.
- Acacia Seyal:Derived from Acacia seyal trees, this grade offers good solubility and viscosity, used in less demanding emulsification.
- Organic Gum Arabic:Certified organic gum arabic meets specific cultivation and processing standards, appealing to clean-label food manufacturers.
- Spray Dried Gum Arabic:This highly processed form involves atomizing a gum arabic solution, producing fine, soluble powder with enhanced purity. Pharmaceutical and premium beverage sectors drive procurement, valuing standardized quality.
- Crude Gum Arabic:Unprocessed resin collected directly from acacia trees, primarily serves as raw material for further purification.
Crude Gum Arabic retains volume leadership; Spray Dried Gum Arabic holds the steepest expansion curve.
Application:
Application segments highlight diverse functional requirements gum arabic fulfills across industrial uses. Each sector leverages its unique properties as an emulsifier, stabilizer, or binding agent.
- Food & Beverages:Gum arabic functions as a natural emulsifier, stabilizer, and texturizer, preventing ingredient separation. Confectionery and soft drink production in Germany and the United States drives demand for clean-label ingredients.
- Cosmetics:Used as film-former, emulsifier, and thickener in cosmetic formulations, enhancing product texture.
- Pharmaceuticals:This sector utilizes gum arabic as an excipient, binding agent for tablets, and an emulsifier in liquid suspensions. Drug formulators in Europe and North America seek high-purity grades for safety compliance.
- Inks & Paints:Serves as binder and protective colloid in water-based inks, improving adhesion and pigment dispersion.
- Textile Finishing:Applied in textile sizing and printing, providing stiffness and improved print clarity to fabrics.
Sectoral demand patterns reveal Food & Beverages drives largest consumption; Pharmaceuticals commands premium pricing.
End User:
End user segmentation delineates primary customer types procuring gum arabic, reflecting varied purchasing volumes, quality specifications, and supply chain expectations.
- Food Manufacturers:These entities integrate gum arabic into confectionery, bakery items, and dairy alternatives for emulsification and stabilization. Large food processing centers in France and the United Kingdom prioritize consistent quality.
- Personal Care Producers:Utilize gum arabic in lotions, shampoos, and toothpaste for its emulsifying and film-forming properties.
- Drug Formulators:These companies incorporate gum arabic as a pharmaceutical excipient, aiding in tablet binding and emulsion stability. Strict regulatory compliance from FDA and EMA mandates high-purity, traceable gum arabic.
- Printing Houses:Employ gum arabic in offset lithography as a desensitizing agent and to improve ink adhesion on printing plates.
- Textile Mills:Use gum arabic as a sizing agent to strengthen yarns and as a thickener in textile printing pastes.
The largest customer base resides with Food Manufacturers, while Drug Formulators exhibit the most stringent quality requirements.
Packaging Type:
Packaging type reflects considerations for logistics, cost efficiency, and product protection. Choices align with volume and value of gum arabic shipped.
- Bags:Used for smaller quantities of gum arabic, providing cost-effective and flexible packaging for various buyers.
- Drums:Drums, often fiber or steel, protect gum arabic from moisture and contamination, suitable for intermediate volumes of processed grades. Mid-sized food ingredient distributors in the United States prefer drums for efficient handling.
- Bulk Containers:These large-capacity containers, like FIBCs, facilitate cost-effective transport of significant raw or semi-processed gum arabic volumes. Major industrial users and large-scale processors in China and India leverage bulk containers.
- Boxes:Offer convenient packaging for consumer-facing or smaller industrial quantities, ensuring product integrity.
- Tins:Provide robust, airtight storage for premium or sensitive gum arabic grades, protecting against environmental factors.
Bulk packaging optimizes freight costs, while drums and boxes cater to processed grades requiring enhanced protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for gum arabic varies significantly across global markets; some buyers prioritize cost-effectiveness for standard grades, while others demand premium, high-purity forms for specialized applications. This differentiation in purchasing priorities shapes regional consumption patterns and influences supply chain investments. Consequently, regions with advanced food and pharmaceutical industries drive demand for processed, high-value gum arabic.
Germany
German demand for gum arabic centers on clean-label food and beverage ingredients, particularly within confectionery and dairy alternatives. The EU's Corporate Sustainability Reporting Directive (CSRD) significantly impacts ingredient importers, requiring detailed environmental and social disclosures. Major food processing centers in Bavaria and North Rhine-Westphalia are actively investing in data collection to ensure compliance and maintain market access.
France
French manufacturers seek gum arabic as a natural emulsifier for sophisticated food formulations and high-end beverage products. The European Food Safety Authority (EFSA) designation E414 provides a clear regulatory framework for its widespread use. Large food processing centers in Île-de-France and Auvergne-Rhône-Alpes prioritize suppliers who can guarantee consistent quality and full traceability.
United States
United States consumption is propelled by its large confectionery and soft drink industries, which require natural emulsifiers to meet clean-label consumer preferences. The U.S. Food and Drug Administration's (FDA) Generally Recognized as Safe (GRAS) status underpins its extensive application in consumer products. Food and beverage manufacturers in the Midwest and Northeast are establishing long-term strategic partnerships to secure stable supplies of premium Acacia senegal gum.
United Kingdom
United Kingdom food manufacturers integrate gum arabic into bakery items, dairy alternatives, and flavor emulsions for its stabilizing and texturizing properties. Post-Brexit, the UK's food additive regulations largely align with EFSA standards, ensuring continued market access for compliant products. Processing hubs in London and Manchester focus on consistent quality to support diverse product development efforts.
Netherlands
Netherlands serves as a crucial re-export and distribution hub for gum arabic, with mid-sized food ingredient distributors procuring intermediate volumes for European markets. Compliance with EU import standards and food additive regulations is paramount for all incoming shipments. The port of Rotterdam and its extensive logistics infrastructure facilitate efficient handling and onward distribution of processed gum arabic grades.
Gum Arabic Market Key Industry Players
Capability concentration sits with one tier of players, specializing in advanced R&D and proprietary formulations, while scale advantage sits with another, leveraging extensive sourcing and processing infrastructure. The market structure is tiered, encompassing highly specialized ingredient developers, global food ingredient giants, and traditional commodity traders. Strategic partnerships and continuous investment in advanced processing capabilities represent dominant competitive moves.
Specialized ingredient developers like Nexira SAS exemplify the focus on proprietary hydrocolloid blends for food and beverage clients. Global ingredient giants such as Cargill, Incorporated and Ingredion Incorporated, on the other hand, anchor the market with extensive sourcing networks and large-scale processing facilities. These entities control significant portions of the supply chain, leveraging their scale to meet diverse industry demands.
| Leading Market Players |
|---|
| Farbest Brands |
| Alland & Robert SAS |
| Nexira SAS |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Kerry Group Plc |
| Sudanese Gum Arabic Company Limited |
| Agrigum International Ltd |
| Others |
Cost & Logistics Intelligence
Commodity volatility in raw gum arabic, stemming from climate instability and geopolitical risks in the African Sahel, directly shapes pricing tier spreads and the fragmented supply chain for processed grades. This volatility creates distinct pricing for crude versus high-purity gum arabic.
Pricing Analysis
Premium pricing for specialized, processed gum arabic, offering consistent performance and verifiable quality, drives long-term client relationships and higher lifetime value. Pricing stratifies across crude gum arabic, which trades on commodity spot markets, and high-purity, contract-based grades. Quality grade, such as Acacia senegal's superior emulsification, and certification levels for pharmaceutical use, differentiate prices significantly. Pricing pressure stems from raw material volatility for crude grades, while specialized formulations command premiums. Pharmaceutical and high-end food manufacturers exhibit lower price sensitivity compared to general industrial users.
Supply Chain Analysis
Upstream feedstock for gum arabic draws primarily from the African Sahel region, particularly Sudan, Chad, and Nigeria, where Acacia senegal and Acacia seyal trees are harvested. This concentration creates a single-source vulnerability, exposing the supply chain to geopolitical instability and climate change-induced droughts. Inconsistent raw material quality also presents a structural risk for processors. Distribution runs through extensive networks controlled by global ingredient giants and specialized hydrocolloid developers, marginalizing transactional commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gum arabic market is poised for high-growth disruption, driven by the consumer-led push for clean-label ingredients and the European Union’s Corporate Sustainability Reporting Directive (CSRD). This regulatory inflection compels detailed environmental and social disclosures, reshaping sourcing practices.
For Market Incumbents: Entrench market leadership by investing in deep R&D for proprietary hydrocolloid blends, particularly for emerging sectors like plant-based alternatives. Expand advanced processing capabilities, including spray drying and purification, to consistently meet high-purity requirements from pharmaceutical and premium beverage clients. Diversify sourcing origins beyond the African Sahel to mitigate geopolitical and climate-related supply risks. Strengthen supply chain traceability using blockchain to counter the threat of inconsistent raw material quality and meet sustainability mandates.
For New Entrants and Emerging Players: Nutraceuticals and functional foods represent a penetrable entry point, capitalizing on gum arabic's prebiotic and dietary fiber properties. Focus on developing high-value, application-specific hydrocolloid blends for plant-based meat alternatives and microencapsulation technologies. A go-to-market angle emphasizing certified organic gum arabic with verified sustainability credentials can attract clean-label food manufacturers. Target regions with strong demand for natural ingredients, such as the United States and Europe, through direct partnerships with formulators.
For Investors and Strategic Acquirers: The European Union’s Corporate Sustainability Reporting Directive (CSRD) reshapes the acquisition landscape, favoring entities with robust environmental and social data. Long-term viability in the gum arabic market centers on companies capable of producing high-purity, traceable grades for pharmaceutical and premium food applications. Acquisition targets should include specialized processors with advanced spray-drying capabilities or firms with established, diversified sourcing networks. The signal to watch is the widespread adoption of blockchain-based traceability platforms, indicating enhanced supply chain transparency and resilience.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Proprietary Hydrocolloid Blends | Nexira SAS and similar specialists can capture higher margins by innovating functional systems for food and beverage clients. |
| Invest in Advanced Processing Technologies | Global ingredient giants like Cargill, Incorporated ensure consistent quality for high-purity grades demanded by pharmaceutical applications. |
| Diversify Sourcing Beyond African Sahel | Mitigates geopolitical and climate-related risks, improving supply chain resilience for all market participants. |
| Implement Blockchain Traceability Platforms | Food and beverage manufacturers gain immutable records of origin, authenticating compliance with sustainability mandates. |
| Form Long-Term Strategic Partnerships | Beverage and confectionery buyers secure stable supplies of premium Acacia senegal gum, bypassing transactional spot markets. |
Research Approach
Initial hypotheses were tested against primary input from food manufacturers, drug formulators, ingredient distributors, and R&D specialists, then refined. This involved combining insights from in-depth interviews with extensive secondary validation. Secondary data sources included regulatory filings from EFSA and FDA, trade association publications, and company financial disclosures. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy across all segments.
Demand-supply-balance formed the core of the analytical framework across the modeling period, integrating various market forces. The model segmented the market by product type, application, end-user, packaging type, and key regional consumption patterns. Compound Annual Growth Rates were derived from historical growth trends and projected market dynamics. Key industry-specific forecast inputs included clean-label ingredient demand, regulatory support for gum arabic, and raw material availability.
Practitioners should monitor geopolitical instability in the African Sahel and significant climate-related events for early signals of supply disruption. Forecasts reflect assumptions regarding raw material availability and regulatory stability. Cross-checking against global hydrocolloid market reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sunflower Protein Market
Ingredients
Campesterol Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Specialty Yeast Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Fucoidan Extract Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Coconut Flour Market
Ingredients
Barley Flake Market
Ingredients
Alginate Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Guar Gum Market
Ingredients
China Soy Protein Market