
 Fish Feed Ingredients Market | 2026-2036
Fish Feed Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Feed Ingredients Market Insights
Market Overview
Peruvian fishmeal output is rebalancing after quota adjustments tightened global supply of marine proteins. Cargill, Incorporated leverages its integrated oilseed processing network to secure soybean meal volumes for aquaculture formulations. Nutreco N.V. anchors European demand through its Skretting AS subsidiary, which specializes in salmonid nutrition. BioMar Group competes across multiple geographies with species-specific feed portfolios.
Segmentation Analysis
Fish feed ingredients comprise formulated nutritional inputs—proteins, lipids, carbohydrates, vitamins, and minerals—blended to meet species-specific growth requirements, with protein content typically ranging from 25% to 55% depending on target species and life stage. Plant-based ingredients occupy the largest volume share as soybean meal and processed grain proteins displace fishmeal in omnivorous species diets. Omega-3 fatty acid concentrates command premium positioning within nutritional value segments due to their critical role in salmonid health and fillet quality. Microbial ingredients represent the fastest-expanding ingredient type as single-cell proteins gain regulatory approval for aquaculture applications.
Regulatory Environment and Future Outlook
EFSA and national regulators across EU member states enforce strict maximum residue limits and feed safety standards under the EU Feed Hygiene Regulation, while the EU Green Deal's Farm to Fork Strategy pressures ingredient traceability and sustainability certification. The FDA and USDA coordinate feed ingredient approvals in the United States, with novel proteins requiring GRAS determinations or food additive petitions. Stakeholders must monitor evolving novel protein regulatory pathways in major aquaculture markets to anticipate which alternative ingredients achieve commercial scale.
Market Dynamics
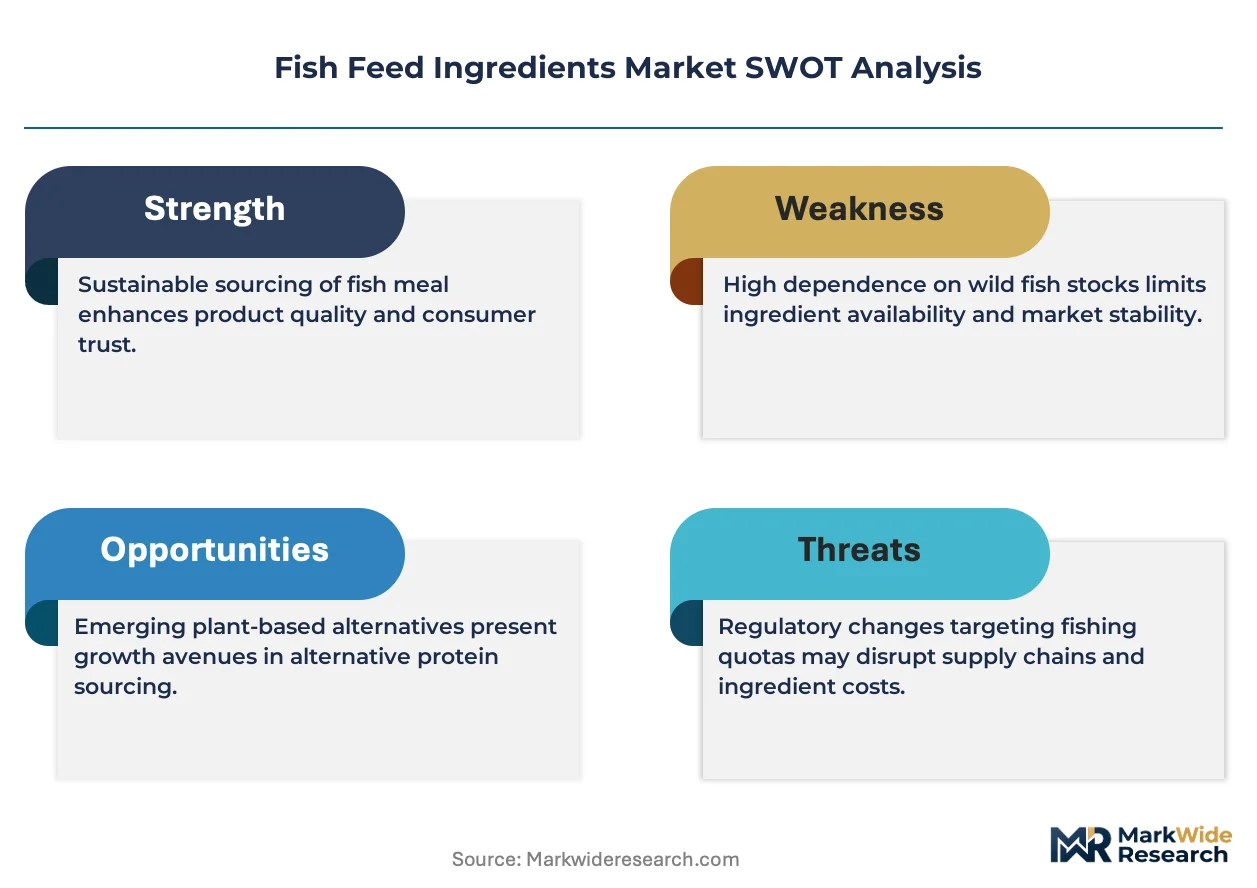
EU Green Deal sustainability mandates are compressing the marine protein supply base while accelerating microbial and plant-based ingredient approvals, fundamentally restructuring procurement specifications across Atlantic salmon farming corridors.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding sustainability targets for aquaculture feed are redirecting ingredient sourcing toward certified plant proteins and microbial alternatives across Norwegian and Scottish farming zones.
- Salmonid omega-3 enrichment protocols:Fillet quality premiums for EPA/DHA content are sustaining demand for algal oil concentrates and specialized lipid formulations in premium aquaculture segments.
- Southeast Asian intensification:Shrimp farming expansion in Vietnam and Indonesia is scaling formulated feed programs and displacing farm-made feeds with commercial extruded diets.
Market Restraints
- Peruvian anchovy quota volatility:Marine protein supply concentration in the Humboldt Current ecosystem creates input cost instability for high-performance salmonid formulations.
- EFSA novel protein approval timelines:Single-cell protein and insect meal authorizations face extended safety evaluation periods that delay commercial scale-up across EU member states.
- Soybean meal price correlation:Oilseed commodity futures directly transmit volatility into omnivorous species feed costs, compressing margin structures for shrimp and tilapia producers.
Strategic Opportunities
- Indian aquaculture feed formalization:Underpenetrated commercial feed adoption in Andhra Pradesh and Gujarat shrimp farming presents volume expansion potential for extruded feed suppliers.
- Algae fermentation infrastructure:Converging photobioreactor engineering with precision fermentation is enabling domestic omega-3 production independent of marine capture fisheries.
- EU deforestation-free supply chain regulation:Mandatory due diligence for soy and palm derivatives creates first-mover advantage for certified sustainable ingredient traceability platforms.
Industry Challenges
- Novel protein scale-up engineering:Single-cell protein and insect meal facilities require specialized bioprocess expertise that remains concentrated in pharmaceutical and enzyme manufacturing talent pools.
- Multi-certification compliance burden:Simultaneous ASC, BAP, and EU organic feed standard maintenance demands dedicated quality systems infrastructure that mid-scale blenders struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Feed Ingredients Market |
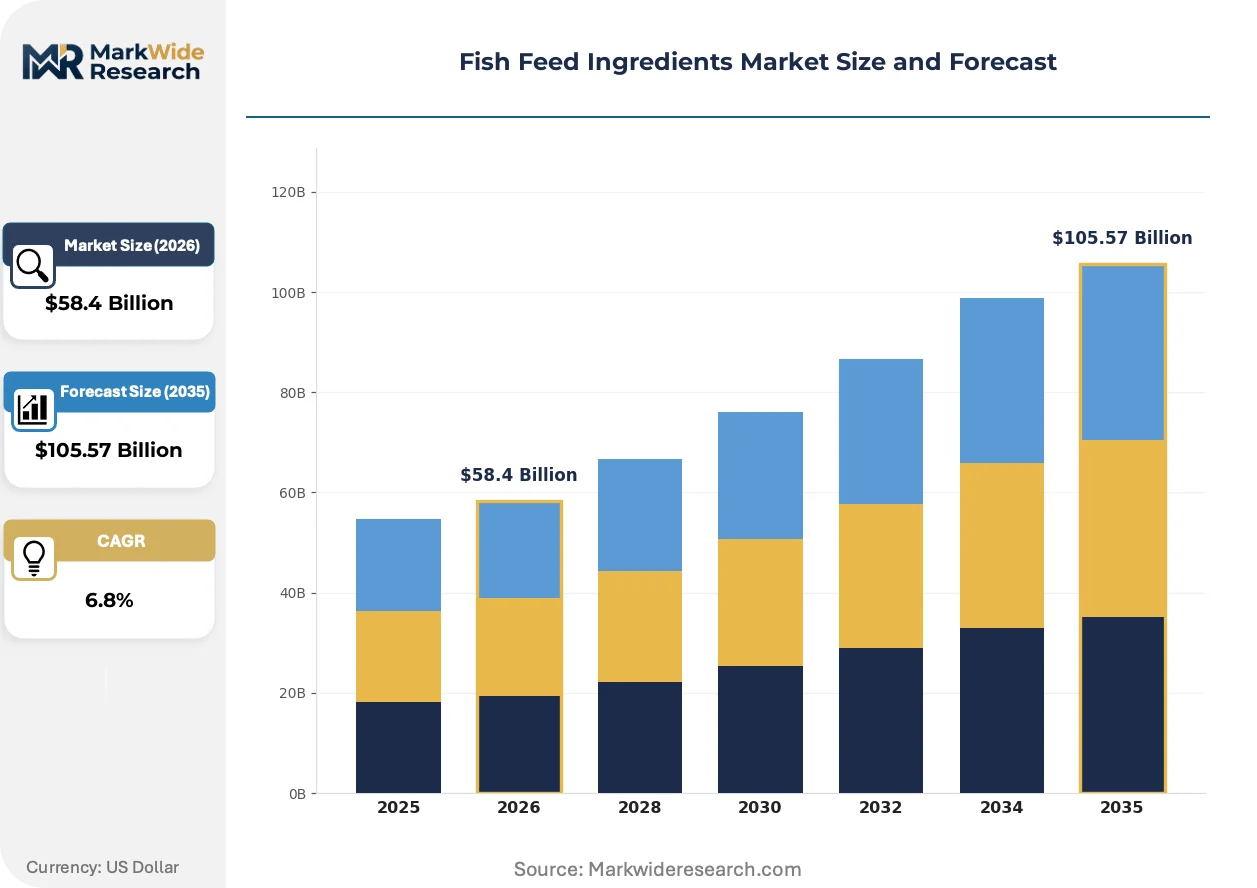
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Plant-Based, Animal-Based, Microbial, Synthetic Form: Pellets, Crumbles, Flakes, Powder Nutritional Value: Protein, Omega-3 Fatty Acids, Vitamins, Minerals Target Species: Tilapia, Salmon, Catfish, Trout |
| Companies Covered | Cargill, Incorporated, Nutreco N.V., BioMar Group, Archer Daniels Midland Company, Skretting AS, Charoen Pokphand Foods PCL, Tongwei Co., Ltd., Aller Aqua Group, Zeigler Bros., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Feed Ingredients Market Trends and Innovations
Formulation science is converging with systems biology and alternative protein manufacturing, compressing development cycles for species-specific nutritional solutions while fragmenting the incumbent marine protein supply base.
Precision fermentation of microbial biomass is unifying protein production with omega-3 synthesis in single-organism platforms. Salmonid nutrition specialists in Norway and Chile are piloting these integrated inputs at commercial scale. The technology is unifying what were separate supply chains for fishmeal and fish oil into consolidated microbial ingredient streams.
EFSA's evolving novel food and feed ingredient guidance is compressing approval timelines for single-cell proteins while tightening safety data requirements. Industrial biotech developers are pre-submission consulting with Parma regulators to align toxicology packages. Norwegian feed compounders are most affected, accelerating partnerships with approved microbial protein suppliers ahead of formal authorization expansions.
Buyer consolidation among integrated salmon farming groups is compressing formulation specification cycles and unbundling technical service from ingredient supply contracts. Large-scale Norwegian and Chilean producers are internalizing nutrition teams and direct-sourcing base ingredients. This pattern is most visible in the Bergen-to-Stavanger corridor, where vertically integrated farming groups now specify raw material profiles rather than finished feed products.
Fish Feed Ingredients Market Segmentation
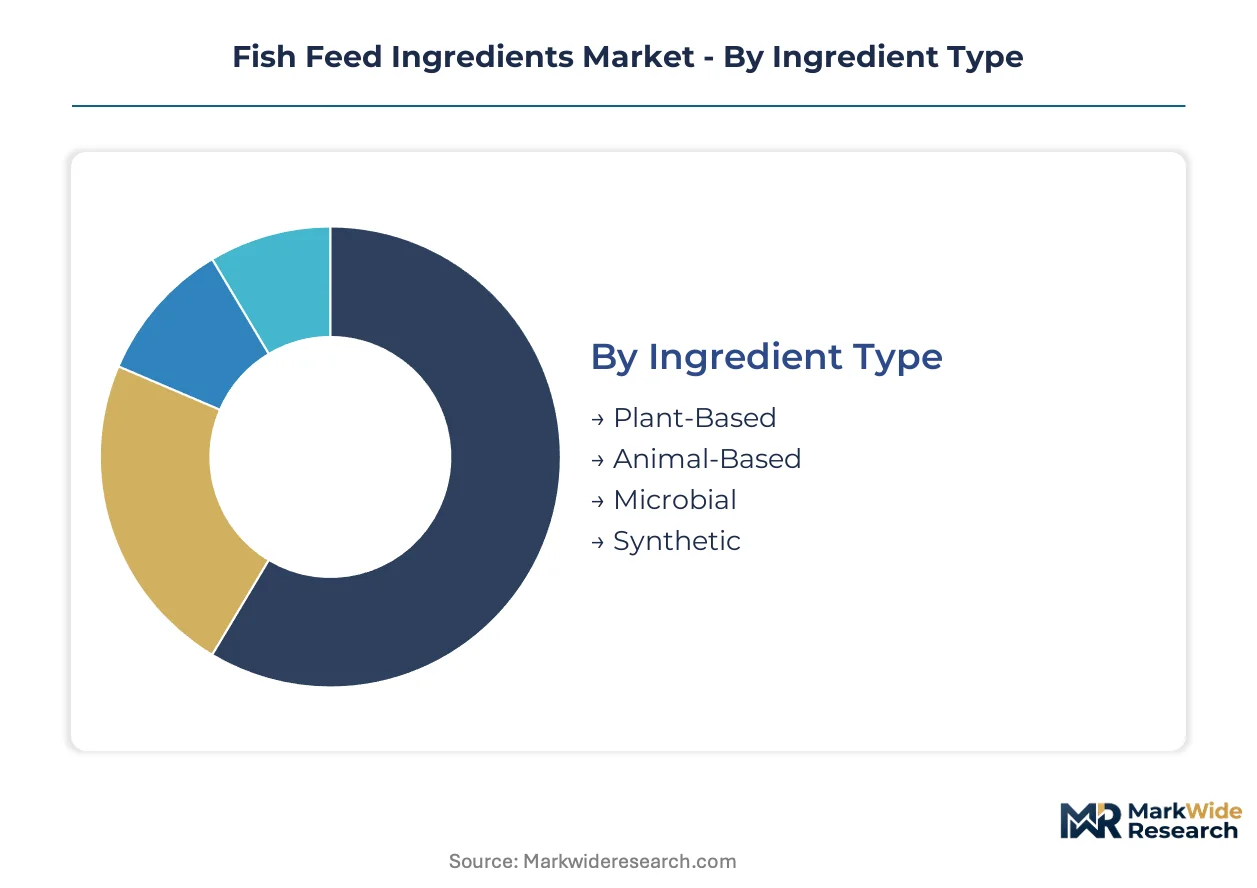
Ingredient classification determines procurement specifications, formulation costs, and regulatory compliance pathways across aquaculture value chains. Feed compounders segment inputs by nutritional function, physical handling properties, and species-specific digestibility requirements to optimize conversion ratios and fillet quality outcomes.
Ingredient Type:
Cost tier separates commodity-scale buyers from premium formulation specialists seeking functional differentiation.
- Plant-Based:Soybean meal, processed grain proteins, and oilseed derivatives constitute the dominant volume base for omnivorous species diets. Vietnamese shrimp farming clusters and Indonesian tilapia operations are scaling certified sustainable soy procurement to meet EU import standards for processed seafood.
- Animal-Based:Peruvian anchovy fishmeal and North Atlantic fish oil concentrates deliver essential amino acid profiles and long-chain omega-3s for salmonid growth stages. Norwegian farming corridors maintain offtake agreements with marine protein traders despite tightening sustainability quotas under the EU Green Deal.
- Microbial:Single-cell proteins from precision fermentation and autotrophic cultivation are securing novel feed authorizations from EFSA. These inputs bypass marine capture dependency while matching fishmeal amino acid scores.
- Synthetic:Laboratory-synthesized amino acids, carotenoids, and vitamin premixes enable precise nutritional fortification. DSM-Firmenich and BASF supply synthetic astaxanthin for salmon pigmentation.
Plant-based ingredients lead volumes today; microbial alternatives are gaining share fastest.
Form:
Physical form selection hinges on species feeding behavior, water stability requirements, and extrusion equipment capabilities at compounder facilities.
- Pellets:Extruded sinking and floating formulations dominate commercial aquaculture for salmon, trout, and catfish. Chilean and Norwegian feed mills operate high-capacity twin-screw extruders producing water-stable pellets with controlled leaching profiles.
- Crumles:Fragmented feed particles suit larval and juvenile stages where mouth gape limits ingestion. Shrimp hatcheries in Andhra Pradesh and Ecuador specify crumble grades for post-larval transitions.
- Flakes:Thin, expanded sheets serve ornamental fish and research aquaculture with slow-release nutrient characteristics. Flake production concentrates in specialized European and Japanese facilities serving niche aquarium markets.
- Powder:Fine-ground meals enable farm-made feed blending and larval microdiets. Artisanal shrimp producers in Vietnam combine commercial powders with local ingredients for pond-side formulation.
Pellet formats command the largest manufacturing capacity; crumble specifications are expanding most rapidly with shrimp intensification.
Nutritional Value:
Margin structure diverges sharply between commodity macronutrients and functional micronutrients commanding formulation premiums.
- Protein:Essential amino acid profiles from marine, plant, and microbial sources drive growth performance and feed conversion efficiency. Salmonid formulations target 40-50% crude protein with digestible lysine and methionine minimums.
- Omega-3 Fatty Acids:EPA and DHA concentrates from fish oil and algal fermentation sustain fillet nutritional quality for human health positioning. Norwegian producers pay premiums for algal oil to decouple from Peruvian anchovy supply volatility.
- Vitamins:Fat-soluble and water-soluble premixes prevent deficiency pathologies across intensive production cycles. Vitamin C stability in extruded feeds requires phosphate-esterified forms.
- Minerals:Trace element chelates and macro-mineral supplements optimize bone development, osmoregulation, and metabolic enzyme function. Organic selenium sources replace inorganic forms for bioavailability advantages.
Protein inputs absorb the largest procurement expenditure; omega-3 fatty acids deliver the steepest price per kilogram.
Target Species:
Customer type segmentation aligns formulation R&D with species-specific digestive physiology and market positioning requirements.
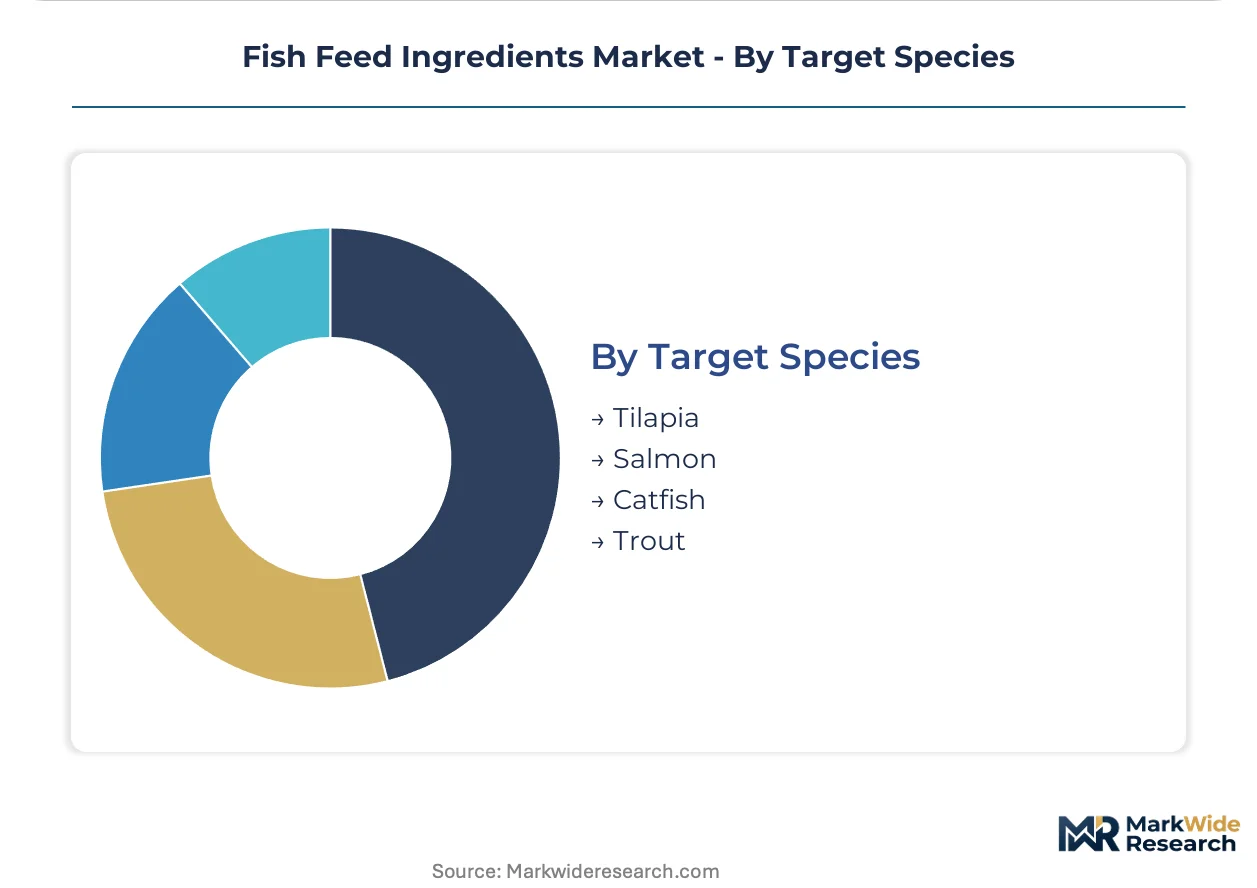
- Tilapia:Omnivorous tolerance enables high plant-protein inclusion rates and cost-optimized feeds. Sub-Saharan African and Southeast Asian farming zones prioritize affordable extruded diets over marine protein dependency.
- Salmon:Carnivorous nutritional requirements sustain premium marine and microbial protein demand despite sustainability pressures. Atlantic salmon farming corridors in Norway, Scotland, and Chile set the benchmark for high-performance formulation specifications.
- Catfish:Channel catfish in the US Southeast and African catfish in Nigeria accept grain-based diets with moderate protein supplementation. Feed mills in Mississippi and Alabama operate dedicated catfish lines with regional grain sourcing.
- Trout:Rainbow and brook trout production in freshwater raceways and sea cages mirrors salmon nutritional requirements at smaller scale. Alpine and Balkan farming regions maintain specialized trout feed supply chains.
Salmon feed specifications command the highest ingredient quality premiums; tilapia diets are expanding production volume most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's Atlantic salmon farming corridor demands higher-grade marine proteins than Vietnam's shrimp intensification zones, yet both markets are accelerating certified sustainable ingredient procurement under tightening export standards.
Norway
Atlantic salmon farming in the Bergen-to-Stavanger corridor drives premium marine protein consumption for high-performance feed formulations. The EU Green Deal's Farm to Fork Strategy binds Norwegian producers to certified sustainable sourcing mandates. Integrated farming groups in Rogaland now specify raw material profiles directly rather than purchasing finished feeds.
Vietnam
Shrimp farming expansion in the Mekong Delta is displacing farm-made feeds with commercial extruded diets at accelerating rates. The country's fisheries regulator enforces feed safety standards aligned with EU import requirements for processed seafood. Bac Lieu and Ca Mau provinces concentrate new extrusion capacity serving export-oriented aquaculture operations.
Indonesia
Tilapia and shrimp farming clusters in Java and Sumatra are scaling formulated feed adoption as intensification deepens. National agricultural agencies promote certified sustainable soy procurement to maintain EU market access for processed aquaculture products. Lampung province anchors growing commercial feed demand from smallholder pond systems.
Chile
Salmonid farming in the Los Lagos and Aysén regions sustains demand for marine proteins and specialized lipid formulations despite sustainability pressures. Chile's national fisheries service enforces strict feed residue monitoring under export certification programs. Puerto Montt concentrates feed milling capacity serving vertically integrated farming operations.
India
Shrimp farming in Andhra Pradesh and Gujarat presents underpenetrated commercial feed adoption opportunities as pond intensification advances. The Food Safety and Standards Authority of India regulates aquaculture feed composition and labeling for domestic and export markets. Visakhapatnam and Bhavnagar districts concentrate emerging extruded feed demand from transitioning farm-made operations.
Fish Feed Ingredients Market Competitive Landscape
European producers anchor the premium marine protein and salmonid nutrition tier; Asian specialists hold volume positions in shrimp and tilapia feed formulations. The market structure fragments across geographic specialization rather than consolidating around universal portfolios. Three archetypes dominate: integrated agribusiness conglomerates with oilseed processing networks, aquaculture-focused nutrition specialists with species-specific R&D capabilities, and regional feed compounders serving intensifying smallholder markets. Capacity expansion and backward integration into alternative protein manufacturing represent the dominant competitive vectors.
Among integrated agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify the oilseed-to-feed processing archetype with commodity-scale supply capabilities. Nutreco N.V. occupies a position representing aquaculture nutrition specialization through its Skretting AS subsidiary structure. BioMar Group sits within the species-specific portfolio tier, anchoring multi-geographic formulation expertise across salmonid and shrimp segments.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Nutreco N.V. |
| BioMar Group |
| Archer Daniels Midland Company |
| Skretting AS |
| Charoen Pokphand Foods PCL |
| Tongwei Co., Ltd. |
| Aller Aqua Group |
| Zeigler Bros., Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU Green Deal-compliant marine proteins and uncertified commodity alternatives shapes both procurement premiums and supplier qualification pathways across Norwegian and Vietnamese farming corridors. Buyers in the Bergen-to-Stavanger corridor pay substantial uplifts for ASC-certified fishmeal and deforestation-free soy derivatives, while Mekong Delta shrimp operations absorb lower per-kilogram costs for standard-grade formulations lacking equivalent traceability documentation.
Pricing Analysis
Distributor margins for algal oil concentrates and single-cell proteins compress as integrated salmon farming groups in Norway and Chile shift toward direct sourcing from fermentation facilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, omega-3 potency, and amino acid digestibility scores. Pricing pressure stems from Peruvian anchovy quota volatility transmitting cost spikes into marine protein-dependent formulations. Shrimp producers in Vietnam and Indonesia exhibit highest price sensitivity, while Norwegian salmonid operations prioritize performance metrics over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Santos anchor hub-and-spoke patterns for bulk ingredient flows into European, Southeast Asian, and South American aquaculture zones. Raw material sourcing concentrates in Peru for fishmeal, Brazil and Argentina for soybean meal, and Norway for salmon oil refining. Supply chain risk centers on single-source vulnerability for EPA/DHA concentrates from the Humboldt Current ecosystem. Distribution runs through specialized marine protein traders and oilseed processors before reaching compounder extrusion facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA novel protein approval timelines in Europe lag behind FDA-authorized microbial ingredient scale-up in the United States, creating regulatory-lead time differentials for fermentation facility investment.
For Market Incumbents: Acquire precision fermentation capacity in North American jurisdictions ahead of EFSA authorization expansions. Secure backward integration into algal oil production to decouple from Peruvian anchovy supply volatility. Defend market position by pre-qualifying microbial protein suppliers before novel feed ingredient approvals compress procurement specifications. For New Entrants and Emerging Players: Begin with underpenetrated commercial feed adoption in Andhra Pradesh and Gujarat shrimp farming districts where farm-made feed displacement accelerates. Target certified sustainable soy procurement platforms serving EU export-oriented Vietnamese processors. Establish technical service partnerships with regional extrusion facilities rather than competing on capital-intensive milling infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale compounders lack quality systems infrastructure for simultaneous ASC, BAP, and EU organic certification maintenance. Long-term viability favors acquisition targets with established novel protein supplier relationships and species-specific formulation R&D capabilities. Watch EFSA single-cell protein authorization expansions as the inflection signal for microbial ingredient market share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Enables domestic omega-3 production independent of Peruvian anchovy quotas for Norwegian salmonid feed formulators. |
| Deforestation-Free Supply Chain Certification | Mandatory EU due diligence creates first-mover advantage for soy and palm derivative traceability platforms. |
| Species-Specific R&D Partnership | Shrimp larval nutrition specialization addresses crumble-grade demand expansion in Vietnamese hatchery operations. |
| Integrated Farming Group Direct Sourcing | Bypasses distributor margins as Bergen-to-Stavanger corridor producers specify raw material profiles directly. |
| Novel Protein Regulatory Pre-Submission | Industrial biotech developers align toxicology packages with Parma regulators to compress EFSA approval timelines. |
Research Methodology
Multiple input streams — structured interviews with feed compounder procurement directors, primary discussions with aquaculture nutrition specialists, and secondary validation through regulatory filings — were reconciled to construct segment-level demand estimates. Stakeholder engagement spanned Skretting AS formulation scientists, BioMar Group regional managers, EFSA feed safety officers, and Vietnamese shrimp farming cooperative leaders. Secondary sources included EU Feed Hygiene Regulation documentation, Peruvian PRODUCE anchovy quota announcements, and FAO aquaculture production statistics. Bottom-up volume modeling triangulated against top-down value projections derived from ingredient trade flow analysis.
Data-stream reconciliation applied across the analysis window integrated species-specific feed conversion ratio assumptions with raw material cost trajectories. Segmentation dimensions modeled encompassed ingredient type, physical form, nutritional value tier, and target species digestive physiology. CAGRs were derived from trend extrapolation of certified sustainable procurement adoption rates and microbial protein authorization progressions. Industry-specific forecast inputs included salmonid farming intensity projections for Norwegian sea-cage operations and shrimp pond stocking density trends in Mekong Delta provinces.
Several conditions sit outside the modeled scope, including unannounced EFSA novel protein approval accelerations, abrupt Peruvian anchovy fishery closures, and geopolitical disruptions to South American soybean export flows. Forecasts reflect documented assumptions regarding regulatory trajectory continuity and commodity price correlation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Home Baking Ingredients Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
US Vegetable Oil Market
Ingredients
Bean Flour Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Revivable Yeast Market
Ingredients
Europe Protein Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Native Starch Market
Ingredients
Barley Flake Market
Ingredients
Jasmine Extract Market
Ingredients
Global Tomato Powder Market
Ingredients
Casein Hydrolysate Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Wheat Starch Market