
 China Soy Protein Market | 2026-2036
China Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Soy Protein Market Outlook
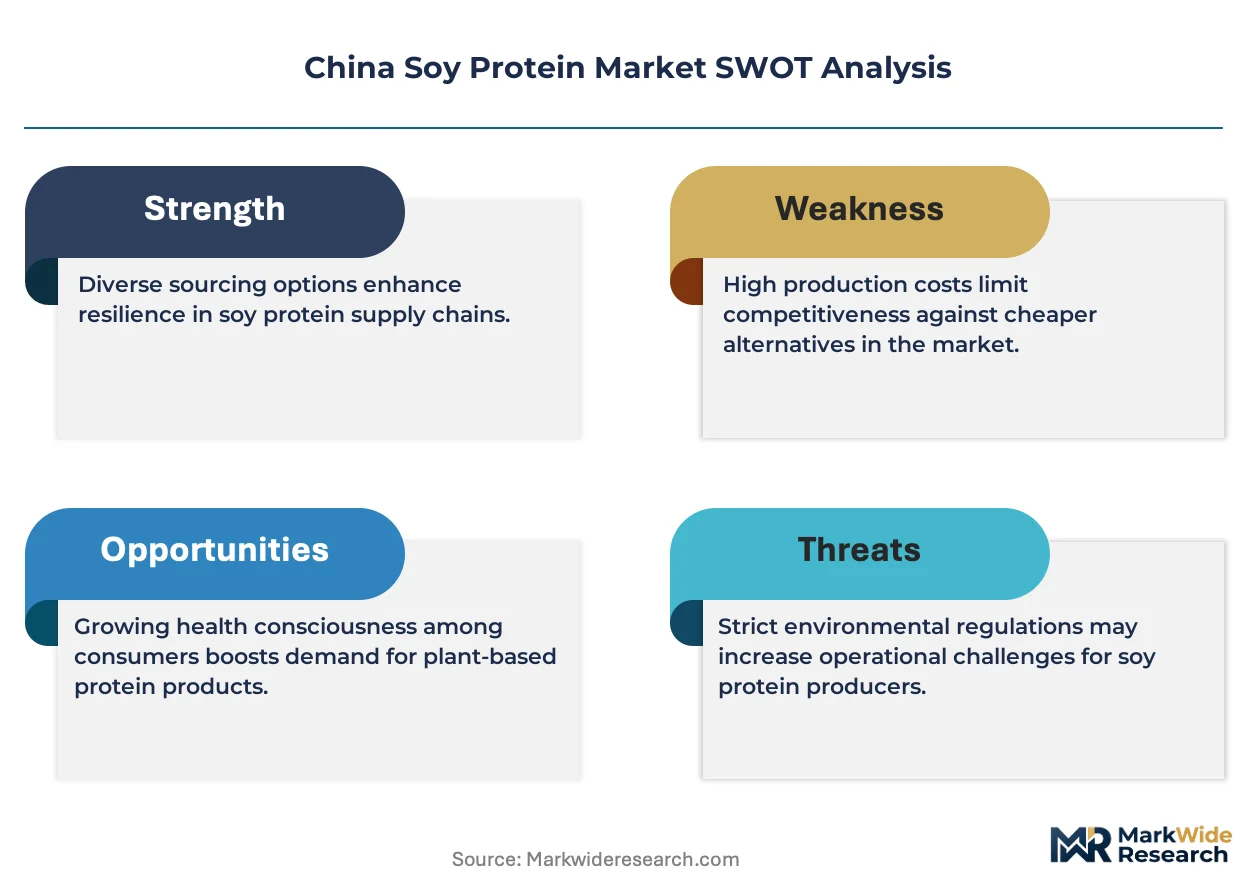
GB 20371 national food safety standards for plant protein is reorganizing market access across China's soy protein sector. Archer Daniels Midland Company leverages its crushing infrastructure in coastal provinces to secure raw material flow. Cargill Incorporated sustains advantage through backward integration into soybean origination and oilseed processing. Crown Soya Protein Group Company dominates domestic textured protein output for regional food manufacturers.
Soy protein denotes protein extracted from defatted soybean meal through alkaline solubilization and isoelectric precipitation, yielding products with protein concentrations ranging from 50% in flour to 90% in isolate grades. The ingredient functions as an emulsifier, water binder, and nutritional fortifier across meat analogs, dairy alternatives, and sports nutrition formulations. Soy isolate commands premium positioning in protein supplements and clinical nutrition due to superior amino acid completeness and minimal flavor carryover. Textured soy protein registers the fastest volume expansion through penetration into quick-service restaurant supply chains and frozen dim sum production.
SAMR administers GB standards compliance for soy protein labeling and additive thresholds, while NMPA oversees novel food ingredient registrations for emerging isolate applications in functional foods. MIIT's dual carbon goals are pressuring processors to retrofit solvent extraction facilities with aqueous or enzyme-based methods. Stakeholders must track evolving GB standard revision timelines and carbon intensity benchmarks to anticipate which processing configurations will retain market access.
Market Dynamics
GB 20371 national food safety standards are reorganizing market access across China's soy protein sector, tightening ingredient disclosure rules and forcing processors to retrofit solvent extraction facilities. MIIT's dual carbon goals pressure manufacturers toward aqueous or enzyme-based methods.
Growth Catalysts
- Textured soy protein adoption:Quick-service restaurant supply chains and frozen dim sum production in the Yangtze River Delta food processing cluster are expanding procurement volumes.
- GB 20371 compliance upgrades:Tighter ingredient disclosure rules under China's updated national food safety standards for plant proteins are accelerating facility modernization.
- Dual carbon policy pressure:MIIT's carbon intensity benchmarks are forcing solvent extraction retrofits, creating demand for aqueous processing equipment.
Market Restraints
- Soybean import dependency:Raw material flow concentrates through coastal crushing infrastructure, exposing margins to origination volatility and maritime logistics.
- Protein isolate technical limitations:Flavor carryover and solubility challenges constrain applications in high-clarity beverage formulations.
- SAMR regulatory friction:Novel food ingredient registrations for emerging isolate applications in functional foods create multi-quarter approval timelines.
Strategic Opportunities
- Guangdong processing expansion:Plant-based meat manufacturers in this province are scaling textured protein procurement faster than Yangtze River Delta saturation.
- Sports nutrition formulation:Soy isolate's amino acid completeness positions it for penetration into protein supplements and clinical nutrition segments.
- Enzyme-aqueous technology convergence:Combining enzymatic extraction with water-based processing reduces solvent residue compliance costs under GB standards.
Industry Challenges
- Carbon accounting skill gaps:Facilities lack personnel trained to document aqueous method carbon intensity for MIIT dual carbon reporting.
- Legacy solvent system capex:Full aqueous retrofitting requires capital deployment for precipitation tanks and membrane filtration arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Soy Protein Market |
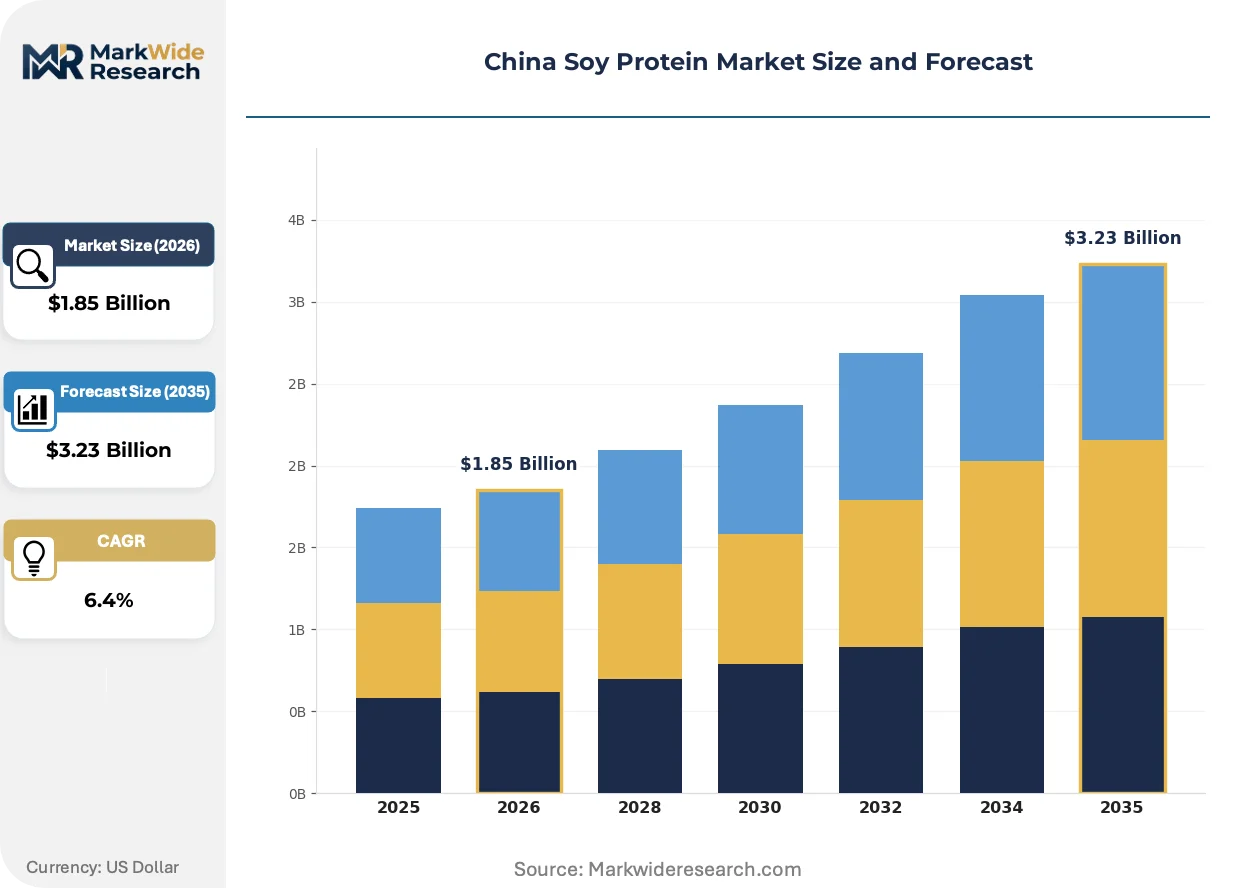
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Isolate, Soy Concentrate, Textured Soy Protein, Soy Flour Application: Meat Alternatives, Dairy Alternatives, Protein Supplements, Bakery Products Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Direct Sales End User: Food Manufacturers, Health-conscious Consumers, Vegetarians, Vegan Athletes |
| Companies Covered | Kerry Group, CJ Group, Archer Daniels Midland Company, China Foodstuff & Protein Group Co., Ltd., DuPont de Nemours, Inc., Cargill Incorporated, Wilmar International Limited, Crown Soya Protein Group Company, Bunge Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Soy Protein Market Strategic Shifts
Enzyme-based extraction methods are displacing hexane solvent systems across China's soy protein processing base. This shift compresses carbon footprints while complicating legacy equipment amortization schedules.
Aqueous extraction technology is displacing conventional hexane-based defatting across coastal processing facilities. Food manufacturers in Shanghai and Guangdong are adopting enzyme-assisted methods to meet GB 20371 residue thresholds. This displacement is compressing capital recovery timelines for solvent-based infrastructure while rewarding early aqueous adopters with SAMR compliance advantages.
GB 20371 national food safety standards for plant proteins are tightening additive thresholds and labeling requirements. Processors must now disclose enzymatic treatment stages and isolate purity grades on consumer packaging. Textured soy protein destined for quick-service restaurant supply chains faces the steepest compliance burden, with manufacturers accelerating aqueous method validation to maintain access.
Buyer concentration among Yangtze River Delta food processing clusters is shortening procurement cycles for textured protein grades. Large frozen dim sum producers are consolidating supplier rosters and demanding carbon intensity documentation alongside GB compliance certificates. This behavioral shift is most visible in Shanghai, where plant-based meat manufacturers now specify aqueous-extracted isolates in tender specifications.
China Soy Protein Market Segmentation
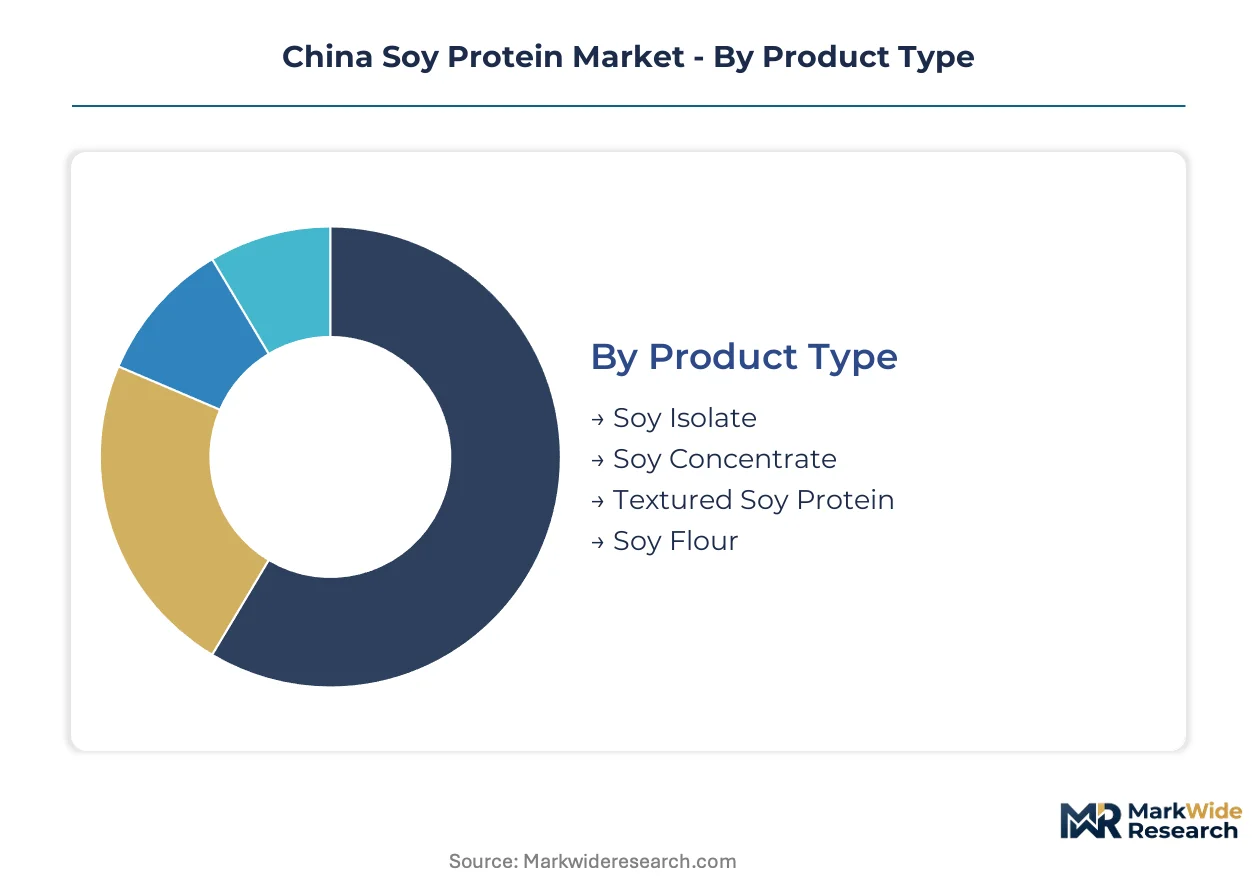
Segmentation reveals how GB 20371 compliance costs and MIIT carbon benchmarks redistribute margin pools across China's soy protein value chain. Product grade and application end-use determine which processors capture premium positioning versus commodity exposure.
Product Type:
Margin pools concentrate in high-purity grades where SAMR labeling requirements create compliance barriers for smaller processors.
- Soy Isolate:Protein concentrations reach 90% through isoelectric precipitation and membrane filtration. Shanghai sports nutrition formulators specify isolates for clinical nutrition applications, paying premiums for enzymatic extraction methods that satisfy GB 20371 residue thresholds.
- Textured Soy Protein:Extruded defatted meal creates fibrous structures mimicking meat mouthfeel. Guangdong plant-based meat manufacturers are expanding procurement volumes fastest, driven by quick-service restaurant supply chain penetration and frozen dim sum production demand in the Yangtze River Delta.
- Soy Concentrate:70% protein content achieved through aqueous leaching of soluble carbohydrates. Food manufacturers use concentrates for cost-sensitive meat extension applications.
- Soy Flour:50% protein baseline product from minimally processed defatted meal. Bakery applications in regional processing clusters absorb steady volumes at thin margins.
Soy Isolate holds installed capacity. Textured Soy Protein is rotating up the share rankings.
Application:
End-use demand splits between industrial food manufacturing and direct consumer nutrition, with diverging price elasticity and regulatory exposure.
- Meat Alternatives:Textured proteins formulated into analogs for quick-service restaurant supply chains. Guangdong processors lead volume expansion, though Yangtze River Delta frozen dim sum producers are consolidating supplier rosters and demanding carbon intensity documentation.
- Protein Supplements:Isolates dominate sports nutrition and clinical nutrition formulations. Superior amino acid completeness positions soy isolate against whey alternatives, though flavor carryover constraints limit high-clarity beverage applications.
- Dairy Alternatives:Concentrates and isolates provide emulsification and protein fortification in plant-based milk and yogurt analogs. SAMR novel food ingredient registrations create multi-quarter approval timelines for functional positioning claims.
- Bakery Products:Soy flour and concentrates extend shelf life and improve crumb structure in commercial baking. Cost-driven procurement from regional food manufacturers keeps margins compressed.
Meat Alternatives anchor volume demand. Protein Supplements command the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect buyer concentration patterns, with industrial procurement cycles shortening against fragmented retail.
- Direct Sales:Food manufacturers in Shanghai and Guangdong negotiate long-term supply agreements with processors, consolidating textured protein procurement and demanding aqueous extraction validation.
- Online Retail:Isolate and concentrate sales to health-conscious consumers and vegan athletes accelerate through e-commerce platforms, bypassing traditional retail markups.
- Supermarkets:Packaged soy protein ingredients reach household consumers through mass retail, though shelf space competition from international brands constrains domestic processor margins.
- Health Food Stores:Specialty retailers stock premium isolate grades for sports nutrition segments, serving niche demand with higher service intensity.
Direct Sales captures institutional volume. Online Retail is climbing the fastest.
End User:
User sophistication determines specification stringency, with industrial buyers driving process technology upgrades.
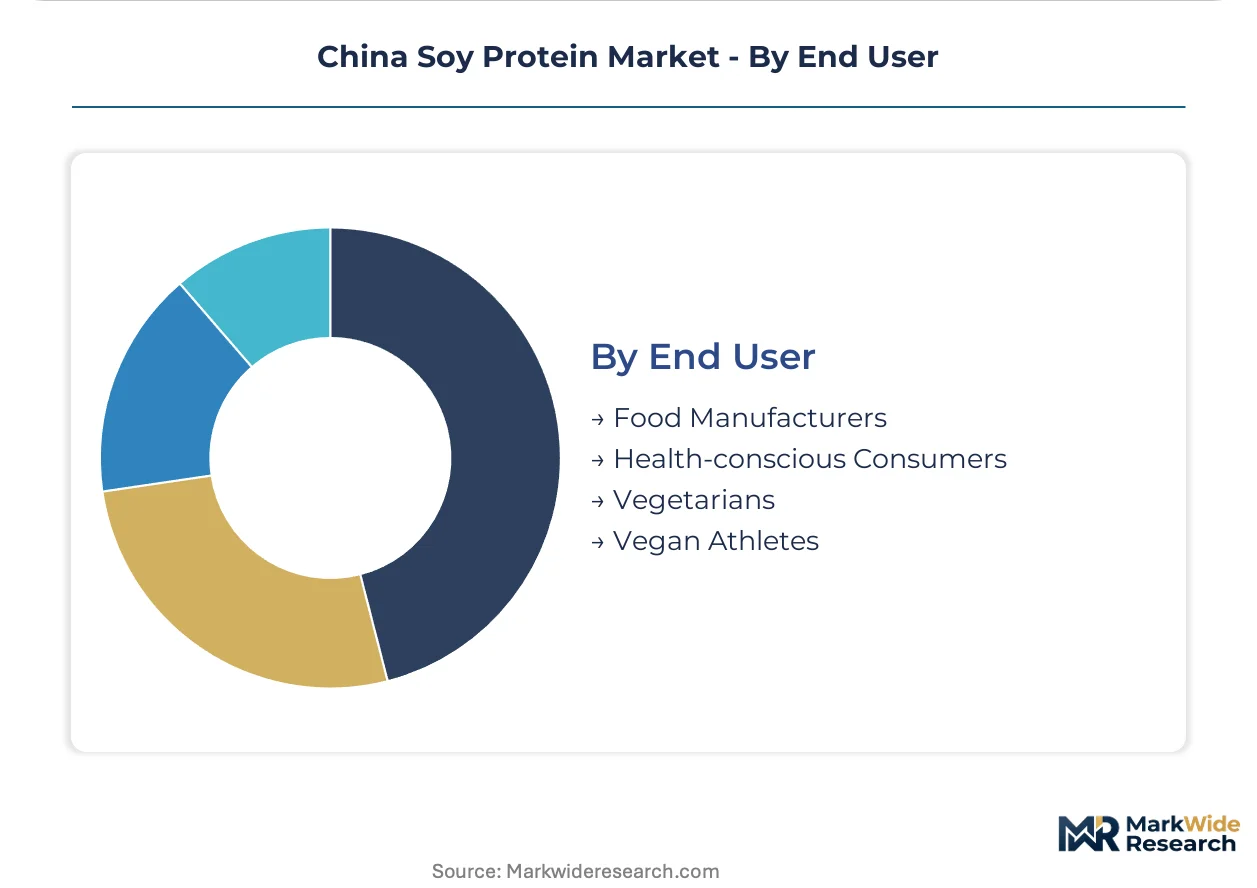
- Food Manufacturers:Yangtze River Delta processing clusters specify aqueous-extracted isolates in tender documentation, consolidating supplier rosters around GB 20371 compliance and carbon intensity benchmarks.
- Health-conscious Consumers:Direct purchases of isolate and concentrate grades for home formulation, price-sensitive but responsive to protein content labeling transparency.
- Vegetarians:Sustained demand for textured proteins as meat alternatives, with preference for clean-label enzymatic processing methods disclosed on packaging.
- Vegan Athletes:Premium isolate consumption in protein supplementation, driving amino acid completeness specifications and minimal flavor carryover requirements.
Food Manufacturers dominate procurement scale. Vegan Athletes are gaining share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deep-water port infrastructure anchors China's soy protein distribution, with Shanghai's container terminals processing defatted meal imports for downstream isolates and textured proteins.
Yangtze River Delta
Shanghai's food processing cluster drives textured soy protein demand through quick-service restaurant supply chains and frozen dim sum production. SAMR enforces GB 20371 labeling requirements that processors must satisfy to access this buyer concentration. Suzhou and Wuxi house aqueous extraction retrofit projects targeting MIIT carbon intensity benchmarks.
Pearl River Delta
Guangdong's plant-based meat manufacturers are expanding procurement faster than Yangtze River Delta saturation rates. GB standards for plant protein additive thresholds tighten disclosure rules for enzymatic treatment stages. Shenzhen processors validate carbon accounting documentation to supply industrial buyers consolidating supplier rosters.
Beijing-Tianjin-Hebei
Sports nutrition formulators in Beijing specify soy isolates for clinical nutrition applications, paying premiums for superior amino acid completeness. NMPA oversees novel food ingredient registrations that create multi-quarter approval timelines for functional positioning claims. Tianjin's crushing infrastructure secures raw material flow through coastal origination.
Shandong Peninsula
Qingdao's oilseed processing base supplies defatted meal to regional isolates and concentrates production. MIIT dual carbon goals pressure facilities toward enzyme-based extraction methods that reduce solvent residue compliance costs. Yantai processors retrofit precipitation tanks and membrane filtration arrays for aqueous system conversion.
Sichuan-Chongqing
Chongqing's food manufacturing sector absorbs soy flour and concentrates for cost-sensitive meat extension and bakery applications. Provincial environmental regulators align with national carbon intensity reporting requirements for aqueous method validation. Chengdu distribution hubs connect western China demand to coastal processing capacity.
China Soy Protein Market Competitive Environment
Listed leaders compete with private specialists across processing technology and compliance certification tiers. The vendor base separates into consolidated multinational traders with crushing infrastructure, domestic textured protein specialists with regional food manufacturer relationships, and diversified agribusiness operators with backward integration into soybean origination. Strategic moves concentrate on aqueous extraction capacity expansion and GB 20371 compliance certification acquisition.
Within the multinational trading tier, Archer Daniels Midland Company and Cargill Incorporated occupy positions anchored by coastal crushing infrastructure and origination control. Crown Soya Protein Group Company exemplifies the domestic specialist archetype with concentrated output for Yangtze River Delta food manufacturers. These three represent distinct competitive vectors: captive supply chains, regulatory compliance depth, and regional buyer consolidation.
| Leading Market Players |
|---|
| Kerry Group |
| CJ Group |
| Archer Daniels Midland Company |
| China Foodstuff & Protein Group Co., Ltd. |
| DuPont de Nemours, Inc. |
| Cargill Incorporated |
| Wilmar International Limited |
| Crown Soya Protein Group Company |
| Bunge Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Yangtze River Delta food manufacturers and coastal processors lock in both soybean meal supply access and price visibility against volatile maritime logistics. These agreements concentrate procurement power among frozen dim sum producers and quick-service restaurant suppliers while compressing spot market liquidity for smaller textured protein buyers.
Pricing Analysis
GB 20371 compliance certification creates the primary spread between aqueous-extracted isolates and legacy solvent-based grades. Three-tier pricing structure across enzymatic premium, aqueous standard, and solvent economy levels stratifies the market, with Shanghai sports nutrition formulators paying steep premiums for carbon intensity documentation. Cost compression in solvent-extracted concentrates is intensifying because MIIT dual carbon retrofit deadlines accelerate facility obsolescence. Regional bakery manufacturers represent the most price-sensitive segment, while clinical nutrition buyers exhibit minimal elasticity for amino acid completeness.
Supply Chain Analysis
Strategic stockpiling of defatted soybean meal dominates inventory strategy among coastal crushing facilities, buffering against Brazilian and Argentine origination volatility. Raw material flow centers on imported soybeans from Brazil, Argentina, and the United States, with domestic crushing infrastructure concentrated in Shandong and Guangdong provinces. Single-source vulnerability runs through maritime chokepoints at Shanghai and Ningbo-Zhoushan ports. Distribution feeds from processor direct sales into Yangtze River Delta and Pearl River Delta food manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's soy protein market functions as a regulatory entrenchment story where GB 20371 compliance certification and carbon intensity documentation create formidable switching costs for industrial buyers. Network effects concentrate among aqueous extraction adopters who capture tender specifications from consolidating food manufacturer rosters.
For Market Incumbents: Consolidate supplier relationships with Yangtze River Delta frozen dim sum producers by embedding carbon accounting services into long-term contracts. Accelerate aqueous retrofit completion at Shandong facilities before MIIT dual carbon enforcement windows tighten, capturing stranded solvent-based competitors. For New Entrants and Emerging Players: Anchor in Guangdong's plant-based meat manufacturing expansion where textured protein procurement growth outpaces Yangtze River Delta saturation. Target sports nutrition isolate formulations for vegan athletes, leveraging enzyme-based extraction as a clean-label differentiation wedge against established solvent processors. For Investors and Strategic Acquirers: The market sits at a compliance-transition phase that favors aqueous technology specialists with validated carbon documentation capabilities. Five-to-ten year viability hinges on processors achieving MIIT dual carbon benchmarks ahead of enforcement escalation. Acquisition focus should center on mid-cap facilities with membrane filtration arrays and precipitation tank infrastructure. The signal to watch is SAMR novel food ingredient registration approval velocity for functional isolate applications.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Extraction Retrofit | MIIT dual carbon compliance secures market access against solvent facility obsolescence. |
| Carbon Accounting Certification | Yangtze River Delta buyer consolidation demands documented intensity for tender eligibility. |
| Enzyme-Assisted Technology Licensing | GB 20371 residue thresholds reward early adopters with SAMR compliance advantages. |
| Backward Integration into Crushing | Coastal origination control buffers Brazilian supply volatility for isolate producers. |
| Sports Nutrition Formulation Partnership | Clinical nutrition applications command premium pricing for amino acid completeness. |
Study Parameters
Cross-validation between primary interviews with plant operations managers, food manufacturer procurement leads, and regulatory affairs specialists anchors the qualitative findings against secondary validation. Bottom-up and top-down triangulation draws from SAMR GB standard revision filings, MIIT carbon intensity disclosure databases, coastal customs import records, and NMPA novel food ingredient registration logs.
Sensitivity analysis across product grade tiers, extraction technology configurations, and regional buyer concentration patterns informs the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by compliance cost pass-through elasticity. Modeled inputs include enzyme-based processing capacity buildout schedules and GB 20371 enforcement phase-in assumptions.
Decision-makers should treat outputs as directional under stable Brazilian soybean origination and MIIT dual carbon timeline assumptions; material deviation would warrant model refresh. Revision becomes warranted when SAMR accelerates novel food ingredient registration timelines or maritime logistics disruptions exceed historical variance bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Psyllium Husk Powder Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
North America Corn Starch Market
Ingredients
Mineral Premix Market
Ingredients
Functional Flours Market
Ingredients
South America Vegetable Oil Market
Ingredients
Chickpea Fiber Market
Ingredients
Fruit Concentrate Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Carotenes Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
North America Potato Starch Market
Ingredients
Sugar Beet Pectin Market