
 Cold Water Swelling Starch Market | 2026-2036
Cold Water Swelling Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Water Swelling Starch Market Outlook
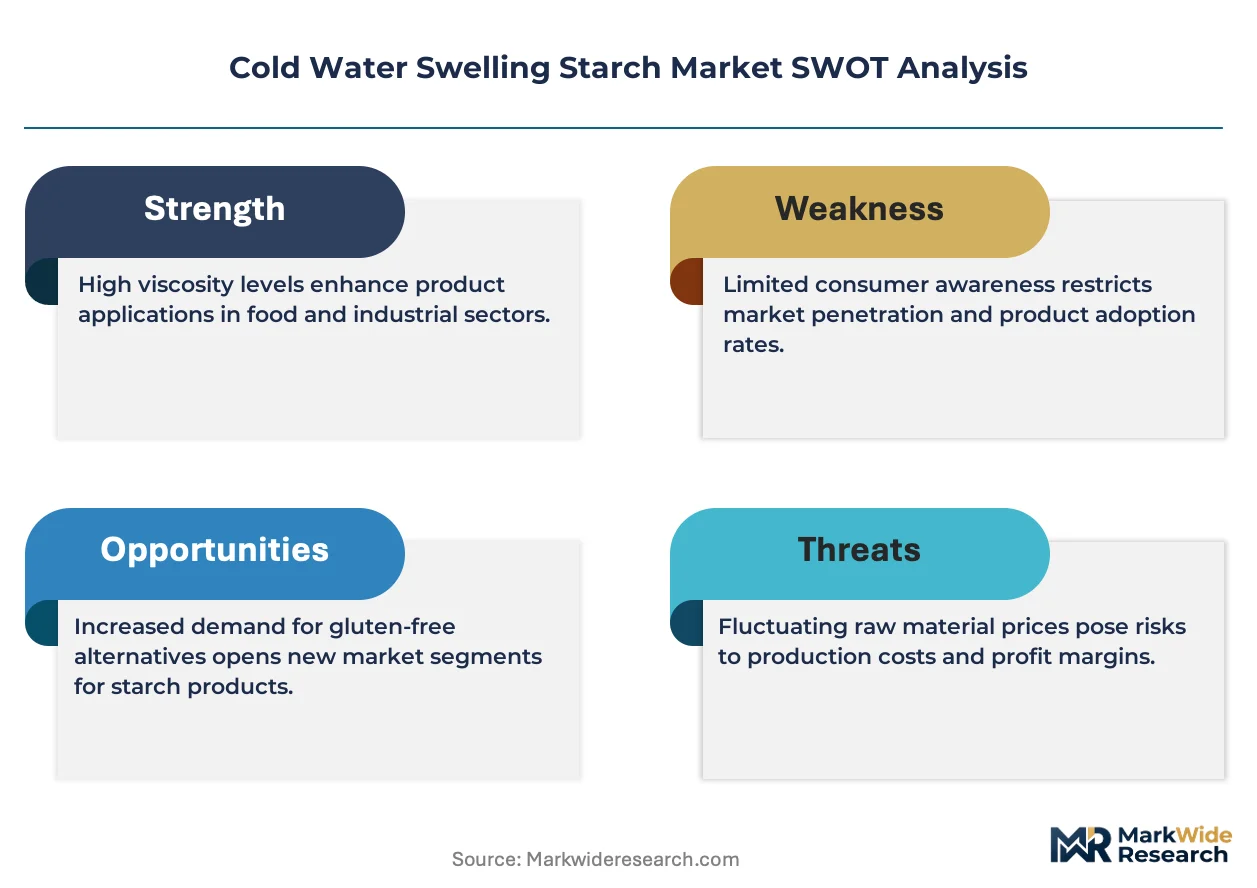
Ingredient customization revenue is rewriting profitability expectations across the value chain. Cargill leverages its North American grain origination network to secure waxy corn supply for cold water swelling variants. Roquette Frères anchors European demand through its potato starch specialization and pharma-grade certification. Tate & Lyle PLC differentiates via tapioca-based instant starch formulations targeting Asian food service channels.
Cold water swelling starch refers to pregelatinized starch granules that hydrate and develop viscosity without heat application, typically manufactured through drum drying or extrusion to achieve rapid dispersibility in ambient-temperature liquids. Its primary purpose centers on enabling cold-process food manufacturing, pharmaceutical tablet binding, and personal care emulsion stability where thermal processing would degrade active ingredients or sensory profiles. Modified starch dominates current revenue contribution due to established supply chains and broad functionality across thickening and stabilizing applications, while organic starch represents the fastest-expanding category as EU organic labeling regulations and North American non-GMO project verification create premium positioning. Instant starch occupies a specialized niche in food service and convenience product formulations where reconstitution speed determines operational throughput.
The FDA governs food-grade starch purity and labeling in the United States, while the EMA and EFSA jointly shape pharmaceutical excipient standards and food additive safety assessments across European markets. REACH compliance requirements for chemical processing aids used in starch modification affect import access and manufacturing location decisions for suppliers serving European industrial buyers. Stakeholders must monitor evolving clean-label certification thresholds and regional regulatory divergence between North American and European frameworks to align product portfolios with diverging compliance costs and premium positioning opportunities.
Market Dynamics
Clean-label formulation mandates from major retail chains are compressing acceptable ingredient lists and forcing starch suppliers to requalify excipient grades without synthetic processing aids. This pressure converges with FDA purity benchmark tightening and EU organic certification expansion to reshape supplier qualification timelines.
Growth Catalysts
- Clean-label retail mandates:Major grocery chains now require non-GMO verification and synthetic additive exclusion, pulling cold water swelling starch into reformulated sauces and ready meals.
- EMA pharmaceutical excipient standards:Updated purity protocols for tablet binders are disqualifying heat-processed alternatives in European generic drug manufacturing.
- Drum drying efficiency gains:Energy recovery systems in pregelatinization equipment are lowering unit costs for ambient-hydration starch variants.
Market Restraints
- Waxy corn supply concentration:North American grain origination networks control premium amylopectin feedstock, exposing processors to crop yield volatility.
- REACH chemical processing aid restrictions:Modification reagents face authorization hurdles that extend European market entry timelines for Asian suppliers.
- Native starch price compression:Unmodified alternatives in paper and textile applications limit pricing power at the commodity end of the spectrum.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-NF and EP compliance for cold-process tablet binding opens high-margin supply contracts with generic drug manufacturers.
- Personal care emulsion stability:Skincare formulators are adopting instant starch to replace synthetic rheology modifiers in clean beauty positioning.
- Asian food service channels:Tapioca-based instant formulations address ambient-temperature reconstitution needs in tropical climate quick-service operations.
Industry Challenges
- Pharma-grade validation timelines:Excipient master file preparation and FDA Type II DMF submission cycles extend working capital lockup periods.
- Clean-label certification stacking:Simultaneous Non-GMO Project, EU organic, and kosher audits multiply compliance overhead without harmonized documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Water Swelling Starch Market |
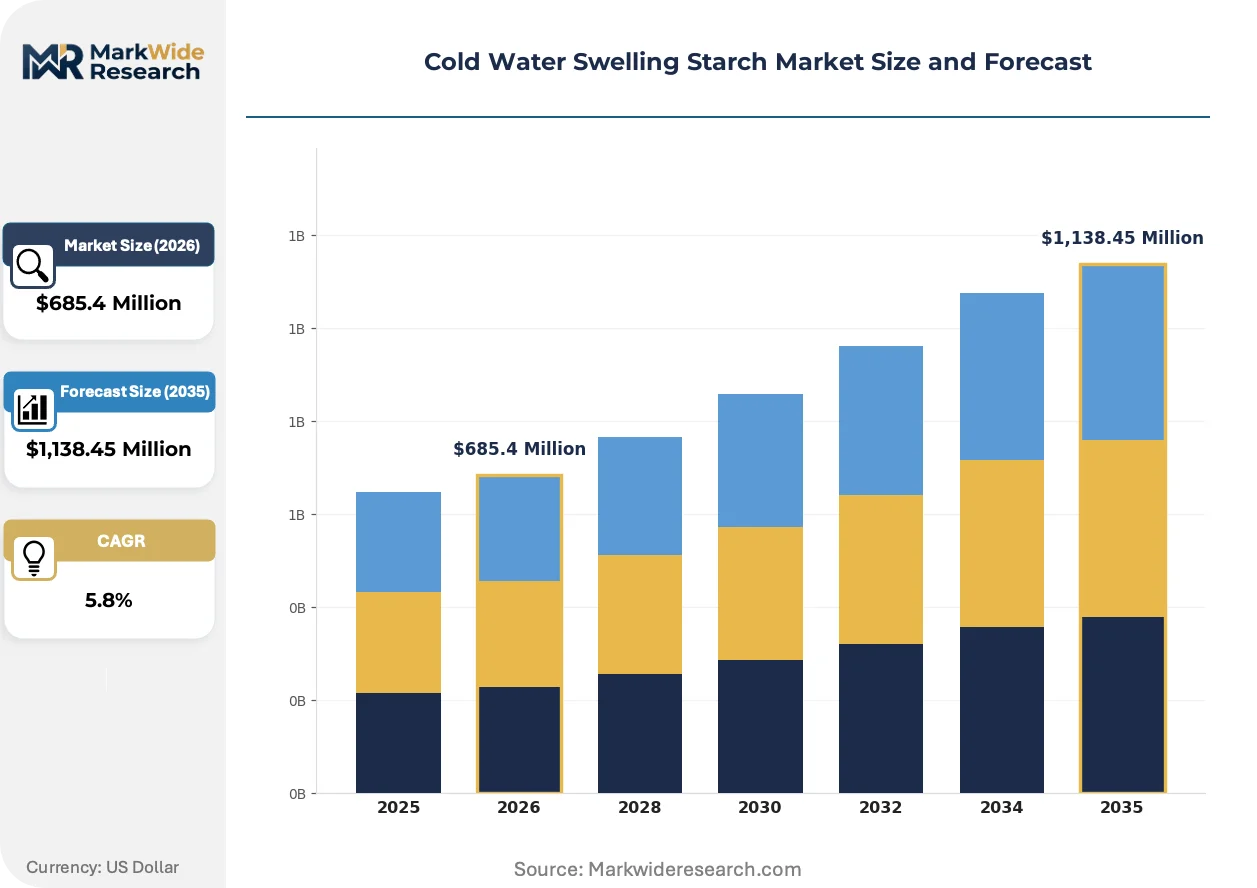
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Organic Starch, Non-GMO Starch, Instant Starch End User: Food Industry, Pharmaceutical Sector, Bakery Products, Personal Care Application: Thickening Agent, Stabilizer, Texture Modifier, Emulsifier Distribution Channel: Online Retail, Food Service, Direct Sales, Specialty Stores |
| Companies Covered | Ingredion Incorporated, Cargill, Tate & Lyle PLC, Archer Daniels Midland Company, Roquette Frères, AVEBE U.A., KMC, Grain Processing Corporation, Tereos S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Water Swelling Starch Market Strategic Shifts
Processing technology convergence and regulatory divergence are creating parallel innovation tracks—one optimizing manufacturing efficiency, the other redefining acceptable ingredient provenance for premium positioning.
Extrusion-cooked pregelatinization is hybridizing with controlled moisture drum drying to produce cold water swelling starches with tunable viscosity profiles and cleaner flavor footprints. Industrial bakeries in Germany and pharmaceutical contract manufacturers in Switzerland are adopting these hybrid-process variants to reduce hydration time without heat-degrading active ingredients. The technology is hybridizing equipment supplier portfolios as single-process vendors lose specification battles to integrated system providers.
REACH authorization requirements for chemical modification reagents are forcing reformulation of cross-linked starch variants used in European food and pharma applications. ECHA's 2024 updated candidate list for substances of very high concern now captures several phosphate esterification catalysts common in viscosity-stable starch production. Suppliers serving EU industrial buyers are accelerating enzymatic modification research to bypass synthetic processing aid dependencies entirely.
Ingredient specification centralization by multinational food manufacturers is consolidating approved supplier lists and extending qualification cycles for regional starch processors. Category managers at major sauce and dressing brands now mandate simultaneous clean-label certification, carbon footprint disclosure, and allergen-free facility audits before trial volumes. This concentration is most visible in German and Benelux industrial bakery clusters where three-buyer networks control the majority of modified starch procurement decisions.
Cold Water Swelling Starch Market Segmentation
Cold water swelling starch suppliers engineer distinct product architectures to match formulation constraints across ambient-temperature processing environments. Segment-specific qualification requirements—pharmaceutical excipient certification versus clean-label food verification—determine margin structures and customer lock-in intensity.
Product Type:
After-sales service intensity escalates with regulatory complexity, as pharmaceutical and organic grades demand ongoing compliance documentation and batch-specific certification support.
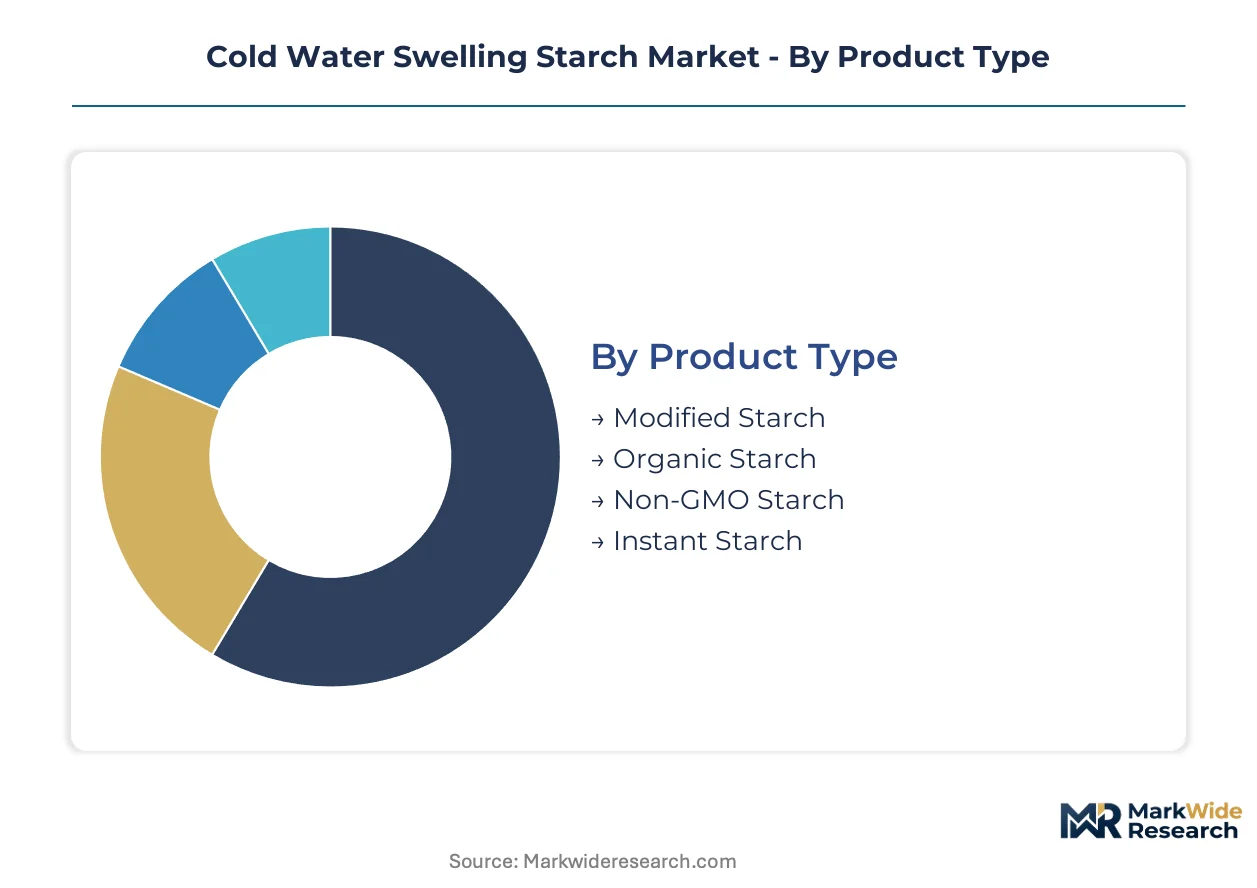
- Modified Starch:Cross-linked and pregelatinized variants deliver tunable viscosity profiles through phosphate esterification or enzymatic treatment. Industrial bakeries in Germany specify these grades for cold-process dough conditioning where thermal degradation would compromise texture. FDA purity benchmark tightening and REACH authorization hurdles for chemical processing aids are extending qualification timelines for Asian suppliers seeking European market entry.
- Organic Starch:EU organic labeling regulations and North American Non-GMO Project verification create premium positioning through synthetic additive exclusion and traceable supply chains. German pharmaceutical excipient producers and clean-label sauce manufacturers in the Benelux region are expanding procurement of certified organic grades to meet retailer mandate compliance.
- Non-GMO Starch:Identity-preserved grain sourcing from North American waxy corn networks supports clean-label positioning without full organic certification overhead.
- Instant Starch:Extrusion-cooked or drum-dried granules engineered for rapid ambient-temperature hydration in tropical climate food service operations.
Modified starch holds the largest share; momentum sits with organic starch as certification stacking multiplies compliance overhead for conventional alternatives.
End User:
Cost tier differentiation separates commodity-grade applications from high-margin certified segments where documentation burden justifies pricing premiums.
- Food Industry:Sauce, dressing, and ready meal manufacturers specify cold water swelling starch for cold-process thickening where heat would degrade flavor compounds or active ingredients. Clean-label retail mandates from major grocery chains are compressing acceptable ingredient lists and forcing reformulation toward non-GMO and organic certified grades.
- Pharmaceutical Sector:Tablet binders and controlled-release matrices require USP-NF and EP compliance with excipient master file documentation. Swiss contract manufacturers and German generic drug producers are adopting cold-process starch to avoid heat degradation of temperature-sensitive APIs.
- Bakery Products:Industrial-scale bread and pastry operations in Germany leverage instant starch for ambient-temperature dough conditioning and moisture retention.
- Personal Care:Skincare formulators replace synthetic rheology modifiers with instant starch to achieve clean beauty positioning in emulsion stability applications.
The food industry commands volume leadership; pharmaceutical sector applications are expanding most quickly as EMA excipient standards disqualify heat-processed alternatives.
Application:
Volume concentration tracks formulation complexity, with multi-functional grades commanding premium positioning over single-purpose commodity variants.
- Thickening Agent:Cold water swelling starch develops viscosity without heat application, enabling ambient-temperature processing in sauce and soup manufacturing. Asian food service channels in tropical climates specify tapioca-based instant formulations where rapid reconstitution determines operational throughput.
- Stabilizer:Cross-linked variants maintain viscosity through freeze-thaw cycles and acid exposure, supporting extended shelf-life requirements in dressing and dairy applications.
- Texture Modifier:Granule architecture engineering delivers specific mouthfeel profiles from creamy to pulpy in convenience food formulations.
- Emulsifier:Surface-modified starch granules stabilize oil-water interfaces in personal care emulsions and reduced-fat food systems.
Thickening applications anchor current demand; stabilizer functionality is gaining share fastest as clean-label mandates displace synthetic hydrocolloids.
Distribution Channel:
Supply concentration favors direct relationships with large-scale industrial buyers, while specialty channels serve fragmented premium segments requiring technical support.
- Direct Sales:Multinational food manufacturers and pharmaceutical contract producers negotiate long-term supply agreements with integrated technical service support. Ingredient specification centralization by major sauce and dressing brands mandates simultaneous clean-label certification, carbon footprint disclosure, and allergen-free facility audits before trial volumes.
- Food Service:Quick-service operators and institutional caterers procure instant starch through broadline distributors for ambient-temperature reconstitution in tropical climate operations.
- Online Retail:E-commerce platforms serve small-scale bakery and personal care formulators requiring lower minimum order quantities with delayed technical support response.
- Specialty Stores:Regional distributors focus on organic and non-GMO certified grades for artisanal food producers and independent cosmetic formulators.
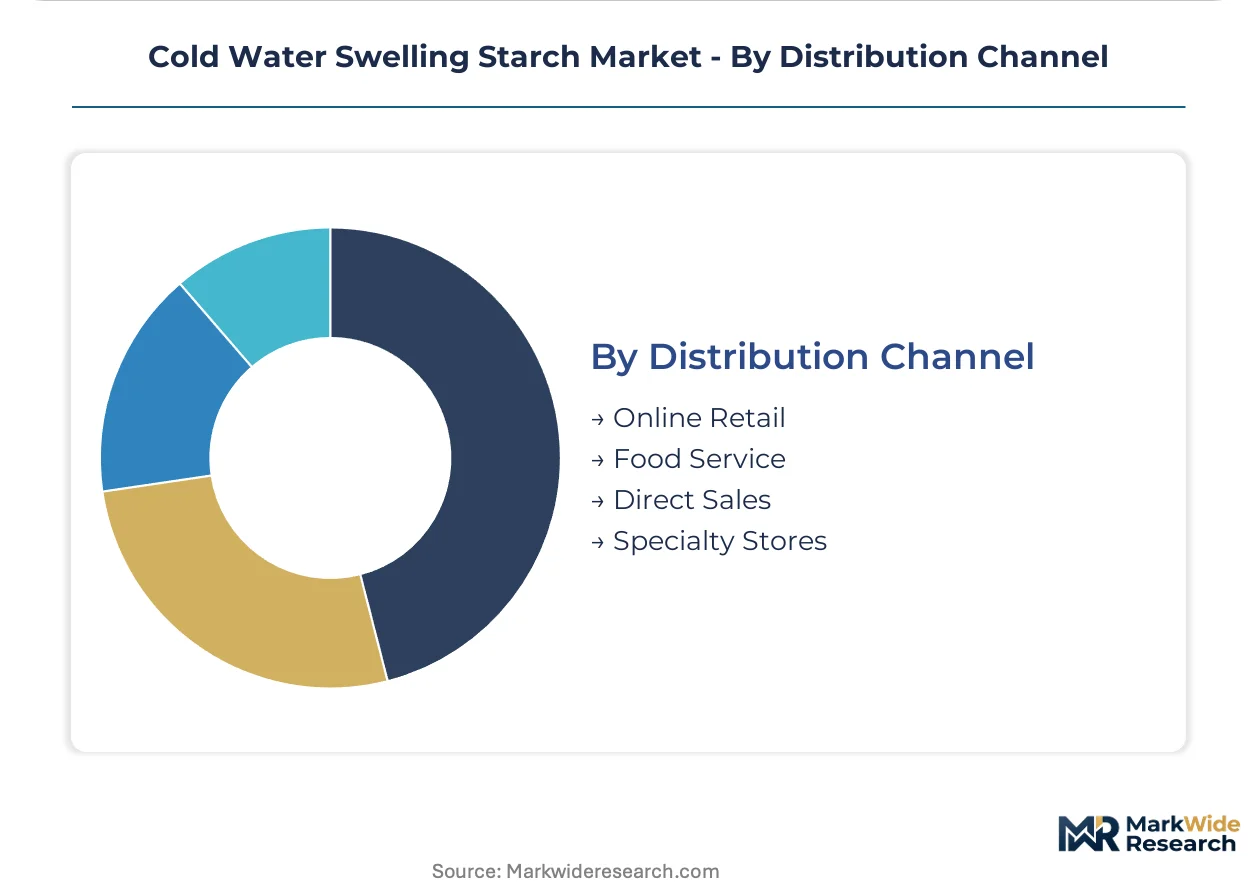
Direct sales capture the largest share; food service channels are climbing the fastest as quick-service penetration expands in Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German pharmaceutical excipient buyers absorb premium pricing for certified grades, while Southeast Asian food service operators prioritize cost-efficient instant formulations. This divergence shapes regional supply strategies.
Germany
Industrial bakeries in Baden-Württemberg and pharmaceutical contract manufacturers in Bavaria drive demand for drum-dried pregelatinized starch. EMA excipient purity protocols are disqualifying heat-processed alternatives in generic drug production. The Mannheim-Ludwigshafen chemical cluster hosts modified starch processing facilities expanding capacity for cold-process tablet binders.
United States
North American waxy corn origination networks supply premium amylopectin feedstock for modified starch production. FDA food additive review protocols are tightening purity benchmarks for imported modified starch grades. Midwest grain processing hubs in Iowa and Illinois anchor domestic pregelatinization capacity serving sauce and dressing manufacturers.
Switzerland
Swissmedic pharmaceutical standards and proximity to German generic drug markets position the country as a high-margin excipient demand center. REACH authorization requirements for chemical modification reagents are accelerating enzymatic starch research at Basel-area biotech clusters. The Basel-Land canton hosts specialty chemical facilities qualifying cold water swelling grades for USP-NF compliance.
China
Tapioca-based instant starch production in Guangxi and Yunnan provinces targets Southeast Asian food service channels. SAMR food additive safety assessments and GB standards for modified starch are converging with international purity benchmarks. The Pearl River Delta manufacturing belt supplies ambient-hydration grades for tropical climate quick-service operations.
India
Domestic pharmaceutical tablet manufacturing in Maharashtra and Gujarat is adopting cold-process starch binders to protect temperature-sensitive APIs. CDSCO excipient guidelines and FSSAI food additive regulations are tightening documentation requirements for imported grades. The Mumbai-Pune industrial corridor hosts formulation facilities qualifying new excipient suppliers for generic drug export contracts.
Cold Water Swelling Starch Market Competitive Environment
Capability concentration sits with specialized pharma-grade certifiers; scale advantage sits with integrated grain processors. The market structures around three tiers: multinational agribusiness conglomerates with captive feedstock, European potato starch specialists with pharmaceutical certification depth, and regional tapioca processors serving tropical food service channels. Dominant competitive moves include backward integration into identity-preserved grain sourcing and strategic partnerships with excipient master file consultants to compress FDA qualification timelines.
Among North American agribusiness conglomerates, Cargill and Archer Daniels Midland Company exemplify the scale-driven archetype with captive waxy corn supply chains. Roquette Frères and AVEBE U.A. occupy positions within the European specialist tier, leveraging potato starch origin and pharmaceutical-grade processing infrastructure. Tate & Lyle PLC represents the formulation-technology vector, with tapioca-based instant starch development targeting Asian ambient-temperature reconstitution requirements.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Roquette Frères |
| AVEBE U.A. |
| KMC |
| Grain Processing Corporation |
| Tereos S.A. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Asian tapioca processing facilities is compressing spot pricing for instant starch grades while tightening margins for drum-dried variants in European pharma-certified tiers. This utilization divergence is forcing suppliers to redirect feedstock toward higher-margin excipient contracts and away from commoditized food service channels.
Pricing Analysis
After-sales service revenue from ongoing compliance documentation and batch-specific certification support drives lifetime value in pharmaceutical and organic grades. Three-tier pricing structure across premium, standard, and economy levels separates USP-NF certified excipients from clean-label food grades and unmodified native starch. Cost compression in the economy tier is intensifying because Asian suppliers face REACH authorization hurdles that extend European market entry timelines. Industrial bakeries in Germany exhibit lowest price sensitivity due to formulation lock-in, while Southeast Asian quick-service operators prioritize cost-efficient instant formulations.
Supply Chain Analysis
Tariff exposure between North American grain markets and European pharmaceutical buyers dominates supply chain risk planning for modified starch processors. Feedstock sourcing draws from Iowa and Illinois waxy corn networks, Guangxi and Yunnan tapioca plantations, and Benelux potato starch cooperatives. Single-source vulnerability concentrates in North American amylopectin supply where crop yield volatility threatens premium feedstock availability. Distribution runs through direct long-term supply agreements with multinational food manufacturers and pharmaceutical contract producers, supplemented by broadline distributors serving fragmented food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers to entry. Certification stacking requirements and excipient master file preparation cycles lock in incumbent positions.
For Market Incumbents: Harden qualification timelines by accelerating enzymatic modification research to bypass REACH-authorized chemical processing aids entirely. Expand backward integration into identity-preserved grain sourcing to secure captive waxy corn supply against crop yield volatility. Deepen technical service capabilities to extend customer lock-in through ongoing compliance documentation support. For New Entrants and Emerging Players: Build out personal care emulsion stability applications where clean beauty positioning displaces synthetic rheology modifiers with minimal regulatory overhead. Target Southeast Asian food service channels with tapioca-based instant formulations optimized for tropical climate ambient-temperature reconstitution. Pursue white-label partnerships with regional distributors serving artisanal bakery and independent cosmetic formulator segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharma-grade certifiers with established USP-NF and EP compliance infrastructure. Long-term viability centers on suppliers with demonstrated excipient master file preparation capabilities and FDA Type II DMF submission track records. Monitor ECHA candidate list updates for substances of very high concern as inflection indicators for enzymatic modification technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Grain Sourcing | Cargill and ADM secure captive waxy corn supply against North American crop yield volatility. |
| Enzymatic Modification Technology Development | Roquette Frères and AVEBE bypass REACH-authorized phosphate esterification catalysts for European market access. |
| Pharmaceutical Excipient Master File Preparation | Swiss and German contract manufacturers compress FDA Type II DMF submission cycles for generic drug supply contracts. |
| Asian Food Service Channel Expansion | Tate & Lyle PLC targets tropical climate quick-service operations with tapioca-based instant starch formulations. |
| Clean Beauty Personal Care Positioning | Specialty starch suppliers replace synthetic rheology modifiers in skincare emulsion stability applications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at modified starch processing facilities, procurement leads at industrial bakeries and pharmaceutical contract manufacturers, technical R&D directors developing enzymatic modification processes, and distribution channel partners serving food service and specialty store segments. Secondary validation drew from FDA food additive filings, EMA excipient guidelines, ECHA REACH authorization databases, and customs trade data tracking waxy corn and tapioca starch flows. Bottom-up volume modeling across product type, end user, application, and distribution channel segments was triangulated against top-down market sizing from grain processing capacity disclosures.
Calibration against historical capacity utilization rates and qualification timeline benchmarks anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included modified versus organic versus instant starch grades, food industry versus pharmaceutical sector versus personal care end users, thickening versus stabilizing versus emulsifying applications, and direct sales versus food service versus online retail channels. CAGRs were derived from elasticity-adjusted demand projections incorporating clean-label retail mandate penetration rates and EMA excipient standard adoption curves.
Stress conditions across waxy corn yield volatility, REACH authorization timeline extensions, and FDA purity benchmark tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained clean-label certification stacking requirements and pharmaceutical excipient demand conversion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Murumuru Butter Market
Ingredients
Potato Starch Market
Ingredients
Banana Essence Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Lupin Flour Market
Ingredients
Plant Based Thickener Market
Ingredients
Savory Ingredients Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Pet Food Premix Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
All Purpose Flour Market
Ingredients
Starch Market
Ingredients
Fluid Lecithin Market
Ingredients
Organic Starch Market
Ingredients
Passion Fruit Powder Market