
 Specialty Yeast Market | 2026-2036
Specialty Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Yeast Market Analysis
Consolidation among multinational food manufacturers is recalibrating procurement volumes for high-performance yeast strains. Lesaffre leverages its integrated fermentation infrastructure to secure long-term supply contracts with industrial bakeries. Lallemand Inc. anchors North American brewing demand through specialized liquid yeast portfolios. Angel Yeast Co., Ltd. dominates Asian nutraceutical channels with autolyzed yeast extract production at scale.
Specialty yeast denotes cultivated Saccharomyces and non-Saccharomyces strains processed into active, inactive, or derived formats with specified cell viability counts, protein content exceeding 40 percent in autolyzed grades, and standardized nucleotide profiles for flavor modulation. These organisms serve primarily as fermentation catalysts, nutritional enhancers, and umami precursors across commercial food systems. Instant yeast commands premium positioning in industrial baking due to reduced proofing time and extended ambient stability. Nutraceutical applications represent the fastest-expanding margin pool as yeast beta-glucan draws interest from immune-health formulators. Liquid yeast retains mature share in craft brewing where strain-specific flavor contributions justify cold-chain logistics.
The FDA oversees GRAS self-affirmation pathways for novel yeast-derived ingredients entering US food channels. EFSA evaluates health claim substantiation for yeast beta-glucan under EU nutrition and health claims regulation. BIS certification requirements in India constrain import of unregistered active dry yeast strains for commercial baking. Stakeholders must monitor evolving strain-level transparency mandates as clean-label procurement protocols harden across regulated jurisdictions.
Market Dynamics
Clean-label procurement mandates from multinational food manufacturers are compressing strain development cycles and forcing transparency upgrades across fermentation supply chains. Buyers now require documented cell viability counts and nucleotide profiles for every batch, reshaping how yeast propagators qualify their biological assets.
Growth Catalysts
- EU F-Gas Regulation:Tightening process standards for yeast-derived bioproducts are accelerating capital deployment into closed-system fermentation infrastructure that reduces refrigerant leakage and improves batch consistency.
- Craft brewing clusters:Strain-specific liquid yeast portfolios are drawing premium positioning as brewers prioritize flavor modulation over cost minimization, particularly in North American metropolitan brewing corridors.
- Beta-glucan extraction:Immune-health formulators are pulling autolyzed yeast extracts into functional food matrices, creating new margin pools beyond traditional fermentation catalyst applications.
Market Restraints
- Molasses price volatility:Cane sugar supply disruptions in key producing zones are transmitting cost spikes into yeast propagation economics, squeezing mid-scale propagators without long-term feedstock contracts.
- German supply concentration:Industrial baking and brewing procurement gravity in southern Germany creates single-point vulnerability for European strain distribution networks.
- Active dry shelf-life limitations:Ambient stability constraints in instant yeast formats restrict distribution reach into tropical climates without cold-chain overlay.
Strategic Opportunities
- Indian nutraceutical channels:BIS certification requirements for unregistered strains are creating first-mover advantages for propagators that navigate the compliance timeline ahead of competitors.
- Fermentation-derived umami precursors:Clean-label displacement of synthetic flavor enhancers in Asian processed foods is opening formulation partnerships with regional sauce and seasoning manufacturers.
- CRISPR strain optimization:Precision editing of Saccharomyces metabolic pathways is converging with automated bioreactor controls to compress development cycles for novel functional strains.
Industry Challenges
- Strain banking expertise:Cryopreservation protocols for maintaining genetic stability across master cell banks require specialized microbiological talent that propagators struggle to recruit at scale.
- GRAS substantiation timelines:FDA self-affirmation pathways for novel yeast-derived ingredients impose documentation burdens that extend market entry schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Yeast Market |
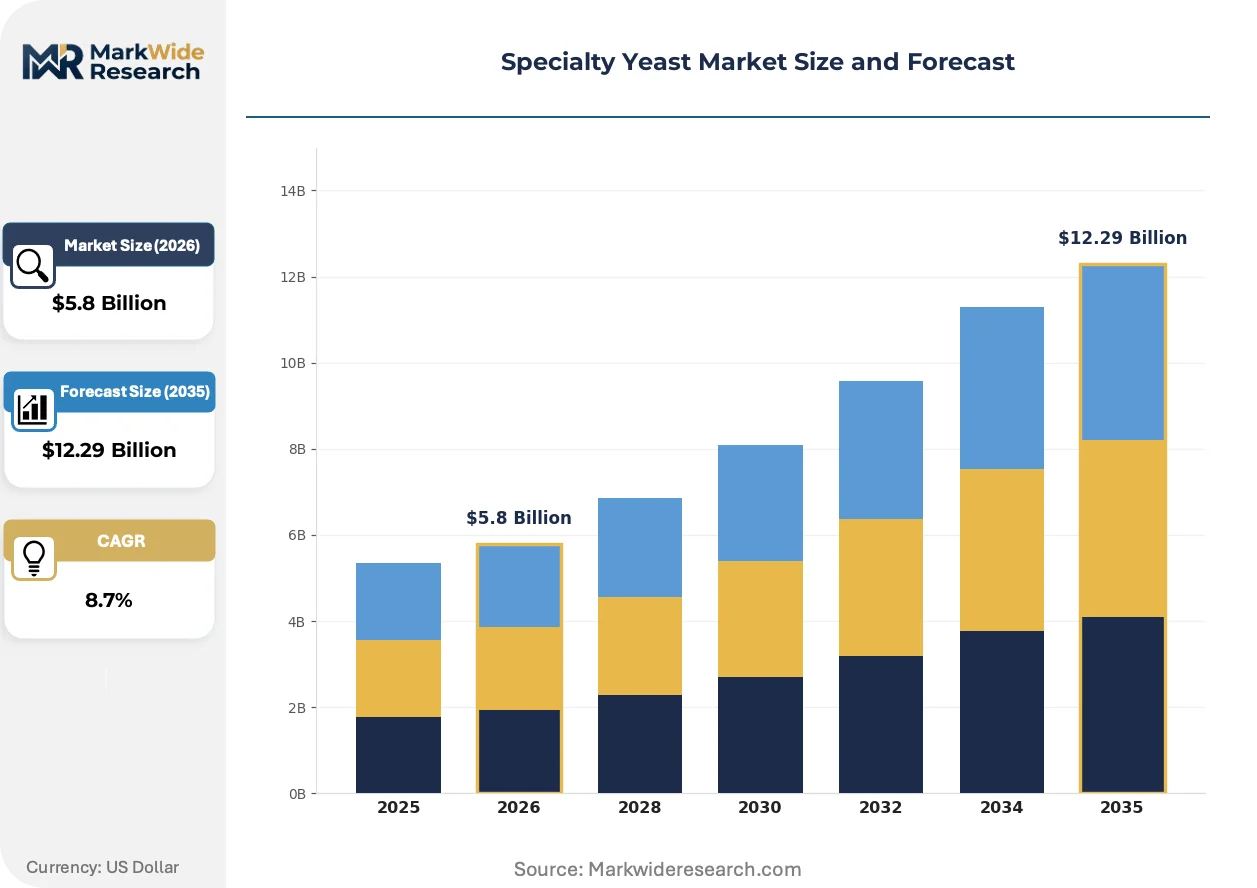
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Liquid Yeast, Fresh Yeast, Instant Yeast Application: Baking, Brewing, Fermentation, Nutraceuticals Form: Granulated, Powdered, Liquid, Flakes End User: Food Industry, Beverage Industry, Pharmaceutical, Agriculture |
| Companies Covered | Lesaffre, Lallemand Inc., Associated British Foods, Angel Yeast Co., Ltd., ADM, DSM, Kerry Group, Chr. Hansen Holding A/S, Biorigin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Yeast Market Emerging Trajectories
Fermentation infrastructure is digitizing rapidly while biological asset management converges with computational strain design. These shifts are compressing the gap between laboratory discovery and commercial propagation.
Single-use bioreactor systems are overtaking stainless-steel fermentation trains in mid-scale yeast propagation facilities. Contract manufacturers serving nutraceutical formulators are adopting disposable vessel technologies to reduce cross-contamination risk between strain runs. This hardware transition is overtaking capital-intensive facility designs and enabling faster product changeovers for smaller batch sizes.
REACH framework amendments are tightening substance registration requirements for yeast-derived metabolites entering EU food and feed channels. ECHA evaluation timelines are extending pre-market preparation phases for novel extracts. Nutraceutical ingredient suppliers are responding by front-loading toxicological dossiers and establishing dedicated regulatory affairs functions in Brussels.
Direct strain procurement from propagators is displacing distributor intermediaries in North American craft brewing. Brewery technical staffs are building direct relationships with liquid yeast laboratories to secure exclusive strain access and technical support. This channel compression is most visible in Pacific Northwest and New England brewing clusters where scale permits dedicated logistics arrangements.
Specialty Yeast Market Segmentation
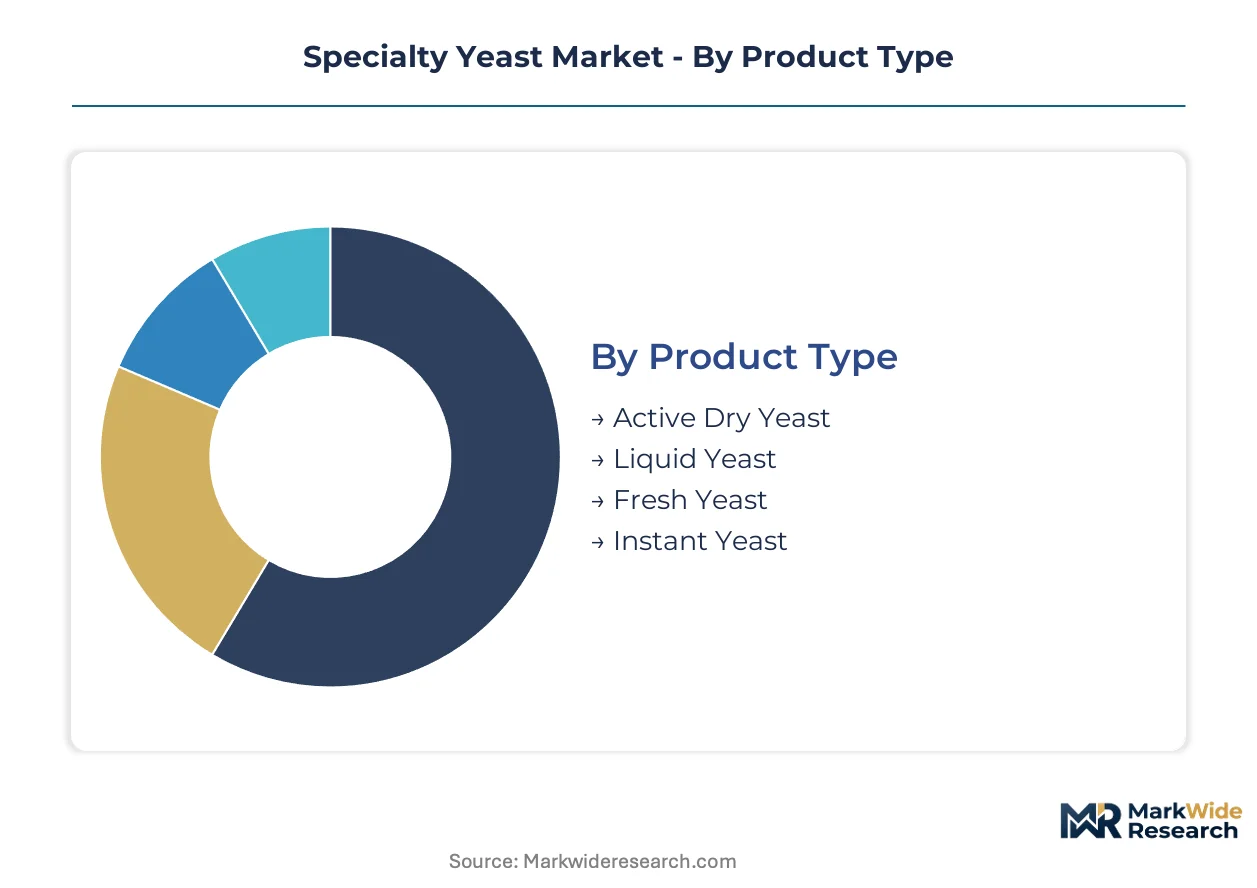
Specialty yeast procurement decisions hinge on fermentation performance specifications, cold-chain requirements, and clean-label compliance thresholds. Manufacturers segment offerings across viability formats, application matrices, and end-use regulatory environments to capture margin pools.
Product Type:
Cell viability preservation technology and ambient stability specifications differentiate procurement tiers across industrial bakeries, craft breweries, and nutraceutical formulators.
- Instant Yeast:Dehydrated Saccharomyces cerevisiae with cell viability exceeding 95 percent and rapid rehydration kinetics. Industrial bakeries in Germany prioritize instant formats for reduced proofing cycles in high-throughput production lines.
- Liquid Yeast:Propagated cultures in nutrient-rich suspension requiring cold-chain maintenance between 2-8°C. North American craft brewing clusters in Portland and Boston drive demand for strain-specific flavor contributions that justify logistics complexity.
- Active Dry Yeast:Vacuum-packed granules with 12-24 month ambient stability for distribution into tropical climates without refrigeration infrastructure.
- Fresh Yeast:Compressed cream yeast with 2-3 week refrigerated shelf life, retaining maximum enzymatic activity for artisan baking applications.
Instant yeast leads on scale; liquid yeast leads on momentum.
Application:
End-use performance requirements and regulatory substantiation burdens reshape how propagators allocate strain development resources and fermentation capacity.
- Baking:Fermentation catalyst applications demand standardized gassing power and consistent proofing velocity. Industrial-scale procurement in Germany and France concentrates volume through long-term supply contracts with integrated mill-bakery operations.
- Nutraceuticals:Beta-glucan extraction and autolyzed protein concentrates require documented immunomodulatory activity and GRAS or EFSA health claim substantiation. Immune-health formulators in the United States and EU are expanding autolyzed yeast extract portfolios fastest.
- Brewing:Strain-specific ester and phenol production profiles enable flavor differentiation in saturated craft beer markets.
- Fermentation:Industrial ethanol and biochemical production utilize high-tolerance yeast strains for stress-resistant catalytic performance.
Baking commands procurement volume; nutraceuticals expand most quickly.
Form:
Physical presentation determines dissolution kinetics, storage economics, and cross-contamination risk in multi-strain manufacturing environments.
- Powdered:Spray-dried autolyzed extracts with standardized protein content exceeding 40 percent. Nutraceutical formulators prefer powders for precise dosing in capsule and tablet matrices.
- Liquid:Suspension formats for direct pitching into brewing wort or fermentation broths without rehydration protocols.
- Granulated:Free-flowing particles with anti-caking agents for automated dosing equipment in industrial baking.
- Flakes:Debittered nutritional yeast for direct consumption and savory flavoring applications in plant-based food systems.
Powdered form dominates nutraceutical channels; liquid form anchors brewing procurement.
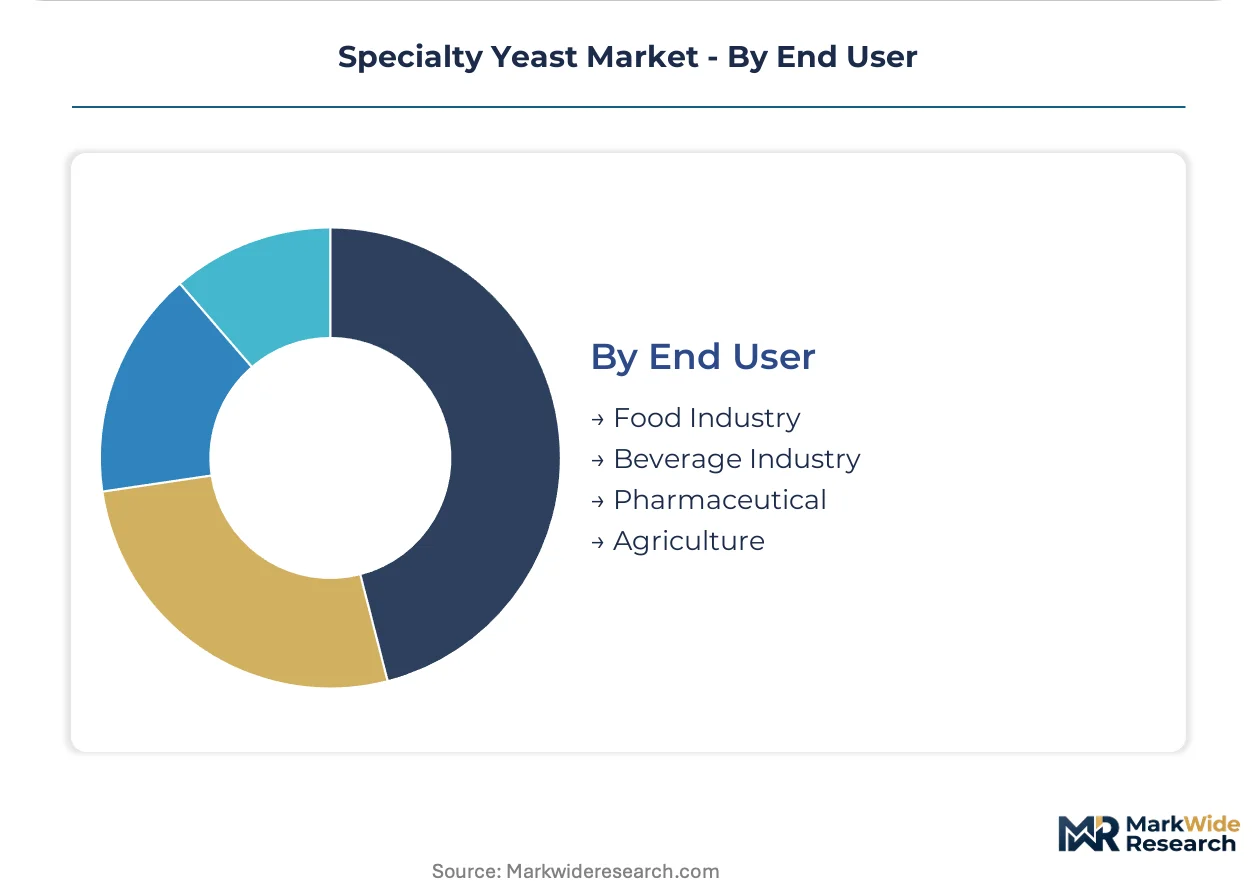
End User:
Regulatory compliance depth and technical specification rigor vary sharply across food, beverage, pharmaceutical, and agricultural channels.
- Food Industry:Clean-label mandates from multinational manufacturers require batch-level transparency on strain origin and nucleotide profiles. EU F-Gas Regulation compliance adds process documentation burdens for yeast-derived bioproducts entering continental supply chains.
- Pharmaceutical:cGMP fermentation standards and FDA drug master file requirements constrain supplier qualification to propagators with dedicated pharmaceutical-grade facilities.
- Beverage Industry:Craft brewing technical staffs build direct procurement relationships with liquid yeast laboratories, compressing distributor intermediaries in Pacific Northwest and New England clusters.
- Agriculture:Probiotic feed additive applications face BIS certification requirements in India and varying strain registration protocols across national veterinary authorities.
Food industry generates procurement volume; pharmaceutical channels impose specification rigor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialty yeast procurement more intensely than any other single country, while the United States and China pursue divergent paths toward nutraceutical and industrial fermentation applications.
Germany
Industrial baking and brewing clusters in Bavaria and Baden-Württemberg drive bulk procurement of high-performance yeast strains. The EU F-Gas Regulation enforces closed-system fermentation standards that favor capital-intensive propagators with integrated refrigeration infrastructure. Munich and Stuttgart anchor continental supply chain gravity for instant and liquid yeast distribution across the EU single market.
United States
Immune-health formulators in California and Massachusetts expand autolyzed yeast extract portfolios for functional food matrices. FDA GRAS self-affirmation pathways impose documentation burdens that extend market entry timelines for novel yeast-derived ingredients. Portland and Boston brewing corridors sustain direct procurement relationships with liquid yeast laboratories, compressing traditional distributor channels.
China
Nutraceutical manufacturers in the Yangtze River Delta scale autolyzed yeast production for domestic and export markets. SAMR and GB standards govern food-grade yeast strain registration and process documentation requirements. Zhengzhou and Shanghai host integrated fermentation facilities serving both traditional baking and emerging beta-glucan extraction demand.
India
Commercial bakeries in Maharashtra and Gujarat face BIS certification constraints on unregistered active dry yeast imports. FSSAI and BIS frameworks create compliance timelines that advantage early-moving propagators with established registration dossiers. Mumbai and Ahmedabad concentrate procurement volume for industrial baking applications amid rapid urbanization of food consumption patterns.
France
Artisan baking traditions in Île-de-France and Auvergne-Rhône-Alpes sustain demand for fresh and compressed yeast formats with maximum enzymatic activity. EFSA evaluates health claim substantiation for yeast beta-glucan under EU nutrition and health claims regulation. Paris and Lyon anchor premium yeast distribution networks serving both domestic retail channels and export-oriented processed food manufacturers.
Specialty Yeast Market Vendor Landscape
European producers anchor the premium tier through integrated fermentation infrastructure and regulatory compliance depth; Asian specialists hold volume positions in cost-sensitive nutraceutical and industrial baking channels. The vendor base stratifies across three functional tiers: propagators with captive strain banks, contract manufacturers with flexible bioreactor assets, and regional distributors with logistics overlay. Two dominant competitive moves define current positioning: backward integration into molasses feedstock sourcing to buffer price volatility, and technology licensing partnerships to access CRISPR strain optimization capabilities without captive R&D investment.
Within the integrated propagator tier, Lesaffre and Lallemand Inc. exemplify geographic anchoring strategies—French and Canadian corporate structures respectively—while Angel Yeast Co., Ltd. occupies a position representing Chinese-scale fermentation infrastructure. These three entities illustrate how regional regulatory fluency and feedstock access shape competitive boundaries more than product differentiation alone.
| Leading Market Players |
|---|
| Lesaffre |
| Lallemand Inc. |
| Associated British Foods |
| Angel Yeast Co., Ltd. |
| ADM |
| DSM |
| Kerry Group |
| Chr. Hansen Holding A/S |
| Biorigin |
| Others |
Supply Flow & Price Mechanics
Industrial bakery procurement clusters in southern Germany anchor contract-based pricing power, locking in multi-year offtake agreements that buffer mid-scale propagators from molasses cost spikes while compressing margins for spot-market suppliers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for autolyzed yeast extracts, intensifying competition in nutraceutical channels. Three-tier pricing structure across premium, standard, and economy levels separates GRAS-substantiated beta-glucan grades from commodity baking strains. Cost compression in standard-tier instant yeast runs through cane sugar supply disruptions in Brazil and India. Small-scale craft brewers exhibit highest price sensitivity, while pharmaceutical-grade cGMP strains command inelastic demand.
Supply Chain Analysis
India's BIS certification requirements for unregistered active dry yeast strains are reshaping sourcing patterns, forcing propagators to front-load compliance investments or cede market access. Manufacturing concentrates in Germany, China, and France, with molasses feedstock drawing from Brazilian cane sugar and Thai cassava processors. Single-source vulnerability centers on German distribution networks serving EU industrial baking clusters. Distribution runs through direct-procurement relationships in North American craft brewing, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty yeast offers margin-expansion headroom as automated bioreactor controls compress production costs and immune-health formulators absorb premium pricing for beta-glucan extracts.
For Market Incumbents: Extend strain banking capabilities through cryopreservation infrastructure investments that lock in genetic stability advantages. Deepen captive molasses sourcing through long-term contracts with Brazilian and Thai feedstock suppliers, insulating propagation economics from commodity volatility. Defend against CRISPR-optimized strain disruptors by accelerating automated metabolic pathway editing partnerships. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for propagators with closed-system fermentation assets to capture industrial bakery contracts from legacy suppliers facing retrofit costs. Target Indian nutraceutical channels ahead of BIS certification backlogs, securing first-mover registration advantages. Lead with direct technical support models that mirror Pacific Northwest craft brewing procurement patterns. For Investors and Strategic Acquirers: Multinational food manufacturers are the most active acquirer in this space, seeking captive supply of clean-label fermentation-derived ingredients. Five-to-ten-year viability hinges on regulatory fluency depth rather than scale alone. Monitor EFSA health claim substantiation timelines for yeast beta-glucan as the inflection signal for nutraceutical margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Feedstock | Long-term supply contracts with Brazilian cane processors buffer price volatility. |
| CRISPR Strain Optimization Partnership | Precision editing of Saccharomyces metabolic pathways compresses novel strain development cycles. |
| Closed-System Fermentation Retrofit | EU F-Gas Regulation compliance secures German industrial bakery procurement contracts. |
| BIS Certification Pre-Registration | Early dossier submission in India captures nutraceutical channel share ahead of competitors. |
| Direct Liquid Yeast Distribution | Bypassing distributor intermediaries in Portland and Boston brewing corridors improves margin capture. |
Methodological Framework
Multiple input streams — fermentation facility site visits, regulatory filing analysis, and procurement manager interviews — were reconciled to construct supply-side capacity and demand-side specification matrices. Primary discussions with yeast propagation executives, industrial bakery procurement leads, craft brewery technical directors, and nutraceutical formulators were cross-referenced against EFSA health claim submissions, FDA GRAS notifications, BIS registration databases, and customs trade flow records. Bottom-up strain-level production estimates and top-down sectoral demand aggregation were triangulated for consistency.
Historical propagation capacity expansion patterns were cross-referenced against panel input from fermentation infrastructure investors to anchor growth assumptions across the analysis window. Segmentation modeling spanned product viability format, application matrix, physical form, and end-use regulatory environment. CAGRs were derived from reconciling bottom-up strain adoption curves with top-down sectoral spending trajectories, incorporating molasses price elasticity and clean-label procurement premium absorption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH framework amendments or sudden cane sugar supply disruptions. Projections reflect documented assumptions regarding regulatory timeline stability and strain registration pathway continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oat Ingredients Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Bran Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Pet Food Ingredients Market
Ingredients
High Oleic Oil Market
Ingredients
Smoked Yeast Market
Ingredients
Pea Flour Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Omega 6 Market
Ingredients
Lentils Flour Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
Barley Flake Market
Ingredients
Gum Arabic Market