
 Barley Flake Market | 2026-2036
Barley Flake Market Size, Share, and Industry Trends Forecast 2026-2036
Barley Flake Market Outlook
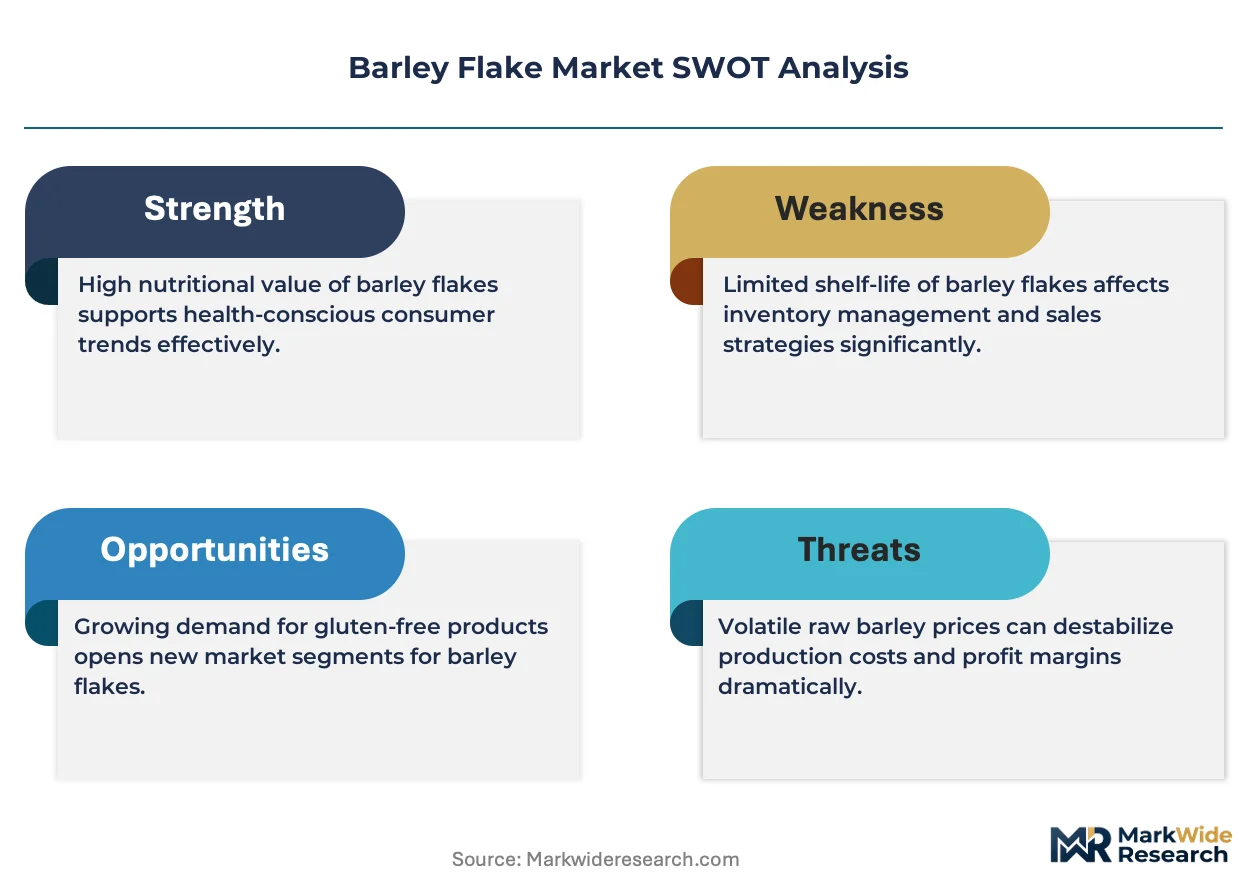
The barley flake category is pivoting between premium organic positioning and commodity grain alternatives, with pricing spreads widening as ingredient provenance becomes a purchase trigger. Bob's Red Mill Natural Foods leverages its employee-owned structure to sustain long-term supplier relationships across North American organic barley cooperatives. King Arthur Baking Company anchors its retail presence through recipe-driven content that converts home bakers into repeat purchasers of specialty grain formats.
Barley flakes consist of steamed, rolled, and dried barley kernels typically processed to thicknesses between 0.3 and 0.8 millimeters, yielding a cooking time of 10–15 minutes and a chewy texture suited for hot cereals, granolas, and artisan bread inclusions. Organic barley flakes command margin premiums through certified supply chains, while instant barley flakes target convenience-oriented home consumers seeking reduced preparation time. Whole grain barley flakes retain the bran and germ layers, delivering beta-glucan fiber levels that health food stores feature prominently in functional nutrition merchandising.
The FDA's whole grain health claim standards and USDA organic certification requirements shape product formulation and label compliance across domestic supply chains. EFSA's Article 13.1 health claims on barley beta-glucan cholesterol reduction create market access conditions for European exporters seeking positioning in functional food segments. Stakeholders must monitor evolving whole grain definition standards and beta-glucan concentration thresholds as regulatory divergence between major markets intensifies sourcing complexity.
Market Dynamics
Clean-label breakfast demand is compressing supply chains toward certified organic barley cooperatives, while regulatory divergence between FDA and EFSA beta-glucan thresholds forces dual-track formulation strategies.
Growth Catalysts
- FDA Whole Grain Health Claims:Updated labeling guidelines push manufacturers toward verifiable fiber content, accelerating bakery reformulation toward barley inclusions.
- German Bakery Sector:Ancient grain substitution in industrial bread production concentrates procurement from certified organic barley cooperatives.
- Steam-Roll Processing Advances:Thickness precision between 0.3-0.8 millimeters enables texture customization for hot cereal and granola applications.
Market Restraints
- Organic Input Cost Volatility:Certified barley seed and rotational crop premiums expose processors to farmgate price swings.
- North American Supply Concentration:Organic barley cooperative structures limit spot market liquidity for non-contract buyers.
- Oat Beta-Glucan Substitution:Established oat fiber supply chains compete for cholesterol-reduction positioning in functional foods.
Strategic Opportunities
- Instant Format Expansion:Convenience-oriented home consumers drive reduced-preparation-time product development.
- EFSA Article 13.1 Tailwind:European cholesterol-reduction health claims create market access for beta-glancan-verified exporters.
- Health Food Channel Innovation:Functional nutrition merchandising expands shelf space allocation for whole grain positioning.
Industry Challenges
- Dual Certification Timelines:USDA organic and FDA whole grain compliance create parallel audit requirements.
- Legacy Mill Equipment Retrofit:Steam-roll thickness control systems require capital outlay for precision processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barley Flake Market |
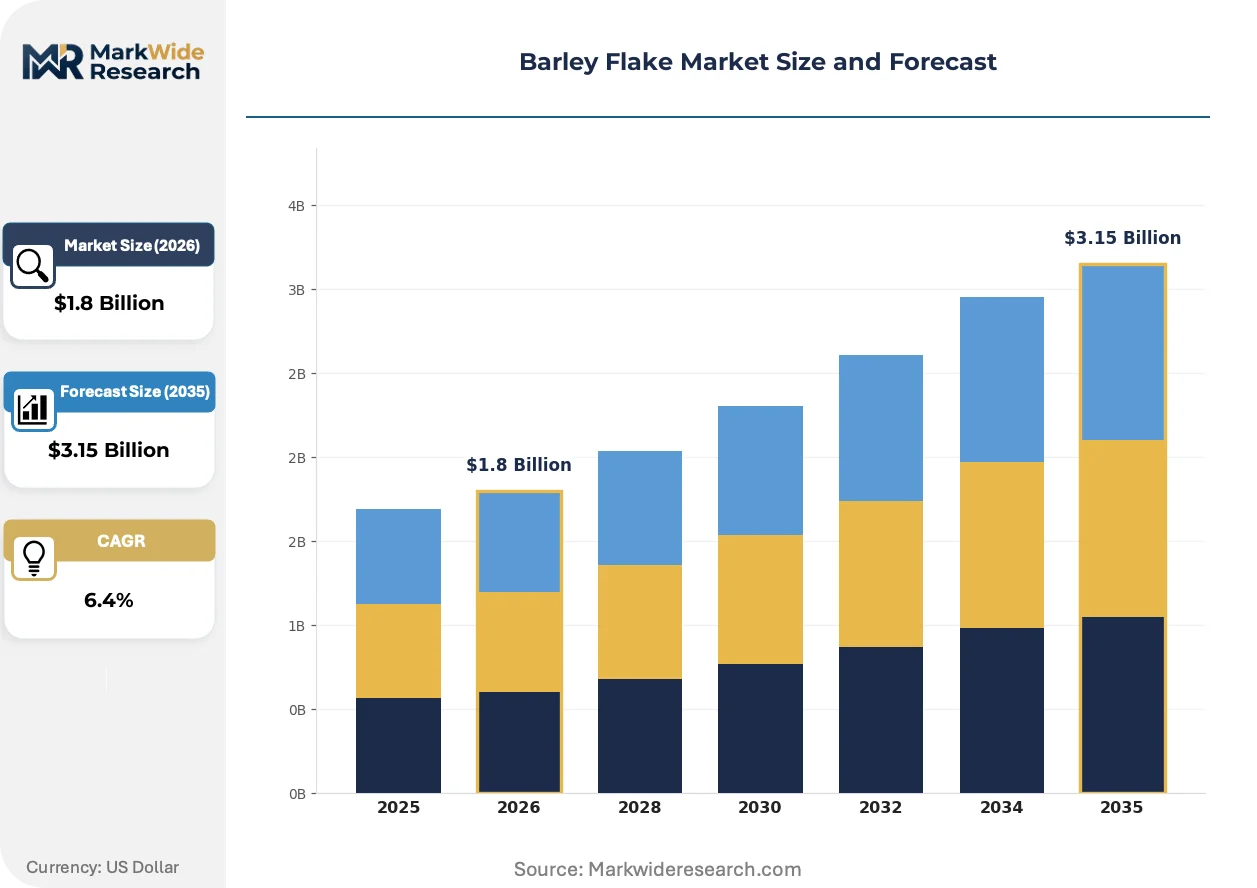
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Barley Flakes, Instant Barley Flakes, Whole Grain Barley Flakes, Flavored Barley Flakes End User: Restaurants, Bakeries, Health Food Stores, Home Consumers Packaging Type: Bags, Boxes, Bulk Containers, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Bob’s Red Mill Natural Foods, King Arthur Baking Company, Honeyville, Shiloh Farms, Nestlé, WK Kellogg Co, The Quaker Oats Company, Briess Malt & Ingredients, Vitasana Foods Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barley Flake Market Strategic Shifts
Processing transparency and provenance verification are restructuring competitive differentiation, with technology and regulatory frameworks converging to reshape ingredient sourcing hierarchies.
Precision steam-roll thickness control systems are decentralizing production scale requirements across the barley flake category. Small-batch mill operators in specialty grain regions now achieve texture specifications previously reserved for industrial processors. This capability compression enables regional organic cooperatives to supply national granola and artisan bread manufacturers without intermediary toll processing.
EFSA's Article 13.1 health claim framework on barley beta-glucan cholesterol reduction is tightening European import specifications. Manufacturers seeking functional food positioning must now document beta-glucan concentration thresholds at batch level. German and Dutch bakery ingredient divisions are responding by locking multi-year contracts with certified organic barley suppliers capable of third-party verification.
Recipe-driven content conversion is displacing traditional retail merchandising for specialty grain formats. Home baker communities on social platforms now drive repeat purchase velocity for specific flake thickness grades. This channel shift concentrates marketing investment toward digital recipe development rather than slotting fee competition in conventional grocery.
Barley Flake Market Segmentation
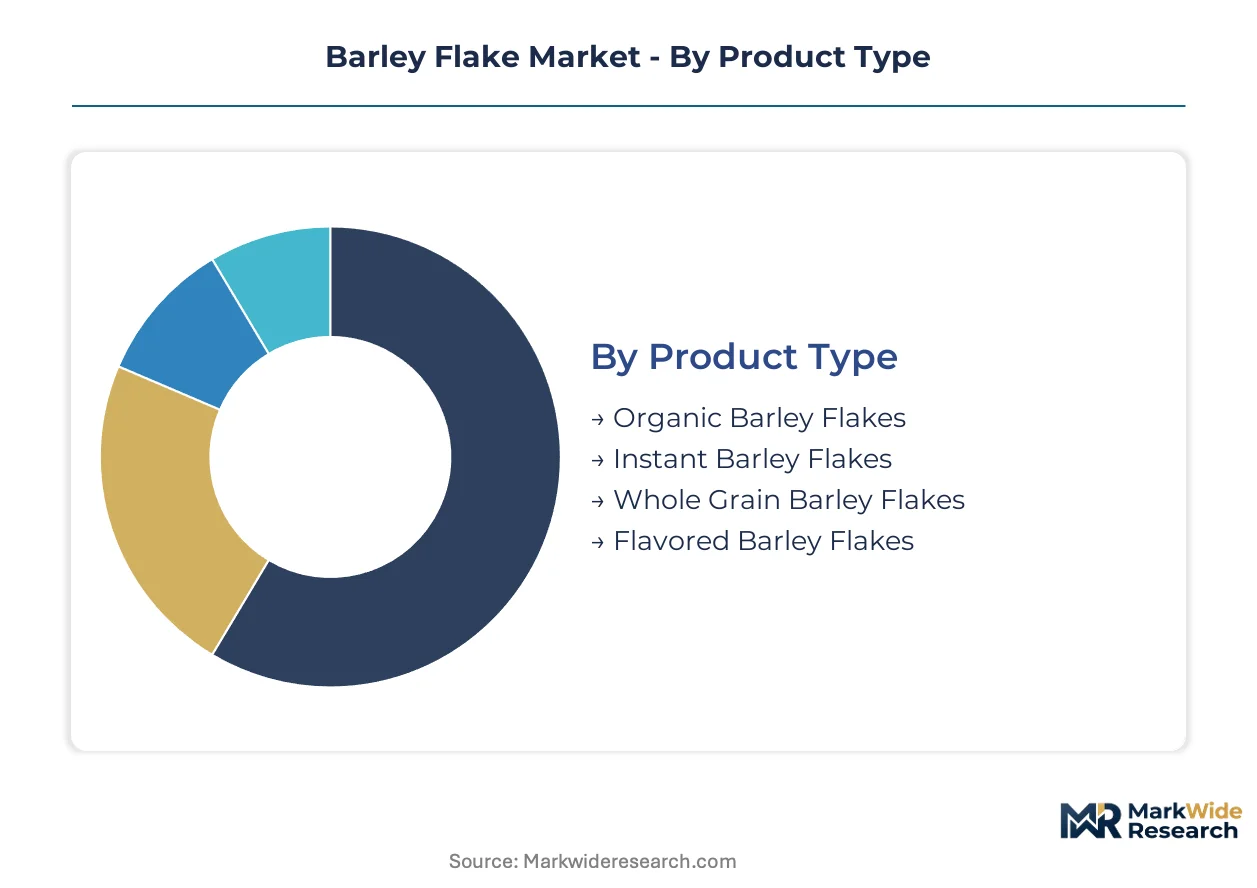
Barley flake manufacturers navigate divergent margin structures across organic certification tiers and convenience formats. Segmentation reveals where premium positioning commands price multiples versus commodity-grade volume plays.
Product Type:
Volume concentrates in conventional whole grain formats while certified organic and instant varieties capture margin premiums through differentiated supply chains.
- Organic Barley Flakes:Certified supply chains from North American barley cooperatives deliver beta-glucan levels that health food stores merchandise under clean-label positioning. German bakery reformulation toward ancient grains concentrates procurement from these verified organic sources.
- Instant Barley Flakes:Pre-cooked and dehydrated kernels reduce preparation time to under three minutes, targeting convenience-oriented home consumers in urban markets. Steam-roll thickness precision below 0.4 millimeters enables rapid hydration without texture degradation.
- Whole Grain Barley Flakes:Retain bran and germ layers with documented fiber content supporting FDA whole grain health claims.
- Flavored Barley Flakes:Maple, cinnamon, and fruit-infused varieties target children's breakfast segments through sweetened positioning.
Mature deployment sits with Whole Grain Barley Flakes. Newer deployment is concentrated in Instant Barley Flakes.
End User:
Demand bifurcates between foodservice procurement at scale and retail channels where recipe content drives repeat purchase velocity.
- Restaurants:Bulk procurement of unflavored flakes for hot cereal breakfast programs and granola bowl inclusions. Menu transparency requirements push toward certified organic sourcing for customer-facing ingredient stories.
- Health Food Stores:Functional nutrition merchandising allocates expanded shelf space to beta-glucan-verified organic formats. Staff training programs convert beta-glucan cholesterol claims into customer education at point of purchase.
- Bakeries:Ancient grain bread inclusions utilize specific flake thickness grades for texture control in artisan loaves.
- Home Consumers:Digital recipe communities on social platforms drive trial and repeat purchase of specialty thickness grades.
Volume leadership rests with Restaurants. Margin expansion is concentrated in Health Food Stores.
Packaging Type:
Format selection tracks channel economics: retail-ready packaging commands per-unit premiums while bulk containers minimize handling costs for industrial buyers.
- Bags:Stand-up pouches with resealable closures dominate health food store shelves. Windowed film structures showcase flake color and thickness as quality signals.
- Bulk Containers:Foodservice and bakery procurement utilizes 25-50 pound poly-lined fiber drums. Reduced packaging overhead aligns with sustainability positioning for commercial accounts.
- Boxes:Shelf-stable cartons with portion-control inner bags target club store multipack formats.
- Pouches:Single-serve sachets support travel and workplace consumption occasions.
Industrial-scale deployment sits with Bulk Containers. Consumer-facing innovation is concentrated in Bags.
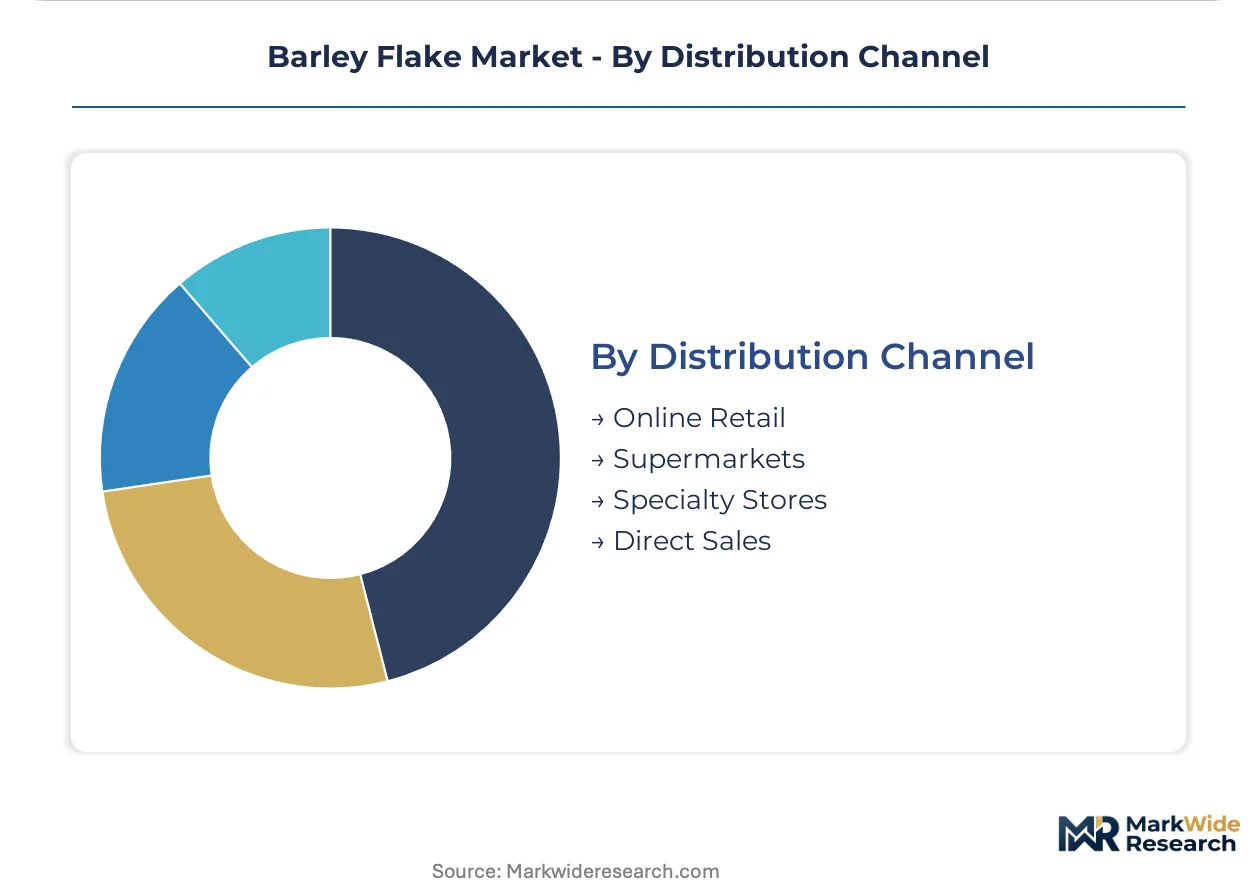
Distribution Channel:
Channel strategy determines margin capture: direct relationships preserve pricing control while retail intermediaries demand trade investment.
- Specialty Stores:Independent natural foods retailers provide curated placement and staff recommendation leverage. Slotting fee avoidance preserves margin for emerging organic brands.
- Online Retail:Direct-to-consumer subscription models convert recipe content engagement into recurring revenue. Amazon and Thrive Market algorithmic placement depends on review velocity and organic certification badges.
- Supermarkets:Conventional grocery reset timing determines shelf space allocation against oat and wheat flake incumbents.
- Direct Sales:Bakery and foodservice accounts bypass distributor markups through mill-direct procurement.
Established volume flows through Supermarkets. Channel expansion is concentrated in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European barley flake procurement through its industrial bakery ingredient corridor linking Bavarian organic cooperatives to reformulated bread production lines.
United States
Portland, Oregon, and Minneapolis, Minnesota, concentrate organic barley processing infrastructure serving health food store distribution networks. FDA whole grain labeling guidelines push manufacturers toward verifiable fiber documentation. The Pacific Northwest organic barley cooperative belt supplies national granola and artisan bread manufacturers with certified beta-glucan-verified flakes.
Germany
Industrial bakeries in Lower Saxony and North Rhine-Westphalia drive ancient grain substitution in commercial bread production. EFSA Article 13.1 health claims on barley beta-glucan cholesterol reduction tighten import specifications for functional food positioning. Hamburg port facilities handle third-party verified organic barley shipments from North American cooperatives.
Canada
Prairie Provinces organic barley growers supply clean-label breakfast manufacturers with certified seed stock. Health Canada whole grain guidance aligns with FDA fiber claim standards, easing cross-border formulation strategies. Alberta processing facilities steam-roll precision thickness grades for hot cereal and granola applications.
United Kingdom
London health food retailers expand shelf space allocation for beta-glucan-verified organic formats. FSA compliance with EU-derived whole grain standards maintains label continuity post-Brexit. Midlands artisan bakeries source specific flake thickness grades for ancient grain bread inclusions.
India
Punjab and Haryana barley cooperatives supply domestic instant flake processors targeting urban convenience markets. FSSAI labeling requirements for whole grain claims drive documentation investments at mill level. Mumbai and Bangalore health food channels trial imported organic formats for premium positioning.
Barley Flake Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and thickness precision capabilities. The vendor base stratifies between employee-owned organic cooperatives, diversified baking ingredient divisions, and instant format specialists. Three archetypes dominate: heritage mill operators with cooperative supply relationships, diversified food conglomerates with breakfast portfolio breadth, and contract processors serving private-label retail. Competitive moves concentrate on multi-year organic supply contracts and precision steam-roll equipment retrofit.
Within the heritage mill tier, Bob's Red Mill Natural Foods and King Arthur Baking Company exemplify employee-owned structures sustaining long-term supplier relationships across North American organic barley cooperatives. These Portland-based and Vermont-based operators anchor premium positioning through recipe-driven content conversion. Among diversified breakfast portfolios, Nestlé and WK Kellogg Co occupy positions spanning conventional and health-oriented flake formats, with supply chain scale enabling cross-category formulation flexibility. The competitive field compresses around certification credibility and thickness precision as primary differentiation vectors.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| King Arthur Baking Company |
| Honeyville |
| Shiloh Farms |
| Nestlé |
| WK Kellogg Co |
| The Quaker Oats Company |
| Briess Malt & Ingredients |
| Vitasana Foods Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
German bakery reformulation toward certified organic barley cooperatives is forcing North American suppliers to lock multi-year contracts at fixed premiums, compressing spot market liquidity and widening the spread between contracted organic and conventional commodity grades.
Pricing Analysis
Beta-glucan-verified health outcomes anchor value-based pricing for functional food positioning, with EFSA Article 13.1 cholesterol-reduction claims commanding premium multiples over unverified conventional flakes. Three-tier pricing structure across certified organic, conventional whole grain, and instant convenience formats differentiates margin capture by certification grade and thickness precision. Cost compression in conventional grades is intensifying because oat beta-glucan substitutes compete for shelf space with lower input costs. Foodservice bulk buyers exhibit highest price sensitivity, while health food stores absorb premiums for verified organic provenance.
Supply Chain Analysis
Single-source vulnerability sits with North American organic barley cooperative structures that limit non-contract buyer access to certified seed stock. Production gravity centers on the Pacific Northwest United States, Prairie Provinces of Canada, and Bavarian organic growing regions in Germany. Processing infrastructure draws from steam-roll precision equipment, certified organic seed stock, and third-party beta-glucan verification laboratories. Tariff exposure on European-bound shipments creates margin risk for exporters seeking EFSA-compliant positioning. Distribution runs through mill-direct relationships with industrial bakeries and health food store distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barley flake market consolidation accelerates as dual certification timelines for USDA organic and FDA whole grain compliance force sub-scale processors toward acquisition or exit.
For Market Incumbents: Anticipate oat beta-glucan substitution pressure by deepening backward integration into certified organic barley cooperatives in the Pacific Northwest and Prairie Provinces. Lock multi-year supply agreements before EFSA import specifications tighten further. Prioritize steam-roll equipment retrofit for thickness precision below 0.4 millimeters to capture instant format growth. For New Entrants and Emerging Players: Precision steam-roll thickness control technology offers entry into regional artisan bread supply chains previously served by industrial toll processors. Target underpenetrated instant barley flake demand in urban Indian convenience markets where FSSAI whole grain labeling investments lag. Deploy recipe-driven digital content partnerships to bypass conventional grocery slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors employee-owned heritage mill operators with established organic cooperative relationships and verified beta-glucan documentation capabilities. Long-term viability hinges on supply chain control extending through certified seed stock to finished flake processing. Watch for EFSA batch-level verification requirements as the inflection signal forcing consolidation among undifferentiated commodity processors.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Organic Supply Contracting | Locks certified barley seed stock ahead of EFSA tightening and German bakery demand expansion. |
| Precision Steam-Roll Equipment Retrofit | Enables thickness customization for instant formats and artisan bread texture specifications. |
| Third-Party Beta-Glucan Verification | Documents EFSA Article 13.1 compliance for European functional food market access. |
| Recipe-Driven Digital Content Platform | Converts social platform home baker engagement into direct-to-consumer recurring revenue. |
| Health Food Channel Shelf Space Expansion | Captures functional nutrition merchandising allocation through staff training on cholesterol claims. |
Study Parameters
Multi-period observation of FDA whole grain labeling guideline revisions, EFSA health claim adjudications, and German bakery ingredient procurement patterns anchored the trend analysis, supplemented by interviews with organic barley cooperative managers, specialty grain mill operators, health food store category buyers, and industrial bakery procurement directors. Secondary validation drew from USDA organic certification databases, FDA food labeling guidance documents, EFSA Article 13.1 health claim registers, and customs trade flow records. Bottom-up volume modeling and top-down market sizing were triangulated against processor capacity disclosures.
Segment-weighting applied product type, end user channel, and geographic regulatory cluster dimensions across the modeling period. CAGRs were derived from rolling average growth rate analysis applied to certified organic, conventional whole grain, and instant format trajectories. Forecast inputs incorporated beta-glucan concentration threshold evolution, steam-roll processing capacity expansion timelines, and health food channel shelf space allocation trends.
Several conditions sit outside the modeled scope, including unforeseen commodity price shocks in organic barley seed markets, abrupt EFSA regulatory reversals on beta-glucan claims, and disruptive oat fiber technology advances. Forecasts reflect documented assumptions about certification timeline stability and cooperative supply contract renewal rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Camelina Oil Market
Ingredients
Soy Lecithin Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Clean Label Flour Market
Ingredients
Wheat Malt Market
Ingredients
Potato Protein Market
Ingredients
Salt Market
Ingredients
Egg Yolk Powder Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Cocoa Solids Market
Ingredients
Spelt Flour Market
Ingredients
China Protein Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Europe Amino Acid Market
Ingredients
Asia-Pacific Dairy Ingredients Market