
 Synthetic Food Colors Market | 2026-2036
Synthetic Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Food Colors Market Analytics
Specialized color chemist talent is redrawing competitive boundaries in the synthetic food colors sector, as formulation expertise for heat-stable, pH-resistant dyes becomes scarce and geographically concentrated. BASF SE leverages its integrated pigment chemistry capabilities to sustain supply security across European beverage accounts. Sensient Technologies Corporation anchors North American demand through its controlled distribution of certified color solutions for dairy and confectionery applications. Chr. Hansen Holdings A/S differentiates via its specialized focus on natural-alternative hybrid portfolios that navigate tightening regulatory thresholds.
Synthetic food colors are azo and triarylmethane-based dyes manufactured through controlled sulfonation, diazotization, and coupling reactions to achieve defined hue, light stability, and solubility specifications for edible applications. These colorants serve the primary commercial purpose of standardizing visual appeal across processed food and beverage batches where natural pigment variability would undermine brand consistency. Lake colors occupy the highest-margin structural position due to their fat-dispersible properties and concentrated use in coated confectionery and snack seasonings. Liquid colors represent the fastest-expanding form segment as beverage producers automate dosing systems and reduce powder-handling contamination risks. Artificial colors remain the mature volume base, though reformulation pressures from food manufacturers are shifting procurement toward certified batch-lot grades with enhanced traceability documentation.
The FDA's Color Additive Status List and the EU's Food Additives Regulation, enforced by EFSA, jointly define permissible daily intake thresholds and purity specifications that determine which chemistries qualify for market access in their respective jurisdictions. India's FSSAI has tightened labeling mandates for synthetic dyes in packaged foods, compelling domestic manufacturers to reformulate or risk distribution penalties. Stakeholders must monitor regulatory divergence between major consuming blocs, as misaligned certification requirements threaten to fragment formulation strategies and complicate cross-border supply planning.
Market Dynamics
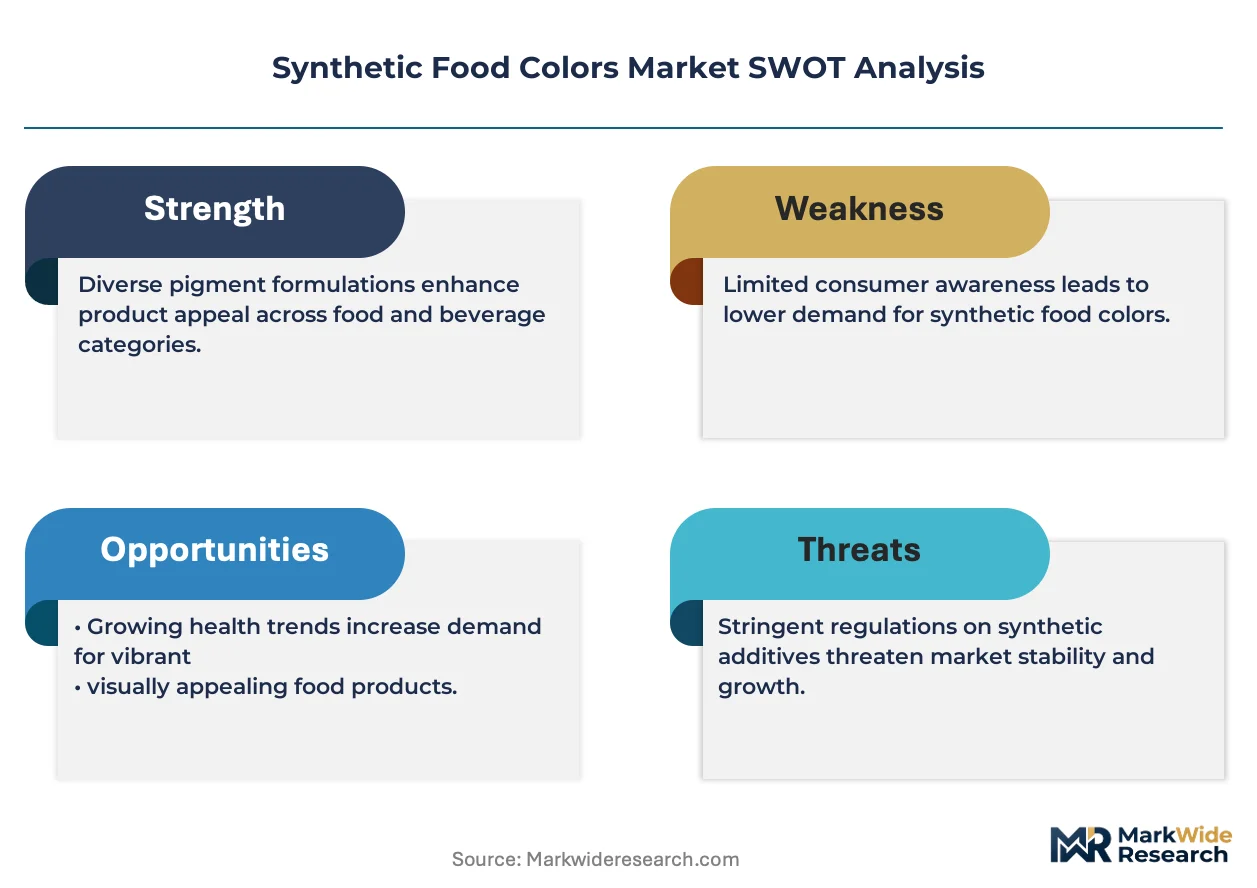
Reformulation pressure from tightening purity mandates is compressing batch certification timelines and forcing manufacturers to revalidate entire colorant portfolios against evolving EFSA and FSSAI specifications.
Growth Catalysts
- Carbonated beverage automation:Beverage producers in India and Brazil are retrofitting dosing lines with liquid colorant systems to reduce contamination risk and accelerate throughput.
- EU Food Additives Regulation revisions:The European Commission's accelerated purity benchmarks are compelling manufacturers to upgrade filtration and sulfonation infrastructure ahead of enforcement deadlines.
- Confectionery export scaling:Indian snack manufacturers are expanding lake color capacity to serve Middle Eastern and African markets demanding heat-stable coatings.
Market Restraints
- Petrochemical feedstock volatility:Naphtha and benzene derivative costs fluctuate with refinery output, squeezing margin on azo dye intermediates.
- Specialized chemist scarcity:Formulation expertise for pH-resistant, heat-stable dyes concentrates in Western Europe and select Indian clusters, limiting geographic production expansion.
- Natural colorant substitution:Food manufacturers facing clean-label pressure from retailers are reformulating with carotenoid and anthocyanin alternatives in premium SKU lines.
Strategic Opportunities
- Functional beverage penetration:Vitamin-fortified and probiotic drink segments in Indonesia and Vietnam remain underpenetrated by certified synthetic color suppliers.
- Hybrid natural-synthetic portfolios:Blended color solutions that combine light stability of synthetics with regulatory positioning of naturals open reformulation service revenue streams.
- FSSAI labeling mandate compliance services:Domestic Indian manufacturers require technical partnership to navigate new disclosure requirements without line shutdowns.
Industry Challenges
- Cross-jurisdictional certification complexity:Manufacturers serving both FDA and EFSA markets must maintain dual batch documentation systems with divergent heavy metal thresholds.
- Legacy powder-handling infrastructure:Beverage plants automating liquid dosing face capital-intensive line reconfiguration and wastewater system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Food Colors Market |
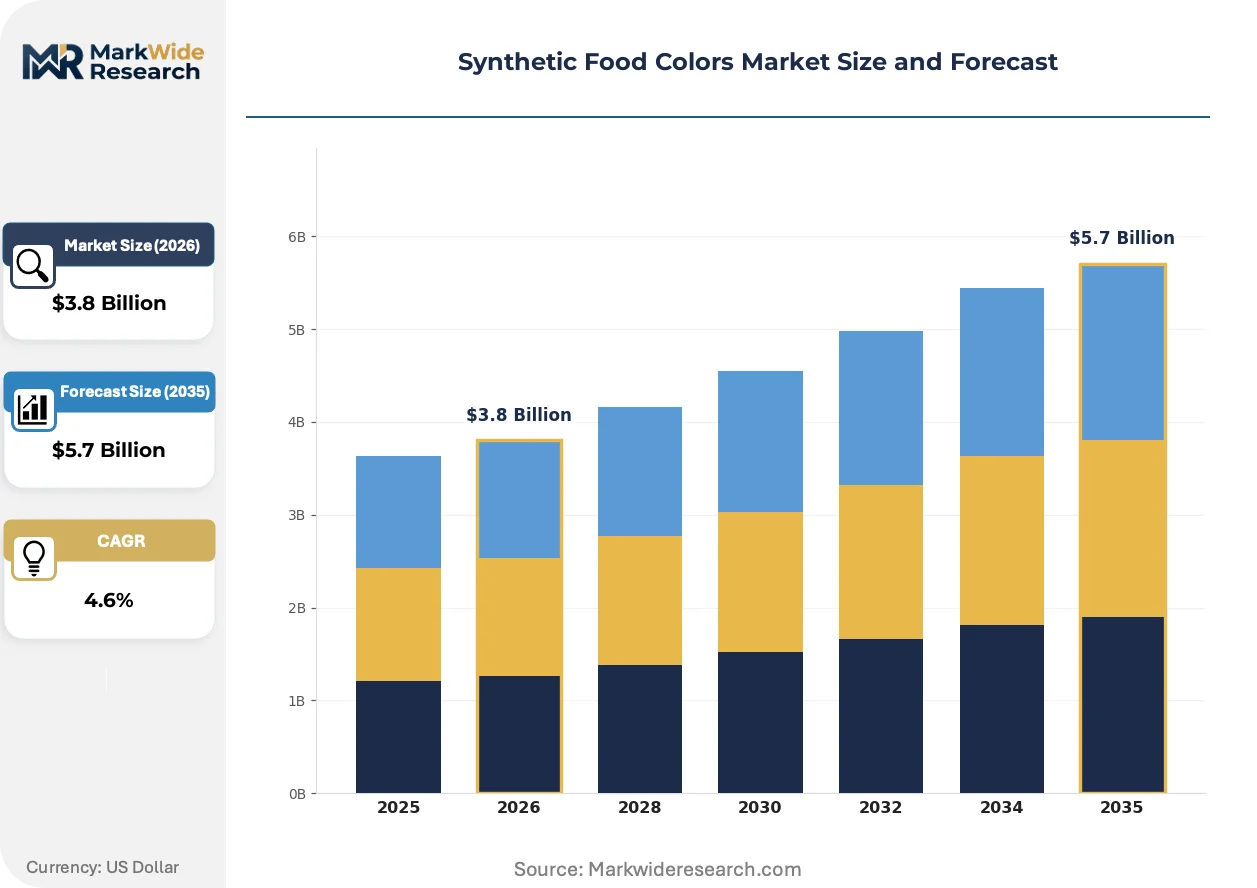
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dyes, Artificial Colors, Lake Colors, Liquid Colors Application: Beverages, Dairy Products, Bakery Items, Snack Foods End User: Food Manufacturers, Beverage Producers, Confectionery Industry, Snack Makers Form: Powder, Liquid, Gel, Granulated |
| Companies Covered | Sensient Technologies Corporation, BASF SE, Archer Daniels Midland Company, Chr. Hansen Holdings A/S, Dohler Group, Neelikon Food Dyes & Chemicals, Denim Colourchem (P) Limited, Vinayak Ingredients India Pvt Ltd, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Food Colors Market Evolving Landscape
Digital color matching and microencapsulation chemistries are compressing development cycles while regulatory divergence between major blocs fragments formulation standardization.
Microencapsulation technology is miniaturizing synthetic dye particles to enhance heat and light stability in confectionery applications. Coated colorant systems now enable manufacturers to reduce dosage rates by one-third while maintaining visual intensity through extended shelf life. This particle engineering is compressing competitive differentiation around stability performance rather than hue range alone.
EFSA's ongoing re-evaluation of aluminum lake specifications is forcing reformulation of coated candy and seasoning applications across European manufacturing. The regulatory body has signaled potential restrictions on acceptable daily intake levels that would displace current formulations within eighteen months. Confectionery producers are accelerating alternative carrier system testing to preempt supply disruption.
Consolidated procurement by multinational beverage brands is compressing supplier qualification timelines and unbundling technical service from base chemical supply. Category managers at major soft drink and dairy companies now mandate dedicated regulatory affairs support as a contract condition. This purchasing pattern shift is most pronounced in North American and Western European accounts where buyer concentration has intensified.
Synthetic Food Colors Market Segmentation
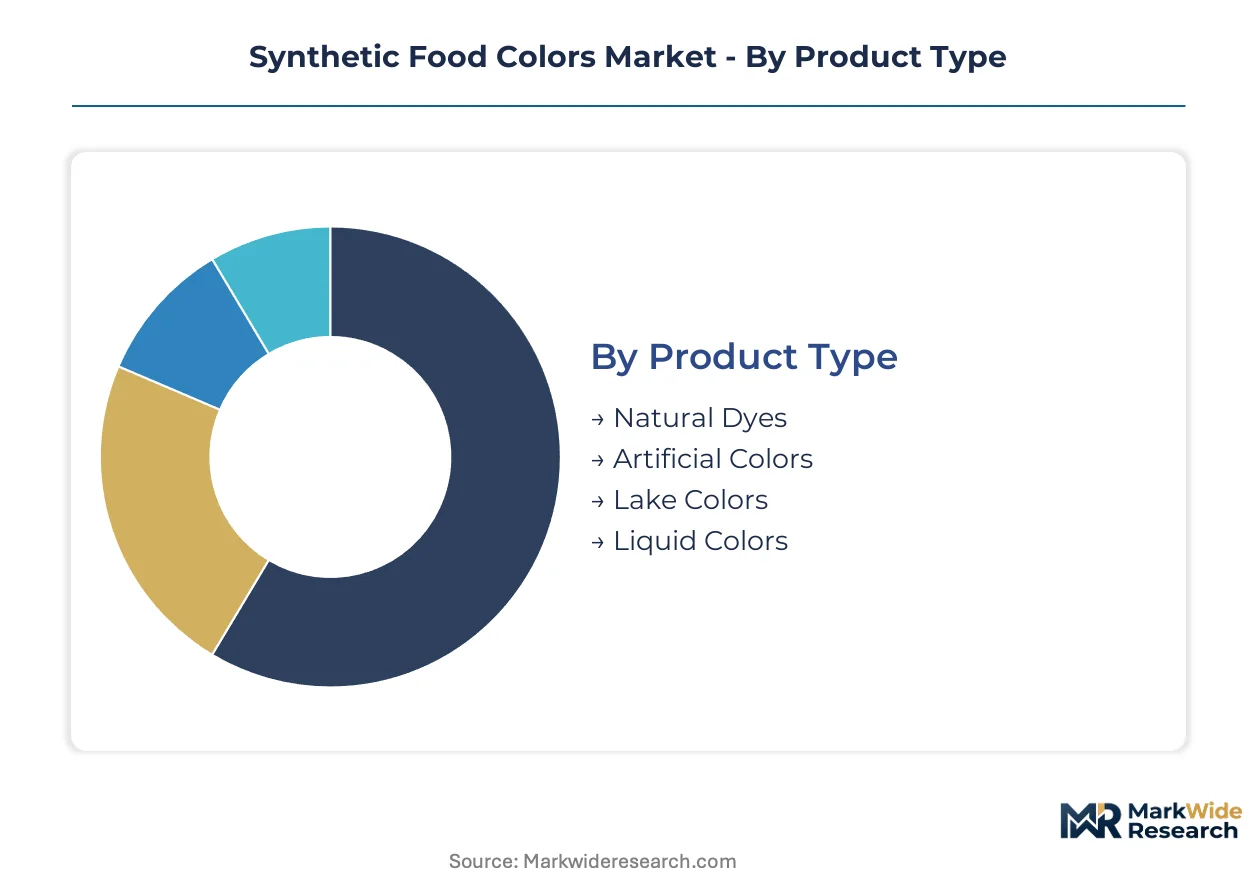
Segmentation in synthetic food colors reveals how formulation chemistry, physical state, and end-use requirements fragment procurement patterns. Manufacturers configure supply chains differently for beverage automation lines versus confectionery coating operations, creating distinct margin structures within each segment cluster.
Product Type:
Lake colors and liquid concentrates flow through technical distribution partnerships, while powder dyes move via bulk chemical channels with lower service attachment.
- Lake Colors:Fat-dispersible pigments formed by precipitating water-soluble dyes onto aluminum hydrate substrates. Indian snack manufacturers expanding into Middle Eastern export markets are scaling lake color procurement for heat-stable seasoning coatings.
- Liquid Colors:Pre-dispersed aqueous or propylene glycol solutions with standardized viscosity for automated dosing. Brazilian and Indonesian beverage producers retrofitting filling lines are driving specification tightening around microbial contamination thresholds.
- Natural Dyes:Carotenoid and anthocyanin extracts positioned as clean-label alternatives in premium SKU reformulations.
- Artificial Colors:Azo and triarylmethane-based certified dyes serving mature volume applications in mass-market processed foods.
Artificial colors dominate installed base. Liquid colors are where expansion concentrates.
Application:
Cost tier stratification separates pharmaceutical-grade color specifications from industrial food-grade volumes, with beverage applications commanding premium certification documentation.
- Beverages:Carbonated and functional drinks require pH-stable, light-fast colorants that maintain hue through pasteurization and extended shelf storage. Producers in Vietnam and Indonesia are penetrating vitamin-fortified segments with certified synthetic color systems.
- Snack Foods:Seasonings and coatings demand heat-stable pigments surviving frying and baking temperatures. Indian manufacturers scaling export capacity to African markets are concentrating lake color demand in this application.
- Dairy Products:Yogurt and flavored milk applications require acid-stable colorants with controlled particle size distribution.
- Bakery Items:Heat-exposed applications necessitate thermal degradation resistance in fondants and icings.
Beverage applications anchor premium pricing tiers. Snack foods are climbing the fastest in volume terms.
End User:
Customer type fragmentation splits between multinational procurement consolidation and domestic manufacturer technical service dependence.
- Beverage Producers:Carbonated and functional drink companies mandate dedicated regulatory affairs support as contract conditions. North American and Western European accounts have intensified buyer concentration, compressing supplier qualification timelines.
- Food Manufacturers:Processed food companies face reformulation pressure from tightening EFSA and FSSAI purity mandates, requiring batch revalidation against evolving specifications.
- Confectionery Industry:Coated candy producers are accelerating alternative carrier system testing as EFSA signals potential aluminum lake restrictions.
- Snack Makers:Seasoning and coating operations in India require technical partnership to navigate FSSAI labeling mandates without production line shutdowns.
Food manufacturers represent the broadest installed base. Beverage producers are where procurement consolidation concentrates.
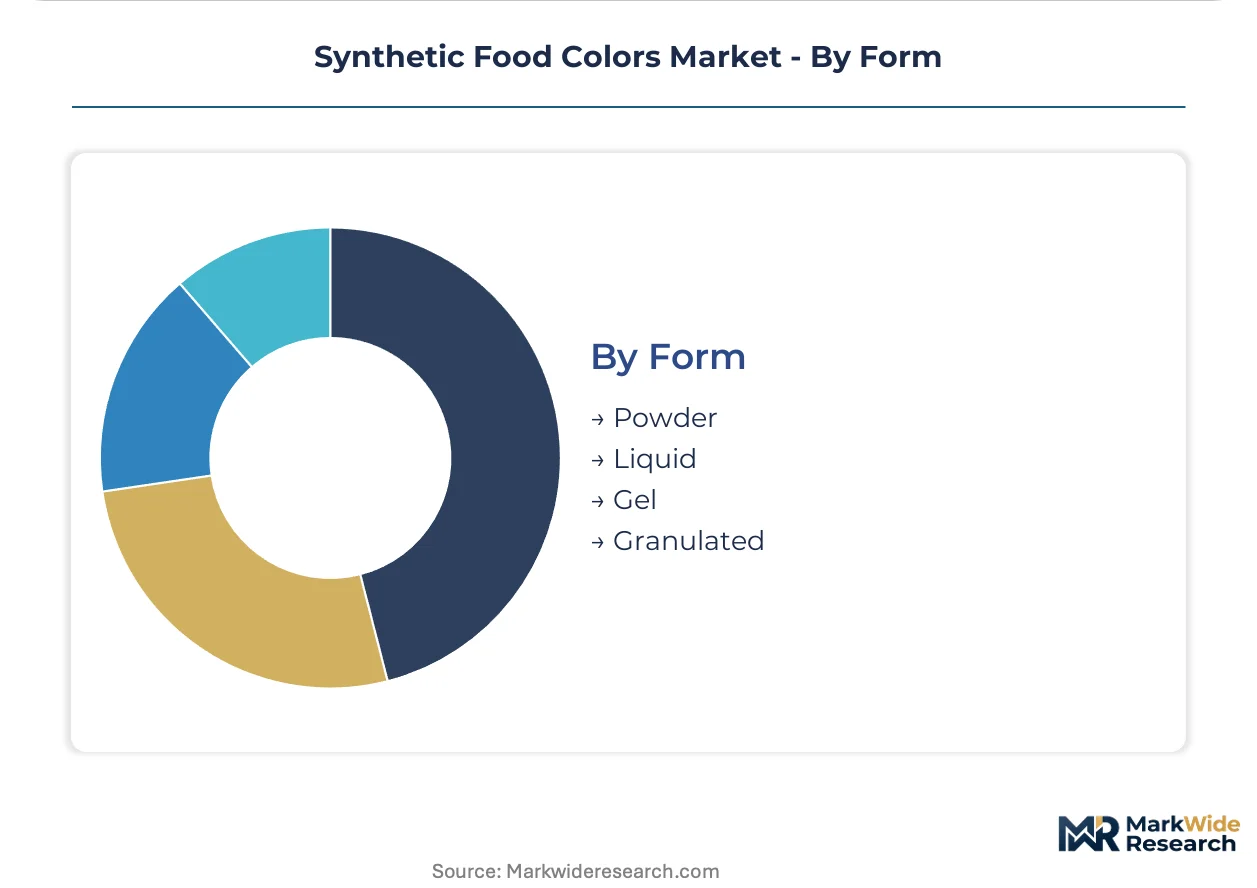
Form:
Supply concentration in Western European and select Indian chemical clusters limits geographic production expansion for specialized pH-resistant formulations.
- Powder:Standardized crystalline or spray-dried pigments requiring dust-controlled handling infrastructure. Legacy beverage plants face capital-intensive line reconfiguration and wastewater system upgrades when automating away from powder systems.
- Liquid:Pre-dispersed solutions reducing contamination risk and enabling precise automated dosing. Microencapsulation advances are miniaturizing particle engineering to enhance stability performance.
- Gel:High-viscosity suspensions for specialized confectionery and bakery applications requiring controlled release characteristics.
- Granulated:Low-dust agglomerated powders bridging handling convenience with dispersibility performance.
Powder forms dominate legacy installed base. Liquid forms are where automation investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys synthetic food colors predominantly in snack seasoning and confectionery coatings, while Germany concentrates usage in beverage automation and pharmaceutical-grade applications, creating divergent specification requirements across major consuming blocs.
United States
Beverage producers in Georgia and Texas are retrofitting automated dosing lines with liquid colorant systems to serve carbonated and functional drink portfolios. The FDA's Color Additive Status List mandates batch-lot certification documentation that compresses supplier qualification timelines for multinational accounts. Chicago-area technical distribution hubs coordinate regulatory affairs support as a standard contract condition for dairy and confectionery manufacturers.
Germany
Lake color demand from confectionery exporters concentrates in North Rhine-Westphalia as manufacturers preempt EFSA aluminum lake restrictions. The EU Food Additives Regulation enforces tightening purity benchmarks through EFSA re-evaluations that accelerate reformulation deadlines. BASF SE leverages integrated pigment chemistry capabilities from its Ludwigshafen complex to sustain supply security across European beverage accounts.
India
Domestic snack manufacturers in Maharashtra and Gujarat are scaling lake color procurement to serve Middle Eastern and African export markets with heat-stable coatings. FSSAI labeling mandates for synthetic dyes in packaged foods compel reformulation or risk distribution penalties. Mumbai and Ahmedabad industrial corridors concentrate formulation expertise for pH-resistant, heat-stable dyes that remains geographically scarce.
Brazil
Carbonated beverage automation in São Paulo state drives specification tightening around microbial contamination thresholds for liquid color systems. ANVISA enforces alignment with Mercosur food additive harmonization protocols that diverge from FDA and EFSA benchmarks. Campinas and Sorocaba manufacturing clusters retrofit filling lines to reduce powder-handling contamination risks in high-throughput operations.
Indonesia
Vitamin-fortified and probiotic drink segments in Java remain underpenetrated by certified synthetic color suppliers relative to regional peers. The national food and drug regulator applies evolving halal certification requirements that intersect with colorant purity specifications. Jakarta and Surabaya beverage production facilities represent primary targets for technical partnership penetration in functional beverage applications.
Synthetic Food Colors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates controlling pigment chemistry infrastructure while regional formulators capture niche certification services. The specialist tier fragments across geography-specific regulatory expertise, particularly for FSSAI compliance in India and EFSA navigation in Europe. Three archetypes dominate: integrated pigment-chemistry majors, certified-color solution distributors, and natural-alternative hybrid portfolio builders. Competitive moves concentrate on backward integration into sulfonation and diazotization intermediates, plus geographic expansion through technical distribution partnerships in Southeast Asian beverage markets.
Among integrated pigment-chemistry majors, BASF SE and Sensient Technologies Corporation exemplify divergent strategic positioning—BASF anchoring European supply security through captive chemical infrastructure, Sensient controlling North American distribution of certified solutions for dairy and confectionery applications. Chr. Hansen Holdings A/S occupies a distinct tier as a natural-alternative hybrid specialist navigating tightening regulatory thresholds. Indian specialists including Neelikon Food Dyes & Chemicals and Vinayak Ingredients India Pvt Ltd represent regional formulators with concentrated expertise in FSSAI compliance and heat-stable lake color production for export markets.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| BASF SE |
| Archer Daniels Midland Company |
| Chr. Hansen Holdings A/S |
| Dohler Group |
| Neelikon Food Dyes & Chemicals |
| Denim Colourchem (P) Limited |
| Vinayak Ingredients India Pvt Ltd |
| Symrise AG |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between multinational beverage producers and certified color suppliers lock in supply access and price visibility across volatile petrochemical feedstock cycles, particularly as naphtha-derived intermediates fluctuate with refinery output in India and Germany.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between major beverage producers and integrated pigment-chemistry majors, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation hinges on FDA versus EFSA batch-lot documentation and dedicated regulatory affairs support bundling. Cost compression in standard-grade azo dyes is intensifying because Indian snack manufacturers are scaling export capacity and squeezing margin on mature volume applications. Food manufacturers represent the most price-sensitive buyer segment due to reformulation pressure from tightening purity mandates, while pharmaceutical-grade specifications command the least sensitivity.
Supply Chain Analysis
Ludwigshafen chemical complex output and Mumbai-Ahmedabad industrial corridor production serve as chokepoints for European and Asian beverage supply security respectively. Manufacturing concentrates in Germany, India, and the United States for specialized sulfonation and diazotization intermediates. The supply chain draws from benzene derivatives, naphtha streams, and aluminum hydrate substrates as critical inputs. Single-source vulnerability around pH-resistant formulation expertise in Western European clusters threatens geographic expansion. Distribution runs through technical distribution partnerships for liquid concentrates and bulk chemical channels for powder dyes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent synthetic food color suppliers face sustained substitution pressure from carotenoid and anthocyanin alternatives in premium SKU lines, requiring defensive portfolio restructuring to maintain relevance across reformulation service revenue streams.
For Market Incumbents: Secure backward integration into sulfonation intermediates to insulate margin from naphtha volatility and anchor supply security for European beverage accounts. Expand technical distribution partnerships in Indonesia and Vietnam to preempt natural-alternative displacement in functional beverage segments.
For New Entrants and Emerging Players: FSSAI fast-track certification services represent the most penetrable white-space target, as domestic Indian manufacturers require technical partnership to navigate labeling mandates without production line shutdowns. Target vitamin-fortified drink segments in Java through regulatory affairs support bundling as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward regional formulators with concentrated FSSAI compliance expertise and heat-stable lake color production capabilities for Middle Eastern export markets. Long-term viability across the analysis window depends on hybrid natural-synthetic portfolio positioning that navigates tightening EFSA thresholds. Watch EFSA aluminum lake restriction signals as the critical inflection indicator for confectionery carrier system displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive sulfonation capacity insulates BASF and Sensient from naphtha volatility in European supply. |
| Technical Distribution Partnership | Indonesian beverage automation lines require localized regulatory affairs support for halal certification alignment. |
| Hybrid Portfolio Development | Blended color solutions open reformulation service revenue as Chr. Hansen navigates EFSA thresholds. |
| FSSAI Compliance Service Expansion | Neelikon and Vinayak capture domestic Indian manufacturer dependence on technical partnership for labeling mandates. |
| Microencapsulation R&D Investment | Particle engineering advances compress competitive differentiation around stability performance in confectionery applications. |
Research Methodology
Initial hypotheses were tested against primary input from color chemists at Indian lake color manufacturers, regulatory affairs directors at European beverage companies, procurement leads at multinational confectionery producers, and technical distribution partners in Southeast Asia, then refined through secondary validation against EFSA re-evaluation documentation, FSSAI labeling mandate circulars, FDA Color Additive Status List updates, and customs trade data for benzene derivative flows. Bottom-up volume modeling triangulated with top-down value estimates across product type, application, and regional production hub segmentation.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by grade tier and certification level. The analytical framework models liquid versus powder form penetration, beverage versus snack food application growth, and end-user procurement consolidation patterns. CAGRs were derived from segmented growth rate synthesis calibrated to industry-specific inputs including carbonated beverage automation retrofit timelines and EFSA enforcement deadline acceleration.
Decision-makers should treat outputs as directional under assumptions of sustained petrochemical feedstock availability and regulatory divergence between FDA and EFSA benchmarks; material deviation in aluminum lake restriction timing or FSSAI enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as natural colorant substitution rates and hybrid portfolio adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Citrus Extract Market