
 Dry Brewing Ingredients Market | 2026-2036
Dry Brewing Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Brewing Ingredients Market Insights
Asset-light leasing models for malting equipment and contract processing arrangements are fragmenting capital barriers across the competitive landscape. Malteurop Groupe leverages vertical integration from barley procurement to specialty malt finishing, sustaining margin capture across multiple quality grades. Rahr Corporation anchors its position through geographic dominance in North American distribution, while Lallemand Inc. differentiates via yeast strain biotechnology leadership. Viking Malt competes through Nordic sourcing control and sustainability certifications.
Dry brewing ingredients comprise malted cereals, processed hop products, active dried yeast, and adjunct carbohydrates, typically supplied with moisture content below 10 percent to ensure shelf stability and enzymatic consistency during mashing. These inputs function as the primary fermentable substrate, bittering agent, and flavor compound source in beer production. Malt and hop pellets occupy the largest value share within ingredient type segmentation, reflecting their irreplaceable role in recipe formulation across commercial brewing. Craft brewing applications demonstrate the fastest expansion trajectory, driven by portfolio diversification and small-batch experimentation. Powder and extract forms command premium positioning in home brewing channels where storage convenience and dosing precision matter most.
FDA food-contact regulations and EFSA processing standards govern contaminant thresholds and labeling protocols for cross-border ingredient trade. The EU Green Deal and associated farm-to-fork sustainability targets are reshaping barley cultivation contracts and malting energy benchmarks. Brewers Association quality guidelines in the United States add voluntary certification layers that influence procurement decisions. Stakeholders must monitor evolving carbon accounting requirements and water stewardship standards as these criteria penetrate supplier scorecards and contract renewal negotiations.
Market Dynamics
Specialty malt and hop pellet procurement is fragmenting as craft breweries in Germany, the United States, and Belgium bypass traditional distribution tiers to secure direct contracts with Nordic and Baltic suppliers, compressing intermediary margins while elevating quality-grade specifications.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Barley cultivation contracts across Denmark and Sweden now embed carbon accounting clauses, incentivizing malters to retrofit kilns with heat-recovery systems and capture sustainability premiums in export pricing.
- Craft brewing experimentation:Small-batch brewers in Portland, Oregon and Asheville, North Carolina are trialing heirloom barley varieties and experimental hop hybrids, generating pull-through demand for micro-maltsters and specialty pellet processors.
- Hop pellet processing:Cryogenic grinding and nitrogen-flushed packaging is extending alpha-acid stability from 12 to 24 months, enabling ocean freight substitution for air cargo and reducing landed costs for Asia-Pacific importers.
Market Restraints
- Barley price volatility:Drought cycles in Australia and Canada are amplifying futures contract spreads, forcing maltsters to hedge six to nine months forward and eroding margin predictability on fixed-price brewery contracts.
- Supply concentration in Rhineland-Palatinate:Three malting groups control 60 percent of German specialty malt capacity, creating bottleneck risk when kiln maintenance schedules align or barley harvests underperform.
- Moisture specification rigidity:FDA and EFSA thresholds below 10 percent moisture content require continuous thermal monitoring that legacy floor-malting facilities cannot retrofit without seven-figure capital outlays.
Strategic Opportunities
- India craft brewing emergence:Bangalore and Mumbai microbreweries are importing Belgian specialty malts and American aroma hop pellets, creating first-mover advantage for suppliers willing to navigate FSSAI import licensing complexity.
- Home brewing channel digitization:Direct-to-consumer platforms are disintermediating hobby-store distribution, enabling precision-dosed extract sachets and yeast vials with QR-linked brewing protocols.
- Carbon border adjustment mechanism:The EU's phased CBAM implementation is advantaging Nordic maltsters with certified renewable energy inputs, allowing premium positioning against Ukrainian and Argentine competitors.
Industry Challenges
- Malting chemist talent scarcity:European technical universities are graduating fewer kiln operators and diastatic power analysts than replacement demand requires, forcing employers to poach from competitor facilities or retrain food-process engineers.
- Legacy ERP integration:Batch-tracking requirements under FDA 21 CFR Part 117 are exposing data architecture gaps at mid-tier maltsters, necessitating expensive MES overlays or cloud migration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Brewing Ingredients Market |
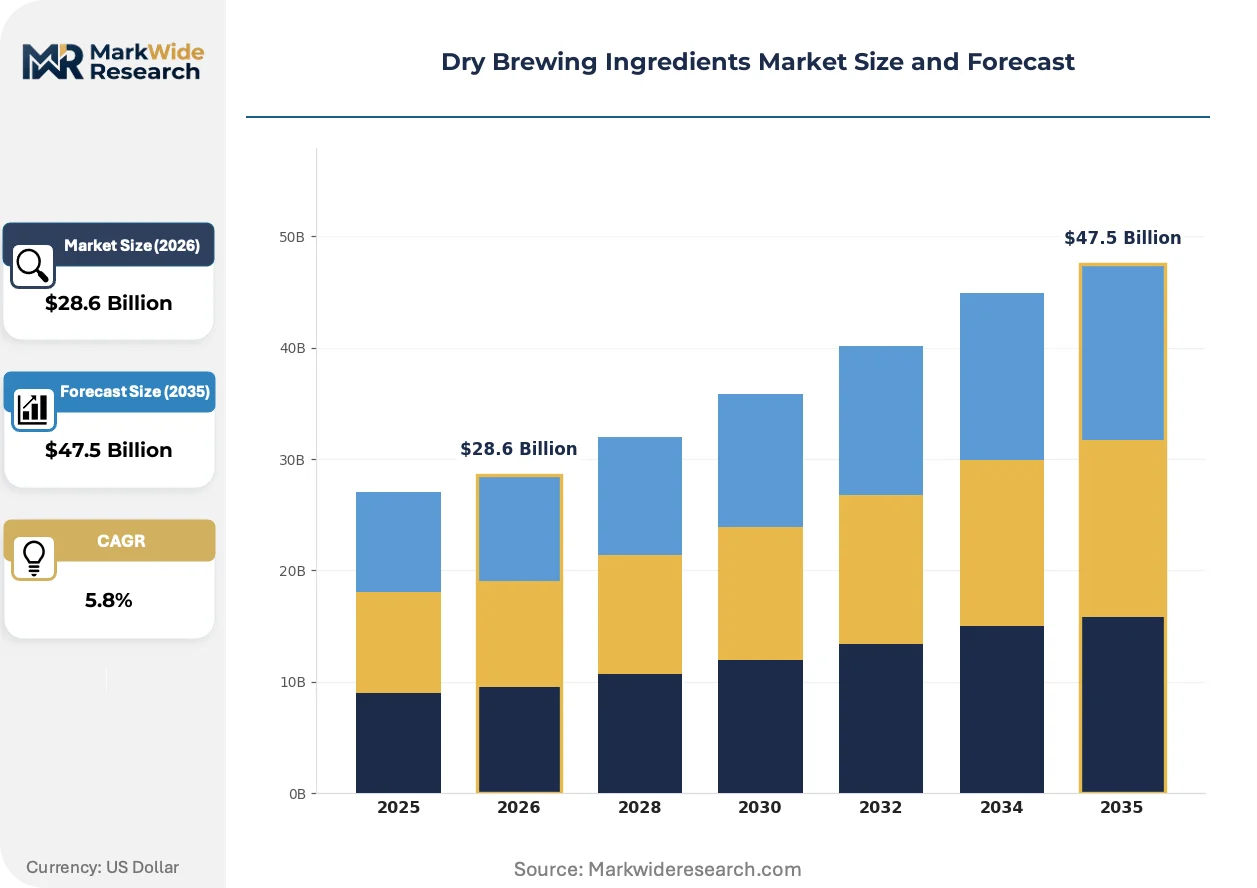
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Malt, Hops, Yeast, Adjuncts Form: Powder, Granule, Pellets, Extract Application: Beer Production, Home Brewing, Craft Brewing, Commercial Brewing Quality Grade: Standard, Organic, Premium, Specialty |
| Companies Covered | Angel Yeast Co. Ltd., Boortmalt, Malteurop Groupe, Rahr Corporation, Lallemand Inc., Viking Malt, Lesaffre, Maltexco S.A., Simpsons Malt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Brewing Ingredients Market Trends and Innovations
Process intensification and sustainability verification are restructuring how brewing inputs are produced, procured, and priced. Three developments are compressing timelines and elevating transparency expectations across the value chain.
Precision kilning using microwave-assisted drying is collapsing the traditional germination-to-kiln cycle from seven days to 48 hours. Craft maltsters in Scotland and the Czech Republic are piloting these systems to enable just-in-time specialty roast production. The technology is collapsing inventory carrying costs and allowing flavor-profile customization at order placement rather than harvest commitment.
EFSA's revised processing aid regulations and the EU's Corporate Sustainability Reporting Directive are mandating supply-chain disclosure down to barley variety and farm geolocation. Malt exporters to Germany must now document nitrogen fertilizer application rates and irrigation source compliance. Large brewing groups are responding by embedding auditors into Baltic and Black Sea supplier operations six months ahead of contract renewals.
Brewery procurement departments are consolidating supplier panels and demanding outcome-based malt specifications rather than varietal origin certificates. This behavior shift is displacing spot-market purchasing with three-year framework agreements indexed to alpha-acid potency and FAN levels. The transformation is most visible in Denmark and the Netherlands, where Carlsberg and Heineken operating companies are reducing active malt suppliers from twelve to four while doubling minimum contract volumes.
Dry Brewing Ingredients Market Segmentation
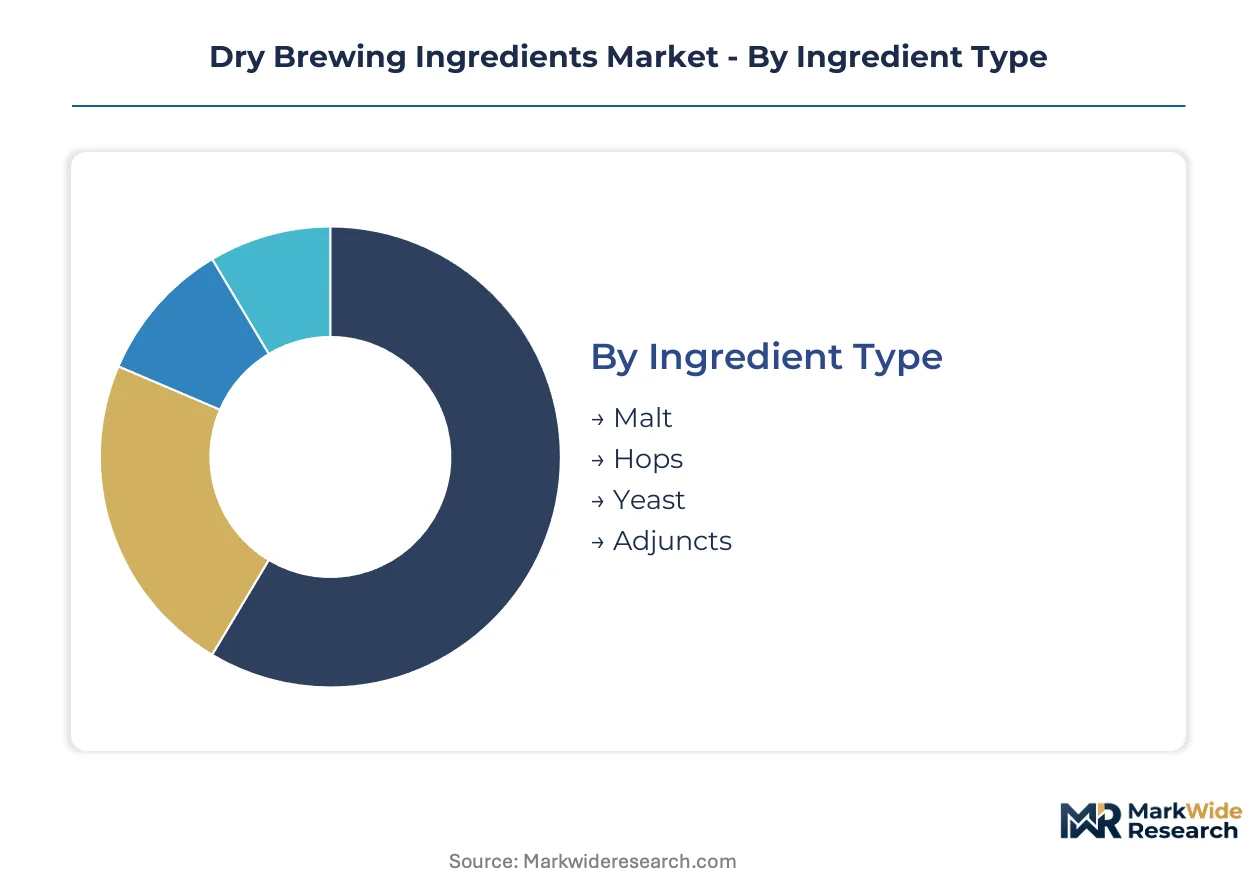
Dry brewing ingredients segment along four intersecting dimensions that determine procurement workflows, storage protocols, and margin structures. Ingredient type and form dictate equipment compatibility and shelf-life economics, while application and quality grade shape supplier qualification requirements and pricing frameworks.
Ingredient Type:
After-sales service intensity varies sharply across ingredient categories, with yeast requiring technical support for strain viability and malt demanding kiln maintenance partnerships.
- Malt:Germinated cereal grains dried to sub-10% moisture provide enzymatic diastatic power for starch conversion during mashing. Demand concentrates in German export-oriented breweries seeking Reinheitsgebot-compliant base malts and specialty roasts, driven by traditional protocol adherence and premium positioning requirements.
- Hops:Dried female cone flowers or processed pellets deliver alpha acids for bittering and essential oils for aroma. Pacific Northwest craft brewers in Oregon and Washington are expanding contracts for experimental aroma varieties, constrained by multi-year bine establishment cycles and proprietary breeding program access.
- Yeast:Active dried or liquid cultures of Saccharomyces strains execute fermentation and flavor biotransformation. Belgian and Czech brewers prioritize strain-specific propagation services from suppliers.
- Adjuncts:Unmalted cereals and fermentable sugars supplement malt bills for cost reduction or recipe differentiation. Corn and rice processors serve mass-market lager producers in the United States.
By volume, Malt leads. By growth pace, Hops is ahead.
Form:
Processing intensity and logistics economics separate powder and extract premium positioning from bulk granule and pellet commodity flows.
- Pellets:Compressed hop cones with standardized alpha-acid content enable precise dosing and extended stability. Cryogenic grinding with nitrogen flushing now extends viability to 24 months, allowing Asia-Pacific importers to substitute ocean freight for air cargo and reduce landed costs significantly.
- Extract:Concentrated hop or malt derivatives dissolve directly into wort without filtration residue. Home brewing channels in Germany and Belgium favor precision-dosed sachets with QR-linked protocols, driven by storage convenience and batch-size flexibility for apartment-scale production.
- Powder:Spray-dried yeast or malt extracts optimize for extended ambient storage. Direct-to-consumer platforms are disintermediating hobby-store distribution.
- Granule:Coarse-milled malt or agglomerated adjuncts suit high-volume brewhouse automation. North American commercial breweries favor bulk pneumatic conveying compatibility.
By volume, Granule leads. By growth pace, Extract is climbing the fastest.
Application:
Customer scale and technical sophistication create diverging service models, from mass-production procurement desks to enthusiast support hotlines.
- Craft Brewing:Small-batch producers experimenting with heirloom varieties and hybrid hop strains. Portland and Asheville brewers generate pull-through demand for micro-maltsters and specialty pellet processors, constrained by limited capital for multi-year ingredient contracts.
- Commercial Brewing:Large-scale facilities with automated brewhouses and consolidated supplier panels. Danish and Dutch operating companies are reducing active malt suppliers from twelve to four while doubling minimum contract volumes.
- Beer Production:Integrated operations spanning brewing, packaging, and distribution. German export-oriented facilities sustain premium ingredient procurement through traditional protocol adherence.
- Home Brewing:Enthusiast consumers purchasing through digital channels. Bangalore and Mumbai microbreweries are importing Belgian specialty malts and American aroma hop pellets, navigating FSSAI import licensing complexity.
By volume, Beer Production leads. By growth pace, Craft Brewing is gaining share fastest.
Quality Grade:
Certification tiers separate commodity spot-market transactions from framework agreements with embedded sustainability auditing and traceability documentation.
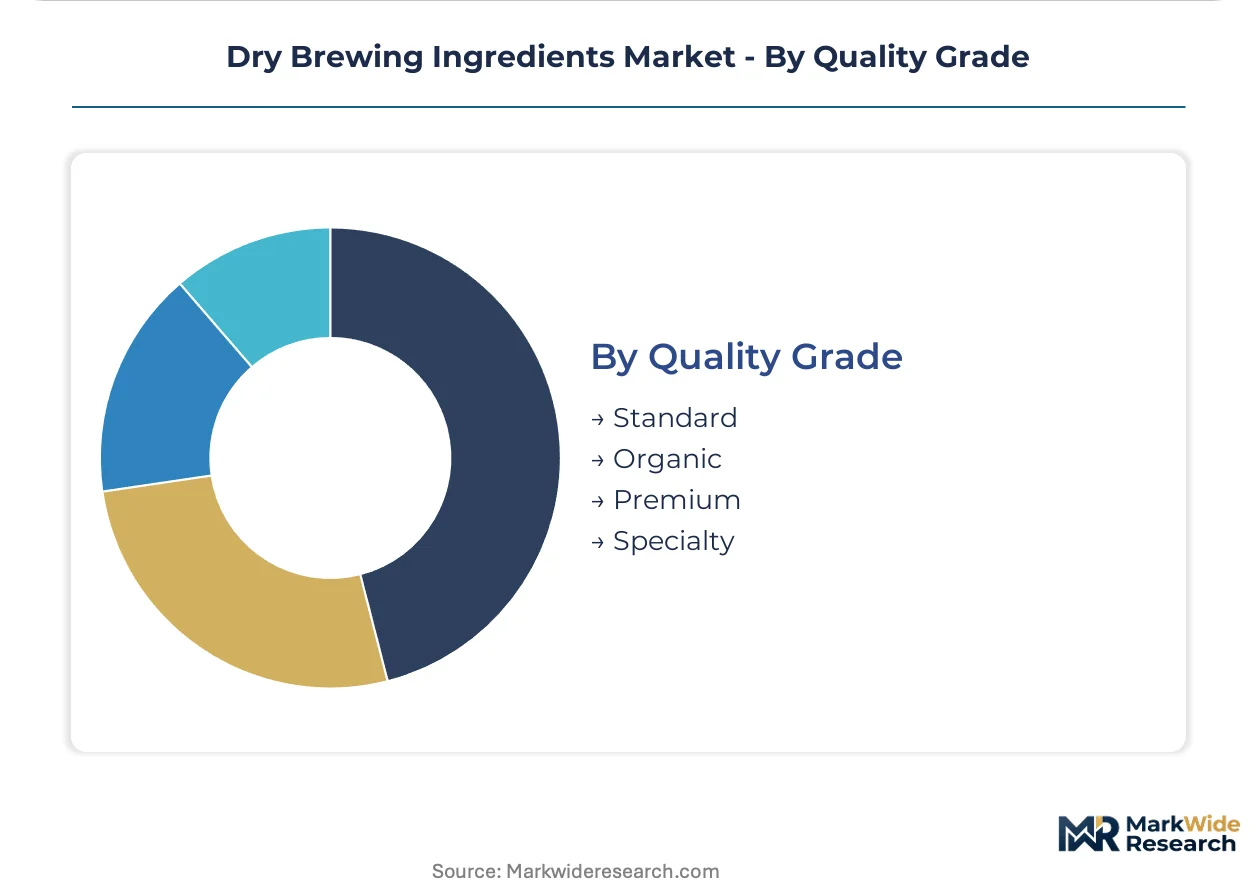
- Specialty:Limited-batch malts with defined flavor profiles from specific barley varieties or roasting protocols. Scotland and Czech Republic craft maltsters pilot microwave-assisted kilning to collapse germination-to-kiln cycles from seven days to 48 hours.
- Organic:Cultivation without synthetic fertilizers or pesticides, certified to EU or USDA standards. Nordic maltsters leverage certified renewable energy inputs to capture premiums against Ukrainian and Argentine competitors under CBAM implementation.
- Premium:Elevated specifications for protein content, moisture uniformity, or alpha-acid potency. Large brewing groups embed auditors into Baltic supplier operations six months ahead of contract renewals.
- Standard:Commodity-grade inputs meeting baseline FDA and EFSA thresholds. Floor-malting facilities face retrofit costs for continuous thermal monitoring compliance.
By volume, Standard leads. By growth pace, Specialty shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal farm-to-fork targets are reshaping barley cultivation contracts across northern Europe, embedding carbon accounting clauses that advantage certified renewable energy inputs. FDA and EFSA frameworks are tightening contaminant thresholds and cross-border labeling protocols, elevating supplier qualification requirements in key export markets.
Germany
Traditional brewing protocols and export-oriented production sustain premium ingredient procurement, with Reinheitsgebot compliance remaining mandatory for domestic positioning. The EU Green Deal is accelerating kiln retrofit requirements for heat-recovery systems. Rhineland-Palatinate hosts concentrated specialty malting capacity where three groups control the majority of output.
United States
Craft brewing experimentation in Oregon and North Carolina generates pull-through demand for heirloom barley varieties and experimental hop hybrids. FDA 21 CFR Part 117 batch-tracking requirements are exposing data architecture gaps at mid-tier maltsters. Portland and Asheville microbreweries bypass traditional distribution tiers to secure direct contracts with specialty suppliers.
Belgium
Strain-specific yeast propagation services anchor procurement relationships with traditional lambic and abbey-style producers. EFSA processing standards govern cross-border ingredient trade with neighboring Netherlands and France. Brussels-Antwerp corridor facilities prioritize certified organic malt streams for premium positioning.
India
Bangalore and Mumbai microbreweries are importing Belgian specialty malts and American aroma hop pellets, creating first-mover advantage for navigators of FSSAI import licensing complexity. The country's national food safety regulator is tightening processing aid approvals for foreign-sourced inputs. Western Maharashtra and Karnataka urban clusters concentrate craft brewing emergence.
Denmark
Operating companies are reducing active malt suppliers from twelve to four while doubling minimum contract volumes, consolidating procurement panels. CSRD supply-chain disclosure mandates are requiring barley variety and farm geolocation documentation. Copenhagen-based brewing groups embed auditors into Baltic supplier operations ahead of contract renewals.
Dry Brewing Ingredients Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated malting groups, specialized biotechnology providers, and regional sourcing specialists. Three strategic archetypes dominate: grain-to-malt integrators controlling barley procurement through finishing, biotechnology leaders leveraging strain development capabilities, and sustainability-certified regional players capturing carbon-accounting premiums. Competitive moves center on three-year framework agreements replacing spot purchasing, and geographic expansion into emerging craft brewing markets.
Within the integrated malting tier, Malteurop Groupe and Boortmalt exemplify backward integration from agricultural sourcing through specialty finishing, capturing margin across multiple quality grades. Rahr Corporation anchors North American distribution dominance, while Lallemand Inc. and Lesaffre occupy positions within the biotechnology archetype focused on fermentation strain development. Viking Malt represents the sustainability-certified regional specialist model, leveraging Nordic sourcing control and renewable energy inputs.
| Leading Market Players |
|---|
| Angel Yeast Co. Ltd. |
| Boortmalt |
| Malteurop Groupe |
| Rahr Corporation |
| Lallemand Inc. |
| Viking Malt |
| Lesaffre |
| Maltexco S.A. |
| Simpsons Malt |
| Others |
Pricing and Supply Chain Analysis
Asia-Pacific ocean freight corridors linking Rhineland-Palatinate maltsters to Bangalore and Mumbai microbreweries compress landed costs when nitrogen-flushed hop pellet packaging extends alpha-acid viability to 24 months. This logistics flexibility intensifies price competition among Nordic and Baltic suppliers while elevating quality-grade premiums for direct-contract craft brewers.
Pricing Analysis
Certification level under EFSA and FDA food-contact frameworks creates the primary spread between commodity spot transactions and framework agreements with embedded sustainability auditing. Three-tier pricing structure across premium, standard, and economy levels tracks quality grade and volume scale, with specialty malt and experimental hop hybrids commanding significant premiums. Cost compression in standard-grade malt is intensifying because legacy floor-malting facilities face seven-figure retrofit costs for continuous thermal monitoring compliance. Craft brewing applications demonstrate the least price sensitivity due to portfolio differentiation requirements, while mass-market lager producers exhibit acute sensitivity to barley futures volatility.
Supply Chain Analysis
Tariff exposure between EU-origin specialty malts and Indian craft brewing importers dominates supply chain risk planning as FSSAI licensing complexity lengthens customs clearance timelines. Geographic supply concentrates in Germany, Denmark, and Belgium for premium malt finishing, while Pacific Northwest hop cultivation in Oregon and Washington anchors alpha-acid sourcing. Raw material dependencies rest on Australian and Canadian barley, proprietary hop breeding programs, and strain-specific yeast propagation services. Single-source vulnerability emerges from three malting groups controlling majority German specialty malt capacity. Distribution runs through consolidated procurement panels at Carlsberg and Heineken operating companies, with direct-to-consumer platforms disintermediating home brewing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barley harvest cyclicality and drought-induced futures volatility position this market for recovery as maltsters rebuild margin buffers through kiln retrofit investments and carbon-accounting premium capture.
For Market Incumbents: Build captive supply moats through backward integration into Baltic and Black Sea barley procurement with embedded farm-geolocation auditing. Consolidate supplier panels from twelve to four active malt relationships while doubling minimum contract volumes to secure volume commitments. Invest in microwave-assisted kilning R&D to collapse germination-to-kiln cycles and enable just-in-time specialty roast production. Counter the threat of craft brewer direct-contracting with Nordic suppliers by embedding technical service teams into Portland and Asheville brewing clusters. For New Entrants and Emerging Players: Mid-market craft maltsters in Scotland and the Czech Republic piloting precision kilning technology represent the most penetrable entry point for equipment-leasing and contract processing services. Bangalore and Mumbai microbrewery import demand for Belgian specialty malts and American aroma hop pellets offers first-mover positioning for FSSAI-licensed navigators. Home brewing channel digitization through precision-dosed extract sachets with QR-linked protocols enables direct-to-consumer bypass of hobby-store distribution. For Investors and Strategic Acquirers: Sustainability-certified regional specialists with Nordic sourcing control and renewable energy inputs present compelling acquisition targets as EU CBAM implementation advantages their carbon-accounting positioning. Long-term viability hinges on three-year framework agreement penetration replacing spot-market purchasing across Danish and Dutch operating companies. Monitor craft brewing experimentation rates in Oregon and North Carolina as early signals of pull-through demand inflection for micro-maltsters and specialty pellet processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Procurement | Captures margin across multiple quality grades while embedding CSRD-compliant farm-geolocation documentation. |
| Microwave-Assisted Kilning Technology Deployment | Collapses germination-to-kiln cycles from seven days to 48 hours for just-in-time specialty roast production. |
| Carbon Border Adjustment Mechanism Certification | Allows Nordic maltsters premium positioning against Ukrainian and Argentine competitors under phased EU implementation. |
| Direct-to-Consumer Home Brewing Platform Launch | Disintermediates hobby-store distribution through precision-dosed extract sachets with QR-linked brewing protocols. |
| Three-Year Framework Agreement Consolidation | Reduces active malt suppliers from twelve to four while doubling minimum contract volumes at Carlsberg and Heineken operating companies. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA processing standards documentation, FDA 21 CFR Part 117 batch-tracking requirements, EU Green Deal farm-to-fork target disclosures, and customs trade data from Baltic and Black Sea barley corridors. Primary interviews with malting plant managers, craft brewery procurement leads, kiln operations technicians, and FSSAI licensing consultants were combined with bottom-up volume triangulation against top-down value estimates. Secondary validation drew from Brewers Association quality guidelines, SEC filings of publicly traded brewing groups, and Nordic sustainability certification databases.
Forecast inputs include ingredient type segmentation across malt, hops, yeast, and adjuncts; form differentiation between pellets, extracts, powders, and granules; application tiers spanning craft brewing, commercial brewing, beer production, and home brewing; and quality grade stratification from specialty through standard levels. CAGRs were derived through regression analysis of historical procurement volumes against barley cultivation contract trends and craft brewery establishment rates. Industry-specific inputs incorporate kiln retrofit investment cycles, hop bine establishment timelines, and yeast strain propagation lead times.
Practitioners should monitor barley harvest underperformance in Australia and Canada, Rhineland-Palatinate kiln maintenance alignment, and FSSAI import licensing processing delays for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Canola Meal Market
Ingredients
Wheat Malt Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Chewing Gum Base Market
Ingredients
Terminalia Extract Market
Ingredients
Marine Protein Market
Ingredients
Jojoba Oil Market
Ingredients
Low Fat Cooking Oil Market