
 Blue Light Protection Ingredients Market | 2026-2036
Blue Light Protection Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Blue Light Protection Ingredients Market Outlook
Cosmetic chemist expertise in photoprotection formulation is redrawing competitive boundaries in the Blue Light Protection Ingredients Market. BASF Group leverages its pigment and dispersion technology leadership to anchor supply relationships with multinational skincare houses. Croda International Plc sustains R&D intensity through dedicated biotech screening programs for novel antioxidant mechanisms. DSM Nutritional Products differentiates via its nutritional-to-topical ingredient crossover portfolio, occupying a unique position between ingestible and dermal blue light defense.
Blue light protection ingredients comprise topical actives engineered to absorb, reflect, or neutralize high-energy visible light in the 380-500 nanometer range, primarily through inclusion of mineral oxides, organic filters, and polyphenolic compounds that mitigate reactive oxygen species generation in skin tissue. Antioxidants command the deepest margin pools as brands seek clinically substantiated claims beyond basic SPF equivalence, while filters face formulation compatibility constraints that limit their deployment in clear-finish serums. Skincare applications dominate volume uptake, though sunscreens represent the fastest-growing segment as regulators and consumers collapse the distinction between UV and HEV protection.
The U.S. FDA governs cosmetic ingredient safety through the Federal Food, Drug, and Cosmetic Act, while the EU's REACH framework and Cosmetic Product Regulation impose pre-market safety dossier requirements that shape formulation choices across export-oriented suppliers. China's NMPA and GB standards for cosmetics create additional testing burdens for antioxidant and filter claims in that market. Stakeholders must monitor evolving photobiology standards from ISO and national dermatological associations to anticipate where clinical evidence thresholds will next tighten.
Market Dynamics
EU Cosmetic Product Regulation amendments are forcing ingredient dossier upgrades across blue light protection portfolios, compressing supplier timelines while elevating clinical substantiation costs for antioxidant and mineral filter formulations.
Growth Catalysts
- REACH compliance layering:European formulators now integrate HEV-active compounds into existing SPF pipelines to satisfy consolidated safety dossier requirements, accelerating dual-claim product development.
- Dermatological endorsement channels:South Korean medical aesthetic clinics prescribe blue light defense serums as post-procedure protocols, embedding ingredients into reimbursed skincare regimens.
- Biotech screening platforms:Automated polyphenolic compound discovery is shortening antioxidant development cycles from traditional botanical extraction timelines.
Market Restraints
- Mineral oxide supply concentration:Ultra-fine zinc oxide and titanium dioxide production clusters in Chinese pigment manufacturing zones, exposing formulators to export licensing volatility.
- Formulation compatibility barriers:Organic HEV filters exhibit photodegradation in clear-finish serum matrices, limiting deployment in premium transparent facial products.
- Regulatory fragmentation:China's NMPA maintains distinct GB standards for antioxidant efficacy claims, requiring separate clinical testing protocols from EU dossiers.
Strategic Opportunities
- Underpenetrated Indian cosmetic market:Rising smartphone penetration and limited domestic HEV-active production create import substitution openings for European antioxidant suppliers.
- Ingestible-topical convergence:Nutraceutical brands are licensing dermal delivery patents to create oral blue light defense capsules, expanding addressable channels beyond skincare.
- ISO photobiology standardization:Emerging consensus on HEV exposure metrics will mandate certified testing, favoring laboratories with established dermatological validation partnerships.
Industry Challenges
- Cosmetic chemist talent scarcity:Photoprotection formulation expertise concentrates among aging specialists in German and Swiss R&D clusters, constraining scale-up capacity.
- Clinical substantiation timelines:OECD-compliant in-vitro HEV testing protocols require 18-24 month validation cycles, delaying product launches beyond traditional cosmetic development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue Light Protection Ingredients Market |
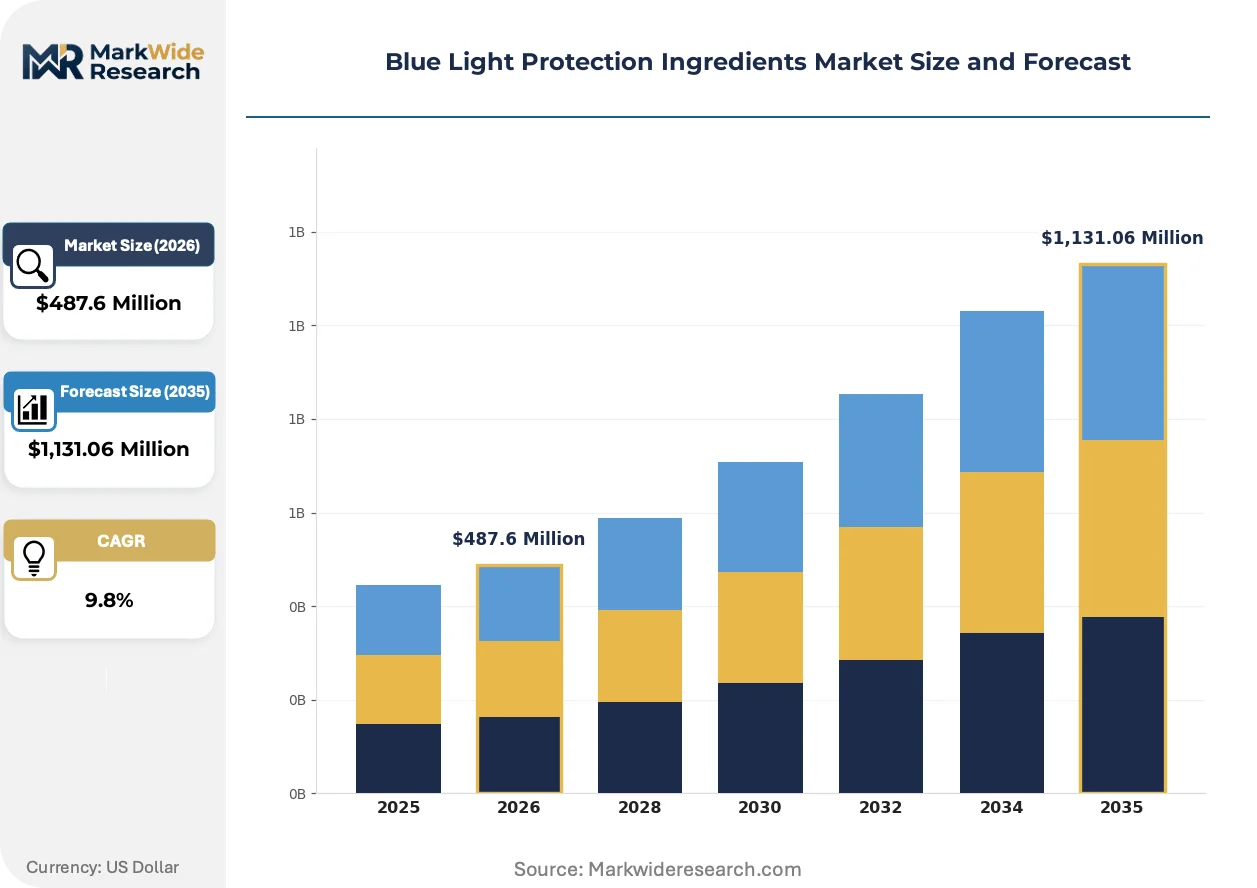
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Antioxidants, Filters, Emollients, Sunscreen Agents Application: Skincare, Haircare, Cosmetics, Sunscreens End User: Retail Consumers, Dermatologists, Salons, Spa Professionals Formulation Type: Creams, Serums, Lotions, Gels |
| Companies Covered | Croda International Plc, RAHN AG, DSM Nutritional Products, Kobo Products, Ashland Global Specialty Chemicals, BASF Group, Evonik Industries, Lonza Group, Clariant International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue Light Protection Ingredients Market Strategic Shifts
Formulation science is fragmenting along photoprotection specialization lines, with mineral dispersion technology, biotech-derived antioxidants, and dual-function UV-HEV compounds competing for R&D capital allocation.
Microencapsulated mineral oxide systems are decomposing traditional formulation trade-offs between protection density and cosmetic elegance. Prestige skincare houses in the United States and Germany are adopting these systems for tinted moisturizer launches. The technology is decomposing the historical premium attached to transparent organic filters, compressing margin structures for legacy chemical sunscreen suppliers.
REACH authorization requirements for novel cosmetic ingredients are tightening evidentiary thresholds for ROS-neutralization claims. European formulators must now submit extended safety profiles for polyphenolic compounds targeting the 400-500 nanometer range. Sunscreen manufacturers face the steepest compliance burden, as regulators collapse distinctions between UV and HEV protection categories.
Direct-to-dermatologist sampling is displacing traditional retail education for professional-grade blue light defense products. Medical aesthetic channels in South Korea and Germany now account for the primary volume of high-concentration antioxidant serums. This channel rotation is most visible in Seoul's Gangnam district clinic clusters, where procedure bundling embeds ingredient claims into treatment protocols.
Blue Light Protection Ingredients Market Segmentation
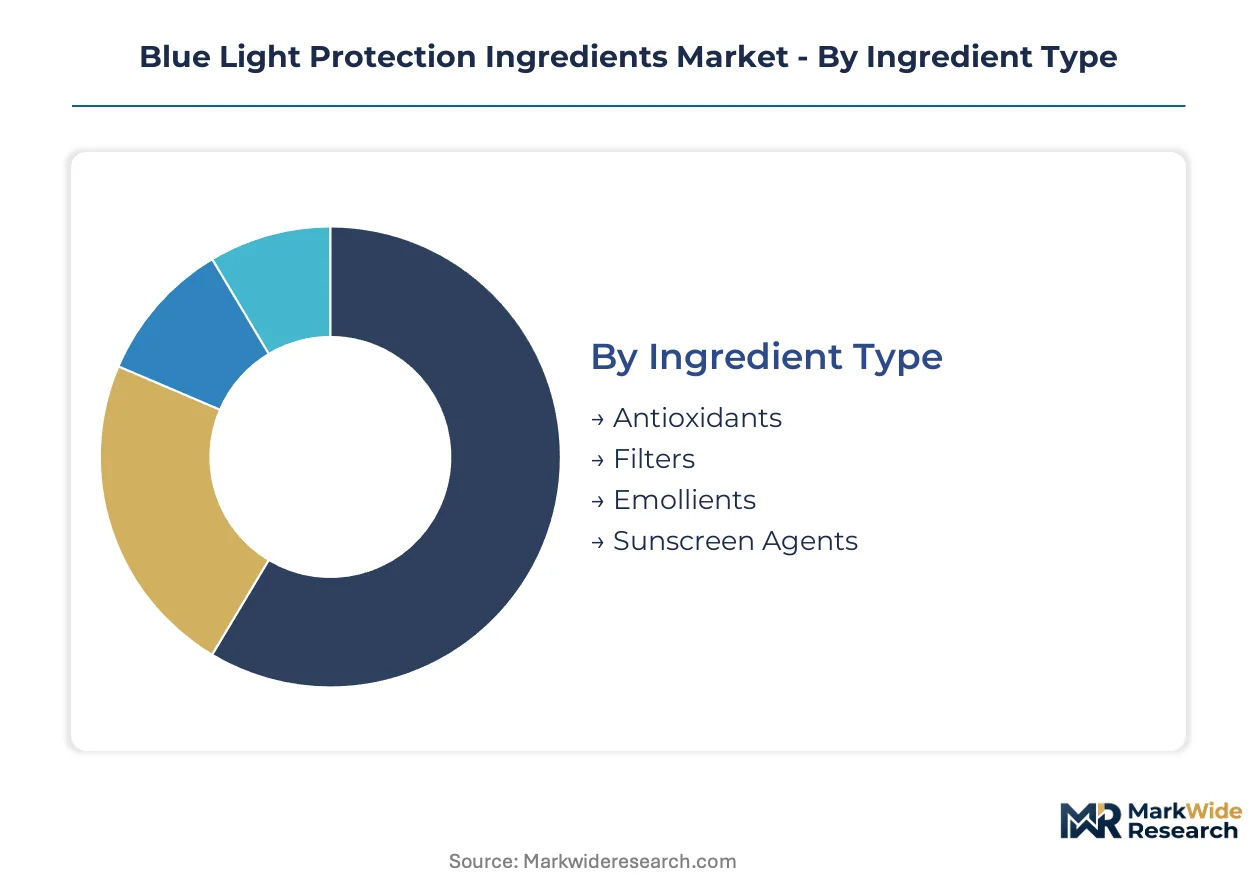
Channel configuration determines which ingredient segments capture margin in blue light protection. Professional channels favor clinically substantiated antioxidants, while mass retail concentrates on filter-based daily wear formulations.
Ingredient Type:
Antioxidants flow primarily through dermatologist and medical aesthetic channels where clinical validation commands premium positioning. Filters distribute through mass retail and e-commerce where SPF equivalence messaging simplifies consumer education.
- Antioxidants:Polyphenolic compounds and carotenoid complexes neutralize reactive oxygen species generated by HEV exposure. Demand concentrates in South Korean medical aesthetic clinics where post-procedure protocols bundle high-concentration serums into reimbursed treatment regimens.
- Filters:Mineral oxides and organic HEV-specific compounds absorb or reflect 380-500 nanometer wavelengths. Formulators in Germany face REACH authorization pressures that extend safety dossier timelines for novel organic filter molecules.
- Emollients:Barrier-supporting lipids enhance antioxidant penetration while improving cosmetic elegance in daily wear products.
- Sunscreen Agents:Dual-function UV-HEV compounds collapse regulatory distinctions between protection categories, accelerating consolidated product development pipelines.
By volume, filters lead. By growth pace, antioxidants are climbing the fastest.
Application:
Cost tier stratification separates professional-grade treatments from accessible daily defense, with medical channels capturing the steepest margin premiums.
- Skincare:Facial serums and moisturizers dominate absolute volume as brands expand blue light claims across existing SPF-adjacent product lines. United States prestige houses drive microencapsulated mineral oxide adoption for tinted formulations.
- Sunscreens:Regulatory convergence of UV and HEV protection categories is accelerating dual-claim product launches. South Korean manufacturers face the shortest path to market given established MFDS testing protocols for photoprotection.
- Haircare:Scalp-focused HEV defense emerges as a differentiation vector in professional salon channels.
- Cosmetics:Color-infused protection integrates mineral oxides into foundation and concealer matrices where transparency requirements limit organic filter deployment.
Skincare captures the deepest revenue pool. Sunscreens gain share fastest as regulatory frameworks consolidate.
End User:
Customer type determines clinical substantiation intensity and pricing architecture across the value chain.
- Dermatologists:Prescription-grade protocols in Seoul's Gangnam district clinic clusters embed high-concentration antioxidants into reimbursed post-laser regimens. German dermatological associations are tightening evidence thresholds for HEV-neutralization claims.
- Retail Consumers:E-commerce and specialty beauty retailers filter demand toward accessible price points where SPF equivalence messaging substitutes for complex photobiology education.
- Salons:Professional treatment bundling creates volume for cream-based applications with immediate cosmetic finish.
- Spa Professionals:Wellness-oriented positioning emphasizes ingestible-topical convergence in premium resort and destination spa channels.
Dermatologists anchor premium pricing. Retail consumers provide volume scale.
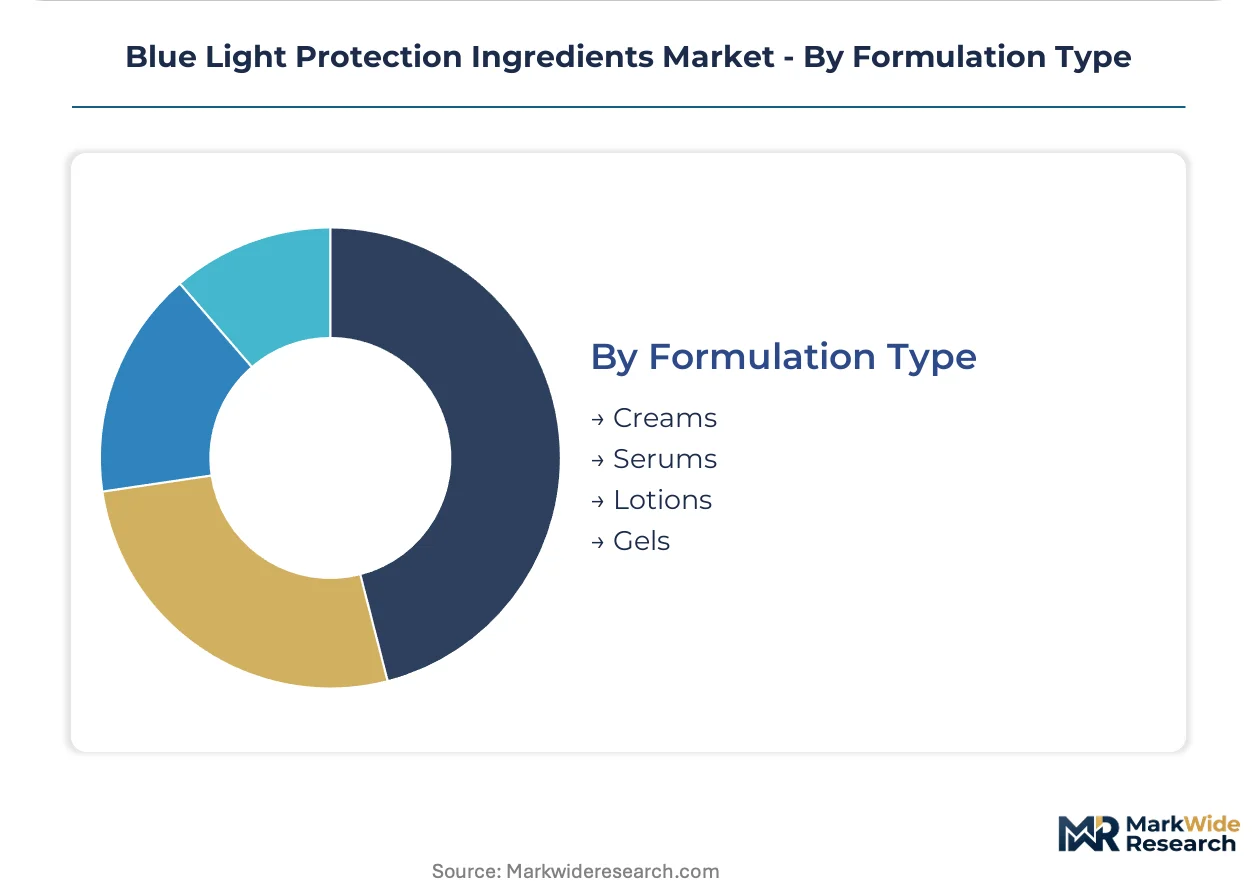
Formulation Type:
Supply concentration in Chinese ultra-fine mineral oxide production shapes which formats achieve cost-competitive transparency.
- Serums:Clear-finish matrices favor microencapsulated mineral systems over photodegradable organic filters. United States prestige launches in 2023-2024 demonstrated technical viability for transparent zinc oxide at cosmetic elegance parity with chemical alternatives.
- Creams:Traditional emulsion vehicles accommodate the widest range of antioxidant loadings and mineral oxide concentrations. German R&D clusters concentrate formulation expertise for high-protection density creams.
- Lotions:Body-scale applications favor cost-optimized mineral dispersions where cosmetic elegance constraints relax.
- Gels:Water-based matrices suit oil-averse consumer segments in humid climates, though HEV-active compatibility remains technically constrained.
Creams maintain volume leadership. Serums show the steepest expansion trajectory as transparency engineering matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic ingredient oversight in the United States anchors the dominant geography, though REACH dossier requirements in Germany and MFDS testing protocols in South Korea exert comparable regulatory gravity on formulation choices.
United States
Prestige skincare houses drive microencapsulated mineral oxide adoption for tinted moisturizers and clear-finish serums. The FDA's Federal Food, Drug, and Cosmetic Act governs safety substantiation for antioxidant claims. New York and Los Angeles R&D clusters concentrate formulation expertise for dual-function UV-HEV compounds.
Germany
REACH authorization timelines compress supplier development cycles for novel organic HEV filters. ECHA dossier requirements elevate clinical evidence thresholds for ROS-neutralization claims. The Rhine-Main region hosts specialized photoprotection formulation laboratories serving export-oriented cosmetic houses.
South Korea
Medical aesthetic clinics in Seoul's Gangnam district embed high-concentration antioxidants into reimbursed post-laser treatment protocols. MFDS testing frameworks provide the shortest regulatory path for photoprotection product launches. Busan-Ulsan manufacturing zones supply ultra-fine mineral oxides to domestic and regional formulators.
China
NMPA GB standards create distinct testing burdens for antioxidant efficacy claims separate from EU dossier requirements. Rising smartphone penetration drives consumer awareness of HEV skin damage. Yangtze River Delta pigment production clusters concentrate ultra-fine zinc oxide and titanium dioxide manufacturing capacity.
India
Limited domestic HEV-active ingredient production creates import substitution openings for European antioxidant suppliers. BIS cosmetic safety standards are evolving to address novel photoprotection claims. Maharashtra's Mumbai-Pune industrial corridor attracts contract manufacturing investment for skincare export production.
Blue Light Protection Ingredients Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Blue Light Protection Ingredients Market. Multinational chemical conglomerates with integrated pigment and dispersion capabilities occupy the technology frontier, while specialized biotech screening firms command premium positioning for novel antioxidant mechanisms. Three archetypes dominate: diversified chemical majors with cosmetic ingredient divisions, dedicated cosmetic active suppliers with biotech pipelines, and mineral oxide specialists with dispersion engineering expertise. Competitive moves concentrate on strategic partnerships for clinical validation and geographic licensing agreements to access medical aesthetic channels.
Among diversified chemical majors, BASF Group and Evonik Industries occupy positions anchored in pigment technology and specialty chemical formulation expertise respectively. DSM Nutritional Products exemplifies the nutritional-to-topical crossover archetype, bridging ingestible and dermal blue light defense applications. Croda International Plc represents dedicated cosmetic active suppliers with sustained R&D intensity through biotech screening programs.
| Leading Market Players |
|---|
| Croda International Plc |
| RAHN AG |
| DSM Nutritional Products |
| Kobo Products |
| Ashland Global Specialty Chemicals |
| BASF Group |
| Evonik Industries |
| Lonza Group |
| Clariant International Ltd |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month REACH authorization timelines for novel HEV-active compounds concentrate pricing power among European suppliers with validated safety dossiers, while compressing margins for formulators forced into dual-claim product development cycles. Inventory cycles for ultra-fine mineral oxides now stretch 90-120 days as Chinese pigment manufacturers face export licensing volatility, creating tiered cost structures that separate premium microencapsulated systems from commodity dispersions.
Pricing Analysis
Geographic price spreads between German REACH-compliant antioxidants and Indian import-substitution alternatives exceed 40 percent at equivalent concentration loadings, reflecting certification-grade differentiation. Pricing stratifies across premium, standard, and economy tiers based on clinical substantiation depth and dermatological endorsement channel access. Cost compression in standard-grade mineral oxide dispersions is intensifying because Yangtze River Delta production clusters face environmental compliance layering. Retail consumers exhibit highest price sensitivity, while Seoul medical aesthetic clinics absorb premium markups for post-procedure protocol integration.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for antioxidant raw materials sourced from Chinese botanical extraction facilities. Ultra-fine zinc oxide and titanium dioxide production concentrates in China, with secondary clusters in South Korea and Germany. The supply chain draws from polyphenolic compound feedstocks, carotenoid complexes, and specialized mineral dispersion agents. Single-source vulnerability persists in microencapsulation technology licensing controlled by Rhine-Main region specialists. Distribution runs through multinational skincare house procurement divisions, regional contract manufacturers, and direct-to-clinic channels in Seoul's Gangnam district.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across photoprotection specialization lines creates niche capture opportunities as dermatological endorsement channels displace traditional retail education for professional-grade formulations.
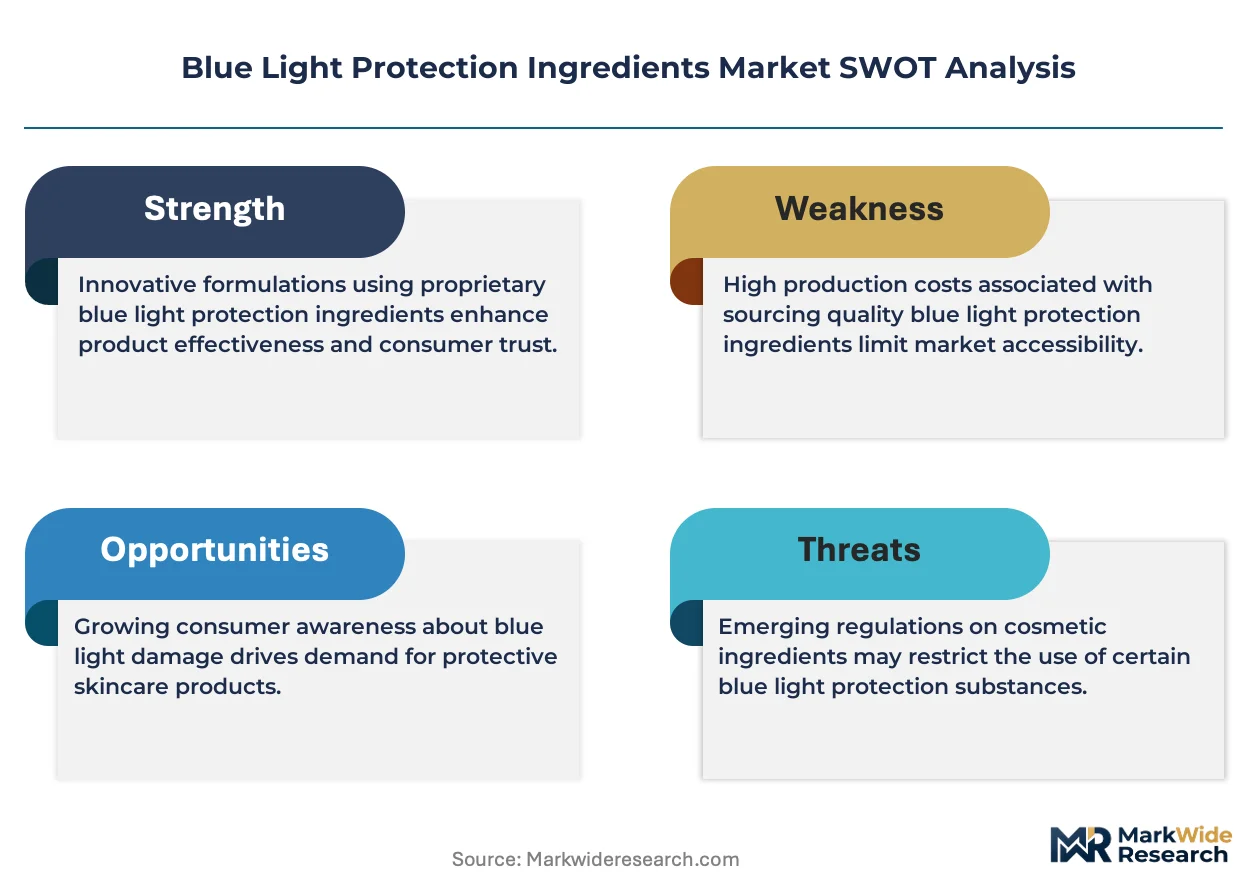
For Market Incumbents: Consolidate formulation expertise through targeted acquisition of biotech screening platforms in German and Swiss R&D clusters, where photoprotection chemist talent scarcity constrains scale-up capacity. Deepen captive supply of microencapsulated mineral oxide systems to defend against transparent organic filter substitution in clear-finish serum matrices. Prioritize REACH dossier pre-validation investments to compress competitor authorization timelines. For New Entrants and Emerging Players: Post-procedure protocol bundling in South Korean medical aesthetic clinics represents an underserved service layer where incumbents under-serve at price points accessible to mid-tier antioxidant suppliers. Target Indian import substitution demand for HEV-active ingredients as smartphone penetration accelerates consumer awareness ahead of domestic production capacity. Pursue direct-to-dermatologist sampling agreements as the primary go-to-market angle, bypassing retail margin compression. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because REACH authorization barriers and MFDS testing protocol convergence will consolidate value capture among dossier-rich suppliers. Acquisition targets should emphasize cosmetic chemist talent density and established dermatological validation partnerships rather than commodity mineral oxide capacity. Watch for ISO photobiology standardization announcements as the signal indicating which testing laboratories will capture certified validation revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Screening Platform Acquisition | Novel antioxidant mechanism discovery shortens development cycles beyond traditional botanical extraction timelines. |
| REACH Dossier Pre-Validation Investment | Extended safety profiles for 400-500 nanometer compounds compress competitor authorization windows under ECHA requirements. |
| Direct-to-Dermatologist Channel Development | Seoul Gangnam clinic clusters embed ingredient claims into reimbursed post-laser treatment protocols. |
| Microencapsulation Technology Licensing | Rhine-Main region dispersion engineering expertise enables transparent zinc oxide parity with chemical filter cosmetic elegance. |
| Ingestible-Topical Convergence Partnership | Nutraceutical licensing of dermal delivery patents expands addressable channels beyond skincare into oral defense capsules. |
Study Parameters
Initial hypotheses were tested against primary input from cosmetic chemists, regulatory affairs specialists at ECHA-notified bodies, procurement directors at multinational skincare houses, and medical aesthetic clinic operators in Seoul, then refined through secondary validation against REACH authorization databases, MFDS photoprotection testing protocols, FDA Federal Food Drug and Cosmetic Act guidance documents, and customs trade data for ultra-fine mineral oxide imports. Bottom-up ingredient demand modeling triangulated against top-down market sizing from prestige and mass retail channel revenue flows.
Variance decomposition across the projection horizon isolates volume drivers by ingredient type, application format, end-user channel, and formulation technology maturity. Segmentation dimensions modeled include antioxidant versus filter versus emollient classification, skincare versus sunscreen versus haircare application, dermatologist versus retail consumer versus salon end-user, and serum versus cream versus gel formulation matrix. CAGRs were derived from regression analysis of historical authorization timelines and channel penetration rates, with specific inputs from OECD-compliant in-vitro HEV testing protocol adoption curves and medical aesthetic procedure volume growth in reimbursed skincare regimens.
Forecasts assume regulatory continuity in EU REACH, US FDA, and South Korea MFDS frameworks; material policy shifts in photoprotection claim substantiation thresholds would require re-modeling. Specific risk factors include export licensing volatility in Chinese pigment manufacturing zones, photodegradation failure rates for organic HEV filters in clear-finish matrices, and clinical validation timeline extensions under tightening German dermatological association evidence standards. Practitioners should keep alternative scenarios live as ISO photobiology standardization and ingestible-topical convergence patent litigation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Pet Food Ingredients Market
Ingredients
China Beer Adjuncts Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Broccoli Powder Market
Ingredients
US Vegetable Oil Market
Ingredients
Non-GMO Oil Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Cocoa Fiber Market
Ingredients
France Soy Protein Market
Ingredients
Omega 6 Market
Ingredients
Fermentation Ingredient Market
Ingredients
Dark Yeast Extract Market
Ingredients
Avocado Powder Market