
 Middle-East and Africa Vegetable Oil Market | 2026-2036
Middle-East and Africa Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Vegetable Oil Market Foresight
Mechanical pressing and solvent extraction integration is reconfiguring crush economics across North African refineries. Cargill Incorporated leverages its Red Sea logistics network to supply Egyptian and Saudi food manufacturers. Wilmar International Limited anchors palm oil throughput at its West African port facilities. ADVOC competes on refined sunflower and soybean oil output for UAE domestic consumption.
Vegetable oil comprises triglycerides extracted from oilseed or fruit mesocarp through pressing, solvent extraction, or rendering, with free fatty acid content and iodine value determining suitability for food, oleochemical, or fuel applications. Palm oil dominates volume flows into the region's food processing sector due to cost advantages in frying and shortening formulations. Sunflower oil captures premium positioning in retail channels across South Africa and Morocco as consumers prioritize monounsaturated fat profiles. The industrial use segment extends into biodiesel feedstock and lubricant base stocks, though policy support varies by jurisdiction.
Saudi Food and Drug Authority and South African Department of Health enforce maximum aflatoxin limits and labeling standards that filter out unregistered suppliers. EAC customs union rules and COMESA tariff structures shape intra-regional trade corridors for Ugandan and Tanzanian sunflower seed. Gulf Standards Organization harmonization reduces technical barriers for UAE, Kuwait, and Omani distributors. Stakeholders must track how Egypt's food subsidy reforms and Nigeria's palm oil development programs redirect procurement patterns before committing to crush capacity expansions.
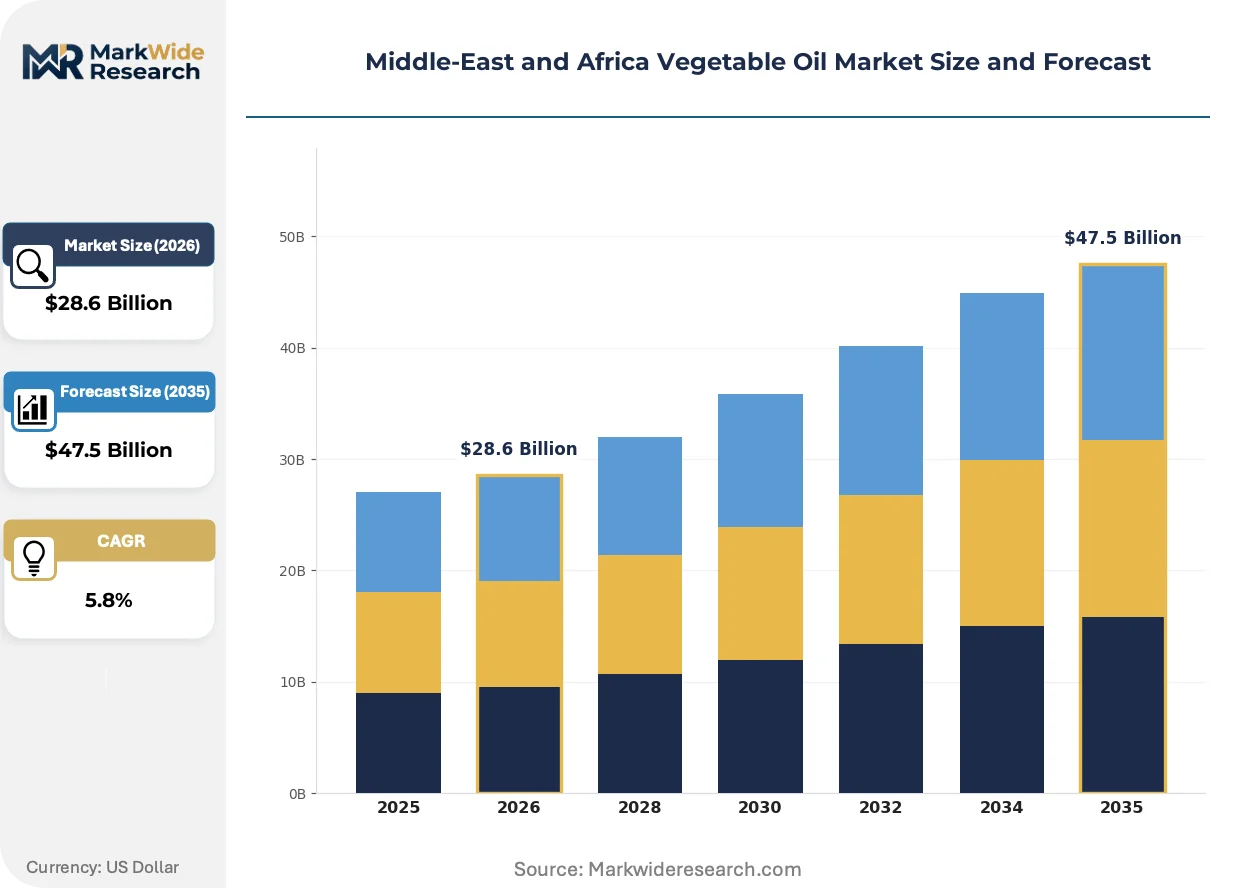
Market Dynamics
Mechanical pressing and solvent extraction integration is compressing crush margins across North African refineries while Saudi Arabia's retail and hospitality sectors absorb volumes beyond domestic crushing capacity.
Growth Catalysts
- Gulf Standards Organization harmonization:Unified technical barriers reduction enables UAE, Kuwait, and Omani distributors to scale cross-border refined oil flows without redundant testing protocols.
- Food processing expansion:Nigerian and Egyptian packaged goods manufacturers are expanding refined oil offtake for frying and shortening formulations in snack and bakery lines.
- Palm oil cost structure:Malaysian and Indonesian supply chains maintain delivered cost advantages into regional food service channels against locally crushed alternatives.
Market Restraints
- Seed supply concentration:Ugandan and Tanzanian sunflower seed flows depend on EAC customs union rules and COMESA tariff structures that fragment intra-regional procurement.
- Aflatoxin compliance friction:Saudi Food and Drug Authority and South African Department of Health maximum limits filter unregistered suppliers from formal distribution channels.
- Local crushing underinvestment:Saudi domestic crushing capacity lags consumption growth, forcing reliance on Red Sea import corridors subject to freight volatility.
Strategic Opportunities
- Morocco retail premiumization:Sunflower oil positioning around monounsaturated fat profiles captures shelf space in formal retail channels serving health-conscious urban consumers.
- Biodiesel feedstock pivot:Industrial use segments extend into lubricant base stocks where policy support in South Africa and Nigeria creates offtake certainty.
- Egypt subsidy reform timing:Food subsidy restructuring redirects public procurement patterns toward private crush capacity investments ahead of program implementation.
Industry Challenges
- Refinery skill scarcity:Solvent extraction and deodorization operations require process engineers that North African labor markets undersupply relative to capacity expansion timelines.
- Certification lag:Gulf Cooperation Council import compliance documentation stretches lead times for new market entrants unfamiliar with harmonized food safety standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Vegetable Oil Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunflower Oil, Palm Oil, Soybean Oil, Olive Oil End User: Food Processing, Personal Care, Household, Industrial Use Distribution Channel: Retail, Wholesale, Online, Direct Sales Packaging Type: Bottles, Cans, Pouches, Bulk |
| Companies Covered | Sime Darby Plantation Berhad, Amira Nature Foods Ltd, Cargill Incorporated, Savola Group, Archer Daniels Midland Co., ADVOC (ABU DHABI VEGETABLE OIL COMPANY), Omani Vegetable Oils & Derivatives Co.(L.L.C), IFFCO Group, Wilmar International Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Vegetable Oil Market Shifts & Advancements
Digital process control systems and sustainability verification protocols are restructuring how vegetable oil moves from crush facilities to end-use formulations across the Middle-East and Africa corridor.
Near-infrared spectroscopy for real-time oil quality monitoring is virtualizing laboratory testing workflows at Egyptian and Saudi refineries. Large-scale food manufacturers are adopting inline analysis to compress batch release cycles from hours to minutes. This capability is virtualizing quality assurance labor costs while enabling just-in-time formulation adjustments that reduce waste.
Gulf Standards Organization food safety harmonization is consolidating technical requirements across UAE, Kuwait, and Omani import regimes. Refiners now submit single compliance documentation for multi-territory distribution rather than parallel national registrations. Egyptian and Saudi food manufacturers benefit most, as their suppliers face reduced administrative duplication when serving GCC markets.
Food service operators in Saudi Arabia and South Africa are consolidating procurement through integrated supply contracts that bundle oil with packaging and distribution services. Traditional spot-market purchasing through commodity brokers loses share to annual framework agreements with crush facilities or integrated traders. This consolidation concentrates buying power among national hospitality chains and quick-service restaurant groups with multi-outlet footprints.
Middle-East and Africa Vegetable Oil Market Segmentation
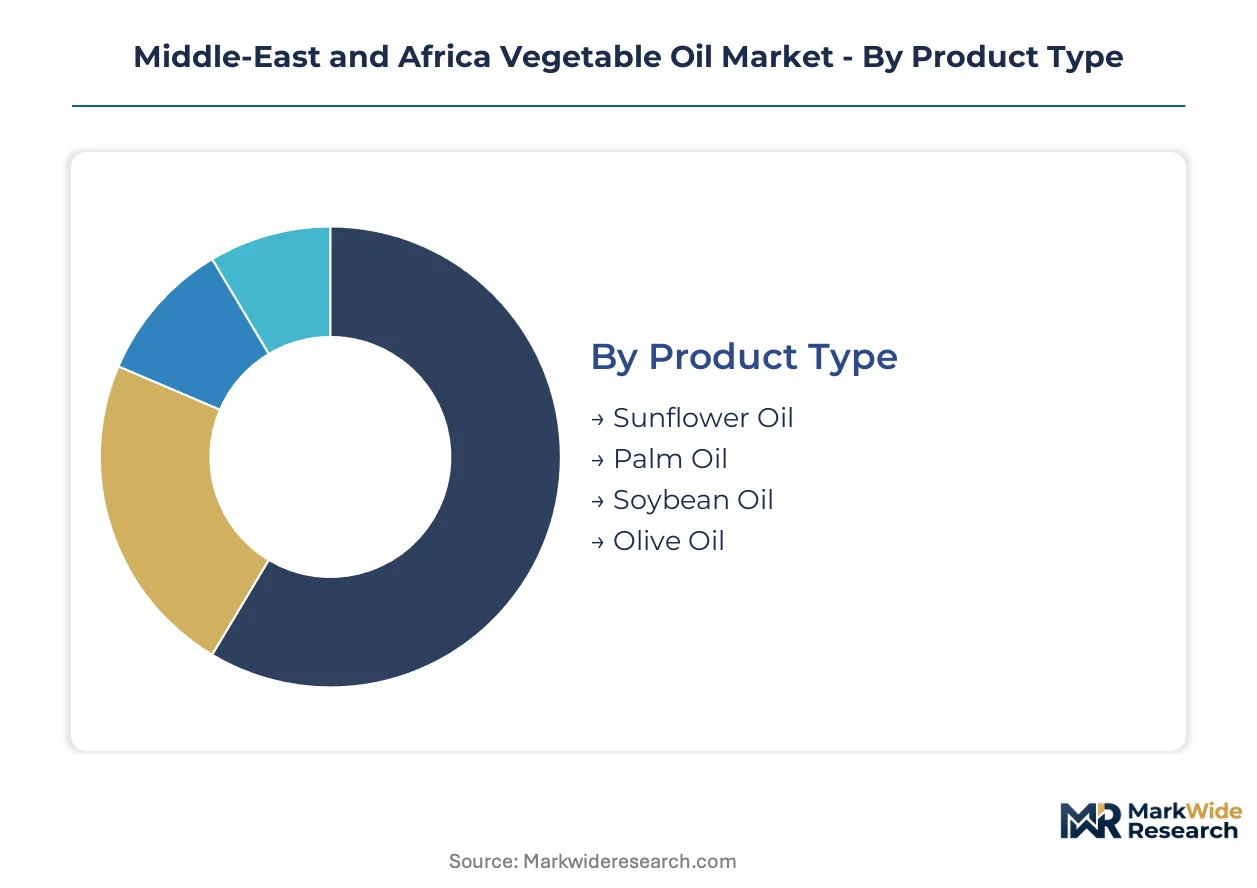
Segmentation in Middle-East and Africa vegetable oil markets reveals how procurement cycles, regulatory exposure, and margin structures vary dramatically across product categories and channel configurations. Understanding these divides allows suppliers to align crushing investments with actual consumption velocity rather than aggregate demand signals.
Product Type:
Palm oil turns over fastest through food service channels with minimal specification lag, while olive oil sits longest in inventory due to vintage positioning and premium retail cycles.
- Palm Oil:Semi-solid at room temperature with high saturated fat content and oxidative stability suited for repeated frying cycles. Nigerian and Egyptian snack manufacturers absorb the largest volumes for shortening and frying fat formulations, though Malaysian and Indonesian import dependency exposes margins to freight volatility.
- Sunflower Oil:Light-colored refined oil with high oleic variants commanding shelf space in formal retail. South African and Moroccan urban consumers drive demand through health-positioned purchasing, with monounsaturated fat profiles supporting premium pricing against polyunsaturated alternatives.
- Soybean Oil:Versatile liquid oil with moderate linoleic acid content serving industrial biodiesel offtake in South Africa and Nigeria where policy frameworks create demand certainty.
- Olive Oil:Extra-virgin and refined grades differentiated by free fatty acid thresholds and polyphenol retention, concentrated in Gulf retail channels serving expatriate and affluent local households.
Palm oil anchors the volume base while sunflower oil gains share at the steepest rate.
End User:
Cost tiers separate commodity-scale buyers with annual framework contracts from premium-positioned purchasers accepting specification premiums for certification or traceability.
- Food Processing:Integrated snack, bakery, and confectionery manufacturers operating continuous production lines with just-in-time oil delivery requirements and inline quality monitoring systems. Egyptian and Saudi packaged goods producers represent the largest contracted offtake segment.
- Industrial Use:Biodiesel refiners and lubricant compounders purchasing technical-grade oils with specific iodine value and moisture parameters. South African renewable fuel policy and Nigerian blending mandates create structural demand.
- Household:Retail consumers purchasing through modern trade and traditional souk channels, with pouch and bottle formats dominating frequency-driven replenishment patterns.
- Personal Care:Cosmetic formulators requiring deodorized and winterized grades with tight peroxide value specifications for emulsion stability in skincare and haircare products.
Food processing commands the largest revenue pool while industrial use demonstrates the most elastic expansion trajectory.
Distribution Channel:
Customer type stratification runs from multinational hospitality groups with centralized procurement to fragmented traditional retail requiring credit-extending intermediaries.
- Wholesale:Volume aggregation through commodity traders and regional distributors supplying food manufacturers and institutional kitchens across Red Sea and Mediterranean corridors.
- Retail:Supermarket and hypermarket chains in Saudi Arabia, UAE, and South Africa controlling shelf access and private label development for mid-tier positioning.
- Direct Sales:Crush facilities and integrated traders contracting directly with national quick-service restaurant chains and bakery groups, displacing traditional broker intermediation.
- Online:Emerging e-commerce platforms and subscription services capturing urban convenience-seeking segments with premium and specialty oil assortments.
Wholesale retains volume dominance while direct sales climbs fastest as procurement consolidation accelerates.
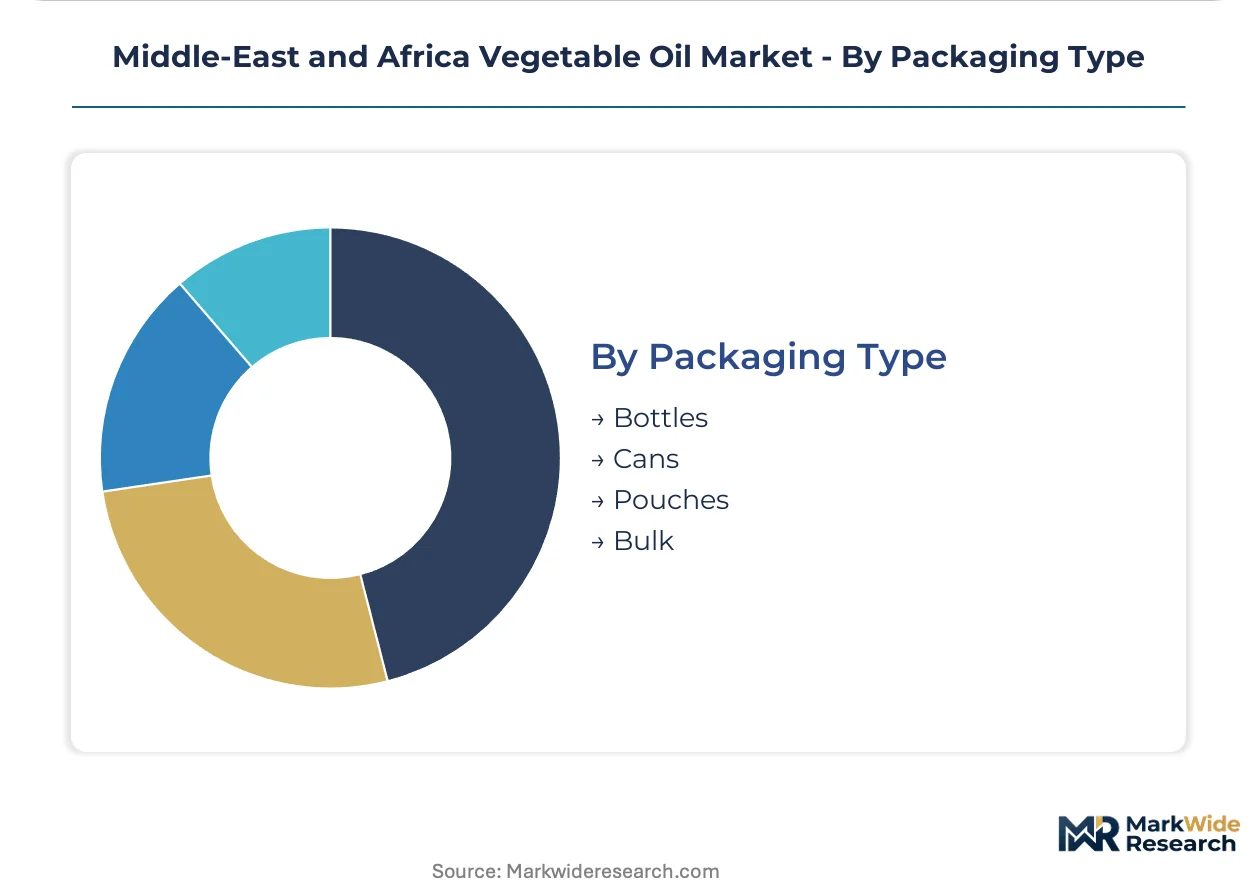
Packaging Type:
Supply concentration varies from single-source bulk terminal deliveries to fragmented multi-supplier bottle and pouch sourcing networks.
- Bulk:Tanker and flexitank shipments serving refineries and large-scale food manufacturers with dedicated storage infrastructure at Red Sea and West African port facilities.
- Pouches:Flexible laminate packaging dominating household replenishment in North African and Levant markets with cost-efficient unit economics for price-sensitive consumers.
- Bottles:PET and glass containers for retail premium positioning, with label real estate supporting health claims and origin storytelling in Gulf modern trade.
- Cans:Metal packaging for food service and industrial segments requiring light protection and stackability in high-temperature storage environments.
Bulk shipments anchor throughput economics while pouch formats expand most quickly through modern trade penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers and hospitality chains across the Middle-East and Africa drive procurement concentration, with national quick-service restaurant groups and packaged goods producers commanding annual framework contracts that displace spot-market purchasing.
Saudi Arabia
Retail and hospitality sectors absorb refined oil volumes beyond domestic crushing capacity, forcing reliance on Red Sea import corridors. The Saudi Food and Drug Authority enforces maximum aflatoxin limits that filter unregistered suppliers from formal distribution channels. Riyadh and Jeddah host the largest food service procurement clusters where national quick-service restaurant chains consolidate buying power through integrated supply contracts.
Egypt
Packaged goods manufacturers expand refined oil offtake for frying and shortening formulations in snack and bakery production lines. Food subsidy reforms redirect public procurement patterns toward private crush capacity investments ahead of program implementation. Cairo and Alexandria industrial zones concentrate the largest food processing clusters where just-in-time oil delivery requirements favor suppliers with dedicated storage infrastructure.
Nigeria
Palm oil development programs redirect procurement patterns toward domestic crushing investments as food processing industries expand consumption of refined oils. The country's national food safety regulator enforces labeling standards that reshape import compliance requirements for regional traders. Lagos and Port Harcourt anchor West African port facilities where integrated traders manage throughput economics for bulk shipments serving regional refineries.
South Africa
Urban consumers drive demand for sunflower oil through health-positioned purchasing in formal retail channels, prioritizing monounsaturated fat profiles. The Department of Health enforces maximum aflatoxin limits that filter out unregistered suppliers from formal distribution. Johannesburg and Cape Town metropolitan areas concentrate modern trade penetration where supermarket chains control shelf access and private label development for mid-tier positioning.
UAE
Gulf Standards Organization harmonization reduces technical barriers for distributors scaling cross-border refined oil flows without redundant testing protocols. The Ministry of Health and Prevention enforces food safety standards that consolidate technical requirements across multi-territory distribution. Dubai and Abu Dhabi serve as logistics hubs where crush facilities and integrated traders contract directly with hospitality groups, displacing traditional broker intermediation.
Middle-East and Africa Vegetable Oil Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement consolidation and crush capacity positioning. The vendor base fragments between integrated traders managing Red Sea logistics networks and regional refineries competing on refined output for domestic consumption. Three archetypes dominate: multinational agricultural traders with global supply chain reach, regional crush specialists with port-adjacent facilities, and Gulf-based distributors leveraging harmonized compliance documentation. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure offtake certainty ahead of subsidy reform implementation.
Among multinational agricultural traders, Cargill Incorporated and Archer Daniels Midland Co. exemplify the integrated supply chain archetype with global origination networks. Wilmar International Limited anchors the regional crush specialist tier with port facility positioning. ADVOC occupies a position within the Gulf-based distributor segment, leveraging Abu Dhabi logistics infrastructure for UAE domestic consumption. These three companies represent the strategic positioning spectrum from global supply chain control to regional processing concentration to distribution-focused market access.
| Leading Market Players |
|---|
| Sime Darby Plantation Berhad |
| Amira Nature Foods Ltd |
| Cargill Incorporated |
| Savola Group |
| Archer Daniels Midland Co. |
| ADVOC (ABU DHABI VEGETABLE OIL COMPANY) |
| Omani Vegetable Oils & Derivatives Co.(L.L.C) |
| IFFCO Group |
| Wilmar International Limited |
| Others |
Supply & Pricing Matrix
Port Harcourt's bulk terminal infrastructure anchors West African throughput economics, where integrated traders leverage storage capacity to arbitrage freight volatility against Egyptian and Saudi food manufacturers facing just-in-time delivery requirements. This geographic concentration grants handlers pricing power over downstream refiners lacking dedicated Red Sea port access.
Pricing Analysis
Cost-plus contracts indexed to Malaysian palm oil futures dominate procurement between integrated traders and Nigerian snack manufacturers, with freight differentials and aflatoxin certification tiers driving price spreads. Three-tier pricing structure across premium, standard, and economy levels separates high-oleic sunflower oil for Moroccan retail from commodity palm olein for food service. Pricing pressure stems from Saudi domestic crushing underinvestment forcing reliance on volatile import corridors. Food processing buyers exhibit highest price sensitivity due to continuous production line economics, while personal care formulators accept specification premiums for tight peroxide value grades.
Supply Chain Analysis
Export-control regimes on solvent extraction technology limit North African refinery upgrades, compressing margins against Malaysian and Indonesian palm oil imports that flow unencumbered through Gulf Cooperation Council harmonized standards. Supply concentrates in Indonesia, Malaysia, and Uganda for palm and sunflower seed feedstocks. Raw material dependencies include crude palm oil, sunflower seed, and soybean meal for protein extraction. Single-source vulnerability runs through the Strait of Malacca chokepoint for Asian-origin supply. Distribution runs through integrated traders managing Red Sea logistics networks, with direct sales to national quick-service restaurant chains displacing traditional commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
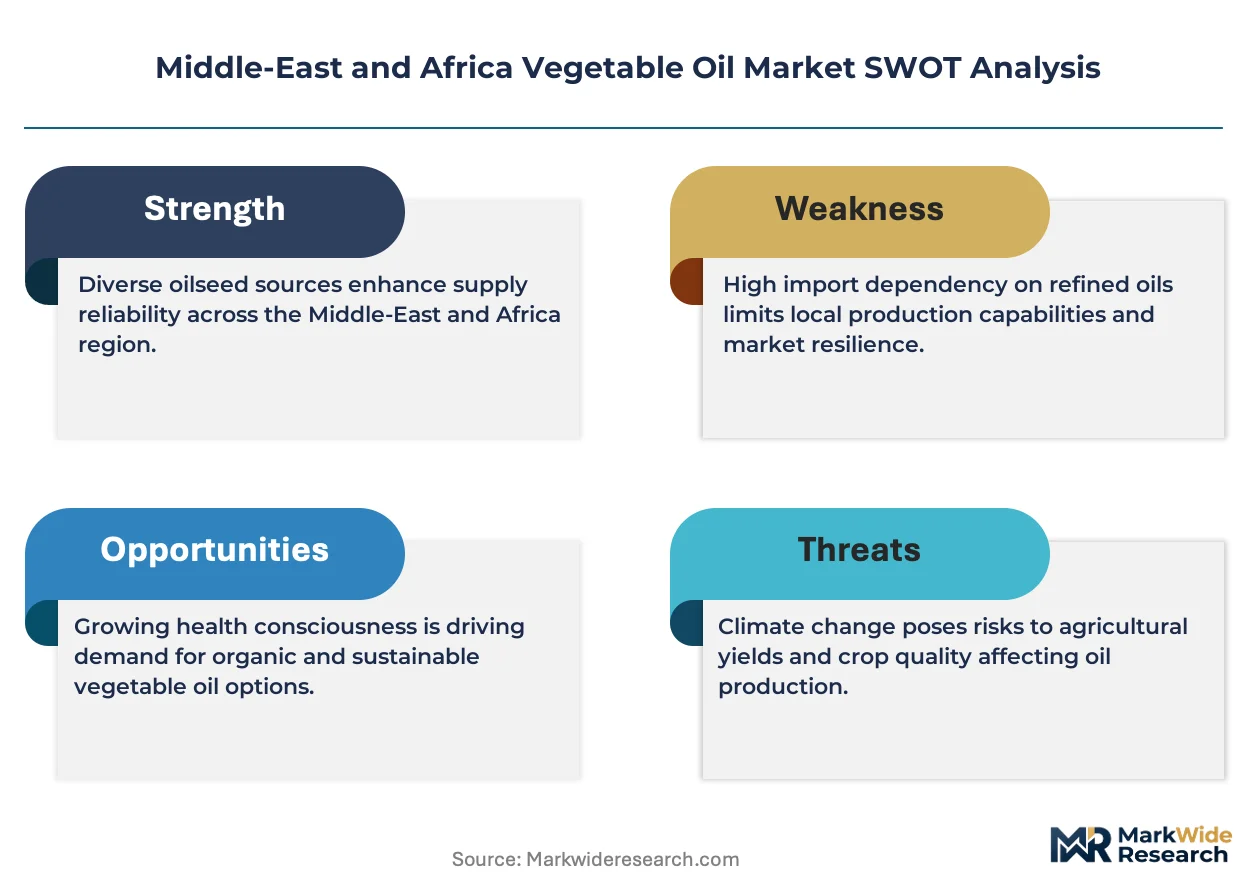
Gulf Standards Organization harmonization is disrupting import compliance documentation, compressing lead times for multi-territory distribution and favoring crush facilities with pre-positioned certification investments.
For Market Incumbents: Insulate margin position by securing backward integration into Ugandan and Tanzanian sunflower seed origination ahead of EAC customs union rule changes. Expand deodorization capacity at Egyptian port facilities to capture food processing demand from Cairo and Alexandria industrial clusters. Certification investment in Gulf Standards Organization compliance documentation creates switching costs against unregistered suppliers filtered by Saudi Food and Drug Authority aflatoxin limits.
For New Entrants and Emerging Players: Pursue white-space positioning in South African biodiesel feedstock supply, where renewable fuel policy creates structural demand certainty absent from food service channels. Target Moroccan retail premiumization for high-oleic sunflower oil with monounsaturated fat profile positioning. Go-to-market leverage rests on direct contracting with national hospitality chains consolidating procurement through integrated supply agreements.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because Red Sea port-adjacent crush capacity commands scarcity rents as Saudi consumption outpaces domestic supply. Acquisition targets include regional refineries with Gulf Standards Organization pre-certification and Egyptian private crush capacity positioned ahead of subsidy reform implementation. Watch Egyptian food subsidy restructuring timelines as inflection signal for procurement pattern redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Origination | Ugandan and Tanzanian sunflower seed sourcing secures feedstock against EAC customs fragmentation. |
| Port-Adjacent Capacity Expansion | Red Sea crush facilities capture Saudi demand exceeding domestic crushing capability. |
| Gulf Standards Organization Certification Investment | Harmonized documentation reduces redundant testing for UAE, Kuwait, and Omani distribution. |
| Direct Sales to Hospitality Chains | National quick-service restaurant procurement consolidation displaces traditional broker intermediation. |
| Biodiesel Feedstock Pivot | South African renewable fuel policy and Nigerian blending mandates create industrial offtake certainty. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with crush facility operations managers, food processing procurement leads at Egyptian and Saudi packaged goods manufacturers, Gulf-based integrated traders, and South African biodiesel refinery planners; alongside secondary validation through customs and trade flow databases, Saudi Food and Drug Authority regulatory filings, Gulf Standards Organization harmonization protocols, and EAC and COMESA tariff schedule documentation. Bottom-up volume triangulation from crush capacity utilization rates and top-down demand validation from food service procurement consolidation patterns were cross-referenced for convergence.
Forecast inputs span palm oil, sunflower oil, soybean oil, and olive oil product categories; food processing, industrial use, household, and personal care end-user segments; and wholesale, retail, direct sales, and online distribution channels across the analysis window. CAGRs were derived from elasticity-adjusted consumption growth trajectories incorporating Egyptian subsidy reform timing and Nigerian palm oil development program implementation. Industry-specific inputs include Red Sea freight volatility indices and aflatoxin compliance cost burdens.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Malaysian and Indonesian state-linked plantation groups to acquire Red Sea port capacity would shift outcomes. Material shifts in Gulf Cooperation Council food safety harmonization implementation schedules or Egyptian food subsidy reform acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Cocoa Ingredients Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Chewing Gum Base Market
Ingredients
Protein Ingredients Market
Ingredients
Asparagus Extract Market
Ingredients
Low Fat Oil Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Potato Protein Market
Ingredients
North America Phytosterols Market
Ingredients
Waxy Maize Starch Market
Ingredients
China Corn Glucose Market
Ingredients
Phytogenic Market
Ingredients
North America Brewing Enzymes Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Bulk Food Ingredients Market