
 Coconut Flour Market | 2026-2036
Coconut Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Flour Market Analysis
Organic certification tiers are rotating toward the center of supplier strategy as buyers demand traceable sourcing. Nutiva Inc. leverages its established organic supply chain to secure premium shelf placement in North American retail channels. Celebes Coconut Corporation anchors its position through integrated Philippine milling operations that control raw coconut quality from copra through finished flour. Bob's Red Mill Natural Foods differentiates via its employee-owned brand architecture and dedicated gluten-free production facilities.
Coconut flour is a defatted, finely milled powder derived from dried coconut meat after virgin oil extraction, typically containing 60-70% dietary fiber and 8-15% protein by dry weight. Its high water-binding capacity and low carbohydrate profile make it functional in reduced-sugar and grain-free formulations across commercial baking and nutritional supplement manufacturing. Organic coconut flour commands the strongest margin pool as certification costs create barriers for commodity suppliers, while gluten-free coconut flour segments expand fastest through co-manufacturer partnerships with mainstream CPG brands. Application demand in baking and nutritional supplements concentrates among food manufacturers seeking clean-label ingredient declarations.
FDA gluten-free labeling rules and EFSA nutrition and health claims regulations enforce strict compositional thresholds that reshape product development cycles for coconut flour suppliers. USDA organic standards and EU organic certification requirements further segment market access based on farm-level documentation and third-party audit compliance. Stakeholders must monitor evolving allergen threshold science and pending updates to Codex Alimentarius gluten-free standards that could recalibrate competitive positioning across certified and conventional product tiers.
Market Dynamics
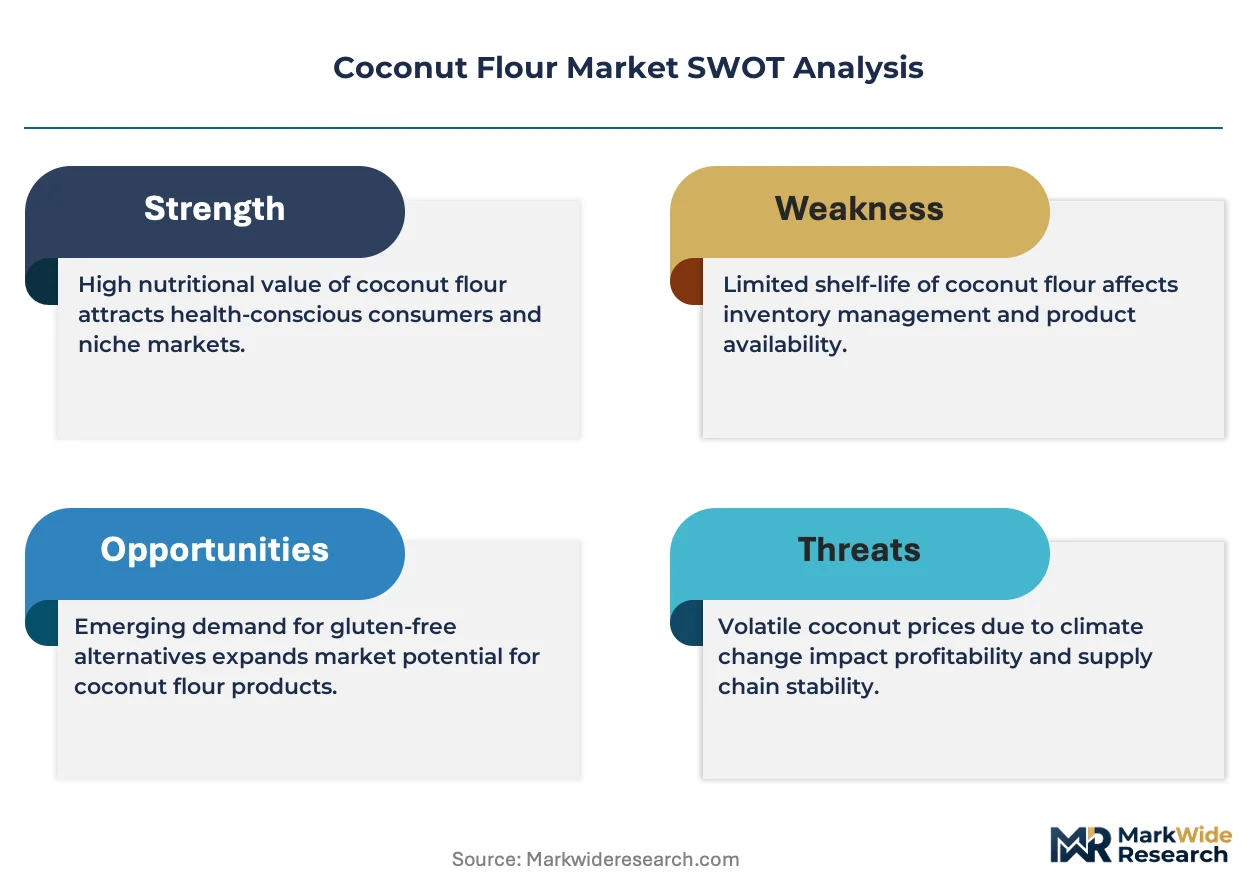
Clean-label certification requirements are compressing supplier margins while simultaneously locking in premium pricing tiers for verified organic and allergen-free coconut flour batches.
Growth Catalysts
- Gluten-free labeling mandates:FDA enforcement of 20 ppm gluten thresholds drives reformulation demand across commercial bakeries seeking compliant alternative flours.
- Philippines copra quality premiums:Integrated milling operations in Mindanao and Quezon provinces secure superior raw material access for defatted flour production.
- Low-carbohydrate diet protocols:Ketogenic and paleo nutrition frameworks accelerate coconut flour adoption in specialty packaged goods manufacturing.
Market Restraints
- Copra price volatility:Weather-driven coconut harvest fluctuations in Indonesia and Philippines transmit directly to input cost instability.
- Defatting capacity concentration:Virgin coconut oil extraction infrastructure clusters in Southeast Asian coastal zones, creating geographic supply bottlenecks.
- Almond flour substitution:Established gluten-free baking supply chains favor almond-based formulations with longer track records in consumer acceptance testing.
Strategic Opportunities
- EU organic certification expansion:EFSA-aligned farm-to-fork traceability protocols enable premium shelf access across German and French retail channels.
- Plant-based protein fortification:Sports nutrition manufacturers blend coconut flour with pea and rice proteins for clean-label powder formulations.
- Direct-to-bakery distribution:Bypassing traditional ingredient distributors, suppliers establish captive supply relationships with regional artisan bread cooperatives.
Industry Challenges
- Organic certification timeline compression:USDA three-year transition periods strain working capital for conventional coconut processors seeking premium tier access.
- Moisture control expertise scarcity:High-fiber flour stabilization requires specialized drying engineering talent concentrated in tropical food processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Flour Market |
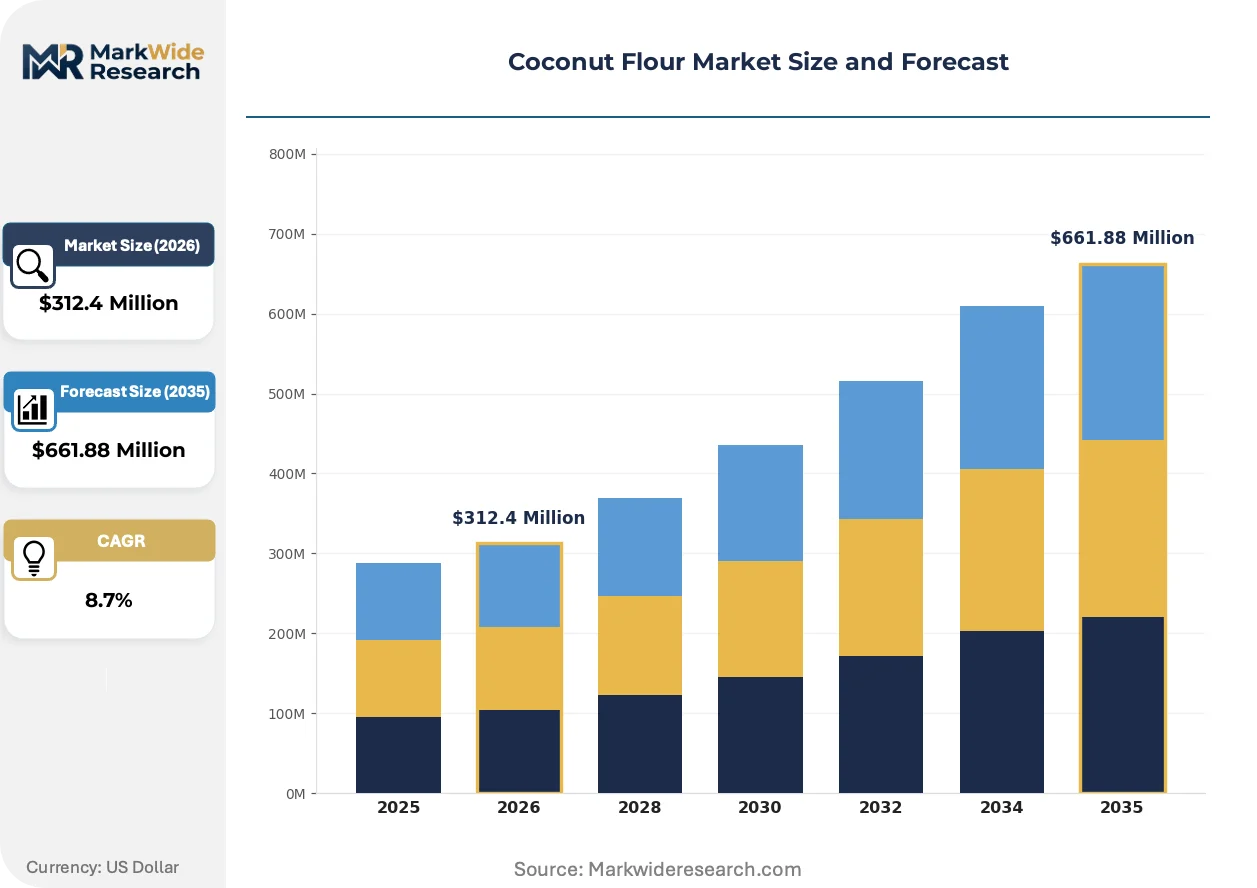
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Coconut Flour, Conventional Coconut Flour, Gluten-Free Coconut Flour, High-Fiber Coconut Flour Application: Baking, Food Coating, Thickening Agent, Nutritional Supplements Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Households, Food Manufacturers, Restaurants, Bakeries |
| Companies Covered | The Coconut Company, Groovy Food Company Ltd, Bob's Red Mill Natural Foods, Primex Coco Products, Connecticut Coconut Company, Nutiva Inc., Anthony's Goods, Dr. Goerg GmbH & Co. KG, Celebes Coconut Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Flour Market Emerging Trajectories
Processing technology convergence with precision agriculture is redefining quality assurance protocols from plantation through finished flour packaging.
Low-temperature vacuum drying is supplanting conventional hot-air dehydration in premium coconut flour production. Specialty organic brands adopt this method to preserve heat-sensitive micronutrients and volatile aromatic compounds. The shift is compressing commodity-grade pricing power while enabling 40-60% moisture retention control that conventional lines cannot match.
EU organic regulation 2018/848 implementation tightens farm-level documentation requirements for imported coconut products. Third-country suppliers must demonstrate equivalent compliance to EU organic standards through accredited body certification. Philippine and Indonesian exporters are restructuring cooperative audit systems to maintain continental market access.
Ingredient specification sheets now dominate bakery procurement decisions, displacing traditional broker-mediated sample-based purchasing. Large commercial bakers mandate batch-level allergen testing documentation and origin traceability before contract execution. This pattern concentrates buying power among North American and Western European food manufacturers with dedicated supplier quality teams.
Coconut Flour Market Segmentation
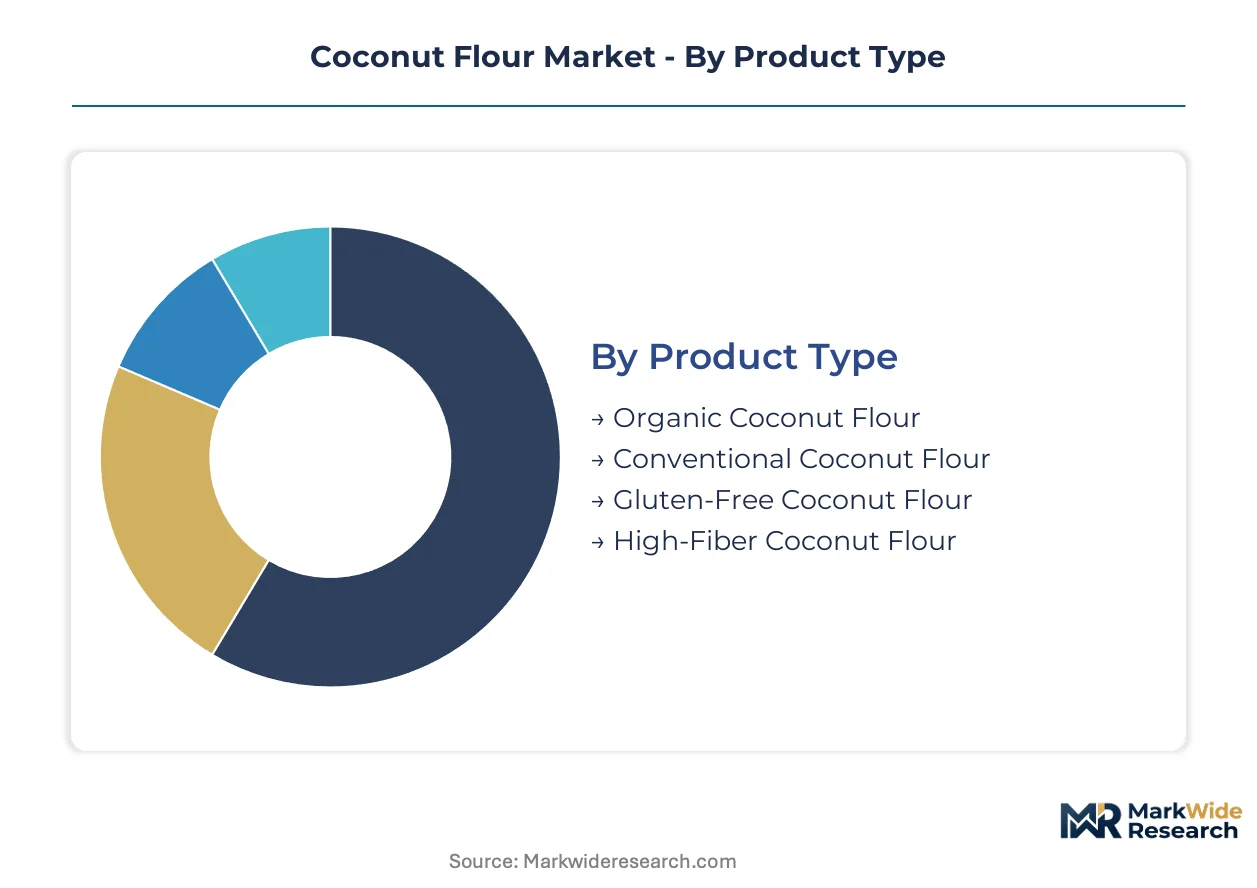
Coconut flour segmentation reflects divergent certification economics and functional specialization. Product tiers command distinct margin structures based on farm-level documentation burden and end-use compliance requirements.
Product Type:
Substitution pressure from almond and cassava flours hits conventional grades hardest, while certified organic and allergen-free segments defend position through regulatory moats.
- Organic Coconut Flour:USDA and EU organic certification requires three-year farm transition periods and third-party audit trails. Premium shelf placement in German and French retail channels depends on EFSA-aligned traceability documentation. Input cost premiums of 30-40% above conventional grades compress working capital for processors.
- Gluten-Free Coconut Flour:FDA 20 ppm threshold compliance and dedicated production facility requirements create supply scarcity. Commercial bakeries in the United States mandate batch-level allergen testing before contract execution. Co-manufacturer partnerships with mainstream CPG brands accelerate volume uptake.
- Conventional Coconut Flour:Commodity-grade production concentrates in Philippine and Indonesian coastal mills with established defatting infrastructure.
- High-Fiber Coconut Flour:60-70% dietary fiber content targets ketogenic and paleo nutrition formulations with specific macronutrient labeling claims.
Conventional coconut flour retains volume leadership; gluten-free coconut flour holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity ingredient sales from premium functional positioning across end-use categories.
- Baking:Water-binding capacity and low carbohydrate profile enable reduced-sugar and grain-free formulations. Artisan bread cooperatives in the United States establish direct supplier relationships bypassing traditional distributors. Clean-label declarations drive procurement decisions at commercial bakery operations.
- Nutritional Supplements:Sports nutrition manufacturers blend with pea and rice proteins for plant-based powder formulations. Precision drying technology preserves heat-sensitive micronutrients for premium positioning. Batch-level specification sheets dominate procurement protocols.
- Food Coating:Defatted particle structure provides adhesion properties for battered and breaded product applications.
- Thickening Agent:High fiber content delivers viscosity control in sauces and gravies without grain-based starch alternatives.
Baking commands absolute volume; nutritional supplements are expanding most quickly through protein fortification demand.
Distribution Channel:
Customer type fragmentation separates institutional procurement teams from individual purchase behavior across channel structures.
- Online Retail:Direct-to-consumer subscription models capture recurring revenue from ketogenic and paleo diet adherents. Amazon and specialty health platforms dominate North American premium organic sales. Digital shelf placement algorithms favor products with complete certification documentation.
- Supermarkets:Mass-market penetration depends on slotting fee negotiations and private-label program participation. Gluten-free shelf sets in United States chains require dedicated supplier quality teams for compliance verification.
- Health Food Stores:Independent retailers prioritize local and traceable sourcing narratives for consumer education.
- Specialty Stores:Ethnic grocery channels in Filipino and Southeast Asian communities sustain demand for conventional grades.
Supermarkets retain volume leadership; online retail climbs the fastest through subscription model adoption.
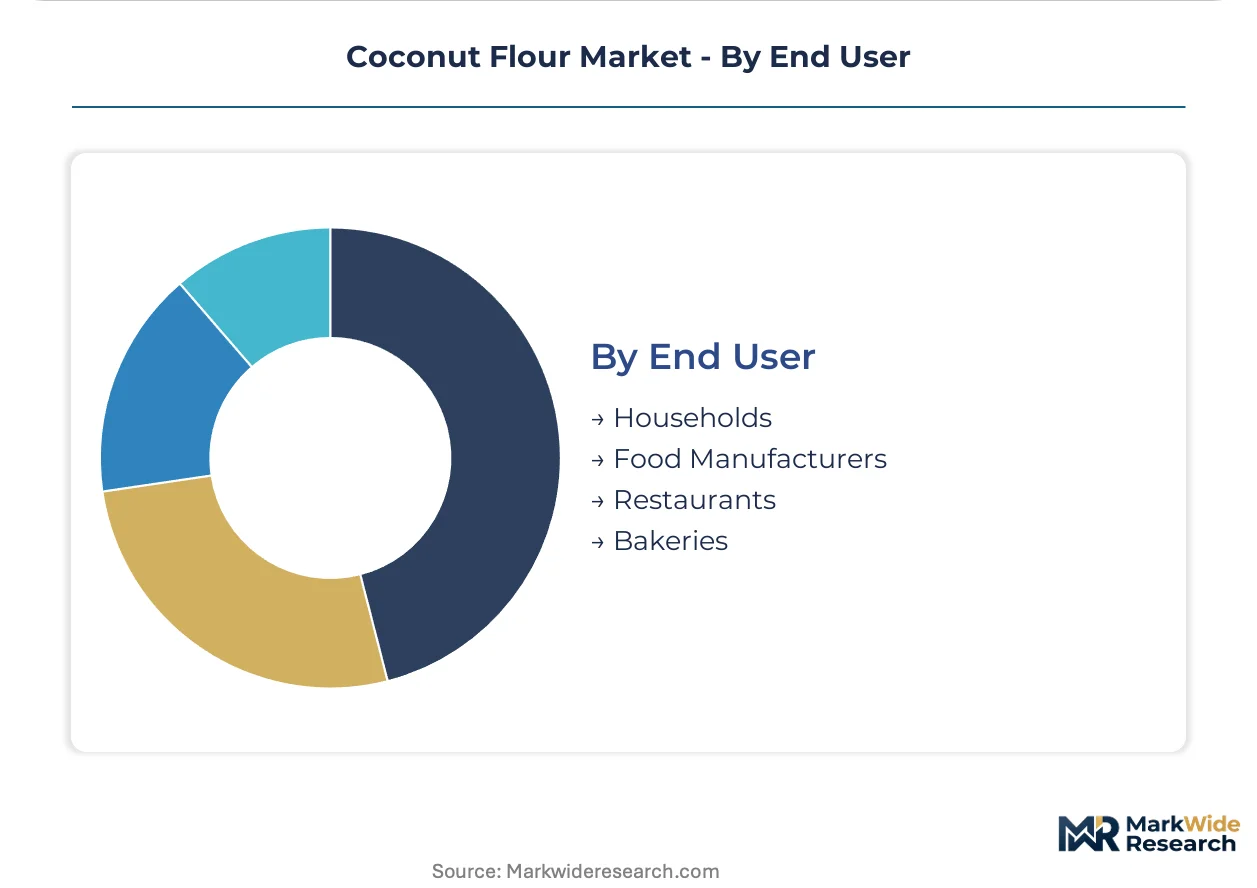
End User:
Supply concentration among Southeast Asian milling clusters shapes service level differentiation across buyer types.
- Food Manufacturers:Large-scale procurement mandates origin traceability and batch-level allergen documentation before contract execution. Ingredient specification sheets displace broker-mediated sample-based purchasing. Dedicated supplier quality teams concentrate in North American operations.
- Bakeries:Regional artisan cooperatives establish captive supply relationships with direct mill connections. Moisture control expertise scarcity limits supplier options for high-fiber flour stabilization.
- Households:Recipe bloggers and social media influencers drive trial adoption through grain-free baking content.
- Restaurants:Menu innovation teams experiment with coconut flour in gluten-free and low-carbohydrate dish development.
Food manufacturers retain volume leadership; bakeries gain share fastest through direct sourcing relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defatting infrastructure clusters along Southeast Asian coastlines concentrate raw material conversion capacity, while North American and European markets absorb premium-certified output through specialized distribution channels. FDA and EFSA compliance requirements reshape import flows toward documented supply chains.
Philippines
Mindanao and Quezon provinces host integrated milling operations controlling copra quality from harvest through finished flour. The Philippine Coconut Authority enforces quality standards for export-grade defatted products. Davao City anchors the national coconut processing corridor where virgin oil extraction facilities supply feedstock to specialty flour manufacturers.
United States
Commercial bakeries in California and Texas drive bulk procurement of gluten-free certified batches for reformulated product lines. FDA 20 ppm gluten threshold enforcement mandates dedicated facility documentation before contract execution. Chicago and Los Angeles distribution hubs consolidate inbound Southeast Asian container volumes for redistribution to regional baking operations.
Germany
EFSA-aligned organic certification requirements filter import access toward traceable Philippine and Indonesian suppliers. The EU organic regulation 2018/848 implementation tightens farm-level documentation for third-country exporters. Hamburg port facilities handle the largest European coconut product import volumes with dedicated organic commodity segregation infrastructure.
Indonesia
Sulawesi and North Sumatra copra harvest fluctuations transmit price volatility through global supply chains. The national standards body enforces food safety protocols for export-oriented defatting operations. Surabaya processing zones concentrate virgin coconut oil extraction capacity that feeds regional flour milling downstream.
France
Paris and Lyon retail channels command premium shelf placement for EFSA-compliant organic coconut flour with complete farm-to-fork traceability. ANSM monitors health claim compliance for nutritional supplement applications containing coconut-derived ingredients. The French organic market prioritizes Philippine cooperative suppliers with EU-equivalent certification documentation.
Coconut Flour Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Southeast Asian integrated processors dominate cost-efficient commodity-grade production through captive copra supply and coastal defatting infrastructure. North American and European branded suppliers capture premium tiers through organic certification and dedicated gluten-free facility investments. Two strategic moves define current positioning: backward integration into plantation-level sourcing by Asian processors, and direct-to-bakery distribution bypass by specialty brands seeking margin capture.
Among Philippine integrated processors, Celebes Coconut Corporation exemplifies the vertically controlled supply chain archetype with milling operations spanning copra through finished flour. Nutiva Inc. and Bob's Red Mill Natural Foods occupy differentiated positions in North American premium distribution, with the former leveraging established organic supply chains and the latter deploying employee-owned brand architecture. Dr. Goerg GmbH & Co. KG represents European market access specialization through EFSA-aligned certification protocols.
| Leading Market Players |
|---|
| The Coconut Company |
| Groovy Food Company Ltd |
| Bob's Red Mill Natural Foods |
| Primex Coco Products |
| Connecticut Coconut Company |
| Nutiva Inc. |
| Anthony's Goods |
| Dr. Goerg GmbH & Co. KG |
| Celebes Coconut Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day container lead times from Philippine and Indonesian mills to North American distribution hubs concentrate pricing power among integrated processors with captive copra supply. FDA gluten-free certification requirements and EU organic regulation 2018/848 compliance costs create tiered margin structures that commodity suppliers cannot match.
Pricing Analysis
USDA organic standards and EFSA nutrition claims regulations dictate the pricing tier structure across coconut flour grades. Three-tier pricing separates certified organic batches from gluten-free verified lots from conventional commodity grades. Price differentiation rests on farm-level documentation burden and dedicated facility investments. Cost compression in conventional segments is intensifying because almond flour substitution erodes volume leverage. Commercial bakeries in the United States show highest price sensitivity; sports nutrition manufacturers demonstrate lowest sensitivity due to premium positioning requirements.
Supply Chain Analysis
Strategic stockpiling of copra feedstock dominates procurement behavior among Philippine integrated processors facing monsoon harvest volatility. Geographic supply concentrates in the Philippines, Indonesia, and Sri Lanka. Raw material dependencies center on virgin coconut oil extraction residue, tropical copra harvests, and defatting infrastructure capacity. Single-source vulnerability runs through Mindanao and Quezon province milling clusters concentrated in coastal zones. Distribution runs through Hamburg and Los Angeles port consolidation hubs serving regional bakery and supplement manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coconut flour demand tracks cyclical recovery patterns in specialty diet adoption, with ketogenic and paleo nutrition frameworks driving reformulation waves across commercial baking operations.
For Market Incumbents: Compound certification moats by accelerating EU organic regulation 2018/848 compliance documentation and securing dedicated gluten-free facility investments before FDA enforcement tightens. Almond flour substitution in mainstream gluten-free baking supply chains threatens volume growth; backward integration into Mindanao copra sourcing locks in raw material quality premiums.
For New Entrants and Emerging Players: Anchor in direct-to-bakery distribution bypassing traditional ingredient brokers, targeting regional artisan bread cooperatives in California and Texas with moisture-controlled high-fiber flour specifications. White-space opportunity concentrates in sports nutrition protein fortification blends; co-manufacturer partnerships with established CPG brands offer fastest volume ramp.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because regulatory compliance costs compound barriers for commodity entrants. Acquisition targets should display integrated Philippine milling operations with EU-equivalent organic audit trails. The signal to watch is Codex Alimentarius gluten-free standard revisions that could recalibrate competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Organic Certification Expansion | EFSA-aligned farm-to-fork traceability unlocks German and French retail shelf access. |
| Direct-to-Bakery Distribution | Bypassing traditional brokers captures margin from regional artisan bread cooperatives. |
| Low-Temperature Vacuum Drying Investment | Preserving heat-sensitive micronutrients enables 40-60% moisture retention control. |
| Plant-Based Protein Fortification Partnerships | Blending with pea and rice proteins opens sports nutrition powder formulations. |
| Backward Integration into Copra Sourcing | Mindanao plantation control secures superior raw material quality premiums. |
Methodological Framework
Initial hypotheses were tested against primary input from commercial bakery procurement managers, sports nutrition product development leads, Philippine coconut mill operations directors, and EU organic certification auditors and refined through secondary validation. Primary fieldwork drew from FDA gluten-free labeling guidance documents, USDA organic standards filings, EFSA nutrition claims registers, and Philippine Coconut Authority export statistics. Bottom-up volume modeling triangulated against top-down category spending analysis.
Variance decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions included certification grade, application category, distribution channel type, and end-user procurement scale. CAGRs were derived from fitted growth curves applied to normalized baseline observations. Industry-specific forecast inputs incorporated copra harvest yield variability and organic farm transition timeline constraints.
Decision-makers should treat outputs as directional under stable FDA enforcement intensity and EFSA organic equivalence recognition; material deviation would warrant model refresh. Revision becomes warranted when Codex Alimentarius gluten-free threshold proposals advance to final standard status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Halal Ingredients Market
Ingredients
North America Protein Ingredients Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Oat Grass Powder Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Global Malt Ingredients Market
Ingredients
Boysenberry Extract Market
Ingredients
North America Phytosterols Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Corn Steep Liquor Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Bean Ingredients Market
Ingredients
Plant Extracts Market
Ingredients
Bleached Flour Market
Ingredients
Codonopsis Extract Market