
 Middle East and Africa Yerba Mate Market | 2026-2036
Middle East and Africa Yerba Mate Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Yerba Mate Market Foresight
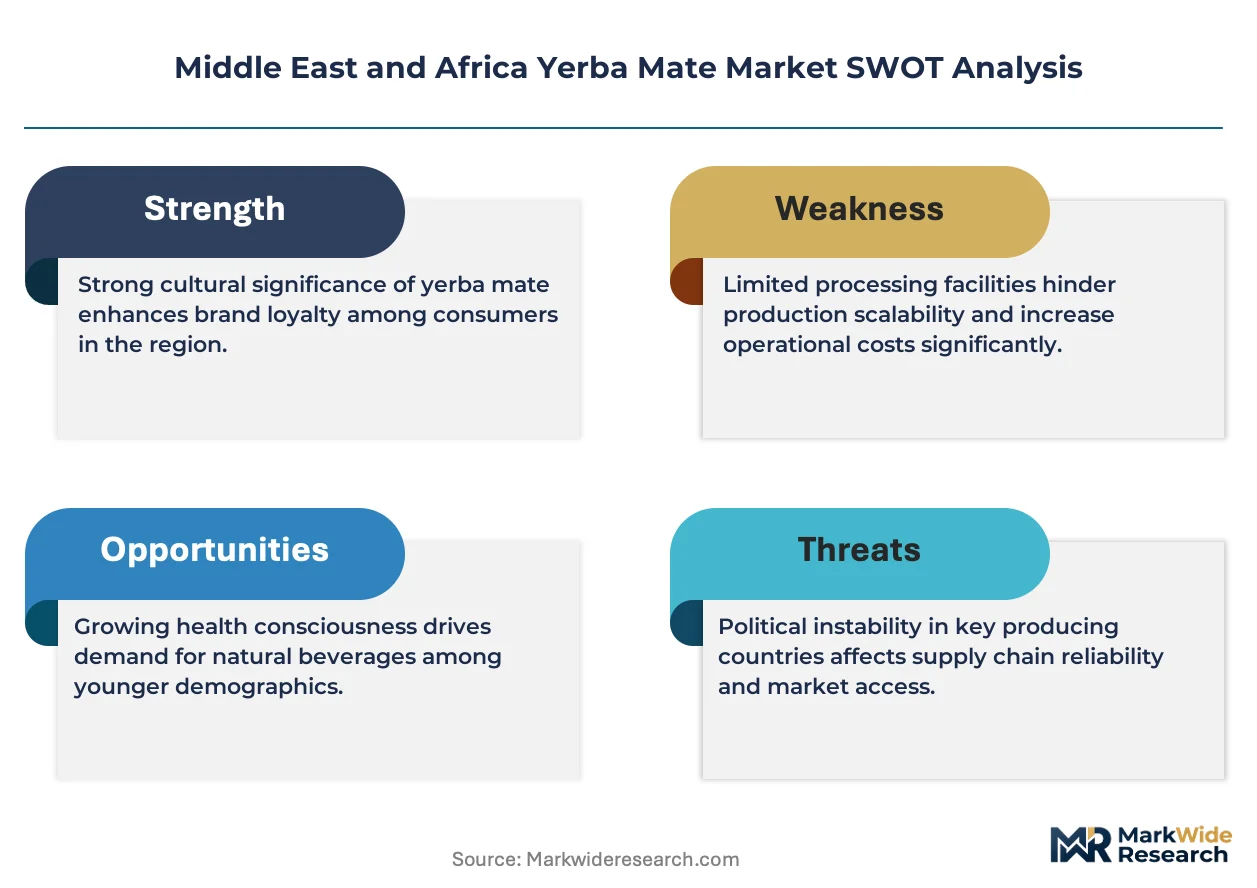
Asset-light importing and third-party logistics leasing is fragmenting competitive entry barriers across the Middle East and Africa Yerba Mate Market. Rosamonte leverages established South American supply relationships to secure consistent container volumes into Gulf ports. Taragüi anchors premium positioning through controlled distribution in specialty retail channels. Las Marías S.A. competes via vertical integration from Argentine cultivation through export-grade processing.
Yerba mate comprises dried leaves and twigs of Ilex paraguariensis, typically containing 1-2% caffeine by dry weight and processed through fire-drying or air-drying methods to produce a bitter, stimulating infusion consumed hot or cold. Traditional and organic product types command margin concentration due to authenticity signaling and clean-label positioning among wellness consumers. Instant formats occupy faster-growing niche demand from convenience-oriented urban households and foodservice operations seeking reduced preparation protocols.
South Africa's Department of Health, the UAE's Emirates Authority for Standardization and Metrology, and Saudi Arabia's SFDA each enforce distinct labeling, import registration, and food safety verification requirements that shape product formulation and documentation burdens for cross-border suppliers. Compliance complexity favors established exporters with dedicated regulatory affairs capacity over opportunistic traders. Stakeholders must monitor evolving national herbal product classifications and halal certification protocols to sustain market access across jurisdictions with divergent approval timelines.
Market Dynamics
Specialty cafés in Dubai and Cape Town are expanding yerba mate menus as wellness-oriented consumers seek alternatives to conventional caffeinated beverages, fragmenting competitive entry barriers through asset-light importing and third-party logistics leasing across Gulf and Southern African corridors.
Growth Catalysts
- Expatriate Latin American communities:Concentrated demand in the United Arab Emirates creates established consumption bases that normalize yerba mate among adjacent health-conscious local consumers in urban retail corridors.
- SFDA import registration protocols:Saudi Arabia's structured food safety verification requirements, once navigated, confer legitimacy that accelerates shelf placement in modern retail channels.
- Instant format technology:Reduced preparation protocols enable penetration into convenience-oriented urban households and foodservice operations seeking operational efficiency.
Market Restraints
- Argentine supply concentration:Fire-drying and air-drying processing capacity clusters in South American cultivation zones, exposing importers to container logistics volatility and currency fluctuation risk.
- Emirates Authority for Standardization and Metrology labeling requirements:Divergent national herbal product classifications across the Middle East and Africa force redundant documentation burdens and reformulation costs.
- Conventional coffee and tea substitution:Established caffeinated beverage infrastructure in South African and Gulf markets retains consumer habit formation and retail shelf dominance.
Strategic Opportunities
- Halal certification protocols:Proactive alignment with Islamic dietary standards unlocks access to Saudi Arabian and broader GCC consumer segments where religious compliance gates market entry.
- Cold-brew ready-to-drink applications:Premium positioning in UAE specialty retail channels captures younger demographics seeking portable wellness formats distinct from traditional hot infusion preparation.
- South African Department of Health regulatory harmonization:Early compliance with herbal product labeling requirements establishes template documentation transferable to adjacent African markets with similar frameworks.
Industry Challenges
- Regulatory affairs capacity scarcity:Dedicated compliance expertise required to navigate UAE, Saudi Arabia, and South Africa's divergent approval timelines exceeds resource availability among opportunistic traders.
- Organic certification timeline compression:Authenticity signaling through clean-label positioning demands third-party verification processes that lag velocity requirements of fast-moving consumer goods launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Yerba Mate Market |
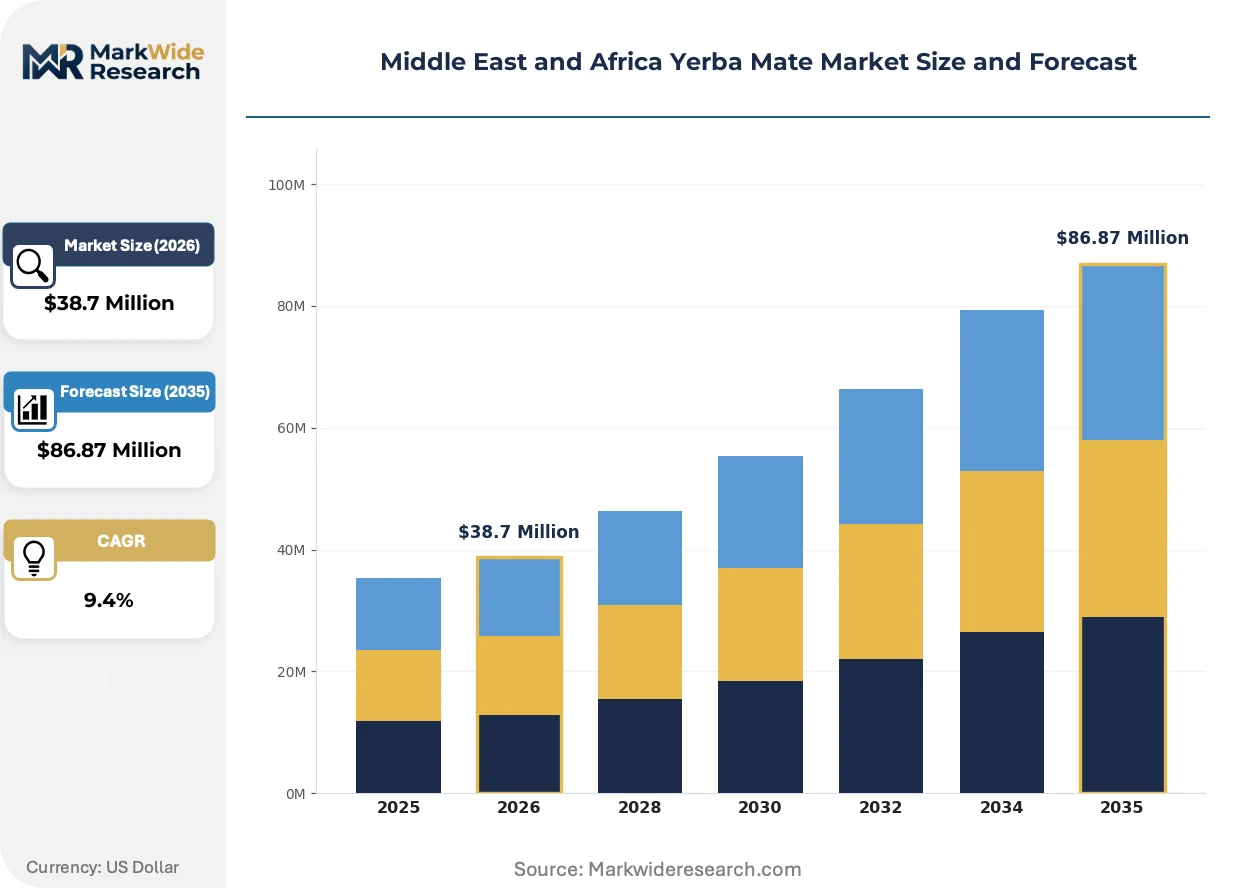
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Flavored, Organic, Instant Packaging Type: Bags, Loose Leaves, Bottles, Tea Pouches End User: Households, Cafés, Restaurants, Retail Outlets Sales Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Rosamonte, Taragüi, Las Marías S.A., Canarias, Cruz de Malta, Amanda Yerba Mate, CBSe, Guayaki Yerba Mate, Selecta, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Yerba Mate Market Shifts & Advancements
Product format innovation and regulatory alignment are actively reshaping competitive positioning in Middle East and Africa yerba mate distribution, compressing traditional preparation barriers while elevating documentation and certification requirements for sustained market access.
Instant yerba mate extract technology is collapsing the preparation time differential between traditional loose-leaf consumption and convenience-oriented beverage formats. Urban foodservice operators in Dubai and Johannesburg are adopting spray-dried and freeze-dried concentrates to reduce labor protocols and equipment footprint. This compression enables penetration into grab-and-go retail channels previously inaccessible to fire-dried leaf products requiring gourd and bombilla preparation infrastructure.
MOHAP herbal product classification frameworks in the United Arab Emirates are tightening import registration and food safety verification requirements for botanical stimulants. Industrial consequence includes mandatory reformulation of packaging claims and submission of toxicological documentation for caffeine-containing botanicals. Specialty retail channels in Dubai are responding by consolidating supplier relationships toward established exporters with dedicated regulatory affairs capacity capable of sustaining multi-jurisdiction compliance.
Wellness-oriented procurement patterns are rotating demand toward authenticity-signaling traditional and organic product types among health-conscious consumers in Cape Town and Abu Dhabi. E-commerce platforms and direct-to-consumer subscription models are displacing conventional import-distributor-retail hierarchies that historically gated product discovery. This channel disintermediation is most visible in the United Arab Emirates, where expatriate community networks accelerate word-of-mouth adoption faster than traditional retail expansion timelines permit.
Middle East and Africa Yerba Mate Market Segmentation
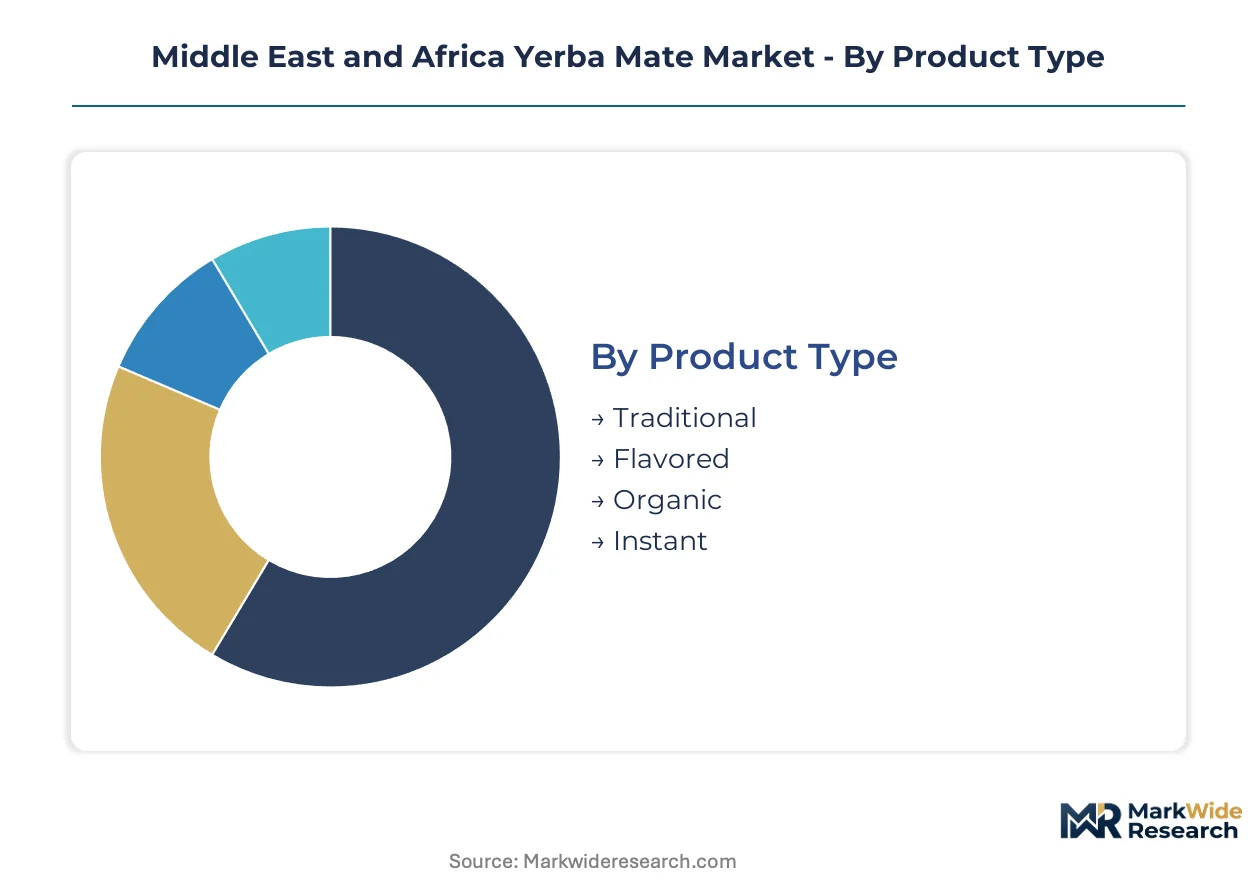
Yerba mate consumption patterns across Middle East and Africa diverge sharply by preparation tradition, regulatory tolerance, and retail infrastructure maturity. Segmentation reveals where Argentine supply chains intersect with Gulf wellness positioning and Southern African herbal product frameworks.
Product Type:
Mature formats rooted in South American heritage coexist with emerging convenience technologies reshaping urban consumption protocols.
- Traditional:Fire-dried or air-dried Ilex paraguariensis leaves and twigs retain 1-2% caffeine content and require gourd-and-bombilla preparation. Expatriate Latin American communities in Dubai and Abu Dhabi sustain demand that normalizes consumption among adjacent health-conscious local consumers.
- Organic:Third-party certified cultivation without synthetic inputs commands premium positioning through clean-label authenticity signaling. MOHAP herbal product classification frameworks in the United Arab Emirates mandate toxicological documentation that favors established exporters with dedicated regulatory affairs capacity.
- Flavored:Blended variants incorporate citrus, mint, or floral notes to soften bitter native taste profiles for novice consumers in Cape Town specialty cafés.
- Instant:Spray-dried and freeze-dried concentrates collapse preparation time differentials for foodservice operators seeking reduced labor protocols.
Traditional handles the majority of throughput; Instant is gaining share fastest among convenience-oriented urban households.
Packaging Type:
Packaging selection tracks preparation infrastructure availability and regulatory labeling burden across divergent national herbal product frameworks.
- Loose Leaves:Bulk dried botanical material in unprocessed form requires dedicated brewing equipment and appeals to heritage-pursuing consumers in Argentine expatriate communities.
- Bags:Pre-portioned filter sachets reduce measurement variability and enable penetration into South African retail outlets with limited staff training capacity.
- Tea Pouches:Single-serve formats align with grab-and-go consumption patterns in Dubai foodservice corridors where labor efficiency gates menu expansion.
- Bottles:Ready-to-drink liquid formulations in cold-brew configurations capture younger demographics seeking portable wellness formats distinct from hot infusion preparation.
Bags handle the majority of throughput; Bottles are expanding most quickly through UAE specialty retail channels.
End User:
Demand concentration varies by preparation expertise requirements and regulatory exposure tolerance across consumer and commercial settings.
- Cafés:Specialty beverage operators in Dubai and Cape Town are expanding yerba mate menus as wellness-oriented consumers seek alternatives to conventional caffeinated beverages, fragmenting competitive entry through asset-light importing.
- Households:Domestic consumption clusters among expatriate Latin American communities in the United Arab Emirates where social network effects accelerate adoption faster than traditional retail expansion timelines.
- Restaurants:Foodservice establishments leverage instant formats to reduce equipment footprint and staff training burdens while capturing wellness-oriented procurement rotations.
- Retail Outlets:Supermarket and specialty store shelf placement requires navigation of SFDA import registration protocols in Saudi Arabia and South Africa's Department of Health labeling requirements.
Cafés handle the majority of throughput; Households are climbing the fastest as e-commerce platforms displace conventional import-distributor hierarchies.
Sales Channel:
Channel selection reflects documentation burden tolerance and speed-to-shelf requirements across divergent regulatory jurisdictions.
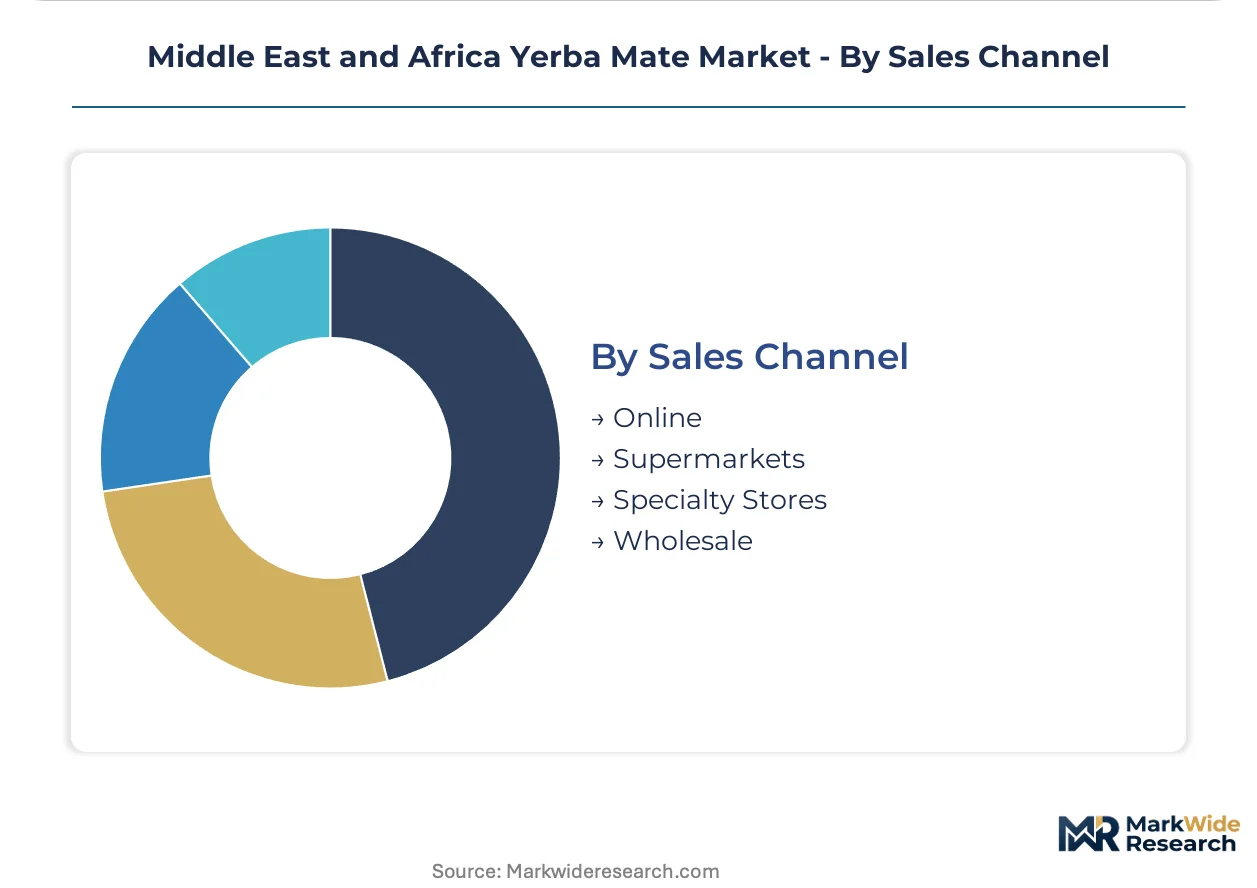
- Specialty Stores:Curated retail environments in Dubai urban corridors consolidate supplier relationships toward established exporters capable of sustaining multi-jurisdiction compliance with Emirates Authority for Standardization and Metrology requirements.
- Online:Direct-to-consumer subscription models and e-commerce platforms disintermediate traditional import hierarchies, accelerating product discovery through expatriate community network effects.
- Supermarkets:Mass retail placement demands halal certification protocols and structured food safety verification that confer legitimacy once navigated.
- Wholesale:Bulk distribution to foodservice and retail intermediaries concentrates in container logistics corridors through Gulf ports with established South American supply relationships.
Specialty Stores handle the majority of throughput; Online is the fastest mover on share through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expatriate Latin American communities and wellness-seeking urban consumers concentrate demand across Gulf and Southern African corridors, with regulatory fragmentation shaping import protocols and shelf placement economics.
United Arab Emirates
Health-conscious local consumers and Argentine expatriate networks overlap in Dubai's urban retail corridors, normalizing yerba mate consumption beyond heritage communities. MOHAP herbal product classification frameworks mandate toxicological documentation and reformulated packaging claims for caffeine-containing botanicals. Specialty cafés across Dubai and Abu Dhabi consolidate supplier relationships toward established exporters capable of sustaining multi-jurisdiction compliance.
Saudi Arabia
Structured food safety verification requirements under SFDA import registration protocols confer retail legitimacy once navigated, accelerating shelf placement in modern trade channels. Halal certification gates market entry for religiously compliant consumer segments across Riyadh and Jeddah. Proactive alignment with Islamic dietary standards unlocks access to broader GCC consumer bases where religious compliance determines procurement eligibility.
South Africa
Wellness-oriented consumers in Cape Town specialty cafés seek alternatives to conventional caffeinated beverages, fragmenting competitive entry through asset-light importing models. The Department of Health labeling requirements for herbal products force redundant documentation burdens and packaging reformulation costs on importers. Early compliance with these frameworks establishes template documentation transferable to adjacent African markets with similar regulatory architectures.
Israel
Specialty beverage operators in Tel Aviv adopt instant format technologies to reduce labor protocols and equipment footprint in grab-and-go retail channels. The national food safety regulator enforces distinct import registration requirements for botanical stimulants that shape product formulation and certification documentation. Urban foodservice corridors concentrate demand among convenience-oriented demographics seeking reduced preparation protocols.
Egypt
Container logistics volatility and currency fluctuation risk expose importers to Argentine supply concentration in fire-drying and air-drying processing zones. The country's national food safety authority maintains evolving herbal product classifications that lag regional harmonization timelines. Cairo-based distributors navigate divergent approval timelines that favor established exporters with dedicated regulatory affairs capacity over opportunistic traders.
Middle East and Africa Yerba Mate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent regulatory jurisdictions, with compliance complexity favoring established exporters over opportunistic traders. The vendor base fragments between heritage Argentine suppliers with cultivation-to-export verticality and agile importers leveraging third-party logistics leasing. Two strategic archetypes dominate: vertically integrated South American producers with captive supply chains, and regulatory-specialist distributors with dedicated affairs capacity across UAE, Saudi Arabia, and South African frameworks. Dominant competitive moves include halal certification acquisition for GCC market access and instant format technology licensing for foodservice penetration.
Among heritage Argentine producers, Rosamonte, Taragüi, and Las Marías S.A. exemplify distinct competitive positioning archetypes. Rosamonte occupies a position anchored in established South American supply relationships securing consistent container volumes into Gulf ports. Taragüi represents premium-tier positioning through controlled distribution in specialty retail channels with regulatory documentation depth. Las Marías S.A. sits within the vertically integrated archetype, with S.A. corporate structure signaling cultivation-through-processing control that supports export-grade certification burdens across multiple jurisdictions.
| Leading Market Players |
|---|
| Rosamonte |
| Taragüi |
| Las Marías S.A. |
| Canarias |
| Cruz de Malta |
| Amanda Yerba Mate |
| CBSe |
| Guayaki Yerba Mate |
| Selecta |
| Others |
Supply & Pricing Matrix
Argentine peso volatility against container freight indexation determines both pricing tier spreads and supply chain shape across Middle East and Africa corridors. Cost-plus contracts indexed to Buenos Aires export parity create margin compression that forces importers toward either premium organic positioning or economy-grade bulk sourcing.
Pricing Analysis
Cost-plus contracts with Argentine suppliers index to weekly container freight rates and harvest-season quality differentials. Pricing stratifies across premium organic tiers with MOHAP toxicological documentation, standard fire-dried heritage grades, and economy bulk lots for foodservice blending. Price erosion runs through standard grades as UAE and Saudi Arabian importers consolidate volume commitments. Household consumers in Dubai exhibit lowest price sensitivity due to expatriate community network effects, while South African retail outlets face acute sensitivity from constrained working capital cycles.
Supply Chain Analysis
Export-control regimes on agricultural biotechnology inputs limit Argentine processing equipment upgrades, constraining fire-drying capacity expansion. Supply concentrates in Argentina's Misiones and Corrientes provinces, with secondary sourcing from southern Brazil's Rio Grande do Sul. Raw material dependencies include diesel for field combustion drying, jute for traditional packaging, and aluminum laminates for retail sachets. Single-source vulnerability from Buenos Aires port concentration exposes importers to grain corridor competition for container allocation. Distribution runs through Dubai's Jebel Ali Free Zone consolidation hubs into Gulf Cooperation Council markets, with Cape Town and Johannesburg serving Southern African spokes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instant format technology represents a high-growth disruption, with spray-dried concentrate patents collapsing preparation barriers that historically gated foodservice penetration across wellness-oriented urban corridors.
For Market Incumbents: Insulate Argentine supply relationships through multi-year offtake agreements denominated in blended currency baskets, neutralizing peso-dollar volatility that erodes contract economics. Deepen backward integration into organic certification pipelines to preempt MOHAP documentation bottlenecks that delay UAE shelf placement. Channel control through Jebel Ali bonded warehousing creates switching costs against opportunistic traders lacking regulatory affairs capacity. For New Entrants and Emerging Players: Cold-brew ready-to-drink white space in UAE specialty retail channels offers the most penetrable entry point, with younger demographics seeking portable formats distinct from gourd preparation heritage. South African Department of Health template documentation, once established, transfers to adjacent African markets with similar herbal product frameworks, enabling geographic optionality without redundant compliance investment. Direct-to-consumer subscription models leveraging expatriate community network effects bypass conventional import-distributor margin stacking. For Investors and Strategic Acquirers: Regulatory-specialist distributors with dedicated affairs capacity across UAE, Saudi Arabia, and South African frameworks present the most defensible acquisition archetype, as compliance complexity permanently disadvantages generalist traders. Long-term viability hinges on halal certification protocol mastery and instant format technology licensing positions. Watch for SFDA import registration timeline compression as signal of Saudi Arabian market access liberalization or restriction.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acquisition | Unlocks Saudi Arabian and broader GCC consumer segments where religious compliance gates procurement eligibility. |
| Instant Format Technology Licensing | Enables penetration into Dubai and Johannesburg foodservice channels seeking reduced labor protocols. |
| Organic Certification Pipeline Investment | Preempts MOHAP toxicological documentation requirements that favor established exporters with verification depth. |
| Jebel Ali Bonded Warehousing | Creates distribution switching costs against opportunistic traders lacking multi-jurisdiction compliance capacity. |
| Direct-to-Consumer Subscription Launch | Disintermediates conventional import-distributor hierarchies through expatriate community network acceleration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs declarations, MOHAP herbal product registration databases, and SFDA import clearance records. Primary interviews engaged yerba mate importers, specialty café operators in Dubai and Cape Town, regulatory affairs consultants, and third-party logistics providers across Gulf and Southern African corridors. Secondary validation drew from Argentine export statistics, Emirates Authority for Standardization and Metrology labeling guidelines, and South African Department of Health herbal product frameworks. Bottom-up volume estimates from channel checks triangulate against top-down trade flow analysis.
Forecast inputs span product type evolution, packaging format substitution rates, and channel disintermediation velocity across the projection horizon. Segmentation dimensions modeled include preparation tradition, certification tier, end-user category, and sales channel structure. CAGRs derive from regression against historical trade volume trajectories, adjusted for regulatory approval timeline variations and expatriate community growth patterns. Industry-specific inputs incorporate instant format technology adoption curves and halal certification penetration thresholds.
Macroeconomic conditions sit as an overlay; deviation in Argentine peso stability, container freight rate volatility, or Gulf Cooperation Council consumer confidence would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and substitution elasticity against conventional coffee and tea. Material shifts in MOHAP herbal product reclassification or SFDA import registration protocol restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Kosher Food Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Super Foods Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Silver Food Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Global Truffle Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Acacia Honey Market