
 Plant Based Thickener Market | 2026-2036
Plant Based Thickener Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Thickener Market Analytics
Direct procurement between ingredient suppliers and food manufacturers is tilting away from traditional distributor networks. Cargill leverages its global agricultural sourcing to secure consistent guar and pectin supply chains. ADM anchors North American production capacity through integrated oilseed processing that yields complementary gum outputs. Tate & Lyle competes in Europe with specialized starch and hydrocolloid formulations tailored to clean-label bakery applications.
Plant based thickeners comprise polysaccharide hydrocolloids extracted from seeds, seaweed, or microbial fermentation, typically achieving viscosities between 1,000 and 10,000 centipoise at low inclusion rates of 0.1% to 1.0% by weight. These substances function primarily to modify rheology, stabilize emulsions, and control moisture migration in processed foods and pharmaceutical suspensions. Xanthan gum dominates industrial volumes due to its pseudoplastic flow behavior and broad pH stability across beverage applications. Pectin captures premium positioning in acid-set dairy and fruit-based systems where gel strength and mouthfeel precision command higher margins. Carrageenan sustains entrenched demand in dairy alternatives despite ongoing clean-label reformulation pressures from European retailers.
REACH in Europe mandates full substance registration and toxicity documentation for hydrocolloid imports, while FDA GRAS self-affirmation governs US market entry without pre-market approval. EFSA evaluations of refined carrageenan safety continue to influence reformulation decisions among contract manufacturers supplying private-label brands. Stakeholders must monitor evolving clean-label definitions across retail banners and align hydrocolloid portfolios with shifting regulatory thresholds for processed food classification.
Market Dynamics
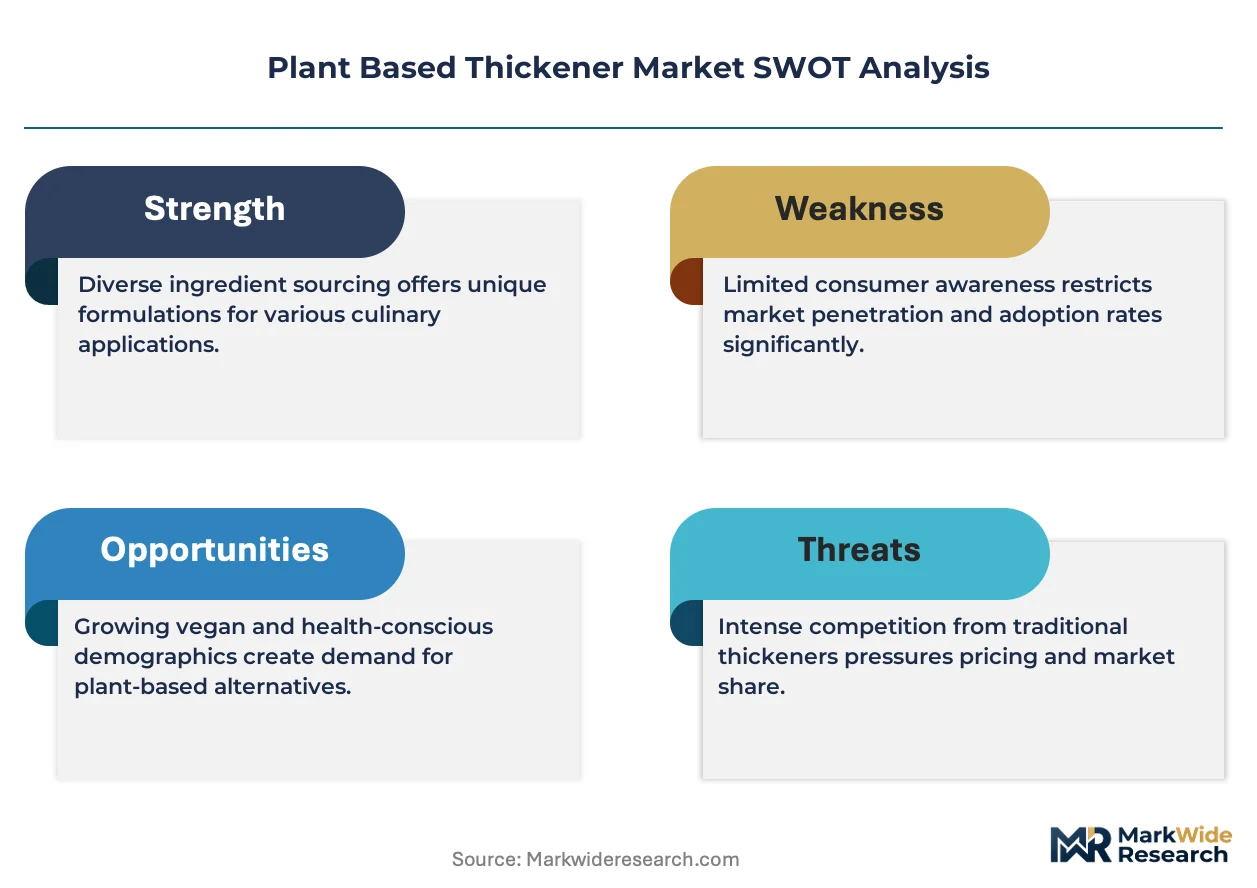
REACH registration requirements are compressing supplier margins while forcing consolidation among European hydrocolloid importers, creating a bifurcation between compliant integrated producers and distributor-dependent formulators.
Growth Catalysts
- Clean-label mandates:EFSA safety evaluations of refined carrageenan push dairy alternative manufacturers toward pectin and guar systems. Reformulation cycles accelerate as private-label brands respond to retailer clean-label thresholds.
- Beverage rheology demands:Pseudoplastic flow requirements in acidified drinks expand xanthan gum volumes. Low-pH stability specifications favor microbial fermentation hydrocolloids over seed-derived alternatives.
- Germany bakery sector:Industrial bakers replace modified starches with native hydrocolloids to meet processed food classification limits. Pectin-starch blends capture premium positioning in fruit-filled applications.
Market Restraints
- Guar seed supply volatility:Monsoon-dependent Indian harvests create 12-18 month price cycles. Gum processors face margin compression when seed costs spike without corresponding formula price adjustments.
- REACH documentation burdens:Full substance registration for novel hydrocolloids requires 2-3 year timelines and six-figure toxicology investments. Small importers exit rather than absorb compliance costs.
- Enzymatic starch thinning:Amylase-treated native starches achieve viscosity targets at lower inclusion rates. Cost-conscious sauce manufacturers substitute modified starches for hydrocolloids in neutral pH systems.
Strategic Opportunities
- Fermentation-derived alternatives:Precision fermentation platforms produce cellulose and curdlan with batch-to-batch consistency. Startups target pharmaceutical suspensions where purity specifications exceed agricultural extraction capabilities.
- Direct supplier-manufacturer contracting:Food manufacturers bypass distributors to secure volume commitments and technical service. Cargill and ADM expand dedicated account teams for mid-sized European processors.
- EU Green Deal alignment:Bio-based content thresholds in public procurement favor seaweed-derived carrageenan and agar. Irish and French coastal processors scale tank cultivation to reduce wild-harvest dependency.
Industry Challenges
- Clean-label definition fragmentation:Retail banners apply divergent processed food thresholds. Formulators maintain multiple ingredient portfolios to satisfy competing retailer specifications.
- Emulsion stabilization complexity:Hydrocolloid-protein interactions in oat milk systems require application-specific optimization. Technical service teams strain to support simultaneous reformulation across dairy alternative SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Thickener Market |
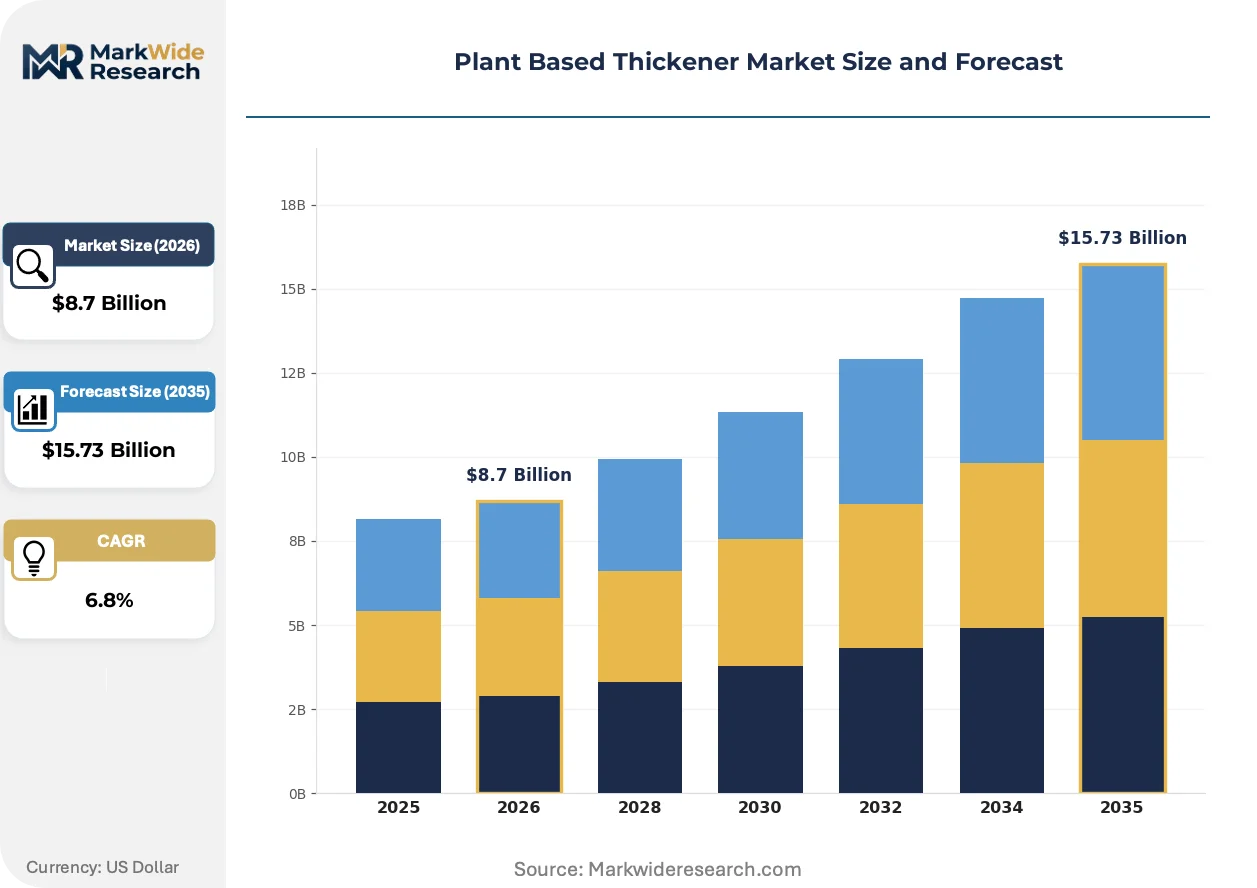
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Xanthan Gum, Guar Gum, Pectin, Carrageenan Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Bakeries, Beverage Companies, Contract Manufacturers Form: Powder, Liquid, Gel, Granules |
| Companies Covered | Cargill, Archer Daniels Midland Company (ADM), DuPont de Nemours, Tate & Lyle PLC, CP Kelco, Kerry Group, Ingredion Incorporated, Roquette Frères, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Thickener Market Evolving Landscape
Digital process control and real-time viscosity monitoring are compressing development cycles for hydrocolloid formulations. Suppliers now embed sensors directly into customer production lines.
Inline rheometry is digitizing quality assurance protocols for beverage manufacturers. Sensor arrays measure pseudoplastic flow curves during batch processing, eliminating offline lab testing delays. Coca-Cola European Partners and similar operators deploy these systems across German filling plants. The technology is digitizing specification compliance, reducing batch release times from hours to minutes.
REACH substance registration deadlines are compressing the supplier base for novel hydrocolloids. ECHA toxicity data requirements favor established players with dedicated regulatory affairs functions. Small importers of emerging seaweed extracts face registration cost barriers. German and French contract manufacturers consolidate supplier lists to reduce compliance audit burdens.
Buyer concentration among European private-label food processors is extending payment terms and demanding technical co-development. Mid-sized hydrocolloid distributors lose share to direct supplier relationships. Aldi and Lidl sourcing teams negotiate multi-year volume contracts with pectin and xanthan gum producers. This procurement restructuring concentrates technical service resources on top-five food manufacturing accounts.
Plant Based Thickener Market Segmentation
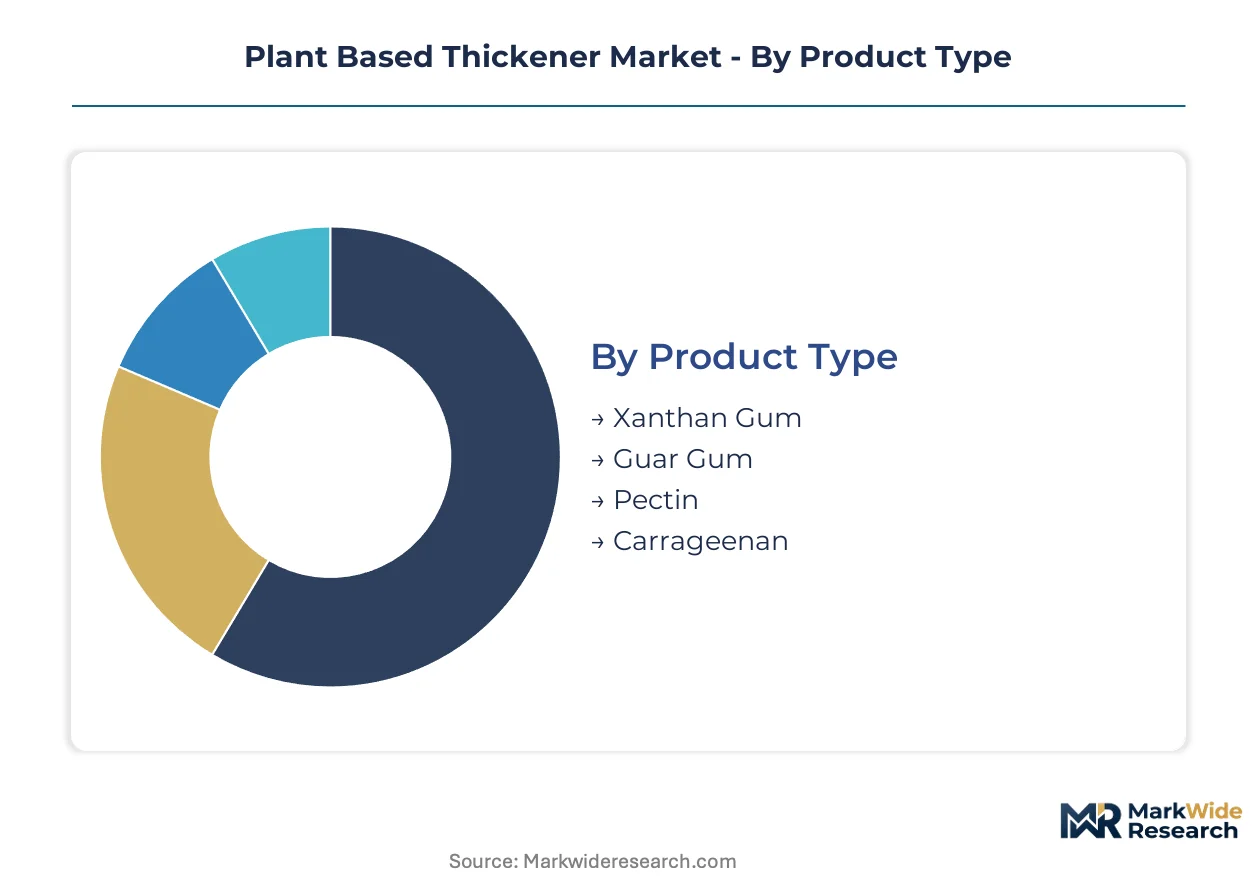
Plant based thickener portfolios fragment across functional specifications, regulatory tolerances, and processing requirements. Procurement teams select hydrocolloids based on viscosity targets, pH stability, and clean-label alignment rather than commodity pricing alone. This segmentation reveals where technical service investments concentrate and which specifications command formulation premiums.
Product Type:
Cost tier determines procurement behavior across hydrocolloid categories, with fermentation-derived and agricultural-extracted options occupying distinct margin bands.
- Xanthan Gum:Microbial fermentation yields this extracellular polysaccharide with pseudoplastic flow behavior stable across pH 2-12. Beverage manufacturers in Germany specify xanthan for acidified drinks where seed-derived alternatives fail. EFSA-compliant production lines at Cargill and ADM supply industrial volumes to Coca-Cola European Partners filling plants.
- Guar Gum:Endosperm extraction from Cyamopsis tetragonoloba seeds produces galactomannan hydrocolloids with cold-water solubility. Indian monsoon volatility creates 12-18 month price cycles that compress processor margins. Bakery applications in France favor guar for dough conditioning where cost sensitivity exceeds clean-label requirements.
- Pectin:Citrus peel and apple pomace extraction yields high-methoxyl and low-methoxyl grades for gel-strength precision. Acid-set dairy alternatives specify pectin amid carrageenan safety debates.
- Carrageenan:Red seaweed extraction delivers kappa, iota, and lambda fractions with distinct gel textures. Irish coastal processors scale tank cultivation to reduce wild-harvest dependency.
Xanthan gum commands the established base. The steepest expansion runs through pectin as dairy alternative reformulation accelerates.
Application:
Application scope determines viscosity specifications, with food and pharmaceutical sectors imposing divergent purity and documentation requirements.
- Food & Beverages:Rheology modification spans sauces, dairy alternatives, and bakery systems where mouthfeel precision determines consumer acceptance. German industrial bakers replace modified starches with native hydrocolloids to meet processed food classification limits under retailer clean-label thresholds.
- Pharmaceuticals:Suspension stability and controlled-release matrices demand pharmacopeia-grade hydrocolloids with batch-to-batch consistency. Precision fermentation platforms target this segment where purity specifications exceed agricultural extraction capabilities.
- Cosmetics:Emulsion stabilization and texture enhancement in personal care formulations prioritize sensory attributes over cost minimization.
- Nutraceuticals:Encapsulation matrices and viscosity control in functional food applications bridge food and pharmaceutical specifications.
Food and beverages anchors volume demand. Pharmaceuticals posts the steepest expansion trajectory as fermentation-derived alternatives gain regulatory traction.
End User:
Customer type shapes procurement patterns, with direct supplier relationships displacing distributor networks among scale buyers.
- Food Manufacturers:Integrated processors negotiate multi-year volume contracts with technical co-development requirements. Aldi and Lidl sourcing teams consolidate supplier lists to reduce REACH compliance audit burdens.
- Bakeries:Industrial and artisanal segments diverge on specification tolerance, with large-scale operators demanding lot-to-lot consistency.
- Beverage Companies:Acidified drink formulations specify pseudoplastic flow curves measurable through inline rheometry systems.
- Contract Manufacturers:Private-label formulators maintain multiple ingredient portfolios to satisfy divergent retailer clean-label definitions.
Food manufacturers command the established base. Contract manufacturers are gaining share fastest as private-label outsourcing accelerates.
Form:
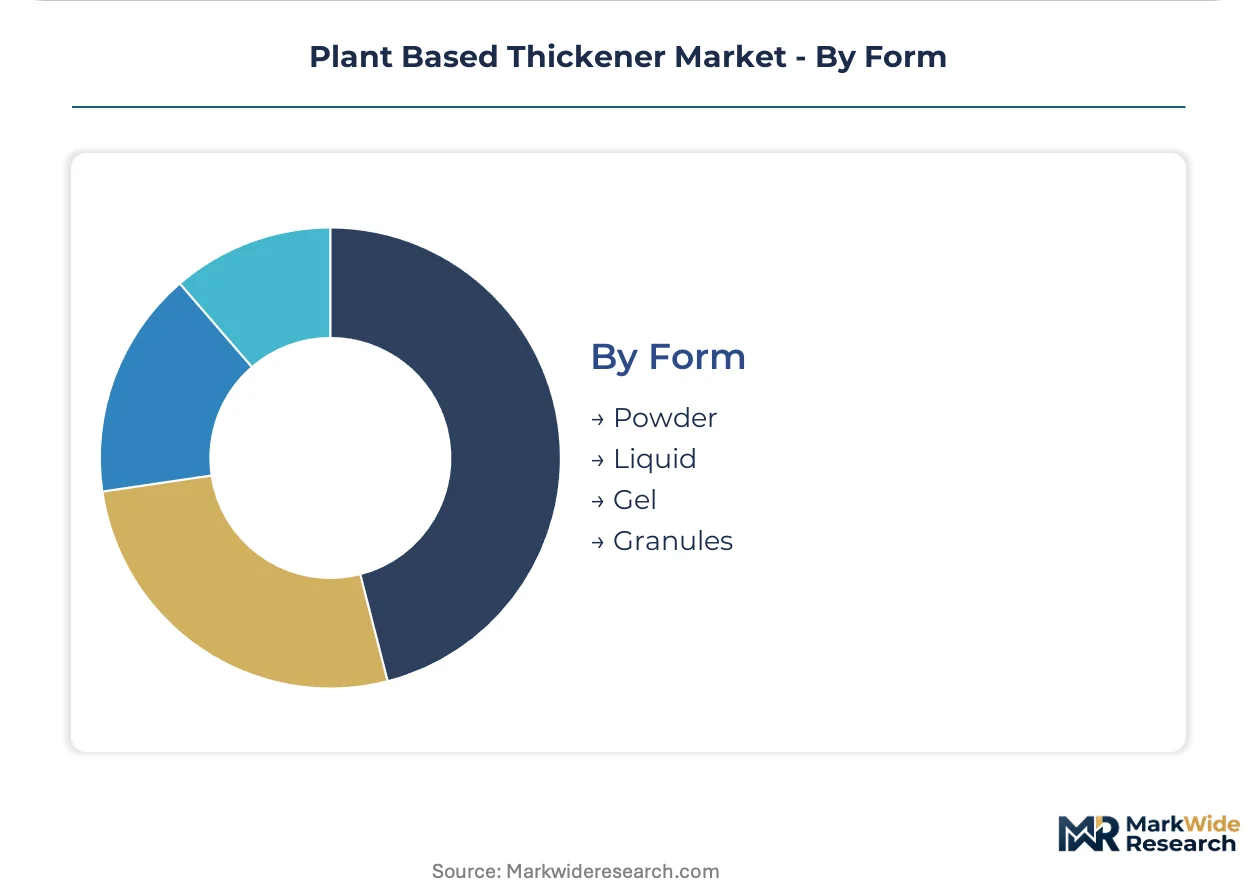
Physical format determines handling economics and dissolution kinetics, with powder dominating industrial scale and liquid concentrates serving specialized applications.
- Powder:Spray-dried and milled grades offer shelf stability and flexible dosing across dry-mix and wet-processing applications. Bulk handling systems at European compounders favor powder for inventory efficiency.
- Liquid:Pre-hydrated suspensions eliminate dust exposure and dissolution time in high-throughput beverage lines.
- Gel:Pre-formed gel structures serve specialized applications requiring immediate texture contribution without hydration delays.
- Granules:Agglomerated formats improve dispersibility in high-shear mixing environments.
Powder commands the established base. Liquid concentrates are climbing the fastest as beverage manufacturers optimize line efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European hydrocolloid import flows, handling bulk guar and pectin shipments from Indian subcontinent and Latin American citrus belt origins. Rotterdam's integrated chemical terminals distribute xanthan gum fermentation outputs across German industrial bakeries and Dutch beverage compounders.
Germany
Industrial bakers in Bavaria and North Rhine-Westphalia replace modified starches with native hydrocolloids to meet retailer clean-label thresholds. EFSA safety evaluations of refined carrageenan push dairy alternative manufacturers toward pectin systems. Cologne-based contract manufacturers consolidate supplier lists to reduce REACH compliance audit burdens.
France
Parisian private-label processors negotiate multi-year volume contracts for pectin-starch blends in fruit-filled bakery applications. ANSM pharmaceutical regulations favor pharmacopeia-grade hydrocolloids with batch-to-batch consistency. Brittany coastal processors scale tank cultivation of red seaweed to reduce wild-harvest dependency for carrageenan extraction.
United States
Midwest oilseed processing yields complementary gum outputs through integrated ADM facilities in Illinois and Iowa. FDA GRAS self-affirmation governs market entry without pre-market approval. Chicago-area beverage manufacturers deploy inline rheometry systems to measure pseudoplastic flow curves during batch processing.
India
Rajasthan and Gujarat monsoon-dependent harvests create 12-18 month guar seed price cycles that compress processor margins. FSSAI clean-label guidelines accelerate reformulation away from synthetic thickeners. Mumbai gum processors face margin compression when seed costs spike without corresponding formula price adjustments.
China
Shandong Peninsula fermentation platforms produce xanthan gum with pseudoplastic flow behavior stable across broad pH ranges. SAMR food safety regulations align with international pharmacopeia standards for hydrocolloid purity. Qingdao chemical terminals export microbial fermentation hydrocolloids to Southeast Asian beverage manufacturers.
Plant Based Thickener Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agricultural processors and specialized hydrocolloid formulators. Tiered competitive positioning separates global agricultural traders with captive raw material access from regional distributors dependent on spot procurement. Three archetypes dominate: seed-to-gum integrated processors, fermentation platform operators, and citrus peel extraction specialists. Dominant competitive moves include backward integration into agricultural sourcing and direct supplier-manufacturer contracting that bypasses traditional distribution networks.
Among North American agricultural processors, Cargill and Archer Daniels Midland Company exemplify integrated seed-to-gum structures with oilseed processing outputs yielding complementary hydrocolloid volumes. Tate & Lyle PLC occupies a position within the European formulation specialist tier, anchoring clean-label bakery application expertise. These three represent distinct strategic postures: agricultural commodity leverage, integrated oilseed processing scale, and application-specific technical service depth.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company (ADM) |
| DuPont de Nemours |
| Tate & Lyle PLC |
| CP Kelco |
| Kerry Group |
| Ingredion Incorporated |
| Roquette Frères |
| Ashland |
| Others |
Value Network & Pricing Analysis
Rajasthan and Gujarat guar seed processing clusters anchor global supply, with monsoon-dependent harvest volatility translating directly into 12-18 month price cycles that compress processor margins when seed costs spike without formula price adjustments. This agricultural concentration creates asymmetric pricing power where integrated oilseed processors capture margin stability that spot-dependent distributors cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeia-grade fermentation hydrocolloids from agricultural-extracted alternatives. Price differentiation rests on REACH compliance certification and volume scale, with pharmaceutical suspensions commanding premiums for batch-to-batch consistency. Pricing pressure stems from enzymatic starch thinning in neutral pH sauce applications, where cost-conscious manufacturers substitute modified starches. Contract manufacturers exhibit highest price sensitivity due to private-label margin compression, while pharmaceutical formulators prioritize purity over cost.
Supply Chain Analysis
Upstream guar seed dependence draws from Indian monsoon agriculture, while citrus peel pectin extraction feeds from Latin American and Mediterranean orchards. Xanthan gum fermentation capacity concentrates in Shandong Peninsula and Midwest US oilseed processing corridors. Single-source vulnerability runs through Indian guar harvests, where climate volatility disrupts 12-18 month procurement cycles. Distribution runs through Rotterdam chemical terminals and Hamburg bulk handling for European compounders, with direct supplier-manufacturer contracting displacing traditional distributor networks among scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory affairs capabilities and precision fermentation platforms are scarce assets that concentrate competitive advantage among integrated processors, while small importers face forced exit under REACH documentation burdens.
For Market Incumbents: Entrench REACH-compliant supply chains through captive agricultural sourcing in Rajasthan and Gujarat seed belts. Expand dedicated account teams for mid-sized European processors seeking technical co-development. Defend against enzymatic starch substitution by embedding inline rheometry sensors into customer production lines, converting specification compliance into switching costs. For New Entrants and Emerging Players: French coastal tank cultivation of red seaweed offers underpenetrated supply security for carrageenan extraction, bypassing wild-harvest volatility. Target pharmaceutical suspension formulators with precision fermentation platforms where purity specifications exceed agricultural extraction capabilities. Pursue EU Green Deal bio-based procurement alignment as the go-to-market wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with neglected hydrocolloid divisions lacking REACH registration infrastructure. Long-term viability favors fermentation platform operators and citrus peel extraction specialists with backward-integrated orchard access. Watch EFSA carrageenan safety evaluation timelines as the signal for pectin demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Supply | Cargill and ADM secure Rajasthan guar harvests through direct farmer contracting, insulating margin from monsoon volatility. |
| REACH Registration Investment | Specialized toxicology documentation creates six-figure barriers that force small importer consolidation. |
| Precision Fermentation Scale-Up | Startups target pharmaceutical suspensions where batch consistency exceeds agricultural extraction capabilities. |
| Inline Rheometry Deployment | Coca-Cola European Partners reduces batch release times from hours to minutes through sensor-embedded production lines. |
| Tank Cultivation Expansion | Brittany and Irish coastal processors reduce wild-harvest dependency for EU Green Deal bio-content compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA safety evaluations, ECHA substance registration databases, and EU customs trade flows. Hydrocolloid procurement managers at German industrial bakeries, French private-label processors, and Dutch beverage compounders provided operational validation. Technical directors at fermentation platforms and citrus peel extraction facilities supplied capacity and purity specification data. Bottom-up volume estimates triangulated against top-down market sizing from trade association filings and SEC disclosures by integrated agricultural processors.
Forecast inputs span hydrocolloid grade tier, end-use application, regulatory compliance cluster, and regional production hub across the analysis window. CAGRs derive from segment-level growth rate reconciliation with macroeconomic drivers and regulatory timeline impacts. Modeled dimensions include food versus pharmaceutical purity specifications, fermentation-derived versus agricultural-extracted sourcing, and direct contracting versus distributor-mediated procurement channels. Input variables incorporate REACH registration deadline effects, clean-label threshold evolution, and enzymatic substitution elasticity in neutral pH applications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fermentation platforms or accelerated EFSA carrageenan restrictions would shift outcomes materially. Cross-checking against ECHA substance registration volumes and EU import customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Yeast Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Botanical Extracts Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Green Gram Powder Market
Ingredients
Food Colors Market
Ingredients
Corn Oil Market
Ingredients
Microparticulated Egg White Protein Market
Ingredients
South America Malt Ingredient Market
Ingredients
Sesame Oil Market
Ingredients
Resistant Starch Market
Ingredients
Industrial Sugar Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Instant Dry Yeast Market
Ingredients
Casein Market