
 Xanthan Gum Market | 2026-2036
Xanthan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
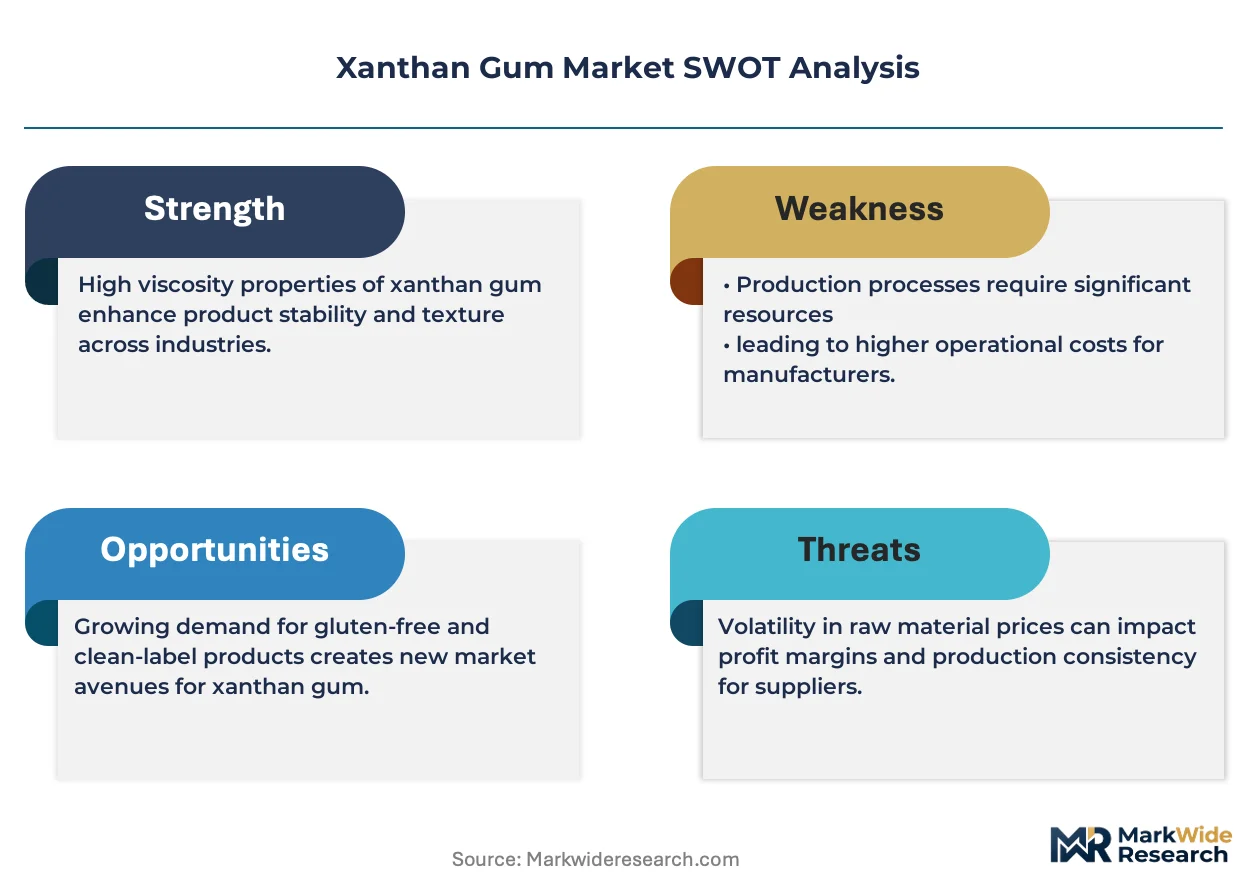
Xanthan Gum Market Analysis
Fermentation process optimization is fragmenting xanthan gum production economics as precision bioprocessing reduces batch variability and raw material waste. CP Kelco leverages its marine biotechnology heritage to sustain premium positioning in food-grade and pharmaceutical-grade segments. Fufeng Group anchors global supply through massive fermentation capacity in Shandong Province, while MeiHua Holdings Group competes on backward integration into corn starch feedstock.
Xanthan gum is a high-molecular-weight extracellular polysaccharide produced by Xanthomonas campestris fermentation, composed of glucose, mannose, and glucuronic acid units with a cellulose backbone and trisaccharide side chains; its 1% aqueous solution yields viscosities from 1,200 to 1,600 cP, making it effective at low concentrations across pH ranges. The polysaccharide functions primarily as a rheology modifier, stabilizer, and water-binding agent in formulations ranging from salad dressings to drilling muds. Food-grade xanthan dominates volume but faces margin compression from commoditization, whereas pharmaceutical-grade commands premium pricing due to USP-NF compliance burdens and limited qualified fermentation capacity. Oil and gas applications represent a cyclical demand reservoir that expands during upstream activity surges but contracts sharply during price downturns.
FDA GRAS status and EFSA food additive evaluations shape formulation eligibility across North American and European markets, while China's NMPA and GB standards govern pharmaceutical-grade imports and domestic sales. REACH registration requirements in Europe constrain non-compliant suppliers from accessing industrial-grade channels. Stakeholders must monitor regulatory divergence between jurisdictions, as tightening purity specifications in one region create arbitrage opportunities or exclusion risks depending on certification alignment.
Market Dynamics
Fermentation capacity concentration in Shandong Province is compressing global pricing power while clean-label mandates across food and pharmaceutical channels simultaneously pull premium-grade supply toward certified facilities. This structural squeeze rewards backward-integrated producers with captive corn starch supply and penalizes toll manufacturers exposed to spot feedstock costs.
Growth Catalysts
- FDA GRAS expansion into novel delivery formats:The designation's extension to gummy vitamins and beverage emulsions opens formulation latitude for hydrocolloid suppliers targeting functional food channels.
- Cell-cultured meat scaffolding:Xanthan gum's shear-thinning rheology provides texture support in extrusion-based meat analog production, with pilot facilities in Singapore and the Netherlands qualifying suppliers.
- China's dual carbon goals:Fermentation efficiency mandates under MEE directives are accelerating anaerobic digestion retrofits that lower energy intensity per kilogram of polysaccharide output.
Market Restraints
- Corn starch price volatility:Feedstock costs swing with US Midwest crop yields and ethanol policy, squeezing toll processors without long-term grain procurement contracts.
- Shandong supply concentration:Three facilities control over sixty percent of global fermentation volume, creating single-point failure exposure during environmental compliance shutdowns.
- Guar gum substitution in hydraulic fracturing:Permian Basin operators revert to guar during xanthan price spikes, fragmenting demand loyalty in oilfield applications.
Strategic Opportunities
- Pharmaceutical-grade USP-NF qualification:Limited fermentation capacity meeting endotoxin specifications creates margin expansion for producers investing in GMP-certified bioreactor lines.
- Direct-to-bakery distribution platforms:E-commerce ingredient portals bypass traditional foodservice distributors, capturing formulation specification data from artisan and industrial bakers.
- EFSA clean-label tailwinds:E-number avoidance trends in Western European retail channels favor xanthan gum's "fermented sugar" positioning over chemically modified starches.
Industry Challenges
- Precision fermentation talent scarcity:Bioprocess engineers with Xanthomonas campestris strain optimization experience command premium compensation in competing biopharma sectors.
- Cross-contamination certification timelines:Pharmaceutical-grade qualification requires eighteen-to-twenty-four-month validation cycles that delay revenue conversion from capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xanthan Gum Market |
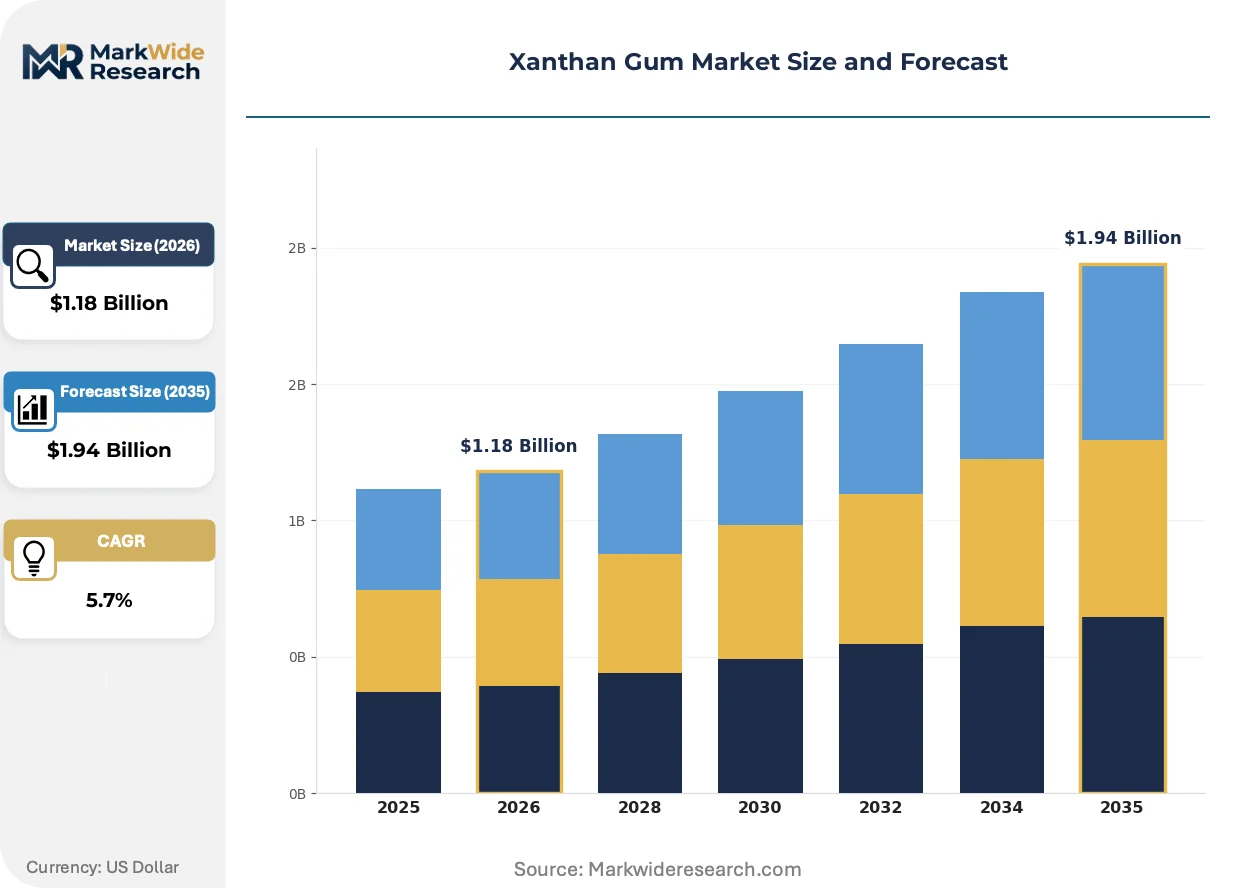
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.94 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food & Beverage, Pharmaceuticals, Personal Care, Oil & Gas End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Oil Industry Form: Powder, Liquid, Granules, Gel |
| Companies Covered | Archer Daniels Midland Company, Solvay, CP Kelco, MeiHua Holdings Group, Jungbunzlauer Suisse AG, Fufeng Group, Ingredion Incorporated, Hebei Xinhe Biochemical, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xanthan Gum Market Emerging Trajectories
Continuous fermentation monitoring via Raman spectroscopy is compressing batch-to-batch variability while regulatory divergence between FDA and EFSA purity benchmarks fragments specification requirements. These forces reward agile producers with modular quality systems.
Precision bioprocessing platforms integrating real-time metabolite sensing with automated feed control are rendering obsolete manual sampling protocols that introduced lag in glucose supplementation timing. Pharmaceutical-grade manufacturers in Switzerland and North Carolina deploy these systems to tighten endotoxin consistency, compressing rejection rates and qualifying supply for parenteral drug formulations.
REACH registration deadlines for industrial-grade hydrocolloids are tightening purity disclosure requirements that disqualify non-compliant Asian suppliers from European oilfield and construction channels. ECHA's updated dossier standards demand comprehensive ecotoxicology data that smaller fermentation facilities cannot generate without third-party testing expenditure. Industrial-grade distributors in the Netherlands and Germany are consolidating supplier lists to pre-registered entities, compressing market access for unqualified producers.
Specification-driven procurement in North American food manufacturing is consolidating approved supplier lists to three-to-five qualified vendors per category, displacing spot purchasing relationships that dominated prior decades. Large bakery and sauce manufacturers now require annual third-party audits and certificate of analysis consistency that smaller fermentation facilities cannot sustain. This concentration is most visible in Midwestern US food processing corridors where Cargill and ADM procurement teams enforce unified qualification standards across multiple plant locations.
Xanthan Gum Market Segmentation
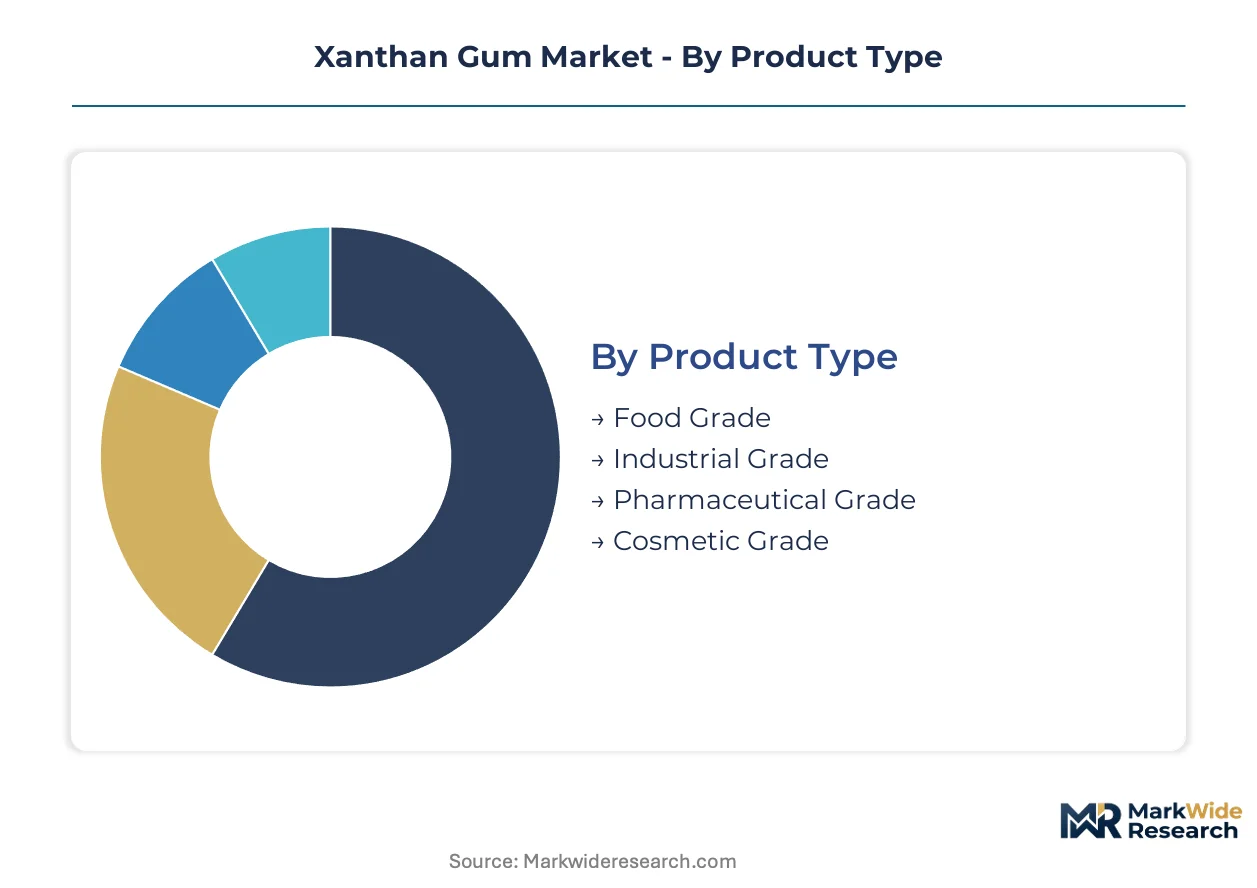
Xanthan gum's functional versatility across viscosity ranges and pH stability creates distinct specification tiers that command divergent pricing and certification burdens. Segmentation reveals how fermentation capacity allocates across margin-differentiated channels rather than uniform commodity production.
Product Type:
Cost tier stratification separates mass-market hydrocolloid supply from qualified pharmaceutical channels demanding endotoxin control and GMP documentation.
- Food Grade:Standardized viscosity between 1,200-1,600 cP at 1% concentration serves salad dressings, sauces, and gluten-free bakery applications. Demand concentrates in Midwestern US food processing corridors where Cargill and ADM procurement teams enforce unified qualification standards across multiple plant locations.
- Pharmaceutical Grade:USP-NF compliance with endotoxin specifications below 10 EU/g qualifies material for parenteral drug formulations and oral suspensions. Swiss and North Carolina manufacturers deploy Raman spectroscopy monitoring to tighten batch consistency and compress rejection rates from limited qualified fermentation capacity.
- Industrial Grade:Permian Basin drilling mud formulations tolerate higher protein residues than food or pharmaceutical channels.
- Cosmetic Grade:Personal care applications require microbial limits stricter than industrial specifications but less stringent than pharmaceutical tiers.
Food grade commands the established base. The steepest expansion runs through pharmaceutical grade.
Application:
End-use diversification spans cyclical oilfield demand reservoirs and steady food formulation requirements with divergent specification rigor.
- Food & Beverage:Clean-label stabilization in beverage emulsions and gummy vitamin matrices leverages FDA GRAS expansion into novel delivery formats. EFSA E-number avoidance trends in Western European retail channels favor fermented sugar positioning over chemically modified starches.
- Oil & Gas:Hydraulic fracturing fluid rheology modification faces substitution pressure from guar gum during xanthan price spikes. Shandong fermentation concentration creates single-point failure exposure during environmental compliance shutdowns that disrupt upstream supply security.
- Pharmaceuticals:Controlled-release tablet matrices and suspension stabilizers require eighteen-to-twenty-four-month validation cycles.
- Personal Care:Cream and lotion texture modification competes with alternative hydrocolloids on cost-performance ratios.
Food and beverage anchors volume throughput. Pharmaceuticals deliver the highest margin capture per kilogram.
End User:
Customer type determines procurement sophistication from spot purchasing relationships to consolidated approved supplier lists with annual third-party audit requirements.
- Food Manufacturers:Large bakery and sauce manufacturers now require certificate of analysis consistency that smaller fermentation facilities cannot sustain, consolidating approved vendor lists to three-to-five qualified suppliers per category.
- Pharmaceutical Firms:Parenteral drug manufacturers demand GMP-certified bioreactor lines with documented strain lineage and media component traceability that disqualifies toll processors.
- Cosmetic Companies:Formulation houses prioritize sensory performance and label claims over certification depth.
- Oil Industry:Permian Basin operators revert to guar during price spikes, fragmenting demand loyalty.
Food manufacturers drive volume aggregation. Pharmaceutical firms concentrate premium supply access.
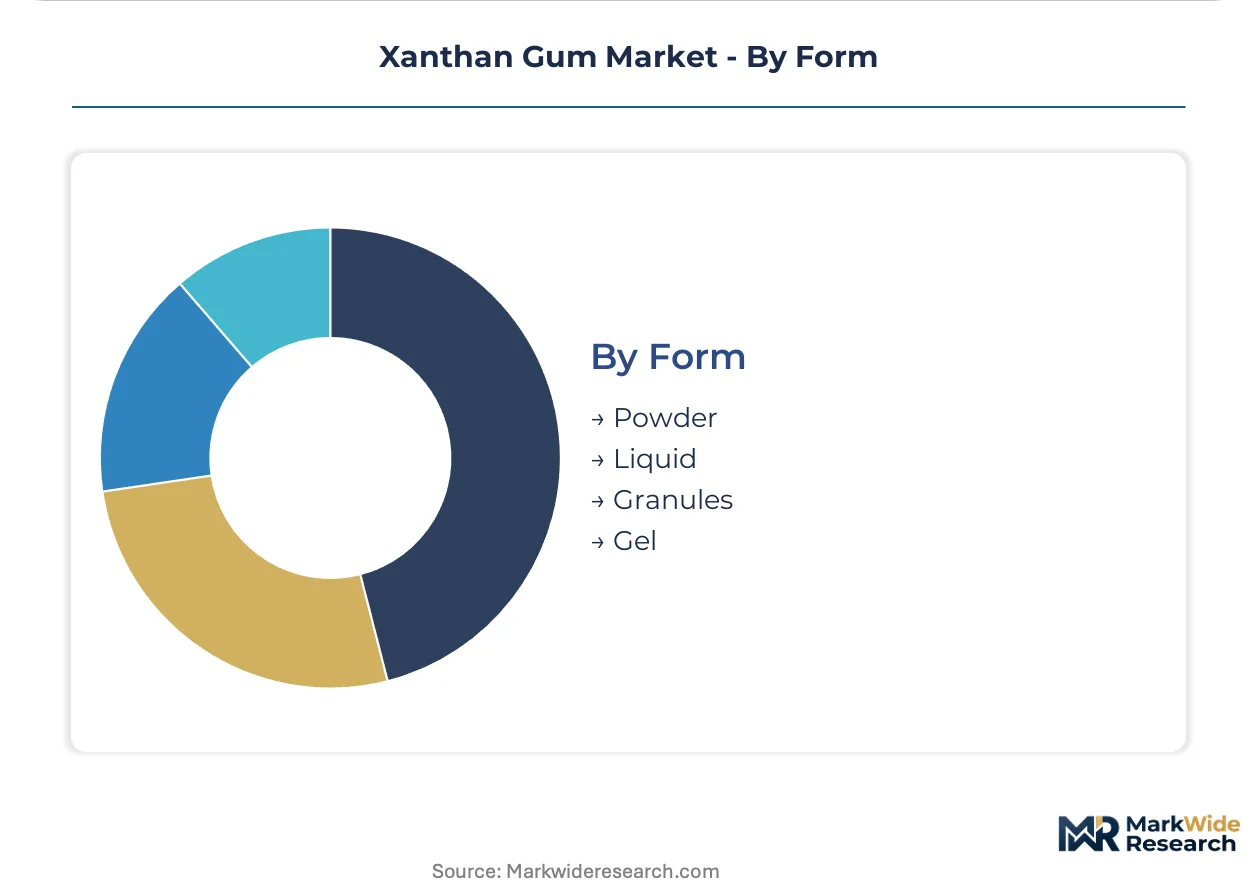
Form:
Physical presentation shapes dissolution kinetics, dust exposure, and handling economics across manufacturing environments.
- Powder:Standard bulk delivery format for industrial-scale food and oilfield applications with established pneumatic conveying infrastructure.
- Liquid:Pre-hydrated solutions eliminate dusting and accelerate incorporation for cosmetic and pharmaceutical formulation facilities lacking high-shear mixing equipment.
- Granules:Reduced dust generation improves occupational safety profiles in high-volume bakery operations.
- Gel:Concentrated dispersions target specialized personal care and pharmaceutical suspension applications.
Powder dominates tonnage movement. Liquid formats gain share in premium formulation channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation facilities in Shandong Province export bulk hydrocolloid supply to North American food processors and European pharmaceutical formulators, establishing the dominant trade-flow corridor for xanthan gum distribution.
China
Shandong Province hosts concentrated fermentation capacity serving global food-grade and industrial-grade demand. MEE directives on dual carbon goals mandate anaerobic digestion retrofits that reduce energy intensity per kilogram of output. Weifang and Yantai industrial clusters anchor production gravity for export-oriented supply.
United States
Midwestern food processing corridors in Illinois and Iowa drive specification-driven procurement from consolidated approved supplier lists. FDA GRAS designation for novel delivery formats expands formulation latitude in gummy vitamin and beverage emulsion channels. Chicago-area distribution hubs coordinate just-in-time delivery to Cargill and ADM procurement networks.
Switzerland
Swissmedic oversight and USP-NF compliance requirements position the country as a pharmaceutical-grade qualification center. Precision bioprocessing platforms with Raman spectroscopy monitoring tighten endotoxin consistency for parenteral drug formulations. Basel-region facilities serve European pharmaceutical manufacturers with documented strain lineage traceability.
Germany
REACH registration deadlines for industrial-grade hydrocolloids constrain market access to pre-registered entities. ECHA's updated dossier standards demand ecotoxicology data that filters non-compliant suppliers from oilfield and construction channels. Rotterdam-Antwerp corridor distributors consolidate supplier lists around ECHA-registered fermentation sources.
India
FSSAI food additive regulations and evolving CDSCO pharmaceutical standards shape import requirements for hydrocolloid raw materials. Domestic formulation houses in Maharashtra and Gujarat source certified grades for bakery and sauce applications. Mumbai port infrastructure handles transshipment flows for South Asian processed food manufacturers.
Xanthan Gum Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered certification segments. Food-grade supply concentrates around backward-integrated fermentation operators with captive corn starch feedstock, while pharmaceutical-grade channels fragment across limited qualified bioreactor capacity. Three archetypes dominate: scale-driven bulk fermenters, premium-grade qualification specialists, and toll-dependent regional processors. Competitive moves center on GMP-certified capacity expansion and direct-to-formulator distribution platform development.
Within the premium-grade tier, CP Kelco exemplifies marine biotechnology heritage positioning, while Fufeng Group anchors scale-driven supply from Shandong-based fermentation assets. MeiHua Holdings Group occupies a backward-integrated position with upstream control over corn starch feedstock procurement.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Solvay |
| CP Kelco |
| MeiHua Holdings Group |
| Jungbunzlauer Suisse AG |
| Fufeng Group |
| Ingredion Incorporated |
| Hebei Xinhe Biochemical |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Shandong Province fermentation clusters anchor global xanthan gum pricing power through concentrated capacity that compresses spot market premiums while amplifying contract negotiation leverage for backward-integrated operators. Corn starch feedstock volatility and MEE environmental compliance costs feed directly into margin structures across food-grade and pharmaceutical-grade tiers.
Pricing Analysis
Pharmaceutical-grade Raman-spectroscopy-enabled production commands substantial premiums over standard food-grade fermentation, while industrial-grade drilling mud formulations trade at commodity floors. Three-tier pricing structure across pharmaceutical, food, and industrial levels separates USP-NF certified supply from GRAS-compliant food channels and unqualified industrial batches. Cost compression in food-grade is intensifying because Shandong capacity expansion outpaces clean-label demand growth, squeezing toll processors without captive corn starch supply. Oilfield buyers exhibit highest price sensitivity, reverting to guar gum during xanthan price spikes, whereas parenteral drug manufacturers accept premium pricing for endotoxin-controlled supply.
Supply Chain Analysis
Fufeng Group, MeiHua Holdings Group, and CP Kelco fermentation assets control the majority of qualified bioreactor capacity serving global hydrocolloid demand. Manufacturing concentrates in China, Switzerland, and North Carolina, with Shandong Province hosting the dominant share of food-grade and industrial-grade output. Feedstock supply draws from US Midwest corn starch, Chinese domestic grain processors, and European glucose refiners. Single-source vulnerability concentrates in Shandong environmental compliance shutdowns that disrupt upstream supply security. Distribution runs through Rotterdam-Antwerp corridor distributors for European pharmaceutical and industrial channels, with Chicago-area hubs coordinating North American food processor just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation fragmentation across food, pharmaceutical, and cell-cultured meat channels creates multiple entry niches for specialized grade suppliers. Certification divergence between FDA GRAS expansion and EFSA E-number positioning rewards agile producers with modular quality systems.
For Market Incumbents: Entrench pharmaceutical-grade positioning through GMP-certified bioreactor line investments that tighten endotoxin consistency and compress eighteen-to-twenty-four-month validation cycles. Defend against Shandong supply concentration risks by diversifying fermentation footprint into Swiss and North Carolina precision bioprocessing platforms with Raman spectroscopy monitoring. Secure backward integration into corn starch feedstock through long-term grain procurement contracts that insulate against US Midwest crop yield volatility. For New Entrants and Emerging Players: Build out direct-to-bakery e-commerce distribution platforms that bypass traditional foodservice distributors and capture formulation specification data from artisan and industrial bakers. Target pharmaceutical-grade USP-NF qualification as the most penetrable premium segment, given limited fermentation capacity meeting endotoxin specifications. Pursue cell-cultured meat scaffolding applications in Singapore and Netherlands pilot facilities as a novel delivery format with qualification pathways still open. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision bioprocessing platform owners with real-time metabolite sensing and automated feed control capabilities that render manual sampling protocols obsolete. Five-to-ten year viability hinges on regulatory alignment across FDA, EFSA, and NMPA purity benchmarks that fragment specification requirements. Acquisition target archetype: GMP-certified fermentation facilities with documented strain lineage and existing pharmaceutical customer relationships. Watch for ECHA REACH registration deadline enforcement as inflection indicator that filters non-compliant Asian suppliers from European oilfield and construction channels.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Certified Capacity Expansion | Qualifies supply for parenteral drug formulations requiring endotoxin specifications below 10 EU/g. |
| Backward Integration into Corn Starch | Captive feedstock supply insulates margin structures from US Midwest ethanol policy swings. |
| Precision Bioprocessing Platform Deployment | Raman spectroscopy monitoring compresses batch-to-batch variability and rejection rates. |
| Direct-to-Formulator Distribution Platform | E-commerce ingredient portals capture specification data from artisan and industrial bakers. |
| Pharmaceutical-Grade USP-NF Qualification | Eighteen-to-twenty-four-month validation cycles create scarcity premium for qualified fermentation capacity. |
Methodological Framework
Operator-level perspectives from fermentation plant managers, hydrocolloid procurement leads at Cargill and ADM, pharmaceutical formulation scientists, and oilfield fluid engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA GRAS notices, EFSA food additive opinions, ECHA REACH registration databases, and SEC 10-K filings from listed fermentation operators. Bottom-up capacity modeling triangulated against top-down demand segmentation across food, pharmaceutical, industrial, and personal care channels.
Scenario-bracketing framed projections across base, upside, and downside cases reflecting corn starch price volatility, Shandong environmental compliance enforcement intensity, and cell-cultured meat commercialization pace. Segmentation dimensions modeled include grade tier, end-use application, physical form, and regional regulatory cluster. CAGRs derived from historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporated MEE dual carbon goal implementation timelines and FDA novel delivery format GRAS expansion pathways.
Sensitivities concentrate around corn starch feedstock cost spikes, Shandong single-point failure exposure during environmental compliance shutdowns, and guar gum substitution elasticity in Permian Basin hydraulic fracturing. Forecasts reflect assumptions on fermentation efficiency gains from anaerobic digestion retrofits and precision bioprocessing platform adoption rates. Quarterly review of ECHA REACH registration compliance rates, FDA GRAS expansion decisions, and MEE enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Lime Oil Market