
 Guar Gum Market | 2026-2036
Guar Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Guar Gum Market Analysis
Buyer concentration among oilfield service companies is realigning procurement volumes toward fewer integrated drilling contractors with multi-basin contracts. Cargill, Incorporated leverages its agricultural origination network to secure raw guar seed supply before regional crushers can bid. Vikas WSP Ltd anchors its position through captive processing facilities in Rajasthan's guar belt, controlling quality from seed to refined powder. Hindustan Gum & Chemicals Ltd competes by sustaining long-term supply agreements with European food manufacturers requiring traceable non-GMO documentation.
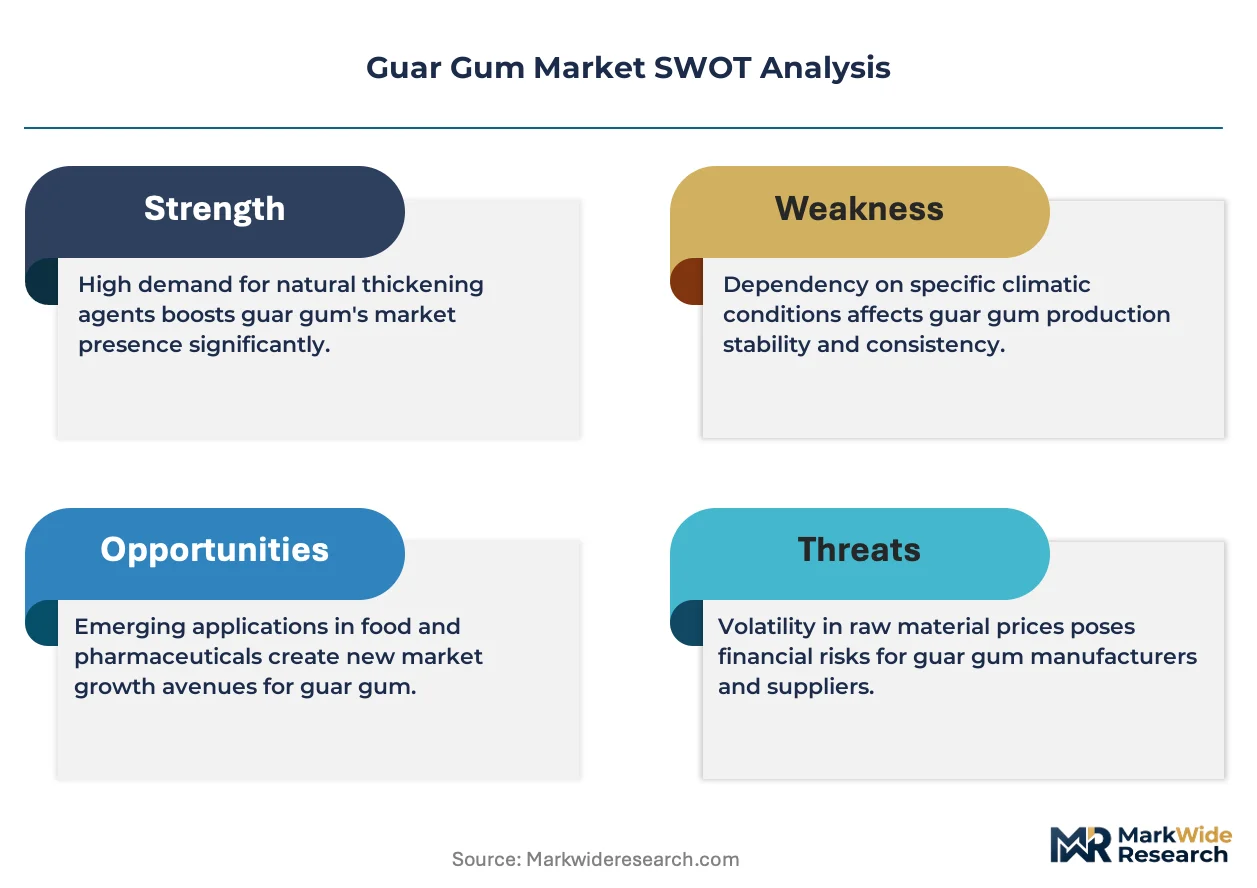
Guar gum is a galactomannan polysaccharide extracted from Cyamopsis tetragonoloba seeds, with a mannose-to-galactose ratio of approximately 2:1 that yields high-viscosity aqueous solutions at low concentrations. Its primary commercial purpose centers on thickening, stabilizing, and gelling across food systems, hydraulic fracturing fluids, and pharmaceutical tablet binders. Food Grade guar dominates value capture due to stringent purity requirements and premium pricing for allergen-free certifications, while Oil & Gas application volumes fluctuate with rig counts and completion intensity in North American shale plays. Industrial Grade segments occupy mature margin pools where price competition from synthetic polymers constrains expansion.
FDA food additive regulations under 21 CFR 184.1339 govern U.S. market access for edible guar derivatives, while India's FSSAI enforces contaminant limits on domestic and export-bound food-grade production. REACH registration requirements in Europe shape formulation choices for industrial applications, particularly where guar substitutes for synthetic thickeners in eco-labeled products. Stakeholders must monitor fracking fluid formulation shifts toward cellulose-based alternatives and track India's monsoon-dependent guar seed yields as decisive variables for supply planning and inventory positioning.
Market Dynamics
Buyer consolidation among North American shale operators is compressing procurement timelines and forcing guar gum suppliers to absorb inventory risk through just-in-time delivery commitments.
Growth Catalysts
- Shale completion intensity:Permian Basin operators are expanding slickwater fracturing programs that require high-viscosity guar-based friction reducers.
- FSSAI purity mandates:India's tightened food-grade contaminant limits are pushing Rajasthan processors toward certified export-ready production lines.
- Cellulose substitution limits:Synthetic polymer thickeners face REACH registration barriers in European eco-label formulations, preserving guar's cost position.
Market Restraints
- Monsoon yield volatility:Rajasthan's rain-dependent guar seed harvests create 15-40% annual production swings that crush margin predictability.
- Cellulose ether encroachment:CMC and HEC suppliers are capturing mid-viscosity oilfield slots through synthetic supply security guarantees.
- Single-origin concentration:Jodhpur's 200-kilometer processing radius houses over 80% of India's crushing capacity, creating systemic disruption exposure.
Strategic Opportunities
- Pharmaceutical tablet binders:USP-grade guar derivatives for controlled-release formulations remain underpenetrated versus gelatin and starch alternatives.
- EU Green Deal biopolymer mandates:REACH-registered natural thickeners qualify for public procurement preferences in eco-labeled cleaning products.
- Direct farm-gate contracting:Bypassing Jodhpur spot markets through seed-to-powder traceability agreements secures non-GMO documentation for European food manufacturers.
Industry Challenges
- BIS certification bottlenecks:India's laboratory testing backlog for food-grade guar derivatives stretches approval timelines to 8-14 weeks.
- Seed quality heterogeneity:Rajasthan's smallholder farming structure produces inconsistent galactomannan ratios that complicate powder standardization.
- Frac fluid formulation turnover:Oilfield service companies cycle guar specifications every 18-24 months, forcing R&D reinvestment without long-term purchase guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guar Gum Market |
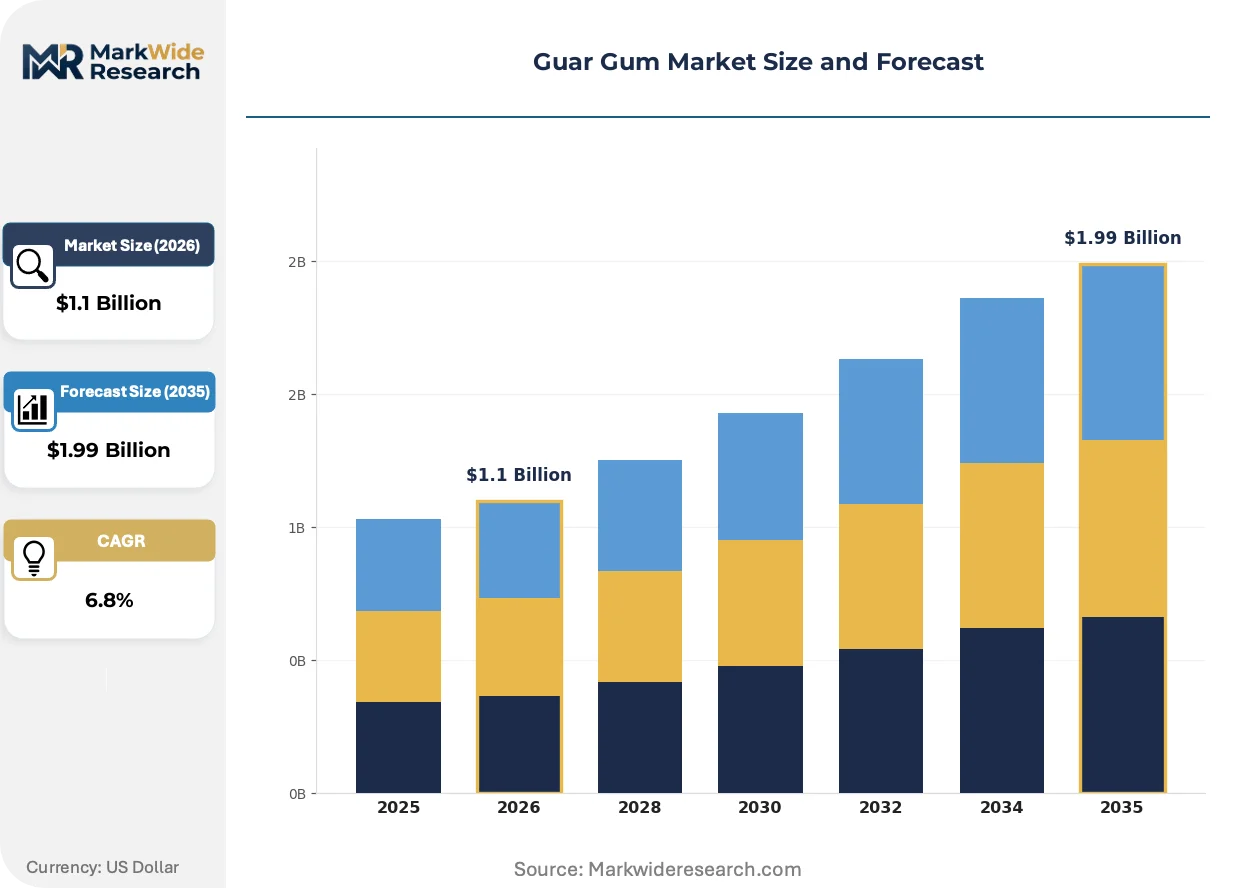
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Baking, Personal Care, Pharmaceuticals, Oil & Gas End User: Food Industry, Healthcare, Agriculture, Cosmetics Packaging Type: Bags, Drums, Bulk, Sachets |
| Companies Covered | Cargill, Incorporated, Vikas WSP Ltd, Hindustan Gum & Chemicals Ltd, Lucid Colloids Ltd, Ingredion Incorporated, Neelkanth Polymers, India Glycols Ltd, Shree Ram Industries, Rama Gum Industries (India) Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guar Gum Market Emerging Trajectories
Processing automation and regulatory traceability requirements are reconfiguring how guar gum moves from Rajasthan farms to end-use formulations across three distinct vectors.
Near-infrared spectroscopy is automating real-time galactomannan content verification at Rajasthan crushing facilities. Oilfield service companies adopting this technology reduce batch rejection rates and compress qualification cycles for new suppliers. The shift is automating quality control labor out of mid-tier processors while concentrating procurement relationships with capital-equipped integrated operators.
REACH registration deadlines for polymer thickeners are tightening documentary requirements for synthetic alternatives in European industrial applications. Guar derivatives with established biodegradability certifications capture formulation slots in eco-labeled detergents and personal care products. German and Dutch formulators are accelerating substitution trials ahead of 2026 re-registration windows.
Consolidated drilling contractors are unbundling chemical procurement from bundled service agreements. Integrated oilfield services firms now source guar gum directly through annual volume contracts rather than through fluid system providers. This pattern is most visible in the Permian and Eagle Ford basins where Halliburton and Schlumberger affiliates have established direct Rajasthan supplier relationships.
Guar Gum Market Segmentation
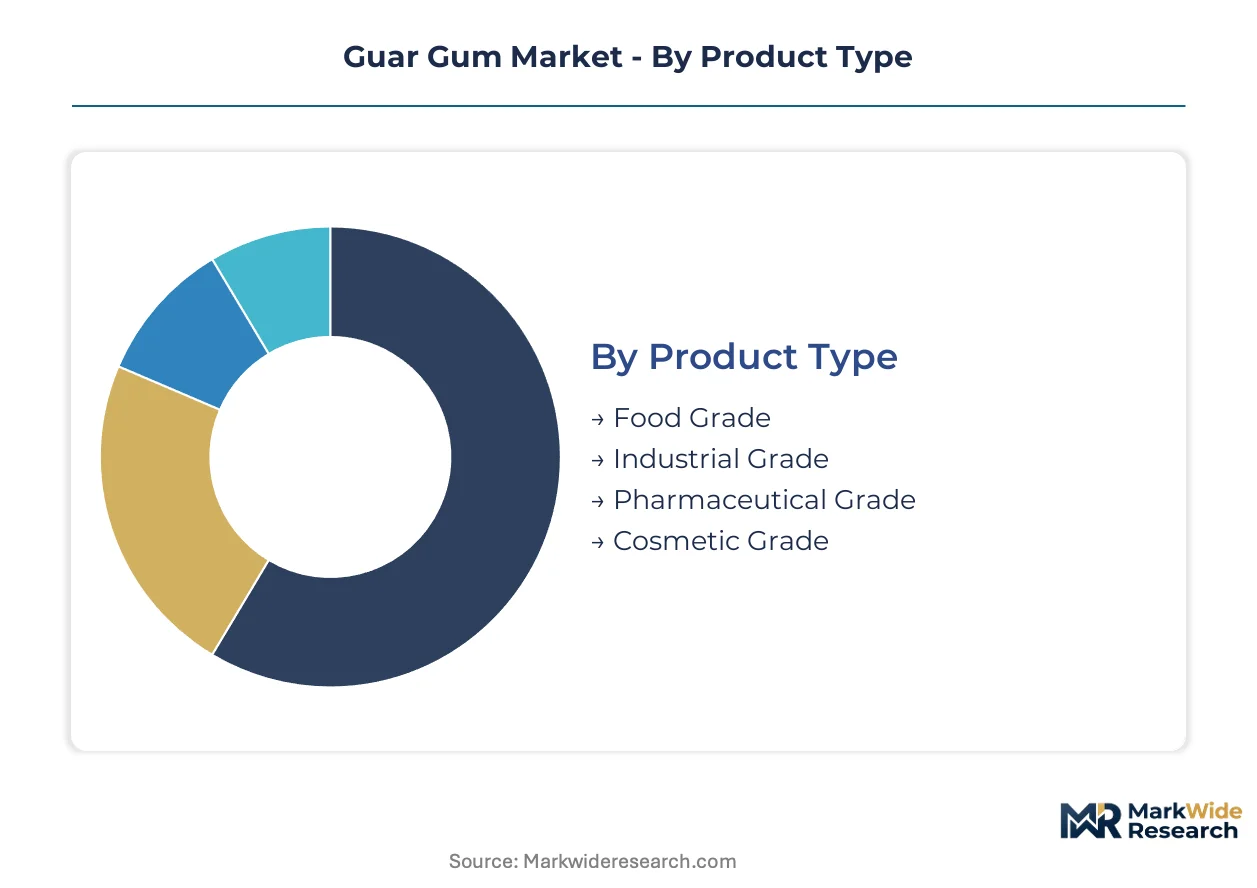
Guar gum's divergent purity standards and end-use performance requirements create distinct economic tiers. Segmentation reveals where premium pricing power concentrates versus where volume commoditization dominates procurement negotiations.
Product Type:
Volume concentrates in industrial specifications, while margin capture belongs to certified pharmaceutical and food derivatives.
- Food Grade:Refined to FSSAI and FDA contaminant limits with allergen-free documentation for European export. Demand clusters with Rajasthan processors pursuing BIS certification to bypass laboratory approval bottlenecks.
- Industrial Grade:Lower viscosity specifications serve mature applications where synthetic polymer substitution pressure is intense. Price competition from cellulose ethers constrains expansion in mid-viscosity oilfield slots.
- Pharmaceutical Grade:USP-certified derivatives for tablet binders and controlled-release matrices command premium spreads over food-grade equivalents.
- Cosmetic Grade:Purified to personal care microbiological standards with traceability documentation for EU eco-label compliance.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Customer procurement patterns split between cyclical commodity buyers and stability-seeking formulation houses.
- Oil & Gas:Hydraulic fracturing fluids in Permian Basin slickwater programs absorb high-viscosity guar-based friction reducers. Rig count volatility and 18-24 month specification cycles compress supplier margins.
- Pharmaceuticals:Controlled-release tablet binders and excipient applications remain underpenetrated versus gelatin alternatives. USP documentation requirements filter out unqualified Rajasthan processors.
- Baking:Gluten-free bread systems and frozen dough stabilization drive consistent food-service procurement from certified exporters.
- Personal Care:Eco-labeled shampoos and lotions in German and Dutch markets substitute REACH-registered guar for synthetic thickeners ahead of re-registration deadlines.
Procurement stability characterizes Pharmaceuticals. Demand fluctuation defines Oil & Gas.
End User:
Traceability requirements intensify as you move from commodity agriculture toward regulated consumer products.
- Food Industry:European manufacturers demand non-GMO seed-to-powder documentation that only direct farm-gate contracting can satisfy. Jodhpur spot market purchases fail this standard.
- Healthcare:Hospital and clinical procurement of pharmaceutical-grade excipients prioritizes USP certification over price minimization.
- Cosmetics:Formulators in REACH jurisdictions accelerate biodegradability-certified guar trials for Green Deal-compliant product lines.
- Agriculture:Seed coating and soil conditioning applications absorb lower-grade material with minimal purity documentation.
Specification stringency peaks with Food Industry. Price sensitivity dominates Agriculture.
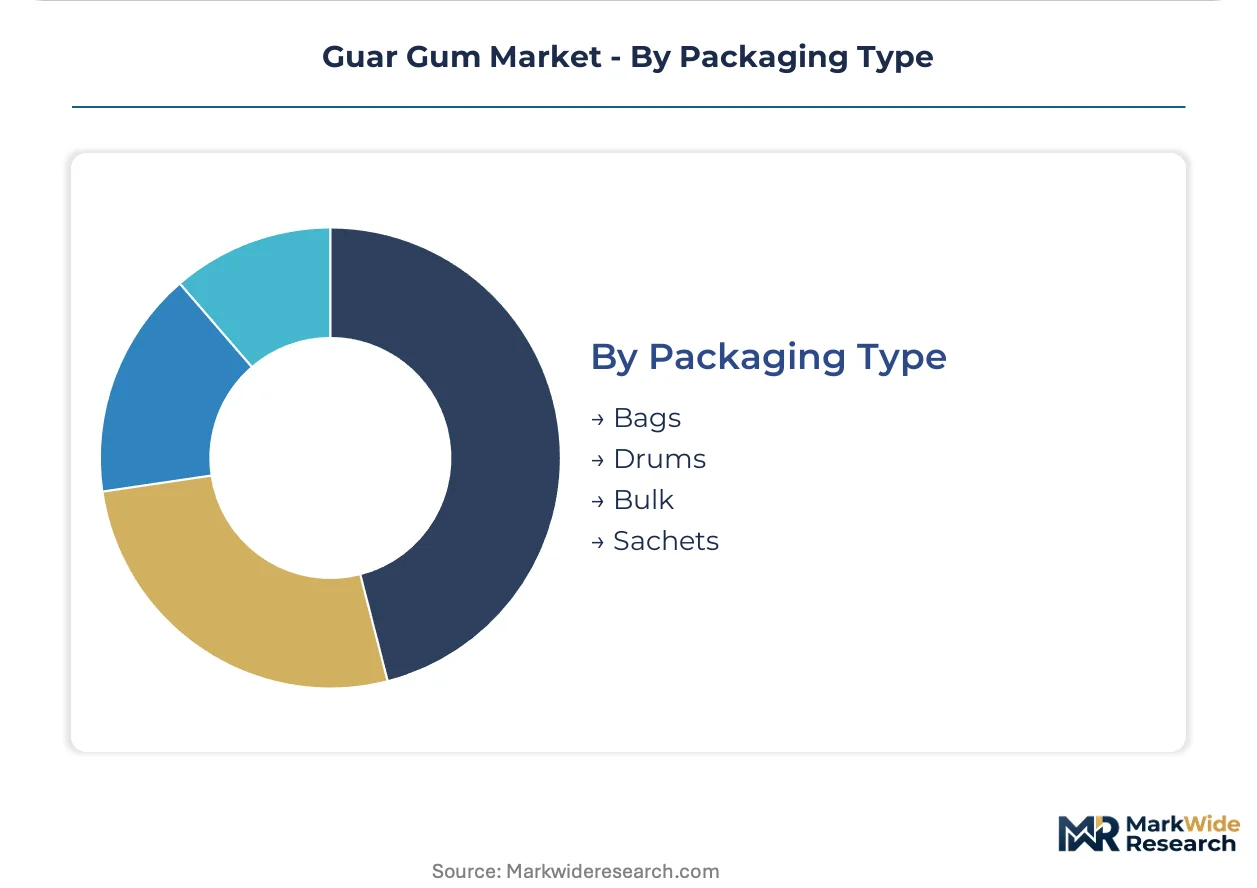
Packaging Type:
Supply chain configuration separates bulk commodity flows from precision-distribution channels.
- Bulk:Tanker and railcar deliveries serve Permian Basin drilling contractors with just-in-time inventory commitments. Rajasthan crushers with captive logistics capture this segment.
- Drums:Intermediate quantities for pharmaceutical and food manufacturing plants balance handling efficiency with lot traceability.
- Bags:Standard 25-50 kg woven polypropylene units dominate export shipments from Jodhpur processing clusters.
- Sachets:Retail and small-batch cosmetic formulators require pre-measured units with moisture barrier properties.
Logistics integration matters most for Bulk. Margin per kilogram peaks with Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan's Jodhpur corridor anchors guar gum processing capacity, concentrating over 80 percent of India's crushing infrastructure within a 200-kilometer radius. This geographic clustering shapes supply security calculations for North American oilfield service companies and European food manufacturers alike.
United States
Permian Basin operators in Texas and New Mexico absorb high-viscosity guar-based friction reducers for slickwater fracturing programs. The EPA regulates hydraulic fracturing fluid disclosure under state-level chemical reporting mandates. Houston-headquartered drilling contractors now source directly from Rajasthan processors through annual volume contracts, bypassing traditional fluid system intermediaries.
Germany
REACH-registered guar derivatives capture formulation slots in eco-labeled detergents and personal care products ahead of 2026 polymer re-registration deadlines. The ECHA documentation requirements filter out uncertified suppliers. Cologne and Düsseldorf formulators accelerate biodegradability-certified substitution trials for Green Deal-compliant product lines.
India
FSSAI tightened contaminant limits push Rajasthan processors toward certified export-ready production lines for European food manufacturers. BIS laboratory testing backlogs stretch food-grade approval timelines to 8-14 weeks. Jodhpur's processing clusters remain vulnerable to monsoon-dependent yield swings that create 15-40 percent annual production volatility.
United Arab Emirates
MOHAP pharmaceutical-grade import standards create a Gulf transshipment node for USP-certified excipients bound for Middle East healthcare markets. Dubai's free trade zones offer re-export advantages for Indian-origin guar derivatives. Local formulators prioritize traceable non-GMO documentation that direct farm-gate contracting from Rajasthan can satisfy.
Brazil
ANVISA pharmaceutical excipient regulations filter import eligibility for tablet binder applications in Latin America's largest healthcare market. São Paulo-based distributors serve as consolidation points for Indian-origin pharmaceutical-grade shipments. Domestic food manufacturers remain price-sensitive consumers of industrial-grade material for processed meat and dairy stabilization.
Guar Gum Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and direct farm-gate traceability agreements. The vendor base splits between integrated agricultural processors with captive Rajasthan crushing facilities and specialized refiners serving food and pharmaceutical purity benchmarks. Three archetypes dominate: seed-to-powder integrators controlling Jodhpur-area supply chains, FSSAI-certified exporters capturing European food manufacturer contracts, and oilfield-focused suppliers absorbing Permian Basin procurement consolidation. Capacity expansion and backward integration into farm-gate seed contracting represent the dominant competitive vectors.
Among India-based processors, Vikas WSP Ltd, Hindustan Gum & Chemicals Ltd, and Rama Gum Industries (India) Ltd exemplify the integrated archetype. These entities occupy positions within Rajasthan's Jodhpur processing belt, representing the concentration of domestic crushing infrastructure. Their structural positioning reflects the single-origin supply geography that defines industry risk profiles. Cargill, Incorporated anchors the agricultural trading tier, leveraging origination networks to secure raw seed supply ahead of regional crusher bidding. Lucid Colloids Ltd and Ingredion Incorporated sit within the international formulation supplier tier, bridging Indian-origin material with end-user specification requirements across multiple geographies.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Vikas WSP Ltd |
| Hindustan Gum & Chemicals Ltd |
| Lucid Colloids Ltd |
| Ingredion Incorporated |
| Neelkanth Polymers |
| India Glycols Ltd |
| Shree Ram Industries |
| Rama Gum Industries (India) Ltd |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between USP pharmaceutical and industrial oilfield specifications splits guar gum procurement into parallel pricing universes with distinct supply chain architectures. FSSAI-certified food-grade derivatives command premium spreads through documentary traceability requirements, while Permian Basin drilling contractors negotiate volume-based friction reducer contracts that compress margins through just-in-time inventory absorption.
Pricing Analysis
Service unbundling separates chemical procurement from integrated drilling contracts, forcing suppliers to absorb qualification and logistics costs previously covered by fluid system providers. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects purity documentation burdens and buyer concentration differentials. Pricing pressure stems from cellulose ether substitution in mid-viscosity oilfield slots where synthetic supply security guarantees displace natural polymer commitments. Oilfield service companies exhibit highest price sensitivity due to 18-24 month specification cycles without long-term purchase guarantees, while pharmaceutical formulators prioritize USP certification over cost minimization.
Supply Chain Analysis
Direct-to-processor channels handle consolidated drilling contractor demand through annual volume contracts bypassing traditional intermediaries. Geographic supply concentrates in India, specifically Rajasthan's Jodhpur processing belt, with secondary refining capacity in Germany and the United States for pharmaceutical-grade finishing. Raw material flows draw from monsoon-dependent guar seed harvests, synthetic polymer substitute availability, and REACH-registered biocide inputs for preservation. Single-origin concentration within a 200-kilometer processing radius creates systemic disruption exposure from Rajasthan drought or logistics chokepoints. Distribution runs through Jodhpur export clusters for bagged shipments, bulk tanker deliveries for Permian Basin contractors, and drum quantities for European pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Guar gum market economics function as a cost-of-compliance story where FSSAI purity mandates and REACH registration requirements erect barrier-to-entry moats that reward certified incumbents while filtering speculative entrants.
For Market Incumbents: Hedge monsoon yield volatility through backward integration into Rajasthan farm-gate seed contracting that secures non-GMO traceability documentation for European food manufacturers. Expand near-infrared spectroscopy automation at crushing facilities to compress BIS laboratory approval timelines and capture procurement relationships from capital-constrained mid-tier processors. Cellulose ether encroachment in mid-viscosity oilfield slots represents the priority threat requiring R&D investment in high-viscosity friction reducer formulations that synthetic alternatives cannot replicate. For New Entrants and Emerging Players: Enter via pharmaceutical-grade USP certification for controlled-release tablet binders, a segment underpenetrated versus gelatin and starch alternatives where incumbent processors lack dedicated capacity. Target direct farm-gate traceability agreements with Rajasthan smallholders that bypass Jodhpur spot markets and satisfy European food manufacturer non-GMO documentation requirements. Position through biodegradable certification for EU Green Deal-compliant personal care formulations where REACH re-registration deadlines accelerate natural thickener substitution trials. For Investors and Strategic Acquirers: Re-rating potential sits with integrated seed-to-powder processors possessing captive Rajasthan crushing facilities and established FSSAI export certifications, given tightening purity mandates that concentrate procurement toward qualified suppliers. Long-term viability across the analysis window hinges on pharmaceutical-grade capacity expansion and direct oilfield service company relationships that survive specification cycle turnover. Monitor cellulose ether market share progression in Permian Basin friction reducer applications as the inflection indicator for natural polymer pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Contracting | Secures non-GMO seed traceability that Jodhpur spot markets cannot satisfy for European food manufacturers. |
| Near-Infrared Spectroscopy Deployment | Automates real-time galactomannan verification at Rajasthan facilities to compress BIS approval timelines. |
| Pharmaceutical-Grade USP Certification | Captures premium spreads in controlled-release tablet binders where gelatin alternatives dominate. |
| REACH-Registered Biodegradability Certification | Qualifies guar derivatives for EU Green Deal procurement preferences in eco-labeled cleaning products. |
| Direct Annual Volume Contracts | Bypasses fluid system intermediaries to serve consolidated Permian Basin drilling contractors. |
Methodological Framework
Trade data from India's DGFT, FSSAI export certification records, and Rajasthan agricultural department harvest statistics formed the secondary backbone for supply-side modeling. Primary interviews with Rajasthan crushing facility operators, Permian Basin drilling contractor procurement leads, and European food manufacturer quality assurance directors validated secondary assumptions. Bottom-up triangulation across seed-to-powder processing costs and top-down cross-check against end-use consumption patterns anchored volume estimates.
Bottom-up segmentation modeling tracked pharmaceutical, food, industrial, and cosmetic grade tiers across oilfield, pharmaceutical, baking, and personal care applications. The analytical lens weighted monsoon-dependent yield volatility, REACH re-registration timelines, and fracking fluid formulation shifts as decisive variables. CAGRs derived from regression against rig count trajectories, purity mandate implementation schedules, and substitution elasticity parameters for cellulose ether alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Rajasthan drought conditions or accelerated cellulose ether penetration in Permian Basin friction reducer slots. Projections reflect assumptions regarding FSSAI enforcement consistency, BIS laboratory capacity expansion, and oilfield service company procurement consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitamin C Ingredients Market
Ingredients
Cocoa Fiber Market
Ingredients
Food Minerals Market
Ingredients
Low Calorie Oil Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Liquid Feed Market
Ingredients
Global Gelatin Market
Ingredients
Functional Flours Market
Ingredients
Cheese Ingredients Market
Ingredients
Carotenes Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Fruit Powder Market
Ingredients
Colombia Food Ingredients Market