
 South America Canned Fruits Market | 2026-2036
South America Canned Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
South America Canned Fruits Market Analytics
Private-label contract manufacturing is reshaping margin distribution across the South America Canned Fruits Market. Del Monte Foods leverages backward integration into tropical fruit sourcing to sustain cost advantages in pineapple processing. Dole plc anchors its regional position through controlled cold-chain logistics from Costa Rica and Ecuador into Brazilian port terminals. Conservas Oderich SA specializes in peach and pear varieties tailored to Mercosur consumer taste profiles.
Canned fruits comprise thermally processed tree and tropical fruits preserved in syrup, juice, or water within hermetically sealed containers, with pH levels and thermal processing parameters calibrated to inhibit microbial spoilage across ambient storage conditions. The product category serves retail households, industrial food manufacturers, and institutional food service operators requiring year-round ingredient availability independent of harvest cycles. Metal cans dominate packaging volume due to lower unit costs and established recycling infrastructure, though glass jars capture premium positioning in Brazilian and Argentine supermarket channels. Peaches and pineapples represent the most widely distributed product types, with pineapples registering faster volume growth linked to expanding juice bar and smoothie chain penetration in São Paulo and Rio de Janeiro.
ANVISA governs food safety standards and import registration requirements for canned fruits entering Brazil, while Argentina's national food code enforces parallel additive limits and origin labeling rules that non-Mercosur suppliers must satisfy. The EU-Mercosur trade agreement negotiations continue to influence tariff-rate quota allocations that affect Chilean and Thai competitor access to Brazilian buyers. Stakeholders must monitor evolving sodium and added-sugar reduction mandates across Brazilian and Argentine federal health agencies, as reformulation requirements could alter syrup formulations and processing economics for established product lines.
Market Dynamics
ANVISA's updated additive and labeling standards are compressing formulation flexibility for imported canned fruits while Brazilian food service operators accelerate procurement of shelf-stable tropical ingredients for bakery and dessert applications.
Growth Catalysts
- Urban retail density:São Paulo state and Buenos Aires province concentrate volume throughput through supermarket and hypermarket channels serving time-constrained households.
- EU-Mercosur trade negotiations:Tariff-rate quota allocations under discussion would alter competitive access for Chilean and Thai suppliers into Brazilian port terminals.
- Juice bar penetration:Smoothie chains across Rio de Janeiro and São Paulo are expanding pineapple procurement for year-round menu consistency independent of fresh harvest cycles.
Market Restraints
- Metal can input volatility:Tinplate and aluminum price swings directly compress processing margins for syrup-packed fruit lines.
- Origin labeling friction:Argentina's national food code enforces parallel additive limits that non-Mercosur suppliers must satisfy before customs clearance.
- Fresh fruit substitution:Improved cold-chain logistics from domestic producers threaten ambient shelf-stable positioning in premium supermarket tiers.
Strategic Opportunities
- Reduced-sugar reformulation:Brazilian federal health agency mandates on added-sugar reduction create first-mover advantage for processors recalibrating syrup formulations.
- Glass jar premiumization:Brazilian and Argentine supermarket channels reward hermetic glass packaging with shelf placement premiums and consumer willingness to pay.
- Industrial ingredient supply:Food manufacturers in Mercosur trade bloc seek captive suppliers of diced peach and pear for bakery and confectionery applications.
Industry Challenges
- Thermal process engineering talent:pH calibration and retort optimization expertise remains concentrated among legacy processors, constraining new facility commissioning.
- ANVISA registration timelines:Import registration requirements for novel additive formulations extend time-to-market for reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Canned Fruits Market |
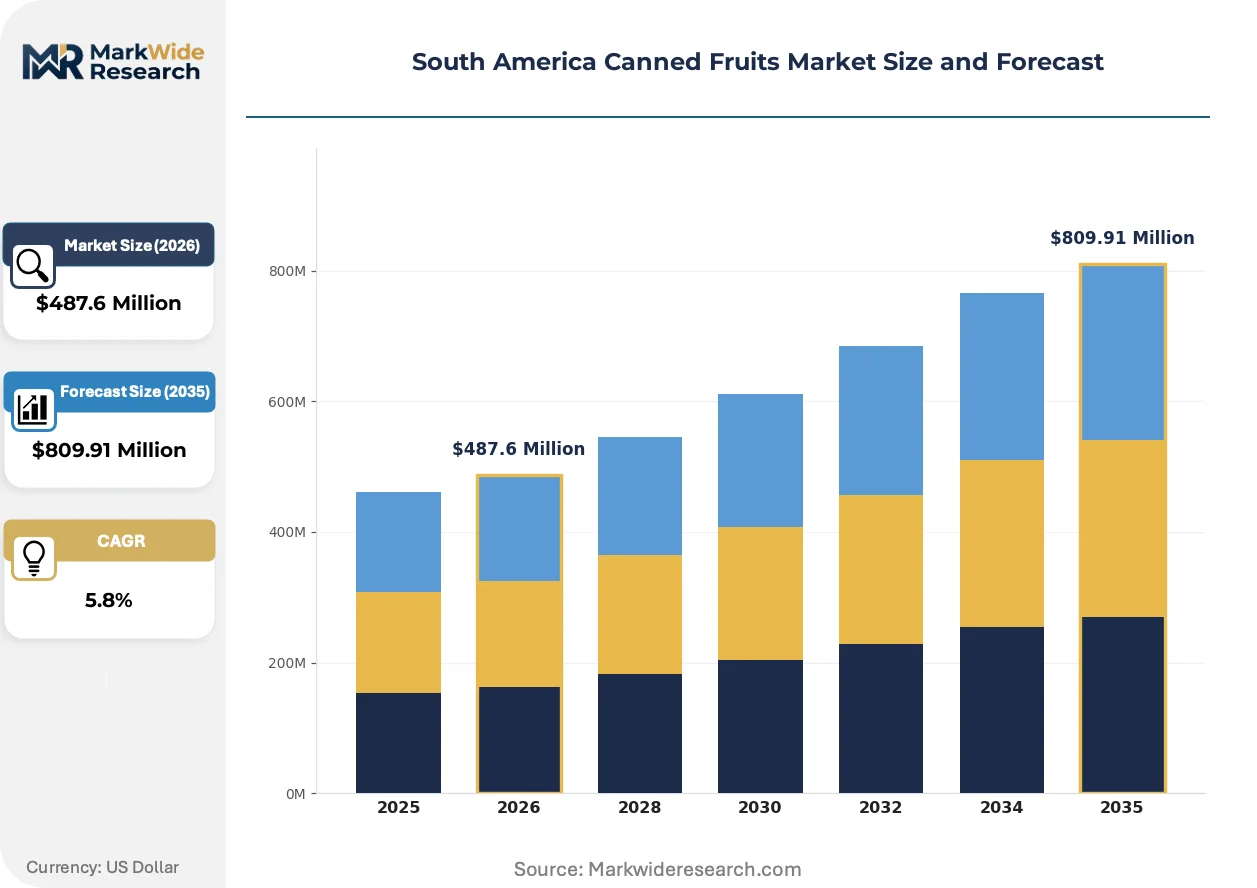
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peaches, Pears, Pineapples, Apricots Packaging Type: Glass Jars, Metal Cans, Tetra Packs, Pouches Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale End User: Households, Food Service, Retailers, Exporters |
| Companies Covered | Del Monte Foods, Inc., Dole plc, Conservas Oderich SA, Angelo Auriccho & CIA LTDA, Aconcagua Foods SA, ConAgra Foods, Kraft Heinz, Nestlé, Campbell Soup, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Canned Fruits Market Evolving Landscape
Processing technology and regulatory compliance requirements are converging to reshape competitive economics across Brazilian and Argentine canned fruit supply chains.
Aseptic bulk processing technology is collapsing the cost gap between ambient shelf-stable and refrigerated fruit preparations. Industrial food manufacturers in São Paulo's bakery cluster are adopting aseptic bag-in-box formats for diced pineapple and peach at accelerating pace. This compression is enabling contract manufacturers to displace traditional canning lines in ingredient supply contracts.
ANVISA's updated food additive standards are tightening maximum permissible levels for sulfite-based preservatives in imported canned fruits. Processors must reformulate with alternative antimicrobial systems or face detention at Brazilian port terminals. Argentine suppliers with established Mercosur certification pathways are capturing displaced volume from Asian competitors.
Food service procurement is consolidating around specification-grade contracts with guaranteed brix and acidity tolerances. Chain bakery and dessert operators in Buenos Aires province are replacing spot market purchasing with annual volume agreements tied to sensory consistency metrics. This specification-driven sourcing is most visible among franchised juice bar networks expanding across southeastern Brazil.
South America Canned Fruits Market Segmentation
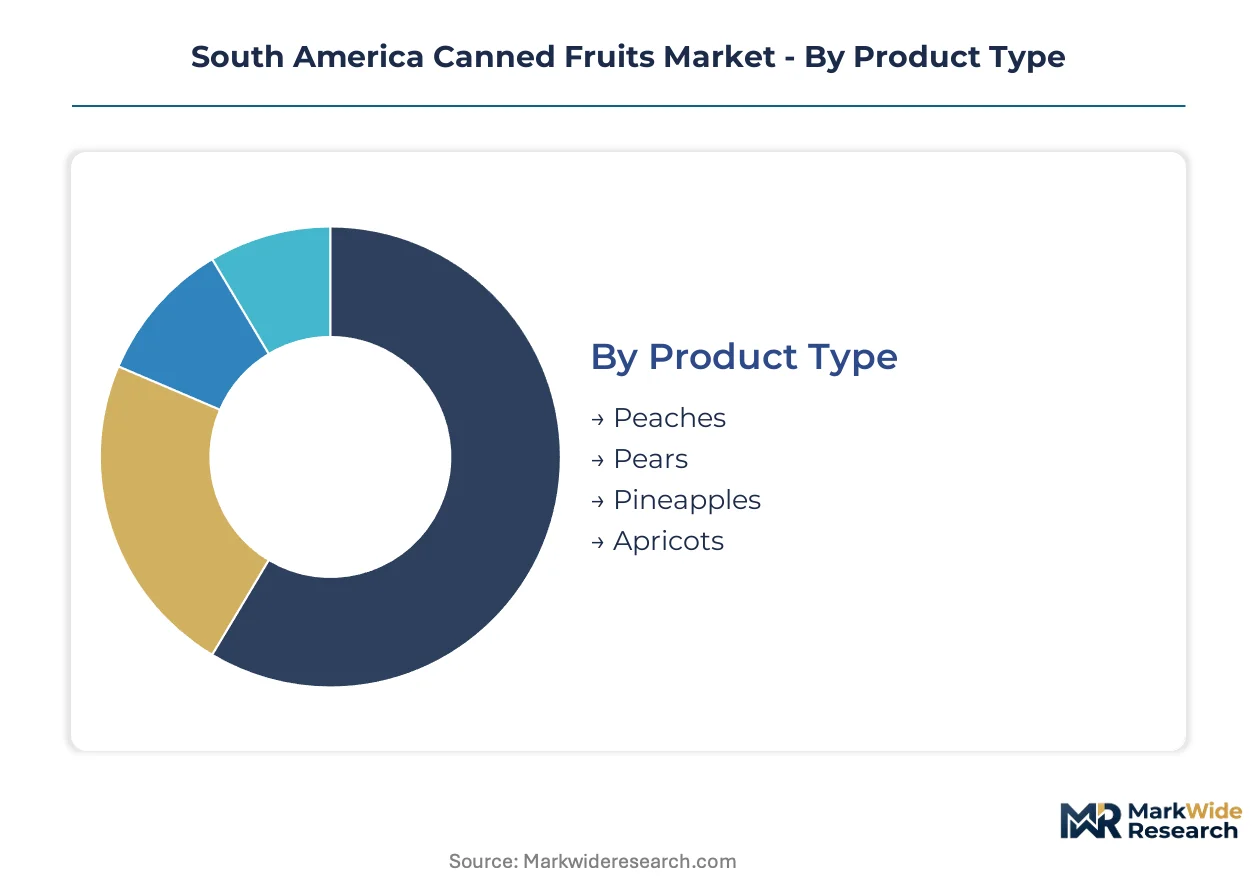
Segmentation reveals how procurement patterns diverge across South American markets. Product type and packaging format choices directly reflect channel economics and regulatory constraints. Understanding these splits enables targeted positioning against ANVISA compliance requirements and food service specification demands.
Product Type:
Application-driven demand splits across fruit varieties reveal distinct supply chain and processing economics for tropical versus temperate origin products.
- Peaches:Yellow-fleshed clingstone varieties dominate Mercosur formulations due to superior texture retention through thermal processing. São Paulo's bakery cluster and Buenos Aires dessert manufacturers specify calibrated brix levels for year-round ingredient consistency. Argentine processors in Mendoza province leverage established orchard relationships to secure contract volumes.
- Pineapples:Costa Rica and Ecuador supply the majority of tropical feedstock entering Brazilian port terminals. Juice bar chains across Rio de Janeiro and São Paulo drive specification-grade procurement for smoothie applications independent of fresh harvest windows. ANVISA's sulfite limits are forcing reformulation of traditional preservation protocols.
- Pears:Bartlett and d'Anjou varieties serve premium supermarket tiers in Brazilian glass jar presentations.
- Apricots:Limited commercial volumes concentrate in Argentine domestic consumption and specialty export preparations.
Peaches command the established base. The steepest expansion runs through pineapples.
Packaging Type:
Cost tier differentiation across material formats shapes margin capture and shelf placement economics in Brazilian and Argentine retail channels.
- Metal Cans:Tinplate and aluminum formats deliver lowest unit cost and leverage established recycling infrastructure across Mercosur markets. São Paulo state hypermarkets move volume through economy-tier private label lines. Input price volatility for steel and aluminum directly compresses processor margins.
- Glass Jars:Hermetic sealing and visual product clarity support premium positioning in Brazilian and Argentine supermarket channels. Buenos Aires province retailers reward glass packaging with preferred shelf placement and consumer willingness to pay. Higher freight costs limit distribution radius from production facilities.
- Tetra Packs:Aseptic carton formats gain traction in industrial ingredient supply for food manufacturers seeking ambient storage efficiency.
- Pouches:Flexible packaging remains niche, concentrated in food service portion-control applications and export-oriented convenience formats.
Metal cans anchor volume throughput. Glass jars are climbing the fastest on margin contribution.
Distribution Channel:
Customer type concentration determines service level requirements and working capital intensity across the South American canned fruits supply chain.
- Supermarkets:Hypermarket and supermarket chains in São Paulo state and Buenos Aires province consolidate household purchasing through promotional calendar alignment. Private label contract manufacturing is displacing branded volume in standard fruit lines. Slotting fees and listing requirements create barrier to entry for new suppliers.
- Food Service:Chain bakeries, dessert operators, and juice bar networks are replacing spot market purchasing with annual specification contracts tied to sensory consistency metrics. Procurement consolidation around brix and acidity tolerances favors processors with laboratory quality control capabilities.
- Online Retailers:E-commerce penetration remains limited by shipping economics for heavy, liquid-containing formats.
- Convenience Stores:Small-format retail in Brazilian urban centers moves single-serve and impulse-oriented pack sizes.
- Wholesale:Cash-and-carry operators serve independent food service accounts and regional retailers outside major metropolitan corridors.
Supermarkets retain the volume base. Food service is gaining share fastest on contract consolidation.
End User:
Volume scale and specification stringency create divergent margin profiles across household, industrial, and export-oriented demand segments.
- Households:Time-constrained urban consumers in São Paulo and Buenos Aires metro areas prioritize shelf stability and preparation convenience over fresh alternatives. Retail purchasing concentrates around promotional cycles and seasonal dessert preparation occasions.
- Food Service:Industrial food manufacturers and chain operators require captive suppliers of diced and sliced formats with guaranteed dimensional tolerances for automated production lines. Specification-grade contracts now dominate procurement for bakery and confectionery applications.
- Retailers:Private-label program operators seek backward integration into tropical sourcing to sustain cost advantages against branded competitors.
- Exporters:Mercosur-origin products face origin labeling friction in non-bloc destinations, with Argentine and Brazilian federal codes enforcing additive disclosure requirements that Asian competitors struggle to satisfy.
Households anchor the consumption base. Food service is expanding most quickly on specification-driven contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian buyers exhibit the highest price elasticity in São Paulo's hypermarket channels, while Argentine food service operators in Buenos Aires province absorb premium pricing for specification-grade contracts tied to sensory consistency metrics.
Brazil
São Paulo state concentrates volume throughput through supermarket and hypermarket chains serving time-constrained households. ANVISA's updated food additive and labeling standards tighten compliance requirements for imported canned products entering Brazilian port terminals. Rio de Janeiro's juice bar networks are expanding pineapple procurement for year-round menu consistency independent of fresh harvest cycles.
Argentina
Buenos Aires province anchors demand from chain bakeries and dessert operators replacing spot market purchasing with annual volume agreements. The national food code enforces additive limits and origin labeling rules that non-Mercosur suppliers must satisfy before customs clearance. Mendoza province processors leverage established orchard relationships to secure contract volumes of yellow-fleshed clingstone peach varieties.
Chile
Central Valley fruit processors face tariff-rate quota uncertainty as EU-Mercosur trade negotiations continue to influence competitive access to Brazilian buyers. The country's national food regulator enforces parallel standards on sulfite-based preservatives that align with Mercosur bloc requirements. Santiago-based exporters are repositioning toward specification-grade industrial ingredient contracts as retail margin compression intensifies.
Colombia
Bogotá's urban retail corridors are developing procurement infrastructure for ambient shelf-stable fruit formats targeting household convenience segments. The national health institute maintains additive disclosure requirements that imported products must satisfy. Antioquia department's emerging food manufacturing cluster is testing captive supply arrangements for diced tropical fruit ingredients.
Peru
Lima's food service distributors are consolidating procurement around brix-calibrated pineapple and peach preparations for bakery and confectionery applications. The country's sanitary authority enforces origin labeling friction that Asian competitors struggle to navigate. Coastal agricultural valleys are expanding cold-chain infrastructure that threatens ambient shelf-stable positioning in premium supermarket tiers.
South America Canned Fruits Market Competitive Landscape
Multinational processors and regional specialists split the market between scale-driven cost positions and Mercosur certification proximity. Consolidation pressures concentrate among legacy canning operations with established ANVISA registration pathways, while contract manufacturers exploit aseptic bulk technology to displace traditional lines. Three archetypes dominate: tropical-source backward integrators, temperate-fruit regional processors, and specification-grade industrial ingredient suppliers. Capacity rationalization and private-label contract manufacturing represent the dominant competitive moves reshaping margin distribution.
Within the tropical-source tier, Del Monte Foods and Dole plc exemplify scale-driven positioning through controlled logistics and sourcing infrastructure. Del Monte leverages backward integration into pineapple supply chains to sustain cost advantages in processing economics. Dole anchors regional distribution through cold-chain logistics from Central American origins into Brazilian port terminals. Conservas Oderich SA occupies a specialist position focused on peach and pear varieties calibrated to Mercosur consumer taste profiles. These three entities represent distinct strategic postures: multinational scale, logistics integration, and regional specialization.
| Leading Market Players |
|---|
| Del Monte Foods, Inc. |
| Dole plc |
| Conservas Oderich SA |
| Angelo Auriccho & CIA LTDA |
| Aconcagua Foods SA |
| ConAgra Foods |
| Kraft Heinz |
| Nestlé |
| Campbell Soup |
| Others |
Value Network & Pricing Analysis
Overcapacity in Brazilian tinplate can manufacturing is compressing processor margins while forcing suppliers toward specification-grade contracting to defend pricing power. São Paulo state hypermarkets exploit this surplus to extract promotional concessions, while Argentine glass jar producers leverage freight-cost barriers to sustain premium positioning.
Pricing Analysis
After-sales ingredient supply contracts now drive lifetime value for industrial food manufacturers seeking guaranteed brix calibration. Three-tier pricing structure across premium glass, standard metal, and economy private-label levels stratifies by packaging material and certification grade. Pricing pressure stems from ANVISA's reformulation mandates requiring alternative preservative investments. Food service operators in Buenos Aires province exhibit lowest price sensitivity due to sensory consistency requirements, while São Paulo households maximize promotional responsiveness.
Supply Chain Analysis
Tariff exposure between Thailand and Brazil under pending EU-Mercosur negotiations dominates supply chain risk planning for imported pineapple feedstock. Costa Rica, Ecuador, and Argentina concentrate tropical and temperate fruit supply, with raw material dependencies centering on tinplate, aluminum, and sulfite-free preservative alternatives. Single-source vulnerability runs through Costa Rican pineapple logistics corridors into Santos port terminals. Distribution runs through São Paulo hypermarket chains and Buenos Aires cash-and-carry wholesalers serving independent food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's sulfite-limit enforcement is disrupting established preservation protocols and opening first-mover windows for reformulation-capable processors. This regulatory inflection accelerates competitive turnover across the South America Canned Fruits Market.
For Market Incumbents: Harden ANVISA registration pathways by pre-positioning alternative antimicrobial formulations ahead of compliance deadlines. Expand backward integration into Mendoza province peach orchards to secure contract volumes against Argentine processors. Channel control through exclusive glass jar shelf placement agreements in Buenos Aires supermarkets represents the critical defensive lever. For New Entrants and Emerging Players: Aseptic bag-in-box industrial ingredient supply to São Paulo bakery clusters represents the most penetrable entry point for bypassing legacy canning capital requirements. Specification-grade diced pineapple contracts for juice bar chains offer volume visibility independent of retail slotting barriers. Go-to-market execution should anchor on laboratory quality control capabilities that satisfy food service brix and acidity tolerances. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with locked annual volume agreements from chain bakery and dessert operators. Long-term viability across the analysis window favors acquisition targets with established Mercosur certification pathways and retort optimization engineering talent. Monitor EU-Mercosur tariff-rate quota allocations as the critical inflection signal for competitive access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Sugar Reformulation | ANVISA compliance mandates create first-mover positioning for processors recalibrating syrup formulations. |
| Backward Integration into Orchards | Mendoza province peach sourcing secures contract volumes against Argentine regional competitors. |
| Aseptic Bulk Technology Adoption | Bag-in-box formats displace traditional canning lines in São Paulo bakery cluster ingredient contracts. |
| Glass Jar Premiumization | Hermetic sealing commands shelf placement premiums in Brazilian and Argentine supermarket channels. |
| Specification-Grade Contracting | Locked annual agreements with food service operators convert spot purchasing into recurring revenue streams. |
Research Methodology
Initial hypotheses were tested against primary input from fruit processing plant managers, ANVISA regulatory affairs specialists, São Paulo supermarket category buyers, and Buenos Aires food service procurement directors and refined through customs trade data, ANVISA registration filings, Mercosur tariff schedules, and SEC processor disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, distribution channel, and end-user segmentation dimensions.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Fruit variety splits, preservative reformulation timelines, and cold-chain infrastructure buildout curves served as industry-specific forecast inputs throughout the modeling period.
Practitioners should monitor EU-Mercosur negotiation outcomes, ANVISA additive standard revisions, and domestic fresh fruit cold-chain expansion for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Canned Goods Market
Packaged Foods
Freekeh Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Instant Cereals Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Global Food Spread Market
Packaged Foods
North America Pasta and Noodles Market