
 Custom Dry Ingredients Blends Market | 2026-2036
Custom Dry Ingredients Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Dry Ingredients Blends Market Analysis
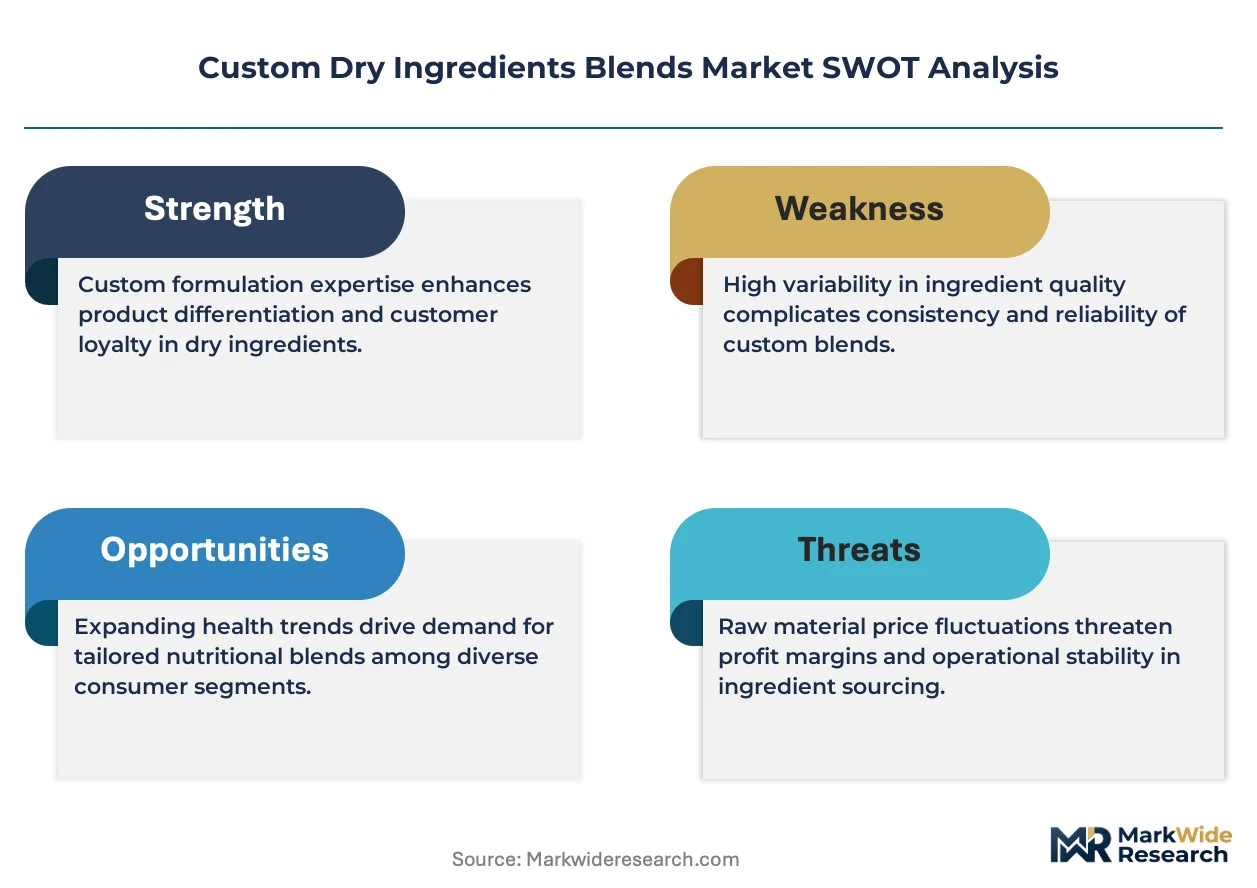
The divergence between premium custom blends and commodity dry mixes is realigning procurement strategies across food manufacturing. H T Griffin Food Ingredients leverages vertical integration into spice sourcing to sustain margin control on high-heat flavor systems. Stewart Ingredient Systems Inc anchors its position through specialized blending equipment that competes on precision tolerances for bakery applications. Rocky Mountain Spice Company differentiates via regional flavor profiles that dominate Southwestern and Latin American taste categories.
Custom dry ingredients blends comprise precisely proportioned mixtures of seasonings, flavorings, powdered ingredients, and stabilizers formulated to specific functional parameters such as particle size distribution, moisture activity below 0.6, and shelf-life stability. These blends serve industrial food production by standardizing taste, texture, and preservation across batch-scale manufacturing. Seasonings and stabilizers command the strongest margin pools as food manufacturers prioritize clean-label emulsification and sodium reduction without compromising structural integrity. Powdered ingredients in beverage applications represent the fastest-growing consumption vector, driven by ready-to-drink protein fortification and plant-based milk alternatives. The granules and powders form factor leads volume due to superior flowability in automated dispensing systems and reduced caking during extended storage.
The FDA enforces Current Good Manufacturing Practice and Hazard Analysis Critical Control Point standards that dictate microbial limits and allergen segregation protocols for domestic blend production. The EPA oversees volatile organic compound emissions from spray-drying operations, while FSMA's Foreign Supplier Verification Program shapes import sourcing decisions for offshore ingredient procurement. Stakeholders must monitor evolving state-level packaging waste regulations and third-party certification requirements as non-negotiable market access conditions.
Market Dynamics
Clean-label reformulation mandates from the FDA and EFSA are forcing food manufacturers to replace synthetic stabilizers with plant-derived alternatives, compressing formulation cycles and rewiring supplier qualification protocols across industrial baking and beverage production.
Growth Catalysts
- FSMA Foreign Supplier Verification Program:The FDA's enforcement of offshore ingredient auditing is accelerating domestic blend production capacity expansion as manufacturers seek to eliminate import compliance latency.
- Plant-based milk alternatives:Oat, pea, and almond protein fortification in ready-to-drink formats is pulling powdered stabilizer volumes into beverage applications at rates outpacing traditional bakery demand.
- EU Green Deal-aligned sourcing:Carbon footprint disclosure requirements for agricultural inputs are concentrating procurement toward vertically integrated spice and herb suppliers with certified sustainable cultivation.
Market Restraints
- Input cost volatility:Weather-driven supply shocks in Vietnamese black pepper and Indian turmeric are destabilizing seasoning blend margins without contract hedging mechanisms.
- Supply concentration risk:Spray-drying capacity for heat-sensitive flavor encapsulation clusters in the US Midwest and northern Italy, creating single-point vulnerability for European and North American customers.
- Technical limitation:Clean-label emulsification systems currently fail to match the shelf-life extension of synthetic alternatives in high-fat bakery applications, constraining reformulation depth.
Strategic Opportunities
- Underpenetrated geography:Brazil's industrial baking sector lacks localized custom blend infrastructure, creating first-mover advantage for suppliers establishing São Paulo-area production.
- Regulatory tailwind:China's dual carbon goals and SAMR clean-label guidelines are mandating sodium reduction and natural preservative adoption, opening formulation service contracts with domestic food processors.
- Technology convergence:Precision fermentation-derived proteins combined with traditional spice matrices are enabling novel functional blends for sports nutrition and clinical food segments.
Industry Challenges
- Certification timeline compression:Third-party organic and non-GMO verification cycles now exceed product development windows, forcing parallel-track qualification that strains quality assurance staffing.
- Legacy equipment incompatibility:Automated dispensing systems designed for synthetic stabilizer flow properties require retrofitting to handle hygroscopic plant-based alternatives without caking or segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Dry Ingredients Blends Market |
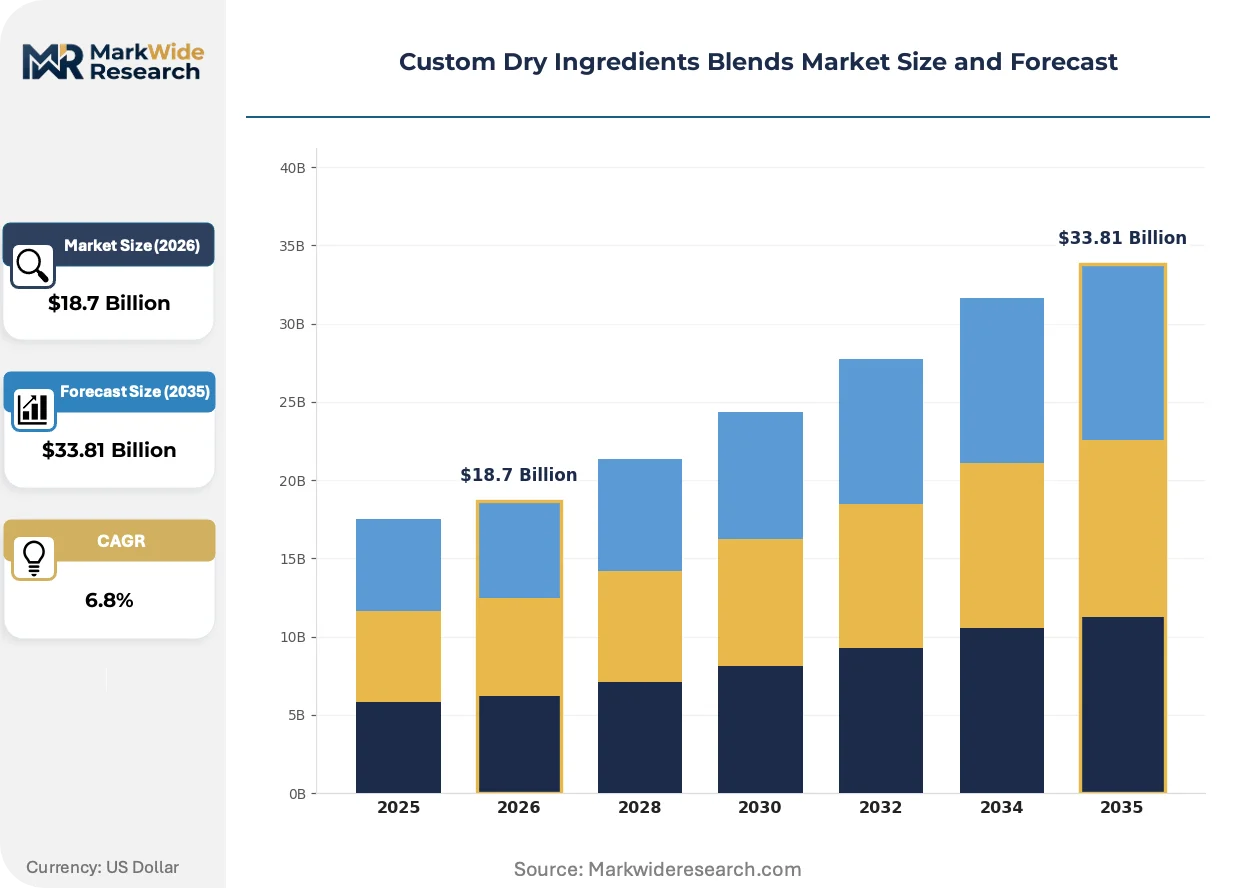
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasonings, Flavorings, Powdered Ingredients, Stabilizers Application: Baking, Snacks, Beverages, Sauces End User: Food Manufacturers, Restaurants, Retailers, Bakeries Form: Granules, Powders, Flakes, Crystals |
| Companies Covered | H T Griffin Food Ingredients, Stewart Ingredient Systems Inc, ABS Food Ingredients, Rocky Mountain Spice Company, Brisan Group, JES Foods, Pacific Blends Ltd., All Seasonings Ingredients Inc, Blendex Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Dry Ingredients Blends Market Emerging Trajectories
Reformulation science is converging with digital quality control to compress development cycles, while regulatory disclosure requirements and shifting procurement models are rewiring how blend specifications reach industrial kitchens.
Encapsulation technologies using modified starch and lipid matrices are overtaking traditional spray-dried flavor systems in heat-stressed applications. Bakery manufacturers in Germany and the United States are adopting these systems at pilot scale now, with full production integration expected within eighteen months. This shift is overtaking commodity flavor houses that lack precision particle engineering capabilities, compressing their addressable market to low-heat beverage applications.
REACH registration requirements for novel food contact substances are extending approval timelines for new encapsulation materials entering the European Union. Industrial blenders must now submit full toxicological dossiers for any ingredient above 0.1% concentration in finished formulations. Bakery and savory snack segments are responding by reverting to grandfathered ingredient lists, slowing innovation velocity in the EU relative to North American markets.
Direct specification contracts between food manufacturers and raw material growers are displacing traditional spice merchant intermediaries in high-value seasoning procurement. Large-scale processors in the United States and China are contracting directly with Malabar pepper estates and Madagascar vanilla cooperatives, capturing traceability data for ESG reporting. This disintermediation is most visible in premium clean-label lines where lot-level blockchain verification commands shelf price premiums.
Custom Dry Ingredients Blends Market Segmentation
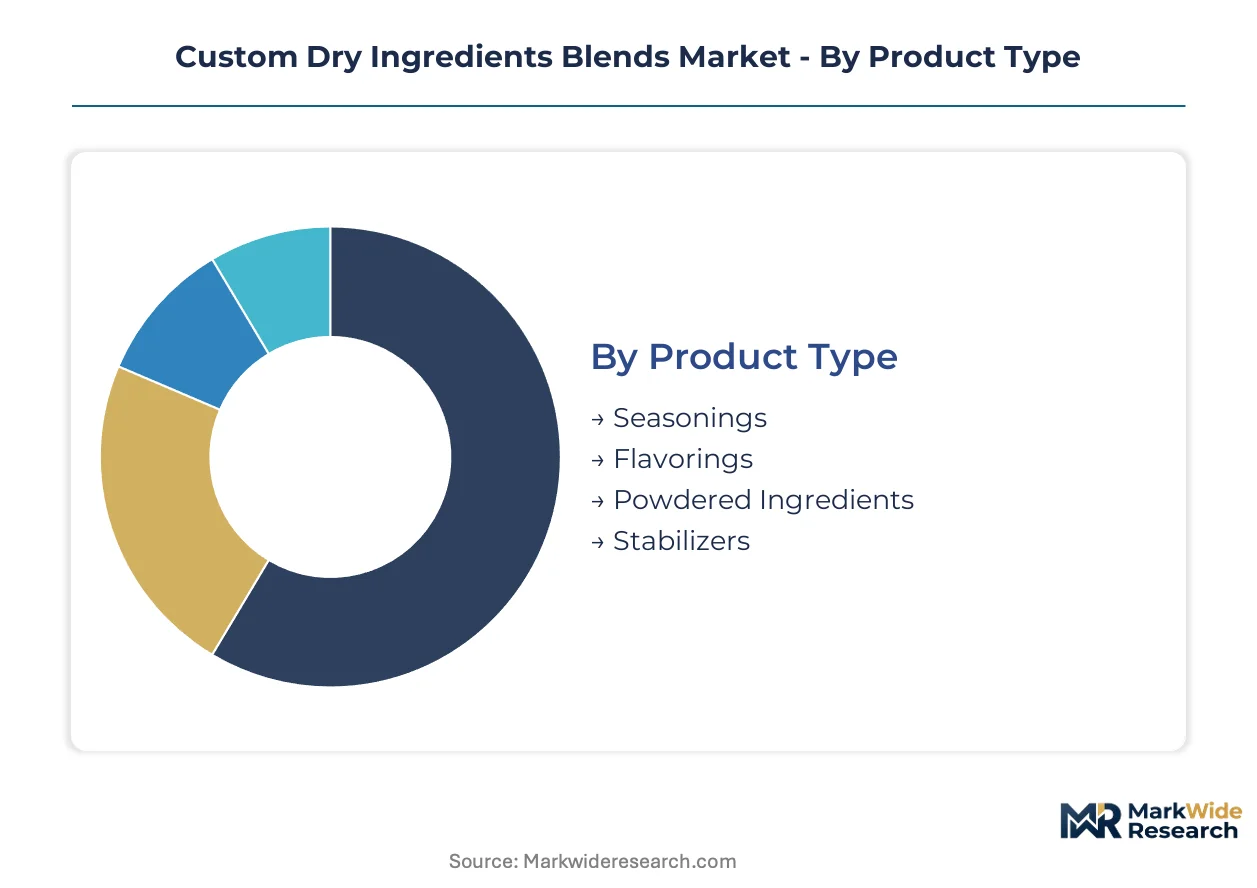
Segmentation in custom dry ingredients blends determines which formulation specifications trigger distinct regulatory pathways and which customer types command premium service tiers. Procurement managers segment by product type to align with FDA allergen controls and by application to match equipment compatibility constraints.
Product Type:
Certification burdens vary sharply across product types, with organic and non-GMO verification timelines stretching longest for spice-derived seasonings and shortest for mineral-based stabilizers.
- Seasonings:Spice and herb matrices requiring heat-stable volatile oil retention. Demand concentrates in United States Southwest and Latin American regional profiles where clean-label sodium reduction mandates from the FDA drive reformulation. Certification cycles for organic pepper and turmeric now exceed eighteen months.
- Flavorings:Encapsulated and spray-dried systems delivering taste impact at low use rates. German and United States bakery manufacturers are adopting modified starch encapsulation for heat-stressed applications, outpacing traditional spray-dried houses lacking precision particle engineering.
- Powdered Ingredients:Protein fortification matrices and plant-based milk alternatives.
- Stabilizers:Emulsification and texture modification systems, synthetic and plant-derived.
Seasonings sit at the top of the volume ranking, with powdered ingredients climbing the fastest.
Application:
Cost tier differentiation separates high-specification baking blends from commodity snack seasonings, with beverage applications commanding the steepest price premiums for heat-stable protein systems.
- Baking:Precision-tolerance blends for structural integrity in high-fat and clean-label formulations. United States and German industrial bakers are retrofitting automated dispensing systems to handle hygroscopic plant-based stabilizers without caking.
- Beverages:Ready-to-drink protein fortification and plant-based milk alternatives. Oat, pea, and almond protein volumes are expanding most quickly in North American and Chinese markets where SAMR guidelines mandate sodium reduction.
- Snacks:Seasoning adherence systems for extruded and fried products.
- Sauces:Hydration-stable thickeners and flavor dispersion matrices.
Baking commands the largest revenue pool, with beverages gaining share fastest.
End User:
Customer type determines service intensity, with food manufacturers requiring full formulation partnerships and retailers accepting off-the-shelf blends with limited technical support.
- Food Manufacturers:Large-scale processors seeking direct grower contracts and lot-level traceability. United States and China-based manufacturers are disintermediating spice merchants by contracting directly with Malabar pepper estates and Madagascar vanilla cooperatives for ESG reporting data.
- Bakeries:Mid-scale operations requiring precision tolerances for automated production lines. Equipment retrofit costs for plant-based stabilizer flow properties concentrate demand among vertically integrated suppliers.
- Restaurants:Foodservice operators with limited R&D capacity.
- Retailers:Private-label brands seeking speed-to-market with reduced technical specification.
Food manufacturers dominate procurement value, with bakeries expanding most quickly in regional flavor localization.
Form:
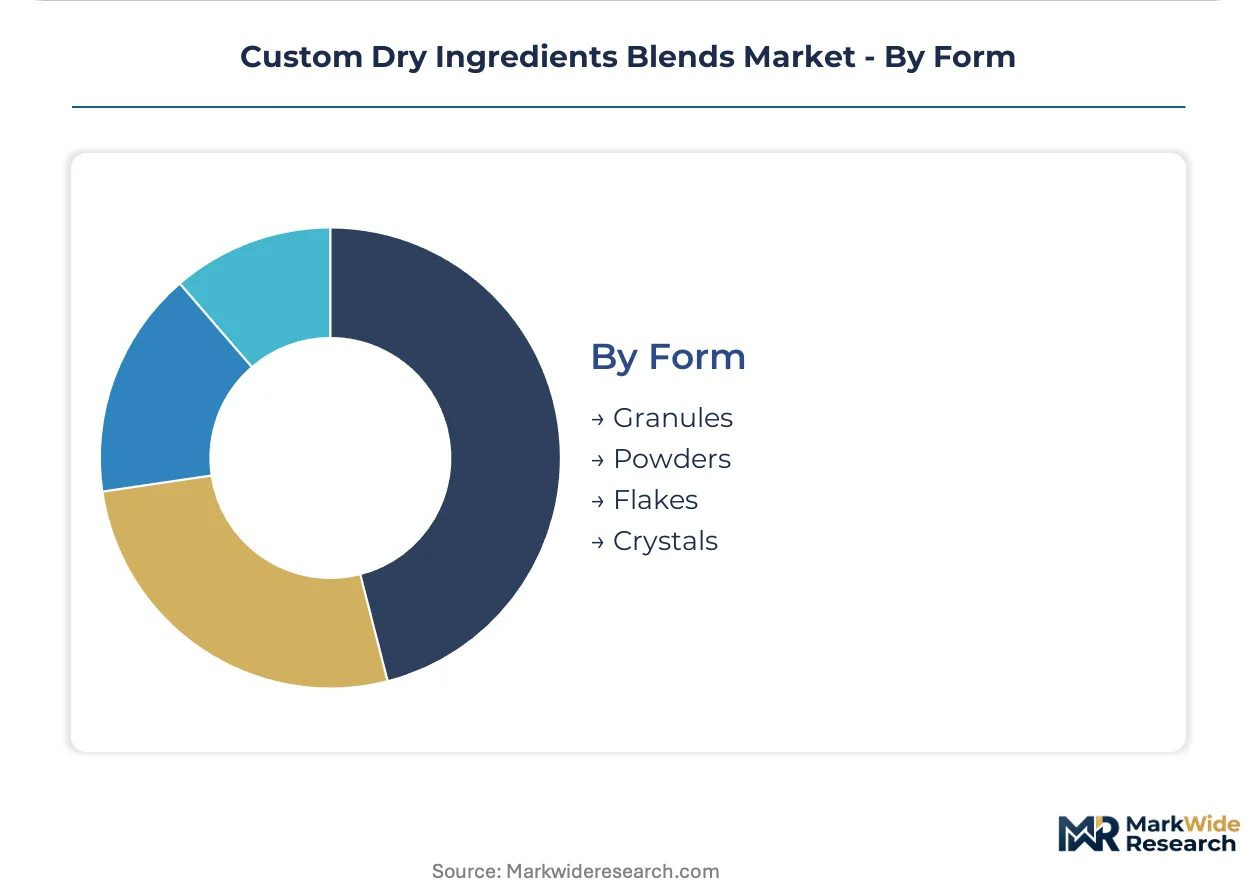
Supply concentration for spray-drying capacity shapes form selection, with granule and powder production clustering in the United States Midwest and northern Italy.
- Granules:Agglomerated particles optimized for flowability in high-speed dispensing. Automated bakery lines in Germany and the United States specify granule form to prevent segregation during extended storage.
- Powders:Fine particle systems for rapid hydration and uniform dispersion. Beverage applications in China and the United States are pulling powder volumes for protein fortification at rates outpacing traditional bakery demand.
- Flakes:Visual texture elements for topical seasoning applications.
- Crystals:Dissolution-controlled systems for controlled-release flavor.
Granules lead volume due to superior flowability, with powders climbing fastest on beverage demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and flavor chemists cluster in the United States, Germany, and China, anchoring the industry's formulation expertise and pilot-scale testing infrastructure.
United States
Industrial bakers in Chicago and Minneapolis retrofit automated dispensing systems for hygroscopic plant-based stabilizers. The FDA enforces FSMA Foreign Supplier Verification Program audits that compress procurement timelines toward domestic blend production. Spray-drying capacity concentrates in the Midwest corridor, serving beverage fortification demand from oat and pea protein startups.
Germany
Precision-tolerance bakery applications in Bavaria and North Rhine-Westphalia drive specification contracts for heat-stable encapsulation systems. EFSA clean-label mandates accelerate reformulation away from synthetic emulsifiers. REACH registration requirements for novel food contact substances extend approval timelines, pushing manufacturers toward grandfathered ingredient portfolios.
China
Ready-to-drink protein fortification in Shanghai and Guangzhou pulls powdered stabilizer volumes at rates outpacing traditional bakery demand. SAMR sodium reduction guidelines and dual carbon goals mandate natural preservative adoption. Domestic food processors seek localized formulation partnerships to replace import-dependent seasoning supply chains.
Brazil
São Paulo's industrial baking sector lacks localized custom blend infrastructure, creating first-mover positioning for suppliers establishing regional production. ANVISA alignment with international food safety standards reshapes import qualification protocols. Direct grower contracts for black pepper and tropical spices displace traditional merchant intermediaries in premium clean-label procurement.
India
Malabar pepper estates and turmeric cultivation regions in Kerala and Karnataka attract direct specification contracts from multinational food manufacturers. FSSAI enforcement of contaminant limits and allergen labeling accelerates domestic blending capacity investment. Mumbai and Delhi processing clusters specialize in heat-stable seasoning matrices for export-oriented savory snack production.
Custom Dry Ingredients Blends Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the custom dry ingredients blends market. Vertically integrated spice processors with captive agricultural sourcing anchor the premium tier, while specialized blending houses compete on precision equipment and formulation speed. The structure fragments across three archetypes: upstream-controlled ingredient suppliers, precision-engineering blend specialists, and regional flavor profile curators. Capacity expansion in spray-drying clusters and backward integration into spice origins constitute the dominant competitive vectors.
Among North American specialists, H T Griffin Food Ingredients and Rocky Mountain Spice Company occupy positions within the upstream-controlled and regional-curator archetypes respectively. Stewart Ingredient Systems Inc exemplifies the precision-engineering tier through its specialized blending equipment focus. European presence includes ABS Food Ingredients and Brisan Group, representing scale-driven formulation service models. These named entities anchor industry-level patterns without constituting exhaustive market coverage.
| Leading Market Players |
|---|
| H T Griffin Food Ingredients |
| Stewart Ingredient Systems Inc |
| ABS Food Ingredients |
| Rocky Mountain Spice Company |
| Brisan Group |
| JES Foods |
| Pacific Blends Ltd. |
| All Seasonings Ingredients Inc |
| Blendex Company |
| Others |
Supply Flow & Price Mechanics
Premium-clean-label certification ladders bifurcate procurement economics, with USDA Organic and Non-GMO Project verified blends commanding three-to-five-fold premiums over conventional commodity mixes while concentrating supply relationships among vertically integrated spice processors with captive agricultural sourcing. This tier divergence funnels large-scale food manufacturers toward direct grower contracts for Malabar pepper and Madagascar vanilla, compressing merchant intermediary margins and rewiring working capital requirements across the value chain.
Pricing Analysis
Bundled formulation services versus unbundled commodity supply splits the pricing architecture, with full-service partnerships incorporating R&D co-development, lot-level traceability, and regulatory dossier preparation sitting atop the value pyramid. Price differentiation rests on certification grade and customization depth, with SAMR-aligned sodium reduction formulations and ESG-verified spice origins extracting premiums. Cost compression in mid-tier stabilizer blends is intensifying because Vietnamese black pepper and Indian turmeric weather shocks transmit directly into unhedged contract positions. Private-label retailers exhibit acute price sensitivity, while multinational food manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse logistics for expired or non-conforming seasoning lots remains underdeveloped, with most processors landfilling out-of-specification blends rather than recovering volatile oils or reprocessing spice matrices. Geographic supply concentration clusters in Vietnam for black pepper, India for turmeric and cumin, and Madagascar for vanilla, with spray-drying capacity for heat-sensitive encapsulation anchored in the United States Midwest and northern Italy. Raw material dependencies draw from tropical spice origins, fossil-fuel-derived modified starches, and precision fermentation-derived proteins. Single-source vulnerability pervades the Italian spray-drying corridor, where equipment failure or energy disruption cascades across European bakery supply chains. Distribution runs through direct specification contracts between food manufacturers and agricultural cooperatives, disintermediating traditional spice merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where clean-label reformulation mandates from the FDA and EFSA have shifted procurement priority toward certified sustainable sourcing and precision-tolerance blending capabilities. Food manufacturers now prioritize supplier qualification depth over transactional cost minimization.
For Market Incumbents: Extend backward integration into Malabar pepper estates and Madagascar vanilla cooperatives to lock in traceability data for ESG reporting and capture shelf-price premiums. Add spray-drying capacity in the United States Midwest to eliminate European single-point vulnerability. Certification investment in USDA Organic and Non-GMO Project verification defends margin position against commodity blend competitors facing eighteen-month approval timelines. For New Entrants and Emerging Players: Capture São Paulo-area production capacity to serve Brazil's underpenetrated industrial baking sector before ANVISA alignment with international standards hardens import barriers. Target ready-to-drink protein fortification in Chinese beverage applications where SAMR sodium reduction guidelines mandate natural preservative adoption. A formulation-service-first go-to-market angle outcompetes commodity blenders lacking technical support infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where spray-drying capacity scarcity intersects with clean-label certification bottlenecks, favoring acquisition of precision-engineering blend specialists with proprietary particle engineering capabilities over upstream spice traders. Long-term viability over the next decade hinges on captive agricultural sourcing and regulatory dossier preparation expertise. Watch for FDA enforcement actions against offshore ingredient suppliers as an inflection indicator for domestic capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spice Origins | Captures ESG traceability data and insulates margin from Vietnamese pepper price volatility. |
| Spray-Drying Capacity Expansion | Eliminates European single-point vulnerability concentrated in northern Italy corridor. |
| Precision Encapsulation Technology Investment | Enables heat-stable flavor systems that commodity spray-dried houses cannot replicate. |
| Direct Grower Contracting Programs | Disintermediates spice merchants and secures lot-level blockchain verification for premium lines. |
| Regulatory Dossier Preparation Services | Accelerates REACH registration timelines that currently exceed product development windows. |
Methodological Framework
Direct dialogue with food manufacturing procurement directors, blending equipment engineers, spice cooperative agronomists, and regulatory affairs specialists grounded the qualitative foundation, cross-referenced with FDA FSMA enforcement records, EFSA clean-label guidance documents, SAMR sodium reduction circulars, customs trade data for Vietnamese and Indian spice exports, and SEC filings from publicly traded ingredient suppliers. Bottom-up demand modeling from individual application segments triangulated against top-down macroeconomic drivers.
Bottom-up volume and value outputs reflect segment-level build-ups across product type, application, end user, and form dimensions, calibrated against macroeconomic indicators and regulatory enforcement patterns across the analysis window. CAGRs derived from weighted average growth rates across modeled segments, incorporating oat and pea protein fortification trajectories, clean-label reformulation penetration curves, and spray-drying capacity utilization assumptions.
Weather-driven supply shocks in tropical spice origins, regulatory timeline extensions for novel encapsulation materials, and certification bottlenecks for organic verification are the dominant revision risks to modeled forecasts. Practitioners should monitor FDA Foreign Supplier Verification Program enforcement intensity and EU Green Deal carbon disclosure implementation for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Borage Oil Market
Ingredients
Soluble Fibers Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Fermented Ingredients Market
Ingredients
Pork Skin Gelatin Market
Ingredients
France Soy Protein Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Mastic Gum Market
Ingredients
Specialty Feed Additives Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Mung Bean Protein Market
Ingredients
Ahiflower Oil Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Low Fat Oil Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Egg Free Premix Market