
 Alginate Market | 2026-2036
Alginate Market Size, Share, and Industry Trends Forecast 2026-2036
Alginate Market Analysis
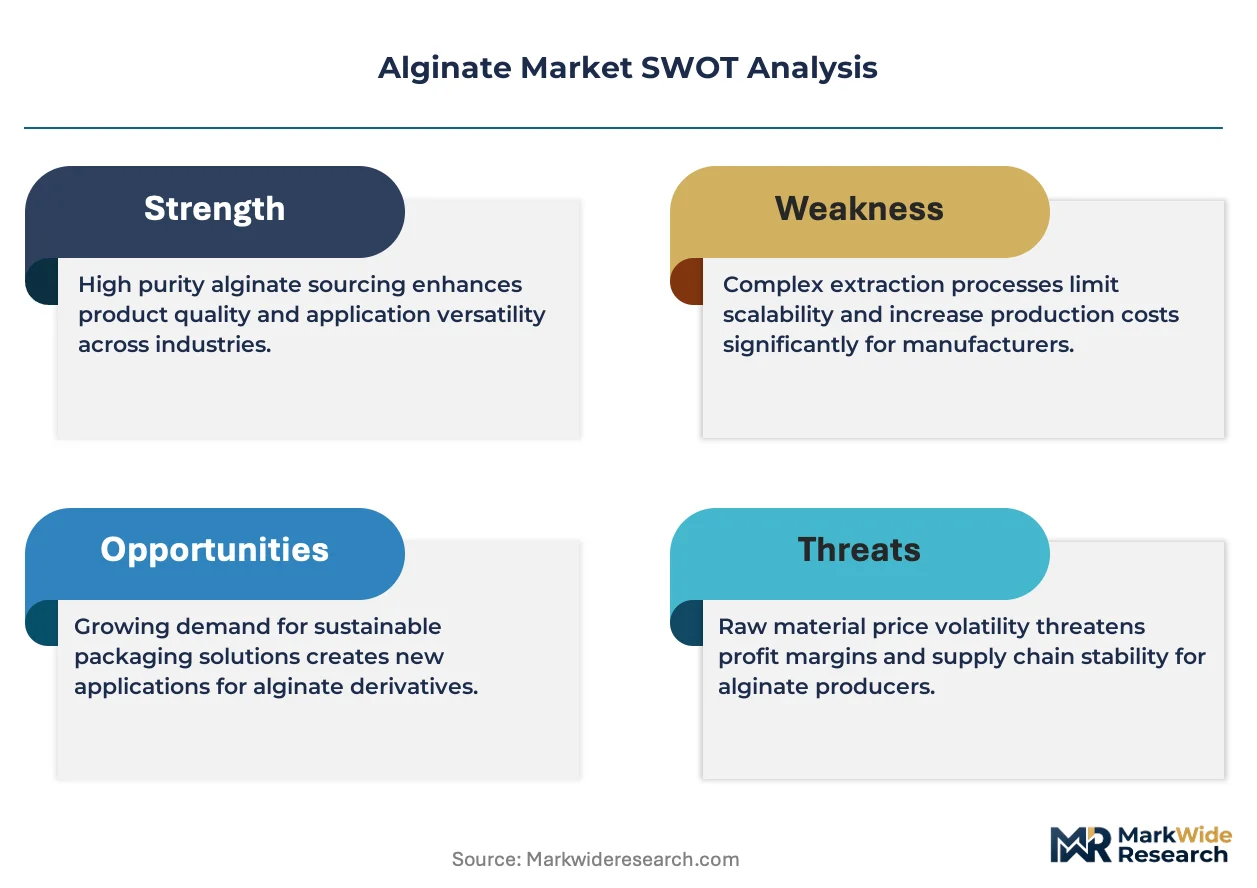
Biopolymer extraction from sustainable seaweed sources is reconfiguring how alginate manufacturers source raw material and manage seasonal supply variability. KIMICA leverages its integrated harvesting operations in Chile and Japan to secure consistent laminaria supply. FMC Corporation sustains pharmaceutical-grade certification across multiple production sites. Cargill competes through backward integration into seaweed farming cooperatives.
Alginate is a linear polysaccharide composed of β-D-mannuronic acid and α-L-guluronic acid residues extracted primarily from brown seaweed cell walls, valued for its ionotropic gelation capacity with divalent cations such as calcium. The material functions as a thickener, stabilizer, and encapsulation matrix across food, pharmaceutical, and biomedical applications. Sodium alginate dominates pharmaceutical formulations due to superior solubility and controlled-release properties, while calcium alginate leads wound dressing applications where gel-forming behavior directly impacts healing outcomes. Food industry applications represent the most mature revenue pool, though alginate gel formats in 3D bioprinting scaffolds command premium positioning.
FDA food additive regulations and EMA pharmaceutical excipient standards govern purity thresholds and heavy metal limits for alginate entering human-contact applications. EFSA evaluations of novel alginate derivatives in functional foods are expanding compliance scope for European suppliers. Stakeholders must monitor how ISO seaweed sustainability criteria and emerging national seaweed aquaculture policies reshape raw material access and certification costs.
Market Dynamics
Seaweed supply concentration in China's Shandong province and Chile's Los Lagos region is forcing alginate manufacturers to secure captive harvesting rights or face raw material rationing during seasonal brown algae shortages.
Growth Catalysts
- EMA pharmaceutical excipient standards:Tightening purity benchmarks for heavy metal limits in sodium alginate formulations are accelerating healthcare sector qualification of high-grade suppliers.
- 3D bioprinting scaffold applications:Alginate hydrogels with tunable ionotropic gelation properties are displacing synthetic matrices in tissue engineering research programs.
- Brown seaweed farming cooperatives:Backward integration into aquaculture operations in Indonesia and the Philippines is stabilizing laminaria supply chains for extraction facilities.
Market Restraints
- Seasonal laminaria harvest volatility:Brown seaweed biomass fluctuates with Pacific Ocean temperature cycles, compressing extraction yields in Chilean and Japanese operations.
- REACH compliance costs:ECHA registration requirements for novel alginate derivatives impose six-figure testing burdens on European specialty chemical producers.
- Carrageenan substitution in food stabilization:Red seaweed extracts compete directly on price in dairy and beverage applications where gel strength requirements are moderate.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO accelerated approval pathways for excipient imports are opening formulation partnerships with Mumbai and Hyderabad drug producers.
- Controlled-release oral dosage formats:Sodium alginate matrix tablets for gastric-resistant drug delivery represent underpenetrated therapeutic categories beyond diabetes management.
- ISO seaweed sustainability certification:Emerging aquaculture standards create first-mover advantage for extraction facilities documenting chain-of-custody from farm to pharmaceutical grade.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA Type II drug master file preparation requires 18-24 month validation cycles that freeze capital in qualification batches.
- Seaweed processing talent scarcity:Specialized expertise in alginate fractionation and M/G ratio optimization concentrates among retiring technicians in Japanese extraction facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alginate Market |
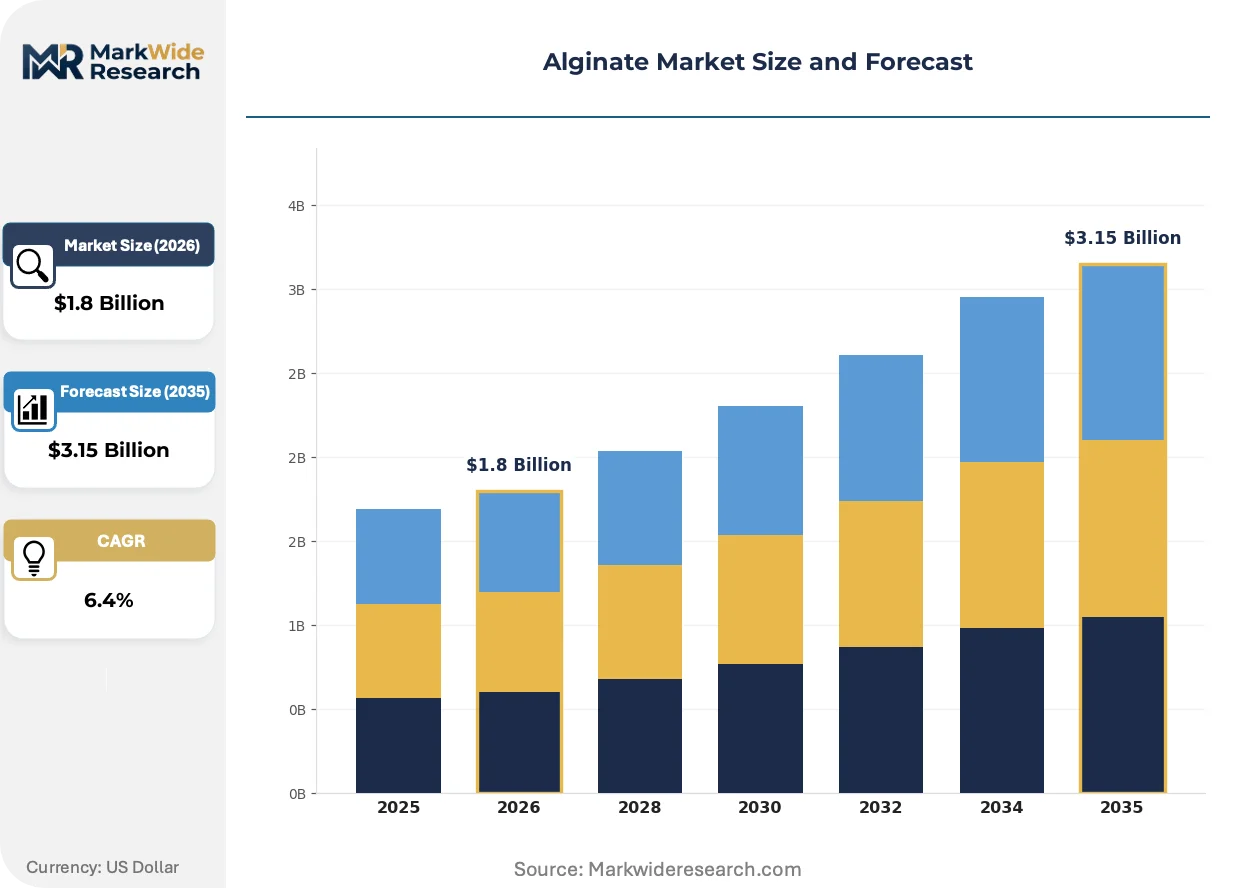
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Alginate, Sodium Alginate, Potassium Alginate, Alginate Gel Application: Food Industry, Pharmaceuticals, Cosmetics, Textile Industry End User: Food Manufacturers, Healthcare Providers, Cosmetic Companies, Textile Producers Form: Powder, Granules, Beads, Liquid |
| Companies Covered | KIMICA, FMC Corporation, Algaia, Shandong Jiejing Group Corporation, Ceamsa, Marine Biopolymers Limited, Cargill, Ingredients Solutions, Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alginate Market Emerging Trajectories
Precision fermentation of bacterial alginate precursors and enzymatic tailoring of polysaccharide block structures are reconfiguring how manufacturers achieve batch-to-batch consistency without geographic dependence on wild seaweed stocks.
Enzymatic epimerase engineering is collapsing the cost differential between laboratory-grade and industrial-scale alginate customization. Biotech firms in Denmark and the Netherlands are deploying recombinant bacterial strains to convert mannuronic acid residues to guluronic acid at specified ratios. Pharmaceutical formulators are now specifying exact M/G block compositions for wound dressing gel strength rather than accepting standard seaweed-derived grades.
REACH authorization requirements for polymer additives are tightening heavy metal thresholds for alginate entering European food contact applications. ECHA's 2023 updates to Annex XVII restricted substances lists have forced extraction facilities to deploy additional ion-exchange purification stages. German and French alginate suppliers are absorbing capital costs for chromatographic metal removal to maintain EFSA-compliant supply positions.
Direct contracting between wound care product manufacturers and seaweed farming cooperatives is compressing traditional chemical distributor margins. Hospital procurement groups in the United States are negotiating multi-year alginate fiber supply agreements that bypass regional ingredient wholesalers. This channel consolidation is most visible in advanced wound dressing segments where FDA 510(k) clearance requirements lock formulation specifications for multi-year product lifecycles.
Alginate Market Segmentation
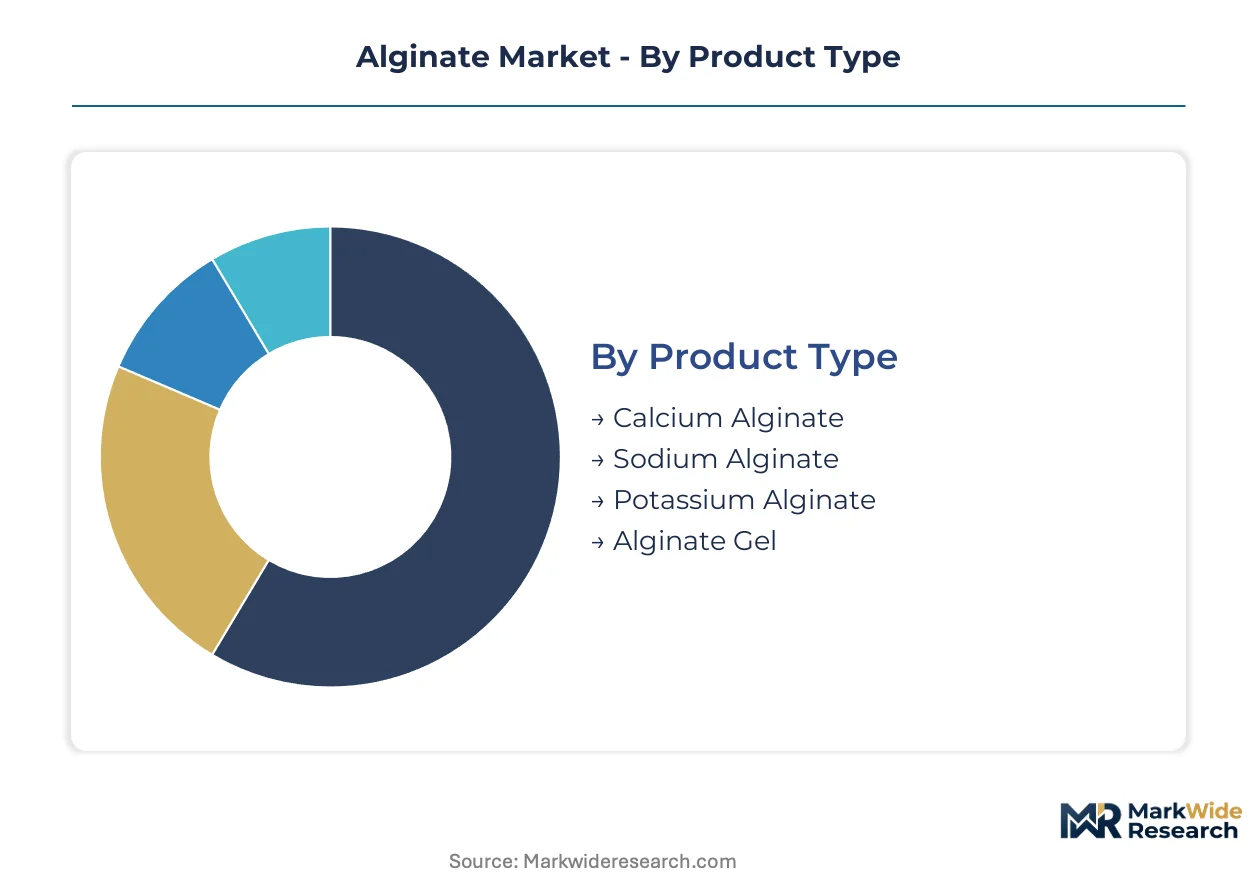
Alginate's functional versatility across ionotropic gelation, thickening, and encapsulation creates distinct value propositions by product chemistry. Segmentation reveals how sodium and calcium variants partition between pharmaceutical precision and food-volume markets.
Product Type:
Mature extraction chemistries dominate volume, while tailored M/G ratio specifications are opening premium positioning in biomedical applications.
- Sodium Alginate:The water-soluble salt of alginic acid enables controlled-release matrix tablets and gastric-resistant drug delivery systems. Pharmaceutical formulators in Germany and Japan specify exact viscosity grades for excipient compatibility, with EMA heavy metal limits tightening supplier qualification thresholds.
- Calcium Alginate:Insoluble in water but forms ionotropic gels upon contact with wound exudate, making it the standard for advanced wound dressings and hemostatic products. Hospital procurement groups in the United States negotiate multi-year fiber supply agreements directly with extraction facilities, bypassing traditional chemical distributors.
- Potassium Alginate:Functions as a low-sodium thickening alternative in reduced-salt food formulations, particularly in Japanese and South Korean processed seafood applications where clean-label positioning commands shelf space.
- Alginate Gel:Pre-hydrated formats serve 3D bioprinting scaffold applications and cell encapsulation protocols where batch-to-batch consistency outweighs cost sensitivity.
Sodium alginate handles the majority of throughput; alginate gel is expanding most quickly on share as tissue engineering programs scale.
Application:
Cost tier stratification separates commodity food stabilization from pharmaceutical-grade certification premiums.
- Food Industry:Sodium and calcium alginates stabilize ice cream, salad dressings, and restructured meat products through cold-soluble thickening and heat-stable gel networks. EFSA evaluations of novel alginate derivatives in functional foods are expanding compliance scope for European suppliers.
- Pharmaceuticals:Controlled-release oral dosage formats and wound dressing matrices require FDA Type II drug master files and 18-24 month validation cycles. CDSCO accelerated approval pathways in India are opening formulation partnerships with Mumbai and Hyderabad drug producers.
- Cosmetics:Facial masks and encapsulation systems leverage alginate's film-forming properties for sustained active ingredient release.
- Textile Industry:Reactive dye printing pastes and warp sizing applications compete with synthetic thickeners on price in Bangladesh and Vietnam garment manufacturing clusters.
Food industry applications anchor volume; pharmaceuticals command the steepest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, from spot-market commodity purchasing to locked multi-year specification agreements.
- Food Manufacturers:Global dairy and beverage processors procure sodium alginate through annual tenders where carrageenan substitution threats moderate pricing power.
- Healthcare Providers:Hospital procurement groups and wound care product manufacturers specify exact gel strength and fiber diameter, with ISO seaweed sustainability certification increasingly appearing in RFP requirements.
- Cosmetic Companies:K-beauty and clean-label skincare brands in South Korea source alginate gels for sheet mask substrates.
- Textile Producers:Reactive dye houses in India's Tirupur cluster and Bangladesh's Dhaka division represent price-sensitive volume demand.
Healthcare providers lock the most rigid specifications; cosmetic companies are climbing fastest on certified-sustainable sourcing requirements.
Form:
Supply concentration in powder processing reflects economies of scale, while liquid and bead formats serve niche delivery requirements.
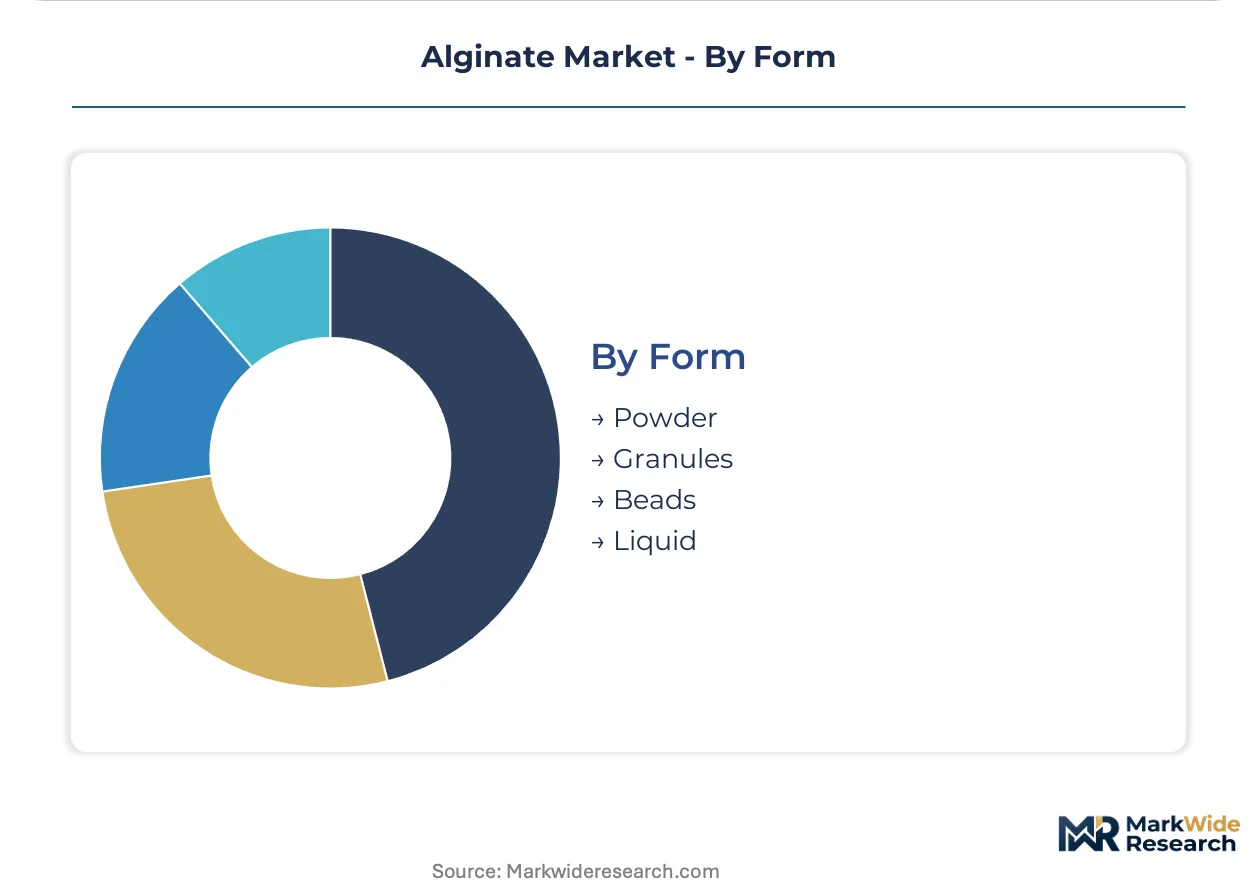
- Powder:Spray-dried sodium alginate dominates pharmaceutical and food formulation inputs, with particle size distribution critical for dissolution rate consistency.
- Granules:Coarser grades serve agricultural seed coating and controlled-release fertilizer encapsulation where slower hydration kinetics are advantageous.
- Beads:Ionotropically gelled calcium alginate spheres immobilize enzymes and cells in bioreactor applications and probiotic delivery systems.
- Liquid:Pre-hydrated colloidal dispersions eliminate dust exposure in cleanroom pharmaceutical manufacturing and enable direct pipeline injection in automated food processing lines.
Powder handles the majority of throughput; beads are gaining share fastest in cell therapy manufacturing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese alginate extraction facilities in Shandong province supply pharmaceutical-grade sodium alginate to German and Japanese formulators. Chilean laminaria harvesters export raw brown seaweed to European wound dressing manufacturers facing seasonal supply gaps.
China
Shandong province hosts the densest concentration of brown seaweed harvesting and alginate extraction infrastructure worldwide. NMPA pharmaceutical excipient standards are tightening heavy metal limits for sodium alginate entering domestic drug formulations. Qingdao and Weihai processing clusters are absorbing capital costs for chromatographic purification to meet EMA export requirements.
Germany
Wound care product manufacturers in North Rhine-Westphalia specify exact gel strength and fiber diameter in multi-year alginate supply agreements. ECHA REACH authorization requirements for polymer additives are forcing extraction facilities to deploy additional ion-exchange purification stages. Cologne and Düsseldorf procurement groups are negotiating direct contracts with seaweed farming cooperatives in Indonesia.
United States
Hospital procurement groups in the Midwest and Southeast are locking multi-year alginate fiber supply agreements for advanced wound dressings. FDA Type II drug master file preparation requires 18-24 month validation cycles that freeze capital in qualification batches. Boston and San Diego biomedical research clusters are scaling 3D bioprinting scaffold applications with tunable M/G ratio specifications.
Japan
Pharmaceutical formulators in Tokyo and Osaka specify exact viscosity grades of sodium alginate for excipient compatibility. PMDA pharmaceutical standards govern purity thresholds for alginate entering controlled-release oral dosage formats. Kobe and Hiroshima extraction facilities face processing talent scarcity as specialized technicians in alginate fractionation retire.
India
Mumbai and Hyderabad drug producers are pursuing CDSCO accelerated approval pathways for excipient imports of pharmaceutical-grade sodium alginate. FSSAI food additive regulations are expanding compliance scope for alginate derivatives in functional foods. Gujarat and Tamil Nadu textile clusters represent price-sensitive volume demand for reactive dye printing pastes.
Alginate Market Vendor Landscape
On the supply side, the industry is consolidating around integrated harvesting operations and pharmaceutical-grade certification capabilities. Tiered competitive positioning separates captive seaweed farming operations from spot-market raw material purchasers. Three archetypes dominate: integrated harvester-extractors with Chilean and Japanese laminaria rights; pharmaceutical-grade specialists sustaining FDA and EMA certifications; and food-grade volume processors competing on backward integration into Indonesian aquaculture cooperatives. Dominant competitive moves include direct contracting with wound care manufacturers and enzymatic tailoring of M/G ratios for biomedical specifications.
Within the integrated harvesting tier, KIMICA exemplifies geographic diversification across Chile and Japan to secure consistent laminaria supply. FMC Corporation occupies a position among pharmaceutical-grade certification specialists, sustaining qualification across multiple production sites. Cargill anchors the food-grade volume segment, representing backward integration into seaweed farming cooperatives. These three firms collectively illustrate how supply security and regulatory compliance are separating sustainable competitive positions from commodity price competition.
| Leading Market Players |
|---|
| KIMICA |
| FMC Corporation |
| Algaia |
| Shandong Jiejing Group Corporation |
| Ceamsa |
| Marine Biopolymers Limited |
| Cargill |
| Ingredients Solutions, Inc. |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese Shandong extraction facilities is compressing spot-market sodium alginate quotes while tightening pharmaceutical-grade contract premiums, as utilization rates below 70% force food-grade suppliers into aggressive pricing while certified producers defend margin through locked multi-year offtake agreements with wound care manufacturers.
Pricing Analysis
Extraction-technology pricing gaps separate legacy acid-precipitation facilities from enzymatic fractionation operations capable of tailoring M/G block ratios. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels reflects EMA heavy metal certification costs and FDA master file preparation timelines. Pricing pressure stems from Indonesian aquaculture cooperatives expanding laminaria farming capacity and flooding mid-tier food stabilization markets. Food manufacturers exhibit highest price sensitivity through annual tender processes, while hospital procurement groups lock rigid specifications with limited substitution tolerance.
Supply Chain Analysis
Export-control regimes restricting dual-use biopolymer processing equipment to Chinese extraction facilities have concentrated pharmaceutical-grade supply among Shandong and Qingdao processors with validated purification infrastructure. Raw material flows draw from Chilean Los Lagos laminaria harvests, Japanese Hokkaido kelp beds, and Indonesian Selayar Island aquaculture cooperatives. Single-source vulnerability concentrates in seasonal Pacific Ocean temperature cycles that compress Chilean biomass yields. Distribution runs through direct contracting between wound care manufacturers and farming cooperatives, bypassing traditional chemical distributors in North American and European hospital supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in alginate fractionation and M/G ratio optimization is retiring from Japanese extraction facilities faster than training pipelines can replenish, creating a capability gap that will determine which suppliers can meet pharmaceutical-grade specifications across the next decade.
For Market Incumbents: Insulate pharmaceutical-grade certification positions by accelerating technician training partnerships with Osaka and Tokyo technical institutes while securing captive harvesting rights in Chilean Los Lagos before seasonal supply volatility intensifies. Carrageenan substitution threats in dairy stabilization demand backward integration into Indonesian aquaculture cooperatives to defend food-grade volume positions against price erosion. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical manufacturing expansion by pursuing CDSCO accelerated approval pathways for excipient imports targeting Mumbai and Hyderabad generic drug producers. 3D bioprinting scaffold applications represent the most penetrable premium segment, with specification flexibility allowing enzymatic tailoring capabilities to displace legacy seaweed-derived grades through direct sales to Boston and San Diego biomedical research clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated harvester-extractors with multi-year wound care supply agreements, as hospital procurement groups lock fiber specifications for FDA 510(k) product lifecycles. Long-term viability favors facilities with documented ISO seaweed sustainability certification and chromatographic purification infrastructure already deployed. The signal to watch is EMA heavy metal limit tightening, which will force consolidation among uncertified European specialty chemical producers unable to absorb six-figure REACH testing burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming Cooperatives | Cargill's Indonesian aquaculture partnerships stabilize laminaria supply against Pacific temperature cycle volatility. |
| Pharmaceutical-Grade Certification Investment | FMC Corporation's multi-site FDA Type II drug master file qualification locks hospital procurement specifications for wound dressing fibers. |
| Enzymatic M/G Ratio Tailoring Capability | Danish biotech firms deploy recombinant bacterial epimerase engineering to achieve batch-to-batch consistency without wild seaweed dependence. |
| Direct Hospital Supply Agreement Negotiation | Midwest and Southeast U.S. hospital procurement groups bypass regional distributors through multi-year alginate fiber contracts. |
| ISO Seaweed Sustainability Certification Program | Chain-of-custody documentation from farm to pharmaceutical grade creates first-mover advantage in European EFSA compliance expansion. |
Methodological Framework
Desk research of EMA excipient guidance documents, FDA Type II drug master file databases, and FAO seaweed aquaculture statistics preceded structured interviews with alginate extraction facility plant managers, pharmaceutical formulator procurement leads, wound care product R&D directors, and hospital GPO contracts managers. Primary fieldwork combined with secondary validation from customs trade data, SEC chemical sector filings, and ECHA REACH registration records enabled bottom-up capacity modeling and top-down demand triangulation across food, pharmaceutical, and biomedical application segments.
Assumptions held fixed include EMA heavy metal limit trajectories, FDA food additive enforcement patterns, and Pacific Ocean temperature cycle periodicity; variables stress-tested included Indonesian aquaculture expansion rates, enzymatic epimerase engineering cost curves, and Indian CDSCO approval pathway acceleration. Segmentation modeling spanned product chemistry, application tier, end-user procurement sophistication, and regional regulatory cluster across the projection horizon. CAGRs derived from installed extraction capacity utilization trends, pharmaceutical formulation partnership formation rates, and biomedical research program scaling patterns.
Stress conditions across laminaria harvest yield volatility, REACH compliance cost escalation, and carrageenan substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline persistence and aquaculture cooperative formation rates. Material shifts in EMA pharmaceutical excipient purity thresholds or Japanese technician retirement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Thickener Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Canola Meal Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Bleached Flour Market
Ingredients
South America Protein Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Refined Coconut Oil Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Encapsulated Salt Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Cocoa Beans Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Cheese Ripening Enzymes Market