
 Sunflower Protein Market | 2026-2036
Sunflower Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Sunflower Protein Market Analytics
Soy protein is pivoting toward sunflower protein across European bakery and dairy analog formulations as allergen concerns and sustainability metrics reshape ingredient procurement. ADM leverages its North American oilseed processing footprint to anchor sunflower protein supply for CPG manufacturers. Roquette Frères competes through specialized extrusion capabilities that sustain textured protein output for meat alternatives. Cargill differentiates via integrated supply chain control from farm gate to ingredient formulation.
Sunflower protein refers to the protein fraction extracted from sunflower seeds, typically containing 45-55% protein by weight in concentrate form and exceeding 90% in isolate grades, produced through aqueous extraction or alkaline-isoelectric precipitation for use in food fortification and nutritional applications. The isolate segment commands premium positioning due to superior amino acid completeness and minimal residual polyphenol content that limits color and flavor defects in finished goods. Food and Beverages applications dominate current volume, though Nutraceuticals represents the fastest-growing structural pool as dietary supplement companies seek non-soy, non-dairy protein sources with complete essential amino acid profiles.
EFSA allergen labeling requirements and REACH chemical safety standards govern ingredient approval and clean-label positioning across European markets, while FDA GRAS determinations shape US market access for novel sunflower protein applications. USDA organic certification and EU organic regulation further segment pricing and channel eligibility for premium-positioned suppliers. Stakeholders must monitor evolving protein content threshold definitions in organic standards and anticipate how carbon intensity scoring in procurement criteria will redistribute contract volumes among processing regions.
Market Dynamics
Allergen labeling mandates under EFSA and REACH chemical safety protocols are forcing bakery and sports nutrition manufacturers to reformulate around soy and dairy proteins, redirecting procurement toward sunflower isolate supply chains.
Growth Catalysts
- EFSA Allergen Framework:Tightened declaration requirements for soy and gluten are accelerating bakery sector trials of sunflower protein as a clean-label alternative in Germany and France.
- Aqueous Extraction Advances:Improved alkaline-isoelectric precipitation methods are reducing residual polyphenol content below flavor-threshold levels, enabling broader beverage applications.
- Sports Nutrition Procurement:Western European contract manufacturers are qualifying sunflower isolate for powder formulations to meet retailer allergen-free positioning requirements.
Market Restraints
- Oilseed Price Volatility:Sunflower seed input costs fluctuate with Black Sea supply disruptions, compressing processor margins and destabilizing long-term contract pricing.
- Processing Concentration:Isolate production capacity clusters in France and Ukraine, creating geographic supply risk and limiting buyer negotiation leverage.
- Amino Acid Profiling Gaps:Lysine content in sunflower protein trails soy and pea alternatives, requiring blending strategies that complicate formulation economics.
Strategic Opportunities
- Indian Nutraceuticals Expansion:FSSAI regulatory clarity on novel protein ingredients is opening dietary supplement channels for isolate imports targeting vegetarian protein demand.
- USDA Organic Premium Tier:Certified organic sunflower protein commands pricing multiples in North American natural products retail, rewarding farm-level conversion investments.
- Cellular Agriculture Feedstock:Precision fermentation startups are evaluating sunflower hydrolysates as nitrogen sources for cultivated meat media, creating technical-grade demand.
Industry Challenges
- Extrusion Expertise Scarcity:Textured protein production requires specialized high-moisture extrusion operators, with limited talent pools outside Roquette and Cargill processing networks.
- Organic Certification Timelines:Three-year field conversion periods and EU organic regulation compliance audits delay new supplier market entry and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunflower Protein Market |
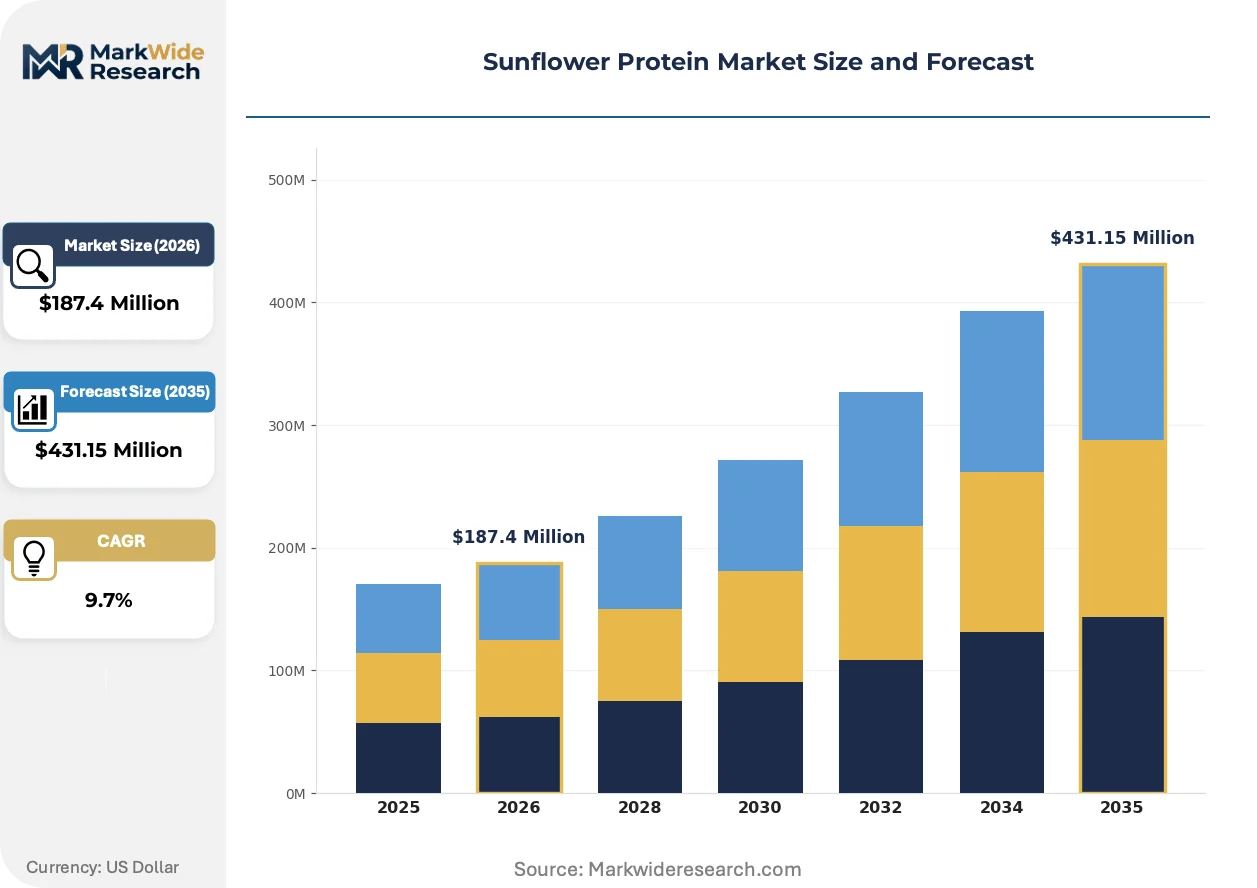
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Textured, Whole Application: Food & Beverages, Nutraceuticals, Animal Feed, Personal Care End User: Food Manufacturers, Dietary Supplement Companies, Livestock Producers, Cosmetic Brands Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company (ADM), Cargill, Incorporated, Roquette Frères, SunOpta Inc., Austrade Inc. (Heliaflor), Bunge Limited, Agridient Inc., BioTechnologies LLC, Tradin Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunflower Protein Market Evolving Landscape
Processing technology and procurement specifications are converging to redefine competitive advantage around protein purity, carbon intensity scoring, and supply chain traceability rather than commodity volume alone.
Enzymatic debittering protocols are overtaking traditional solvent washing for polyphenol reduction in isolate production. Sports nutrition brands in Germany are specifying enzymatically treated grades for unflavored protein powders. This shift is overtaking legacy alkaline extraction in premium contract manufacturing, compressing equipment depreciation schedules for processors without enzymatic capability.
REACH chemical safety standards now require full substance registration for novel protein isolates entering European food contact applications. The industrial consequence is extended approval timelines and elevated testing expenditures for new market entrants. Bakery reformulation projects in France are most affected, with manufacturers reverting to established supplier relationships rather than qualifying unregistered alternatives.
Carbon intensity scoring is penetrating procurement criteria for CPG manufacturers with net-zero commitments. Buyers are requesting farm-level emissions data and processing energy footprints alongside protein content specifications. This behavioral shift is most visible in German retail private label contracts, where suppliers without verified Scope 3 data are losing shelf placement to lower-carbon alternatives.
Sunflower Protein Market Segmentation
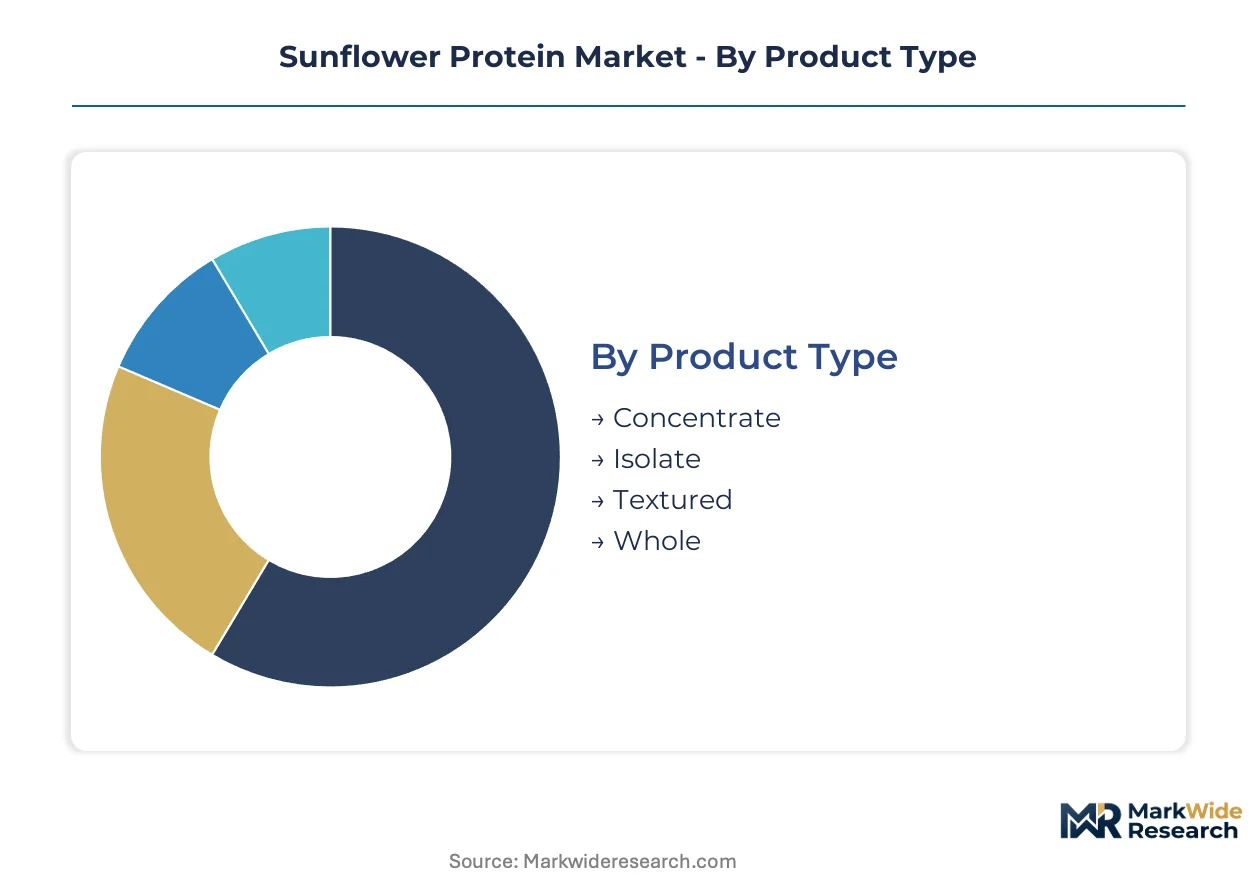
Segmentation in the sunflower protein market reveals how processing intensity and end-use specifications determine pricing power and procurement relationships. Buyers select grades based on amino acid completeness requirements, allergen positioning needs, and formulation compatibility constraints.
Product Type:
Manufacturers upgrade from legacy concentrates to isolates as beverage and sports nutrition applications demand cleaner flavor profiles and higher protein density.
- Isolate:Exceeding 90% protein content with minimal residual polyphenols, this grade serves German sports nutrition brands requiring unflavored powder compatibility and EFSA-compliant allergen-free labeling.
- Concentrate:The 45-55% protein fraction dominates bakery reformulation in France where alkaline extraction costs align with clean-label bread and pastry economics.
- Textured:High-moisture extrusion creates fibrous structures for meat analog applications.
- Whole:Minimally processed seed meal retains fiber and oil fractions for animal feed compounding.
Volume placements concentrate in Concentrate; the faster expansion belongs to Isolate.
Application:
Cost tier differentiation separates commodity feed applications from premium human nutrition segments where organic certification and carbon scoring command price multiples.
- Food & Beverages:Bakery and dairy analog formulations in Western Europe drive procurement volumes, with enzymatic debittering investments enabling beverage-grade isolate adoption.
- Nutraceuticals:Dietary supplement channels in India and North America seek complete essential amino acid profiles without soy or dairy allergen declarations.
- Animal Feed:Livestock producers blend sunflower meal into poultry and aquaculture rations.
- Personal Care:Cosmetic formulators leverage protein hydrolysates for hair conditioning and skin barrier applications.
Food & Beverages holds the installed base; Nutraceuticals climbs the fastest.
End User:
Customer type determines contract structure, with food manufacturers seeking long-term supply security and supplement companies prioritizing batch flexibility and certification documentation.
- Food Manufacturers:Industrial bakeries in Germany and France negotiate multi-year isolate contracts to secure reformulation supply amid EFSA labeling transitions.
- Dietary Supplement Companies:Western European contract manufacturers qualify sunflower isolate for private-label protein powders targeting retailer allergen-free positioning.
- Livestock Producers:Poultry and aquaculture operations procure whole and concentrate grades for feed cost optimization.
- Cosmetic Brands:Personal care formulators source hydrolyzed fractions for functional ingredient applications.
Food Manufacturers anchor procurement volumes; Dietary Supplement Companies show the steepest expansion trajectory.
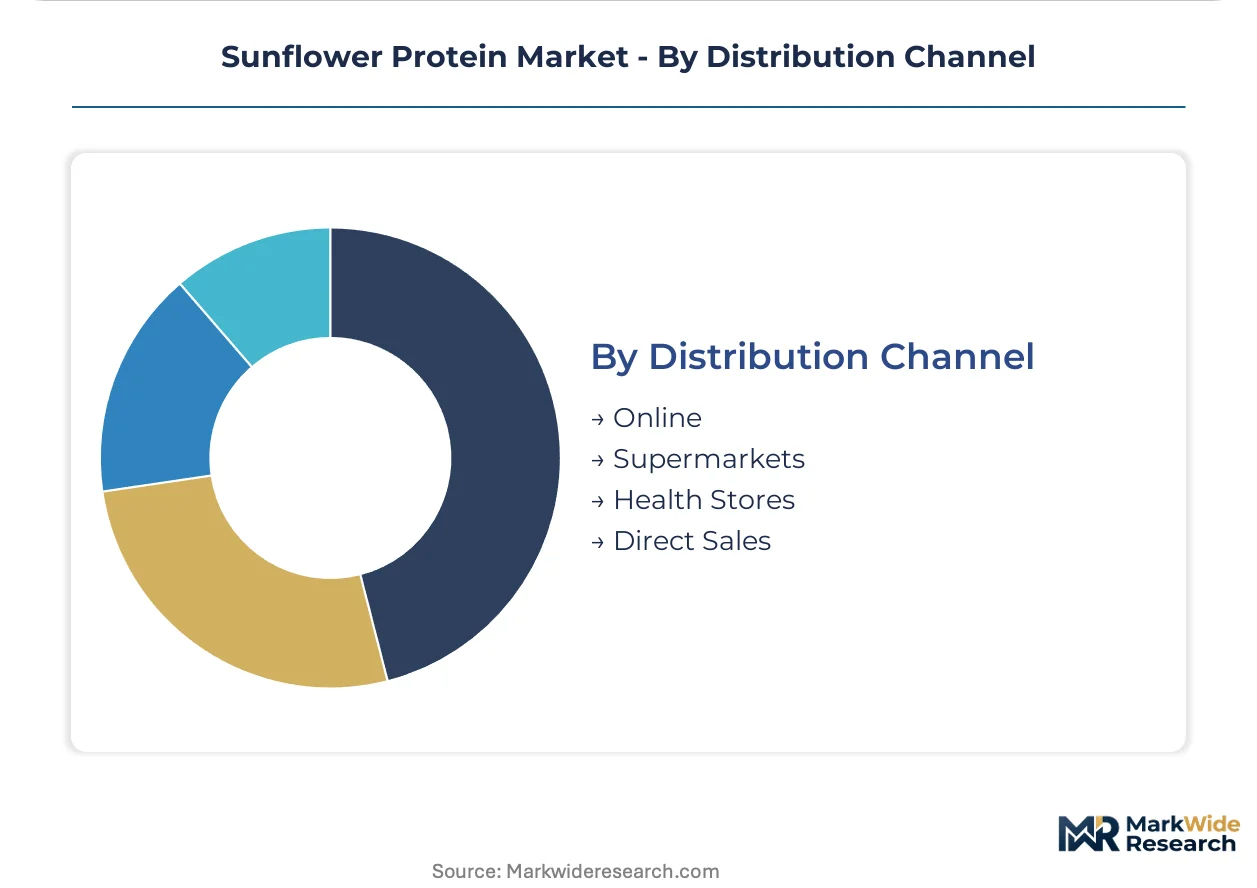
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with bulk industrial users bypassing retail infrastructure entirely.
- Direct Sales:Processor relationships with CPG manufacturers and feed compounders move tonnage without intermediary margins, dominating volume economics.
- Online:E-commerce platforms serve small-scale nutraceutical formulators and specialty ingredient buyers requiring certificate documentation and flexible order sizes.
- Health Stores:Retail channels move packaged consumer protein products to end consumers.
- Supermarkets:Mass retail placement supports branded consumer protein lines.
Direct Sales captures the industrial volume; Online gains share fastest among emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bulgaria and Romania have attracted oilseed processing investments that concentrate sunflower protein capacity near Black Sea sourcing corridors. These zones offer preferential tax treatment and streamlined customs procedures that offset logistics costs from Ukrainian and Russian seed origins.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia are reformulating bread formulations to eliminate soy allergen declarations under tightened EFSA labeling protocols. The country's Federal Office of Consumer Protection and Food Safety enforces strict clean-label compliance timelines. Cologne-based contract manufacturers now qualify sunflower isolate for private-label sports nutrition lines destined for Aldi and Rewe shelves.
France
Roquette Frères operates specialized extrusion facilities in Lestrem that supply textured protein to plant-based meat startups in Paris and Lyon. ANSM and DGCCRF oversight of novel food applications creates regulatory friction for unregistered isolate imports. The Hauts-de-France cluster around Lille has emerged as Europe's densest concentration of sunflower protein research partnerships between processors and INRAE research stations.
Ukraine
Pre-war processing infrastructure in Kharkiv and Dnipropetrovsk oblasts previously supplied concentrate grades to German feed compounders. Ongoing conflict has fragmented Black Sea export logistics and redirected seed flows through Romanian Constanta port corridors. Remaining operational crush facilities in western oblasts now prioritize domestic oil extraction over protein fractionation.
United States
ADM leverages its Decatur, Illinois oilseed complex to supply organic-certified isolate to natural products distributors in Boulder and Austin. FDA GRAS determinations for novel protein applications proceed through voluntary consultation pathways that lack binding timelines. North Dakota and South Dakota farm cooperatives are expanding contracted acreage under USDA organic standards to capture premium pricing multiples in Whole Foods Market channels.
India
Dietary supplement manufacturers in Mumbai and Hyderabad are importing sunflower isolate to formulate vegetarian protein powders for FSSAI-registered brands. The Food Safety and Standards Authority of India's 2022 novel food clarification has reduced import clearance uncertainties for non-soy protein sources. Gujarat-based contract manufacturers now blend sunflower with mung bean protein to address lysine deficiency in finished formulations.
Sunflower Protein Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with isolate production consolidating around aqueous extraction specialists while concentrate supply fragments across regional oilseed crushers. Three archetypes dominate: integrated agribusiness conglomerates controlling farm-gate sourcing, specialized extrusion technology holders, and organic-certified niche suppliers serving natural products channels. Capacity expansion and strategic partnerships represent the primary competitive vectors, as processors seek to lock in multi-year bakery and sports nutrition contracts before EFSA labeling deadlines.
Within the integrated agribusiness tier, Archer Daniels Midland Company exemplifies North American supply chain control, while Cargill, Incorporated occupies a parallel position through its oilseed processing footprint. Roquette Frères represents the specialized technology archetype through its European extrusion capabilities. These three anchors demonstrate how competitive positioning stratifies around either upstream raw material access or downstream formulation expertise.
| Leading Market Players |
|---|
| Archer Daniels Midland Company (ADM) |
| Cargill, Incorporated |
| Roquette Frères |
| SunOpta Inc. |
| Austrade Inc. (Heliaflor) |
| Bunge Limited |
| Agridient Inc. |
| BioTechnologies LLC |
| Tradin Organic |
| Others |
Value Network & Pricing Analysis
German industrial bakeries and French sports nutrition contract manufacturers concentrate procurement volumes, anchoring a contract-based long-term offtake model where multi-year isolate agreements secure reformulation supply ahead of EFSA labeling deadlines. This buyer concentration grants established processors pricing power while compressing spot market liquidity for new entrants lacking certification documentation.
Pricing Analysis
Short lead-time premiums apply to enzymatically debittered isolate grades required by Cologne-based sports nutrition manufacturers for unflavored powder formulations. Three-tier pricing structure across premium, standard, and economy levels separates certified organic isolate from conventional concentrate and whole meal feed grades. Price differentiation rests on EU organic regulation compliance and carbon intensity scoring documentation. Cost compression in conventional concentrate tiers is intensifying because Black Sea oilseed volatility destabilizes input costs. Dietary supplement companies show highest price sensitivity due to batch flexibility requirements, while industrial bakeries accept premium pricing for supply security.
Supply Chain Analysis
Refurbishment flows for extrusion equipment and aqueous extraction systems create secondary machinery markets that sustain smaller processors unable to access new capital equipment financing. Geographic supply concentration centers on France, Ukraine, and Romania, with crush capacity clustering near Black Sea corridors and specialized isolate production in French Hauts-de-France. Raw material dependencies draw from Ukrainian and Russian sunflower seed origins, enzymatic treatment reagents, and high-moisture extrusion dies. Single-source vulnerability runs through Constanta port logistics for Black Sea seed diversion. Distribution runs through direct processor-CPG manufacturer relationships for industrial volume, with online channels serving small-scale nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around processors with integrated farm-gate sourcing and enzymatic debittering capability, as EFSA allergen labeling deadlines and REACH registration requirements force undercapitalized regional crushers into acquisition or exit.
For Market Incumbents: Acquire aqueous extraction specialists with enzymatic debittering capability to secure premium isolate positioning ahead of competitor capacity additions. ADM and Cargill should extend backward integration into North Dakota and South Dakota organic acreage contracts to capture Whole Foods Market channel premiums. Roquette Frères must defend its Lestrem extrusion facilities against emerging precision fermentation feedstock competitors by locking multi-year textured protein supply agreements with Paris and Lyon plant-based meat startups. For New Entrants and Emerging Players: Launch via FSSAI-registered import partnerships targeting Mumbai and Hyderabad dietary supplement manufacturers seeking vegetarian protein alternatives to soy. Indian nutraceuticals represents the most penetrable geography given 2022 novel food regulatory clarity and lysine-blending formulation expertise at Gujarat contract manufacturers. Position on carbon intensity scoring documentation to capture German retail private label contracts where Scope 3 data requirements disqualify incumbent suppliers. For Investors and Strategic Acquirers: The window for entry favors organic-certified niche suppliers with established EU regulation compliance and farm-level emissions verification capability. Five-to-ten year viability hinges on processors controlling both Black Sea sourcing relationships and enzymatic treatment intellectual property. Monitor FSSAI enforcement consistency on novel protein imports and EFSA protein content threshold revisions in organic standards as inflection indicators for capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captures USDA premium multiples in North American natural products retail channels. |
| Enzymatic Debittering Capacity Expansion | Enables beverage-grade isolate adoption by German sports nutrition contract manufacturers. |
| Long-term Supply Agreement with Retail Private Label | Secures shelf placement at Aldi and Rewe ahead of EFSA compliance deadlines. |
| Joint Venture with Indian Contract Manufacturer | Accesses FSSAI-registered blending facilities for lysine-fortified formulations. |
| Carbon Intensity Verification Program | Meets German CPG procurement criteria requiring farm-level Scope 3 emissions data. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with oilseed processing plant managers, CPG procurement leads, sports nutrition contract manufacturers, and EU regulatory affairs specialists. Secondary validation drew from EFSA novel food submissions, REACH substance registrations, FSSAI import clearance documentation, and USDA organic certification databases. Bottom-up volume estimates triangulated against top-down addressable market calculations.
Data-stream reconciliation across processor capacity utilization rates, seed crush margins, and end-use procurement contract tenors informed the analytical framework. Segmentation dimensions modeled include isolate-concentrate-textured-whole grade tiers, food-beverage-nutraceutical-feed application categories, and direct-online-retail distribution channels. CAGRs were derived from trend extrapolation of bakery reformulation timelines and sports nutrition allergen-free positioning adoption curves. Forecast inputs incorporated Black Sea logistics disruption scenarios and enzymatic treatment technology diffusion rates.
Black Sea supply disruption persistence, EFSA protein content threshold revisions, and FSSAI enforcement variability on novel protein imports are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on regulatory timeline adherence and processing technology adoption curves. Practitioners should monitor Ukrainian export corridor stability, enzymatic debittering patent filings, and German retail private label carbon scoring mandate expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Corn Gluten Meal Market
Ingredients
Apple Extract Market
Ingredients
Lupine Peptides Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Coconut Derivatives Market
Ingredients
Jasmine Extract Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Fermentation Ingredient Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Whey Permeate Market
Ingredients
Mirepoix Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
North America Phytosterols Market
Ingredients
Europe Fermented Ingredients Market