
 Fucoidan Extract Market | 2026-2036
Fucoidan Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Fucoidan Extract Market Foresight
The fucoidan extract market is recalibrating around a widening split between pharmaceutical-grade refined extracts commanding purity thresholds above 85% and commodity crude extracts serving bulk nutraceutical buyers. Marinova Pty Ltd. leverages its Tasmanian kelp supply chain to dominate high-purity pharmaceutical segments. Yaizu Suisankagaku Industry Co. Ltd anchors the Japanese functional beverage channel with decades of domestic regulatory alignment. Biosynth Ltd. specializes in custom enzymatic extraction protocols that differentiate its offering for European nutraceutical clients.
Fucoidan extract comprises sulfated polysaccharides derived principally from brown seaweed cell walls, with molecular weight and fucose content varying by species source and extraction method; manufacturers deploy enzymatic extraction to preserve bioactive integrity for pharmaceutical applications while acid extraction remains cost-dominant for commodity output. Refined extract formats capture the strongest margin pools as pharmaceutical manufacturers demand batch-certified purity and documented sulfate profiles. Dietary supplements represent the volume anchor, though functional beverages are attracting accelerated R&D investment from brands seeking differentiated positioning in the Asia-Pacific wellness channel.
FDA dietary supplement regulations and Japan's FOSHU approval system create divergent compliance pathways that filter market access for new entrants, while EFSA novel food evaluations constrain European launch timelines for unconventional seaweed sources. South Korea's MFDS maintains stringent heavy metal and iodine thresholds that favor vertically integrated harvesters with in-house testing laboratories. Stakeholders must monitor evolving iodine content caps and emerging organic certification requirements as coastal sourcing regions face intensifying ocean quality scrutiny.
Market Dynamics
Enzymatic extraction technology is bifurcating the fucoidan extract landscape, creating divergent margin pools between pharmaceutical-grade producers investing in bioactive preservation and commodity suppliers relying on acid-based cost structures.
Growth Catalysts
- Japan's FOSHU Framework:Functional food and beverage manufacturers leverage this regulatory pathway to launch immune-support SKUs with validated health claims, expanding the addressable consumer base beyond supplement aisles.
- Enzymatic Extraction Advancement:Biotechnology firms deploy cellulase and fucoidanase protocols that preserve sulfate group integrity, unlocking pharmaceutical contract manufacturing opportunities previously inaccessible to seaweed processors.
- Coastal East Asian Processing Infrastructure:South Korean and Chinese brown seaweed harvesters command integrated cold-chain logistics from vessel to extraction facility, compressing raw material degradation windows and securing supply security for nutraceutical formulators.
Market Restraints
- Input Cost Volatility:Wild kelp and wakame biomass prices fluctuate with ocean temperature anomalies and seasonal harvest yields, squeezing margin predictability for non-vertically integrated extractors.
- Supply Concentration Risk:Tasmanian and Hokkaido kelp beds supply dominant shares of pharmaceutical-grade raw material, exposing buyers to single-source disruption from marine heatwaves or territorial fishing disputes.
- Regulatory Friction:EFSA novel food evaluations impose 18-24 month approval timelines for unconventional seaweed species, delaying European market entry for innovators sourcing from non-traditional waters.
Strategic Opportunities
- Underpenetrated Dermatology Applications:Topical wound-healing and anti-inflammatory formulations represent nascent demand verticals where sulfate-rich fucoidan profiles command formulation premiums in cosmeceutical pipelines.
- US Dietary Supplement Channel Expansion:FDA notification pathways for New Dietary Ingredients offer faster commercialization than pharmaceutical routes, attracting brands seeking immune-positioning differentiation in crowded supplement shelves.
- Organic Certification Tailwind:EU organic aquaculture standards and USDA National Organic Program seaweed criteria create price-premium positioning for harvesters achieving third-party certification ahead of coastal water quality scrutiny intensification.
Industry Challenges
- Specialized Extraction Engineering Talent:Bioprocess engineers with simultaneous expertise in marine polysaccharide chemistry and GMP pharmaceutical manufacturing command scarcity premiums, constraining facility scale-up timelines.
- Batch-to-Batch Standardization Complexity:Natural seaweed biomass variation in fucose content and molecular weight distributions forces extractors to maintain expensive in-house analytical laboratories for pharmaceutical client compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fucoidan Extract Market |
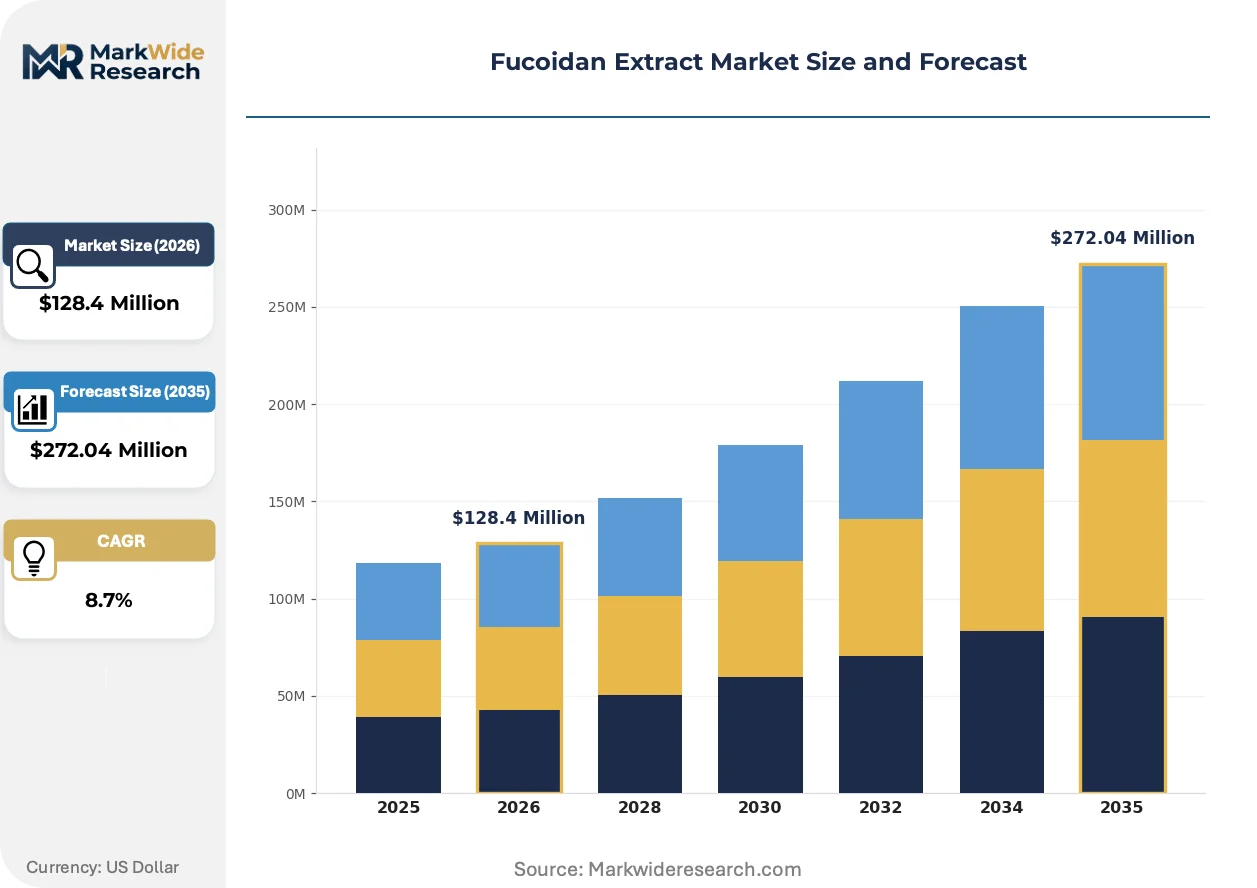
| Market Size in 2026 | $128.4 Million |
| Market Size in 2035 | $272.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Extract, Refined Extract, Powdered Form, Liquid Form, Concentrate Application: Dietary Supplements, Functional Beverages, Pharmaceuticals, Cosmetics, Animal Nutrition Extraction Technology: Enzymatic Extraction, Acid Extraction, Solvent Extraction, Ultrasonic Extraction, Microwave-Assisted Extraction End User Industry: Pharmaceutical Manufacturers, Nutraceutical Companies, Personal Care Brands, Veterinary Industry, Food Processing Units |
| Companies Covered | Marinova Pty Ltd., Merck KGaA, Yaizu Suisankagaku Industry Co. Ltd, Biosynth Ltd., Hi Q Marine Biotech International Ltd., Lantmannen, Kerry Group PLC, Koninklijke DSM NV, Qingdao Seawin Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fucoidan Extract Market Shifts & Advancements
Bioprocess engineering advances and regulatory pathway diversification are compressing traditional extraction economics while opening premium positioning opportunities for manufacturers mastering molecular characterization documentation.
Cell-free enzymatic cascades are integrating into continuous-flow reactor designs that replace batch acid hydrolysis in high-purity production lines. Pharmaceutical contract manufacturers in Japan and South Korea adopt these systems to meet sulfate profile certification requirements for oncology adjuvant trials. This technology is integrating quality assurance directly into production workflow, eliminating separate downstream purification stages and reducing batch rejection rates.
REACH registration requirements for novel seaweed-derived substances are compelling European extractors to submit full toxicological dossiers before commercial scale-up. Industrial consequence includes delayed market entry for startups lacking regulatory affairs capital, while incumbent suppliers with existing registrations capture formulation partnerships. Cosmetic and nutraceutical brands most affected are consolidating supplier bases toward established registrants with documented safety profiles.
Long-term supply agreements with specified sulfate content and molecular weight ranges are displacing spot-market raw material purchasing among major nutraceutical brands. This procurement evolution concentrates volume commitments with vertically integrated harvester-extractors capable of multi-year biomass planning. The shift is most visible in South Korea, where MFDS-mandated heavy metal documentation requirements favor suppliers with captive testing infrastructure and traceable farm-to-extractor chain-of-custody systems.
Fucoidan Extract Market Segmentation
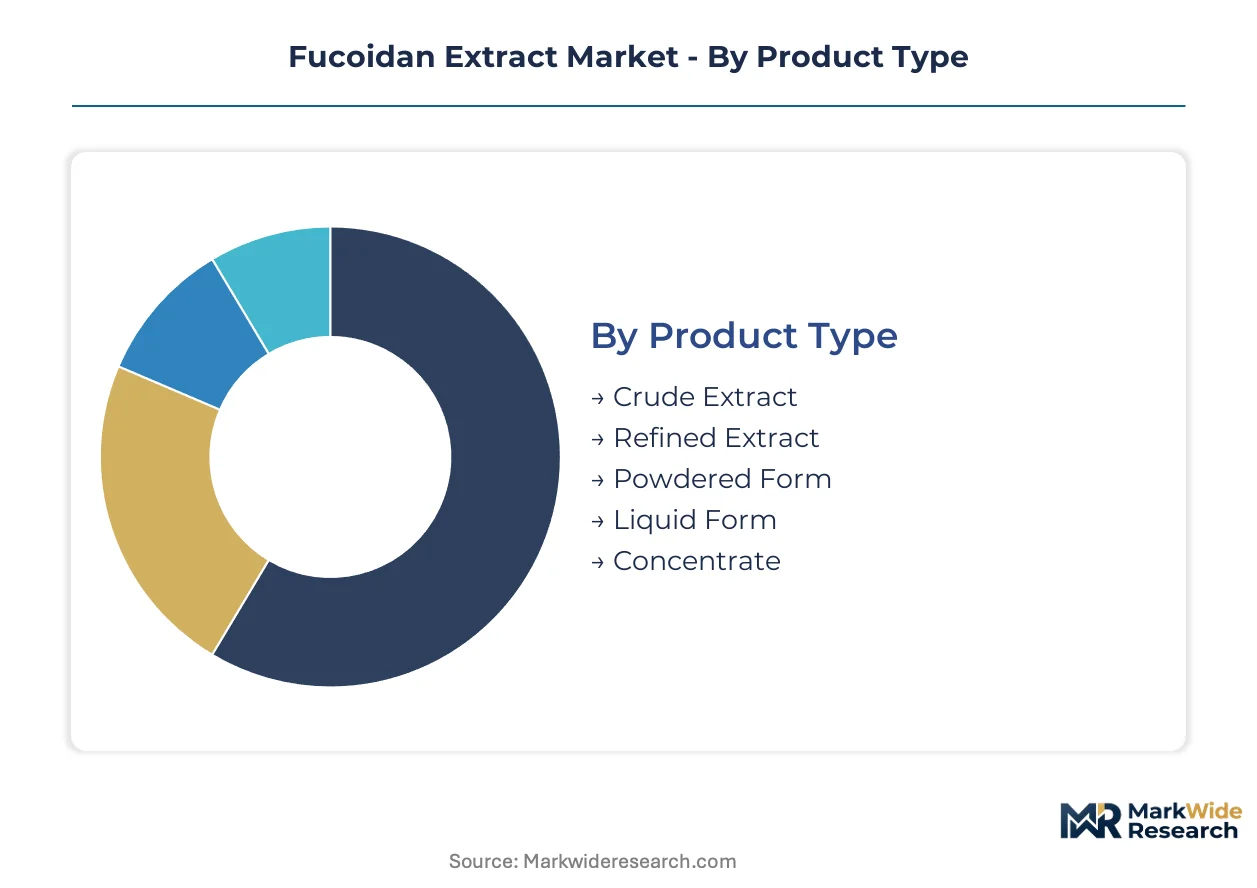
Fucoidan extract segmentation reflects divergent buyer priorities across purity tiers, application channels, and extraction sophistication. Manufacturers configure product portfolios around margin pools that separate pharmaceutical-grade specifications from commodity nutraceutical volumes.
Product Type:
Purchasing decisions hinge on purity thresholds and documentation requirements rather than format alone.
- Crude Extract:Sulfated polysaccharide mixtures with 40-60% fucose content serve bulk nutraceutical formulators in South Korea and China seeking cost-efficient immune-positioning inputs. Coastal processors with captive kelp supply dominate contract manufacturing for this tier.
- Refined Extract:Pharmaceutical-grade outputs achieving 85%+ purity with certified sulfate profiles command formulation partnerships with oncology adjuvant developers in Japan. Tasmanian and Hokkaido harvesters with integrated cold-chain logistics capture premium positioning through batch-certified molecular characterization.
- Powdered Form:Shelf-stable format preferred by capsule and tablet manufacturers across Southeast Asian supplement channels.
- Liquid Form:Functional beverage developers in Japan's FOSHU framework favor this format for ready-to-drink immune support SKUs.
- Concentrate:High-potency inputs for veterinary applications and specialized cosmeceutical formulations requiring minimal excipient loading.
Crude extract leads on scale; refined extract leads on momentum.
Application:
Channel economics vary sharply between regulated health claims and discretionary wellness positioning.
- Dietary Supplements:Volume anchor segment where capsule and softgel manufacturers source both crude and refined grades depending on price-positioning strategy. US FDA New Dietary Ingredient notifications create faster commercialization pathways than pharmaceutical routes.
- Functional Beverages:Japanese manufacturers leverage FOSHU approvals to launch immune-support drinks with validated label claims. Enzymatic extraction preserves bioactive integrity for shelf-stable liquid formulations.
- Pharmaceuticals:Adjuvant and wound-healing applications demand documented sulfate profiles and molecular weight distributions. EMA and PMDA clinical trial material requirements filter supplier qualification.
- Cosmetics:Topical anti-inflammatory and moisture-retention formulations represent nascent demand verticals where sulfate-rich profiles command formulation premiums.
- Animal Nutrition:Aquaculture feed and companion animal supplements drive steady demand for mid-grade concentrates with iodine content documentation.
Dietary supplements anchor current revenue; functional beverages are climbing the fastest.
Extraction Technology:
Technology selection determines access to pharmaceutical contract manufacturing versus commodity nutraceutical supply.
- Enzymatic Extraction:Cellulase and fucoidanase protocols preserve sulfate group integrity for high-purity pharmaceutical applications. Japanese and South Korean manufacturers adopt continuous-flow reactor designs to eliminate downstream purification stages.
- Acid Extraction:Cost-dominant method for crude extract production serving bulk nutraceutical buyers. Hydrochloric or sulfuric acid hydrolysis degrades some bioactive fractions but achieves lower unit economics.
- Solvent Extraction:Ethanol-based methods for specialized applications requiring selective polysaccharide fractionation.
- Ultrasonic Extraction:Emerging mechanical disruption technique reducing extraction time and solvent requirements for mid-tier processors.
- Microwave-Assisted Extraction:Accelerated thermal processing for small-batch custom extractors serving research and cosmetic clients.
Acid extraction dominates volume throughput; enzymatic extraction dominates value capture.
End User Industry:
Customer capabilities in analytical testing and regulatory affairs determine supplier selection criteria.
- Pharmaceutical Manufacturers:Demand batch-certified purity with full chain-of-custody documentation for clinical trial material. REACH registration requirements in Europe and MFDS heavy metal thresholds in South Korea concentrate purchasing with vertically integrated harvester-extractors.
- Nutraceutical Companies:Volume buyers balancing cost efficiency with basic purity verification through third-party testing.
- Personal Care Brands:Cosmeceutical formulators seeking sulfate-rich profiles for topical wound-healing and anti-inflammatory claims.
- Veterinary Industry:Aquaculture feed producers and companion animal supplement brands with specialized iodine content specifications.
- Food Processing Units:Functional food manufacturers navigating novel food evaluations for unconventional seaweed sources.
Nutraceutical companies provide the broadest customer base; pharmaceutical manufacturers deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine bioprocessing engineers cluster along coastal brown seaweed harvesting corridors in East Asia and Tasmania, anchoring extraction capacity to kelp bed proximity.
Japan
Functional beverage manufacturers drive demand through FOSHU-approved immune support SKUs. PMDA pharmaceutical-grade documentation requirements filter supplier qualification toward integrated harvester-extractors. Yaizu City in Shizuoka Prefecture concentrates enzymatic extraction facilities serving oncology adjuvant developers.
China
Coastal processors in Shandong and Fujian provinces leverage integrated cold-chain logistics from vessel to extraction facility. SAMR novel food evaluations for unconventional seaweed sources constrain European-bound export timelines. Qingdao anchors contract manufacturing for mid-grade nutraceutical concentrates.
South Korea
MFDS-mandated heavy metal and iodine thresholds favor vertically integrated harvesters with captive testing laboratories. Jeju Island kelp beds supply pharmaceutical-grade raw material to domestic enzymatic extraction specialists. Busan-Ulsan corridor concentrates GMP-certified facilities for clinical trial material production.
Australia
Tasmanian kelp harvesters command premium positioning through batch-certified purity for pharmaceutical-grade refined extracts. TGA therapeutic goods registration requirements concentrate purchasing with established registrants. Hobart-region facilities integrate continuous-flow reactor designs eliminating downstream purification stages.
United States
FDA New Dietary Ingredient notification pathways attract brands seeking faster commercialization than pharmaceutical routes. California and Pacific Northwest coastal regions host research-stage extraction operations serving cosmeceutical formulators. USDA National Organic Program seaweed criteria create price-premium positioning for certified harvesters.
Fucoidan Extract Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin pools. The vendor base separates between vertically integrated harvester-extractors commanding pharmaceutical-grade certification and commodity processors serving bulk nutraceutical buyers. Three archetypes dominate: Tasmanian kelp-anchored purity specialists, Japanese FOSHU-aligned functional beverage suppliers, and European enzymatic protocol developers. Competitive moves concentrate on backward integration into captive kelp supply and technology licensing for continuous-flow reactor designs.
Within the purity-specialist tier, Marinova Pty Ltd. and Yaizu Suisankagaku Industry Co. Ltd exemplify geographic anchoring to kelp bed proximity. Biosynth Ltd. occupies a position among enzymatic protocol developers serving European nutraceutical clients. These three represent distinct competitive vectors: Tasmanian raw material dominance, Japanese regulatory alignment, and custom bioprocess engineering.
| Leading Market Players |
|---|
| Marinova Pty Ltd. |
| Merck KGaA |
| Yaizu Suisankagaku Industry Co. Ltd |
| Biosynth Ltd. |
| Hi Q Marine Biotech International Ltd. |
| Lantmannen |
| Kerry Group PLC |
| Koninklijke DSM NV |
| Qingdao Seawin Biotech |
| Others |
Supply & Pricing Matrix
Family-owned kelp harvesters in Hokkaido and Tasmania anchor the upstream tier, their multi-generational biomass stewardship creating pricing discipline that resists spot-market volatility while pharmaceutical buyers absorb premiums for documented chain-of-custody. Their captive cold-chain infrastructure compresses degradation windows, forcing commodity processors toward acid-extraction cost structures that surrender margin to enzymatic specialists.
Pricing Analysis
Bundled molecular-characterization services separate pharmaceutical-grade contracts from unbundled crude extract spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds and documentation depth, with batch-certified sulfate profiles commanding formulation premiums from Japanese oncology adjuvant developers. Price differentiation hinges on certification grade and vertical integration depth, as Tasmanian harvesters with in-house GMP laboratories capture margin pools unavailable to non-integrated processors. Pricing pressure stems from South Korean and Chinese acid-extraction capacity expansion feeding bulk nutraceutical buyers. Contract manufacturers sourcing for FOSHU-aligned functional beverages exhibit lowest price sensitivity, while Southeast Asian capsule formulators drive commodity-tier negotiations.
Supply Chain Analysis
Regional distribution centers in Busan, Qingdao, and Hobart consolidate kelp biomass before enzymatic processing, creating hub-and-spoke patterns that compress raw material transit times. Geographic supply concentration centers on Australia, Japan, and South Korea for pharmaceutical-grade biomass, with China and South Korea dominating crude extract throughput. Raw material dependencies rest on Tasmanian and Hokkaido kelp bed yields, cellulase and fucoidanase enzyme supply, and GMP-certified packaging materials. Single-source vulnerability from marine heatwave exposure in Tasmanian waters threatens batch consistency for high-purity contracts. Distribution runs through vertically integrated harvester-extractors serving long-term offtake agreements with nutraceutical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fucoidan extract market functions as a stable compounder, its expansion anchored by Japan's FOSHU framework validating immune-support claims that convert skeptical consumers into repeat purchasers.
For Market Incumbents: Anticipate margin compression from South Korean acid-extraction capacity additions by deepening backward integration into Jeju Island and Tasmanian kelp bed leases. Prioritize enzymatic extraction scale-up in GMP-certified facilities to defend pharmaceutical contract manufacturing share against emerging Chinese bioprocess specialists. Certification investment in EU REACH registration and USDA organic aquaculture standards creates switching costs that lock in multinational nutraceutical partnerships. For New Entrants and Emerging Players: FDA New Dietary Ingredient notification pathways in the United States open a window for mid-grade refined extract positioning between pharmaceutical purity and commodity crude tiers. Target cosmeceutical formulators seeking sulfate-rich topical inputs, a white-space vertical where documentation requirements remain less stringent than pharmaceutical channels. Pursue direct-to-supplement-brand distribution bypassing established South Korean trading houses to capture margin otherwise surrendered to intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among acid-extraction commodity processors facing enzymatic technology obsolescence, presenting distressed turnaround opportunities for private equity with bioprocess engineering capabilities. Long-term viability favors vertically integrated harvester-extractors with captive kelp supply and multi-regional regulatory registrations that compound competitive moats across economic cycles. Monitor MFDS enforcement actions on heavy metal thresholds as an inflection signal concentrating purchasing toward integrated operators with in-house testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kelp Bed Leases | Tasmanian and Hokkaido biomass control secures pharmaceutical-grade raw material supply security against marine heatwave disruption. |
| Enzymatic Extraction Scale-Up | Continuous-flow reactor adoption eliminates downstream purification stages for Japanese oncology adjuvant contract manufacturers. |
| EU REACH Registration Completion | Toxicological dossier submission enables European commercialization ahead of startup competitors lacking regulatory affairs capital. |
| USDA Organic Aquaculture Certification | Price-premium positioning attracts wellness-channel brands anticipating intensified coastal water quality scrutiny. |
| Long-Term Supply Agreement Structuring | Multi-year offtake contracts with specified sulfate content displace spot-market purchasing among major nutraceutical brands. |
Research Methodology
Direct dialogue with extraction facility engineers, regulatory affairs specialists at nutraceutical formulators, kelp harvester cooperative managers, and pharmaceutical contract manufacturing procurement leads grounded qualitative assessment in operational reality. Secondary validation drew from MFDS enforcement bulletins, EFSA novel food evaluation registers, TGA therapeutic goods listings, and customs trade data on brown seaweed biomass flows. Bottom-up capacity modeling across enzymatic and acid-extraction facilities triangulated against top-down demand estimates from FOSHU-approved SKU launches and New Dietary Ingredient notifications.
Top-down macroeconomic drivers and bottom-up facility-level capacity assessments converged across the analysis window. Segmentation modeling incorporated purity tier, extraction technology, application channel, and end-user industry capabilities in analytical testing and regulatory affairs. CAGRs derived from regression analysis against historical kelp biomass yields and functional beverage launch velocities, with cross-validation against pharmaceutical clinical trial pipeline expansion for oncology adjuvant applications.
Revisions become necessary when marine heatwave frequency accelerates beyond historical baselines, enzymatic enzyme supply chains face disruption, or regulatory bodies tighten iodine content thresholds unexpectedly. Forecasts embed assumptions around FOSHU approval continuity, cold-chain infrastructure investment trajectories, and coastal water quality stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sodium Alginate Market
Ingredients
Bouillon Cubes Market
Ingredients
Ben Oil Market
Ingredients
Fiber Rich Flours Market
Ingredients
Europe Dairy Protein Market
Ingredients
Pet Food Ingredients Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Brewer's Yeast Market
Ingredients
Europe Potato Protein Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Diastatic Malt Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Specialty Flours Market
Ingredients
Vegetable Extract Market
Ingredients
North America Vegetable Oils Market
Ingredients
Rice Bran Fatty Alcohols Market