
 Green Ammonia Market | 2026-2036
Green Ammonia Market Size, Share, and Industry Trends Forecast 2026-2036
Green Ammonia Market Intelligence
Expertise in large-scale electrolyzer deployment and renewable energy project management is bifurcating the market. Established chemical producers like Yara International leverage existing ammonia infrastructure and distribution networks. Technology specialists such as Siemens Energy and Nel ASA focus on providing the core electrolysis and process engineering capabilities. ThyssenKrupp competes by offering integrated plant engineering solutions from electrolysis to ammonia synthesis.
Green ammonia is a form of ammonia (NH3) produced without fossil fuels. The process uses hydrogen derived from water electrolysis powered by renewable electricity, which is then combined with nitrogen in a Haber-Bosch reactor. While agriculture remains the largest end-user for fertilizers, the energy sector is emerging as a critical growth driver. Electrochemical and thermochemical technologies represent the leading production pathways being scaled for industrial use.
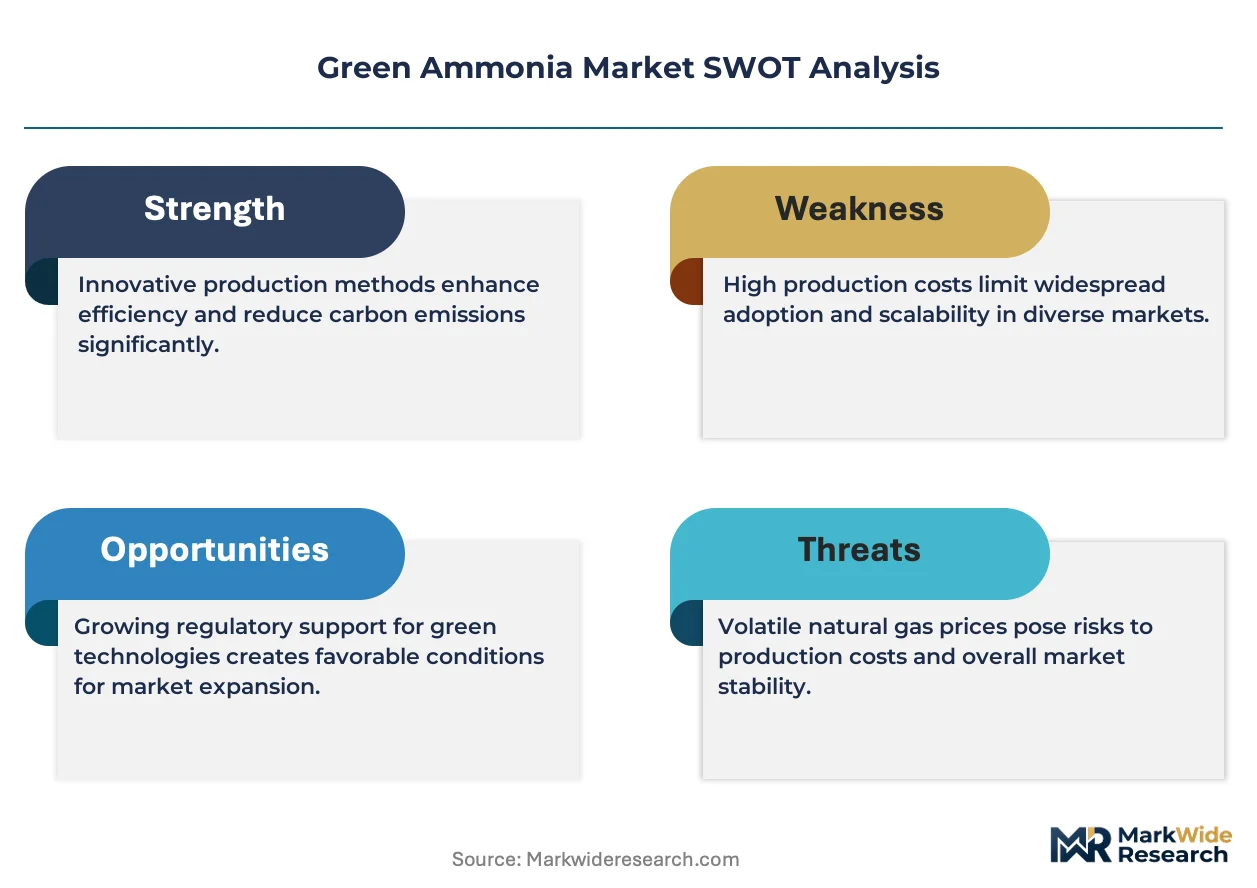
Regulatory frameworks are essential for market creation. The EU's Renewable Energy Directive and the US Inflation Reduction Act (IRA) create direct financial incentives for green ammonia production. These policies, alongside national hydrogen strategies in Japan and South Korea, establish demand signals and de-risk investments. The primary challenge for producers is securing long-term, low-cost renewable power purchase agreements.
Market Dynamics
The green ammonia market's structure is being defined by the dual pursuit of its use as a maritime fuel and as a stable hydrogen carrier for export. This creates a powerful demand signal that is pulling forward massive investment in production hubs, often located in regions with abundant renewable energy potential.
Growth Catalysts
- Policy Incentives:The US Inflation Reduction Act provides significant production tax credits, while the EU's Green Deal establishes a regulatory framework and demand-side mandates that de-risk large-scale capital investments in new green ammonia facilities.
- Maritime Decarbonization:The global shipping industry is actively seeking low-carbon fuel alternatives to meet stringent emissions regulations, with green ammonia emerging as a leading candidate for long-haul vessels due to its energy density.
- Electrolyzer Advancements:Continuous improvements in the efficiency, scale, and cost-effectiveness of water electrolysis technologies, such as PEM and alkaline electrolyzers, are making green hydrogen production, the precursor to green ammonia, more economically viable.
Market Restraints
- Renewable Energy Costs:The high price and intermittent nature of renewable electricity, which can constitute a significant portion of total production costs, remains a primary barrier to achieving cost parity with conventional grey ammonia.
- Infrastructure Deficits:A lack of dedicated global infrastructure for green ammonia storage, transportation, and bunkering at ports creates logistical bottlenecks that hinder its widespread adoption as a traded commodity and marine fuel.
- Conversion Efficiency Losses:The energy-intensive Haber-Bosch process and subsequent cracking of ammonia back to hydrogen result in significant round-trip energy losses, challenging its efficiency as a hydrogen carrier compared to direct hydrogen transport.
Strategic Opportunities
- Export-Oriented Hubs:Development of large-scale production facilities in regions with low-cost solar and wind resources, such as Australia, the Middle East, and Chile, creates an opportunity to supply energy-importing nations like Japan and Germany.
- Grid-Scale Energy Storage:Green ammonia can be used for long-duration energy storage, providing a method to store excess renewable energy for weeks or months and release it during periods of low generation, enhancing grid stability.
- Advanced Synthesis Pathways:Research into alternative, low-pressure, and low-temperature ammonia synthesis methods, including electrochemical and thermochemical routes, presents an opportunity to bypass the capital-intensive Haber-Bosch process and improve overall efficiency.
Industry Challenges
- Capital Intensity:The development of gigawatt-scale green ammonia projects requires enormous upfront capital investment for electrolyzers, renewable power generation, and synthesis loops, posing a significant financing challenge for project developers.
- Certification and Standardization:Establishing a globally recognized certification scheme to verify the green credentials of ammonia is essential for trade but faces complexities in defining emissions boundaries and tracking methodologies across different jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Ammonia Market |
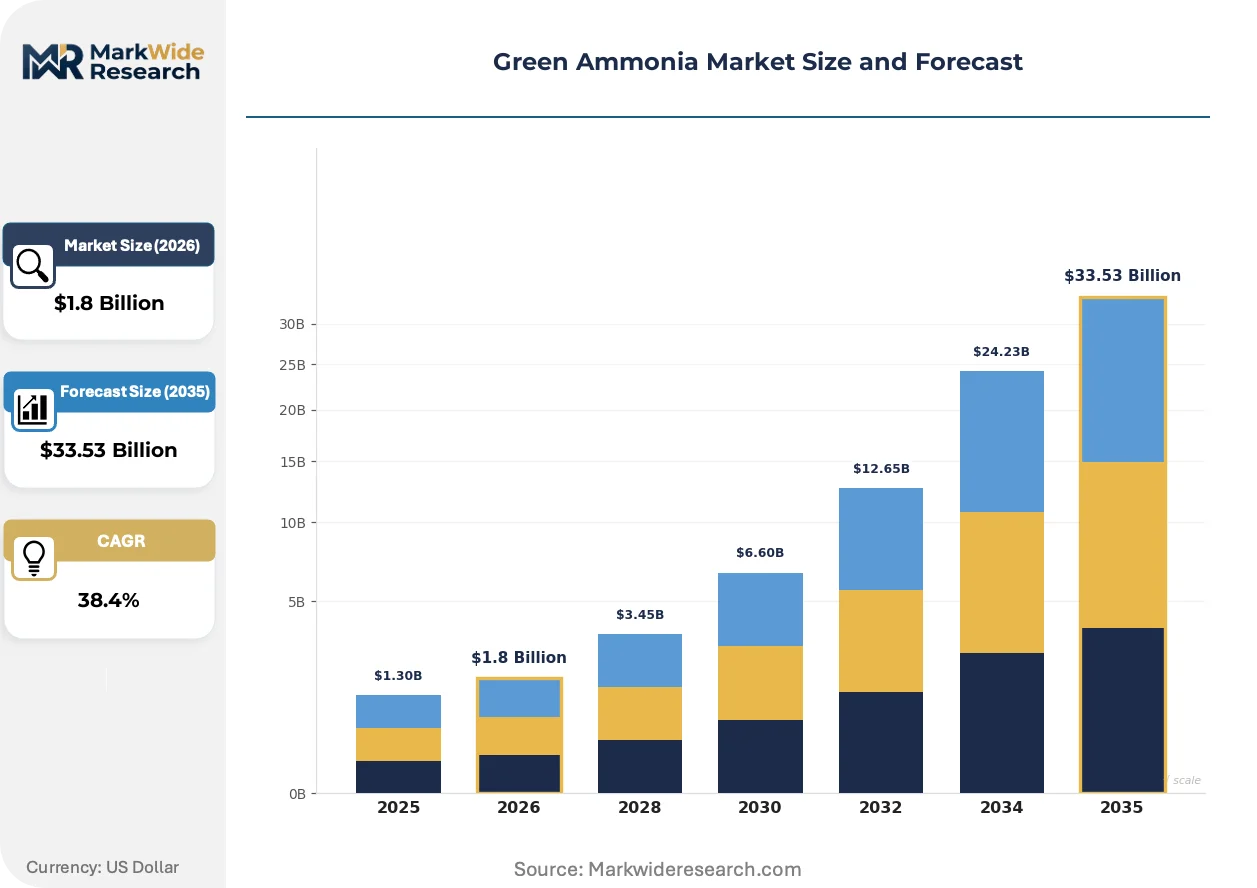
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Ammonia, Solid Ammonia, Anhydrous Ammonia, Aqueous Ammonia Technology: Electrochemical, Haber-Bosch, Thermochemical, Photochemical End User: Agriculture, Chemicals, Energy, Pharmaceuticals Application: Fertilizers, Energy Storage, Fuel Cells, Refrigeration |
| Companies Covered | Yara International, Siemens Energy, CF Industries Holdings, Nel ASA, ACME Group, ThyssenKrupp, Ørsted, Air Products and Chemicals, ENGIE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Ammonia Market Strategic Shifts & Innovations
The convergence of energy policy, chemical process engineering, and logistics is creating new industrial ecosystems. This integration is forcing a re-evaluation of traditional commodity supply chains, with value shifting towards those who can manage complex, multi-stage green energy conversion projects.
Advanced electrolysis technology, particularly Solid Oxide Electrolysis Cells (SOEC), provides a high-temperature pathway to produce hydrogen with greater electrical efficiency. Project developers focused on maximizing output are evaluating these next-generation systems for new builds. This adoption is bifurcating the market between producers leveraging cutting-edge, high-efficiency technologies and those deploying more mature, bankable alkaline or PEM systems.
The European Union's Renewable Energy Directive (RED II) and its associated RFNBO mandates create a clear, legally binding demand signal. This policy forces industrial consumers and transport fuel suppliers within the EU to procure certified green hydrogen and its derivatives. The chemical and refining sectors in Germany and the Netherlands are most directly impacted, accelerating their efforts to secure long-term supply contracts for green ammonia.
A fundamental shift toward long-term, fixed-price offtake agreements is defining procurement patterns for green ammonia. This model is supplanting the spot-price-driven dynamics of the conventional grey ammonia market, providing the revenue certainty needed to finance large-scale projects. This trend is most prominent in supply agreements originating from production hubs in Australia and the Middle East, destined for energy utilities and industrial conglomerates in South Korea and Japan.
Green Ammonia Market Segmentation
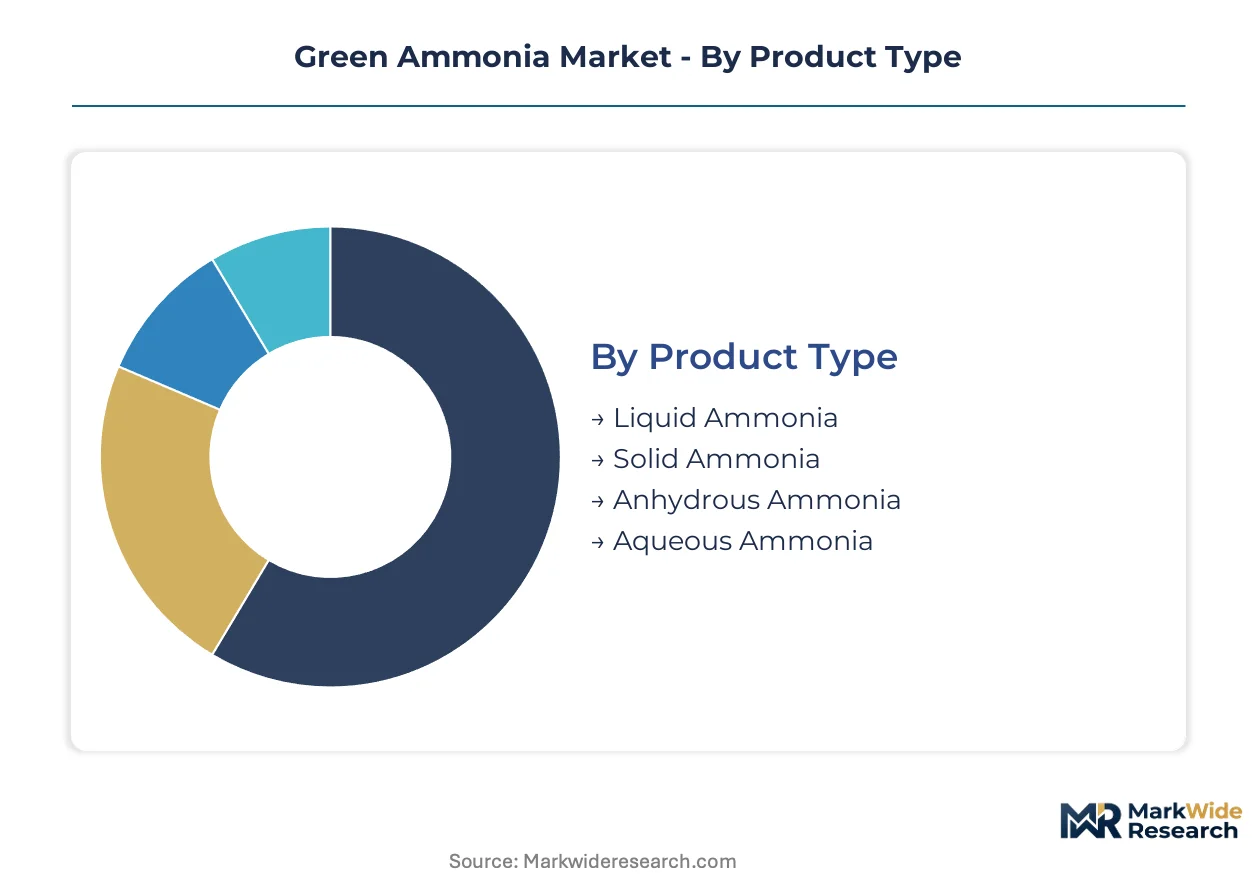
The green ammonia market segments across various dimensions, revealing distinct value propositions and demand patterns. Understanding these segments helps stakeholders identify key growth areas and technological adoption trends. This granular view assists in strategic planning and investment allocation for producers and consumers alike.
Product Type:
The green ammonia product type segments show varied adoption patterns, with some forms dominating domestic use and others geared for international trade.
- Liquid Ammonia:This form is ammonia cooled to -33°C or compressed, facilitating bulk transport and storage across global supply chains. Demand concentrates in maritime bunkering hubs like Rotterdam and Singapore, driven by the shipping industry's decarbonization mandates.
- Anhydrous Ammonia:This highly concentrated form contains virtually no water, making it a preferred choice for large-scale industrial applications and agricultural fertilizers. Its demand is significant in agricultural regions of the US Midwest and industrial clusters in Germany, supported by existing infrastructure.
- Solid Ammonia:Solid ammonia, often in the form of ammonium salts, offers safer handling for specific industrial processes and specialized chemical production.
- Aqueous Ammonia:This diluted solution of ammonia in water is used in niche chemical processes, industrial cleaning, and emissions control systems.
Anhydrous Ammonia commands the established base. The steepest expansion runs through Liquid Ammonia.
Technology:
Green ammonia production technologies range from established industrial processes to nascent, high-potential research pathways, influencing capital expenditure and operational efficiency.
- Haber-Bosch:This mature, energy-intensive process synthesizes ammonia from hydrogen and nitrogen under high pressure and temperature, leveraging decades of operational experience. Demand for this technology concentrates in large-scale production facilities in the Middle East and Australia, aiming for economies of scale.
- Electrochemical:This emerging technology uses electricity to directly synthesize ammonia at lower temperatures and pressures, potentially integrating with intermittent renewable power sources. Its demand is growing for distributed production and in regions with abundant renewable electricity, like Norway.
- Thermochemical:Thermochemical routes explore various catalyst and temperature regimes to optimize ammonia synthesis efficiency and reduce energy consumption.
- Photochemical:Photochemical methods utilize light energy to drive ammonia synthesis, representing a long-term, highly sustainable research frontier for direct solar energy conversion.
The market is experiencing a shift from Haber-Bosch towards Electrochemical technologies for future growth.
End User:
End-user segments for green ammonia reflect its diverse utility, from essential food production to novel energy applications, each with distinct procurement requirements.
- Agriculture:This sector utilizes green ammonia primarily as a nitrogen-rich fertilizer, crucial for global food security and crop yield enhancement. Demand remains globally significant, particularly in regions with intensive farming practices such as Brazil and India, seeking sustainable input materials.
- Energy:The energy sector consumes green ammonia as a carbon-free fuel and a hydrogen carrier, supporting decarbonization efforts across various industries. Demand is rapidly expanding in maritime shipping and power generation in Japan and South Korea, driven by stringent emissions regulations.
- Chemicals:The chemicals industry uses green ammonia as a feedstock for producing plastics, fibers, and other industrial compounds, transitioning from fossil-derived sources.
- Pharmaceuticals:The pharmaceutical sector employs high-purity green ammonia in specific synthesis processes, as a reagent, and for maintaining controlled atmospheric conditions.
Agriculture remains the foundational consumer, while Energy offers the most significant expansion potential.
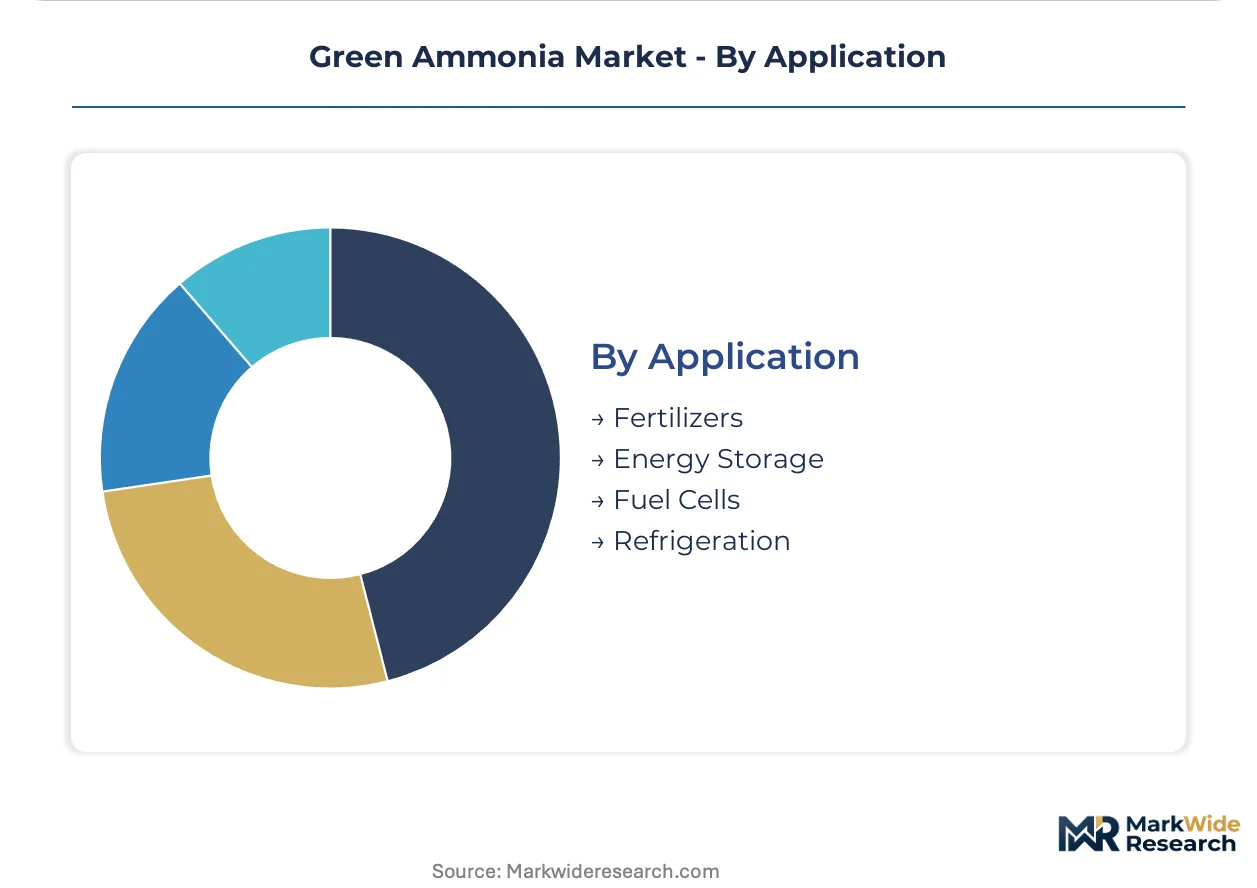
Application:
Green ammonia applications span high-volume industrial uses to specialized, high-value niches, each presenting unique market dynamics and growth trajectories.
- Fertilizers:As a primary source of nitrogen, green ammonia directly supports agricultural productivity by enriching soil and boosting crop growth. This application commands the largest volume globally, with demand sustained by continuous food production needs in regions like China and the United States.
- Energy Storage:Green ammonia functions as a medium for storing renewable energy over long durations, converting excess power into a chemical form for later use. This application is gaining traction in grid-stabilization projects in Australia and Chile, where renewable energy intermittency is a concern.
- Fuel Cells:Green ammonia can be directly or indirectly used in fuel cells to generate electricity, particularly for heavy-duty transport, remote power, and stationary power generation.
- Refrigeration:Ammonia's thermodynamic properties make it an effective refrigerant for industrial cooling systems, cold storage facilities, and large-scale air conditioning.
The market for Fertilizers is mature, whereas Energy Storage applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act provides substantial financial incentives, positioning the United States for significant green ammonia development. Policy frameworks across several nations are de-risking large-scale capital investments. This creates distinct regional demand and supply dynamics.
United States
Agricultural fertilizers represent a foundational demand, alongside emerging energy sector applications for green ammonia. The US Inflation Reduction Act (IRA) provides critical production tax credits for green hydrogen, a direct precursor. The Gulf Coast region is attracting significant investment for new large-scale green ammonia production facilities.
Germany
Industrial decarbonization and chemical feedstock transformation drive green ammonia procurement in Germany. The EU's Renewable Energy Directive (RED II) mandates green hydrogen and derivative use for industrial consumers. The Ruhr industrial cluster and ports like Hamburg are preparing for increased green ammonia imports and usage.
Japan
Energy security and maritime decarbonization are primary demand signals for green ammonia in Japan. Japan's national hydrogen strategy establishes clear import targets for clean hydrogen carriers. Major ports such as Yokohama and Kobe are developing bunkering infrastructure for ammonia-powered vessels.
Australia
Abundant low-cost renewable energy resources position Australia as a major export-oriented green ammonia producer. The Australian government supports large-scale renewable energy projects through various investment funds. Western Australia and Queensland are developing massive production hubs to supply energy-importing nations.
Saudi Arabia
Saudi Arabia leverages its vast solar and wind potential to become a global leader in green hydrogen and ammonia exports. The Saudi Green Initiative aims to reduce emissions and diversify the economy through clean energy projects. NEOM is constructing one of the world's largest green hydrogen and ammonia production facilities for international markets.
Green Ammonia Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the green ammonia market's competitive structure. This market bifurcates between established chemical producers leveraging existing infrastructure and technology-focused electrolysis providers. Strategic archetypes include large-scale project developers, integrated engineering solutions providers, and specialized technology vendors for specific process steps. Capacity expansion, often through gigawatt-scale projects, and strategic partnerships for renewable energy procurement are dominant competitive moves among market participants.
Within the established chemical producer archetype, Yara International exemplifies a player leveraging extensive existing ammonia infrastructure and global distribution networks for fertilizer markets. Technology specialists such as Siemens Energy focus on providing core electrolysis and process engineering capabilities, critical for green hydrogen production. ThyssenKrupp occupies a position as an integrated plant engineering solutions provider, offering comprehensive development from initial electrolysis to full ammonia synthesis plants. These entities collectively demonstrate the diverse approaches to capturing value across the green ammonia supply chain.
| Leading Market Players |
|---|
| Yara International |
| Siemens Energy |
| CF Industries Holdings |
| Nel ASA |
| ACME Group |
| ThyssenKrupp |
| Ørsted |
| Air Products and Chemicals |
| ENGIE |
| Others |
Cost & Logistics Intelligence
Long-term, fixed-price offtake agreements define green ammonia procurement, securing supply access and providing crucial price visibility for project financing. This model supports massive capital investments in new production hubs.
Pricing Analysis
Significant price spreads exist between export-oriented production hubs and energy-importing regions due to logistics and energy costs. Contract-based long-term offtake agreements dominate procurement, providing revenue certainty. Price differentiation stems from green certification levels and geographic delivery costs. Achieving cost parity with conventional grey ammonia remains a key challenge, particularly for agricultural buyers, while energy sector buyers prioritize supply security under decarbonization mandates.
Supply Chain Analysis
Australia and Saudi Arabia are rapidly developing large-scale green ammonia production capacity, leveraging abundant renewable energy resources. The supply chain depends on consistent access to low-cost renewable electricity and advanced electrolyzers for green hydrogen production. Infrastructure deficits for storage, transportation, and bunkering at ports create significant logistical bottlenecks. Global distribution runs through maritime routes, connecting production hubs to energy-importing nations like Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green ammonia market is entering a strong cyclical recovery, driven by escalating global energy security concerns and decarbonization mandates. This momentum pulls forward massive investment into new production capacity.
For Market Incumbents:Compound existing ammonia infrastructure with advanced green hydrogen production capabilities to maintain market share against technology specialists. Invest in long-term, low-cost renewable power purchase agreements to mitigate high energy cost volatility. This strategy protects against margin erosion from novel production pathways and secures feedstock for established distribution networks.
For New Entrants and Emerging Players:Rapid certification pathways for green ammonia provide a critical entry point for new market participants. Target regions with abundant, low-cost renewable resources like Australia for export-oriented production hubs. Develop specialized electrochemical synthesis technologies to offer a differentiated product, specifically for grid-scale energy storage applications.
For Investors and Strategic Acquirers:Project developers with secured long-term power purchase agreements represent attractive acquisition targets for long-term portfolio growth. The market offers substantial viability over the next decade, driven by decarbonization and energy security. Focus on technology specialists advancing electrochemical synthesis or large-scale electrolyzer deployment. The signal to watch is the establishment of a globally recognized certification scheme for green ammonia.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production facilities in Australia addresses rising demand from energy-importing nations. |
| Long-term Supply Agreement | Secures revenue certainty for producers and stable feedstock for industrial consumers in Germany. |
| Green Manufacturing Transition | Adopting advanced electrolysis technologies improves efficiency and reduces operational costs for producers. |
| Joint Venture | Partnerships between chemical producers and renewable energy developers accelerate project deployment. |
| Technology Licensing | Sharing electrochemical synthesis patents fosters wider adoption and reduces capital intensity for new entrants. |
Research Approach
A standing panel of plant managers, renewable energy project developers, and maritime logistics executives provided ongoing calibration for market data. This involved combining insights from primary interviews with extensive secondary validation from sources like the US Inflation Reduction Act and EU's Renewable Energy Directive. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Market outputs were consistently validated against external benchmarks, including national hydrogen strategies and maritime decarbonization targets, across the projection horizon. The analytical framework modeled segmentation dimensions such as product type, technology, and end-user application. Compound annual growth rates were derived from historical trends and projected advancements in electrolyzer efficiency. Renewable energy price forecasts served as a critical input.
Decision-makers should treat outputs as directional under current policy incentive assumptions; material deviation would warrant model refresh. Forecasts reflect a baseline scenario, acknowledging potential shifts in renewable energy costs or infrastructure development. Recalibration cycles align with material shifts in regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Sustainable Marine Fuel Market