
 Smart Power Technologies Market | 2026-2036
Smart Power Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Power Technologies Market Outlook
Silicon carbide is recalibrating cost structures across power conversion systems, enabling higher voltage operation and reduced thermal management overhead. Siemens Energy leverages its turbine-to-grid integration expertise to anchor European utility modernization programs. NextEra Energy sustains its competitive edge through renewable-to-storage project pipelines that embed smart power controls at scale.
Smart Power Technologies encompass digitally controlled hardware and software systems that manage generation, distribution, and consumption of electrical power, typically operating at frequencies from 50-60 Hz up to hundreds of kHz in power electronic converters. These systems employ real-time sensing, bidirectional communication, and automated control algorithms to optimize grid stability, integrate variable renewable sources, and reduce energy losses across transmission and distribution networks. Smart Grid Technology leads deployment value as utilities replace aging infrastructure with self-healing network architectures, while Energy Storage Solutions represents the fastest-expanding segment as lithium-ion and flow battery systems pair with intelligent inverters for frequency regulation and arbitrage. Demand Response Solutions occupies a mature but profitable niche where aggregated commercial and industrial loads provide grid services through automated curtailment protocols.
The US Federal Energy Regulatory Commission Order 2222 enables distributed energy resource aggregation in wholesale markets, compelling technology vendors to certify interoperability with regional transmission organizations. The EU F-Gas Regulation and CE marking requirements under the MDR framework constrain refrigerant-based cooling in power electronics and mandate electromagnetic compatibility testing for grid-connected equipment. Stakeholders must monitor how evolving carbon border adjustment mechanisms and state-level renewable portfolio standards reshape procurement criteria for smart power infrastructure investments.
Market Dynamics
Silicon carbide semiconductor adoption is compressing switching losses and thermal management costs across power conversion architectures, forcing incumbent silicon suppliers to defend position through price repositioning and foundry partnerships.
Growth Catalysts
- Energiwende Policy Framework:Germany's renewable integration mandates compel utilities to procure distributed energy resource management systems with bidirectional power flow capabilities.
- FERC Order 2222:The US regulation enables aggregated distributed resources to participate in wholesale markets, creating certified interoperability requirements for inverter and control system vendors.
- Silicon Carbide Substrates:Wider bandgap materials cut converter losses by half compared to silicon IGBTs, accelerating procurement in electric vehicle charging and solar inverter applications.
Market Restraints
- Substrate Supply Concentration:High-purity silicon carbide wafers concentrate among Japanese and US substrate manufacturers, creating input bottlenecks for European power module assemblers.
- EU F-Gas Regulation:Restrictions on fluorinated refrigerants constrain liquid cooling options for high-density power electronics in grid-scale converters.
- Copper and Rare Earth Volatility:Magnet materials and winding commodities face price swings that compress margin on permanent-magnet motor drives and transformer components.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for solar module and cell manufacturing create localized demand for smart inverters and grid-tied power electronics.
- Vehicle-to-Grid Integration:Bidirectional charging protocols converge with home energy management systems, opening residential markets for aggregated grid services.
- Green Hydrogen Electrolyzers:Gigawatt-scale renewable hydrogen projects require high-frequency power converters with precision current control, a specification gap few incumbent suppliers fill.
Industry Challenges
- Power Electronics Talent Scarcity:Design expertise in wide-bandgap device characterization and electromagnetic compatibility testing outpaces university pipeline output in Europe and North America.
- Multi-Standard Certification Burden:Grid codes diverge across Germany's VDE-AR-N, California's Rule 21, and Japan's JEAC, forcing redundant testing cycles for inverter platforms.
- Legacy SCADA Integration:Brownfield substations running decades-old communication protocols require costly protocol translation layers for smart sensor deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Power Technologies Market |
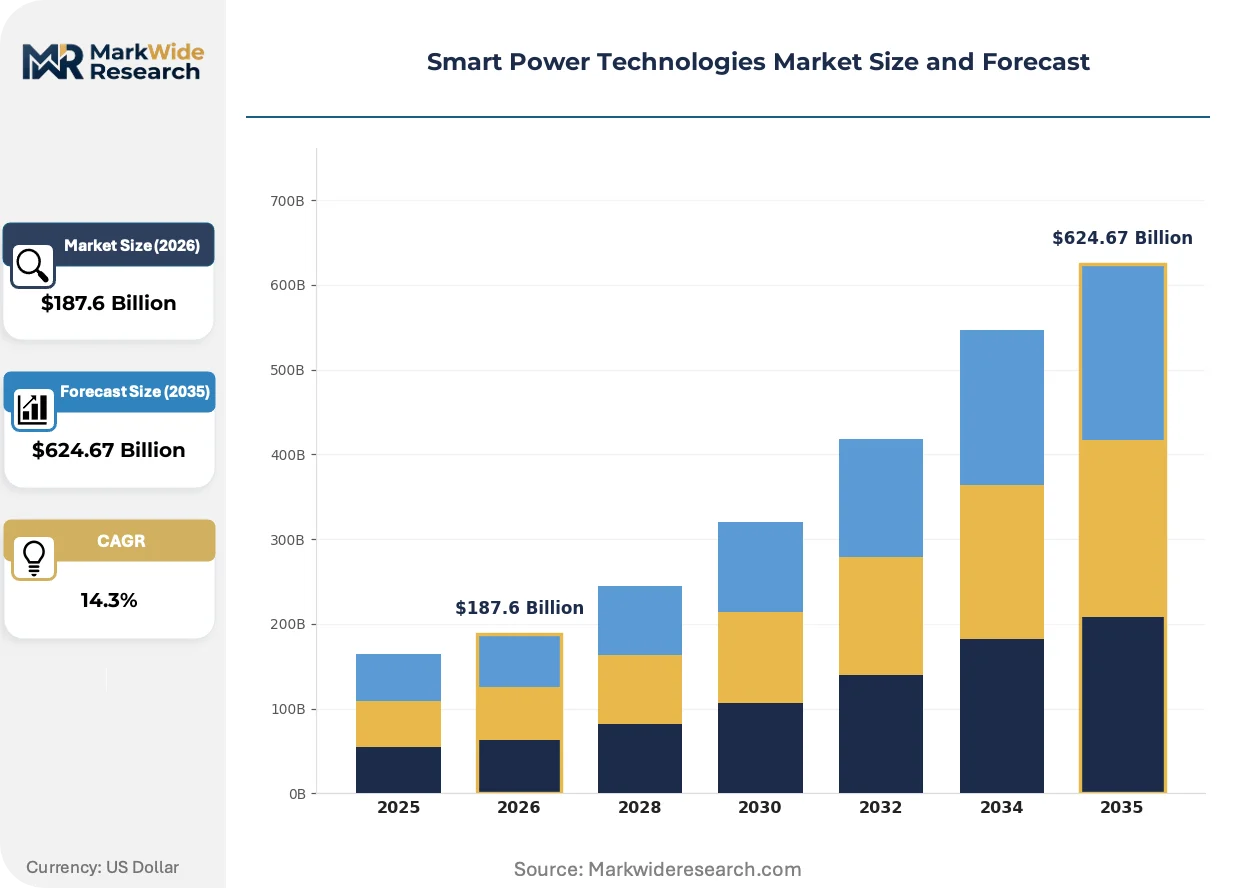
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
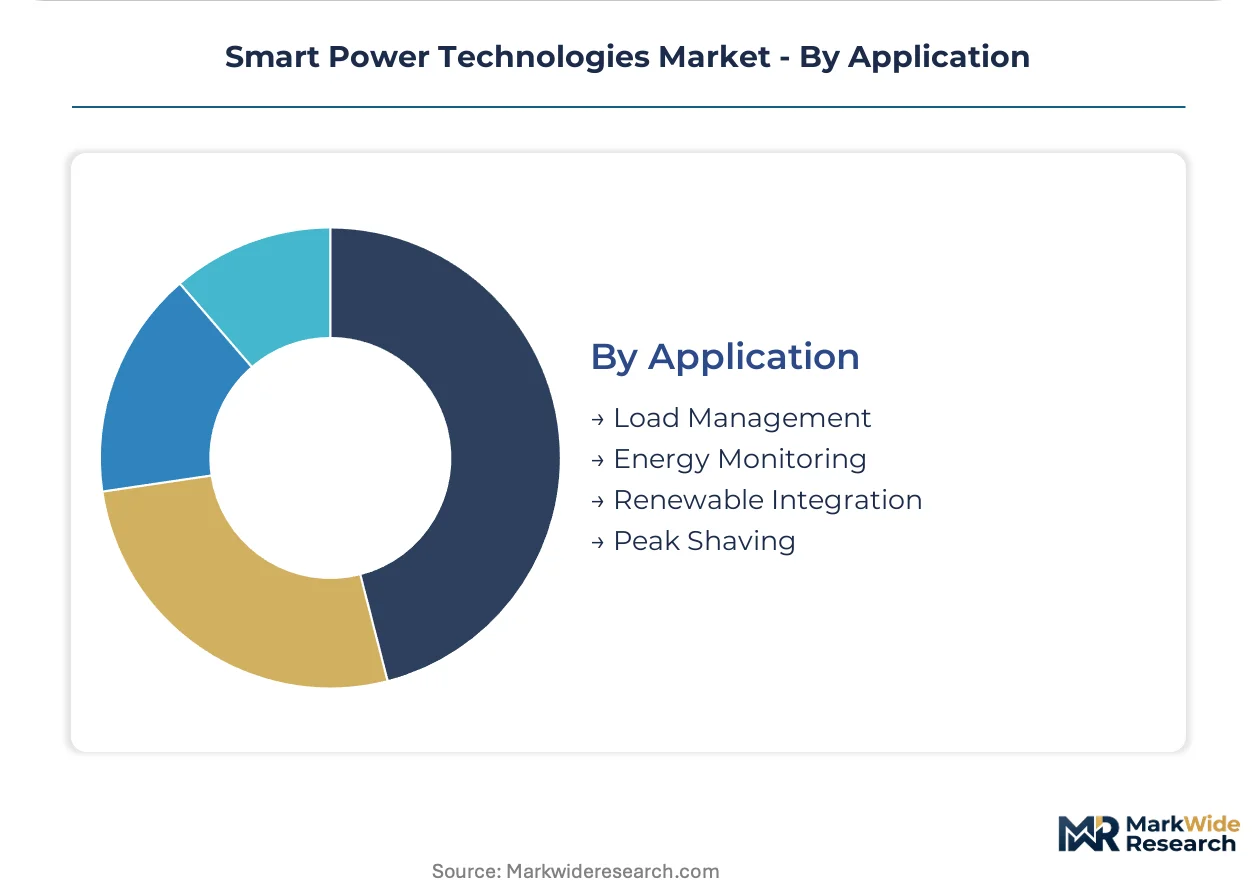
| Segmentation | Product Type: Smart Meters, Energy Management Systems, Power Conditioners, Demand Response Solutions Technology: IoT Integration, Advanced Metering Infrastructure, Energy Storage Solutions, Smart Grid Technology End User: Residential, Commercial, Industrial, Utilities Application: Load Management, Energy Monitoring, Renewable Integration, Peak Shaving |
| Companies Covered | American Electric Power Company, Public Service Enterprise Group, NextEra Energy, Siemens Energy, Bloom Energy, Vistra Corp, Xcel Energy, Toshiba, Sempra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Power Technologies Market Strategic Shifts
Power converter architectures are fragmenting into standardized sub-assemblies that slash engineering lead times and enable vendor substitution at the module level.
Silicon carbide MOSFET modules handle higher switching frequencies with lower losses than silicon IGBTs. Data center UPS and EV fast-charging station builders are standardizing on these packages within eighteen-month procurement cycles. The technology is modularizing converter design into swappable building blocks that compress customization overhead.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in liquid-cooled power electronics, pushing thermal designers toward dielectric fluid and two-phase immersion alternatives. Converter OEMs must requalify cooling systems under MDR electromagnetic compatibility frameworks. Grid-tied battery inverters for the German market face the tightest retesting burden.
Utility procurement departments now specify outcome-based availability contracts rather than equipment purchase orders, transferring operational risk to technology vendors. Engineering-procurement-construction firms and independent power producers are the channels being disrupted, with Siemens Energy and Schneider Electric restructuring sales organizations around performance guarantees. This pattern is most pronounced in Texas and California where merchant solar-plus-storage projects dominate interconnection queues.
Smart Power Technologies Market Segmentation
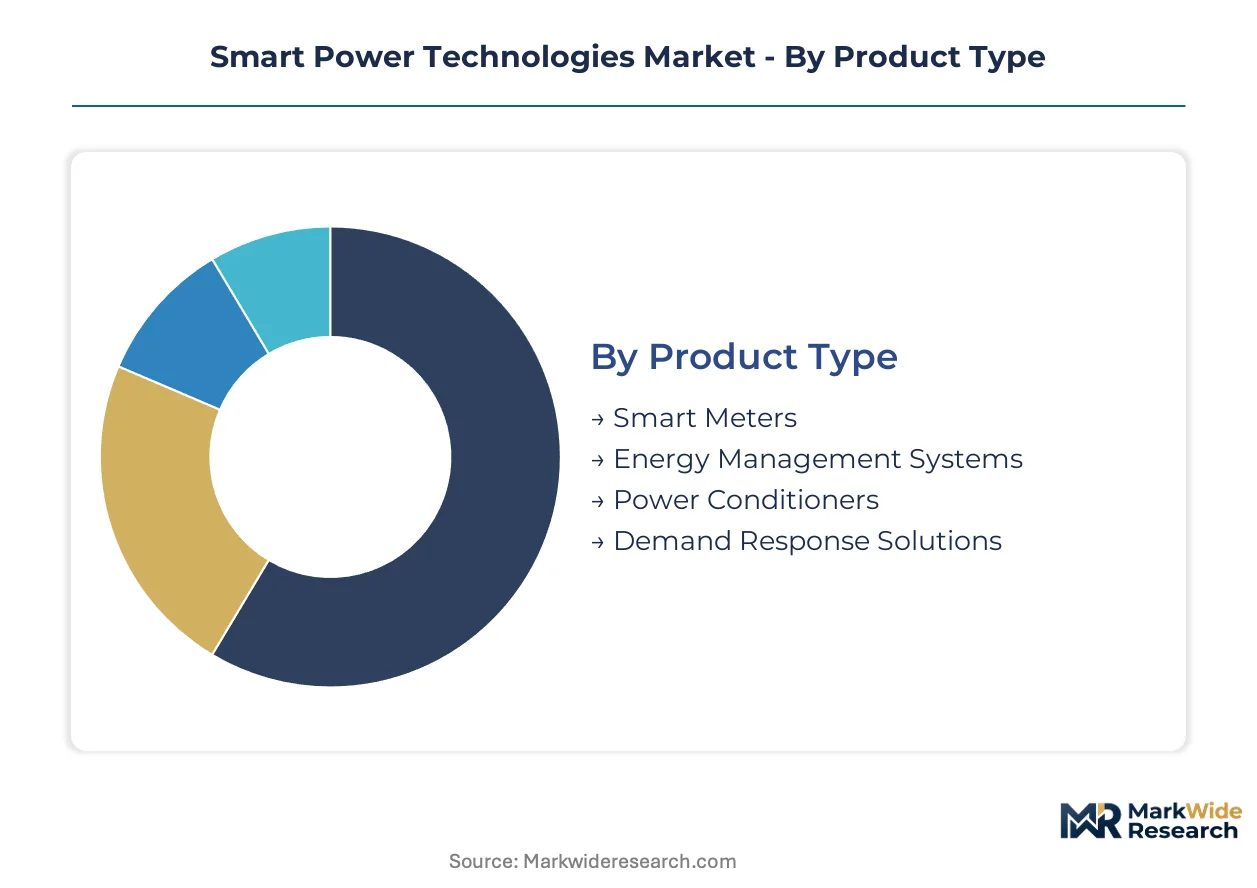
Smart power technologies fragment across hardware, software, and service layers that demand distinct procurement criteria and integration protocols. Buyers prioritize interoperability certification, switching speed specifications, or outcome-based availability guarantees depending on their grid modernization maturity and regulatory exposure.
Product Type:
Cost tier separates mass-deployment hardware from premium systems with embedded analytics and predictive maintenance modules.
- Smart Meters:Bidirectional communication endpoints measure consumption patterns and enable time-of-use pricing through embedded cellular or mesh network radios. Utilities in Germany and California deploy these at scale under Energiewende mandates and FERC Order 2222 aggregation requirements.
- Energy Management Systems:Software platforms aggregate sensor data from distributed assets to automate dispatch decisions and optimize power quality across multiple sites. Commercial and industrial buyers in Texas merchant markets specify these for solar-plus-storage project control.
- Power Conditioners:Voltage regulation and harmonic filtering equipment protects sensitive loads from grid disturbances.
- Demand Response Solutions:Automated load curtailment systems aggregate commercial and industrial flexibility for frequency regulation services.
Smart meters lead volumes today; energy management systems are gaining share fastest.
Technology:
Application maturity determines whether buyers specify proven silicon IGBT architectures or accept qualification risk for silicon carbide wide-bandgap designs.
- IoT Integration:Sensor networks and edge computing nodes enable real-time asset monitoring and predictive maintenance across transmission and distribution infrastructure. German utilities embed these in VDE-AR-N certified converter stations.
- Advanced Metering Infrastructure:Communication backhaul and data management systems that collect and validate smart meter telemetry for billing and operations. US municipal utilities deploy these under state renewable portfolio standards.
- Energy Storage Solutions:Battery management systems and grid-tied inverters pair lithium-ion or flow battery assets with frequency regulation and arbitrage algorithms.
- Smart Grid Technology:Self-healing network architectures with automated fault detection and sectionalizing capabilities.
Smart grid technology anchors current procurement budgets; energy storage solutions show the steepest expansion trajectory.
End User:
Volume scale and technical sophistication separate residential single-phase installations from utility-scale three-phase converter farms.
- Residential:Home energy management systems and rooftop solar inverters with vehicle-to-grid bidirectional charging readiness. California Rule 21 interconnection standards and Japanese JEAC protocols shape product certification requirements.
- Commercial:Building automation integration and behind-the-meter storage for demand charge management. Texas commercial properties specify these for ERCOT price volatility exposure.
- Industrial:Power quality equipment and microgrid controllers for manufacturing continuity.
- Utilities:Transmission automation and distribution management systems for grid modernization programs.
Utilities dominate current deployment value; residential segments are climbing the fastest as vehicle-to-grid protocols mature.
Application:
Margin structure varies by whether the application requires real-time control loops or retrospective data analytics.
- Load Management:Automated demand response and direct load control systems that curtail consumption during peak events or price spikes. Industrial facilities in Germany integrate these with Energiewende flexibility markets.
- Energy Monitoring:Submetering and power quality analytics platforms that identify efficiency opportunities and equipment degradation. Commercial real estate operators deploy these for ESG reporting compliance.
- Renewable Integration:Grid-forming inverters and synchronization equipment for variable solar and wind resource connection.
- Peak Shaving:Battery dispatch and load shifting strategies that reduce maximum demand charges.
Load management commands the largest installed base; renewable integration is expanding most quickly with solar-plus-storage deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters in Bavaria and Baden-Württemberg anchor procurement intensity for wide-bandgap power electronics as the Energiewende policy framework accelerates grid modernization timelines.
Germany
Utility-scale battery inverter deployment and distributed energy resource aggregation drive equipment procurement across Bavaria and North Rhine-Westphalia. The Energiewende mandates under the EU Green Deal compel transmission operators to integrate bidirectional power flow systems. Siemens Energy anchors converter manufacturing in Nuremberg while Munich hosts specialized power module testing facilities.
United States
Merchant solar-plus-storage projects in Texas and California create concentrated demand for grid-forming inverters and automated dispatch platforms. FERC Order 2222 enables distributed resource participation in wholesale markets, forcing certification alignment with ERCOT and CAISO protocols. NextEra Energy sustains project development pipelines across Florida and the Midwest that embed intelligent power controls at gigawatt scale.
China
Dual carbon goals and provincial renewable portfolio standards accelerate procurement of silicon carbide power modules for EV charging infrastructure and grid-tied storage. MIIT industrial policy directs capacity expansion in Yangtze River Delta semiconductor foundries. Shenzhen and Shanghai concentrate inverter manufacturing clusters serving domestic utility-scale solar deployment.
India
Production-linked incentive schemes for solar module manufacturing create localized demand for smart inverters and grid synchronization equipment. Central Electricity Authority mandates specify interoperability standards for distributed generation integration. Gujarat and Tamil Nadu host the fastest-growing manufacturing clusters for power electronics assembly serving domestic renewable auctions.
Japan
Vehicle-to-grid protocol development and residential storage deployment drive inverter demand across Kanto and Kansai regions. METI regulations under the JEAC grid code impose stringent electromagnetic compatibility requirements on grid-connected equipment. Nagoya maintains specialized testing infrastructure for wide-bandgap device characterization serving automotive and industrial converter applications.
Smart Power Technologies Market Competitive Environment
Global majors compete with regional champions across technology certification and utility relationship dimensions, producing a tiered structure where scale-driven conglomerates anchor premium procurement while specialized inverter vendors capture distributed generation niches. The vendor base separates into three strategic archetypes: integrated energy conglomerates with turbine-to-grid portfolios, pure-play power electronics specialists, and utility-captive technology developers. Competitive moves concentrate on M&A for silicon carbide substrate access and strategic partnerships for regional certification acceleration.
Among integrated energy conglomerates, Siemens Energy and NextEra Energy exemplify the scale-driven archetype with end-to-end project development capabilities. Toshiba occupies a position within the power electronics specialist tier, representing Japanese industrial conglomerates with historical converter manufacturing expertise. American Electric Power Company and Public Service Enterprise Group sit within the utility-captive developer category, anchoring North American procurement relationships that shape vendor qualification criteria.
| Leading Market Players |
|---|
| American Electric Power Company |
| Public Service Enterprise Group |
| NextEra Energy |
| Siemens Energy |
| Bloom Energy |
| Vistra Corp |
| Xcel Energy |
| Toshiba |
| Sempra |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate manufacturing migration to 200mm wafer processing simultaneously compresses per-watt converter costs and concentrates supply leverage among Japanese and US substrate vendors. This dual effect reshapes procurement economics for European power module assemblers facing input bottlenecks.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer shortages dominates pricing dynamics across power converter tiers. Three-tier pricing structure across premium, standard, and economy levels separates VDE-AR-N certified grid-tied inverters from commercial-grade equipment and unbranded alternatives. Price differentiation rests on certification grade and volume scale, with utility-scale buyers commanding 15-20 point discounts through multi-year offtakes. Cost compression in mid-tier silicon IGBT architectures is intensifying because incumbent suppliers defend share against wide-bandgap displacement. Residential single-phase inverters show highest price sensitivity; utility-scale three-phase converter farms prioritize availability guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand while distributor networks serve commercial and residential retrofit markets. Geographic supply concentrates in Japan, the United States, and China for high-purity silicon carbide substrates, with Germany and South Korea anchoring power module assembly. Raw material dependencies draw from copper magnet wire, rare-earth permanent magnets, and fluorinated cooling fluids facing regulatory phase-down. Single-source vulnerability runs through Japanese substrate manufacturers controlling 70% of 150mm+ wafer output. Distribution runs through engineering-procurement-construction firms and independent power producers in Texas and California, with direct utility procurement expanding in Germany under Energiewende mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Power Technologies Market functions as a stable compounder anchored by grid modernization mandates that sustain decade-long procurement cycles regardless of commodity cyclicality.
For Market Incumbents: Acquire silicon carbide substrate capacity or foundry partnerships to secure input supply against Japanese and US concentration. Incumbent silicon IGBT suppliers face margin compression from wide-bandgap displacement; defensive consolidation through backward integration into gallium nitride R&D preserves positioning in EV charging infrastructure. Certification investment in Germany's VDE-AR-N and California's Rule 21 grid codes builds switching costs that deter modular competitors. For New Entrants and Emerging Players: FERC Order 2222 in the United States opens a window for distributed energy resource aggregation software and certified interoperability layers. White-space targets concentrate in vehicle-to-grid residential bidirectional charging and green hydrogen electrolyzer power conversion where incumbent coverage gaps persist. Penetrable entry points sit in Texas merchant solar-plus-storage project development, where performance-based availability contracts displace established EPC relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among power electronics specialists with silicon carbide qualification pipelines but limited utility-scale project track records. Long-term viability over a 5-10 year window hinges on substrate supply security and multi-standard certification breadth. Acquisition target archetype: mid-cap inverter vendors with VDE-AR-N or CAISO certification progress and stranded IP in grid-forming controls. Signal to watch: utility procurement shifts from equipment purchase orders to outcome-based availability guarantees, transferring operational risk to technology vendors and favoring balance-sheet-strong platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Acquisition | Secures supply leverage against Japanese wafer concentration for European module assemblers. |
| Multi-Standard Certification Investment | Builds switching costs through VDE-AR-N, Rule 21, and JEAC grid code compliance. |
| Vehicle-to-Grid Protocol Development | Captures residential bidirectional charging growth under California and Japanese regulatory frameworks. |
| Green Hydrogen Converter Specialization | Addresses gigawatt-scale electrolyzer power conversion specification gaps in EU Green Deal projects. |
| Outcome-Based Availability Contracting | Aligns vendor incentives with utility risk transfer trends in Texas and California merchant markets. |
Study Parameters
Direct dialogue with utility planning officers, independent power producer project developers, EPC contractors, and grid operators grounded qualitative assessment in procurement decision dynamics. Secondary validation drew from FERC filings, EIA project databases, IEA renewable integration reports, and EU Green Deal implementation tracking. Bottom-up and top-down triangulation cross-checked equipment shipment data against utility capital expenditure disclosures.
Bottom-up modeling aggregated segment-level assumptions across product type, technology, end user, and application dimensions, while top-down constraints anchored totals to grid investment forecasts from transmission system operators. CAGRs derived from regression analysis of historical procurement patterns and policy-mandated deployment schedules. Key inputs included silicon carbide device adoption curves, battery storage cost trajectories, and regional grid code evolution timelines.
Revisions become necessary when substrate supply disruptions, grid code harmonization failures, or carbon border adjustment mechanism implementations materialize differently than modeled. Forecasts reflect documented assumptions about policy continuity and technology cost reduction slopes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Microgrid Control System Market
Energy Management
Smart Energy Solutions Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Connected Energy Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Energy Management Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Smart Power Management Market
Energy Management
Demand Response Management System Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
Heat Meter Market
Energy Management
Thermostat Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Brazil Energy Sector Market