
 Aviation Biofuels Market | 2026-2036
Aviation Biofuels Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Biofuels Market Analysis
Hydrotreated esters and fatty acids are restructuring conventional jet fuel economics by offering drop-in compatibility with existing turbine engines and airport infrastructure. Neste leverages its Singapore and Rotterdam renewable diesel platforms to anchor global SAF supply. TotalEnergies sustains integrated refining capabilities that position it to compete across European and Middle Eastern supply corridors. Gevo specializes in alcohol-to-jet pathways derived from corn-based ethanol, differentiating its process technology from lipid-based competitors.
Aviation biofuels comprise synthesized hydrocarbons meeting ASTM D7566 specifications, produced through hydroprocessing, gasification-Fischer-Tropsch synthesis, or alcohol-to-jet conversion of biomass-derived feedstocks at 10-50 parts per million sulfur content. Vegetable oils dominate current commercial output due to mature hydroprocessing infrastructure, while non-food biomass and algae represent the fastest-growing feedstock categories as developers target lignocellulosic and waste-stream inputs to avoid food-fuel competition. Commercial aviation absorbs the dominant share of certified volumes, though military aviation commands premium pricing through strategic stockpile contracts with NATO-aligned defense ministries.
The EU Green Deal and ReFuelEU Aviation regulation mandate escalating sustainable aviation fuel blending thresholds, while the US Inflation Reduction Act channels production tax credits through the Department of Energy loan programs office. ASTM D7566 and ISCC certification frameworks govern product qualification and chain-of-custody verification, creating compliance barriers for uncertified producers. Stakeholders must monitor feedstock cost trajectories and offtake contract tenor structures as capacity announcements outpace actual commissioning timelines.
Market Dynamics
Blending mandates under the EU Green Deal and ReFuelEU Aviation are compressing the timeline for sustainable aviation fuel deployment, forcing refiners to reconfigure hydroprocessing assets before cost parity with conventional jet fuel is achieved.
Growth Catalysts
- ReFuelEU Aviation Mandate:The European regulation imposes escalating SAF blending thresholds that lock in demand visibility for producers with certified capacity.
- Hydroprocessing Infrastructure:Existing renewable diesel platforms in Singapore and Rotterdam convert to SAF output with marginal capital deployment.
- US Production Tax Credits:Federal incentives under the Inflation Reduction Act accelerate domestic refinery conversions and greenfield project financing.
Market Restraints
- Feedstock Cost Volatility:Vegetable oil prices fluctuate with edible oil markets, compressing refining margins when palm and soybean oil spike.
- Supply Concentration Risk:Lipid-based SAF output clusters in Northwest Europe and Southeast Asia, exposing buyers to single-corridor disruption.
- ASTM D7566 Certification Friction:The qualification timeline for novel conversion pathways stretches 18-36 months, delaying alcohol-to-jet commercialization.
Strategic Opportunities
- Alcohol-to-Jet Scale-Up:Corn-based ethanol pathways in the US Midwest unlock lignocellulosic feedstock diversification beyond lipid dependence.
- Military Aviation Contracts:NATO-aligned defense ministries procure SAF at premium pricing for strategic stockpile security.
- Waste-Stream Feedstocks:Municipal solid waste and agricultural residue conversion via gasification-Fischer-Tropsch routes bypass food-fuel competition constraints.
Industry Challenges
- ISCC Certification Timeline:Chain-of-custody verification for sustainable biomass sourcing extends project development cycles by 12-18 months.
- Alcohol-to-Jet Integration Complexity:Blending synthetic paraffinic kerosene from ethanol requires dedicated storage and handling infrastructure at airports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Biofuels Market |
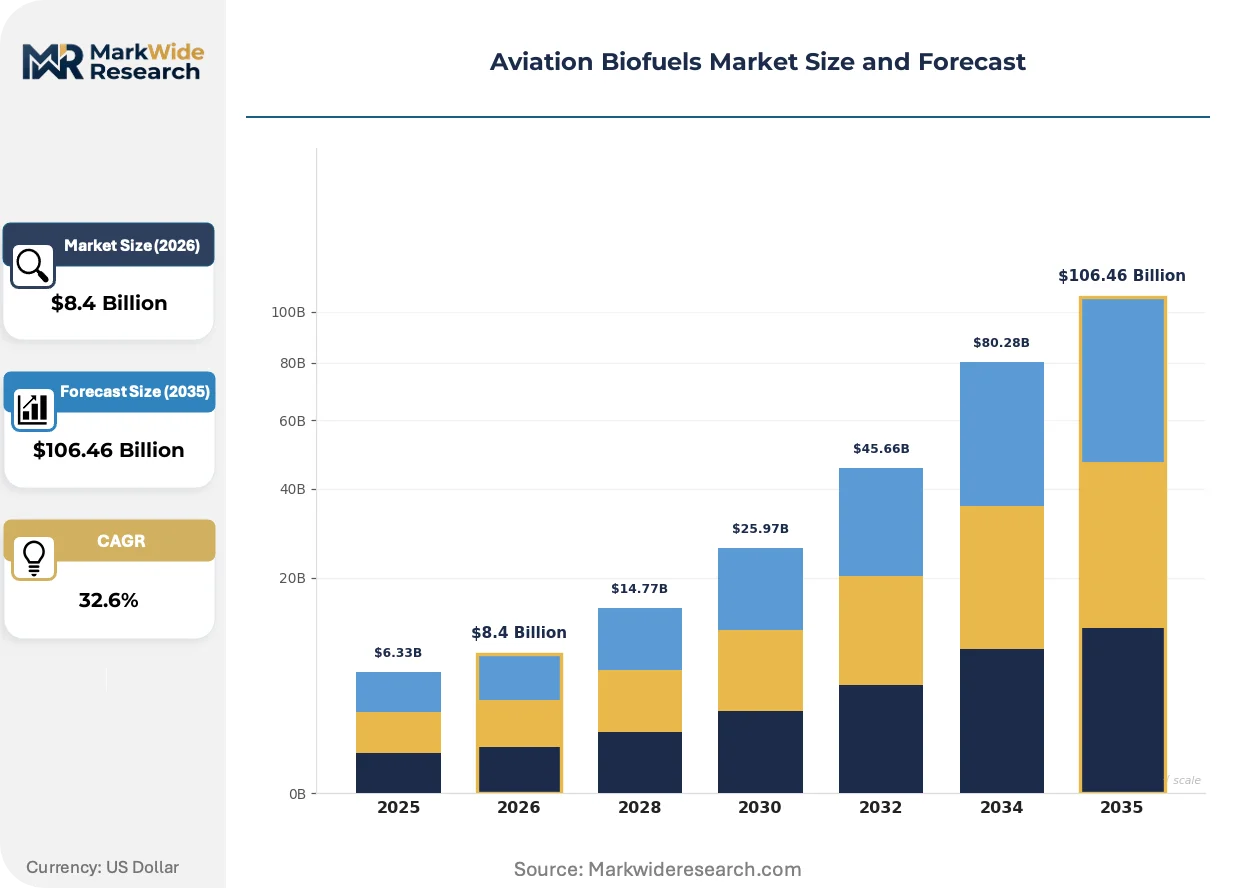
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $106.46 Billion |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Vegetable Oils, Animal Fats, Algae, Non-Food Biomass Production Process: Hydroprocessing, Fermentation, Gasification, Fischer-Tropsch Application Type: Commercial Aviation, Military Aviation, General Aviation, Cargo Aviation Certification Standard: ASTM D7566, EP Specification, ISCC, EN 14214 |
| Companies Covered | Neste, TotalEnergies, Exxon Mobil Corporation, World Energy, Gevo, Red Rock Biofuels, Shell, Eni, Aemetis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Biofuels Market Emerging Trajectories
Conversion pathway diversification is fragmenting technology leadership away from hydroprocessed esters and fatty acids toward alcohol-to-jet and gasification routes. This shift is compressing the dominance of vegetable oil feedstocks.
Power-to-liquid synthesis combining green hydrogen with captured carbon dioxide is overtaking conventional lipid hydroprocessing in long-term capacity announcements. Synthetic fuel producers in Northern Europe and the Middle East are securing offtake agreements with cargo carriers seeking 100% drop-in compatibility. The technology is overtaking first-generation SAF economics by eliminating feedstock competition with food systems entirely.
The EU Green Deal's Fit for 55 package tightens greenhouse gas intensity benchmarks for aviation fuel imports. Refiners must document lifecycle emissions from feedstock cultivation through combustion, favoring producers with integrated carbon accounting systems. European network carriers are responding by signing decade-long purchase agreements that transfer price risk to fuel suppliers.
Corporate travel procurement departments now mandate SAF certificates in airline RFPs regardless of physical fuel delivery. Multinational technology and financial services firms in North America and Western Europe book SAF credits to meet Science Based Targets initiative commitments. This behavioral shift is decoupling premium pricing from actual blending operations at departure airports.
Aviation Biofuels Market Segmentation
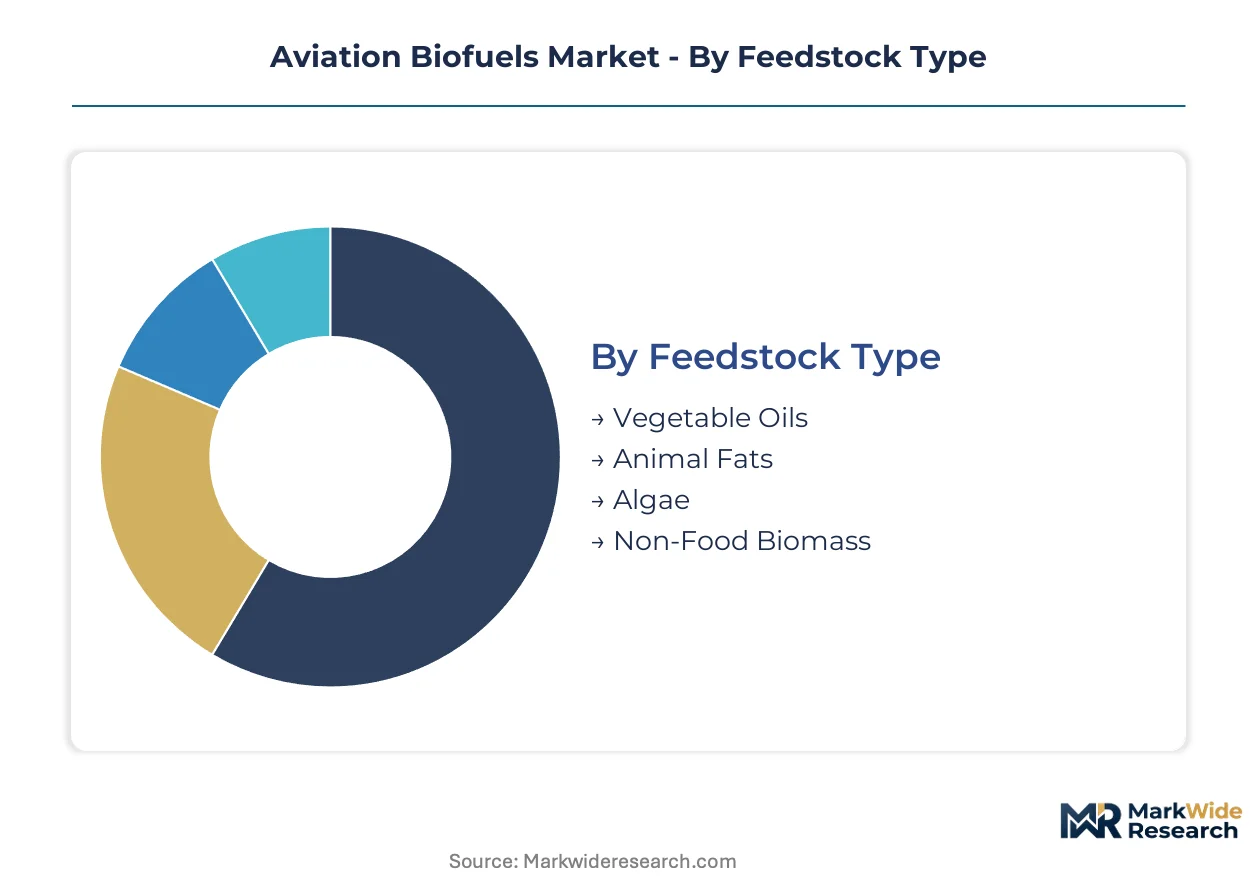
Segmentation in aviation biofuels reveals how feedstock economics, conversion technology, and certification requirements create distinct competitive arenas. Each axis carries different margin profiles and regulatory exposure, forcing producers to prioritize pathways aligned with their asset bases and geographic positioning.
Feedstock Type:
Technology readiness and supply security differentiate feedstock strategies across production platforms.
- Vegetable Oils:Mature hydroprocessing infrastructure processes soybean, rapeseed, and palm oils into drop-in synthetic paraffinic kerosene meeting ASTM D7566 specifications. Demand concentrates in EU member states where ReFuelEU Aviation mandates create guaranteed offtake, though price volatility in edible oil markets compresses refining margins during commodity spikes.
- Animal Fats:Tallow and poultry grease deliver lower carbon intensity scores under lifecycle accounting frameworks, qualifying for premium credits in jurisdictions with stringent GHG benchmarks. Rendering supply chains in the United States and Brazil anchor commercial volumes, with tallow-based pathways gaining preference among European carriers seeking ISCC-EU certification compliance.
- Algae:Photosynthetic cultivation systems promise 10-100x higher oil yields per hectare than terrestrial crops, though commercial scale remains pre-revenue. Developers in Israel, Australia, and the United States target saline-land deployment to bypass agricultural land competition entirely.
- Non-Food Biomass:Lignocellulosic residues and dedicated energy crops eliminate food-fuel conflict, unlocking agricultural waste streams and forestry byproducts for gasification-Fischer-Tropsch conversion. Projects in Sweden, Canada, and the United States pilot commercial-scale deployment with defense ministry offtake backing.
Vegetable oils lead on scale; non-food biomass leads on momentum.
Production Process:
Capital intensity and technology risk partition producer strategies across conversion pathways.
- Hydroprocessing:Hydrotreated esters and fatty acids dominate installed capacity, leveraging existing renewable diesel assets in Rotterdam and Singapore for marginal SAF output expansion. Commercial aviation offtake agreements with European network carriers lock in decade-long revenue visibility.
- Fermentation:Microbial conversion of sugars to hydrocarbon intermediates enables alcohol-to-jet pathways from corn-based ethanol, with Gevo's South Dakota facility anchoring US Midwest production. ASTM D7566 annex qualification timelines of 18-36 months delay commercial deployment.
- Gasification:Thermal decomposition of solid biomass to syngas enables municipal solid waste and agricultural residue utilization, bypassing lipid feedstock constraints entirely. Projects in the United Kingdom and Japan target industrial cluster integration for carbon capture co-deployment.
- Fischer-Tropsch:Syngas-to-liquid synthesis produces fully synthetic paraffinic kerosene with 100% drop-in compatibility, commanding premium pricing from cargo carriers seeking maximum blend flexibility. Synthetic fuel producers in Norway and the United Arab Emirates secure long-term offtake with integrated energy majors.
Hydroprocessing leads on scale; Fischer-Tropsch leads on momentum.
Application Type:
Volume concentration and pricing power diverge sharply across aviation end-uses.
- Commercial Aviation:Scheduled passenger carriers absorb the dominant share of certified SAF volumes, with EU-based airlines front-loading procurement to meet ReFuelEU Aviation blending thresholds. Corporate travel procurement mandates now require SAF certificates in RFPs regardless of physical delivery location.
- Military Aviation:NATO-aligned defense ministries procure synthetic fuel at premium pricing for strategic stockpile security, with specifications emphasizing supply chain resilience over unit cost. The US Department of Defense and UK Ministry of Defence anchor procurement through multi-year framework agreements.
- General Aviation:Business jet operators face fragmented demand across private terminals, limiting dedicated infrastructure investment. Fractional ownership fleets in the United States and Switzerland pilot book-and-claim certificate systems to aggregate purchasing power.
- Cargo Aviation:Integrated express carriers and dedicated freighter operators prioritize 100% drop-in synthetic fuels for hub-and-spoke network optimization, with DHL and FedEx signing power-to-liquid offtake agreements in Germany and the Netherlands.
Commercial aviation leads on scale; cargo aviation leads on momentum.
Certification Standard:
Compliance architecture determines market access and premium capture across jurisdictions.
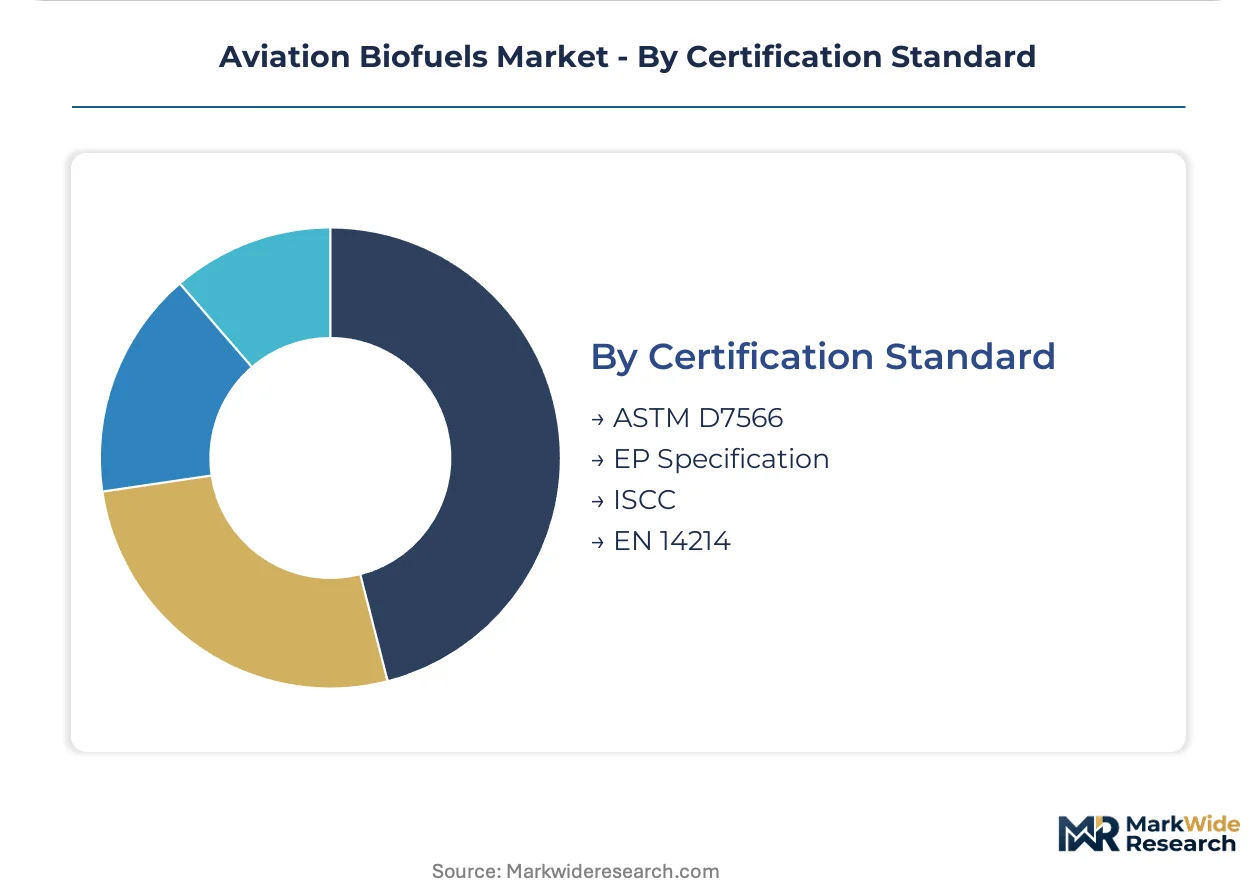
- ASTM D7566:The primary specification governing synthetic paraffinic kerosene blending with conventional jet fuel, with annexes covering hydroprocessed esters, Fischer-Tropsch liquids, and alcohol-to-jet pathways. US and international carriers require ASTM qualification for turbine warranty compliance.
- EP Specification:Engine manufacturer protocols from Pratt & Whitney and Rolls-Royce impose additional testing requirements beyond ASTM baselines, creating de facto barriers for uncertified producers seeking OEM approval.
- ISCC:Chain-of-custody verification for sustainable biomass sourcing extends project development cycles by 12-18 months, with ISCC-EU and ISCC-CORSIA tiers creating differentiated compliance pathways for European and international markets.
- EN 14214:Biodiesel specifications occasionally referenced for fatty acid methyl ester coproducts in integrated biorefinery configurations, though aviation applications require ASTM D7566 conversion to hydrocarbon form.
ASTM D7566 leads on scale; ISCC leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's renewable fuels cluster anchors global sustainable aviation fuel production capacity through integrated hydroprocessing infrastructure serving European network carriers.
United States
Midwest ethanol producers and Gulf Coast refiners drive capacity expansion through IRA production tax credits. The Department of Energy loan programs office channels capital toward greenfield biorefinery development. South Dakota and Louisiana industrial corridors host alcohol-to-jet pilot facilities scaling toward commercial output.
Germany
Power-to-liquid synthetic fuel projects concentrate in Northern industrial clusters seeking 100% drop-in compatibility. The EU Green Deal's Fit for 55 package tightens greenhouse gas intensity benchmarks for aviation fuel imports. Leuna and Hamburg refineries integrate carbon capture with Fischer-Tropsch synthesis for cargo carrier offtake.
Singapore
Jurong Island renewable diesel platforms convert marginal capacity to SAF output for Asia-Pacific airline procurement. Maritime bunkering infrastructure repurposes toward aviation fuel storage and blending. Neste's Singapore facility anchors regional supply security for Cathay Pacific and Singapore Airlines decarbonization commitments.
Netherlands
ReFuelEU Aviation mandates lock in decade-long demand visibility for Rotterdam-based hydroprocessing operators. ISCC-EU certification requirements favor integrated carbon accounting systems at Port of Amsterdam biorefineries. Shell and TotalEnergies sustain European supply corridor dominance through backward integration into vegetable oil feedstock sourcing.
United Arab Emirates
Masdar City synthetic fuel pilots combine green hydrogen with captured carbon dioxide for long-haul carrier testing. Abu Dhabi National Oil Company partners with European cargo operators on power-to-liquid offtake agreements. Dubai's aviation hub status drives strategic stockpile procurement for Emirates' fleet decarbonization roadmap.
Aviation Biofuels Market Vendor Landscape
Capacity expansion dominates the current landscape as renewable diesel operators reconfigure hydroprocessing assets for SAF output. The vendor base concentrates around integrated energy majors and specialized biorefinery developers with certified ASTM D7566 pathways. Three archetypes define competitive positioning: lipid-based hydroprocessors leveraging existing infrastructure, alcohol-to-jet specialists pursuing corn ethanol feedstock diversification, and synthetic fuel developers targeting power-to-liquid scale-up. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with producers securing decade-long airline offtake agreements to transfer price risk.
Among Nordic integrated energy operators, Neste exemplifies the hydroprocessing archetype through its Singapore and Rotterdam renewable diesel platforms. TotalEnergies occupies a position within the European major tier, sustaining refining capabilities across supply corridors. Gevo represents the alcohol-to-jet specialization, anchoring US Midwest production from corn-based ethanol pathways distinct from lipid-based competitors.
| Leading Market Players |
|---|
| Neste |
| TotalEnergies |
| Exxon Mobil Corporation |
| World Energy |
| Gevo |
| Red Rock Biofuels |
| Shell |
| Eni |
| Aemetis |
| Others |
Supply Flow & Price Mechanics
Soybean oil futures on the Chicago Board of Trade cascade through aviation biofuel supply chains, compressing refining margins when edible oil markets spike and forcing buyers toward long-term offtake structures that transfer price risk to producers.
Pricing Analysis
Input-cost pass-through from vegetable oil markets dominates aviation biofuel pricing, with hydroprocessed esters and fatty acids tracking soybean and palm oil benchmarks on a three- to six-month lag. Price differentiation hinges on ISCC-EU certification tier and ASTM D7566 annex qualification status, with fully certified synthetic paraffinic kerosene commanding premiums over uncertified volumes. Pricing pressure stems from feedstock competition with food systems, squeezing margins when edible oil demand surges. Cargo carriers demonstrate lowest price sensitivity, accepting premiums for 100% drop-in compatibility, while regional commercial airlines negotiate hardest on unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and the US Gulf Coast anchor hub-and-spoke aviation fuel logistics, with dedicated storage and blending infrastructure at major airport hubs completing final-mile delivery. Supply concentrates in the Netherlands, Singapore, and the United States, where renewable diesel platforms convert marginal capacity to sustainable aviation fuel output. Feedstock dependence draws from soybean and rapeseed oil markets, tallow rendering supply chains, and emerging lignocellulosic waste streams. Single-corridor disruption risk exposes buyers to concentrated output from Northwest Europe and Southeast Asia. Distribution runs through integrated energy majors with backward integration into vegetable oil sourcing and terminal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation biofuels function as a stable compounder, with regulatory mandates under ReFuelEU Aviation and the US Inflation Reduction Act locking in demand visibility that insulates producers from cyclical fuel market volatility.
For Market Incumbents: Extend certified capacity through ASTM D7566 pathway diversification beyond hydroprocessed esters, capturing alcohol-to-jet and Fischer-Tropsch premiums before novel conversion technologies achieve scale. Deepen upstream control over tallow and waste-stream feedstock supply through rendering partnerships and municipal solid waste offtake agreements, defending margin position against vegetable oil price spikes. For New Entrants and Emerging Players: Launch via power-to-lighthouse projects in Northern European industrial clusters, securing cargo carrier offtake for 100% synthetic paraffinic kerosene before incumbents reconfigure renewable diesel assets. Target military aviation procurement channels, where NATO-aligned defense ministries prioritize supply chain resilience over unit cost and award multi-year framework agreements with premium pricing. For Investors and Strategic Acquirers: Asymmetric upside sits with alcohol-to-jet specialists possessing corn ethanol feedstock access and pending ASTM D7566 annex qualification, as these assets trade at discounts to hydroprocessing peers despite superior long-term feedstock security. Watch for ISCC certification timeline compression as the inflection signal indicating regulatory readiness for capital deployment at scale.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D7566 Pathway Diversification | Alcohol-to-jet and Fischer-Tropsch annex qualifications unlock premium cargo carrier contracts beyond lipid-based volumes. |
| Backward Integration into Feedstock Supply | Tallow rendering partnerships and agricultural residue offtakes insulate margins from edible oil market volatility. |
| Power-to-Liquid Scale-Up | Green hydrogen and captured carbon dioxide synthesis eliminates food-fuel competition entirely for long-haul carrier procurement. |
| Military Aviation Contracting | NATO defense ministry framework agreements provide decade-long revenue visibility at premium pricing for strategic stockpiles. |
| ISCC-EU Certification Investment | Chain-of-custody verification enables access to ReFuelEU Aviation mandated blending pools and associated price premiums. |
Methodological Framework
Direct dialogue with refinery operations managers, sustainable aviation fuel procurement leads at network carriers, ASTM committee members, and ISCC certification auditors grounded qualitative assessments, cross-referenced against customs trade data, SEC 10-K filings from integrated energy majors, EPA renewable fuel standard reports, and EU ETS aviation sector disclosures. Bottom-up capacity announcements and top-down mandate-driven demand projections were triangulated to establish volume baselines.
Bottom-up modeling of individual production facility timelines and feedstock conversion yields was reconciled against top-down regulatory mandate trajectories under ReFuelEU Aviation and the Inflation Reduction Act across the analysis window. Segmentation by feedstock type, production process, application category, and certification standard informed revenue allocation. CAGRs were derived from facility commissioning schedules, not demand extrapolation, with sensitivity analysis around ASTM D7566 qualification delays and ISCC certification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feedstock price volatility and geopolitical disruption to vegetable oil trade flows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
E-Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Jatropha Biodiesel Market