
 Lignocellulosic Feedstock-Based Biofuel Market | 2026-2036
Lignocellulosic Feedstock-Based Biofuel Market Size, Share, and Industry Trends Forecast 2026-2036
Lignocellulosic Feedstock-Based Biofuel Market Insights
Feedstock supply contracting is consolidating how value gets captured across the lignocellulosic biofuel chain. Aemetis Inc. anchors its position through integrated carbon capture and sequestration tied to California ethanol production. Novozymes AS dominates enzyme technology for cellulose hydrolysis, licensing biocatalyst packages to project developers globally. GranBio Investimentos SA leverages Brazilian sugarcane bagasse access to sustain cost-advantaged cellulosic ethanol output.
Lignocellulosic feedstock-based biofuel denotes liquid or gaseous fuel produced through biochemical or thermochemical conversion of cellulose, hemicellulose, and lignin fractions found in woody biomass, agricultural residues, and dedicated energy grasses, typically requiring pretreatment to break recalcitrant polymer bonds before fermentation or gasification releases fermentable sugars or syngas for fuel synthesis. Its primary purpose is displacing fossil-derived gasoline, diesel, and jet fuel in hard-to-electrify transport and industrial heat applications where energy density and drop-in compatibility matter. Corn stover dominates near-term feedstock supply in North American project pipelines, while wood residues anchor European and Nordic capacity builds due to established forest products infrastructure. Fermentation technology leads commercial deployment, though gasification routes are gaining capital attention for broader syngas-to-fuel flexibility including sustainable aviation fuel.
The US Environmental Protection Agency administers Renewable Fuel Standard volume obligations that create mandated demand floors for cellulosic biofuel categories. California Air Resources Board enforces Low Carbon Fuel Standard carbon intensity scoring that rewards lignocellulosic pathways with deeper greenhouse gas reductions versus corn ethanol. Brazil's National Agency of Petroleum, Natural Gas and Biofuels regulates RenovaBio carbon credits, channeling investment toward bagasse and straw conversion projects. Stakeholders must monitor how evolving lifecycle assessment methodologies and sustainability certification requirements reshape which feedstock-technology combinations qualify for premium credit values.
Market Dynamics
Aviation fuel buyers are locking in multi-year offtake agreements for cellulosic ethanol and sustainable aviation fuel, compressing development timelines and forcing project developers to secure feedstock supply before final investment decisions. This procurement pattern is consolidating capital around integrated biorefinery platforms with captive feedstock access.
Growth Catalysts
- California Low Carbon Fuel Standard:Carbon intensity scoring rewards lignocellulosic pathways with deeper greenhouse gas reductions versus corn ethanol, creating premium credit values that improve project returns.
- Sustainable aviation fuel mandates:Airlines face binding blend requirements in the European Union and United States, pulling cellulosic ethanol into hydroprocessed ester and fatty acid synthetic paraffinic kerosene supply chains.
- Bagasse-to-ethanol infrastructure:Brazilian sugarcane milling networks provide pretreatment-ready feedstock streams with established logistics, lowering capital intensity for greenfield cellulosic projects.
Market Restraints
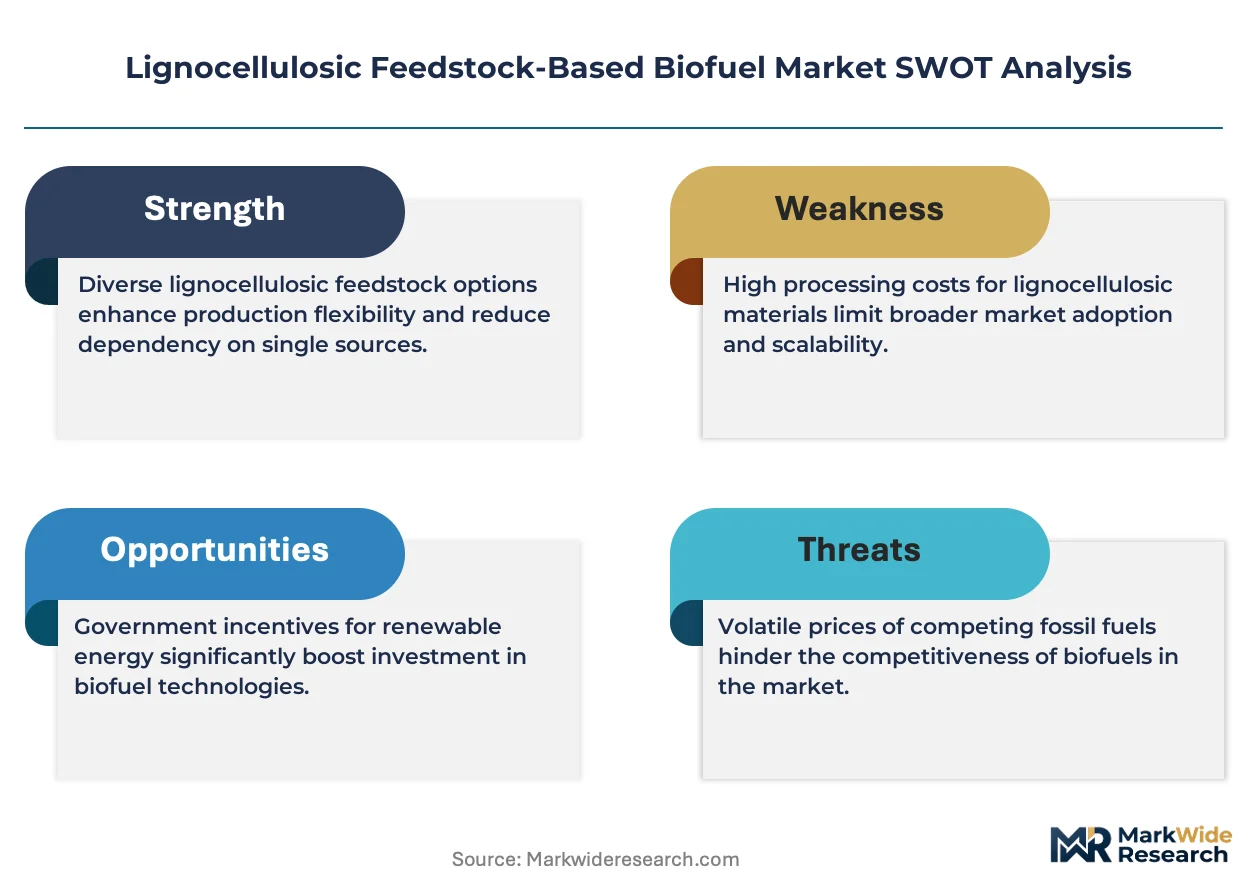
- Enzyme cost concentration:Cellulase and hemicellulase biocatalysts represent 25-35% of operating expenditure, with supply concentrated among specialized biotechnology licensors.
- Feedstock seasonality:Agricultural residues like corn stover and wheat straw require year-round storage or multi-feedstock flexibility, adding handling complexity and working capital burdens.
- Competing biomass uses:Wood residues face diversion to pellet heating markets and pulp production, particularly in Nordic countries with established forest products infrastructure.
Strategic Opportunities
- Carbon capture integration:Fermentation CO2 streams offer low-cost sequestration potential at biorefinery sites, qualifying for federal tax credits under the US Inflation Reduction Act.
- Gasification route commercialization:Thermochemical conversion to syngas enables broader fuel synthesis including diesel and marine fuel, accessing markets beyond ethanol blending.
- India agricultural residue mobilization:Rice straw and cotton stalk availability exceeds 200 million tonnes annually with minimal competing uses, supporting export-oriented project development.
Industry Challenges
- Biochemical engineering talent scarcity:Pretreatment optimization and consolidated bioprocessing require specialized expertise that remains concentrated at national laboratories and select universities.
- Certification timeline compression:Roundtable on Sustainable Biomaterials and International Sustainability and Carbon Certification audits demand 12-18 months for novel feedstock-technology combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignocellulosic Feedstock-Based Biofuel Market |
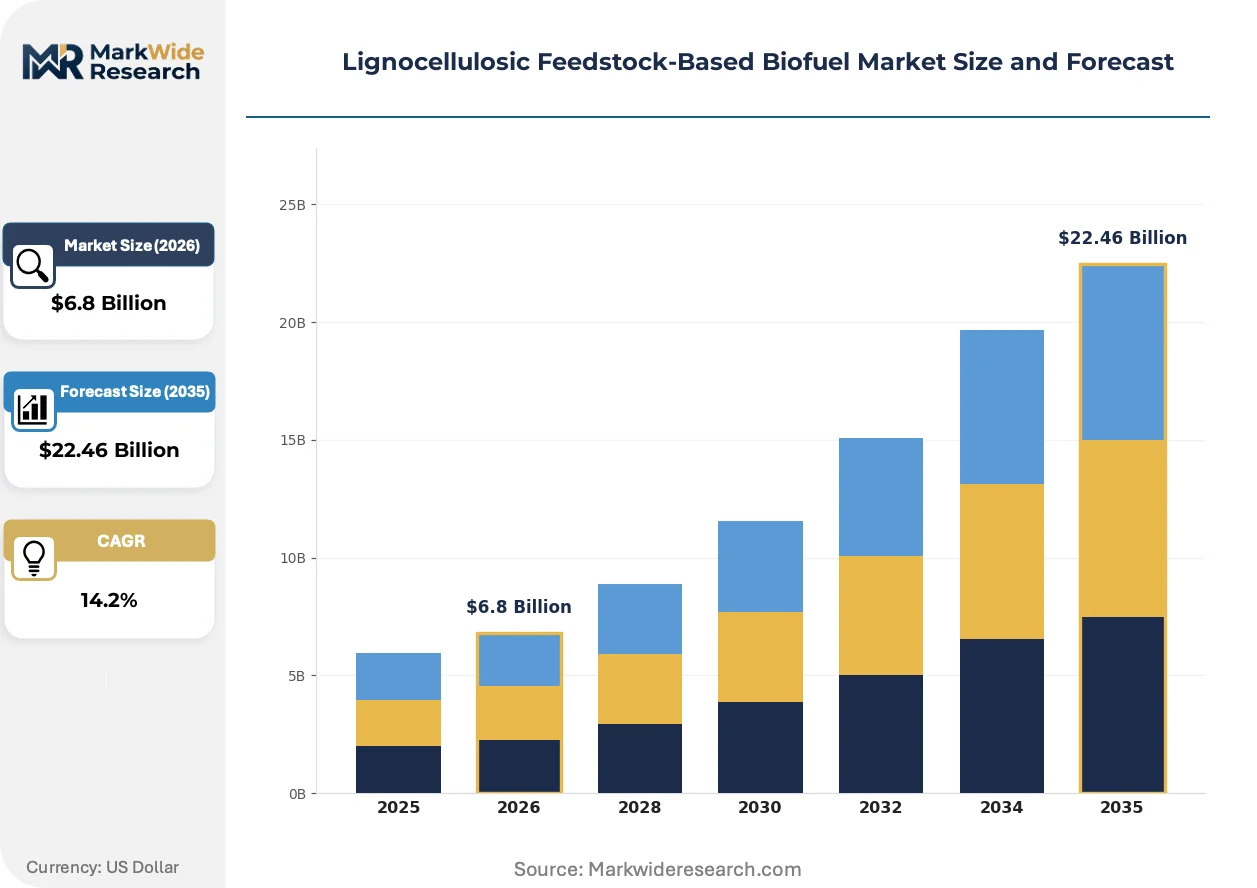
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Sugarcane, Corn Stover, Switchgrass, Wood Residues Technology: Fermentation, Gasification, Hydrolysis, Pyrolysis End Use: Transportation, Heating, Power Generation, Industrial Deployment Model: On-site Production, Centralized Production, Distributed Generation, Blending |
| Companies Covered | Aemetis Inc., Gevo Inc., DuPont de Nemours Inc., Clariant International Ltd., GranBio Investimentos SA, New Energy Blue LLC, Neste Oyj, Cosan S.A., Novozymes AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignocellulosic Feedstock-Based Biofuel Market Trends and Innovations
Consolidated bioprocessing is collapsing separate hydrolysis and fermentation steps into single-unit operations, cutting capital costs and contamination risk. This platform shift is attracting venture investment toward organism engineering and process intensification.
Consolidated bioprocessing using cellulolytic microorganisms is electrifying project economics by eliminating separate enzyme production facilities. Developers including Clariant and Beta Renewables have piloted CBP configurations that reduce capital intensity by 15-20% versus separate hydrolysis and fermentation trains. The technology is compressing breakeven thresholds for agricultural residue projects in North America and Europe.
REACH authorization requirements for ionic liquid pretreatment chemicals are forcing European developers toward dilute acid and steam explosion alternatives. The European Chemicals Agency's scrutiny of imidazolium-based solvents adds regulatory uncertainty to projects planning novel pretreatment chemistries. Nordic and Baltic developers are responding by prioritizing mechanical refining and hot water extraction methods with established safety profiles.
Airline procurement departments are establishing direct supply relationships with biorefinery developers, bypassing traditional fuel trading intermediaries. Singapore Airlines and British Airways have signed offtake agreements with specific project sponsors rather than purchasing through existing jet fuel suppliers. This disintermediation is most visible in sustainable aviation fuel contracting, where buyers seek supply certainty for compliance with CORSIA and national blending mandates.
Lignocellulosic Feedstock-Based Biofuel Market Segmentation
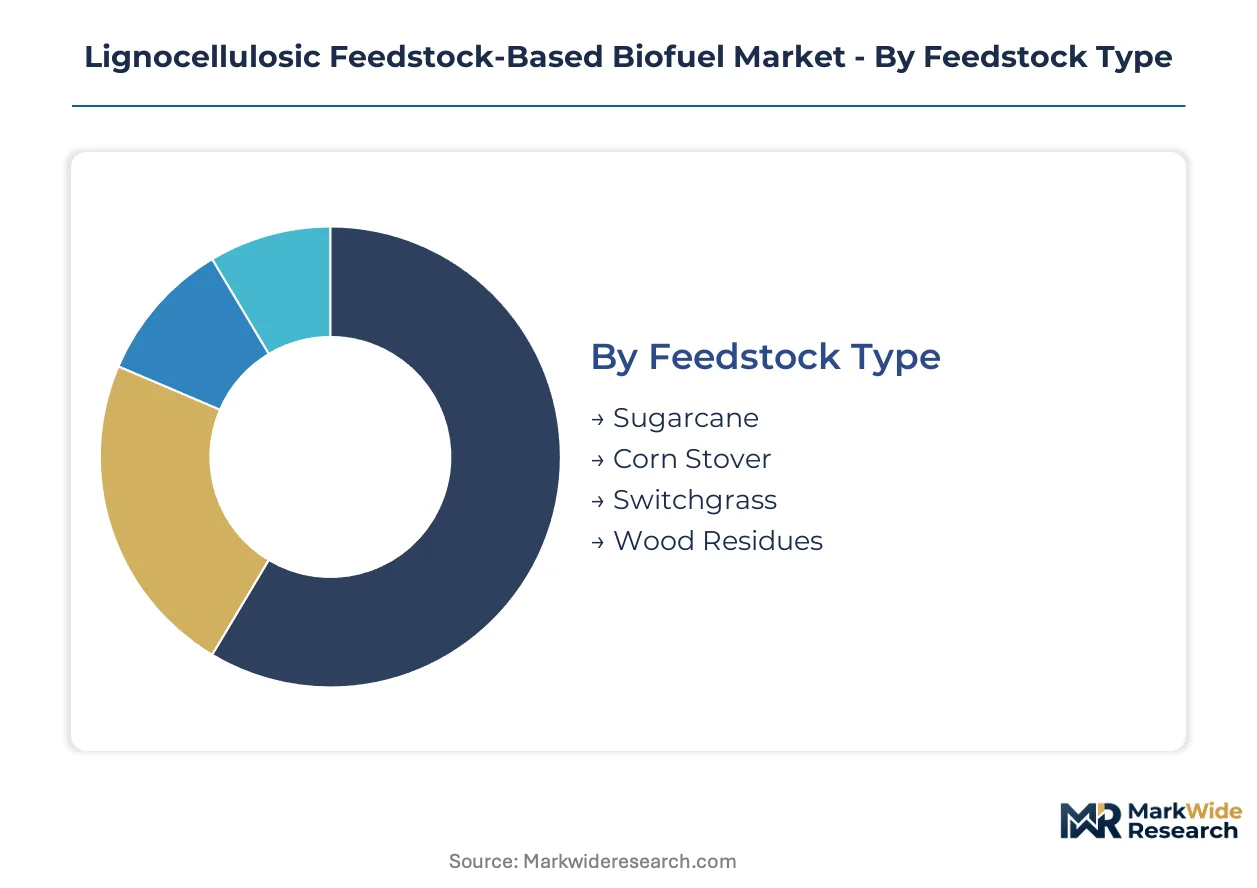
Feedstock chemistry and conversion technology determine capital intensity, carbon intensity scores, and regulatory qualification pathways across lignocellulosic biofuel value chains. Buyers segment procurement by end-use fuel specifications and deployment scale, matching production architecture to offtake security requirements.
Feedstock Type:
Buyers differentiate feedstocks by pretreatment burden, logistics infrastructure, and competing use risks that reshape delivered cost structures.
- Sugarcane:Bagasse streams arrive pretreatment-ready at Brazilian mills with established crushing logistics. Demand concentrates in São Paulo state ethanol complexes where RenovaBio carbon credits reward agricultural residue conversion pathways.
- Corn Stover:Cellulose-rich residue from grain harvest requires densification and dry storage to manage seasonal availability. North American project pipelines anchor on Iowa and Illinois supply sheds where existing grain handling infrastructure reduces collection costs.
- Switchgrass:Dedicated energy grass offers uniform composition and multi-year harvest cycles without food crop competition. Pilot demand tracks toward marginal land programs in the US Department of Agriculture Conservation Reserve.
- Wood Residues:Forest processing byproducts face competing pellet and pulp markets in Nordic countries. Sawmill chips and logging slash supply European biorefineries with established sustainability certification under Forest Stewardship Council chain-of-custody protocols.
Volume sits with sugarcane bagasse in existing milling corridors; growth tilts toward corn stover as US Renewable Fuel Standard obligations tighten cellulosic category mandates.
Technology:
Capital deployment splits between biochemical routes with lower technology risk and thermochemical platforms offering fuel flexibility.
- Fermentation:Saccharification followed by microbial conversion of C5 and C6 sugars to ethanol dominates commercial operations. Clariant and POET-DSM configurations achieve nameplate capacity at Brazilian and US facilities.
- Gasification:Partial oxidation of lignocellulosic biomass to syngas enables Fischer-Tropsch synthesis of diesel and jet fuel. Velocys and Fulcrum BioEnergy pursue modular reactor designs for stranded feedstock locations.
- Hydrolysis:Acid or enzymatic cleavage of glycosidic bonds releases fermentable sugars ahead of downstream conversion. Enzyme cost concentration at Novozymes and DSM drives process economics toward consolidated bioprocessing alternatives.
- Pyrolysis:Thermal decomposition in oxygen-limited environments yields bio-oil for upgrading or combustion applications. Fast pyrolysis units target distributed generation markets with containerized reactor footprints.
Installed capacity clusters around fermentation; steepest expansion trajectory belongs to gasification as sustainable aviation fuel offtake agreements compress development timelines.
End Use:
Fuel specifications and carbon intensity thresholds reshape which conversion pathways qualify for premium credit values in each application.
- Transportation:Drop-in gasoline, diesel, and jet fuel substitutes must meet ASTM fuel standards for engine compatibility. California Air Resources Board Low Carbon Fuel Standard scoring rewards lignocellulosic ethanol with deeper greenhouse gas reductions versus starch-based alternatives.
- Heating:Bio-oil and syngas combustion displaces fuel oil and natural gas in industrial boilers. Nordic district heating networks integrate wood residue gasification for baseload thermal supply.
- Power Generation:Biogas from anaerobic digestion of lignocellulosic fractions feeds combined cycle turbines. Grid balancing contracts favor dispatchable biomass power over intermittent renewable alternatives.
- Industrial:Process heat and chemical feedstock applications require consistent fuel quality and supply security. Cement and steel producers evaluate biomass-derived syngas for calcination and reduction processes.
Transportation claims the dominant revenue share; industrial heat applications expand most quickly as fuel switching accelerates under EU Emissions Trading System carbon pricing.
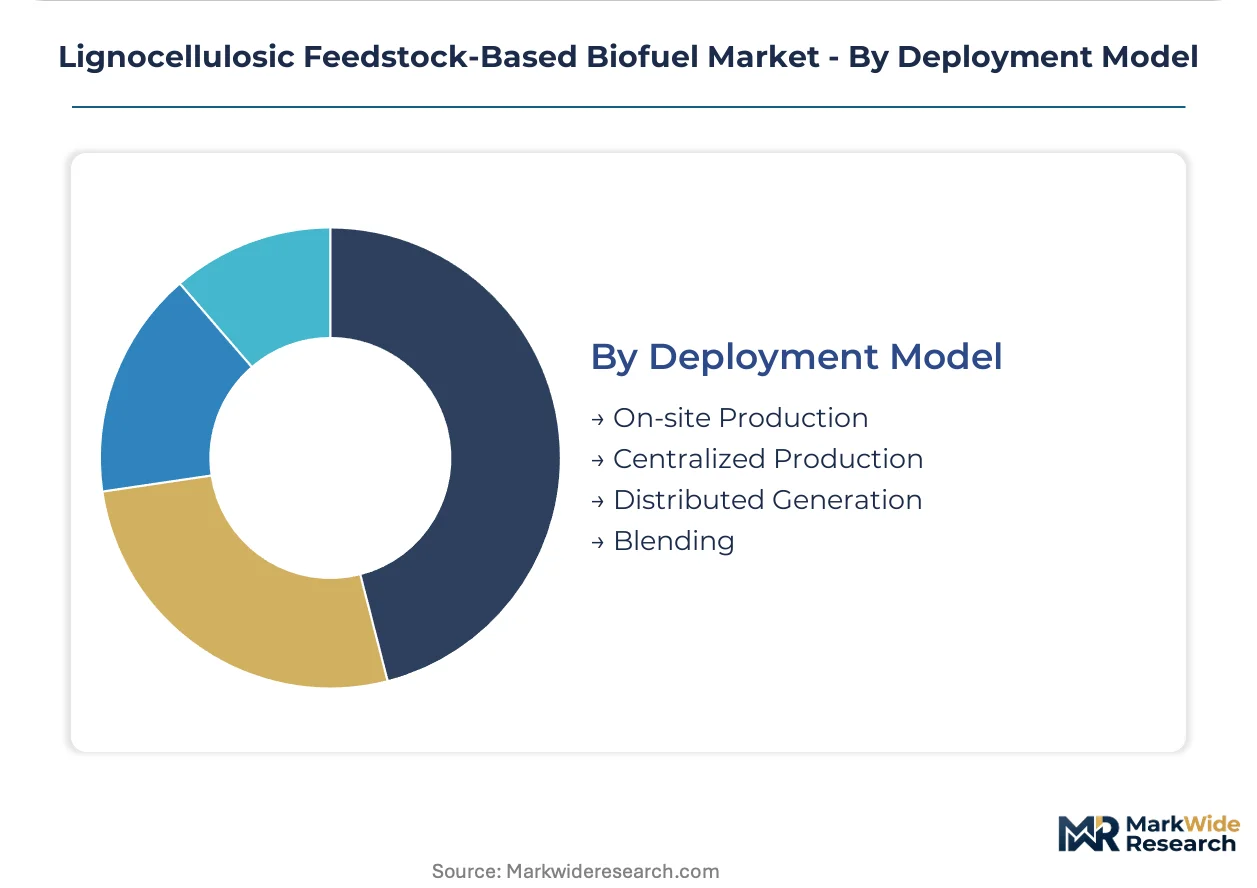
Deployment Model:
Capital structure and offtake risk allocation determine whether developers pursue captive integration or merchant market exposure.
- On-site Production:Biorefineries co-located with feedstock sources eliminate collection and transport costs. Brazilian sugarcane mills exemplify this architecture with bagasse-to-ethanol units adjacent to crushing facilities.
- Centralized Production:Large-scale facilities aggregate multi-source feedstock supply through contracted collection networks. POET-DSM's Emmetsburg, Iowa facility processes corn stover from radius-defined supply sheds.
- Distributed Generation:Small-scale pyrolysis or gasification units serve local industrial heat and power demand. Modular designs reduce feedstock transport distances and enable rural economic development.
- Blending:Intermediate biofuel products integrate with petroleum refinery streams or existing ethanol distribution infrastructure. Hydrotreated renewable diesel and sustainable aviation fuel require finishing at conventional refining complexes.
Centralized production holds current capacity; distributed generation gains share fastest as containerized reactor designs reduce minimum economic scale thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates where bagasse infrastructure and agricultural residue collection networks already exist, while consumption pulls toward jurisdictions with binding low-carbon fuel mandates. This geographic mismatch creates trade flows from feedstock-rich regions to credit-premium markets.
Brazil
São Paulo state sugarcane complexes anchor commercial cellulosic ethanol output through bagasse-to-ethanol units adjacent to crushing facilities. ANP's RenovaBio program channels investment toward agricultural residue conversion with carbon credit mechanisms rewarding deeper greenhouse gas reductions. The Triângulo Mineiro cluster hosts integrated biorefinery platforms leveraging established milling logistics.
United States
Iowa and Illinois corn stover supply sheds feed centralized production facilities seeking compliance with EPA Renewable Fuel Standard cellulosic volume obligations. California Air Resources Board Low Carbon Fuel Standard scoring creates premium credit values for lignocellulosic pathways versus starch-based alternatives. The Central Valley hosts carbon capture integration projects qualifying for Inflation Reduction Act federal tax credits.
India
Punjab and Haryana rice straw availability exceeds 200 million tonnes annually with minimal competing uses, supporting export-oriented project development. Ministry of New and Renewable Energy biofuel policies prioritize agricultural residue mobilization through compressed biogas and ethanol pathways. The Indo-Gangetic Plain presents feedstock aggregation opportunities for first-of-a-kind commercial facilities.
Germany
Baden-Württemberg and Bavaria wood residue supplies face competing pellet and pulp markets under EU Emissions Trading System carbon pricing. ECHA REACH authorization requirements for ionic liquid pretreatment chemicals push developers toward dilute acid and steam explosion alternatives. The Upper Rhine Valley clusters mechanical refining expertise with established Forest Stewardship Council chain-of-custody protocols.
Finland
Nordic district heating networks integrate wood residue gasification for baseload thermal supply under EU Green Deal decarbonization timelines. Finnish sawmill chips and logging slash face diversion pressures from established forest products infrastructure. The Kemi biorefinery corridor exemplifies thermochemical conversion platforms targeting marine and aviation fuel synthesis.
Lignocellulosic Feedstock-Based Biofuel Market Competitive Landscape
Capital-heavy producers compete with asset-light technology licensors across divergent margin structures. Integrated biorefinery operators bearing feedstock logistics and fermentation assets face biocatalyst specialists collecting royalties without commodity price exposure. Market structure fragments across three archetypes: captive feedstock players with milling adjacencies, enzyme technology licensors with recurring revenue streams, and project developers aggregating offtake finance. Dominant competitive moves center on carbon capture integration for tax credit capture and strategic partnerships with airline procurement departments seeking supply certainty.
Within the enzyme technology tier, Novozymes AS and DuPont de Nemours Inc. occupy positions licensing cellulase packages to project developers globally. Aemetis Inc. and GranBio Investimentos SA exemplify captive feedstock archetypes leveraging Brazilian bagasse access and California carbon capture infrastructure respectively. Gevo Inc. and Neste Oyj sit within the sustainable aviation fuel specialization vector, anchoring hydroprocessed ester and fatty acid synthetic paraffinic kerosene supply chains.
| Leading Market Players |
|---|
| Aemetis Inc. |
| Gevo Inc. |
| DuPont de Nemours Inc. |
| Clariant International Ltd. |
| GranBio Investimentos SA |
| New Energy Blue LLC |
| Neste Oyj |
| Cosan S.A. |
| Novozymes AS |
| Others |
Pricing and Supply Chain Analysis
Captive integration into Brazilian bagasse milling networks anchors both supply security and pricing power for first-generation cellulosic ethanol producers. This backward integration choice shields project developers from feedstock spot volatility while compressing delivered cost structures below merchant competitors sourcing agricultural residues through contracted collection networks.
Pricing Analysis
Cost-down pressure on fermentation-based ethanol accelerates because enzyme biocatalysts represent 25-35% of operating expenditure with supply concentrated among Novozymes and DSM. Contract-based long-term offtake agreements dominate, with pricing stratifying across California LCFS credit-premium tiers, standard RIN-compliant volumes, and economy export cargoes without regulatory qualification. Price differentiation hinges on carbon intensity scores and sustainability certification under Roundtable on Sustainable Biomaterials protocols. Merchant project developers show highest price sensitivity due to working capital burdens from feedstock seasonality storage requirements.
Supply Chain Analysis
Dual-sourcing qualification mandates from airline procurement departments force project developers to secure both bagasse and corn stover supply streams before final investment decisions. Feedstock aggregation concentrates in Brazil, the United States, and India where agricultural residue availability exceeds competing uses. Raw material dependencies rest on cellulase enzyme packages, pretreatment chemicals, and logistics infrastructure for densified biomass. Single-source vulnerability sits with specialized biotechnology licensors controlling biocatalyst supply. Distribution runs through existing ethanol blending terminals and emerging sustainable aviation fuel offtake agreements with direct airline relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated biorefinery platforms as enzyme cost concentration and certification timeline compression force sub-scale developers toward strategic exits or acquisition.
For Market Incumbents: Extend carbon capture integration at existing facilities to capture Inflation Reduction Act federal tax credits before qualification windows narrow. Consolidate capacity in São Paulo state and California Central Valley corridors where regulatory credit premiums sustain returns against merchant competitors lacking backward integration into feedstock supply. For New Entrants and Emerging Players: Capture Punjab and Haryana rice straw aggregation opportunities for export-oriented project development with minimal competing biomass uses. Penetrate India's agricultural residue mobilization segment through compressed biogas and ethanol pathways under Ministry of New and Renewable Energy policy support. Pursue joint venture structures with established sugarcane milling networks to leverage existing logistics infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of enzyme technology licensors with recurring royalty streams insulated from commodity ethanol price cycles. Long-term viability favors consolidated bioprocessing platforms achieving 15-20% capital intensity reductions versus separate hydrolysis and fermentation trains. Watch for Roundtable on Sustainable Biomaterials certification timeline compression as inflection indicator for project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Fermentation CO2 sequestration qualifies for IRA federal tax credits at California biorefinery sites. |
| Long-term Offtake Agreement | Singapore Airlines and British Airways direct supply relationships bypass traditional fuel trading intermediaries. |
| Backward Integration into Feedstock | Brazilian sugarcane mills adjacent crushing facilities eliminate collection and transport cost burdens. |
| Technology Licensing | Novozymes cellulase packages generate recurring revenue without commodity price exposure. |
| Joint Venture | POET-DSM Emmetsburg facility demonstrates corn stover aggregation through radius-defined supply sheds. |
Research Methodology
Independent corroboration across biorefinery project developers, airline procurement officers, and enzyme technology licensors underwrites the qualitative findings. Primary interviews with plant managers at Brazilian sugarcane complexes, California LCFS compliance officers, and distribution channel partners in agricultural residue collection networks combined with secondary validation from EPA Renewable Fuel Standard filings, ANP RenovaBio program disclosures, and EU ETS carbon pricing data. Bottom-up facility capacity aggregation and top-down regulatory mandate modeling triangulate volume estimates.
Rate-of-change decomposition across feedstock type, conversion technology, end-use application, and deployment model segments isolates growth drivers throughout the forecast period. CAGRs derive from facility commissioning timelines, regulatory obligation trajectories, and carbon credit value projections. Industry-specific inputs include enzyme cost curves, pretreatment energy balances, and lifecycle assessment methodology revisions affecting carbon intensity scoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA cellulosic volume obligation adjustments and EU sustainable aviation fuel mandate acceleration. Deviation in Roundtable on Sustainable Biomaterials certification timeline standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Bio-Methane Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Global Renewable Fuel Market