
 Renewable Natural Gas Market | 2026-2036
Renewable Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Natural Gas Market Insights
Biogas upgrading service revenue is tilting from small-scale project development toward long-term operational contracts with pipeline interconnection guarantees. Clean Energy Fuels Corp. leverages its nationwide fueling station network to secure offtake priority for transportation-grade RNG. Archaea Energy Inc. anchors its position through captive landfill gas rights and proprietary upgrading assets. Montauk Renewables Inc. specializes in agricultural waste digestion, competing for feedstock access in dairy-intensive geographies.
Renewable natural gas is pipeline-quality biomethane produced from organic waste decomposition, refined to exceed 96 percent methane content through pressure swing adsorption or membrane separation, and injected into utility distribution networks as a fossil natural gas substitute. Anaerobic digestion dominates current production volume, while gasification and pyrolysis represent emerging thermal pathways for lignocellulosic feedstocks. The vehicle fuel application commands premium pricing through EPA Renewable Identification Number credits, though heating and industrial uses are expanding as utilities face decarbonization mandates. Municipalities and agricultural operations supply the dominant share of raw biogas feedstock, with industrial facilities increasingly building captive digestion capacity.
The EPA administers the Renewable Fuel Standard program, which assigns D3 RIN obligations to obligated parties and creates tradable value for cellulosic biofuel pathways including landfill-derived RNG. California Air Resources Board implements the Low Carbon Fuel Standard, generating LCFS credit value that subsidizes out-of-state production shipped into California transportation markets. The FERC interstate pipeline tariff framework governs biogas interconnection access, with state public utility commissions setting injection standards that vary across jurisdictions. Stakeholders must monitor evolving state pipeline access rules and credit banking dynamics as compliance obligations tighten without guaranteed federal policy continuity.
Market Dynamics
Pipeline interconnection guarantees are restructuring competitive positioning in renewable natural gas, as offtake security now outweighs production scale in supplier selection criteria. The shift from merchant risk to contracted revenue streams favors operators with utility relationships over standalone developers.
Growth Catalysts
- California LCFS credit stacking:The Low Carbon Fuel Standard generates tradable credits that subsidize cross-border RNG shipments into California transportation fuel pools, amplifying project economics for out-of-state producers.
- Dairy cluster aggregation:Concentrated animal feeding operations in California's Central Valley and Wisconsin's Fox River Valley supply captive biogas feedstock with predictable methane yields.
- Membrane separation advancement:Polymeric membrane upgrading technology reduces energy intensity versus amine scrubbing, lowering operational expenditure for mid-scale agricultural digesters.
Market Restraints
- Interconnection queue congestion:FERC tariff frameworks create multi-year delays for pipeline injection approval, freezing capital deployment for projects lacking pre-negotiated utility agreements.
- Siloxane contamination:Landfill gas feedstock contains abrasive silicon compounds that degrade upgrading equipment, elevating maintenance expenditure and compressor replacement frequency.
- Natural gas price volatility:Henry Hub benchmark fluctuations compress RNG premium realization, undermining long-term contract pricing that utilities require for procurement authorization.
Strategic Opportunities
- Industrial thermal substitution:Cement and steel manufacturers facing Scope 1 emission targets represent untapped offtake for pipeline-injected biomethane displacing process heat fuels.
- Power-to-gas electrolysis hybridization:Combining anaerobic digestion with green hydrogen injection enables synthetic methane production with negative carbon intensity scores under EPA pathway classification.
- Canadian carbon credit monetization:British Columbia and Alberta compliance markets accept imported RNG for provincial clean fuel mandates, opening export channels for US Gulf Coast production.
Industry Challenges
- Anaerobic digester microbiology expertise:Feedstock variability requires specialized process engineering talent that agricultural operators lack, forcing reliance on third-party O&M contractors with limited geographic coverage.
- EPA RIN pathway certification:Cellulosic biofuel qualification demands 24-month monitoring protocols and third-party engineering review, delaying revenue recognition for new landfill gas facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Natural Gas Market |
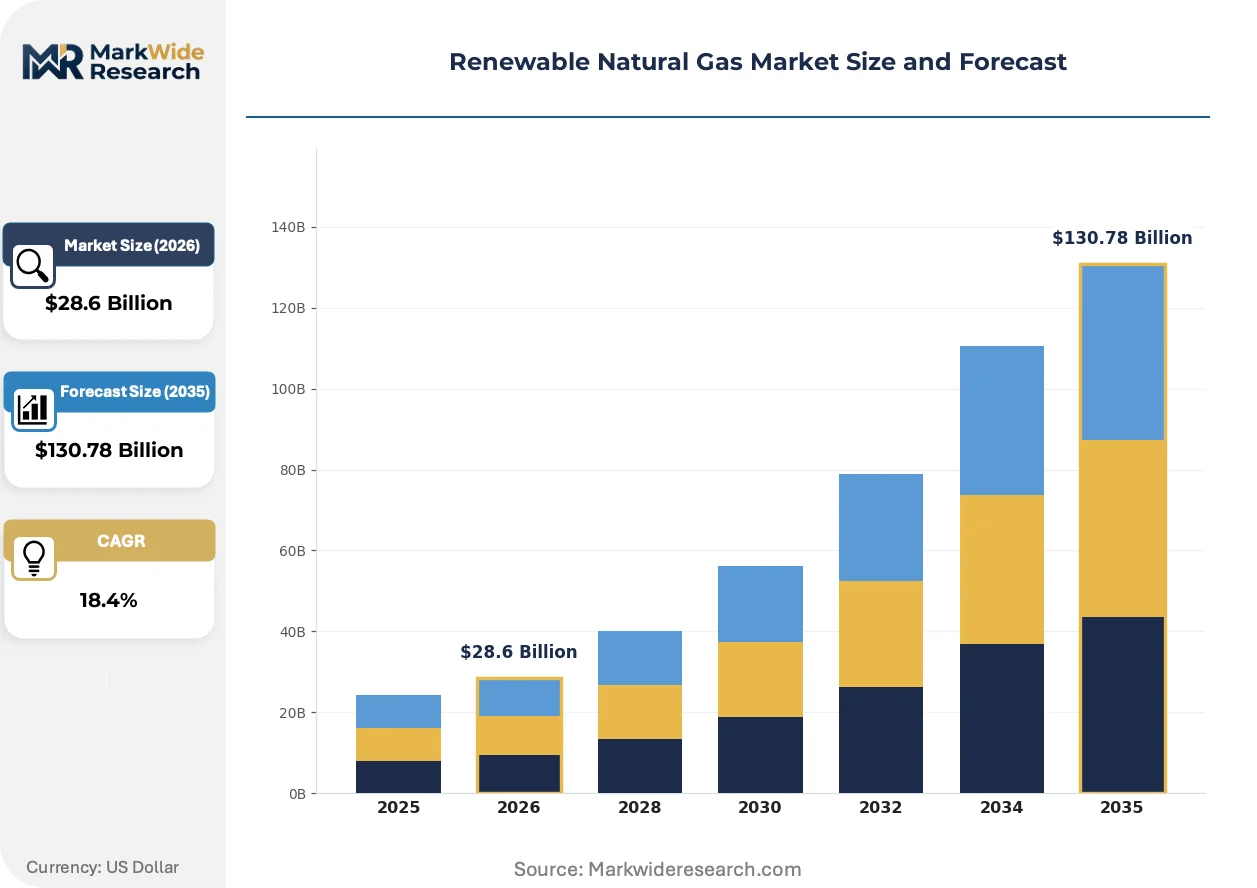
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Anaerobic Digestion, Gasification, Pyrolysis, Catalytic Reforming Application: Electricity Generation, Vehicle Fuel, Heating, Industrial Uses End User: Utilities, Industrial Facilities, Municipalities, Agriculture Distribution Channel: Direct Sale, Wholesalers, Retail, Contracts |
| Companies Covered | Clean Energy Fuels Corp., Archaea Energy Inc., Xebec Adsorption Inc., Brightmark LLC, Ameresco Inc., Montauk Renewables Inc., Waste Management Inc., Renewi PLC, Air Liquide S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Natural Gas Market Trends and Innovations
Technology convergence is compressing project development timelines while regulatory stringency redefines acceptable carbon intensity thresholds. These forces are reallocating value capture across the RNG value chain.
Pressure swing adsorption modularization is collapsing capital barriers for distributed biogas upgrading. Containerized PSA units enable dairy operations with sub-500-scfm feedstock to achieve pipeline injection specifications without centralized processing facilities. Agricultural cooperatives in Dane County, Wisconsin and Tulare County, California are deploying these systems under equipment lease structures that preserve balance sheet capacity.
The EPA's Renewable Fuel Standard maintains D3 cellulosic obligation quotas that tighten annually regardless of production shortfalls. Obligated parties face deficit carryforward limitations that harden RIN price floors, transferring compliance cost burden to merchant refiners lacking captive RNG supply. Transportation fuel suppliers are responding by acquiring offtake positions five to seven years forward to lock in credit generation.
Fleet operators are consolidating fuel procurement around vertically integrated station networks that bundle RNG supply with dispensing infrastructure. Refuse haulers and regional transit authorities now specify fueling contracts with guaranteed carbon intensity scores rather than commodity price indices. This specification shift concentrates purchasing power among multi-state operators with California LCFS exposure, squeezing standalone station developers in Texas and Colorado markets.
Renewable Natural Gas Market Segmentation
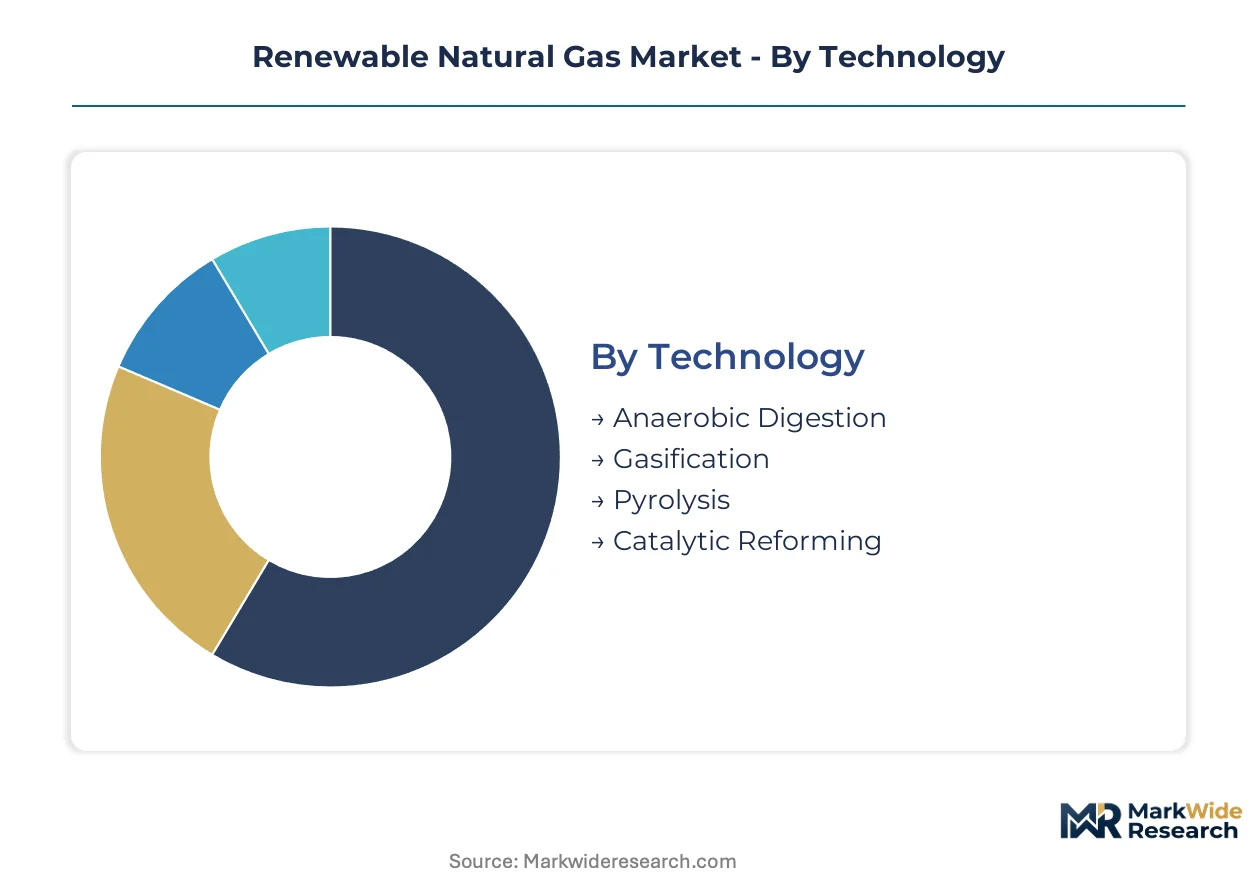
Technology pathways, application endpoints, and distribution structures partition the renewable natural gas market into distinct investment and operational profiles. Each segment carries unique capital intensity, regulatory exposure, and margin characteristics that determine supplier positioning strategies.
Technology:
Anaerobic digestion turns over project inventory fastest due to modular deployment and proven engineering, while thermal pathways require extended development cycles for feedstock validation and equipment commissioning.
- Anaerobic Digestion:Microbial decomposition of organic waste in oxygen-free environments produces raw biogas with 50-70 percent methane content, requiring only water scrubbing or membrane separation to reach pipeline specifications. Dairy operations in California's Central Valley and Wisconsin's Fox River Valley anchor deployment, driven by EPA Renewable Fuel Standard D3 RIN eligibility for agricultural methane capture. This pathway anchors the volume base while Gasification gains share at the steepest rate.
- Gasification:Partial oxidation of lignocellulosic biomass at high temperatures yields syngas for methanation, enabling forestry residue and energy crop utilization beyond wet organic waste streams. Project development concentrates in the US Southeast where pulp and paper industry infrastructure provides feedstock aggregation networks, constrained by higher capital expenditure requirements and extended EPA pathway certification timelines.
- Pyrolysis:Thermal decomposition in oxygen-limited conditions produces bio-oil and syngas fractions, with RNG extraction requiring secondary upgrading stages. Commercial deployment remains limited to demonstration facilities in the Netherlands and Germany.
- Catalytic Reforming:Metal-catalyzed conversion of biogas to hydrogen-rich syngas enables synthetic methane production, currently restricted to pilot-scale operations at research institutions.
Membrane separation advancement is collapsing capital barriers for mid-scale agricultural digesters, while thermal pathway developers compete for lignocellulosic feedstock contracts.
Application:
Vehicle fuel commands the highest effective pricing through credit stacking mechanisms, whereas heating and industrial applications trade at narrower premiums tied to utility procurement mandates.
- Vehicle Fuel:Compressed natural gas and liquefied natural gas dispensing for heavy-duty fleets generates revenue from EPA Renewable Identification Number credits and California Low Carbon Fuel Standard obligations combined with commodity gas value. Refuse haulers and regional transit authorities in California, Oregon, and Washington specify fueling contracts with guaranteed carbon intensity scores, displacing diesel in municipal fleet procurement. This application carries the steepest pricing premium while Heating expands most quickly as utilities face decarbonization mandates.
- Heating:Pipeline-injected biomethane displaces fossil natural gas in residential and commercial building thermal loads, with procurement driven by state-level renewable portfolio standards and clean heat mandates. Northeastern US utilities in Massachusetts and New York lead program development, constrained by interconnection queue delays and distribution network capacity limitations.
- Electricity Generation:On-site biogas combustion in reciprocating engines or turbines supplies baseload power to agricultural operations and wastewater treatment facilities, with revenue dependent on avoided utility demand charges rather than premium gas sales.
- Industrial Uses:Process heat substitution in cement, steel, and food manufacturing represents emerging offtake as Scope 1 emission targets harden corporate procurement specifications.
Transportation fuel procurement concentrates purchasing power among multi-state fleet operators with California LCFS exposure, while industrial thermal substitution opens new demand channels for pipeline-quality biomethane.
End User:
Utilities and industrial facilities deploy capital on decade-long amortization schedules, whereas agricultural operators and municipalities favor shorter payback periods and equipment lease structures.
- Utilities:Natural gas distribution companies procure RNG through long-term offtake agreements to satisfy state renewable thermal mandates and customer clean energy tariffs. Dominion Energy, Duke Energy, and National Grid anchor North American procurement volumes, with interconnection guarantees outweighing production scale in supplier selection.
- Industrial Facilities:Cement and steel manufacturers facing Scope 1 emission targets build captive digestion capacity or contract for pipeline-injected biomethane to displace process heat fuels, with procurement decisions tied to carbon accounting verification requirements.
- Municipalities:Wastewater treatment plants and landfill operators monetize organic waste streams through public-private partnerships, constrained by municipal procurement rules and political budget cycles.
- Agriculture:Concentrated animal feeding operations deploy anaerobic digesters to manage manure liability and generate supplemental revenue, with project economics dependent on EPA RIN value and state environmental compliance cost avoidance.
Utilities anchor the volume base through long-term procurement commitments while Industrial Facilities climb the fastest as manufacturing decarbonization targets harden.
Distribution Channel:
Contract structures dominate high-volume transactions with credit-eligible offtakers, whereas spot and retail channels serve fragmented heating and industrial substitution demand.
- Contracts:Multi-year offtake agreements with pipeline interconnection guarantees secure revenue visibility for project financing, with terms spanning 10-20 years for utility procurement and 5-7 years for transportation fuel suppliers. Clean Energy Fuels Corp. and BP Energy Trading anchor contract volumes.
- Direct Sale:Producer-to-end-user transactions bypass intermediary markups for large industrial thermal substitution, requiring dedicated pipeline lateral construction or virtual pipeline truck delivery.
- Wholesalers:Aggregators bundle production from multiple digesters to meet utility volume minimums and credit verification requirements, capturing margin through logistics coordination and quality standardization.
- Retail:CNG station operators and local gas marketers serve fragmented vehicle fleet and building heating demand, with pricing indexed to Henry Hub plus renewable premium.
Contracts concentrate value capture for credit-eligible production while Direct Sale channels expand most quickly for industrial thermal substitution bypassing utility procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes renewable natural gas predominantly for transportation fuel credits, while Germany and China prioritize pipeline injection for industrial decarbonization, creating divergent procurement specifications across major demand centers.
United States
Dairy cluster aggregation in California's Central Valley and Wisconsin's Fox River Valley supplies concentrated biogas feedstock with predictable methane yields. The EPA's Renewable Fuel Standard assigns D3 RIN obligations that tighten annually, hardening credit price floors for cellulosic biofuel pathways. Clean Energy Fuels Corp. leverages its nationwide fueling station network to secure offtake priority for transportation-grade RNG in these regions.
Canada
British Columbia and Alberta compliance markets accept imported RNG for provincial clean fuel mandates, opening export channels for cross-border production. The country's national energy regulator governs interprovincial pipeline tariff frameworks for biogas injection access. Ontario's agricultural cooperatives deploy containerized upgrading systems under equipment lease structures that preserve balance sheet capacity.
Germany
Industrial thermal substitution demand from cement and steel manufacturers facing Scope 1 emission targets drives pipeline-quality biomethane procurement. The EU Green Deal and national renewable energy directives mandate renewable gas quotas for utility distribution networks. The Emsland region and Bavaria host demonstration facilities for pyrolysis and catalytic reforming pilot operations.
China
Municipal wastewater treatment plants and landfill operators monetize organic waste streams through public-private partnerships constrained by state procurement rules. The country's dual carbon goals and MIIT industrial policy guidance encourage anaerobic digestion deployment for agricultural methane capture. Yangtze River Delta provinces concentrate project development where pulp and paper industry infrastructure provides feedstock aggregation networks.
Netherlands
Power-to-gas electrolysis hybridization combining anaerobic digestion with green hydrogen injection enables synthetic methane production with negative carbon intensity scores. The country's national environmental agency implements renewable gas quality standards that exceed pipeline specifications in neighboring jurisdictions. Rotterdam's industrial cluster represents emerging offtake for process heat fuel displacement in chemical manufacturing.
Renewable Natural Gas Market Competitive Landscape
Capability concentration sits with specialized upgrading technology providers; scale advantage sits with integrated fuel distributors and waste management operators with captive feedstock rights. The market structure tilts toward long-term contracted revenue streams over merchant production, favoring players with utility relationships and pipeline interconnection guarantees. Three archetypes dominate: vertically integrated fuel station networks, captive landfill gas rightsholders, and agricultural waste digestion specialists. Competitive dynamics center on securing offtake positions five to seven years forward and acquiring pre-negotiated utility agreements to bypass interconnection queue congestion.
Among North American integrated operators, Clean Energy Fuels Corp., Archaea Energy Inc., and Montauk Renewables Inc. occupy distinct positioning vectors. Clean Energy Fuels exemplifies the fuel station network archetype with nationwide dispensing infrastructure. Archaea Energy represents captive landfill gas consolidation with proprietary upgrading assets. Montauk Renewables anchors agricultural waste specialization, competing for feedstock access in dairy-intensive geographies. These three illustrate how pipeline interconnection guarantees now outweigh production scale in supplier selection criteria.
| Leading Market Players |
|---|
| Clean Energy Fuels Corp. |
| Archaea Energy Inc. |
| Xebec Adsorption Inc. |
| Brightmark LLC |
| Ameresco Inc. |
| Montauk Renewables Inc. |
| Waste Management Inc. |
| Renewi PLC |
| Air Liquide S.A. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in California's dairy digester upgrading infrastructure tilts supplier behavior toward long-term contract capture and hardens pricing posture for pipeline-interconnected volumes. This utilization squeeze amplifies the premium commanded by producers holding FERC pre-negotiated utility agreements.
Pricing Analysis
Long-term offtake contracts with 10-20 year terms dominate high-volume transactions, locking in Henry Hub-indexed base rates plus renewable premiums that utilities require for procurement authorization. Price differentiation rests on carbon intensity scores and EPA RIN pathway certification tier, with transportation fuel offtakers paying substantial premiums over heating applications. Pricing pressure stems from interconnection queue congestion freezing merchant project deployment, compressing margins for developers lacking pre-negotiated utility positions. Agricultural cooperatives exhibit highest price sensitivity due to balance sheet constraints, while multi-state fleet operators with California LCFS exposure demonstrate lowest sensitivity.
Supply Chain Analysis
Equipment manufacturing for upgrading systems concentrates in Germany, the United States, and the Netherlands, with specialized membrane separation module production anchored in German industrial clusters. Raw material dependencies include polymeric membrane substrates, specialized compressor alloys resistant to siloxane contamination, and high-purity activated carbon for pressure swing adsorption units. Supply chain risk centers on single-source vulnerability for membrane separation technology intellectual property held by limited specialized engineering firms. Distribution runs through equipment lease structures for agricultural cooperatives and direct sale contracts for utility-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with EPA RIN pathway certification and FERC interconnection agreements creating structural barriers that compound over time.
For Market Incumbents: Build switching-cost moats through captive pipeline interconnection rights and proprietary upgrading asset footprints. Secure five-to-seven-year forward offtake positions before queue congestion worsens. Deepen backward integration into landfill gas rights or dairy cluster feedstock contracts to defend against emerging agricultural cooperative aggregators.
For New Entrants and Emerging Players: Wisconsin's Fox River Valley dairy corridor offers underpenetrated digester deployment potential with established grid access infrastructure. Target industrial thermal substitution contracts with cement and steel manufacturers lacking California LCFS exposure but facing Scope 1 emission targets. Enter through equipment lease structures that preserve agricultural operator balance sheet capacity while capturing operational contract revenue.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators combining captive feedstock rights with pipeline interconnection guarantees. Long-term viability hinges on regulatory continuity for EPA RIN and California LCFS credit mechanisms. Monitor FERC tariff framework revisions as the critical inflection signal for interconnection queue clearance rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Interconnection Pre-Negotiation | FERC tariff agreements bypass multi-year queue delays that freeze competing project capital. |
| Carbon Intensity Score Optimization | California LCFS credit stacking amplifies project economics for sub-zero CI pathway holders. |
| Agricultural Cooperative Equipment Leasing | Containerized PSA units enable sub-500-scfm dairy operations to reach pipeline specifications. |
| Industrial Thermal Substitution Contracting | Cement and steel Scope 1 targets open non-transportation offtake for pipeline biomethane. |
| Membrane Separation Technology Licensing | Polymeric membrane advancement reduces energy intensity versus amine scrubbing for mid-scale digesters. |
Research Methodology
The analysis maps anaerobic digestion, gasification, pyrolysis, and catalytic reforming pathways, each validated through utility procurement officers, digester project developers, EPC contractors, and agricultural cooperative managers. Primary fieldwork combined with secondary validation from EPA RIN generation reports, California Air Resources Board LCFS credit transaction data, FERC interstate pipeline tariff filings, and EIA renewable natural gas production statistics. Bottom-up project pipeline assessment triangulates against top-down regulatory obligation modeling.
Assumptions held fixed include EPA D3 RIN obligation quota trajectories and California LCFS carbon intensity benchmark tightening schedules, while Henry Hub price volatility and interconnection queue clearance rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass technology pathway, application endpoint, end-user archetype, and distribution channel structure. CAGRs derive from project pipeline capacity buildout curves and regulatory obligation gap analysis. Industry-specific forecast inputs include dairy herd concentration data and landfill gas capture efficiency benchmarks.
Practitioners should monitor EPA RIN pathway certification timeline extensions and FERC interconnection tariff reform proposals for early signals of forecast revision. Quarterly review of California LCFS credit bank balances and interconnection queue depth indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Alternate Marine Power Market