
 Sustainable Aviation Fuel Market | 2026-2036
Sustainable Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Aviation Fuel Market Outlook
Commercial aviation is repositioning its fuel procurement strategy toward certified low-carbon alternatives as fleet decarbonization targets harden. Neste leverages its Singapore refinery expansion to anchor supply capacity for Asia-Pacific carriers. Shell competes through integrated upstream feedstock partnerships across agricultural and waste streams. LanzaJet specializes in alcohol-to-jet technology leadership, extending its geographic reach via licensing arrangements rather than sole asset ownership.
Sustainable aviation fuel comprises synthetically processed hydrocarbons meeting ASTM D7566 specifications, blended with conventional jet fuel at ratios up to 50 percent by volume to power turbine engines without airframe modification. The hydroprocessed esters and fatty acids pathway dominates current commercial output due to operational maturity and established feedstock supply chains. Fischer-Tropsch routes occupy premium military aviation applications where stringent cold-flow property requirements apply. Alcohol-to-jet represents the fastest-growing production segment as lignocellulosic and waste ethanol streams achieve cost parity with first-generation pathways.
The EU Green Deal's ReFuelEU Aviation mandate establishes binding SAF blending minimums for EU airports, while the FAA's SAF Grand Challenge coordinates US federal agency procurement and R&D funding toward domestic production scale. ASTM D7566 and ICAO's CORSIA certification frameworks govern product eligibility and emissions accounting, directly determining market access for pathway developers and offtake eligibility for airlines. Stakeholders must monitor feedstock sustainability certification integrity and policy durability across electoral cycles as capital commitments lock in multi-decade production assets.
Market Dynamics
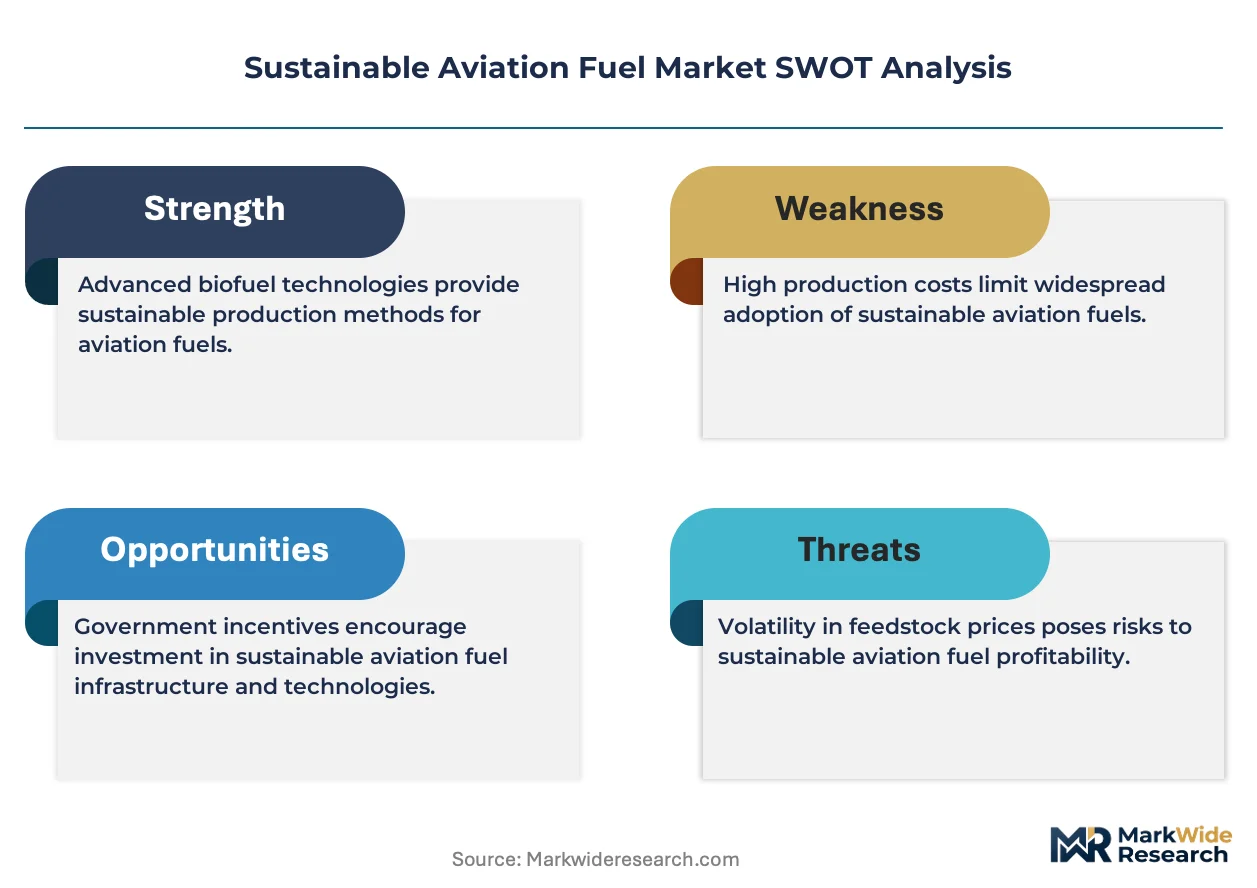
Binding SAF blending mandates under ReFuelEU Aviation and the FAA's SAF Grand Challenge are forcing airlines to renegotiate long-term offtake contracts before production capacity fully materializes, creating a structural supply-demand asymmetry that favors early pathway developers with certified capacity.
Growth Catalysts
- CORSIA Certification Framework:ICAO's carbon offsetting mechanism creates enforceable demand for eligible fuels across international routes, compelling flag carriers to secure certified supply chains regardless of domestic policy status.
- California LCFS Credit Stacking:The state's Low Carbon Fuel Standard generates transferable credits for SAF producers, concentrating private capital deployment toward West Coast production hubs serving trans-Pacific routes.
- Hydrotreated Esters and Fatty Acids:HEFA pathway maturity enables immediate fleet deployment without engine modifications, allowing airlines to meet near-term targets while advanced technologies scale.
Market Restraints
- Feedstock Cost Volatility:Used cooking oil and animal fat prices fluctuate with agricultural commodity cycles, compressing producer margins when vegetable oil markets spike.
- Singapore Supply Concentration:Neste's expanded refinery dominates Asia-Pacific HEFA output, creating single-source dependency risk for regional carriers lacking alternative certified suppliers.
- ASTM D7566 Pathway Limitations:Current certification excludes several emerging conversion technologies, delaying market entry for producers developing power-to-liquid and gasification routes.
Strategic Opportunities
- Brazilian Ethanol Infrastructure:Existing sugarcane processing capacity and established distribution networks position the country for alcohol-to-jet scale-up serving South Atlantic corridor demand.
- Military Aviation Cold-Flow Specifications:Fischer-Tropsch fuels meeting stringent operational requirements open premium pricing tiers for producers with synthetic paraffin capabilities.
- EU Taxonomy Alignment:Green bond eligibility criteria under the EU sustainable finance framework lower capital costs for production assets meeting delegated act technical screening criteria.
Industry Challenges
- ASTM Certification Timeline Compression:Novel pathway approval requires extensive engine testing and data submission, creating 18-36 month delays between pilot demonstration and commercial eligibility.
- Feedstock Traceability System Integration:Mass balance accounting under ISCC and RSB standards demands blockchain or equivalent verification infrastructure that many agricultural suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Aviation Fuel Market |
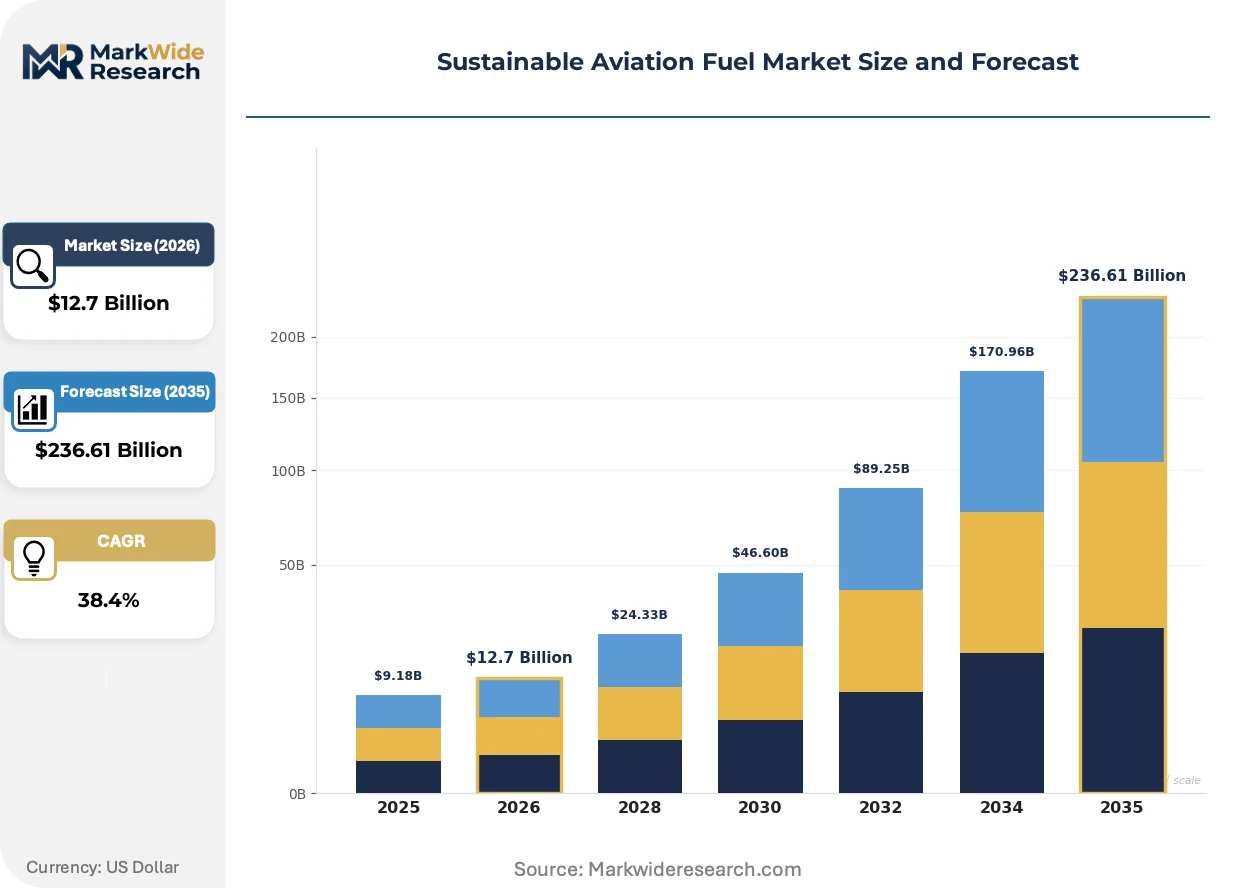
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $236.61 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Vegetable Oils, Animal Fats, Waste Cooking Oils, Biomass Production Pathway: Fischer-Tropsch, Hydroprocessed Esters and Fatty Acids, Alcohol-to-Jet, Direct Sugars to Hydrocarbons Application: Commercial Aviation, Cargo Transport, Military Aviation, Private Jets Distribution Channel: Direct Sales, Online Retail, Partnerships, Distributors |
| Companies Covered | Shell, Eni, Neste, SkyNRG, LanzaJet, TotalEnergies, OMV Aktiengesellschaft, Phillips 66, World Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Aviation Fuel Market Strategic Shifts
Technology developers are racing to diversify beyond lipid-based pathways as feedstock competition intensifies with renewable diesel and maritime fuel sectors. Three concurrent shifts are reconfiguring competitive positioning around conversion efficiency, certification speed, and offtake contract structures.
Alcohol-to-jet technology is decentralizing production geography by enabling modular facilities near waste ethanol sources rather than centralized coastal refineries. LanzaJet's licensed reactor designs allow regional developers to deploy smaller-scale units without proprietary engineering expertise. This distributed model compresses feedstock transport costs and opens markets previously excluded by HEFA supply chain economics.
ReFuelEU Aviation mandates progressive blending minimums at EU airports starting with synthetic fuel quotas, forcing fuel suppliers to secure power-to-liquid and e-kerosene volumes ahead of cost parity. Airlines operating intra-European routes face the steepest compliance curves and are pre-purchasing future output through forward offtake agreements. This regulatory pressure is accelerating electrolyzer and carbon capture co-location projects in Spain, the Netherlands, and Denmark.
Corporate travel procurement departments are embedding carbon intensity metrics into supplier selection criteria beyond traditional cost-per-available-seat-mile calculations. Multinational firms with science-based targets now require documented SAF blending percentages for executive and employee travel contracts. This buyer-driven preference shift is most visible in transatlantic routes serving London-New York and Frankfurt-San Francisco corridors where Fortune 500 travel spend concentrates.
Sustainable Aviation Fuel Market Segmentation
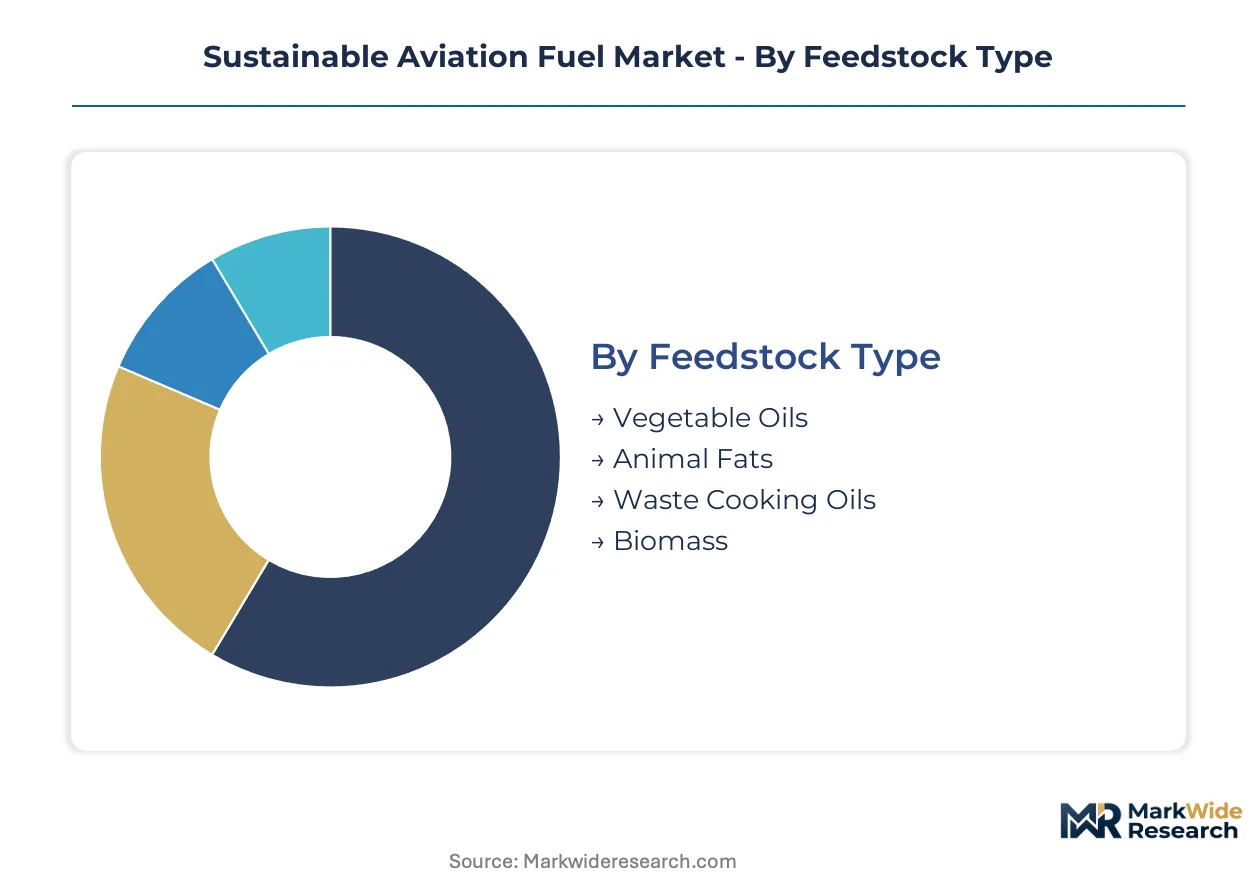
Sustainable aviation fuel segmentation reveals how production economics and certification requirements fragment supply across distinct technical pathways. Feedstock availability and conversion technology maturity determine which segments scale first under binding blending mandates.
Feedstock Type:
Standalone feedstock categories operate through independent supply chains, while embedded sourcing integrates with existing agricultural processing infrastructure.
- Vegetable Oils:Soybean and palm oil streams deliver immediate HEFA pathway compatibility with established crushing and refining infrastructure. Demand concentrates in Southeast Asian supply networks serving Singapore refining hubs, constrained by sustainability certification requirements under EU Green Deal delegated acts.
- Animal Fats:Tallow and poultry fat byproducts from meat processing yield high cetane paraffins with superior cold-flow properties. North American rendering operations anchor supply for military aviation specifications, though competition with renewable diesel producers tightens procurement.
- Waste Cooking Oils:Used frying oils and grease trap collections provide the lowest lifecycle carbon intensity scores under CORSIA accounting frameworks.
- Biomass:Agricultural residues and dedicated energy crops enable cellulosic conversion routes with longer-term cost reduction potential.
Volume placements concentrate in waste cooking oils; the faster expansion belongs to biomass as lignocellulosic pretreatment costs decline.
Production Pathway:
Cost tier separation distinguishes mature commercial technologies from demonstration-scale alternatives still seeking ASTM certification.
- Hydroprocessed Esters and Fatty Acids:Lipid hydrogenation and isomerization produces drop-in paraffinic kerosene meeting ASTM D7566 Annex A1 specifications. Commercial airlines across transatlantic routes secure offtake from Neste, Shell, and World Energy facilities, leveraging immediate fleet compatibility without airframe modifications.
- Alcohol-to-Jet:Ethanol dehydration, oligomerization, and hydrogenation converts sugar-derived alcohols into synthetic paraffins. LanzaJet's Freedom Pines Fuels facility in Georgia anchors US production, with licensed reactor designs enabling distributed deployment near Brazilian sugarcane processing centers.
- Fischer-Tropsch:Syngas conversion via cobalt or iron catalysts yields fully synthetic jet fuel with exceptional cold-flow performance.
- Direct Sugars to Hydrocarbons:Engineered microbial fermentation converts C5 and C6 sugars directly into farnesene and other sesquiterpenes for subsequent hydrogenation.
Cost structures favor HEFA for near-term deployment; the steepest expansion trajectory sits with alcohol-to-jet as waste ethanol logistics mature.
Application:
Customer type segmentation separates price-sensitive volume buyers from specification-driven premium segments with divergent procurement timelines.
- Commercial Aviation:Scheduled passenger carriers operate under CORSIA offset obligations and ReFuelEU Aviation blending minimums, driving long-term offtake contracting. United Airlines, Delta, and Lufthansa Group have committed to multi-billion liter purchase agreements extending through the next decade.
- Military Aviation:Defense departments impose stringent operational requirements including extreme cold-flow performance and energy density specifications. The US Defense Logistics Agency Energy maintains dedicated Fischer-Tropsch procurement for tactical aircraft, paying substantial premiums over commercial jet fuel benchmarks.
- Cargo Transport:Integrated express carriers and dedicated freighter operators face concentrated regulatory pressure on hub-to-hub routes.
- Private Jets:Fractional ownership fleets and high-net-worth individual operators represent a nascent demand segment with limited scale.
Procurement volumes concentrate in commercial aviation; military applications command the highest per-liter pricing tiers.
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships dominating high-volume transactions and intermediary networks filling geographic gaps.
- Direct Sales:Airlines negotiate bilateral offtake agreements with producers for dedicated production slots, securing price certainty and traceability documentation required under ISCC and RSB certification schemes.
- Partnerships:Strategic alliances between fuel suppliers and airport operators co-locate blending infrastructure at major hubs.
- Distributors:Independent fuel marketers aggregate smaller carrier demand and manage logistics for regional airports lacking direct producer relationships.
- Online Retail:Digital platforms facilitate spot market transactions and certificate trading for voluntary corporate travel offset programs.
Transaction volumes concentrate in direct sales; partnership structures are gaining share fastest as airport operators consolidate fuel procurement across carrier tenants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Low Carbon Fuel Standard credit market concentrates private capital deployment along the West Coast, drawing producers toward San Francisco Bay Area blending terminals and Los Angeles basin distribution hubs.
United States
FAA's SAF Grand Challenge coordinates federal procurement and R&D funding toward domestic production scale, while California LCFS credit stacking generates transferable incentives for West Coast producers. The Department of Energy funds biorefinery demonstrations across the Midwest corn belt and Southeast pine belt. LanzaJet's Freedom Pines Fuels facility in Georgia anchors alcohol-to-jet capacity for trans-Atlantic supply.
Singapore
Neste's expanded Tuas refinery dominates Asia-Pacific HEFA output, creating concentrated supply capacity for Cathay Pacific, Singapore Airlines, and Qantas procurement commitments. The Maritime and Port Authority coordinates bunkering infrastructure sharing between aviation and maritime sectors. Jurong Island's integrated petrochemical cluster enables feedstock flexibility across lipid and waste oil streams.
Netherlands
ReFuelEU Aviation mandates progressive synthetic fuel quotas at Amsterdam Schiphol and Rotterdam The Hague airports, forcing KLM and Transavia to secure power-to-liquid volumes ahead of cost parity. The national hydrogen backbone initiative supports electrolyzer co-location with carbon capture projects in the Port of Rotterdam industrial cluster. Shell's Pernis refinery complex processes mixed feedstocks for European distribution.
Brazil
Existing sugarcane ethanol infrastructure positions São Paulo state and Minas Gerais processing centers for alcohol-to-jet scale-up serving South Atlantic corridor demand. Petrobras evaluates retrofitting Paulínia refinery hydrotreaters for renewable jet output. Raízen and Copersucar crush capacity supplies lignocellulosic ethanol streams toward certified conversion pathways.
United Kingdom
The Jet Zero Council coordinates government-industry targets for 10% SAF blending by 2030, with Heathrow and Gatwick airports facing early compliance pressure. The Treasury's revenue certainty mechanism underwrites production risk for first-of-a-kind facilities. Velocys and British Airways pursue gasification-to-jet projects in Immingham and Stansted logistics corridors.
Sustainable Aviation Fuel Market Competitive Environment
Top-tier vendors anchor integrated refining capacity, while technology licensors and regional developers occupy specialist tiers. The market structure stratifies between asset-heavy producers with certified ASTM pathways and modular technology providers scaling through licensing rather than sole ownership. Two dominant archetypes emerge: integrated oil majors leveraging existing hydrogenation infrastructure, and pure-play pathway developers commercializing novel conversion chemistry. Capacity expansion and strategic offtake contracting constitute the primary competitive moves as airlines lock in supply ahead of production availability.
Among integrated European refiners, Shell, TotalEnergies, and OMV Aktiengesellschaft exemplify the asset-heavy archetype through hydrotreater retrofitting and co-processing investments. Neste represents the pure-play specialist model with dedicated renewable product refining. LanzaJet occupies the technology licensing tier, enabling distributed deployment without captive asset ownership. These three patterns—integrated retrofit, dedicated renewable refining, and technology licensing—define competitive positioning as production scales toward mandate-driven demand.
| Leading Market Players |
|---|
| Shell |
| Eni |
| Neste |
| SkyNRG |
| LanzaJet |
| TotalEnergies |
| OMV Aktiengesellschaft |
| Phillips 66 |
| World Energy |
| Others |
Value Chain & Pricing Dynamics
Commercial airlines under CORSIA offset obligations and ReFuelEU Aviation blending mandates operate through long-term offtake contracting rather than spot markets, anchoring pricing power with certified producers holding ASTM D7566 pathway approvals.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as airlines compete for limited certified production slots ahead of mandate deadlines. Three-tier pricing structure across premium Fischer-Tropsch military specifications, standard HEFA commercial grades, and economy-tier alcohol-to-jet volumes reflects certification complexity and feedstock carbon intensity scores. Pricing pressure stems from renewable diesel and maritime fuel sectors bidding for identical lipid feedstocks during agricultural commodity spikes. Cargo carriers and regional airlines exhibit highest price sensitivity, while flag carriers absorbing CORSIA compliance costs show greater tolerance for premium tiers.
Supply Chain Analysis
Single-source vulnerability sits with Singapore's Neste Tuas refinery for Asia-Pacific HEFA output, creating concentrated dependency for Cathay Pacific and Qantas procurement. Feedstock supply draws from Malaysia, Indonesia, and Argentina for palm and soybean oil streams, while waste cooking oil collection networks rest on urban restaurant density in North American and European metropolitan clusters. Tariff exposure on Indonesian palm oil exports threatens margin stability for Singapore refining operations. Distribution runs through airport fuel farm operators co-located at major hubs rather than independent petroleum product terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around ASTM certification holders as capital intensity and 18-36 month approval timelines force unlicensed developers toward acquisition or exit.
For Market Incumbents: Cement supply security through backward integration into Brazilian sugarcane processing and Southeast Asian palm oil crushing infrastructure. Lock in 10-15 year offtake agreements with EU flag carriers facing ReFuelEU Aviation synthetic fuel quotas before power-to-liquid capacity scales. Defend against LanzaJet's licensing model by accelerating proprietary alcohol-to-jet reactor deployments in Georgia and Rotterdam industrial corridors. For New Entrants and Emerging Players: Airport fuel farm operators represent the most accessible channel partners for bypassing incumbent distributor relationships. Target military aviation specifications where Fischer-Tropsch cold-flow premiums offset higher capital requirements. Pursue distributed production models co-located with Brazilian ethanol mills or Midwest corn belt biorefineries to compress feedstock logistics costs below coastal HEFA economics. For Investors and Strategic Acquirers: Distressed-cycle entries favor technology licensors with modular reactor designs and established ASTM certification in the United States and Netherlands. Five-to-ten year viability hinges on power-to-liquid pathway cost parity with electrolyzer scale-up and carbon capture integration. Watch for ReFuelEU Aviation delegated act amendments expanding synthetic fuel quota percentages as the signal for accelerated e-kerosene capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Contracting | United Airlines and KLM secure dedicated production slots ahead of ReFuelEU Aviation compliance deadlines. |
| Feedstock Backward Integration | Shell's agricultural partnerships in Malaysia reduce exposure to renewable diesel sector competition. |
| Technology Licensing Expansion | LanzaJet's reactor designs enable regional developers to deploy alcohol-to-jet capacity without proprietary engineering. |
| Power-to-Liquid Co-location | Electrolyzer and carbon capture projects in Rotterdam support synthetic e-kerosene production for KLM. |
| ASTM D7566 Pathway Diversification | Certification investment opens military aviation premium tiers for producers meeting cold-flow specifications. |
Study Parameters
ASTM International certification databases, ICAO CORSIA eligible fuels registries, and EU Green Deal delegated act technical screening criteria formed the secondary backbone. Primary interviews with SAF procurement directors at major flag carriers, biorefinery operations managers, and fuel supply specialists at airport authorities validated production capacity claims and offtake contract structures. Customs data on vegetable oil and waste fat trade flows, combined with SEC filings from integrated oil majors, enabled bottom-up and top-down triangulation of segment-level volumes.
Bottom-up modeling of HEFA, alcohol-to-jet, Fischer-Tropsch, and power-to-liquid pathway capacities across the projection horizon anchored volume estimates. Segmentation dimensions included feedstock type, production technology, application tier, and regional regulatory framework. CAGRs were derived from mandate-driven demand curves intersecting with announced production buildout timelines. Forecast inputs incorporated California LCFS credit pricing volatility and ReFuelEU Aviation blending minimum escalation schedules.
Caveats apply where ASTM certification timeline delays or feedstock sustainability audit failures could materially shift the outlook. Policy durability across US electoral cycles and EU commission transitions introduces regulatory risk. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Global Cellulosic Ethanol Market