
 Alternative Fuels Market | 2026-2036
Alternative Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Fuels Market Analysis
The EU Green Deal's Fit for 55 package is rebalancing road transport fuel obligations toward renewable alternatives. Neste leverages its Singapore refinery expansion to anchor sustainable aviation fuel supply chains across Asia-Pacific. BP Plc sustains competitive positioning through backward integration into biogenic feedstock collection networks in the United States and Brazil. Shell dominates liquefied hydrogen logistics development at Rotterdam port, controlling critical import infrastructure for European industrial buyers.
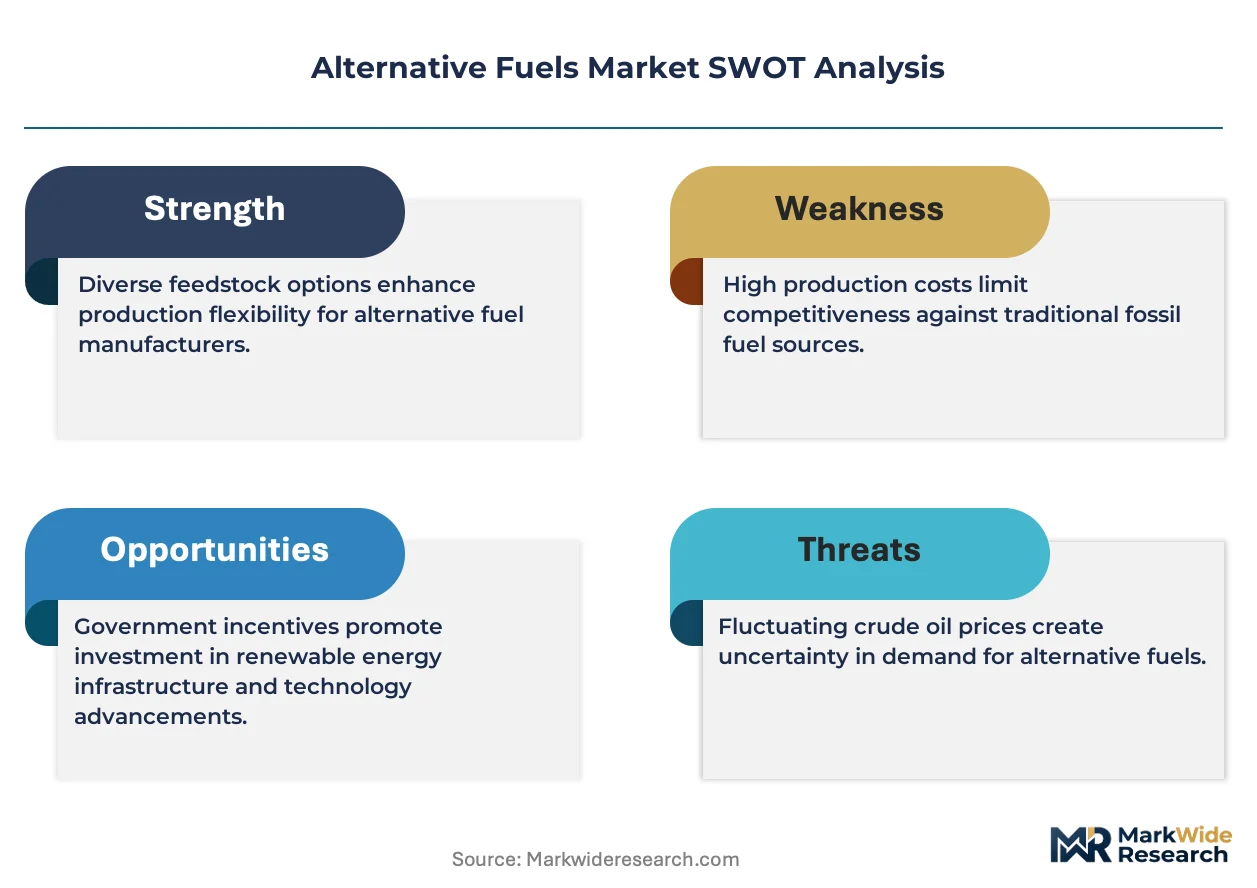
Alternative fuels encompass energy carriers derived from non-petroleum feedstocks—including hydrogen produced via electrolysis, fatty acid methyl ester biodiesel, and cellulosic ethanol with minimum 60% lifecycle greenhouse gas reduction—designed to displace conventional fossil derivatives in combustion engines and fuel cells. Hydrogen fuel cells are attracting the steepest capacity investment as heavy transport operators seek range parity with diesel, while biodiesel occupies the largest existing volume position due to blending mandate compliance in road and maritime segments. Renewable natural gas from anaerobic digestion is carving out margin pools in commercial fleet refueling where pipeline injection protocols allow credit stacking under California's Low Carbon Fuel Standard.
The EPA enforces Renewable Fuel Standard blending obligations that structure US ethanol and biodiesel demand volumes annually, while the EU F-Gas Regulation and REACH framework constrain fluorinated greenhouse gas use in hydrogen cooling systems, shaping equipment supplier qualification requirements. India's MNRE production-linked incentive scheme for green hydrogen electrolyzers is redirecting manufacturing location decisions among Asian equipment vendors. Stakeholders must monitor offtake contract tenor compression as project developers seek to de-risk capital commitments before electrolyzer cost curves flatten.
Market Dynamics
Electrolyzer manufacturing scale-up is compressing green hydrogen production costs and redirecting capital flows from fuel cell vehicle deployment toward industrial feedstock substitution. The International Maritime Organization's carbon intensity regulations are forcing maritime operators into biofuel bunker contracts ahead of scrubber technology payback periods.
Growth Catalysts
- IMO CII Compliance Deadlines:Maritime shipping operators face tightening carbon intensity indicator ratings that mandate biofuel blending or vessel retrofits, creating guaranteed offtake volume for fatty acid methyl ester producers.
- Germany Industrial Cluster Demand:Rhineland chemical complexes are anchoring 10-year green hydrogen offtake agreements that de-risk electrolyzer project finance and validate proton exchange membrane technology at utility scale.
- Electrolyzer Cost Curves:Alkaline and PEM stack manufacturing scale-up in China and India is compressing capital expenditure per megawatt, enabling project developers to undercut gray hydrogen pricing in renewable-rich jurisdictions.
Market Restraints
- Biogenic Feedstock Concentration:Used cooking oil and animal fat supply chains concentrate in Southeast Asian collection networks, creating single-source dependency risks for European and North American renewable diesel refiners.
- Fluorinated Gas Constraints:The EU F-Gas Regulation limits hydrofluorocarbon availability for hydrogen liquefaction cooling systems, extending equipment lead times and qualifying only specialized cryogenic engineering suppliers.
- Pipeline Injection Protocol Variability:Renewable natural gas producers face incompatible grid entry standards across California, Oregon, and British Columbia, fragmenting equipment certification requirements and trapping capital in regional silos.
Strategic Opportunities
- India Electrolyzer Manufacturing:The MNRE production-linked incentive scheme offers capital subsidies for domestic green hydrogen equipment production, redirecting Asian vendor location decisions toward Gujarat and Tamil Nadu industrial corridors.
- Sustainable Aviation Fuel Blending Mandates:Emerging ReFuelEU Aviation obligations create guaranteed demand pools for hydroprocessed esters and fatty acids producers with access to biogenic feedstock collection infrastructure.
- Power-to-X Convergence:Integration of electrolyzer output with Fischer-Tropsch synthesis and methanol production is enabling e-fuel pathways that bypass hydrogen transport infrastructure constraints entirely.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Liquefied hydrogen logistics development faces acute shortages of technicians qualified for minus 253 degree Celsius handling protocols and vacuum-insulated tank construction.
- Certification Timeline Compression:Project developers must secure IEC 62282 fuel cell system approvals and EU RED II sustainability certification simultaneously, creating sequential approval bottlenecks that delay commercial operation dates.
- Legacy Refinery Retrofit Complexity:Converting fluid catalytic cracking units for renewable feedstock processing requires simultaneous catalyst replacement, hydrogen supply reconfiguration, and product slate re-optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Fuels Market |
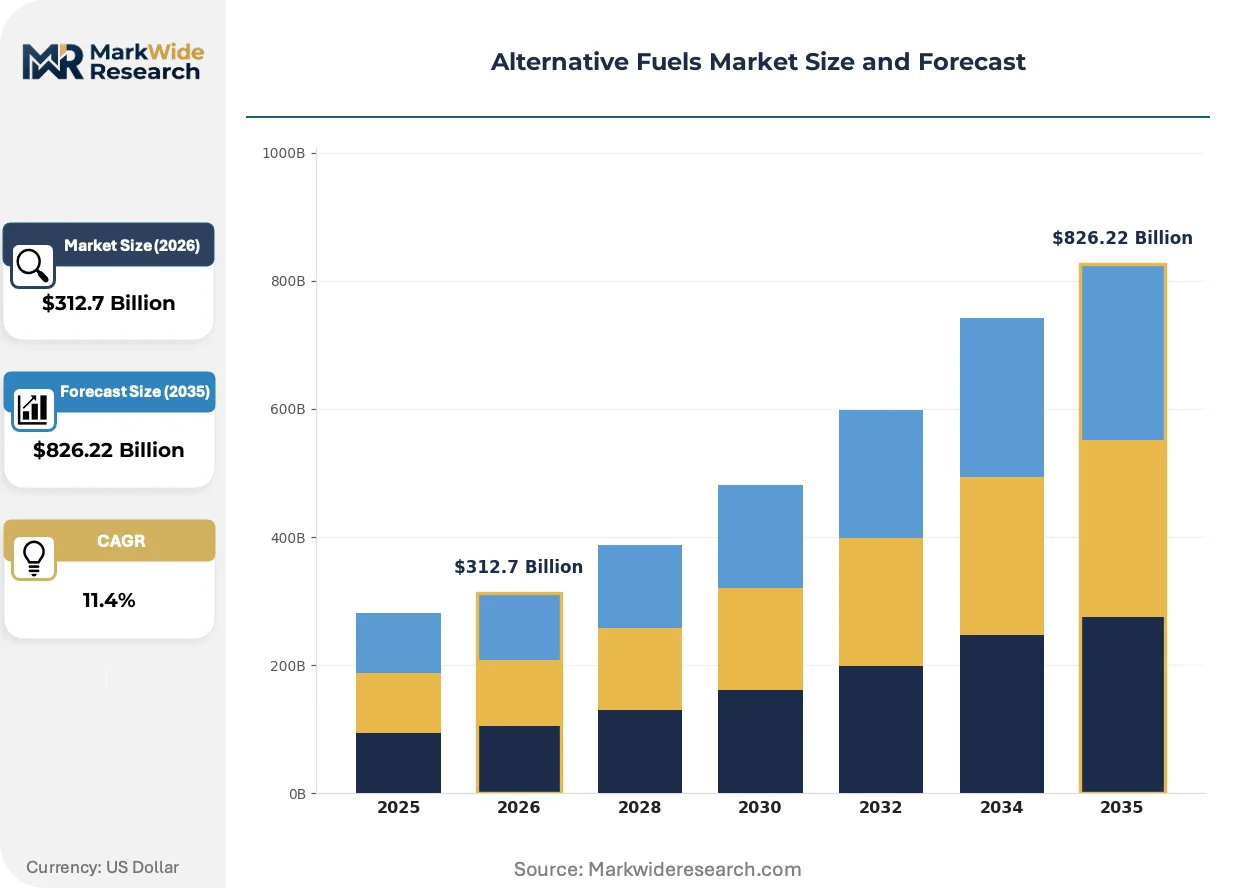
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Biodiesel, Ethanol, Hydrogen, Renewable Natural Gas Application: Transportation, Power Generation, Heating, Industrial Processes End User: Commercial Vehicles, Passenger Vehicles, Railways, Aviation Technology: Gasification, Fermentation, Diesel Engines, Hydrogen Fuel Cells |
| Companies Covered | BP Plc, Neste, ExxonMobil Corporation, Sasol Ltd., TotalEnergies, Shell, Tesla, Inc., BYD Company Ltd., Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Fuels Market Emerging Trajectories
Solid oxide electrolyzer technology is maturing from laboratory demonstration to modular commercial deployment, enabling high-temperature steam utilization that cuts electricity consumption per kilogram of hydrogen output. This thermal integration pathway is attracting industrial off-takers with waste heat availability.
Proton exchange membrane electrolysis is rewriting competitive economics for distributed hydrogen production. Containerized 5-megawatt units are reaching maritime port operators and steel mini-mills within 18-month delivery windows. The technology is compressing viable project scale from utility-grade gigawatts to industrial-site megawatts, fragmenting equipment supplier concentration.
The EPA Renewable Fuel Standard maintains annual blending obligation structures that lock in ethanol and biodiesel demand volumes regardless of compliance credit price volatility. Refiners respond by backward integrating into biogenic feedstock collection networks, securing pipeline-quality renewable diesel supply chains. California's Low Carbon Fuel Standard credit stacking provisions most heavily influence commercial fleet refueling infrastructure deployment.
Offtake contract tenor compression is reshaping project finance structures. Electrolyzer developers now seek 7-year power purchase agreements rather than 15-year tenors, reflecting buyer uncertainty about cost curve trajectories. German industrial clusters and Japanese steel consortiums are pioneering this shift, forcing lenders to accept higher leverage ratios against shorter revenue visibility.
Alternative Fuels Market Segmentation
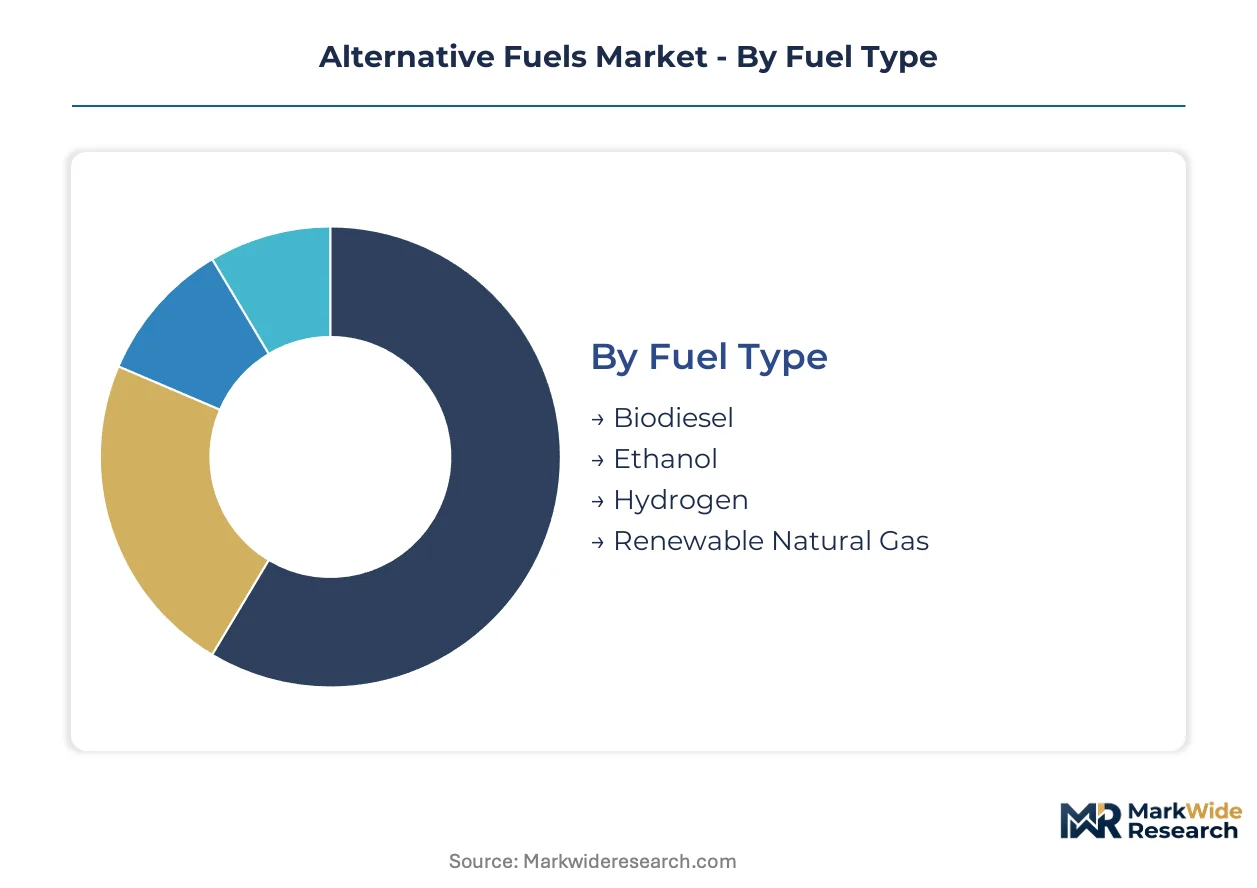
Alternative fuels demand fragments across incompatible infrastructure requirements and regulatory incentive structures. Each segment carries distinct feedstock dependencies, equipment certification timelines, and offtake contract structures that reshape competitive positioning.
Fuel Type:
Hydrogen operates as a standalone energy carrier requiring dedicated distribution infrastructure, while biodiesel and ethanol embed directly into existing liquid fuel supply chains with minimal retrofit.
- Biodiesel:Fatty acid methyl ester produced from vegetable oils and animal fats through transesterification. Maritime shipping operators in Rotterdam and Singapore anchor demand under IMO carbon intensity regulations, though Southeast Asian feedstock concentration creates supply vulnerability.
- Hydrogen:Gaseous or liquefied energy carrier produced via electrolysis or steam methane reforming. German Rhineland chemical complexes anchor offtake agreements that validate proton exchange membrane technology at utility scale, compressing production cost curves fastest.
- Ethanol:Fermentation-derived alcohol blended into gasoline pools. The EPA Renewable Fuel Standard locks in annual blending volumes regardless of compliance credit price volatility.
- Renewable Natural Gas:Methane captured from anaerobic digestion of organic waste. California's Low Carbon Fuel Standard credit stacking provisions concentrate commercial fleet refueling infrastructure deployment.
Volume placements concentrate in biodiesel; the faster expansion belongs to hydrogen.
Application:
Transportation applications command premium pricing due to regulatory mandate intensity, while industrial processes offer scale economies through continuous offtake.
- Transportation:Road, maritime, rail, and aviation fuel substitution requiring engine compatibility certification. ReFuelEU Aviation obligations create guaranteed demand pools for hydroprocessed esters and fatty acids producers with European biogenic feedstock access.
- Industrial Processes:High-temperature heat and chemical feedstock substitution in steel, cement, and ammonia production. Japanese steel consortiums pioneer 7-year power purchase agreement structures that de-risk electrolyzer capital commitments.
- Power Generation:Grid-scale electricity production via combustion turbines or fuel cells. Pipeline injection protocol variability across California, Oregon, and British Columbia fragments renewable natural gas equipment certification requirements.
- Heating:Residential and commercial building thermal energy from renewable sources. District heating networks in Denmark and Sweden integrate electrolyzer waste heat for combined efficiency gains.
Transportation captures the largest revenue share; industrial processes are climbing the fastest as green hydrogen undercuts gray hydrogen pricing.
End User:
Commercial vehicle operators prioritize total cost of ownership parity with diesel, while aviation faces immutable energy density requirements that constrain fuel alternatives.
- Commercial Vehicles:Heavy-duty trucking and logistics fleets with centralized refueling infrastructure. Containerized 5-megawatt proton exchange membrane units reach maritime port operators within 18-month delivery windows.
- Aviation:Jet fuel substitution requiring strict energy density and cold-flow specifications. Neste's Singapore refinery expansion anchors sustainable aviation fuel supply chains across Asia-Pacific.
- Passenger Vehicles:Light-duty automotive applications with distributed refueling requirements. Battery electric technology dominates this segment, constraining hydrogen fuel cell penetration to niche fleet applications.
- Railways:Electrified and non-electrified line haul operations. Deutsche Bahn and SNCF pilot hydrogen multiple units on regional corridors with partial electrification gaps.
Commercial vehicles dominate current offtake volumes; aviation presents the steepest expansion trajectory as ReFuelEU mandates activate.
Technology:
Gasification and fermentation represent mature thermochemical and biochemical pathways, while hydrogen fuel cells and advanced diesel engines require simultaneous fuel and equipment certification.
- Hydrogen Fuel Cells:Electrochemical conversion of hydrogen to electricity with water vapor emission. Solid oxide electrolyzer technology maturation enables high-temperature steam utilization that cuts electricity consumption per kilogram of output.
- Fermentation:Biological conversion of sugars to ethanol through yeast metabolism. US corn belt concentration creates single-source dependency risks for European and North American renewable diesel refiners seeking alternative feedstocks.
- Gasification:Partial oxidation of biomass or waste to synthesis gas. Project developers must secure IEC 62282 fuel cell system approvals and EU RED II sustainability certification simultaneously.
- Diesel Engines:Compression-ignition engines adapted for renewable diesel or biodiesel blends. Converting fluid catalytic cracking units requires simultaneous catalyst replacement and hydrogen supply reconfiguration.
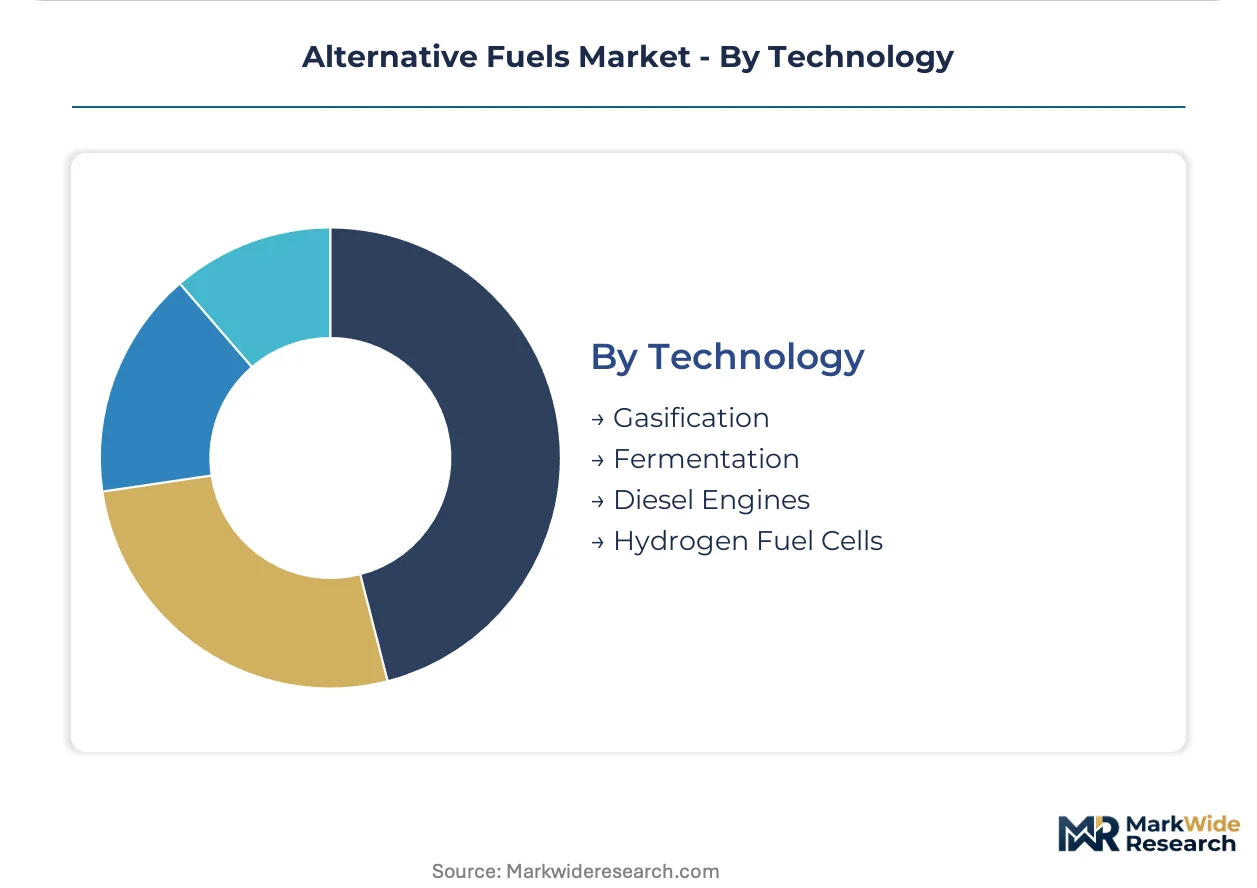
Diesel engine retrofits hold the largest installed base; hydrogen fuel cells are gaining share fastest as heavy transport operators seek range parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European alternative fuels infrastructure through its hydrogen import terminal and biofuel blending facilities, while Singapore and Houston compete for maritime bunkering dominance under tightening carbon regulations.
United States
Commercial fleet operators in California drive renewable natural gas demand through Low Carbon Fuel Standard credit stacking. The EPA enforces Renewable Fuel Standard blending obligations that lock in annual ethanol and biodiesel volumes. Houston's petrochemical corridor hosts fluid catalytic cracking unit retrofits for renewable feedstock processing.
Germany
Rhineland chemical complexes anchor 10-year green hydrogen offtake agreements that de-risk electrolyzer project finance. The EU Green Deal's Fit for 55 package rebalances road transport fuel obligations toward renewable alternatives. Hamburg and Bremen ports pilot containerized proton exchange membrane units for maritime hydrogen refueling.
China
Alkaline and PEM stack manufacturing scale-up compresses capital expenditure per megawatt for domestic and export markets. The country's dual carbon goals redirect industrial policy toward electrolyzer supply chain localization. Yangtze River Delta industrial clusters integrate solid oxide electrolyzer waste heat into district heating networks.
India
The MNRE production-linked incentive scheme offers capital subsidies for domestic green hydrogen equipment production. State-level renewable purchase obligations in Gujarat and Tamil Nadu accelerate electrolyzer manufacturing location decisions. Hazira and Mundra industrial corridors anchor biogenic feedstock collection networks for biodiesel refiners.
Singapore
Maritime shipping operators expand biofuel bunker contracts ahead of International Maritime Organization carbon intensity indicator deadlines. The port authority mandates sustainable aviation fuel blending for transit cargo carriers. Jurong Island refiners backward integrate into Southeast Asian used cooking oil supply chains.
Alternative Fuels Market Vendor Landscape
Premium-margin players sit above commodity-margin players across feedstock security and certification complexity. Integrated energy majors leverage backward integration into biogenic collection networks, while pure-play refiners concentrate on single-technology scale advantages. Three archetypes dominate: port-anchored logistics controllers, feedstock-integrated refiners, and electrolyzer equipment specialists. Competitive moves center on refinery asset retrofitting and offtake contract tenor compression.
Within the integrated energy tier, BP Plc and Shell exemplify port-anchored logistics dominance through Rotterdam and Singapore terminal control. Neste represents feedstock-integrated refining specialization with Singapore refinery expansion anchoring Asia-Pacific sustainable aviation fuel supply. Among diversified industrial conglomerates, TotalEnergies and ExxonMobil Corporation occupy positions spanning conventional asset retrofit and hydrogen import infrastructure development.
| Leading Market Players |
|---|
| BP Plc |
| Neste |
| ExxonMobil Corporation |
| Sasol Ltd. |
| TotalEnergies |
| Shell |
| Tesla, Inc. |
| BYD Company Ltd. |
| Archer Daniels Midland |
| Others |
Supply Flow & Price Mechanics
Electrolyzer manufacturing scale-up in China and India is compressing capital expenditure per megawatt while simultaneously concentrating stack production in Asian industrial corridors. This dual effect reshapes cost economics for project developers and redirects procurement leverage toward equipment vendors with captive cell manufacturing.
Pricing Analysis
Value-based pricing anchors on lifecycle greenhouse gas reduction outcomes rather than energy content alone. Three-tier pricing structure across certified sustainable, transitional, and conventional grades differentiates hydroprocessed esters and fatty acids producers. Cost compression in green hydrogen is intensifying because alkaline and proton exchange membrane stack output is scaling faster than offtake contract liquidity. Maritime shipping operators demonstrate lowest price sensitivity due to International Maritime Organization compliance deadlines, while commercial fleet operators in California exhibit highest sensitivity to renewable natural gas credit volatility.
Supply Chain Analysis
Dual-sourcing requirements for biogenic feedstocks mandate European renewable diesel refiners qualify collection networks across Malaysia, Indonesia, and Argentina simultaneously. Used cooking oil and animal fat supply chains draw from Southeast Asian aggregation points, creating single-source vulnerability during monsoon logistics disruptions. Distribution runs through Rotterdam, Singapore, and Houston as maritime bunkering hubs with backward-integrated storage and blending infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alternative Fuels Market operates as a cost-of-compliance story where International Maritime Organization carbon intensity regulations erect barrier-to-entry moats for certified bunker fuel suppliers. Players lacking biofuel blending infrastructure face stranded asset risk as enforcement deadlines tighten.
For Market Incumbents: To counter electrolyzer cost curve compression from Asian equipment vendors, European refiners should anchor green hydrogen offtake agreements with Rhineland chemical complexes and accelerate fluid catalytic cracking unit retrofits for renewable feedstock processing. Backward integration into biogenic collection networks in Brazil and the United States secures pipeline-quality renewable diesel supply chains. For New Entrants and Emerging Players: Containerized proton exchange membrane electrolyzer technology offers a manufacturing-light entry path into maritime port hydrogen refueling. White-space concentrates in Hamburg and Bremen pilot programs, Indian state-level renewable purchase obligations in Gujarat, and sustainable aviation fuel blending mandates under ReFuelEU Aviation. Go-to-market should prioritize 18-month delivery window guarantees over utility-scale project development. For Investors and Strategic Acquirers: Exit pathways concentrate in port-anchored logistics controllers with Rotterdam or Singapore terminal control and electrolyzer equipment specialists with solid oxide technology maturation. Long-term viability favors players with simultaneous IEC 62282 fuel cell approvals and EU RED II sustainability certification. The signal to watch is offtake contract tenor compression below 10 years, which would force lenders to accept higher leverage ratios and trigger consolidation among pure-play refiners.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Alkaline and PEM stack production in China and India compresses capital expenditure per megawatt for project developers. |
| Backward Integration into Biogenic Feedstocks | BP Plc and Neste anchor supply security through collection networks in the United States, Brazil, and Southeast Asia. |
| Port-Anchored Hydrogen Import Infrastructure | Shell's Rotterdam terminal control secures European industrial buyer access to liquefied hydrogen logistics. |
| Refinery Asset Retrofit for Renewable Processing | Houston petrochemical corridor conversions require simultaneous catalyst replacement and hydrogen supply reconfiguration. |
| Power-to-X Convergence Investment | Fischer-Tropsch synthesis integration with electrolyzer output enables e-fuel pathways bypassing hydrogen transport constraints. |
Methodological Framework
Independent corroboration across electrolyzer project developers, maritime shipping operators, and renewable diesel refinery procurement leads underwrites the qualitative findings in this study. Primary interviews with proton exchange membrane equipment specialists, biogenic feedstock aggregators in Southeast Asia, and German chemical complex offtake managers combined with secondary validation from International Maritime Organization regulatory filings, European Commission RED II certification databases, and United States EPA Renewable Fuel Standard compliance reports. Bottom-up electrolyzer capacity buildouts and top-down fuel substitution demand curves triangulate volume estimates.
Rate-of-change decomposition across fuel type, application, end user, and technology dimensions structures the analytical framework over the projection horizon. Segmentation modeling incorporates electrolyzer manufacturing location decisions, maritime carbon intensity indicator compliance pathways, and sustainable aviation fuel blending mandate trajectories. CAGRs derive from installed capacity buildout schedules cross-referenced against offtake contract execution timelines and feedstock availability constraints.
Several conditions sit outside the modeled scope, including abrupt International Maritime Organization regulatory revision, fluorinated gas supply disruption under EU F-Gas Regulation, and biogenic feedstock trade restriction implementation. Forecasts reflect assumptions about electrolyzer cost curve trajectories and green hydrogen offtake contract liquidity. Deviation in German industrial cluster demand commitment or Chinese stack export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Renewable Aviation Fuel Market