
 United States Propane Market | 2026-2036
United States Propane Market Size, Share, and Industry Trends Forecast 2026-2036
United States Propane Market Analytics
Natural gas is consolidating its role as the baseline fuel against which propane must differentiate on portability and infrastructure avoidance. AmeriGas Propane leverages its national cylinder exchange network to sustain last-mile density in exurban markets where pipeline economics fail. Ferrellgas anchors its position through vertical control of rail-fed storage terminals in the Midwest, while Suburban Propane competes on route-optimized bulk delivery to residential pools in the Northeast.
Propane (C₃H₈), a liquefied petroleum gas derived from natural gas processing and crude oil refining, stores and transports at moderate pressures near 150 psi, serving primarily as a transportable thermal fuel for space heating, cooking, and engine applications where pipeline connectivity proves impractical. Residential propane commands the largest volume share among product types, though agricultural propane for grain drying exhibits the most pronounced seasonal elasticity and pricing power. Forklift fuel within the application dimension sustains steady industrial offtake from manufacturing facilities and warehousing operations, while tank exchange as a delivery mode captures premium margins through convenience positioning against bulk tank installations.
The EPA regulates propane combustion emissions under the Clean Air Act, while OSHA sets workplace exposure limits for liquefied petroleum gas handling, and DOT governs interstate transport through its hazardous materials pipeline safety program. These frameworks collectively elevate compliance costs for smaller distributors while reinforcing the competitive advantage of scaled operators with dedicated safety infrastructure. Stakeholders must monitor the trajectory of electrification mandates in residential building codes and their carve-out provisions for rural and off-grid properties.
Market Dynamics
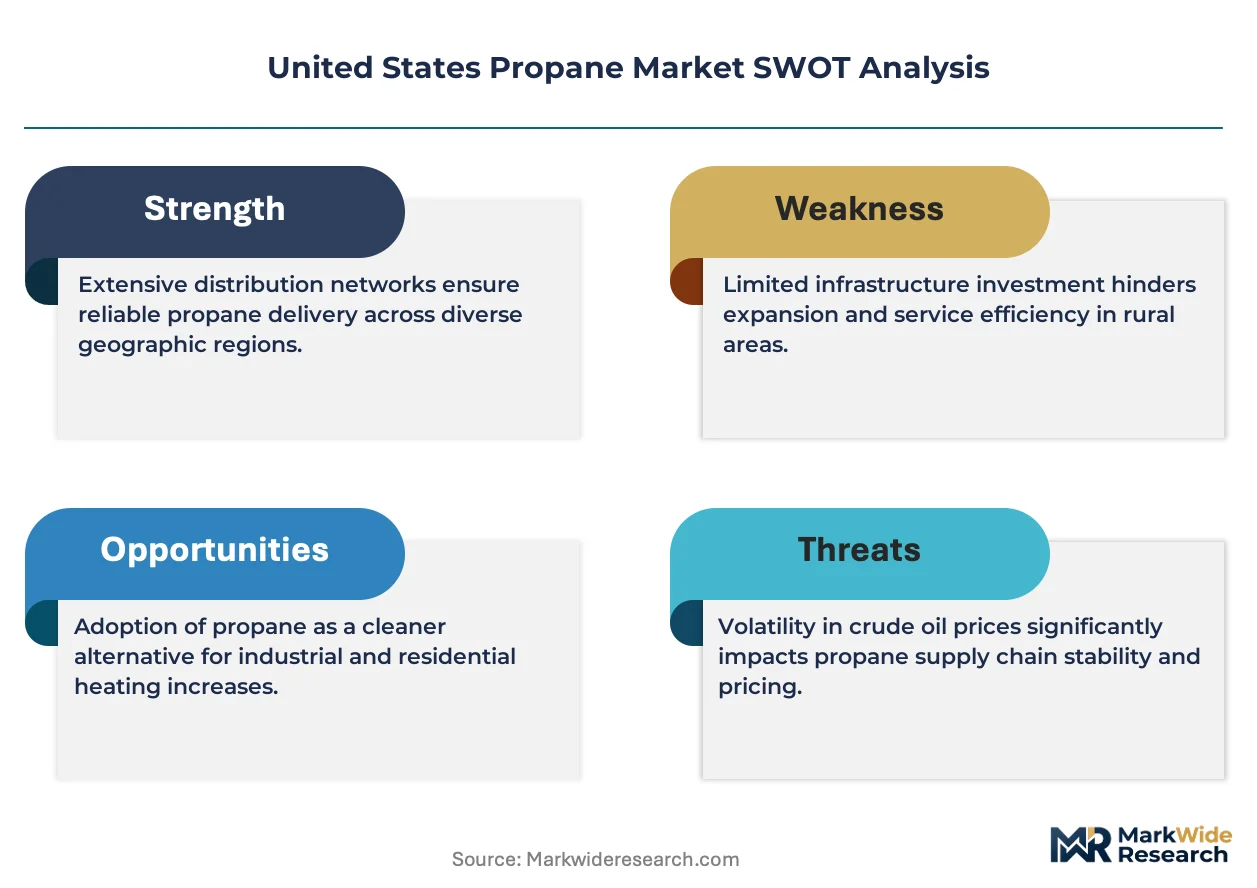
The United States propane market faces structural pressure from electrification mandates in residential building codes, even as rural infrastructure gaps preserve demand for portable thermal fuels. EPA emissions standards for stationary combustion equipment are accelerating fuel-switching decisions in off-grid commercial buildings.
Growth Catalysts
- Clean Air Act stationary source rules:EPA regulations targeting fuel oil and coal combustion in commercial buildings are expanding addressable demand for propane as a compliant bridge fuel in rural and exurban zones.
- Petrochemical feedstock pull:Gulf Coast crackers and Midwest polypropylene facilities are absorbing increasing propane volumes for propylene production, anchoring industrial offtake in Texas and Ohio.
- Grain drying seasonality:Agricultural propane demand surges during harvest windows in Iowa, Illinois, and Nebraska, creating pricing power and volume concentration that supports distributor infrastructure investment.
Market Restraints
- Natural gas lateral economics:Pipeline buildouts in the Marcellus and Utica shale regions are eroding propane's historical stronghold in Pennsylvania residential heating by connecting previously unserved addresses.
- Crude oil price volatility:Propane pricing correlates with NGL fractionation spreads and refinery output decisions, exposing end-users to input cost swings that compressed margins during the 2022 energy price spike.
- Heat pump efficiency thresholds:Cold-climate electric heat pumps achieving coefficient of performance above 2.0 in sub-zero conditions are displacing propane furnaces in new construction across Minnesota and Wisconsin.
Strategic Opportunities
- Autogas fleet conversions:School bus and municipal fleet operators in Texas and California are piloting propane engine retrofits to meet state-level clean air mandates while avoiding EV charging infrastructure costs.
- Renewable propane pathways:Bio-based propane derived from camelina and used cooking oil is qualifying for California LCFS credits and federal renewable fuel standard pathways, opening premium pricing tiers.
- Cylinder exchange densification:Last-mile grill and forklift cylinder networks in exurban Atlanta and Phoenix corridors remain underpenetrated relative to population growth, supporting route optimization investments.
Industry Challenges
- CDL driver recruitment:Bulk transport operators face acute shortages of hazmat-endorsed commercial drivers, constraining delivery capacity during peak heating and agricultural demand windows.
- ASME tank recertification backlog:DOT cylinder and tank inspection intervals are creating service bottlenecks as aging residential infrastructure requires pressure testing and valve replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Propane Market |
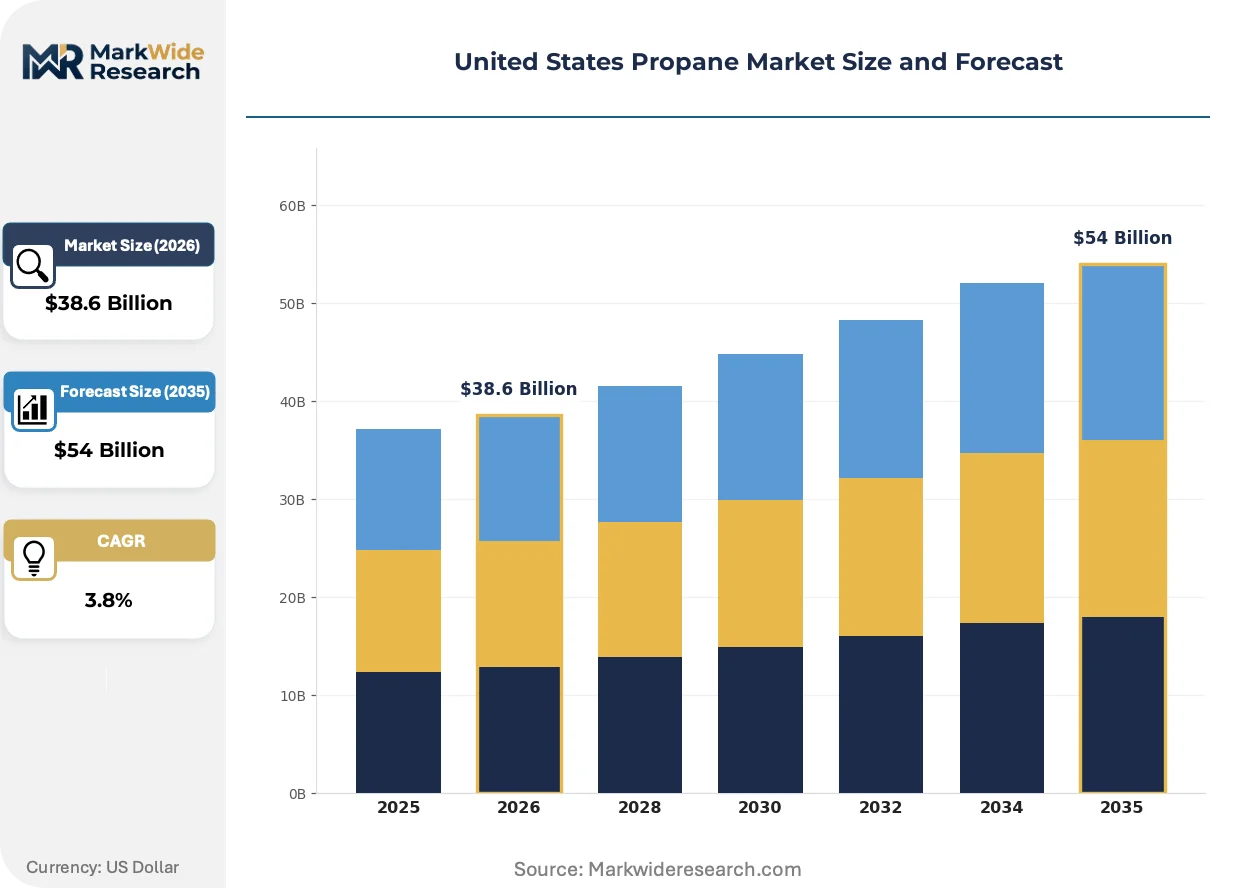
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Propane, Residential Propane, Agricultural Propane, Industrial Propane Application: Heating, Cooking, Forklift Fuel, Power Generation Delivery Mode: Cylinders, Bulk Delivery, Pipelines, Tank Exchange End User: Households, Restaurants, Farms, Manufacturing Facilities |
| Companies Covered | AmeriGas Propane, Ferrellgas, Suburban Propane, Superior Plus Propane, UGI Corporation, ThompsonGas, Blossman Gas, Global Partners, DCC Propane, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Propane Market Evolving Landscape
Propane market evolution centers on fuel positioning within decarbonization pathways, regulatory compliance technology, and distribution model compression. Three forces are actively restructuring competitive advantage.
Renewable propane production pathways are converging with state-level low-carbon fuel standards to create certified product tiers. Neste and Diamond Green Diesel are scaling hydrotreated renewable diesel coproduction that yields bio-propane as a byproduct. California LCFS credit values and Oregon's clean fuels program are pulling this supply into West Coast markets, enabling price premiums over conventional product.
EPA's updated New Source Performance Standards for residential wood heaters and the agency's ongoing review of oil-fired boiler emissions are tightening compliance windows for legacy heating fuels. The industrial consequence is accelerated equipment replacement cycles in Maine, Vermont, and New Hampshire, where fuel oil dominance is eroding. Distributors are responding by bundling propane tankless water heaters and space conditioning systems through contractor channels.
Buyer concentration among national homebuilders is compressing procurement cycles and unbundling installation from fuel supply. D.R. Horton and Lennar are standardizing propane infrastructure in exurban subdivisions across Texas Hill Country and Arizona Sun Corridor, but negotiating multi-year supply agreements that displace spot market relationships. This shift is most visible in Phoenix and Austin metro fringes, where master-planned communities are pre-plumbing for propane despite natural gas proximity.
United States Propane Market Segmentation
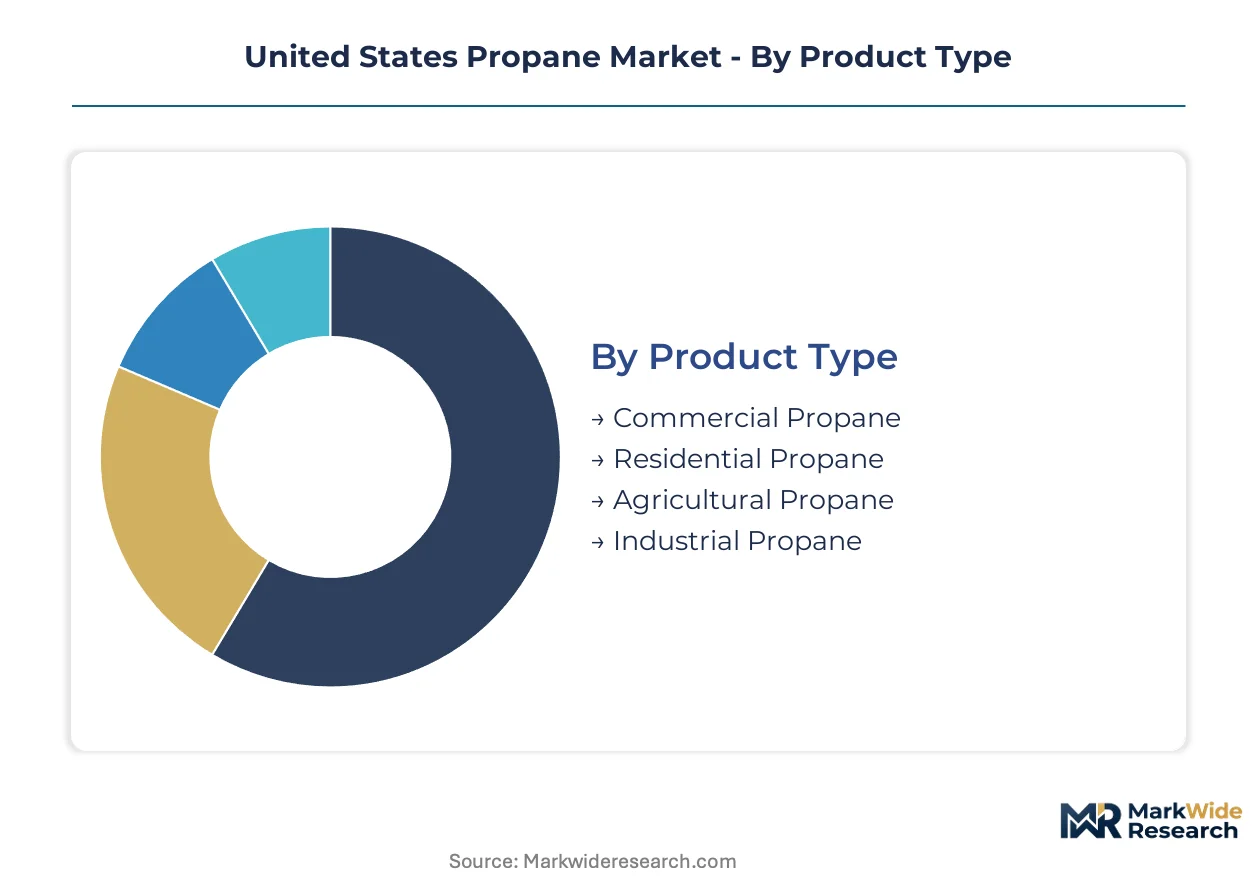
Propane segmentation in the United States reflects infrastructure constraints and thermal load profiles that vary sharply across rural, exurban, and industrial zones. Each category maps to distinct procurement rhythms, regulatory exposure, and margin structures that distributors must navigate.
Product Type:
Standardization dominates commodity propane, yet application-specific purity grades and seasonal demand patterns create meaningful customization tiers across this category.
- Residential Propane:HD-5 grade propane meeting ASTM D1835 specifications serves space heating and water heating in off-grid households. Demand concentrates across Midwestern states where natural gas laterals remain uneconomical, with EPA emissions rules accelerating displacement of fuel oil systems in Maine and Vermont.
- Commercial Propane:Identical HD-5 specification deployed across restaurants, hotels, and retail facilities for cooking and backup generation. Volume aggregates in exurban corridors of Texas Hill Country and Arizona Sun Corridor where master-planned communities pre-plumb infrastructure despite pipeline proximity.
- Agricultural Propane:Seasonal grain drying in Iowa, Illinois, and Nebraska drives concentrated harvest-window demand with pronounced pricing power.
- Industrial Propane:Petrochemical feedstock absorption at Gulf Coast crackers and Midwest polypropylene facilities anchors baseline offtake in Texas and Ohio.
Most installed capacity flows through Residential Propane. Expansion is steepest in Agricultural Propane.
Application:
Volume scale versus margin intensity separates applications, with thermal efficiency regulations reshaping equipment replacement cycles unevenly across use cases.
- Heating:Furnace and boiler combustion in residential and commercial buildings faces electrification pressure from cold-climate heat pump thresholds, though rural infrastructure gaps preserve propane's role in Minnesota and Wisconsin exurbs.
- Cooking:Commercial kitchen demand from independent restaurants and institutional foodservice maintains steady offtake with premium pricing relative to heating applications.
- Forklift Fuel:Indoor material handling operations at manufacturing facilities and warehousing complexes sustain consistent industrial demand with lower seasonal volatility than heating loads.
- Power Generation:Backup generators and prime power systems in off-grid commercial buildings absorb volumes where grid reliability concerns intersect with EPA stationary source compliance requirements.
Heating commands the largest volume share. Forklift Fuel offers the most stable year-round demand profile.
Delivery Mode:
Capital intensity and route density requirements fragment delivery economics, with convenience premiums available only at sufficient scale.
- Bulk Delivery:500-gallon and larger ASME tank installations serve residential heating pools and agricultural operations through scheduled route optimization. Midwest rail-fed storage terminals anchor this infrastructure.
- Tank Exchange:Pre-filled cylinder networks for grills and patio heaters capture convenience premiums in exurban Atlanta and Phoenix corridors where population growth outpaces infrastructure deployment.
- Cylinders:Direct cylinder sales to commercial accounts and individual consumers support portable applications with lower capital barriers than bulk tank commitments.
- Pipelines:Limited to industrial corridors and petrochemical complexes where continuous high-volume offtake justifies dedicated infrastructure investment.
Bulk Delivery moves the majority of volume. Tank Exchange generates the highest per-unit margins.
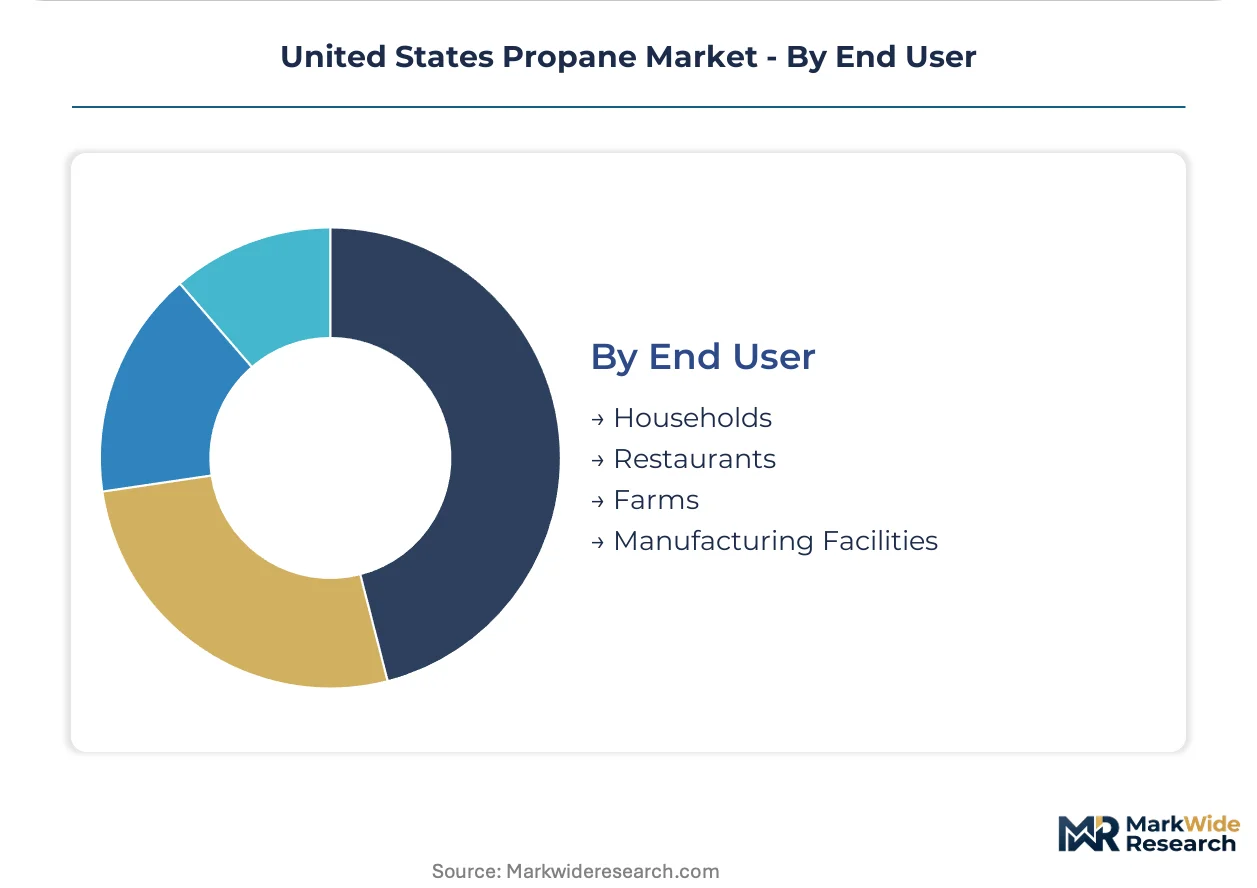
End User:
Procurement sophistication and price sensitivity diverge sharply between fragmented household demand and concentrated industrial accounts.
- Households:Individual residential consumers in rural and exurban zones purchase through spot market relationships or multi-year supply agreements, with national homebuilders standardizing infrastructure in new construction.
- Farms:Grain drying operations in Iowa, Illinois, and Nebraska exhibit extreme seasonal concentration that strains distributor logistics capacity during harvest windows.
- Restaurants:Independent and chain foodservice operators prioritize reliability and delivery frequency over price optimization for cooking applications.
- Manufacturing Facilities:Industrial accounts leverage volume scale for negotiated supply contracts, with forklift fuel and process heat applications driving consistent offtake.
Households represent the broadest addressable base. Farms drive the most acute seasonal pricing dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors national propane demand through propylene production at Texas crackers and fractionation complexes. Midwest grain belts and Northeast heating markets concentrate seasonal offtake patterns. Regional infrastructure investments and regulatory frameworks shape competitive positioning across distinct supply basins.
Texas
Gulf Coast petrochemical facilities absorb industrial propane volumes for propylene production at Mont Belvieu and Corpus Christi complexes. EPA stationary source rules accelerate fuel-switching in off-grid commercial buildings across the Permian Basin. The Houston Ship Channel concentration of NGL fractionators and export terminals anchors national pricing benchmarks.
Pennsylvania
Marcellus shale production supplies regional fractionators with wet gas streams yielding propane for residential heating pools. Natural gas lateral buildouts in the Utica formation erode historical propane strongholds in rural counties. Pittsburgh and Philadelphia metropolitan fringes sustain demand through master-planned community pre-plumbing despite pipeline proximity.
Ohio
Midwest polypropylene facilities in the Ohio River Valley anchor petrochemical feedstock absorption alongside agricultural drying operations. FERC interstate pipeline safety programs govern transport infrastructure connecting Appalachian supply to regional markets. Cleveland-Akron industrial corridors sustain forklift fuel demand from warehousing and manufacturing operations.
California
LCFS credit mechanisms pull renewable propane derived from camelina and used cooking oil into West Coast transportation and heating applications. CARB clean air mandates drive school bus and municipal fleet autogas conversions in Los Angeles and Central Valley corridors. San Joaquin Valley agricultural operations maintain seasonal grain drying demand with pricing exposure to carbon credit volatility.
United States Propane Market Competitive Landscape
Global majors compete with regional champions across delivery density and last-mile infrastructure deployment. The vendor base organizes around three tiers: national cylinder exchange networks, rail-fed bulk storage operators, and route-optimized residential specialists. Strategic archetypes include vertical integrators controlling terminal-to-tank logistics, acquisition-driven consolidators, and niche exurban density builders. Dominant competitive moves center on terminal asset acquisition and cylinder exchange network densification.
Among national-scale distributors, AmeriGas Propane, Ferrellgas, and Suburban Propane exemplify distinct infrastructure strategies. AmeriGas occupies a position emphasizing cylinder exchange density in exurban corridors. Ferrellgas anchors rail-fed terminal control in the Midwest supply basin. Suburban Propane represents route-optimized bulk delivery specialization in Northeast residential pools.
| Leading Market Players |
|---|
| AmeriGas Propane |
| Ferrellgas |
| Suburban Propane |
| Superior Plus Propane |
| UGI Corporation |
| ThompsonGas |
| Blossman Gas |
| Global Partners |
| DCC Propane |
| Others |
Value Network & Pricing Analysis
HD-5 grade certification against renewable propane LCFS qualification splits the United States propane market into parallel pricing architectures, with conventional commodity propane tracking Mont Belvieu NGL benchmarks while California-bound bio-propane captures carbon credit premiums that reshape terminal allocation decisions and transport mode selection.
Pricing Analysis
Mont Belvieu fractionation spreads and crude oil refining runs transmit directly into rack pricing across Texas and Midwest supply basins. Price differentiation separates bulk contract residential heating pools from spot agricultural offtake during Iowa and Illinois harvest windows. Cost compression in conventional propane stems from Permian wet gas oversupply, while renewable product maintains pricing power through Oregon and California clean fuels program eligibility. Agricultural cooperatives exhibit acute price sensitivity during grain drying peaks, whereas petrochemical crackers lock in long-term offtake with volume-scale leverage.
Supply Chain Analysis
Hazmat-endorsed driver shortages and rail car availability constrain last-mile delivery economics more than production capacity. Supply concentrates in Texas Gulf Coast fractionators, Appalachian wet gas processing, and Midwest NGL storage hubs. Raw material dependencies include associated gas from Permian crude production, refinery off-gas streams, and renewable feedstocks of camelina and used cooking oil. Single-source vulnerability runs through FERC-regulated interstate pipeline corridors connecting Mont Belvieu to Northeast markets. Distribution runs through rail-fed terminals for bulk residential pools, cylinder exchange networks for exurban convenience, and dedicated pipeline spurs for Gulf Coast petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States propane market functions as a geographic-arbitrage play where renewable propane LCFS credit eligibility in California and Oregon generates 40-60 cent per gallon pricing premiums against identical molecules sold into unregulated Midwest heating pools.
For Market Incumbents: Hedge fuel-switching risk in Northeast residential heating by accelerating tankless water heater bundling through contractor channels before cold-climate heat pump thresholds displace furnace replacements in Maine and Vermont. Deepen terminal control along Ohio River Valley rail corridors to anchor polypropylene feedstock supply agreements. Prioritize ASME tank recertification service capacity to capture aging infrastructure replacement cycles.
For New Entrants and Emerging Players: A 25-30 cent per gallon spread between bulk residential contract rates and tank exchange convenience pricing creates entry space for cylinder network densification in exurban Atlanta and Phoenix corridors where population growth outpaces pipeline lateral deployment. Target master-planned community pre-plumbing specifications in Texas Hill Country and Arizona Sun Corridor before national homebuilders standardize multi-year supply agreements. Lead with route-optimized bulk delivery to fragmented agricultural cooperatives in Nebraska and Kansas where incumbent coverage gaps persist.
For Investors and Strategic Acquirers: Consolidation pressure builds where CDL driver recruitment constraints cap delivery capacity expansion during peak seasonal demand windows. Frame five-to-ten year viability around renewable propane pathway scaling and state-level clean fuel standard geographic expansion. Acquisition targets should display rail-fed terminal assets with backward integration into NGL fractionation or cylinder exchange networks with exurban density above 15,000 households per distribution point. Monitor EPA stationary source rulemaking timelines as inflection signals for fuel oil displacement acceleration in off-grid commercial buildings.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Propane Production Scale-Up | Neste and Diamond Green Diesel coproduction yields qualify for California LCFS credits and federal RFS pathways. |
| Rail-Fed Terminal Capacity Expansion | Ferrellgas Midwest infrastructure anchors grain drying supply security during Iowa and Illinois harvest peaks. |
| Cylinder Exchange Network Densification | AmeriGas exurban Atlanta and Phoenix corridors capture convenience premiums from population growth. |
| Autogas Fleet Conversion Partnerships | Texas and California school bus pilots avoid EV charging infrastructure costs while meeting CARB mandates. |
| ASME Tank Recertification Service Buildout | DOT inspection intervals create bottlenecks that specialized service operators can monetize. |
Research Methodology
Bottom-up residential heating and agricultural drying modeling reconciled against top-down NGL fractionation and petrochemical feedstock tracking forms the analytical core of this study. Primary interviews with propane distributor operations directors, terminal asset managers, agricultural cooperative procurement leads, and national homebuilder energy specification teams combined with secondary validation from EIA petroleum supply data, FERC interstate pipeline filings, and EPA stationary source compliance databases. Triangulation across these sources produced volume and value estimates calibrated to Mont Belvieu pricing benchmarks and regional rack differentials.
An input-output matrix framing connects propylene production demand at Gulf Coast crackers, grain drying thermal load curves across Midwest harvest windows, and residential heating degree-day patterns to generate segment-level projections across the analysis window. Segmentation dimensions include product grade tier, application thermal profile, delivery mode capital intensity, and end-user procurement sophistication. CAGRs derive from regression analysis of historical NGL fractionation spread volatility, regulatory compliance cost trajectories, and electrification mandate adoption curves. Forecast inputs incorporate renewable propane production pathway scaling and state-level low-carbon fuel standard geographic expansion.
The model assumes a particular technology adoption path; alternative pathways for cold-climate heat pump performance thresholds or renewable propane feedstock availability would alter the outlook for conventional propane displacement rates and premium pricing tier expansion. Forecasts reflect documented assumptions about EPA rulemaking timelines, natural gas lateral economics in Appalachia, and LCFS credit value stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Sustainable Fuel Market