
 Biohydrogen Market | 2026-2036
Biohydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Biohydrogen Market Outlook
Buyer concentration around large fleet operators and industrial off-takers is hardening across the biohydrogen value chain. Air Products leverages its global hydrogen infrastructure network to secure long-term supply contracts with refiners and ammonia producers. Linde sustains technology leadership through proprietary electrolyzer and gas handling systems deployed at scale. Plug Power anchors North American demand through captive offtake agreements with material handling and logistics customers.
Biohydrogen denotes hydrogen produced from biomass feedstocks or biogenic waste streams through microbial, thermochemical, or photolytic pathways, typically yielding purity grades between 95% and 99.9% depending on downstream upgrading requirements. Its primary commercial purpose centers on decarbonizing hard-to-abate sectors where direct electrification proves technically or economically impractical. Dark fermentation and thermochemical routes currently dominate installed production capacity, though photolytic systems attract accelerated R&D investment as conversion efficiencies improve. On the demand side, transportation and industrial end users represent the deepest margin pools, with chemical processing applications following as blue hydrogen substitution timelines tighten.
The EU Hydrogen Strategy, REPowerEU, and the F-Gas Regulation collectively shape production targets, subsidy eligibility, and equipment standards across European member states. The EPA and IRA tax credit structures in the United States similarly steer capital allocation toward qualified renewable hydrogen projects through production incentives and carbon intensity thresholds. Stakeholders must track evolving certification schemes for green versus blue versus biohydrogen origin claims, as these classifications increasingly determine market access and premium pricing eligibility in bilateral supply negotiations.
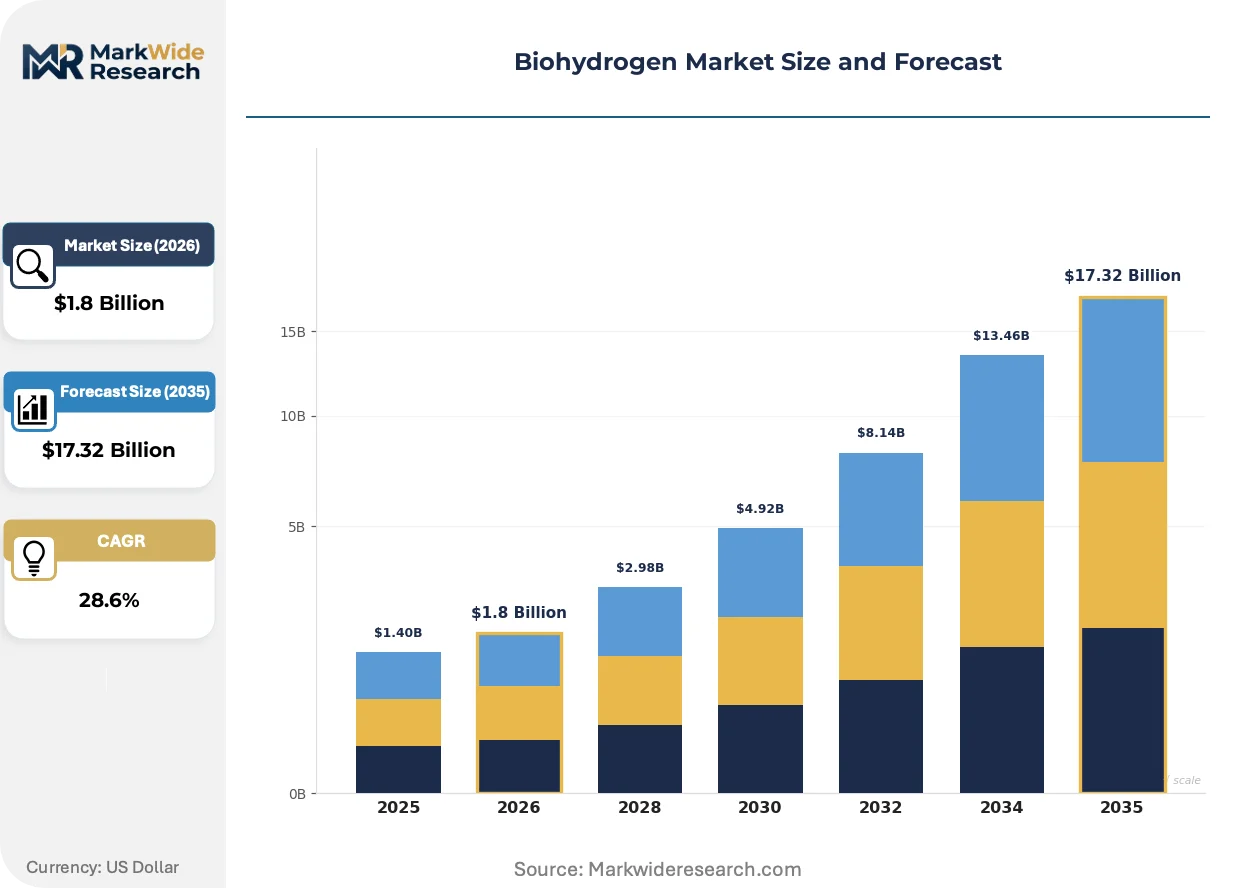
Market Dynamics
Transportation fleets in Europe are consolidating offtake agreements faster than production capacity can scale, creating a structural supply bottleneck that favors early-mover producers with certified biogenic feedstock access. This demand compression is reshaping contract structures across the value chain.
Growth Catalysts
- REPowerEU framework:The EU's production targets for renewable hydrogen accelerate member state subsidy programs and streamline permitting for biogenic pathways. Industrial clusters in Germany and the Netherlands secure priority grid access and carbon credit eligibility.
- Hard-to-abate sectors:Ammonia producers and steelmakers face tightening Scope 3 emissions requirements, driving substitution timelines for gray hydrogen with biohydrogen in high-heat processes where electrification remains uneconomical.
- Dark fermentation:This thermochemical route achieves higher yields from agricultural waste streams than photolytic alternatives, attracting capital deployment from waste management operators seeking circular economy revenue streams.
Market Restraints
- Feedstock concentration risk:Agricultural residue supply clusters in specific European regions, exposing producers to seasonal availability swings and competing demand from biogas and biofuel processors.
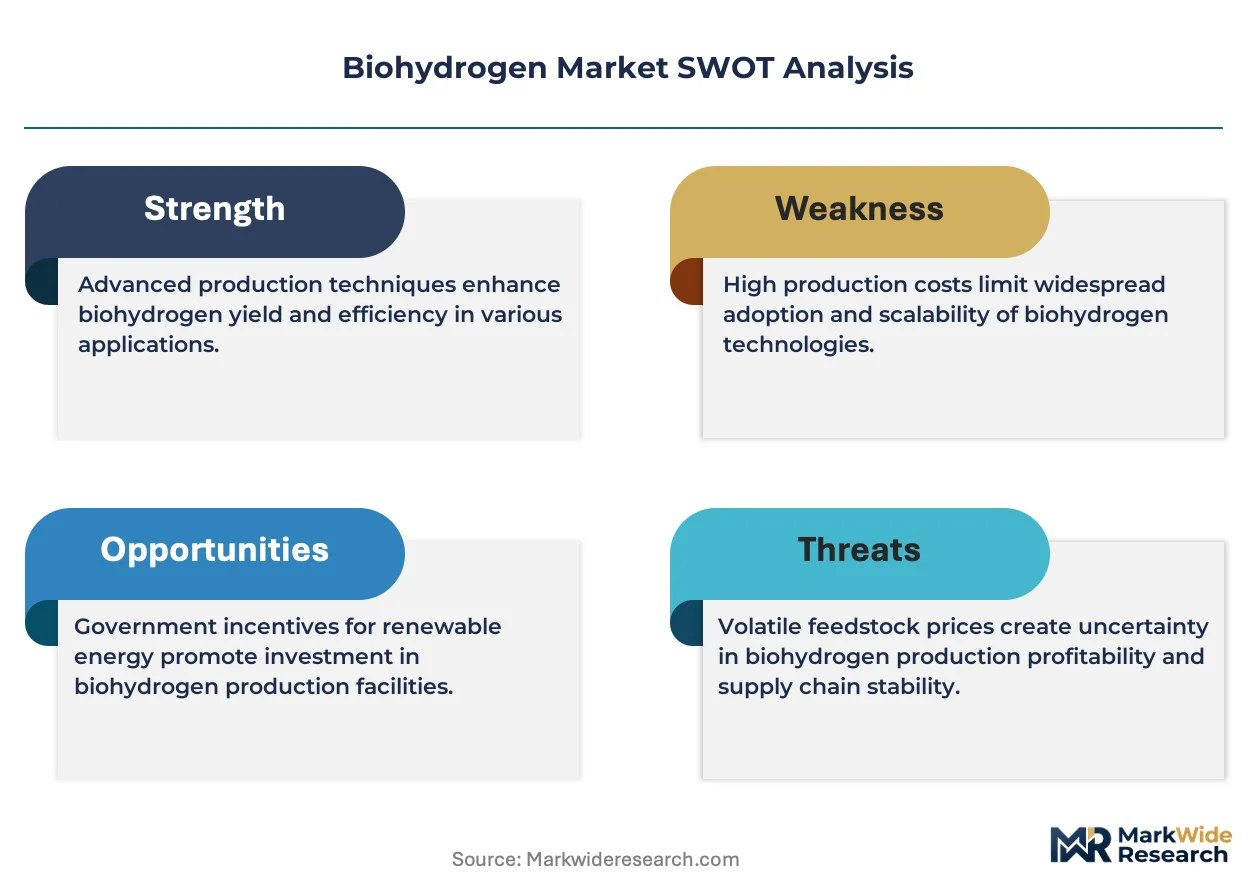
- Electrolyzer cost structure:Proton exchange membrane stacks and precious metal catalysts represent fixed cost anchors that compress project returns until manufacturing scale achieves learning curve effects.
- Blue hydrogen substitution:Steam methane reforming with carbon capture retains cost advantages in regions with cheap natural gas, delaying biohydrogen penetration in price-sensitive industrial applications.
Strategic Opportunities
- Spain's hydrogen valleys:The country's renewable energy surplus and available land for biomass cultivation position it as a low-cost production hub for export to northwest European demand centers.
- Photolytic-microalgae convergence:Combining genetically optimized strains with closed photobioreactor designs promises yield breakthroughs that could reset the cost curve for high-purity biohydrogen.
- Certification arbitrage:The CertifHy and TÜV schemes for renewable hydrogen origin tracking create premium pricing tiers for biohydrogen with verifiable biogenic content, rewarding early compliance investments.
Industry Challenges
- Bioprocess engineering talent scarcity:The specialized skill set spanning microbiology, thermochemical systems, and gas upgrading remains concentrated in academic and national laboratory settings, constraining project execution velocity.
- Pipeline steel embrittlement standards:Existing natural gas infrastructure requires material validation and retrofit protocols before biohydrogen blending, stretching certification timelines with national safety regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biohydrogen Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Technology: Dark Fermentation, Photolytic, Thermochemical, Biological Water Gas Shift End User: Transportation, Energy Generation, Industrial, Chemical Processing Storage Method: Compressed Gas, Liquid Hydrogen, Metal Hydrides, Chemical Hydrides Distribution Channel: Pipelines, Tanker Trucks, Rail Transport, On-site Generation |
| Companies Covered | Air Products, Tidewater Renewables, Linde, Gold Hydrogen, Hazer Group, Plug Power, Ballard Power Systems, Pure Hydrogen, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biohydrogen Market Strategic Shifts
Conversion efficiency gains in biological pathways are compressing the cost gap with electrolytic hydrogen faster than anticipated, while regulatory frameworks harden carbon intensity thresholds that exclude fossil-derived alternatives.
Solid oxide electrolysis cells integrated with biogas reforming are electrifying the efficiency frontier for biohydrogen production by capturing waste heat from adjacent industrial processes. Chemical processors in the Netherlands deploy these hybrid systems to achieve sub-2 kg CO2e per kg H2 carbon intensities. This thermal integration is compressing the delivered cost structure for cluster-based producers with access to paper mill or food processing waste heat.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is tightening equipment standards for hydrogen liquefaction and storage systems deployed across European industrial zones. Compressor manufacturers must retest and recertify cold box designs under updated safety protocols, extending procurement lead times for new production facilities. Northern European project developers are responding by front-loading equipment orders and negotiating regulatory grace periods with national implementation agencies.
Fleet operators are consolidating procurement through multi-year offtake agreements that bundle supply certainty with carbon accounting services, displacing spot market purchasing for transportation applications. Logistics customers in Germany negotiate directly with producers rather than intermediaries, extracting volume discounts in exchange for demand visibility. This direct contracting pattern is most visible in heavy-duty trucking corridors where fuel cell range requirements mandate dedicated supply infrastructure.
Biohydrogen Market Segmentation
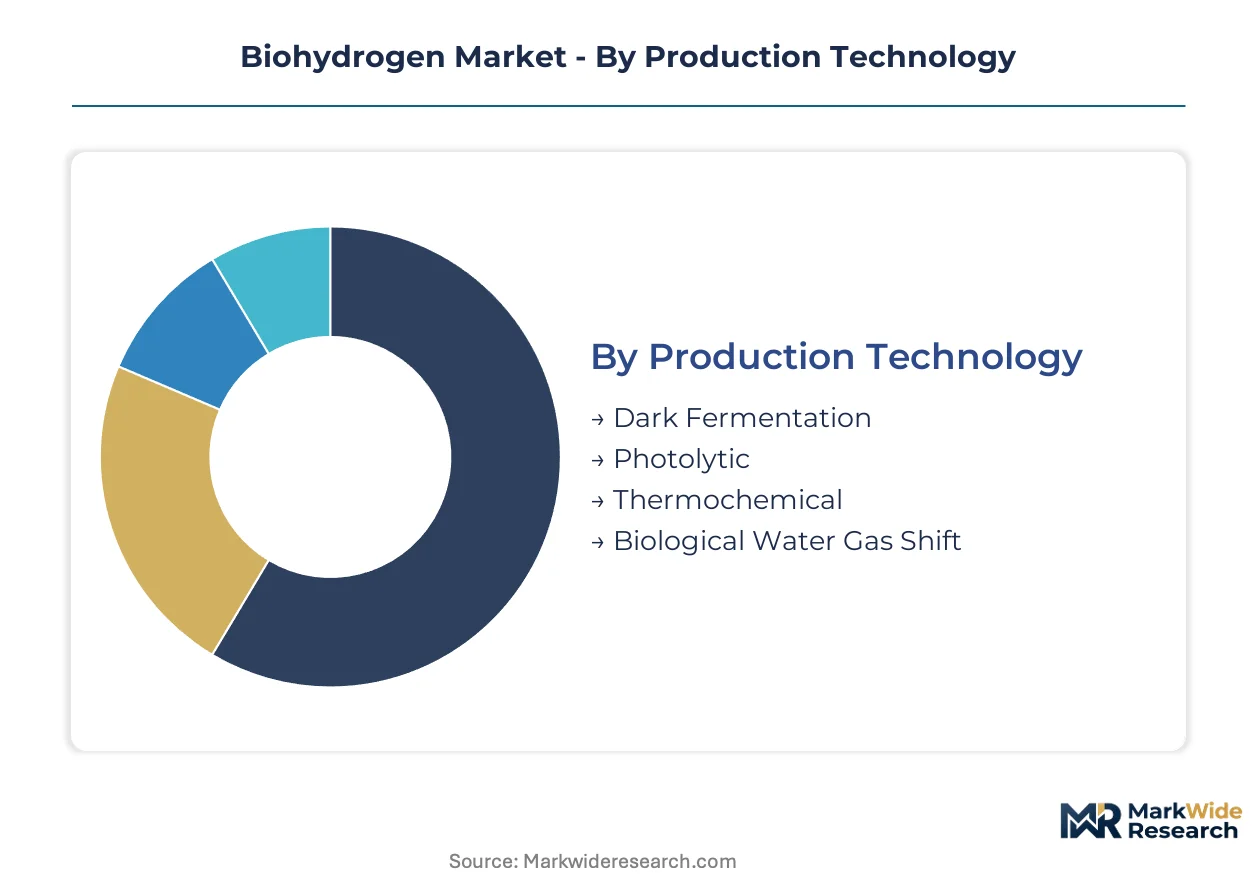
Technology pathways and end-use applications fragment the biohydrogen market into distinct investment and operational profiles. Each segment carries unique carbon intensity thresholds, feedstock requirements, and infrastructure dependencies that shape procurement decisions across European industrial clusters.
Production Technology:
Upgrade cycles in production technology track feedstock availability and carbon accounting precision, with operators replacing first-generation systems to capture subsidy eligibility under tightening EU certification standards.
- Dark Fermentation:Anaerobic bacteria convert carbohydrate-rich agricultural residues into hydrogen and organic acids without external energy input. German biogas operators retrofit existing digesters with gas upgrading membranes to serve ammonia producers in the Ruhr industrial cluster, leveraging established waste collection networks and REPowerEU tariff guarantees.
- Photolytic:Cyanobacteria and microalgae harness solar energy to split water molecules through direct biophotolysis. Dutch pilot facilities near Rotterdam integrate closed photobioreactors with offshore wind curtailed power, targeting sub-1 kg CO2e per kg H2 intensities for export to Belgian steelmakers facing Scope 3 compliance deadlines.
- Thermochemical:Gasification and pyrolysis of lignocellulosic biomass at high temperatures yields syngas for hydrogen extraction. Spanish operators in Extremadura exploit olive pomace and forestry residues with plasma torch reactors.
- Biological Water Gas Shift:Hydrogen-oxidizing bacteria convert carbon monoxide in syngas streams through enzymatic reactions. French chemical parks deploy these systems as bolt-on units to existing syngas infrastructure.
Thermochemical sits at the top of the volume ranking, with photolytic climbing the fastest as Dutch and Spanish demonstration plants scale toward commercial operation.
End User:
Customer type determines purity specifications, delivery reliability requirements, and contract duration, with industrial offtakers demanding 99.9% grades and transportation fleets accepting 95% with mobile refueling flexibility.
- Transportation:Heavy-duty fuel cell trucks and municipal bus fleets consume compressed biohydrogen at 350-700 bar dispensing pressures. German logistics corridors along the Rhine-Alpine TEN-T network anchor demand through dedicated hydrogen refueling stations operated by fleet consortia in Baden-Württemberg.
- Industrial:Steelmakers, cement producers, and glass manufacturers substitute biohydrogen for natural gas in high-heat processes exceeding 1000°C. Swedish steel producer HYBRIT sources biogenic hydrogen for direct reduction ironmaking, displacing coking coal in blast furnace operations.
- Energy Generation:Grid-balancing power plants and combined heat and fuel cell systems utilize biohydrogen for seasonal storage and peak shaving. Italian utilities blend biogenic hydrogen into existing natural gas turbines under F-Gas Regulation transitional permits.
- Chemical Processing:Ammonia, methanol, and refinery hydrotreating operations require consistent high-volume supply with carbon intensity documentation. Dutch chemical cluster operators in the Port of Rotterdam negotiate 10-year offtake agreements tied to CertifHy guarantees of origin.
Industrial applications command the largest contract values, with transportation expanding most quickly as fleet electrification timelines compress and hydrogen corridor infrastructure matures.
Storage Method:
Margin structures vary sharply across storage modalities, with cryogenic systems capturing premium pricing for long-distance maritime export while compressed gas dominates short-haul terrestrial distribution.
- Compressed Gas:Gaseous hydrogen at 200-700 bar in Type IV carbon-fiber composite cylinders enables rapid refueling for mobility applications. German automotive suppliers standardize on 700 bar systems for passenger vehicle compatibility, while industrial tube trailers operate at 200-250 bar for cost efficiency.
- Liquid Hydrogen:Cryogenic liquefaction at -253°C achieves 800x density compression for intercontinental shipping and aerospace applications. Spanish export terminals in the Basque Country develop liquid hydrogen loading infrastructure for Atlantic maritime routes to northwest European demand centers.
- Metal Hydrides:Intermetallic compounds absorb hydrogen at moderate pressures and release it through controlled heating. Japanese stationary storage deployments favor titanium-iron alloys for building-scale fuel cell backup systems.
- Chemical Hydrides:Liquid organic hydrogen carriers and ammonia enable ambient-temperature transport with catalytic release at destination. German chemical engineering firms pilot toluene-methylcyclohexane cycles for rail-based hydrogen logistics.
Compressed gas maintains dominant share in operational installations, with liquid hydrogen gaining share fastest as Iberian export hub development accelerates.
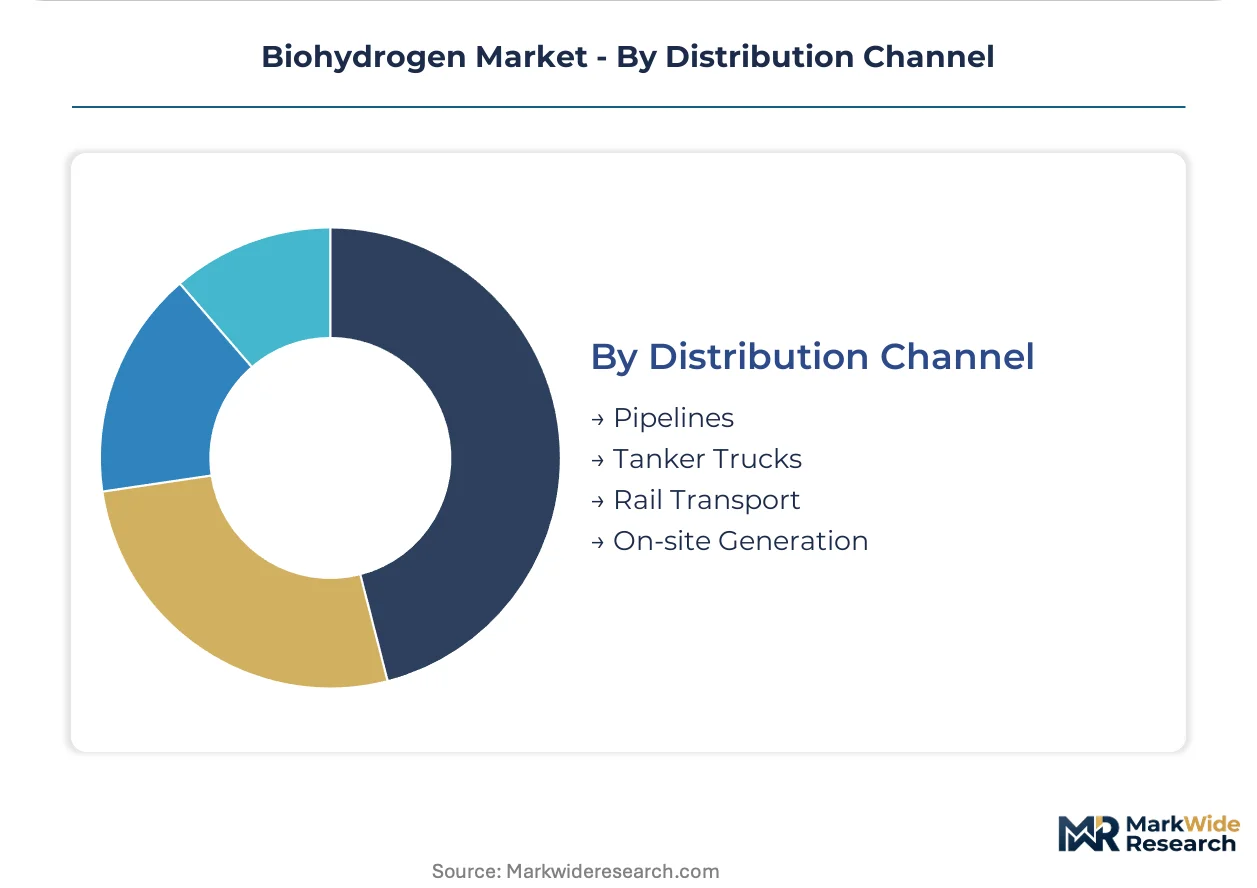
Distribution Channel:
Supply concentration around pipeline networks in industrialized regions creates geographic moats, while mobile distribution modes serve dispersed demand in early-market penetration zones.
- Pipelines:Dedicated hydrogen pipelines and repurposed natural gas infrastructure deliver continuous flow to clustered industrial users. The Netherlands converts existing 12-inch gas pipelines in Zeeland for 100% hydrogen service, connecting biogenic production to Antwerp chemical processors.
- Tanker Trucks:Cryogenic and compressed gas tube trailers bridge supply gaps where pipeline infrastructure remains undeveloped. French distributors deploy 40-ton liquid hydrogen road tankers from Normandy production sites to Paris-region refueling stations.
- Rail Transport:Bulk liquid hydrogen movement via specialized cryogenic railcars serves landlocked industrial zones. German railway operators test modified tank wagons on electrified corridors between Hamburg and Munich industrial belts.
- On-site Generation:Modular electrolyzer and fermentation units eliminate distribution costs for isolated high-volume consumers. Swedish pulp mills install dark fermentation systems adjacent to black liquor processing to capture captive hydrogen for bleaching operations.
Pipelines anchor throughput volumes in established corridors, with on-site generation expanding most quickly as waste-integrated production achieves parity with delivered supply costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest project pipeline in Europe while Spain leverages renewable energy surpluses to undercut production costs elsewhere. This divergence between established demand centers and emerging supply hubs defines regional investment flows.
Germany
Ruhr industrial cluster ammonia producers and Rhine-Alpine hydrogen corridor fleets anchor offtake demand. The national hydrogen strategy allocates EUR 9 billion through 2030 for domestic electrolysis and import infrastructure. Baden-Württemberg logistics consortia operate dedicated refueling stations along the A8 motorway corridor.
Spain
Extremadura olive pomace and forestry residue supplies feed thermochemical production at scale. REPowerEU framework eligibility streamlines permitting for biogenic pathways in designated hydrogen valleys. Basque Country terminals develop liquid hydrogen loading infrastructure for Atlantic export routes.
Netherlands
Port of Rotterdam chemical processors negotiate decade-long supply agreements with carbon intensity documentation requirements. The F-Gas Regulation drives equipment recertification for liquefaction systems deployed at cluster facilities. Zeeland pipeline conversions connect biogenic production to Antwerp demand centers.
Sweden
HYBRIT steel consortium sources biogenic hydrogen for direct reduction ironmaking, displacing coking coal in blast furnace operations. National fossil-free steel mandates accelerate substitution timelines for gray hydrogen. Pulp mills in Norrland install dark fermentation systems adjacent to black liquor processing.
France
Normandy production sites supply liquid hydrogen via 40-ton road tankers to Paris-region refueling stations. The country's national energy regulator certifies biogenic origin claims under EU taxonomy alignment rules. Chemical parks in Lyon deploy biological water gas shift systems as bolt-on units to existing syngas infrastructure.
Biohydrogen Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology and geography vectors. Industrial gas incumbents leverage global hydrogen infrastructure networks to secure long-term supply contracts with refiners and ammonia producers. Three archetypes dominate: vertically integrated energy majors, specialized electrolyzer and fermentation technology providers, and captive fleet operators with dedicated offtake agreements. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing feedstock access through waste management alliances.
Within the industrial gas tier, Air Products and Linde occupy positions as infrastructure-anchored suppliers with proprietary gas handling systems. Plug Power exemplifies the captive demand model through material handling and logistics customer relationships. Tidewater Renewables and Hazer Group represent emerging specialists in biogenic feedstock conversion, with Gold Hydrogen and Pure Hydrogen anchoring the pure-play exploration segment.
| Leading Market Players |
|---|
| Air Products |
| Tidewater Renewables |
| Linde |
| Gold Hydrogen |
| Hazer Group |
| Plug Power |
| Ballard Power Systems |
| Pure Hydrogen |
| Cummins |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement consolidation along Germany's Rhine-Alpine corridor is compressing contract durations and demanding carbon intensity documentation that forces producers to upgrade purification systems and absorb certification costs. This buyer-driven specification tightening propagates through Spanish and Dutch supply nodes, elevating price floors for certified biogenic grades while squeezing margins on uncertified volumes.
Pricing Analysis
Capacity additions in Spain are reshaping price floors for Atlantic-facing supply contracts. Contract-based long-term offtake structures dominate industrial procurement, with CertifHy certification tier and volume scale serving as the primary price differentiation drivers. Cost compression in standard-grade supply is intensifying because thermochemical operators compete for limited agricultural residue feedstocks. Chemical processors in the Netherlands exhibit lowest price sensitivity due to Scope 3 compliance deadlines, while distributed fleet operators in France remain most price-sensitive.
Supply Chain Analysis
Liquid hydrogen freight costs from Spain's Basque Country terminals to northwest European demand centers anchor delivered price structures for export-oriented volumes. Supply concentrates in Spain, Germany, and the Netherlands, with production drawing from olive pomace, forestry residues, and agricultural waste streams. Single-source vulnerability around seasonal feedstock availability in Extremadura and Andalusia exposes producers to procurement disruptions. Distribution runs through repurposed natural gas pipelines in the Netherlands and dedicated hydrogen corridors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biohydrogen functions as a stable compounder anchored by irreversible regulatory mandates in hard-to-abate sectors where electrification remains technically uneconomical.
For Market Incumbents: Hedge against blue hydrogen cost competition by securing captive feedstock access through waste management alliances in Spain and France. Prioritize certification investment under CertifHy and TÜV schemes to defend premium pricing tiers as carbon intensity thresholds tighten. Accelerate capacity additions in Iberian hydrogen valleys before pipeline steel embrittlement standards harden infrastructure deployment timelines.
For New Entrants and Emerging Players: Municipal bus fleets in secondary French and Italian cities represent underserved demand with lower certification barriers and shorter sales cycles than industrial offtakers. Photolytic-microalgae demonstration scale-up offers the most penetrable technology wedge, with Dutch pilot facilities validating yield breakthroughs. Pursue direct contracting with fleet consortia rather than intermediaries to capture margin and demand visibility.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play biogenic specialists holding validated feedstock agreements and REPowerEU subsidy eligibility. Five-to-ten year viability hinges on certification scheme harmonization across member states. Watch for F-Gas Regulation implementation velocity as the inflection signal—accelerated equipment recertification timelines indicate tightening supply constraints and pricing power migration to certified producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Security Agreement | Long-term residue supply contracts with Spanish agricultural cooperatives lock in cost positions. |
| Certification Pre-Compliance | Early CertifHy scheme adoption secures premium pricing eligibility before mandatory thresholds. |
| Pipeline Infrastructure Conversion | Zeeland natural gas pipeline repurposing connects biogenic production to Antwerp chemical demand. |
| Photobioreactor Scale-Up | Dutch closed-system designs achieve sub-1 kg CO2e intensities for Belgian steelmaker contracts. |
| Hydrogen Valley Cluster Entry | Extremadura hub positioning captures REPowerEU tariff guarantees and export logistics advantages. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrogen project developers, EPC contractors, chemical procurement leads, and fleet operations managers with secondary validation against EIA hydrogen databases, IEA technology roadmaps, FERC infrastructure filings, and EU project development registries. Bottom-up capacity installation tracking and top-down policy impact modeling were triangulated against trade flow data.
Historical production cost trajectories anchored the forecast window against comparable-period electrolyzer and fermentation system deployments. Segmentation dimensions spanned production technology pathway, end-use application, storage modality, and distribution channel. CAGRs were derived from feedstock availability curves, subsidy phase-in schedules, and carbon intensity threshold adoption rates across member states.
Inputs from EU project databases and national hydrogen strategies were available through the study window; gaps in commercial-scale photolytic yield data introduce uncertainty bands around cost parity timelines. Forecasts reflect documented assumptions on feedstock competition and certification scheme harmonization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Green Diesel Market
Alternative Fuels
Aviation Alternative Fuel Market